
 Crossover Ladder Market | 2026-2036
Crossover Ladder Market Size, Share, and Industry Trends Forecast 2026-2036
Crossover Ladder Market Analytics
Chinese aluminum extrusion capacity is expanding, feeding raw material pipelines for crossover ladder producers worldwide. Werner Co. leverages vertical integration across fiberglass and aluminum platforms to sustain cost discipline. Louisville Ladder anchors North American distribution through big-box retail partnerships. TB Davies specializes in European-certified industrial-grade configurations.
A crossover ladder is a portable elevated access device featuring hinged or telescoping rails with flat platform steps, typically rated for load capacities between 250 and 375 pounds, designed to bridge workstations, equipment, or obstacles in industrial and commercial environments. Aluminum dominates material selection due to strength-to-weight ratios, though fiberglass segments command premium positioning in electrical hazard zones where dielectric properties matter. Multi-purpose ladder configurations capture the fastest expansion as contractors seek single-unit flexibility across job sites, while step ladder variants retain volume leadership in residential and light commercial channels.
OSHA 1910 walking-working surface standards and ANSI A14 ladder safety specifications shape product certification requirements and channel access across the United States. The EU Machinery Directive and CE marking obligations govern European import eligibility and design liability. Facility managers and procurement officers must track evolving carbon-footprint disclosure rules under CSRD that will soon filter into industrial equipment purchasing criteria.
Market Dynamics
OSHA 1910 walking-working surface standards and tightening ANSI A14 certification requirements are compressing product lifecycles and forcing manufacturers toward multi-purpose aluminum configurations that satisfy evolving height-access compliance mandates across industrial facilities.
Growth Catalysts
- OSHA 1910 compliance deadlines:Facility managers in warehousing and manufacturing accelerate equipment refresh cycles to meet updated fall-protection mandates, creating replacement demand for certified crossover platforms.
- Aluminum extrusion supply expansion:Chinese capacity additions lower raw material input costs for ladder producers, enabling margin expansion and competitive pricing in North American distribution channels.
- Multi-purpose configuration preference:Contractors prioritize single-unit flexibility that bridges workstations, equipment gaps, and obstacle spans without dedicated fixed installations.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations transmit directly to finished goods cost structures, compressing margins for non-integrated producers during commodity upswings.
- Chinese supply concentration:Raw material and component sourcing clusters in Zhejiang and Guangdong provinces create geographic risk exposure for global production networks.
- Fiberglass dielectric premium ceiling:Electrical hazard zone applications face substitution pressure from composite alternatives when price gaps exceed procurement thresholds.
Strategic Opportunities
- EU CSRD carbon disclosure alignment:Early certification to embodied carbon tracking standards creates differentiation for industrial buyers with Scope 3 reduction mandates.
- Maintenance-as-a-service bundling:Equipment leasing with inspection and recertification services penetrates facility management procurement at Fortune 500 industrial campuses.
- Telescoping rail technology convergence:Integration with IoT load-sensing systems enables predictive maintenance contracts and usage-based pricing models.
Industry Challenges
- Welding technician scarcity:Aluminum TIG certification gaps constrain production scaling for manufacturers expanding beyond semi-automated assembly lines.
- ANSI A14.2 testing backlog:Third-party laboratory capacity limits delay new product introductions during peak certification demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crossover Ladder Market |
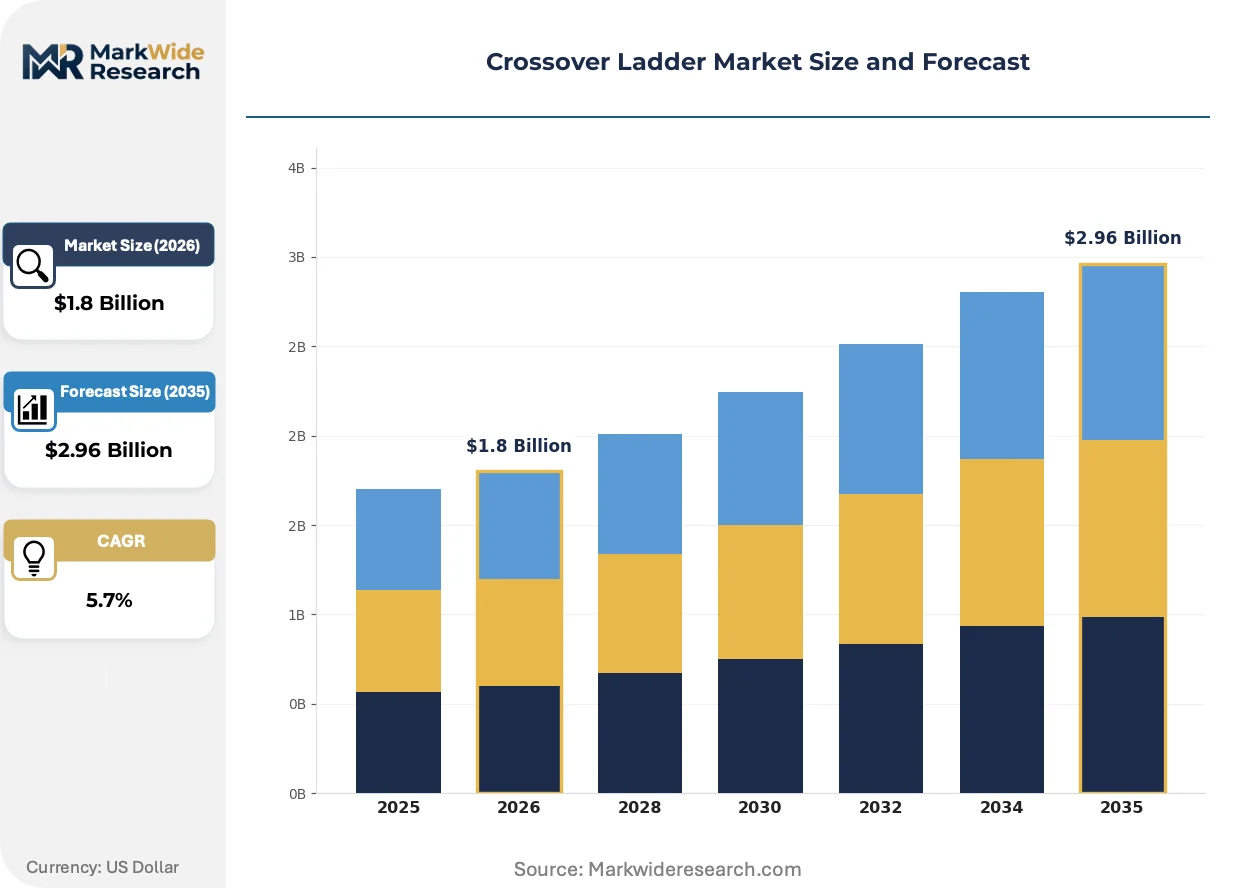
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Purpose Ladder, Telescoping Ladder, Folding Ladder, Step Ladder Material: Aluminum, Fiberglass, Wood, Steel Application: Industrial Use, Residential Use, Commercial Use, Maintenance End User: Contractors, Homeowners, Facility Managers, Retailers |
| Companies Covered | Alaco Ladder, Cotterman, TC Safety Rail, Halmt, Marco Specialty Steel, FS Industries, Werner Co., Louisville Ladder, TB Davies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crossover Ladder Market Evolving Landscape
Material science advances and regulatory disclosure requirements are converging to reshape product architecture, certification workflows, and procurement evaluation criteria across industrial access equipment.
Telescoping aluminum rail systems with integrated platform locking mechanisms are expanding into maintenance departments at automotive assembly plants and pharmaceutical manufacturing facilities. These configurations reduce storage footprint by sixty percent versus fixed-frame alternatives while satisfying load ratings up to 375 pounds. The technology is expanding into rental fleet inventories as equipment lessors seek asset versatility across multi-site customer contracts.
EU CSRD scope 3 emissions disclosure rules are forcing facility managers to document embodied carbon in capital equipment purchases. Industrial buyers now require Environmental Product Declarations from ladder suppliers, with aluminum sourcing transparency becoming a procurement gate. European distributors are responding by segmenting catalogs into CSRD-ready and standard product tiers.
Consolidated procurement through national facilities management contracts is displacing site-level purchasing autonomy. Integrated service providers like Cushman & Wakefield and JLL specify certified crossover platforms across property portfolios, compressing vendor counts and demanding volume pricing transparency. This concentration is most visible in United States logistics warehouse networks where single procurement decisions cover twenty-plus distribution centers.
Crossover Ladder Market Segmentation
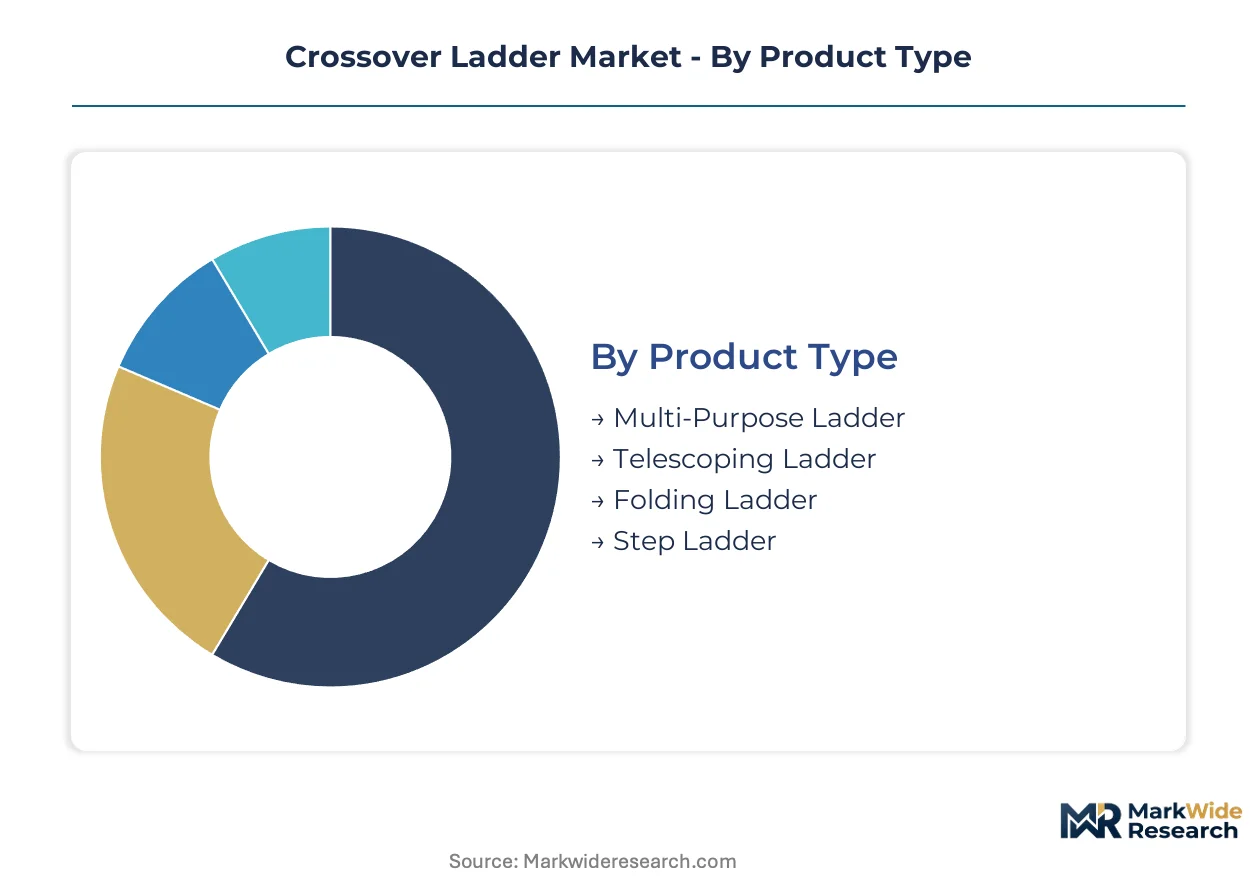
Crossover ladder procurement decisions split across four distinct axes: product architecture determines functional flexibility, material selection governs safety compliance and weight trade-offs, application context dictates load ratings and certification requirements, and end-user identity shapes channel preference and service bundling expectations.
Product Type:
Contractors prioritize single-unit versatility that eliminates redundant equipment purchases across job sites with varying height-access requirements.
- Multi-Purpose Ladder:Hinged rail systems with configurable platform positions adapt to workstation bridging, equipment spanning, and standard elevation tasks. Facility managers at automotive assembly plants in Michigan and warehousing complexes in Texas specify these for fleet standardization that reduces SKU proliferation and training overhead.
- Telescoping Ladder:Collapsible rail mechanisms with nested tube sections compress storage footprints by sixty percent versus fixed-frame alternatives. Pharmaceutical manufacturing facilities in New Jersey and biotech campuses in Massachusetts adopt these for cleanroom environments where space constraints intersect with frequent height-access needs.
- Folding Ladder:Hinge-locked rail systems with compact folded dimensions suit residential storage limitations and light commercial maintenance schedules.
- Step Ladder:Fixed-frame A-frame configurations with platform steps retain dominance in homeowner and retail inventory channels where cost minimization outweighs adaptability requirements.
Volume sits with step ladder configurations in residential and light commercial channels; growth tilts toward multi-purpose designs as industrial procurement consolidates around flexible fleet standards.
Material:
End-use electrical hazard exposure and weight-bearing requirements drive material selection more than initial acquisition cost.
- Aluminum:Extruded 6061-T6 alloy rail systems deliver strength-to-weight ratios that enable single-person portability at load ratings up to 375 pounds. Distribution centers in Ohio and manufacturing corridors in Indiana specify aluminum for high-frequency use where operator fatigue reduction improves throughput metrics.
- Fiberglass:Pultruded rail sections with dielectric properties insulate against electrical shock in utility maintenance and power generation environments. Electric cooperatives in Wisconsin and municipal utility districts in Florida accept price premiums for OSHA-compliant electrical hazard zone access.
- Wood:Traditional rail construction with limited conductivity persists in specialty theatrical rigging and heritage building restoration where aesthetic compatibility matters.
- Steel:Heavy-gauge welded frame systems serve fixed industrial installations where permanent mounting eliminates portability requirements.
Aluminum dominates unit volume across commercial and industrial procurement; fiberglass claims the steepest expansion trajectory as electrical safety enforcement tightens in utility sectors.
Application:
Regulatory jurisdiction and inspection frequency determine whether buyers prioritize certified industrial ratings or accept residential-grade specifications.
- Industrial Use:ANSI A14.2-certified platform systems with documented load testing and traceable manufacturing records satisfy OSHA audit requirements. Chemical processing facilities in Louisiana and petrochemical complexes along the Texas Gulf Coast mandate Type IA duty ratings for daily production floor access.
- Commercial Use:Medium-duty configurations balance durability expectations against capital expenditure constraints in retail backrooms and office building maintenance. Property management firms in Illinois and hospitality operators in Nevada standardize on Type I duty ratings for semi-annual inspection cycles.
- Residential Use:Light-duty step configurations with 200-pound ratings serve intermittent homeowner needs for gutter cleaning and interior maintenance.
- Maintenance:Service-contractor fleets require rapid-deployment platforms that transition between client sites with minimal setup time.
Industrial procurement generates the highest per-unit revenue; commercial maintenance contracts are expanding most quickly as facilities management outsourcing accelerates.
End User:
Purchasing authority concentration and technical specification involvement vary sharply across buyer categories.
- Facility Managers:Corporate procurement officers at Fortune 500 industrial campuses negotiate national contracts that specify certified platforms across twenty-plus distribution centers. Integrated service providers like Cushman & Wakefield and JLL consolidate vendor counts and demand volume pricing transparency.
- Contractors:Independent construction firms and specialty trades prioritize equipment leasing with maintenance bundling to convert capital expenditure to operating expense. Regional rental fleets in Georgia and equipment lessors in Arizona penetrate this segment with usage-based pricing models.
- Homeowners:Big-box retail channels in California and home improvement centers in Pennsylvania serve discretionary purchasers with price-promoted seasonal inventory.
- Retailers:Distributor intermediaries stock breadth across price tiers to capture contractor walk-in traffic and residential project demand.
Facility managers command the largest transaction sizes; contractors represent the fastest-climbing segment as equipment-as-a-service penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese aluminum extrusion capacity in Zhejiang and Guangdong provinces feeds raw material pipelines for crossover ladder producers serving industrial facilities worldwide.
United States
Warehouse operators and automotive assembly plants drive equipment refresh cycles to meet OSHA 1910 walking-working surface mandates. ANSI A14 certification requirements compress product lifecycles and force procurement toward multi-purpose aluminum configurations. Distribution centers across Ohio, Indiana, and Michigan specify Type IA duty-rated platforms for high-frequency production floor access.
Germany
Industrial machinery manufacturers and chemical processing facilities prioritize CE-marked access equipment under EU Machinery Directive obligations. CSRD carbon disclosure rules are forcing facility managers to document embodied carbon in capital equipment purchases. Manufacturing clusters in North Rhine-Westphalia and Baden-Württemberg demand Environmental Product Declarations from ladder suppliers.
China
Domestic logistics expansion and export-oriented manufacturing sustain demand for aluminum multi-purpose configurations. GB standards and SAMR quality supervision shape product certification workflows. Extrusion facilities in Zhejiang province supply rail sections to crossover ladder fabricators serving Southeast Asian and Middle Eastern markets.
United Kingdom
Facilities management outsourcing through integrated service providers consolidates procurement across commercial property portfolios. HSE work-at-height regulations and LOLER lifting equipment standards govern inspection and recertification intervals. Industrial estates in the Midlands and Greater Manchester concentrate maintenance contractor fleets requiring rapid-deployment platforms.
India
Infrastructure investment and manufacturing zone development accelerate demand for industrial-grade access equipment. BIS certification requirements and state-level factory inspectorates enforce load rating compliance. Automotive corridors in Tamil Nadu and Gujarat specify aluminum crossover platforms for assembly line maintenance protocols.
Crossover Ladder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized configurations for electrical hazard zones and telescoping rail applications. The vendor base clusters around three archetypes: vertically integrated aluminum extruders with captive material supply, regional fabricators serving national distribution networks, and specialty manufacturers focused on dielectric fiberglass products. Competitive dynamics center on backward integration into raw material production and strategic partnerships with facilities management service providers.
Among North American fabricators, Werner Co. and Louisville Ladder occupy positions reflecting scale-driven and distribution-anchored archetypes respectively. TB Davies represents the European-certified industrial-grade specialist tier. These three exemplify how geographic origin and company structure align with strategic positioning: Werner Co. leverages in-house production across material platforms; Louisville Ladder anchors big-box retail channels; TB Davies concentrates on regulatory-compliant configurations for EU industrial buyers.
| Leading Market Players |
|---|
| Alaco Ladder |
| Cotterman |
| TC Safety Rail |
| Halmt |
| Marco Specialty Steel |
| FS Industries |
| Werner Co. |
| Louisville Ladder |
| TB Davies |
| Others |
Value Network & Pricing Analysis
Telescoping rail technology adoption in pharmaceutical and automotive facilities is compressing production batch sizes while concentrating fabrication expertise among aluminum TIG-certified shops in the United States and Germany. This dual shift simultaneously elevates labor cost premiums for qualified welding technicians and reinforces pricing power for manufacturers with captive extrusion capacity in Zhejiang province.
Pricing Analysis
Warranty and inspection service bundling separates premium crossover ladder tiers from unbundled transactional sales in North American distribution channels. Three-tier pricing structure across premium, standard, and economy levels reflects ANSI A14.2 certification grade and volume scale under national facilities management contracts. Pricing pressure stems from Chinese aluminum extrusion oversupply feeding raw material pipelines. Homeowners through big-box retail channels exhibit highest price sensitivity; Fortune 500 facility managers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Direct-to-facility-manager channels handle hyperscale buyer demand through integrated service providers like Cushman & Wakefield and JLL, while regional equipment lessors serve contractor leasing demand. Raw material pipelines draw from Chinese extrusion capacity in Zhejiang and Guangdong provinces, with secondary sourcing from South Korean and German aluminum suppliers. Supply chain risk centers on single-source vulnerability for 6061-T6 alloy rail sections. Distribution runs through big-box retail partnerships and industrial distribution networks anchored by Louisville Ladder and Werner Co.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crossover ladder supply is tightening around certified aluminum TIG welding capacity, a bottleneck propping pricing power for manufacturers with qualified technician pipelines in Michigan and Indiana industrial corridors.
For Market Incumbents: Hedge against fiberglass substitution pressure in electrical hazard zones by deepening backward integration into pultruded rail production and securing long-term aluminum offtake agreements with Zhejiang extruders. Expand ANSI A14.2 certification capacity to capture replacement demand from OSHA 1910 compliance deadlines. For New Entrants and Emerging Players: Equipment lessors represent the most penetrable channel partner type for telescoping rail configurations with IoT load-sensing integration. Target maintenance-as-a-service bundling for pharmaceutical manufacturing facilities in New Jersey and biotech campuses in Massachusetts. Pursue white-space in EU CSRD-ready product tiers ahead of embodied carbon disclosure mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty fiberglass manufacturers with dielectric certification and telescoping rail technology holders. Long-term viability favors vertically integrated fabricators with captive aluminum supply and certified welding pipelines. Monitor ANSI A14.2 laboratory testing backlog duration as inflection indicator for new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Werner Co. leverages captive Zhejiang supply to sustain margin discipline against LME volatility. |
| IoT Load-Sensing Platform Integration | Telescoping rail systems with predictive maintenance contracts penetrate automotive assembly plants. |
| CSRD-Ready Certification Investment | Environmental Product Declarations differentiate suppliers for EU facility managers with Scope 3 mandates. |
| Maintenance-as-a-Service Bundling | Equipment leasing with inspection recertification converts capital expenditure to operating expense for contractors. |
| ANSI A14.2 Testing Capacity Expansion | Third-party laboratory investment accelerates new product introductions during peak certification demand windows. |
Research Methodology
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone of this analysis, cross-referenced with primary interviews conducted with maintenance directors at automotive assembly plants, facility managers at Fortune 500 warehousing complexes, procurement officers at integrated service providers, and aftermarket service heads at regional equipment lessors. Bottom-up and top-down triangulation validated volume estimates across product type, material, application, and end-user segmentation dimensions.
Historical trendline analysis of aluminum pricing volatility, OSHA enforcement patterns, and ANSI certification timelines informed the analytical framework across the projection horizon. Modeled segmentation dimensions include product architecture, material selection, regulatory compliance tier, and channel structure. CAGRs were derived from regression analysis against industrial capital expenditure cycles and facilities management outsourcing penetration rates, with specific inputs from LME aluminum forward curves and OSHA 1910 inspection frequency data.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to ANSI A14 standards, sudden trade policy shifts affecting Chinese aluminum tariffs, and breakthrough composite material substitutions for dielectric applications. Practitioners should monitor welding technician certification pipeline capacity and third-party laboratory testing queue lengths for early signals of supply constraint intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Global Crane Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Hydroforming Press Market