
 Global Hurthle Cell Carcinoma Treatment Market | 2026-2036
Global Hurthle Cell Carcinoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hurthle Cell Carcinoma Treatment Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is realigning pharmaceutical development priorities toward greater transparency in clinical trial outcomes and patient access. Bayer Healthcare Pharmaceuticals leverages its extensive oncology portfolio to address rare thyroid cancers. Blueprint Medicines specializes in precision therapies, targeting specific genetic mutations associated with the disease. Novartis competes with a broad pipeline that includes both targeted and immunotherapeutic agents.
Hurthle cell carcinoma treatment encompasses medical and surgical interventions for a rare, distinct subtype of differentiated thyroid cancer. This cancer is defined by the predominance of oncocytes, or Hurthle cells, which are often less responsive to traditional radioactive iodine therapy. While surgical resection remains the primary therapy, the targeted therapy segment is expanding rapidly. Among product types, tyrosine kinase inhibitors represent the leading class of drugs developed specifically for advanced or refractory cases.
Market access is governed by stringent approval processes from bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These agencies' orphan drug designation programs provide critical incentives for developing treatments for rare conditions like Hurthle cell carcinoma. Future investment decisions will hinge on the evolving understanding of tumor biology and the potential for combination therapies.
Market Dynamics
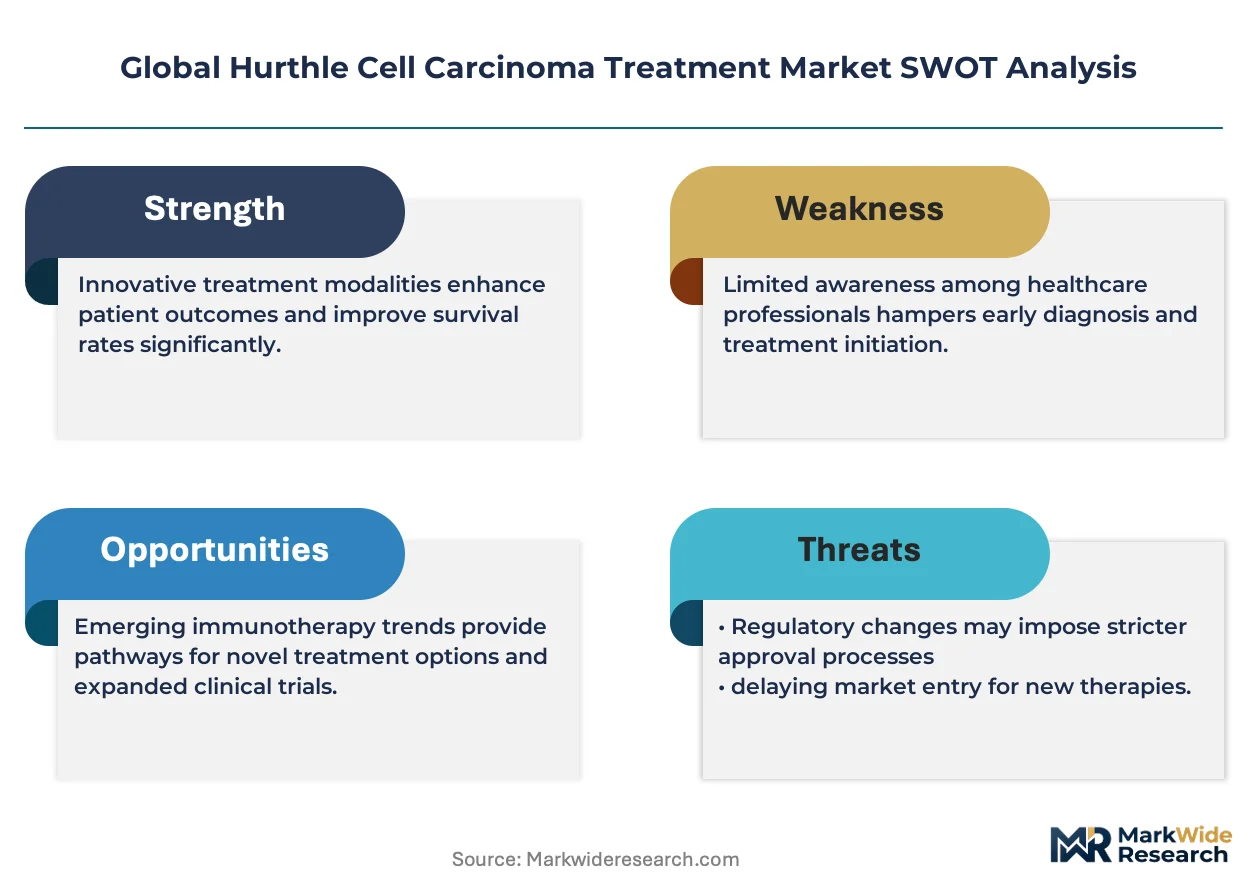
The central force shaping the Hurthle cell carcinoma treatment market is the pivot from generalized thyroid cancer protocols to highly specific, biology-driven interventions. This shift is enabled by the increasing accessibility of genomic sequencing, which identifies actionable mutations for targeted therapies.
Growth Catalysts
- Orphan Drug Incentives:Regulatory frameworks, including the US FDA's Orphan Drug Act and parallel programs from the European Medicines Agency, provide critical market exclusivity and financial incentives that de-risk development for rare diseases.
- Diagnostic Precision:Advances in next-generation sequencing and immunohistochemistry allow for more accurate differentiation of Hurthle cell carcinoma from other thyroid neoplasms, improving patient identification for targeted clinical trials and therapies.
- Oncology Center Specialization:The consolidation of care within specialized oncology centers creates a concentrated demand for advanced treatments and facilitates the recruitment of patients for clinical studies of this rare cancer subtype.
Market Restraints
- High Treatment Costs:The significant expense associated with novel tyrosine kinase inhibitors and complex surgical procedures creates substantial reimbursement hurdles and limits patient access, particularly in healthcare systems with strict budget controls.
- Patient Cohort Rarity:The low incidence of Hurthle cell carcinoma makes it structurally difficult to conduct large-scale, statistically powerful clinical trials, slowing the evidence generation needed for regulatory approval and guideline adoption.
- Inherent Therapy Resistance:A defining biological feature of Hurthle cells is their relative resistance to traditional radioactive iodine therapy, a cornerstone of differentiated thyroid cancer treatment, which narrows the effective therapeutic options.
Strategic Opportunities
- Combination Therapy Development:The convergence of targeted therapies with immunotherapies, such as checkpoint inhibitors, presents a significant opportunity to overcome resistance mechanisms and improve durable response rates in advanced or metastatic disease.
- Biomarker-Driven Drug Discovery:Expanding the understanding of the specific molecular drivers beyond known mutations offers a pathway for developing a new generation of precision medicines tailored to distinct patient subpopulations.
- Geographic Market Expansion:Improving diagnostic infrastructure and rising healthcare expenditure in specific Asia-Pacific countries, such as South Korea and Japan, create opportunities to expand access to novel therapies beyond North America and Europe.
Industry Challenges
- Complex Patient Stratification:Effectively identifying which patients will benefit from specific targeted therapies requires sophisticated and often costly biomarker testing, posing a significant logistical and educational challenge for community oncology practices.
- Reimbursement Pathway Navigation:Securing favorable reimbursement decisions from a fragmented landscape of public and private payers for high-cost orphan drugs requires extensive health economics and outcomes research data.
- Pathology Expertise Scarcity:A shortage of pathologists with specialized expertise in accurately diagnosing rare thyroid malignancies can lead to misclassification and delays in appropriate treatment initiation for patients with Hurthle cell carcinoma.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hurthle Cell Carcinoma Treatment Market |
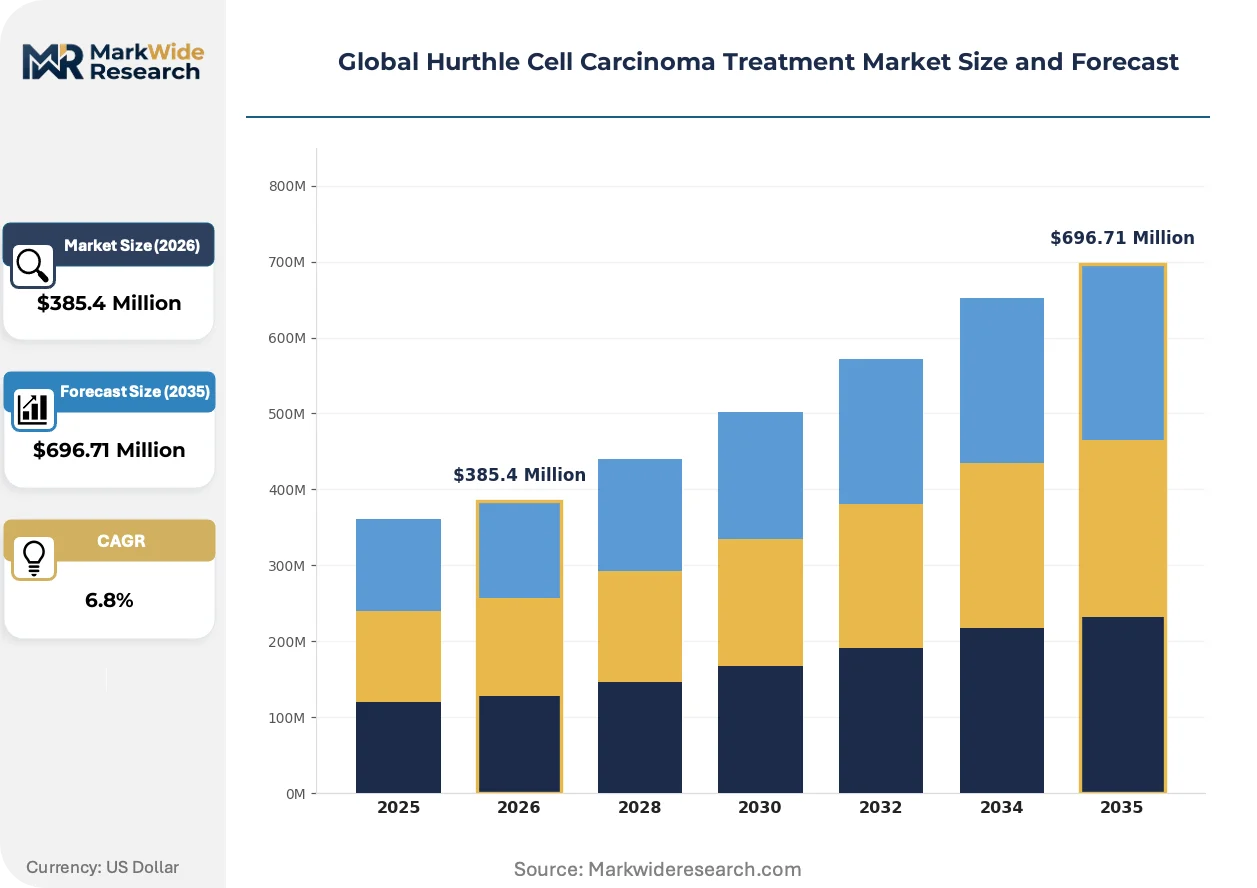
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Surgical Resection, Radioactive Iodine, Targeted Therapy, Chemotherapy, Immunotherapy, Hormone Therapy Product Type: Tyrosine Kinase Inhibitors, Monoclonal Antibodies, Cytotoxic Drugs, Immune Checkpoint Inhibitors, Radiopharmaceuticals, Hormonal Agents End User: Oncology Centers, Specialty Clinics, Cancer Research Institutes, Diagnostic Laboratories, Ambulatory Care Facilities, Clinical Hospitals Delivery Mode: Oral Administration, Intravenous Injection, Subcutaneous Injection, Radioisotope Therapy, External Beam Radiation, Combination Treatment |
| Companies Covered | Bayer Healthcare Pharmaceuticals, Novartis, Pfizer, Blueprint Medicines, Eli Lilly and Company, Sanofi, Amgen, Genentech, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hurthle Cell Carcinoma Treatment Market Strategic Shifts & Innovations
The treatment paradigm for Hurthle cell carcinoma is undergoing a fundamental transformation, driven by a deeper biological understanding of the disease. This evolution prioritizes personalized medicine, where treatment selection is increasingly guided by the specific molecular profile of a patient's tumor.
Liquid biopsy technology provides a non-invasive method for detecting circulating tumor DNA in a patient's bloodstream. Oncologists in specialized cancer centers are adopting these tests to monitor for disease recurrence and assess treatment response without requiring tissue samples. This technology is decentralizing disease surveillance, moving it from reliance on periodic imaging scans to more frequent, data-rich blood tests managed in the clinic.
European Union regulations, specifically the Corporate Sustainability Reporting Directive (CSRD), are introducing new transparency requirements for pharmaceutical companies. The directive compels firms to provide more granular disclosures on clinical trial outcomes, drug pricing rationale, and patient access programs. This directly impacts the targeted therapy segment, where manufacturers now face greater scrutiny and must publicly justify the value proposition of their high-cost orphan drugs.
A notable behavioral shift involves the growing acceptance of real-world evidence (RWE) in complementing data from traditional randomized controlled trials. Health authorities and payers, particularly in the United States and Germany, are developing frameworks to use data from electronic health records and patient registries. This shift is critical for rare diseases like Hurthle cell carcinoma, where RWE can help validate the long-term effectiveness and safety of therapies in a broader population.
Global Hurthle Cell Carcinoma Treatment Market Segmentation
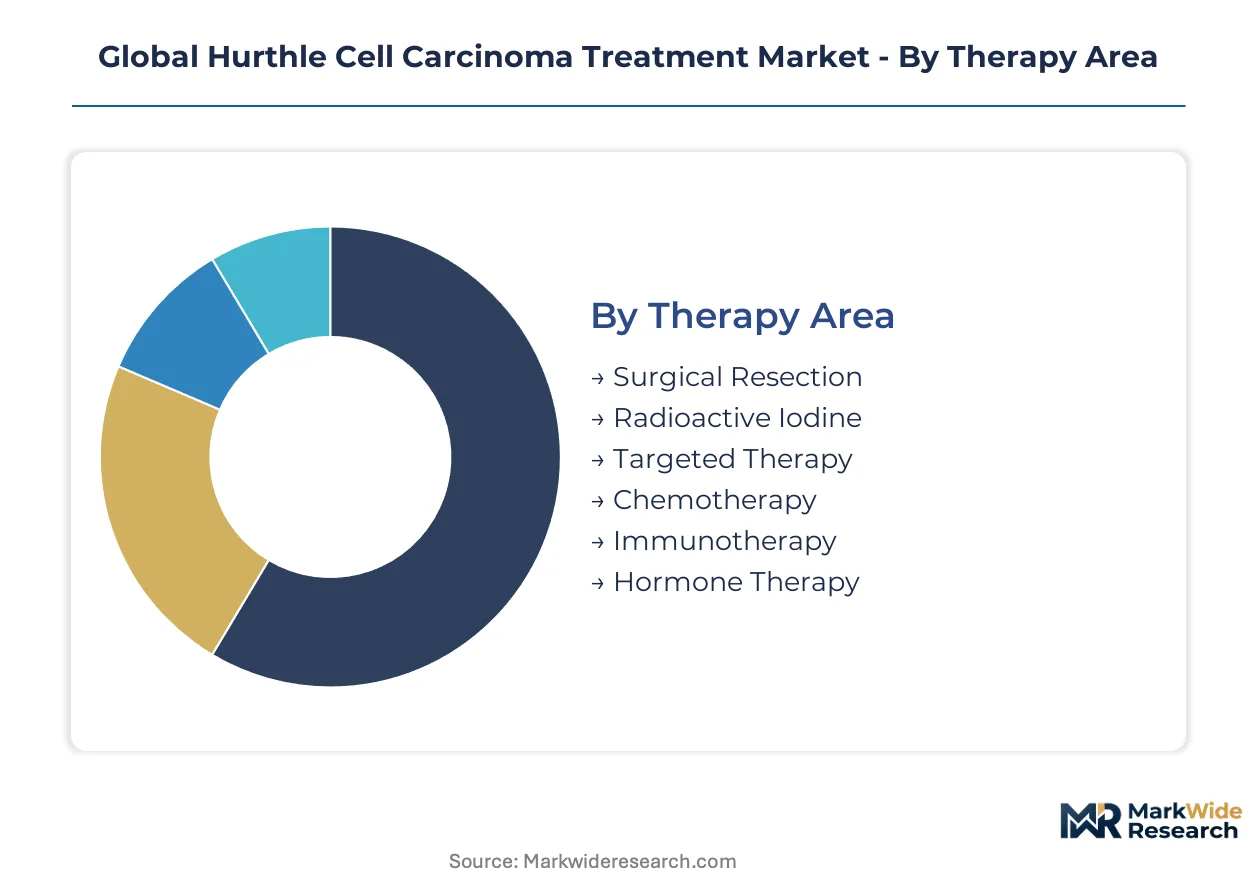
The global Hurthle cell carcinoma treatment market is delineated into distinct segments, reflecting the diverse therapeutic approaches and patient care models employed for this rare thyroid malignancy. Understanding these segments is crucial for stakeholders to identify areas of unmet need and allocate resources effectively for advanced treatment development and deployment.
Therapy Area:
The therapeutic landscape for Hurthle cell carcinoma treatment navigates between highly customized interventions and more standardized protocols, driven by tumor biology and patient presentation. Surgical resection remains foundational, while targeted therapies offer personalized options for advanced cases.
- Surgical Resection:This involves the primary removal of the tumor, often a total thyroidectomy, and is the initial and most definitive treatment for localized Hurthle cell carcinoma. Demand for specialized surgical expertise is concentrated in major oncology centers across the United States and Europe, where complex resections are routinely performed.
- Targeted Therapy:These treatments, including specific kinase inhibitors, precisely interfere with molecular pathways involved in cancer growth, offering an expanding option for patients with advanced or refractory disease. Demand from specialized oncology centers is a primary growth vector, as they are equipped for complex treatment regimens.
- Radioactive Iodine:This systemic radiation therapy utilizes iodine-131 to destroy residual thyroid tissue and cancer cells, though Hurthle cells often exhibit resistance to this traditional treatment.
- Chemotherapy:Systemic cytotoxic drugs are used to destroy cancer cells throughout the body, typically reserved for advanced, aggressive forms of Hurthle cell carcinoma when other treatments are ineffective.
- Immunotherapy:This approach harnesses the body's immune system to fight cancer, with agents like checkpoint inhibitors being explored for their potential in advanced thyroid malignancies.
- Hormone Therapy:Thyroid hormone replacement therapy is administered post-thyroidectomy to suppress TSH levels, which can stimulate residual cancer growth.
Most installed capacity flows through Surgical Resection. Expansion is steepest in Targeted Therapy.
Product Type:
The product type segmentation highlights the cost tiers associated with treatment, ranging from established, often generic, agents to high-value, novel precision medicines. These costs influence market access and reimbursement strategies across different healthcare systems.
- Tyrosine Kinase Inhibitors:These small-molecule drugs block specific enzymes (tyrosine kinases) that promote cancer cell growth and division, representing the leading class of targeted drugs for advanced Hurthle cell carcinoma. Their demand is particularly high in markets with established reimbursement frameworks for orphan drugs, such as the US and Germany.
- Immune Checkpoint Inhibitors:These monoclonal antibodies block proteins that prevent the immune system from attacking cancer cells, showing promise in combination therapies for advanced or metastatic disease. The demand for these agents is driven by clinical trial success and their potential to overcome therapeutic resistance.
- Monoclonal Antibodies:These engineered antibodies target specific proteins on cancer cells or immune cells, offering a precise mechanism of action against various cancer types.
- Cytotoxic Drugs:Traditional chemotherapy agents, these drugs kill rapidly dividing cells, including cancer cells, and are used in aggressive or refractory Hurthle cell carcinoma cases.
- Radiopharmaceuticals:These are radioactive drugs used for diagnostic imaging or therapy, with radioactive iodine being the most prominent for thyroid cancer treatment.
- Hormonal Agents:These medications, primarily levothyroxine, replace thyroid hormones and suppress thyroid-stimulating hormone (TSH) to reduce cancer recurrence risk.
The largest volume of agents comprises Cytotoxic Drugs. Emerging product lines are characterized by Immune Checkpoint Inhibitors.
End User:
This category distinguishes end-users by their application focus, ranging from highly specialized treatment facilities to broader diagnostic and research institutions. Each type of end-user plays a distinct role in the patient journey and therapeutic development.
- Oncology Centers:These specialized facilities provide comprehensive cancer care, including advanced diagnostics, surgical interventions, and targeted therapies, serving as primary hubs for Hurthle cell carcinoma treatment. Oncology centers in major urban areas, particularly in North America, represent significant demand for novel therapies.
- Clinical Hospitals:General hospitals with oncology departments offer a broader range of services for cancer patients, including initial diagnosis, surgery, and systemic treatments, providing essential access points for many patients. These institutions serve a wider geographic base, supporting patient access across diverse regions.
- Specialty Clinics:These outpatient facilities focus on specific aspects of cancer care, such as radiation therapy or medical oncology consultations, complementing larger hospital networks.
- Cancer Research Institutes:These organizations are dedicated to understanding cancer biology and developing new treatments, often conducting clinical trials for novel Hurthle cell carcinoma therapies.
- Diagnostic Laboratories:These facilities perform molecular and pathological analyses, including genomic sequencing and immunohistochemistry, critical for accurate diagnosis and patient stratification.
- Ambulatory Care Facilities:These provide outpatient medical services, including chemotherapy administration or follow-up care, for patients not requiring hospitalization.
Patient demand primarily drives activity in Clinical Hospitals. Research-focused institutions prioritize Cancer Research Institutes.
Delivery Mode:
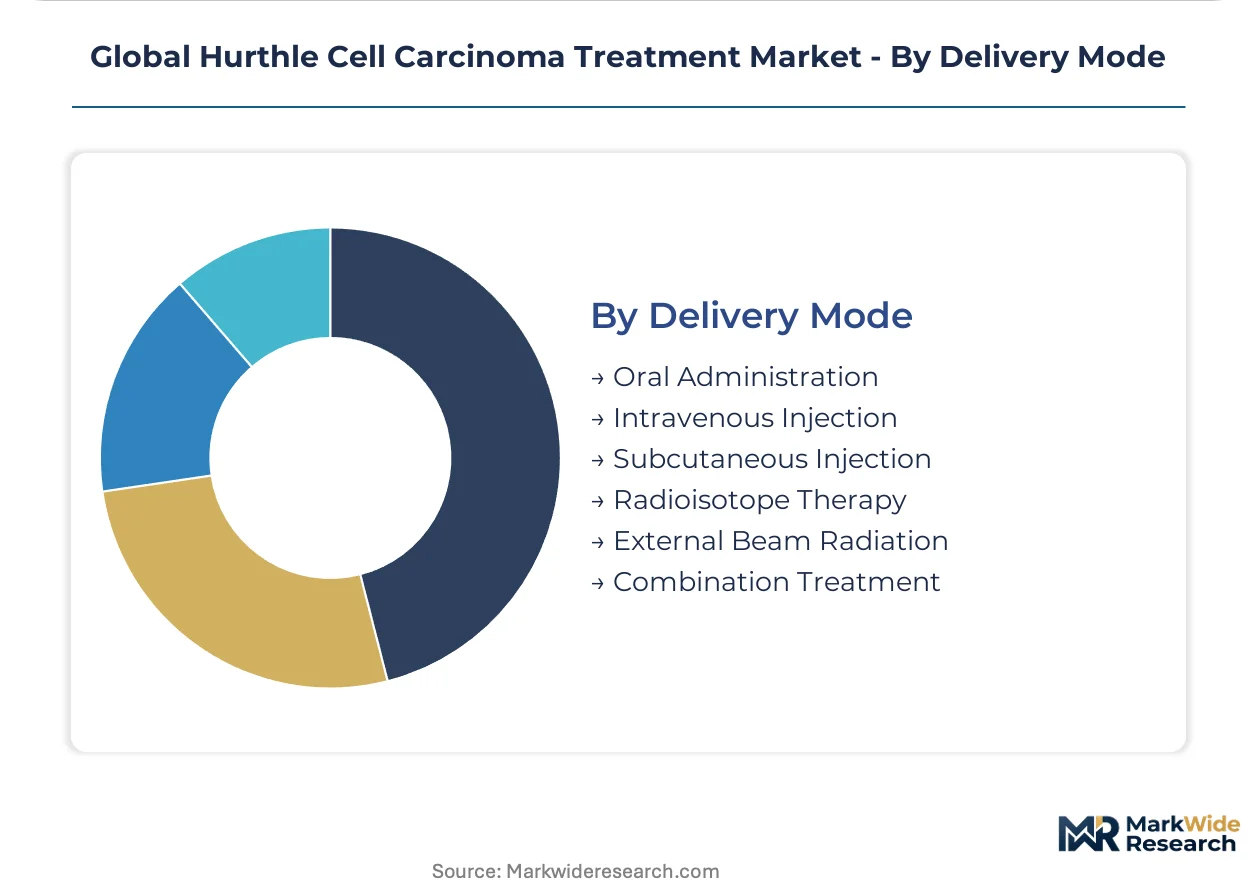
The delivery mode segment reflects the volume and convenience considerations for administering Hurthle cell carcinoma treatments, from high-volume systemic injections to highly specialized radioisotope applications. These methods influence patient compliance and healthcare resource allocation.
- Intravenous Injection:This method involves administering drugs directly into a vein, commonly used for targeted therapies, immunotherapies, and chemotherapy agents, ensuring rapid and complete systemic distribution. This mode is prevalent in hospital settings globally for high-dose or complex drug regimens.
- Oral Administration:This mode allows patients to take medication by mouth, offering convenience and enabling at-home treatment for certain targeted therapies, improving patient adherence. Oral therapies are gaining traction in regions prioritizing patient comfort and decentralized care.
- Subcutaneous Injection:Drugs are administered under the skin, offering an alternative to intravenous delivery for some therapies, potentially reducing hospital visits for patients.
- Radioisotope Therapy:This involves the internal administration of radioactive substances, such as radioactive iodine, to target and destroy cancer cells within the body.
- External Beam Radiation:This non-invasive method uses high-energy rays from outside the body to destroy cancer cells, typically employed for localized disease or metastatic sites.
- Combination Treatment:This approach integrates multiple delivery methods or therapeutic agents concurrently or sequentially to maximize efficacy and overcome resistance.
Higher margins are typically observed in Intravenous Injection. Cost-effectiveness is a primary concern for Oral Administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pharmaceutical industry, central to Hurthle cell carcinoma treatment, scaled significantly within the United States, driven by robust research infrastructure. This historical foundation established a precedent for advanced medical interventions in complex diseases. Specialized oncology centers globally now benefit from this legacy of innovation and continuous development in targeted therapies.
United States
Demand for advanced Hurthle cell carcinoma treatments stems from specialized oncology centers and the expansion of targeted therapy options. The US FDA's Orphan Drug Act provides critical incentives, de-risking development for rare diseases. Boston's biotech cluster attracts significant investment for novel oncology drug development and clinical trials.
Germany
Germany's established healthcare infrastructure and high treatment costs drive demand for innovative oncology solutions. The European Medicines Agency (EMA) approval processes and the CSRD influence pharmaceutical development priorities. Munich's life sciences sector sees strong collaboration between academic research and industry for therapeutic advancements.
Japan
Japan presents opportunities due to improving diagnostic infrastructure and rising healthcare expenditure in precision medicine. The Pharmaceuticals and Medical Devices Agency (PMDA) streamlines approval processes for innovative oncology treatments. Tokyo's medical research institutions are actively exploring new therapeutic modalities and patient access programs.
South Korea
South Korea's growing healthcare expenditure and diagnostic infrastructure improvements create demand for advanced Hurthle cell carcinoma therapies. The Ministry of Food and Drug Safety (MFDS) provides regulatory oversight for novel drug introductions and clinical studies. Seoul's advanced medical facilities focus on precision medicine applications and specialized cancer care.
India
India offers an expanding market with increasing awareness of advanced cancer treatments and improving access to healthcare. The Central Drugs Standard Control Organization (CDSCO) governs drug approvals and clinical trial conduct. Hyderabad's pharmaceutical hub supports both R&D and manufacturing capabilities for various oncology therapies.
Global Hurthle Cell Carcinoma Treatment Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the Hurthle cell carcinoma treatment market, creating a tiered competitive structure. Diversified pharmaceutical giants occupy the top tier, leveraging extensive R&D budgets and global distribution networks. Precision oncology specialists focus on niche molecular targets, driving innovation in advanced therapies. Portfolio diversification and strategic partnerships are dominant competitive moves among these players.
Within the diversified pharmaceutical segment, Bayer Healthcare Pharmaceuticals and Novartis exemplify companies with broad oncology portfolios. These entities leverage extensive established infrastructure for drug development and global market access across multiple therapeutic areas. Blueprint Medicines represents a precision oncology specialist, focusing on targeted therapies for specific genetic mutations associated with rare cancers. Such firms continually explore new therapeutic modalities, including novel kinase inhibitors, and expand their geographic reach through strategic alliances to address unmet medical needs. This dynamic interplay between large-scale pharmaceutical operations and specialized biotechnology firms shapes the innovative landscape of Hurthle cell carcinoma treatment.
| Leading Market Players |
|---|
| Bayer Healthcare Pharmaceuticals |
| Novartis |
| Pfizer |
| Blueprint Medicines |
| Eli Lilly and Company |
| Sanofi |
| Amgen |
| Genentech |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
Research and development costs for novel targeted therapies significantly influence the premium pricing of advanced Hurthle cell carcinoma treatments. These high upfront investments flow through to specialized oncology centers and ultimately impact patient access programs.
Pricing Analysis
Value-based pricing, frequently supported by orphan drug designations, characterizes the Hurthle cell carcinoma treatment market. Price differentiation stems from demonstrated clinical efficacy in advanced cases and the high cost of novel tyrosine kinase inhibitor development. Pricing pressure stems from stringent reimbursement hurdles in European healthcare systems, particularly for high-cost orphan drugs. Patients in public health systems exhibit higher price sensitivity compared to those with comprehensive private insurance plans or in self-pay markets.
Supply Chain Analysis
Regulatory mandates for pharmaceutical manufacturing within specific regions are reshaping sourcing strategies for Hurthle cell carcinoma treatments. Supply of complex active pharmaceutical ingredients (APIs) concentrates in specialized facilities in the United States, Germany, and India. This market depends on a consistent supply of specialized reagents and sterile packaging materials. A structural risk involves single-source vulnerability for rare disease APIs. Distribution runs through a network of specialized hospital pharmacies and oncology centers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hurthle cell carcinoma treatment market presents a margin-expansion story, driven by the shift towards high-value targeted therapies with orphan drug designations. These precision medicines command premium pricing due to their specialized efficacy and limited patient populations.
For Market Incumbents: Anchor existing market share by investing in next-generation tyrosine kinase inhibitors and combination therapies. Diversify portfolios to mitigate the threat of emerging immunotherapies challenging established treatment protocols. Strategic partnerships with diagnostic laboratories represent a critical lever for biomarker-driven drug development and patient stratification.
For New Entrants and Emerging Players: The cost differential between established targeted therapies and more accessible treatment options creates opportunities in underserved patient populations. Target the development of companion diagnostics paired with novel, cost-effective molecularly targeted agents. Focus on geographic expansion into Asia-Pacific countries with rising healthcare expenditure and improving diagnostic infrastructure, leveraging local clinical trial networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where high R&D costs and specialized market access requirements limit smaller players. The long-term viability of this market hinges on continued innovation in precision oncology over the next decade. Seek acquisition targets that possess validated biomarker platforms or novel drug candidates addressing resistance mechanisms. The signal to watch is the successful completion of Phase III trials for combination immunotherapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Advancing Phase III trials for novel tyrosine kinase inhibitors validates efficacy for advanced Hurthle cell carcinoma patients. |
| Regulatory Approval Pathway | Securing orphan drug designation from the US FDA de-risks development and accelerates market entry. |
| Licensing Agreement | Partnering with biotechnology firms expands access to promising immunotherapy candidates for combination regimens. |
| Manufacturing Scale-Up | Increasing production capacity for specialized biologics ensures consistent supply to global oncology centers. |
| Pipeline Diversification | Exploring new molecular targets beyond known mutations expands treatment options for refractory Hurthle cell carcinoma. |
Research Approach
Bottom-up patient demand from oncology centers modeling reconciled against top-down pharmaceutical production and R&D tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided qualitative insights. This was validated against secondary data from FDA filings, EMA submissions, and ClinicalTrials.gov, ensuring comprehensive market understanding. The analysis employed a rigorous triangulation approach to synthesize diverse data points.
An input-output matrix framing guided the forecast framework across the analysis window, integrating various market dynamics. Segmentation dimensions modeled include therapy area, product type, end user, delivery mode, and patient population. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected future growth drivers. Key industry-specific forecast inputs included anticipated clinical trial success rates and new orphan drug designation approvals.
The model assumes a particular technology adoption path; alternative pathways for targeted therapies would alter the outlook. Forecasts reflect assumptions regarding regulatory changes and reimbursement policies. Unforeseen clinical trial failures or shifts in competitor pipelines represent specific risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
South Korea Radiotherapy Market
Oncology
North America Veterinary Oncology Market
Oncology
Bone Cancer Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Interventional Oncology Ablation Market
Oncology
Metastatic Cancer Drug Market
Oncology
Thyroid Cancer Market
Oncology
Precision Oncology Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Oncology Devices Market
Oncology
Germany Radiotherapy Market
Oncology
North America Bone Metastasis Market