
 Germany Radiotherapy Market | 2026-2036
Germany Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Radiotherapy Market Insights
Hypofractionation-grade precision is redrawing competitive boundaries in German radiotherapy. Siemens Healthineers AG leverages its domestic manufacturing footprint to anchor proton therapy system deployments across major university hospitals. Brainlab SE differentiates through integrated software-hardware platforms for cranial and spinal stereotactic applications. Elekta AB competes on linear accelerator service density and adaptive workflow integration.
Radiotherapy employs ionizing radiation—photon, proton, or electron beams calibrated to tumoricidal dose distributions measured in Gray units—to destroy malignant cells while preserving adjacent tissue function. Linear accelerators dominate German installed bases due to reimbursement familiarity and technical staff training depth, while proton therapy systems represent the fastest-growing product category as Heidelberg and Essen centers demonstrate clinical outcomes. Among end users, cancer treatment centers capture the strongest margin pools through bundled care pathways, whereas outpatient clinics remain underpenetrated for complex modalities.
Germany's Medical Device Regulation implementation through BfArM and notified body oversight tightens software validation requirements for radiation therapy planning systems. DIN standards for equipment commissioning and QA protocols shape procurement specifications at state hospital associations. Stakeholders must monitor how BfArM guidance on artificial intelligence-assisted contouring redefines product registration pathways and service contracting structures.
Market Dynamics
Hypofractionation protocols and proton beam therapy are compressing treatment cycles while elevating capital intensity requirements across German hospital networks. BfArM's MDR enforcement timeline is forcing synchronous equipment upgrades and software revalidation across installed linear accelerator bases.
Growth Catalysts
- MDR compliance deadlines:BfArM's phased implementation of Medical Device Regulation is accelerating replacement cycles for legacy cobalt-60 units and first-generation linacs in university hospital networks.
- Proton therapy clinical validation:Heidelberg Ion Beam Therapy Center and West German Proton Therapy Centre Essen are generating outcome data that validates reimbursement pathways for particle therapy in pediatric and ocular malignancies.
- Artificial intelligence-assisted contouring:Deep-learning segmentation algorithms are reducing planning time burdens at high-throughput centers in Bavaria and Baden-Württemberg.
Market Restraints
- Heavy ion facility capital requirements:Proton and carbon-ion installation costs exceed €150 million per center, concentrating supply-side capacity among state-funded university consortia.
- Notified body bottleneck:BfArM-authorized conformity assessment bodies face 18-24 month queues for radiation therapy planning system certifications.
- Technical staff scarcity:Medical physics residency programs in Germany graduate fewer than 80 specialists annually, constraining operational scaling for adaptive therapy workflows.
Strategic Opportunities
- Outpatient clinic penetration:Stereotactic body radiotherapy suites in North Rhine-Westphalia's ambulatory oncology networks remain underdeveloped relative to inpatient capacity.
- Flash radiotherapy research:Ultra-high dose rate electron and proton platforms are converging with real-time magnetic resonance guidance at German research hospitals.
- DIN standard harmonization:Updated equipment commissioning protocols create first-mover advantages for vendors with pre-validated quality assurance toolchains.
Industry Challenges
- Legacy linac integration complexity:Adaptive therapy software from competing vendors lacks interoperability with 2015-era hardware installed across German hospital associations.
- Medical physicist training pipeline:University hospital departments compete for the same limited pool of dosimetry specialists certified in Monte Carlo algorithm validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Radiotherapy Market |
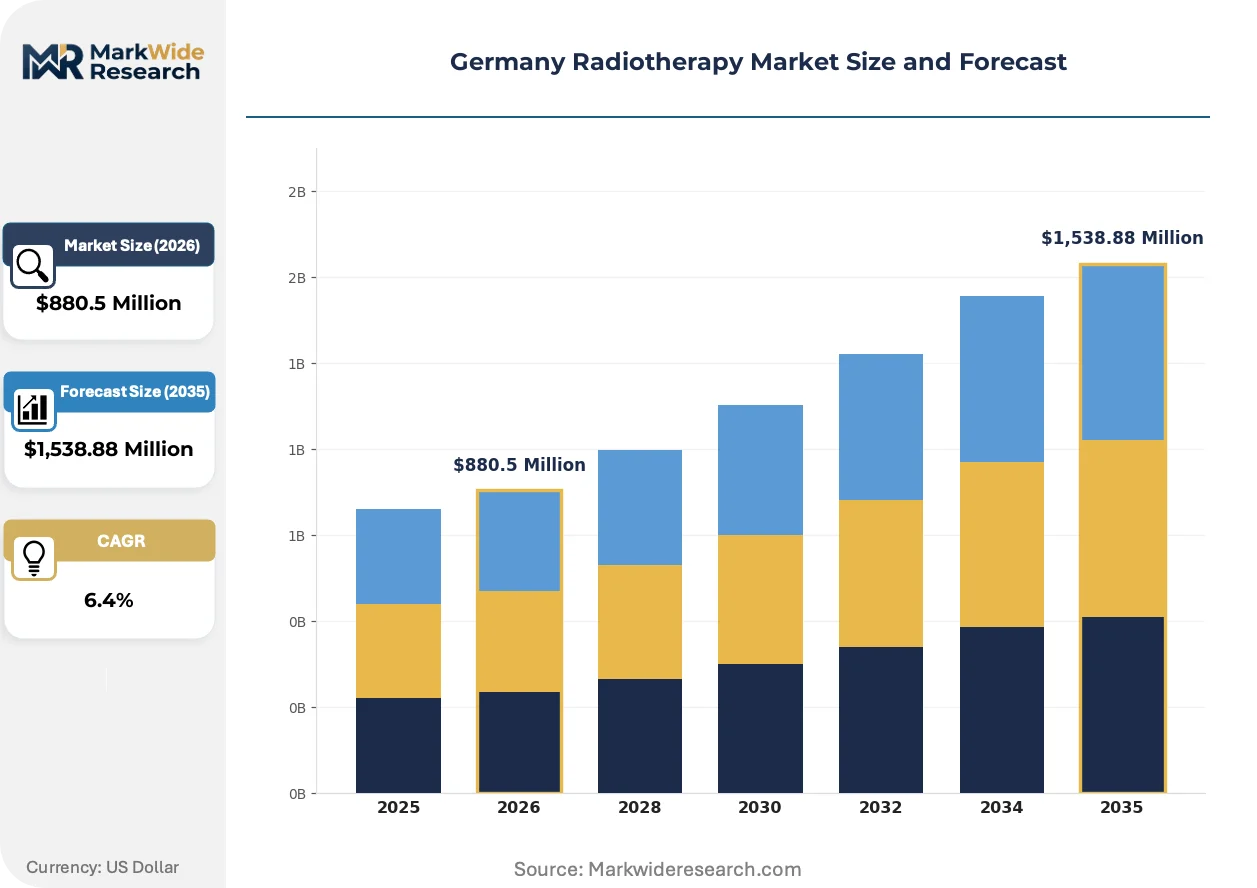
| Market Size in 2026 | $880.5 Million |
| Market Size in 2035 | $1,538.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy Devices, Radiation Therapy Software, Proton Therapy Systems End User: Hospitals, Cancer Treatment Centers, Research Institutions, Outpatient Clinics Technology: Image-Guided Radiotherapy, Intensity-Modulated Radiotherapy, Stereotactic Radiotherapy, 3D Conformational Therapy Application: Oncology, Cardiology, Neurology, Pediatrics |
| Companies Covered | IBA RadioPharma Solutions, Brainlab SE, Siemens Healthineers AG, Curium Pharma, MeVis Medical Solutions AG, Elekta AB, ViewRay, Carl Zeiss Meditec AG, Accuray Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Radiotherapy Market Trends and Innovations
Magnetic resonance-guided radiotherapy systems are collapsing the boundary between diagnostic imaging and therapeutic delivery in German oncology departments. Three distinct vectors are redefining competitive positioning.
MR-linac platforms are supplanting conventional CT-based image guidance in high-value academic centers. University hospitals in Munich and Dresden are adopting 1.5 Tesla integrated systems for soft-tissue visualization during prostate and pancreatic treatments. This displacement is compressing the market for standalone CT-simulator installations while elevating service contract values for cryogen and gradient coil maintenance.
BfArM's guidance on software as a medical device is tightening validation requirements for artificial intelligence-assisted contouring tools. Radiation therapy planning systems must now demonstrate clinical equivalence across patient populations before receiving CE marking under MDR. German university hospital procurement committees are responding by demanding extended pilot periods and outcome-based performance clauses in multi-year service agreements.
Hospital purchasing consortia are consolidating vendor relationships to secure volume discounts on proton therapy service contracts. The Rhineland Hospital Association and Bavarian State Hospital Association are negotiating framework agreements that bundle linear accelerator maintenance with software subscription licenses. This concentration is most visible in North Rhine-Westphalia, where three procurement cooperatives now control equipment decisions for 40 percent of installed radiotherapy capacity.
Germany Radiotherapy Market Segmentation
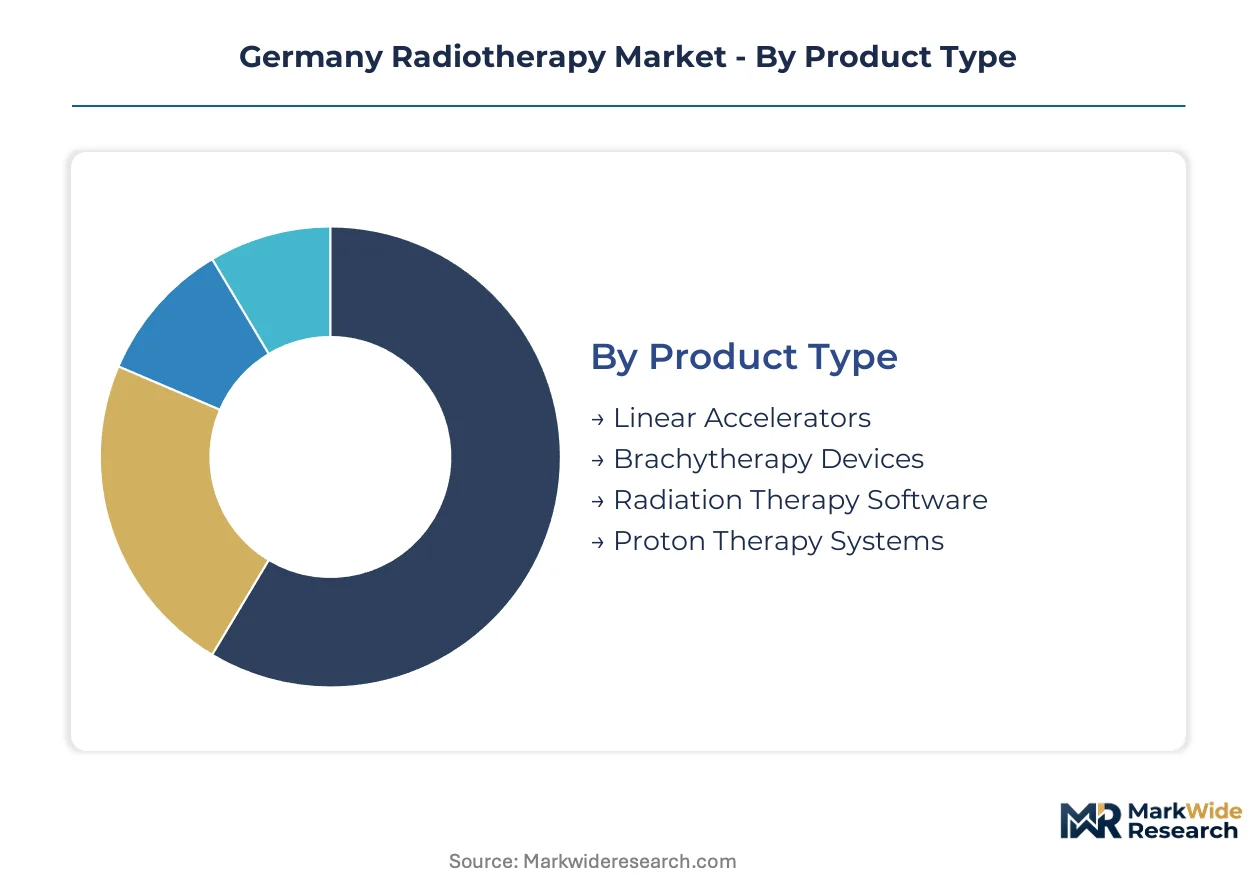
German radiotherapy procurement patterns diver sharply across institutional tiers and technology maturity curves. Understanding these fault lines clarifies where BfArM compliance costs concentrate and which modalities attract Heidelberg-style research investment versus routine clinical deployment.
Product Type:
Domestic manufacturing anchors linear accelerator supply chains through Siemens Healthineers' Forchheim operations, while proton therapy systems depend on cross-border technology licensing from Belgian and American vendors.
- Linear Accelerators:These photon beam systems generate X-ray spectra calibrated to tumoricidal dose distributions through traveling wave or standing wave accelerating structures. Bavarian university hospital networks are consolidating purchases around 6 MV and 10 MV dual-energy platforms capable of flattening-filter-free delivery modes. BfArM's MDR recertification deadlines are accelerating replacement of cobalt-60 teletherapy units installed before 2010.
- Proton Therapy Systems:Cyclotron or synchrotron-based particle accelerators generate Bragg peak dose distributions for pediatric and ocular malignancies. Heidelberg Ion Beam Therapy Center and West German Proton Therapy Centre Essen are expanding treatment room capacity as statutory health insurers validate reimbursement for chordoma and retinoblastoma protocols. Each installation requires €150 million capital commitment and dedicated civil construction for beamline vault shielding.
- Brachytherapy Devices:Afterloading systems deliver Iridium-192 or Cesium-137 sources through applicators positioned in body cavities or interstitial tissue. Gynecological and prostate applications dominate utilization at municipal hospital radiation oncology departments.
- Radiation Therapy Software:Treatment planning systems, contouring algorithms, and dose calculation engines require MDR-compliant software validation through notified body assessment. Monte Carlo-based secondary dose verification is becoming mandatory for stereotactic protocols at German university hospitals.
Linear accelerators command the established base. The steepest expansion runs through proton therapy systems.
End User:
Institutional purchasing power concentrates in state-funded university consortia, while outpatient networks remain fragmented across competing procurement cooperatives.
- Hospitals:General acute care facilities with radiation oncology departments operate linear accelerators for routine fractionation schedules. North Rhine-Westphalia's municipal hospital associations are bundling equipment maintenance contracts to secure volume discounts on Elekta and Varian service agreements.
- Cancer Treatment Centers:Dedicated oncology facilities in Munich, Dresden, and Hamburg integrate multimodal therapy pathways combining surgery, chemotherapy, and precision radiotherapy. These centers capture premium reimbursement rates for hypofractionated stereotactic treatments.
- Research Institutions:German Cancer Research Center and Helmholtz-Zentrum Dresden-Rossendorf operate experimental beam lines for FLASH radiotherapy and carbon-ion therapy development. Federal research ministry funding supports preclinical translation of ultra-high dose rate protocols.
- Outpatient Clinics:Ambulatory radiation oncology practices in Baden-Württemberg and Lower Saxony provide conventional fractionation for prostate and breast malignancies. These facilities face capital constraints for MR-linac adoption and remain dependent on hospital networks for complex stereotactic referrals.
Cancer treatment centers concentrate technology investment. Outpatient clinics present the largest addressable expansion surface.
Technology:
Image guidance sophistication determines reimbursement tier placement, with soft-tissue tracking capabilities commanding premium service contract values.
- Image-Guided Radiotherapy:Cone-beam CT and planar kV imaging integrated into linear accelerator gantries enable daily patient position verification and adaptive replanning. IGRT utilization is standard at German university hospitals performing prostate and lung stereotactic ablative radiotherapy.
- Intensity-Modulated Radiotherapy:Multi-leaf collimator sequencing creates concave dose distributions that spare organs at risk during head-and-neck and gynecological treatments. IMRT has displaced 3D conformal techniques as the reimbursement baseline for complex target geometries.
- Stereotactic Radiotherapy:Sub-millimeter targeting precision delivered through fixed-frame or frameless cranial and extracranial applications. Brainlab's Novalis platforms and CyberKnife installations at Essen and Berlin specialize in spinal and lung oligometastasis protocols.
- 3D Conformational Therapy:Forward-planned beam arrangements using custom cerrobend blocks or multi-leaf collimator shaping. This legacy modality persists in German municipal hospitals with constrained physics staffing and limited adaptive therapy capabilities.
Intensity-modulated radiotherapy anchors routine clinical practice. Stereotactic radiotherapy is climbing the fastest toward standard-of-care status for oligometastatic disease.
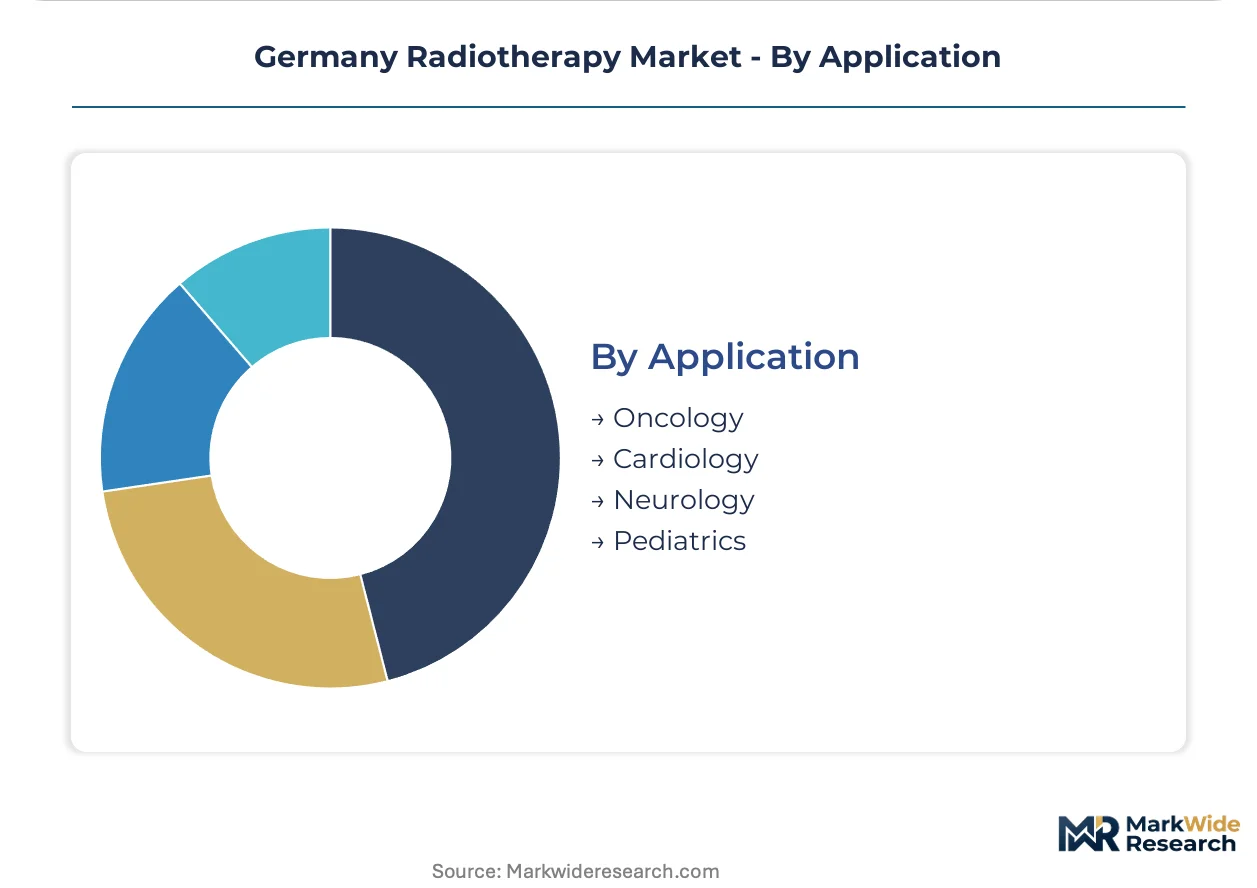
Application:
Oncology reimbursement frameworks subsidize capital equipment across all other therapeutic domains, creating cross-subsidy structures for cardiac and neurological applications.
- Oncology:Curative and palliative radiation protocols for solid tumors and hematological malignancies constitute the overwhelming procedural volume. German statutory health insurance funds reimburse fractionated external beam therapy through diagnosis-related group classifications.
- Cardiology:Ventricular tachycardia ablation using stereotactic radiotherapy is emerging at Heidelberg and Hamburg centers as non-invasive alternative to catheter-based electrophysiology. BfArM has granted provisional reimbursement codes for arrhythmia applications.
- Neurology:Trigeminal neuralgia and arteriovenous malformation radiosurgery utilize Gamma Knife and linear accelerator-based platforms. University hospital neurosurgery departments collaborate with radiation oncology for functional neurosurgery applications.
- Pediatrics:Proton beam therapy minimizes integral dose to developing tissues in medulloblastoma and rhabdomyosarcoma protocols. German Childhood Cancer Registry data supports referral concentration at Heidelberg and Essen proton facilities.
Oncology commands the established base. Cardiology presents the steepest expansion trajectory as electrophysiology-radiation oncology collaboration protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's radiotherapy equipment trade runs a structural surplus in linear accelerator exports while importing proton therapy subsystems from Belgium and the United States. Bavaria and North Rhine-Westphalia absorb the majority of domestic capital deployment, with university hospital networks driving technology adoption cycles.
Bavaria
Munich's university hospital consortium anchors proton therapy demand through the Munich Ion Beam Therapy Center expansion. BfArM's MDR implementation timeline accelerates replacement of legacy cobalt-60 units at municipal facilities in Nuremberg and Augsburg. Siemens Healthineers' Forchheim manufacturing base supplies linear accelerator gantries to hospital associations across southern Germany.
North Rhine-Westphalia
The West German Proton Therapy Centre Essen validates reimbursement pathways for pediatric malignancies through statutory health insurer pilot programs. DIN standards for equipment commissioning shape procurement specifications at the Rhineland Hospital Association. Cologne and Düsseldorf cancer treatment centers are consolidating vendor relationships for bundled linear accelerator maintenance contracts.
Baden-Württemberg
Heidelberg Ion Beam Therapy Center generates clinical outcome data supporting carbon-ion therapy reimbursement expansion. The state's medical physics residency programs at Heidelberg University feed specialist staffing for adaptive therapy workflows. Stuttgart municipal hospitals face capital constraints for MR-linac adoption relative to university-tier facilities.
Lower Saxony
Hannover Medical School operates research beam lines for FLASH radiotherapy development under federal research ministry funding. Outpatient radiation oncology practices in Braunschweig remain dependent on hospital networks for complex stereotactic referrals. The state hospital association bundles conventional linac maintenance to secure volume discounts.
Berlin-Brandenburg
Charité – Universitätsmedizin Berlin integrates multimodal therapy pathways combining surgery, chemotherapy, and precision radiotherapy. The Berlin-Brandenburg hospital procurement cooperative negotiates framework agreements for radiation therapy planning software subscriptions. Gamma Knife installations at Benjamin Franklin Campus specialize in functional neurosurgery applications.
Germany Radiotherapy Market Competitive Landscape
Concentration sits with integrated medical technology conglomerates that combine hardware manufacturing with software platforms. The vendor base stratifies across three tiers: domestic industrial champions with manufacturing footprints, specialized software-hardware integrators focused on neurosurgical applications, and international linear accelerator service providers competing on maintenance density. Strategic moves center on proton therapy capacity expansion through state-funded university consortia and MDR-compliant software revalidation for installed equipment bases.
Within the domestic industrial champion tier, Siemens Healthineers AG anchors linear accelerator supply chains through its Forchheim operations. Brainlab SE and MeVis Medical Solutions AG exemplify the specialized software-hardware integrator archetype, occupying positions in cranial and spinal stereotactic applications. Elekta AB represents the international service-density competitor, sitting within the tier that competes on adaptive workflow integration and maintenance contract penetration across German hospital networks.
| Leading Market Players |
|---|
| IBA RadioPharma Solutions |
| Brainlab SE |
| Siemens Healthineers AG |
| Curium Pharma |
| MeVis Medical Solutions AG |
| Elekta AB |
| ViewRay |
| Carl Zeiss Meditec AG |
| Accuray Inc |
| Others |
Pricing and Supply Chain Analysis
BfArM's MDR certification tiers gate both vendor qualification and price stratification across German radiotherapy procurement, compressing margins for non-compliant equipment while elevating premium capture for pre-validated quality assurance platforms. University hospital networks exploit this bifurcation to extract volume discounts from domestic manufacturers.
Pricing Analysis
Industrial OEM buyers anchor equipment pricing through multi-year framework agreements bundling linear accelerator hardware with software subscription licenses. Three-tier pricing structure across premium, standard, and economy levels separates MDR-validated adaptive therapy platforms from legacy cobalt-60 replacements and refurbished installations. Cost compression in economy-tier municipal hospital contracts is intensifying because BfArM recertification deadlines force synchronous fleet upgrades. Outpatient clinics exhibit highest price sensitivity due to capital constraints for proton therapy adoption, while university consortia command lowest sensitivity through federal research ministry co-funding.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam is elevating inbound logistics costs for proton therapy cyclotron components sourced from Belgium and the United States. Manufacturing concentration centers on Germany for linear accelerator gantries, Belgium for particle therapy subsystems, and the United States for radiation therapy planning software. Supply chain risk manifests as single-source vulnerability for superconducting magnet assemblies in MR-linac platforms. Distribution runs through state hospital association procurement cooperatives that aggregate demand across municipal and university-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as interoperability requirements between radiation therapy planning systems and hospital information systems create winner-take-most dynamics. Vendors must control both hardware commissioning protocols and software validation pipelines to capture recurring revenue streams.
For Market Incumbents: Shield installed base relationships by accelerating MDR-compliant software revalidation for 2015-era linear accelerator hardware before notified body queues extend beyond 24 months. Deepen backward integration into Monte Carlo algorithm development to reduce dependency on third-party dose verification licensing. Priority defensive moves center on locking university hospital networks into exclusive service contracts that bundle maintenance with adaptive therapy workflow upgrades. For New Entrants and Emerging Players: CE marking fast-track through BfArM's software as medical device pathway offers the most penetrable entry vector for AI-assisted contouring tools targeting high-throughput cancer treatment centers in Bavaria and Baden-Württemberg. White-space concentration sits in outpatient stereotactic body radiotherapy suites across North Rhine-Westphalia's ambulatory oncology networks. Go-to-market execution should prioritize pilot partnerships with municipal hospital associations seeking to outsource physics staffing constraints. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across proton therapy center development as Heidelberg-style research consortia demand integrated beamline construction and clinical trial infrastructure. Long-term viability favors acquisition targets with pre-validated quality assurance toolchains and established notified body relationships rather than hardware-only manufacturers. Signal to watch is BfArM guidance on artificial intelligence-assisted contouring reimbursement codes as inflection indicator for software revenue multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Software Revalidation | BfArM compliance deadlines force synchronous upgrades across installed linear accelerator bases. |
| Proton Therapy Capacity Expansion | Heidelberg and Essen centers validate reimbursement pathways for pediatric malignancies. |
| AI Contouring Platform Development | Deep-learning segmentation reduces planning time burdens at Bavarian high-throughput centers. |
| Hospital System Partnership | Rhineland Hospital Association consolidates vendor relationships for bundled maintenance contracts. |
| FLASH Radiotherapy Research Translation | Federal research ministry funding supports preclinical ultra-high dose rate protocol development. |
Research Methodology
Cross-validation between primary interviews with radiation oncology department heads and secondary analysis of BfArM device registration databases anchors the qualitative findings. Stakeholder engagement encompassed medical physicists, hospital procurement committee members, biomedical engineers, GPO contracts managers, and notified body technical assessors. Secondary sources included DIN standards documentation, statutory health insurance reimbursement catalogs, university hospital capital expenditure disclosures, and federal research ministry funding announcements. Bottom-up equipment installation tracking triangulates against top-down market size estimates derived from manufacturer revenue disclosures.
Sensitivity analysis across adoption scenarios for MR-linac platforms and proton therapy capacity expansion shapes the analytical framework. Segmentation dimensions modeled encompass product type, end-user tier, technology sophistication, and application area across the projection horizon. CAGRs derive from equipment replacement cycle analysis, reimbursement pathway validation timelines, and research funding trajectory assessments. Industry-specific forecast inputs include medical physics residency graduation rates and BfArM notified body certification queue lengths.
Decision-makers should treat outputs as directional under assumptions of stable MDR enforcement timelines and continued statutory health insurance reimbursement for particle therapy; material deviation would warrant model refresh. Specific risk factors encompass notified body capacity constraints extending certification delays, proton therapy outcome data failing to support reimbursement expansion, and medical physicist supply shortages constraining adaptive therapy workflow deployment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Angiosarcomas Treatment Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
North America Bone Metastasis Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Glioblastoma Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Global Particle Therapy Market
Oncology
Global Interventional Oncology Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Pituitary Cancer Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Europe Radiotherapy Market
Oncology
Breast Cancer Brachytherapy Market