
 Surgical Smart Glasses Market | 2026-2036
Surgical Smart Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Smart Glasses Market Insights
FDA 510(k) premarket notification and EU MDR Class IIa certification is bifurcating the competitive landscape into compliant incumbents and capital-constrained entrants. Vuzix Corporation leverages in-house waveguide manufacturing to sustain cost advantages across optical see-through architectures. Pixee Medical anchors its position through proprietary augmented reality navigation systems for orthopedic procedures. Iristick competes on modular hardware designs that integrate with existing hospital IT infrastructure across European surgical centers.
Surgical smart glasses comprise wearable optical systems combining micro-displays, sensors, and wireless connectivity to project patient data, anatomical overlays, or remote video feeds into the surgeon's field of view, typically operating at 30-60 frames per second with sub-20 millisecond latency to prevent motion sickness during prolonged procedures. Their primary purpose is reducing cognitive load during complex interventions while enabling real-time collaboration. Augmented reality glasses command the dominant revenue share due to precision overlay requirements in neurosurgery and spine procedures, whereas mixed reality devices represent the fastest-expanding category as academic institutions build immersive surgical training curricula. Head-mounted displays retain mature installed bases in outpatient clinics where cost sensitivity limits upgrade cycles.
FDA, EMA, and EU MDR collectively enforce biocompatibility, electromagnetic compatibility, and optical safety standards that extend development timelines and elevate capital barriers for new entrants. These frameworks shape demand by restricting institutional procurement to certified devices while mandating clinical evidence packages that favor established players with regulatory affairs capacity. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify smart glasses platforms requiring updated conformity assessments.
Market Dynamics
FDA 510(k) clearance timelines and EU MDR Class IIa certification requirements are compressing vendor margins while bifurcating procurement eligibility between compliant incumbents and capital-constrained challengers.
Growth Catalysts
- EU MDR clinical evidence mandates:Academic medical centers in Germany and France accelerate validation partnerships with device manufacturers, creating pull-through demand for certified platforms.
- Orthopedic navigation integration:Spine and joint reconstruction workflows embed augmented reality overlays for pedicle screw placement and implant positioning accuracy.
- Japan METI surgical robotics initiatives:Government funding for intelligent operating theaters drives mixed reality training infrastructure investments across university hospitals.
Market Restraints
- Waveguide manufacturing concentration:Optical engine supply chains cluster in East Asian foundries, exposing procurement to single-source dependencies and input cost volatility.
- FDA biocompatibility testing protocols:Extended skin contact and electromagnetic compatibility validation cycles stretch development budgets for new entrants.
- 2D display substitution:Traditional surgical monitors retain installed bases in cost-sensitive outpatient settings, limiting addressable market expansion.
Strategic Opportunities
- India CDSCO emerging pathway:Regulatory harmonization with IMDRF standards opens institutional procurement channels for mid-tier certified devices.
- Remote surgical mentorship platforms:Real-time video streaming and annotation tools enable telementoring networks connecting tertiary centers with community hospitals.
- 5G-enabled edge computing convergence:Low-latency wireless infrastructure supports cloud-based image processing for intraoperative navigation without local compute hardware.
Industry Challenges
- Optical engineer talent scarcity:Waveguide design and micro-display calibration expertise concentrates in consumer electronics firms, forcing medical device recruiters to compete for limited specialists.
- Legacy EMR integration complexity:Hospital IT departments face multi-month API development cycles to connect smart glasses platforms with existing patient data systems.
- Software-as-medical-device reclassification risk:Evolving FDA guidance on algorithm-based surgical guidance may trigger updated conformity assessments for platforms with AI-enabled overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Smart Glasses Market |
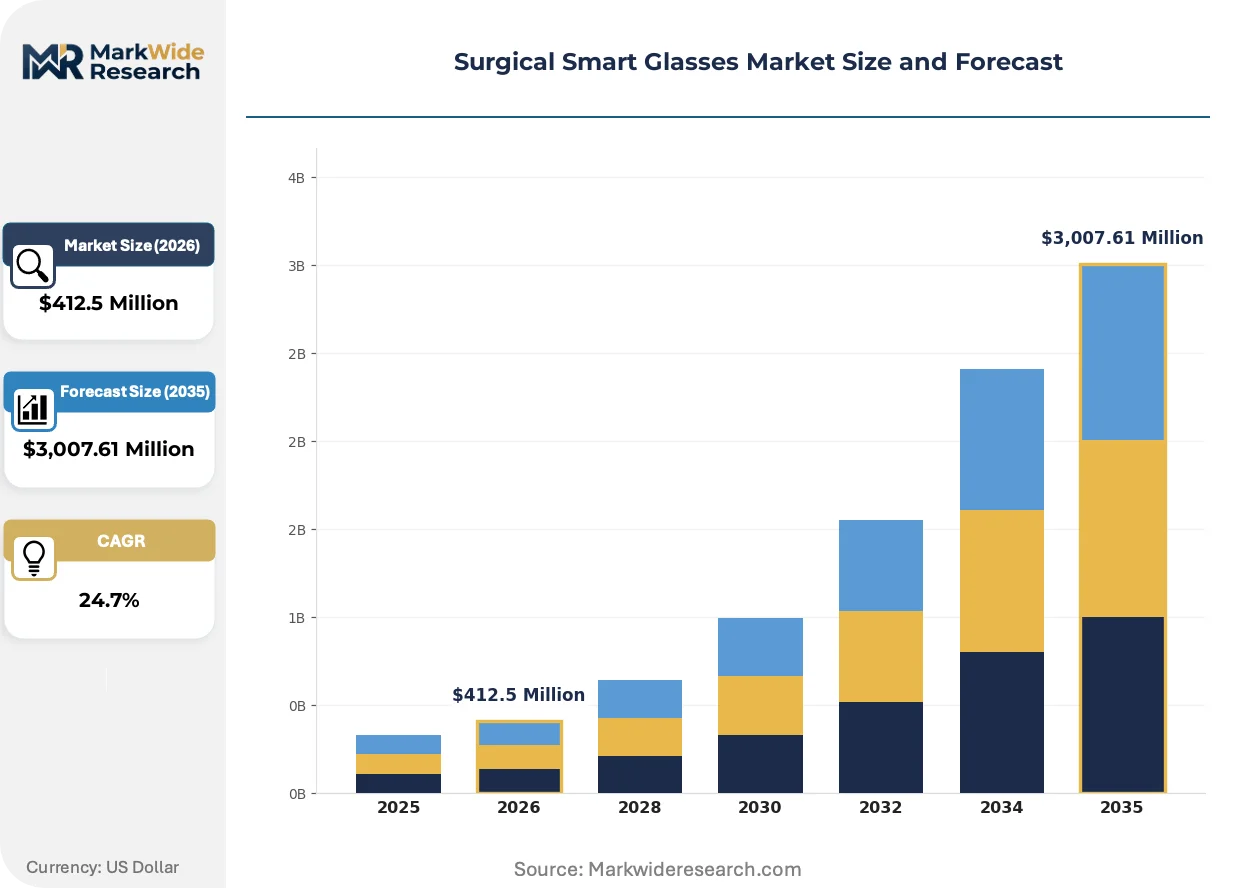
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,007.61 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-mounted Displays, Augmented Reality Glasses, Smart Loupes, Mixed Reality Devices End User: Hospitals, Outpatient Clinics, Surgical Centers, Academic Institutions Technology: Wireless Connectivity, Optical See-through, Digital Overlay, Gesture Recognition Application: Surgical Visualization, Training Simulation, Remote Consultation, Patient Monitoring |
| Companies Covered | MEDITHINQ CO., LTD, Taiwan Main Orthopaedic Biotechnology, Iristick, DTU Srl., Vuzix Corporation, Pixee Medical, RODS AND CONES, Foresee-X, RealWear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Smart Glasses Market Trends and Innovations
Optical see-through architectures are displacing video see-through systems as neurosurgery and spine procedures demand sub-millimeter overlay precision without perceptual latency.
Polymer waveguide substrates with embedded diffractive optical elements are displacing glass-based alternatives in next-generation surgical smart glasses. Academic medical centers in the United States and Germany pilot these lighter-weight platforms for procedures exceeding four hours. The shift is compressing supply chain dependencies on precision glass foundries while enabling new entrants to source optical engines from semiconductor-style contract manufacturers.
EU MDR Annex XIV clinical evaluation requirements are extending post-market surveillance obligations for augmented reality surgical devices. Manufacturers must now generate real-world performance data through implant registries and patient follow-up studies. Spine navigation systems face the steepest compliance burden, driving consolidation of clinical affairs functions among mid-tier vendors unable to sustain expanded regulatory staffing.
Hospital procurement committees are bundling smart glasses acquisitions with multi-year service contracts covering software updates, sterilization protocols, and training certification. Device vendors respond with subscription pricing models that shift revenue recognition from upfront hardware sales to recurring platform fees. This pattern is most pronounced in United States academic medical centers where capital budget constraints favor operational expenditure treatment.
Surgical Smart Glasses Market Segmentation
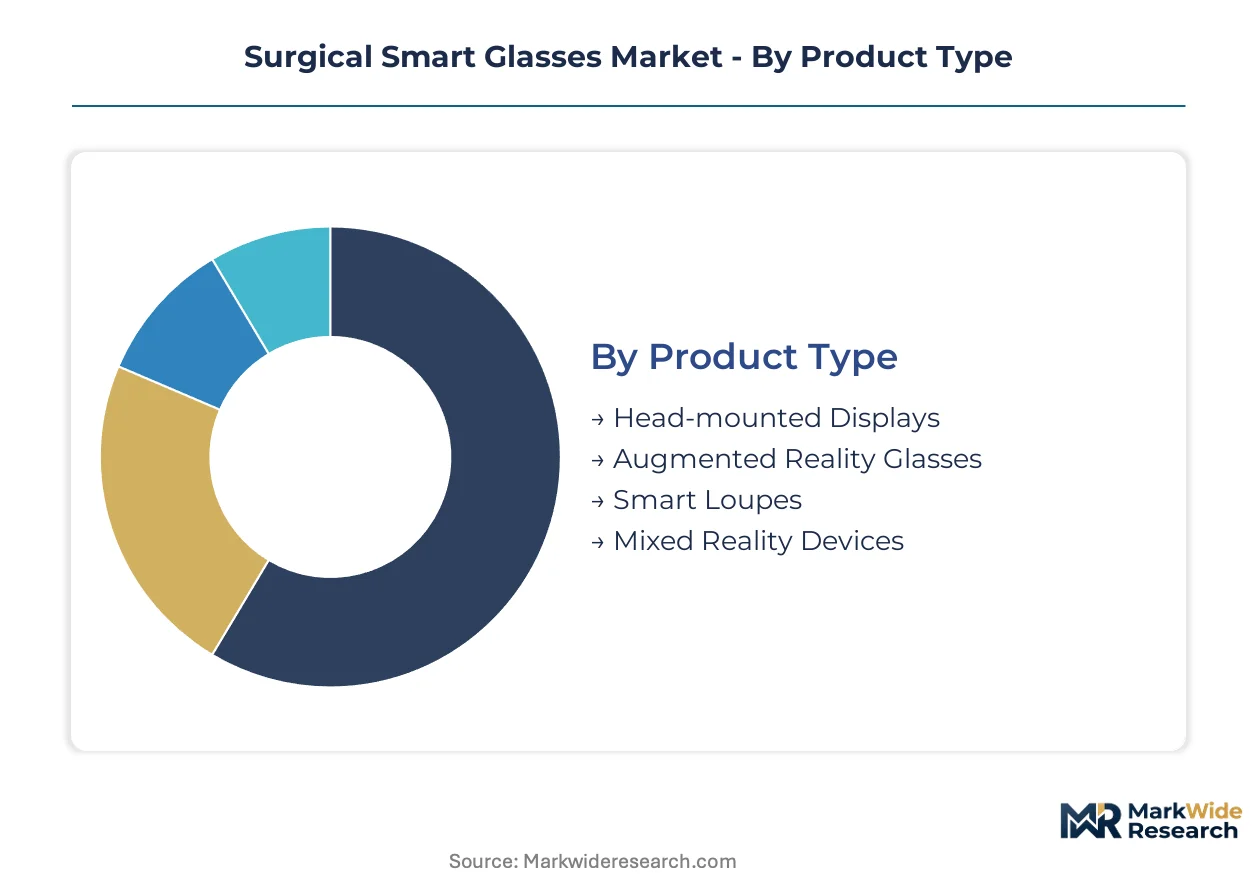
Surgical smart glasses segmentation reveals divergent margin profiles across hardware architectures and institutional buyer tiers. Procurement patterns in Germany and Japan demonstrate how regulatory certification and training infrastructure reshape category priorities.
Product Type:
Margins concentrate in optical engine integration tiers, with waveguide manufacturing depth determining vendor profitability.
- Augmented Reality Glasses:These platforms deploy optical see-through waveguides to project anatomical overlays without obstructing the surgeon's direct field of view. Demand clusters in spine and neurosurgery departments at academic medical centers in Germany and the United States where sub-millimeter registration accuracy commands procurement priority. FDA 510(k) clearance requirements for optical safety and biocompatibility filter vendor eligibility.
- Mixed Reality Devices:Combining spatial mapping with holographic patient models, these systems enable immersive surgical rehearsal and intraoperative navigation. Japanese university hospitals under METI robotics initiatives drive fastest category expansion through curriculum mandates for resident training programs.
- Head-mounted Displays:Video see-through architectures dominate outpatient settings where cost sensitivity limits specification requirements.
- Smart Loupes:Magnification-integrated platforms target microsurgical specialties with embedded camera feeds for documentation.
Augmented Reality Glasses holds installed capacity. Mixed Reality Devices is rotating up the share rankings.
End User:
Procurement authority and capital budget scale determine technology tier access across institutional categories.
- Hospitals:Tertiary centers in the United States and Germany deploy multi-platform fleets across surgical service lines, bundling hardware with multi-year service contracts covering sterilization protocols and software updates. EU MDR Class IIa certification requirements restrict vendor pools to established regulatory affairs teams.
- Academic Institutions:Training curricula and research partnerships drive mixed reality adoption for surgical simulation labs. Japan's government-funded intelligent operating theater programs accelerate infrastructure deployment.
- Surgical Centers:Focused procedure volumes favor single-purpose augmented reality systems for orthopedic navigation.
- Outpatient Clinics:Cost constraints perpetuate 2D monitor substitution, limiting smart glasses penetration to demonstration programs.
Hospitals command procurement volume leadership. Academic Institutions is climbing the fastest as curriculum mandates expand.
Technology:
Architecture choices determine latency performance and supply chain dependencies.
- Optical See-through:Waveguide-based light engines eliminate video processing lag, critical for procedures exceeding four hours. Polymer substrate innovations reduce weight while displacing glass foundry dependencies.
- Wireless Connectivity:5G-enabled edge computing architectures support cloud-based image processing without local compute hardware.
- Digital Overlay:Software-defined projection systems enable rapid protocol updates but require electromagnetic compatibility validation.
- Gesture Recognition:Sterile interface controls reduce scrub-out interruptions during critical procedural phases.
Optical See-through dominates precision applications. Wireless Connectivity is gaining share fastest through infrastructure convergence.
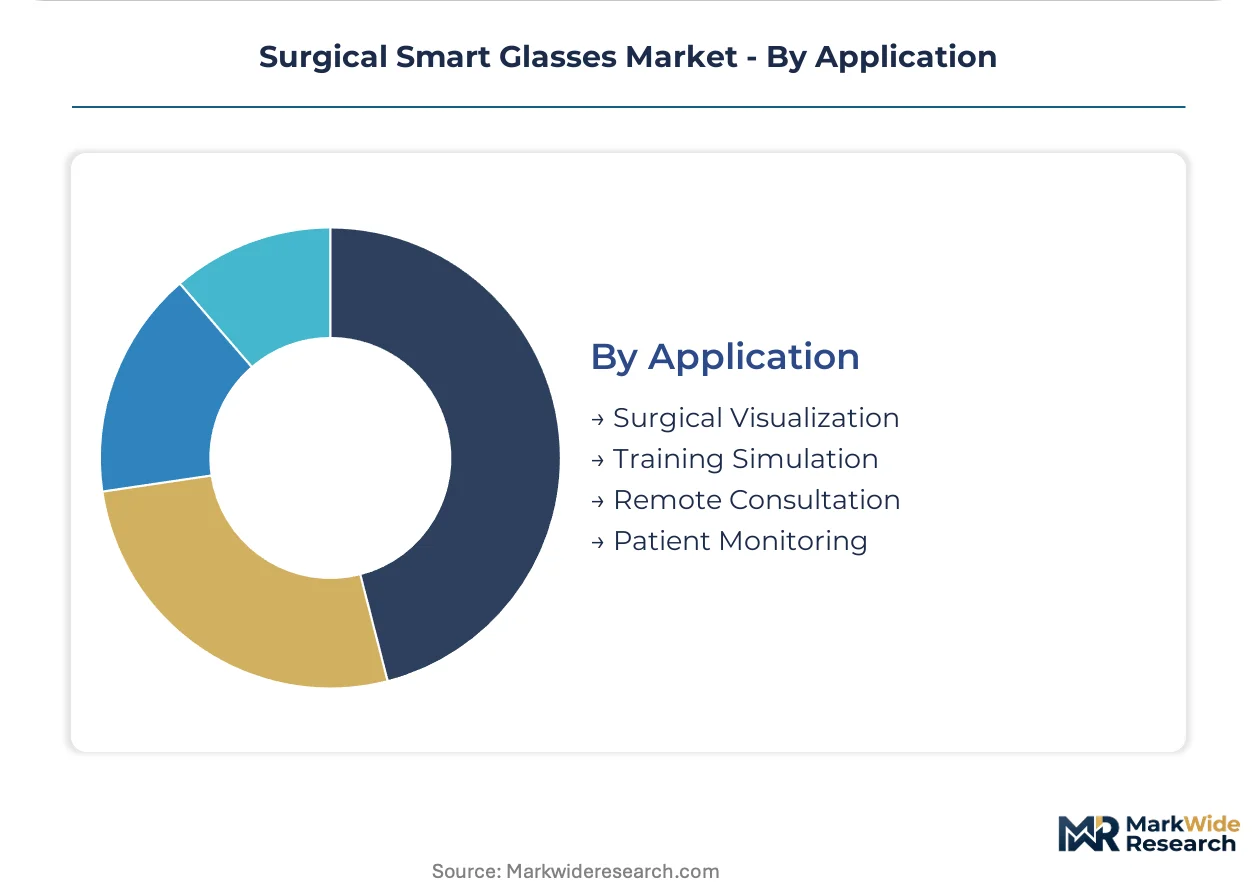
Application:
Use case specificity determines regulatory pathway and evidence generation burden.
- Surgical Visualization:Real-time anatomical overlay for pedicle screw placement and implant positioning drives orthopedic adoption. EU MDR Annex XIV clinical evaluation requirements mandate implant registry linkages for post-market surveillance.
- Training Simulation:Immersive curricula reduce cognitive load for complex procedures. Japanese university hospitals pioneer mixed reality residency requirements.
- Remote Consultation:Telementoring platforms connect tertiary centers with community hospitals through annotated video streams.
- Patient Monitoring:Vital sign projection into the surgical field reduces gaze diversion during critical phases.
Surgical Visualization anchors revenue concentration. Training Simulation is expanding most quickly through academic partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) premarket notification pathways and Japan METI robotics funding programs are accelerating institutional procurement across tertiary surgical centers. Germany's EU MDR compliance investments and India's CDSCO harmonization with IMDRF standards are reshaping vendor eligibility criteria.
United States
Academic medical centers in Boston and Baltimore deploy multi-platform fleets across neurosurgery and spine departments. FDA biocompatibility testing protocols for extended skin contact devices filter vendor pools to established regulatory affairs teams. The Research Triangle Park cluster in North Carolina anchors validation partnerships between device manufacturers and university hospitals.
Germany
University hospitals in Munich and Heidelberg pioneer mixed reality residency curricula under government-funded intelligent operating theater initiatives. EU MDR Annex XIV clinical evaluation requirements mandate implant registry linkages for augmented reality navigation systems. The Baden-Württemberg medical technology corridor concentrates waveguide integration specialists serving orthopedic device vendors.
Japan
METI surgical robotics initiatives channel public funding into mixed reality training infrastructure across Tokyo and Osaka university hospitals. PMDA consultation pathways for software-as-medical-device classifications accelerate conformity assessments for AI-enabled overlay platforms. The Nagoya medical device cluster hosts optical engine calibration facilities for polymer waveguide substrates.
India
CDSCO regulatory harmonization with IMDRF standards opens institutional procurement channels for mid-tier certified devices in Delhi and Mumbai. Government medical colleges in Karnataka and Tamil Nadu pilot telementoring networks connecting tertiary centers with district hospitals. The Hyderabad medical technology park attracts contract manufacturers for optical see-through architectures.
Switzerland
Swissmedic certification requirements for electromagnetic compatibility shape vendor selection at university hospitals in Zurich and Geneva. Private surgical centers in the Lake Geneva region adopt augmented reality systems for orthopedic navigation workflows. The Basel pharmaceutical-medical device corridor funds cross-border validation studies with German academic partners.
Surgical Smart Glasses Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capacity and optical engine manufacturing depth. The vendor base stratifies into three tiers: waveguide-integrated incumbents with FDA 510(k) clearances, modular hardware specialists serving European hospital IT infrastructure, and navigation software providers anchoring orthopedic procedure workflows. Competitive moves concentrate on M&A for clinical affairs talent and strategic partnerships with academic medical centers for real-world evidence generation.
Within the waveguide manufacturing tier, Vuzix Corporation and Pixee Medical exemplify divergent strategic positions. Vuzix anchors optical see-through architectures through in-house production capabilities. Pixee Medical occupies a position within augmented reality navigation systems for orthopedic procedures. Iristick represents the modular hardware archetype, integrating with existing hospital IT infrastructure across European surgical centers.
| Leading Market Players |
|---|
| MEDITHINQ CO., LTD |
| Taiwan Main Orthopaedic Biotechnology |
| Iristick |
| DTU Srl. |
| Vuzix Corporation |
| Pixee Medical |
| RODS AND CONES |
| Foresee-X |
| RealWear |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance and EU MDR Class IIa certification simultaneously gate supply qualification and stratify price tiers across vendor pools. Hospitals restrict procurement to certified devices while manufacturers absorb extended validation costs, compressing margins for capital-constrained entrants and amplifying pricing power for compliant incumbents with regulatory affairs scale.
Pricing Analysis
Certification level (FDA 510(k)-cleared vs. CE-marked vs. uncertified) creates the primary spread between vendor tiers. Three-tier pricing structure across premium, standard, and economy levels reflects optical engine performance, waveguide substrate material, and bundled service contract duration. Cost compression in mid-tier systems is intensifying because polymer waveguide innovations enable new entrants to bypass glass foundry dependencies. Outpatient clinics exhibit highest price sensitivity, while academic medical centers in Germany and Japan prioritize precision specifications over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate optical engine procurement, though strategic stockpiling of polymer waveguide substrates is emerging among tier-one vendors. Manufacturing concentrates in China, Taiwan, and South Korea for micro-display calibration and diffractive optical element fabrication. Raw material dependencies include rare-earth phosphors, precision glass substrates, and semiconductor-grade polymers. Single-source vulnerability in East Asian foundries exposes procurement to geopolitical disruption. Distribution runs through specialized medical device distributors serving hospital procurement committees and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat where FDA and EU MDR entrenchment creates switching costs that lock hospitals into validated vendor relationships. Network effects from training infrastructure and EMR integration deepen incumbent advantages.
For Market Incumbents: Compound regulatory certification depth with backward integration into waveguide manufacturing to defend against modular hardware specialists. Expand clinical affairs staffing to satisfy EU MDR Annex XIV post-market surveillance mandates for spine navigation systems. Prioritize multi-year service contract bundling to shift revenue toward recurring platform fees and reduce capital budget friction at academic medical centers. For New Entrants and Emerging Players: Anchor in India's CDSCO-harmonized procurement channels where regulatory barriers remain lower than FDA or EU MDR pathways. Target telementoring platforms for community hospitals in Karnataka and Tamil Nadu as the most penetrable white-space segment. Pursue white-label optical engine partnerships with Taiwanese contract manufacturers to bypass capital-intensive in-house waveguide fabrication. For Investors and Strategic Acquirers: EU MDR clinical evidence mandates reshape the acquisition landscape toward targets with established implant registry linkages and regulatory affairs capacity. Five-to-ten-year viability favors vendors with software-as-medical-device conformity pathways and 5G-enabled edge computing architectures. Monitor FDA guidance evolution on AI-enabled surgical overlays as the critical inflection signal for platform reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Fast-track clearance for optical see-through platforms reduces time-to-revenue for waveguide-integrated vendors. |
| EU MDR Clinical Evidence Partnership | Academic medical center collaborations in Munich and Heidelberg generate implant registry data for post-market surveillance compliance. |
| Polymer Waveguide Supply Agreement | Semiconductor-style contract manufacturing agreements displace precision glass foundry dependencies. |
| Hospital IT Infrastructure Integration | API development partnerships with EMR vendors reduce multi-month procurement cycles for smart glasses deployment. |
| 5G Edge Computing Convergence | Telecommunications infrastructure investments in Tokyo and Osaka enable cloud-based intraoperative navigation without local hardware. |
Research Methodology
The analysis maps optical see-through architectures, mixed reality training platforms, and video see-through systems, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists. Primary interviews with waveguide manufacturing specialists and orthopedic navigation system users combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and METI robotics initiative disclosures. Bottom-up vendor revenue aggregation and top-down addressable market sizing were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, end-user institution type, application use case, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to historical certification timelines and procurement cycle data. Forecast inputs incorporated polymer waveguide substrate adoption rates and 5G infrastructure deployment trajectories in target hospital systems.
Material uncertainties — regulatory reclassification of software-as-medical-device platforms, waveguide supply disruption, and EMR integration timeline delays — sit outside the modeled envelope. Forecasts reflect assumptions about certification pathway stability and hospital capital budget allocation patterns. Revision becomes warranted when FDA guidance on AI-enabled overlays crosses thresholds triggering updated conformity assessments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Diabetic Eye Disease Devices Market
Medical Devices
Interlaminar Device Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Medical Thermometer Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Solar Surgical Light Market