
 China Precision Medicine Market | 2026-2036
China Precision Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
China Precision Medicine Market Insights
Hospital procurement channels for molecular diagnostics is fragmenting as regional health authorities decentralize purchasing authority. BGI Genomics dominates domestic sequencing infrastructure through massive genomics centers in Shenzhen and Tianjin. WuXi AppTec leverages its integrated CRO platform to anchor companion diagnostic development for multinational pharmaceutical clients. Berry Genomics specializes in non-invasive prenatal testing and extends its reach through direct partnerships with provincial maternity hospitals.
China precision medicine applies genomic profiling, biomarker analysis, and targeted therapeutic design to tailor prevention and treatment strategies to individual patient molecular signatures, utilizing next-generation sequencing platforms capable of whole-exome analysis at sub-thousand-dollar price points. Companion diagnostics represents the most mature revenue pool as pharmaceutical sponsors require co-development pathways for targeted oncology agents. Bioinformatics is accelerating fastest as cloud-based variant interpretation pipelines reduce turnaround times for clinical reports. Genetic testing occupies the broadest patient touchpoint but faces margin compression from provincial centralized tendering.
NMPA oversees in vitro diagnostic registration through its Center for Medical Device Evaluation, while the National Health Commission issues clinical application guidelines that determine which precision tests qualify for reimbursement. China's dual carbon goals are reshaping laboratory energy standards, indirectly affecting sequencing facility operating costs in high-throughput centers. Stakeholders must monitor how municipal basic medical insurance catalogs incorporate next-generation sequencing panels versus excluding them as out-of-pocket services.
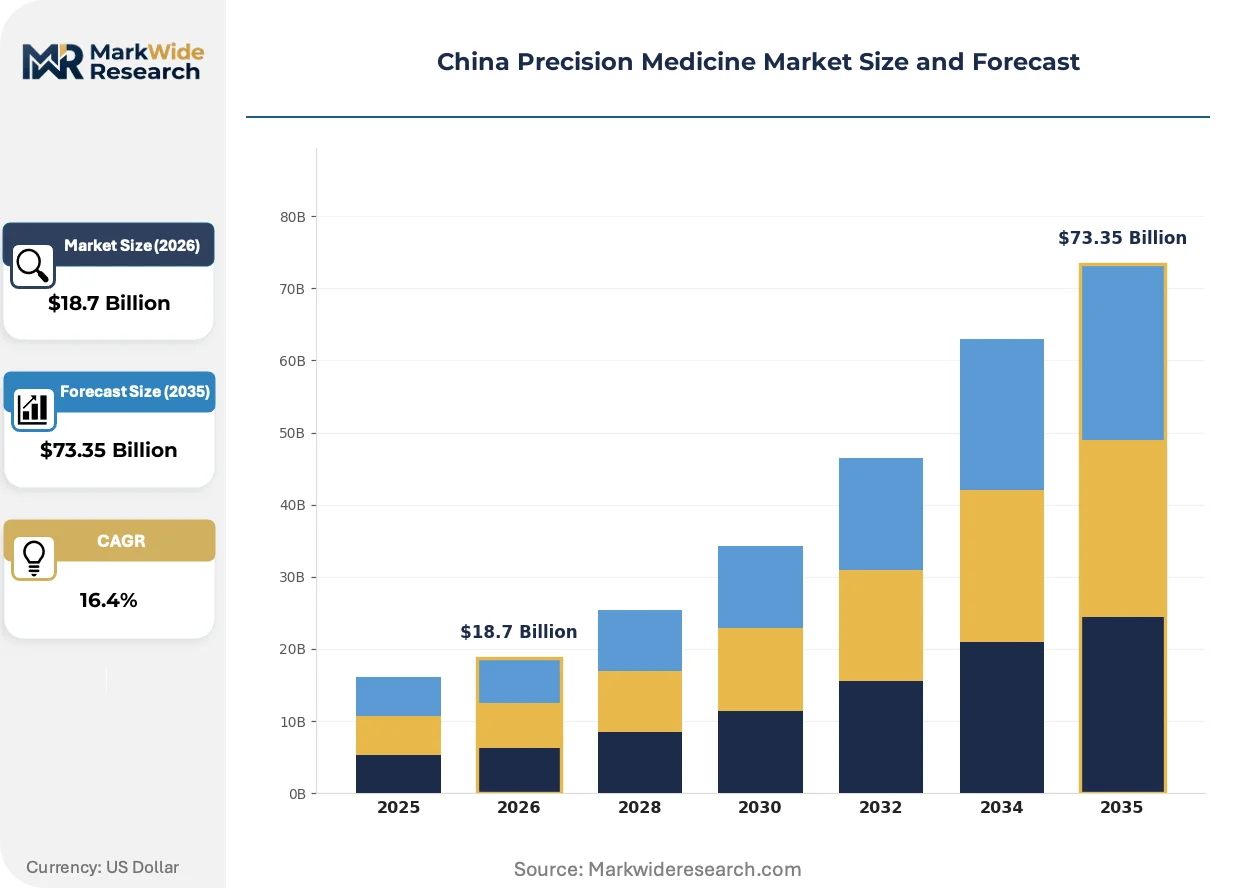
Market Dynamics
Hospital procurement decentralization is fragmenting molecular diagnostic channels as provincial health authorities gain independent purchasing authority under NMPA guidance, reshaping how sequencing platforms and companion diagnostics reach clinical laboratories.
Growth Catalysts
- Dual carbon goals:MEE laboratory energy standards are accelerating facility upgrades in high-throughput sequencing centers, creating replacement demand for efficient instrumentation.
- Oncology molecular profiling:Tertiary hospitals are expanding NGS-based tumor boards under National Health Commission reimbursement guidelines for targeted therapy selection.
- Cloud bioinformatics pipelines:Variant interpretation automation is compressing clinical report turnaround from weeks to days across Beijing and Shanghai hospital networks.
Market Restraints
- Sequencing reagent import dependency:Domestic supply chains for library preparation kits remain concentrated among foreign manufacturers, exposing margins to currency fluctuation.
- Provincial tendering compression:Centralized procurement in maternity hospitals is squeezing non-invasive prenatal testing margins below sustainable levels for mid-tier laboratories.
- Reimbursement exclusion risk:Municipal basic medical insurance catalogs frequently classify whole-exome sequencing as out-of-pocket services, limiting patient access.
Strategic Opportunities
- Western province hospital penetration:Sichuan and Shaanxi tertiary centers lack molecular pathology infrastructure, creating first-mover advantage for platform providers.
- Companion diagnostic co-development:Multinational pharmaceutical sponsors require NMPA-registered CDx pathways for oncology agent approval, opening CRO partnerships.
- CRISPR diagnostic convergence:Beijing biotech clusters are integrating gene editing with point-of-care platforms for infectious disease screening beyond oncology.
Industry Challenges
- Bioinformatics talent scarcity:Clinical interpretation of somatic variants requires hybrid pathology-computational expertise that training programs have failed to produce at scale.
- NMPA registration timelines:In vitro diagnostic classification disputes delay commercial launch by 18-24 months for novel biomarker panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Precision Medicine Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Testing, Biomarkers, Targeted Therapies, Companion Diagnostics Delivery Mode: Home Care, Hospitals, Clinics, Laboratories End User: Pharmaceutical Companies, Research Institutions, Healthcare Providers, Patients Technology: Next-Generation Sequencing, Microarray, CRISPR, Bioinformatics |
| Companies Covered | F Hoffmann-La Roche AG, BGI Genomics, Amoy Diagnostics, Berry Genomics, WuXi AppTec, New Horizon Health Ltd, Zhongyuan Union Stem Cell Bioengineering, Thermo Fisher Scientific, Illumina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Precision Medicine Market Trends and Innovations
Clinical genomics is pivoting from research-grade sequencing toward regulated diagnostic workflows as reimbursement pressure forces laboratories to demonstrate cost-effectiveness per quality-adjusted life year.
Third-generation sequencing is migrating from academic research centers into clinical microbiology laboratories for rapid pathogen identification. Municipal CDC networks in Guangdong and Jiangsu are piloting nanopore platforms for outbreak surveillance. This migration is compressing the competitive window for culture-based diagnostic methods in infectious disease workflows.
NMPA's Center for Medical Device Evaluation issued streamlined guidance for tumor mutation burden companion diagnostics in 2023. Domestic pharmaceutical sponsors now integrate CDx development earlier into clinical trial design. Oncology therapeutic developers face compressed timelines to align biomarker strategies with regulatory submission requirements.
Direct hospital contracting is displacing distributor intermediaries for high-throughput sequencing instruments. Provincial procurement consortia in Zhejiang and Jiangsu negotiate volume pricing directly with manufacturers. This channel consolidation concentrates negotiating leverage among tier-one tertiary hospitals while marginalizing smaller regional laboratories.
China Precision Medicine Market Segmentation
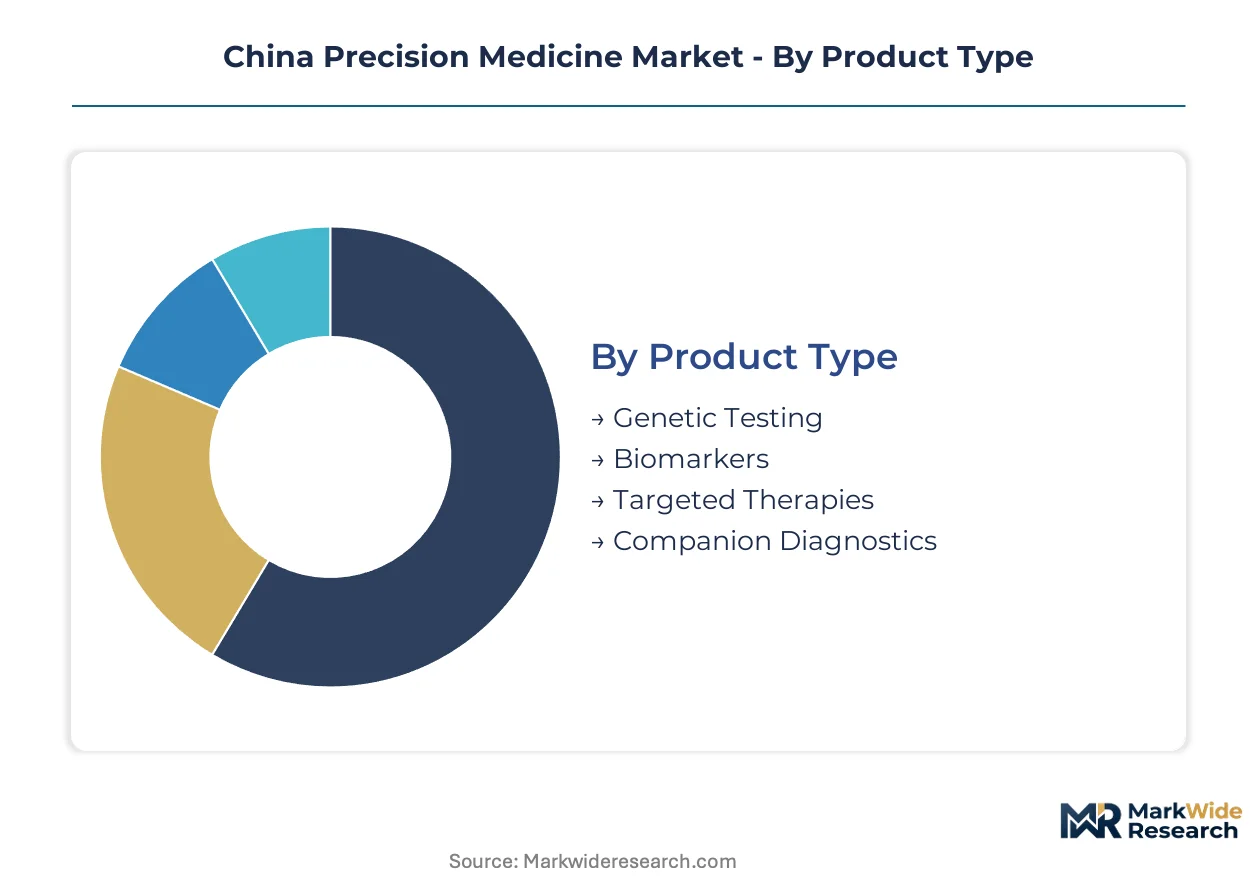
Precision medicine market segmentation reveals distinct service intensity profiles across product categories. After-sales support requirements vary dramatically between instrument-heavy sequencing platforms and consumable-based testing kits. Understanding these structural differences shapes vendor profitability and customer retention strategies.
Product Type:
After-sales-service intensity peaks with sequencing instrumentation requiring continuous calibration and bioinformatics support, while reagent kits demand minimal technical intervention.
- Genetic Testing:Non-invasive prenatal screening and hereditary cancer panels dominate patient volumes. Provincial maternity hospitals in Guangdong and Sichuan drive demand as centralized tendering expands coverage to tier-two cities. Margin compression from volume-based procurement is forcing laboratories toward automated sample processing.
- Biomarkers:Protein and metabolite signatures guide therapeutic selection in oncology and autoimmune conditions. Tertiary hospital pathology departments in Beijing and Shanghai are consolidating biomarker testing into centralized platforms to reduce per-test costs.
- Targeted Therapies:Small-molecule inhibitors and monoclonal antibodies require companion diagnostic validation before reimbursement approval.
- Companion Diagnostics:NMPA-registered CDx pathways anchor pharmaceutical co-development agreements.
By volume, Genetic Testing leads. By growth pace, Companion Diagnostics is expanding most quickly.
Delivery Mode:
Cost tier differentiation separates capital-intensive hospital installations from distributed laboratory networks and emerging direct-to-consumer channels.
- Home Care:Saliva-based collection kits for pharmacogenomics and wellness screening bypass clinical infrastructure. Direct-to-consumer operators face NMPA classification uncertainty as regulators determine whether sample collection constitutes medical device use.
- Hospitals:Tertiary oncology centers anchor molecular tumor board infrastructure under National Health Commission reimbursement guidelines. Beijing Cancer Hospital and Fudan University Shanghai Cancer Center operate the highest-throughput NGS laboratories.
- Clinics:Community health centers lack pathology infrastructure for precision medicine adoption.
- Laboratories:Independent reference laboratories process samples from multiple hospital systems under regional contracts.
By installed base, Hospitals dominate. By expansion trajectory, Home Care is gaining share fastest.
End User:
Customer type determines procurement authority and pricing leverage, with pharmaceutical sponsors commanding co-development terms unavailable to other segments.
- Pharmaceutical Companies:Multinational sponsors require NMPA-registered companion diagnostics for oncology agent approval. WuXi AppTec and domestic CROs anchor CDx development partnerships through integrated discovery-to-registration platforms.
- Research Institutions:Academic medical centers operate research-grade sequencing for translational studies without diagnostic claims.
- Healthcare Providers:Hospital pathology departments face capital constraints for platform upgrades.
- Patients:Out-of-pocket payment for whole-exome sequencing limits access outside affluent urban centers.
By contract value, Pharmaceutical Companies lead. By patient touchpoint volume, Healthcare Providers are ahead.
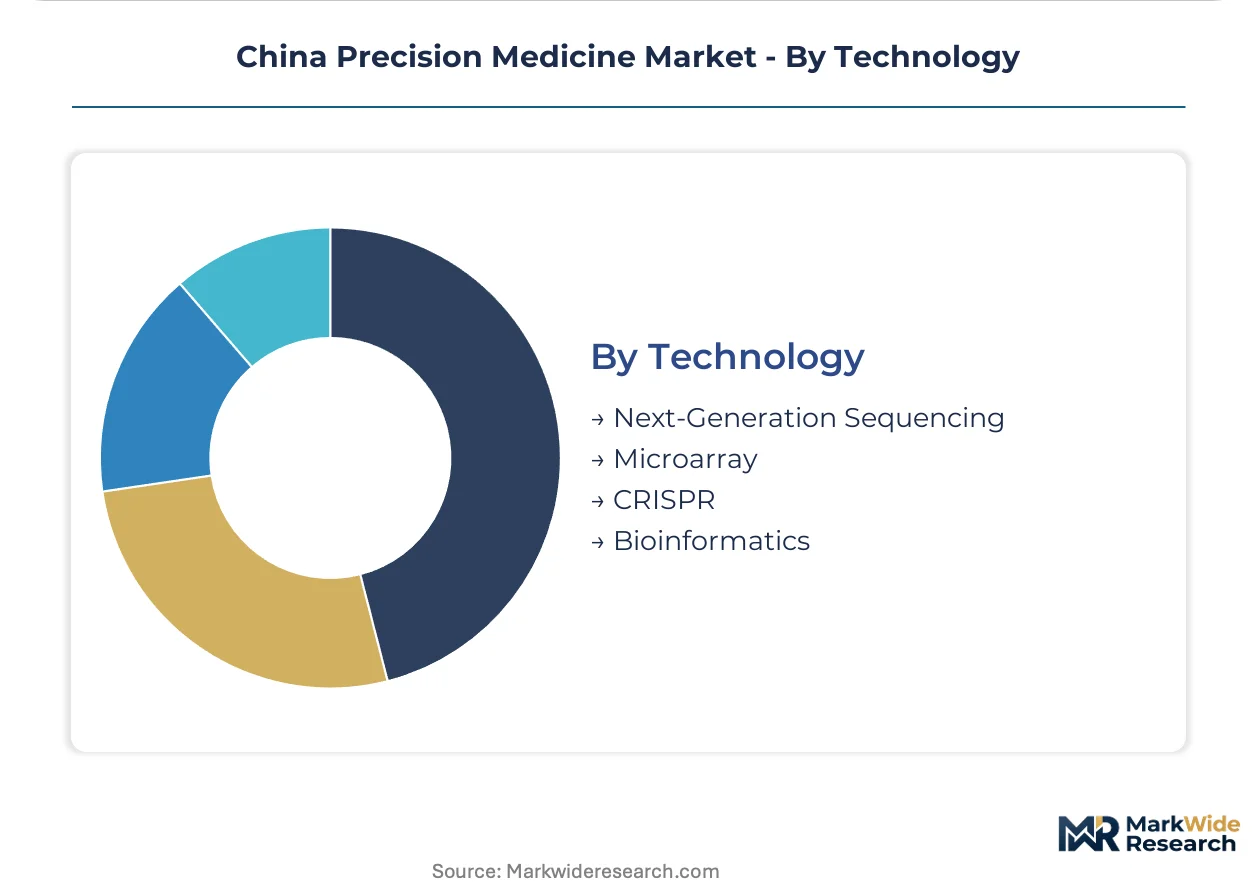
Technology:
Supply concentration varies sharply across technology platforms, with domestic vendors capturing bioinformatics while sequencing hardware remains import-dependent.
- Next-Generation Sequencing:Short-read platforms from Illumina and MGI dominate clinical diagnostics. BGI Genomics operates massive genomics centers in Shenzhen and Tianjin with installed capacity exceeding regional demand.
- Microarray:SNP arrays retain cost advantages for pharmacogenomics screening in community settings. Domestic manufacturers are displacing foreign suppliers for constitutional cytogenetics applications.
- CRISPR:Gene-editing diagnostics concentrate in Beijing biotech clusters for infectious disease point-of-care development.
- Bioinformatics:Cloud-based variant interpretation pipelines reduce clinical report turnaround from weeks to days.
By revenue concentration, Next-Generation Sequencing leads. By capability expansion, Bioinformatics shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National Health Commission reimbursement guidelines and municipal basic medical insurance catalog expansions are directing precision medicine infrastructure toward western provinces previously lacking molecular pathology capacity.
Yangtze River Delta
Shanghai and Jiangsu tertiary oncology centers operate the highest-throughput NGS laboratories for molecular tumor boards. Provincial procurement consortia negotiate volume pricing directly with manufacturers under NMPA guidance. Suzhou and Hangzhou biotech parks host companion diagnostic co-development facilities serving multinational pharmaceutical sponsors.
Pearl River Delta
Guangdong maternity hospitals drive non-invasive prenatal testing volumes through centralized tendering expanded to tier-two cities. Municipal CDC networks pilot nanopore platforms for infectious disease outbreak surveillance. Shenzhen anchors BGI Genomics' massive genomics centers with installed capacity exceeding regional demand.
Beijing-Tianjin-Hebei
CRISPR-based diagnostic development concentrates in Beijing biotech clusters for point-of-care infectious disease screening beyond oncology. Tianjin houses high-throughput sequencing facilities facing dual carbon goal compliance pressure from MEE laboratory energy standards. Hebei provincial hospitals lack molecular profiling infrastructure, creating equipment installation opportunities.
Sichuan-Chongqing
Tertiary centers in Chengdu and Chongqing lack molecular pathology infrastructure, creating first-mover advantage for platform providers expanding westward. Western province hospital penetration strategies target this corridor for companion diagnostic adoption. Local health authorities are decentralizing purchasing authority under NMPA guidance, fragmenting procurement channels.
Shandong Peninsula
Qingdao and Jinan hospital networks are consolidating biomarker testing into centralized platforms to reduce per-test costs. Provincial maternity hospitals face margin compression from centralized tendering for genetic testing services. Municipal basic medical insurance catalogs in this region frequently classify whole-exome sequencing as out-of-pocket services.
China Precision Medicine Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: massive genomics infrastructure operators, integrated CRO-to-diagnostic platforms, and specialized testing service laboratories. Strategic archetypes include domestic sequencing giants with captive instrument capacity, multinational diagnostic divisions leveraging global assay portfolios, and emerging CRISPR diagnostic specialists. Competitive positioning depends on NMPA registration velocity and direct hospital contracting relationships displacing distributor intermediaries.
Among domestic platform operators, BGI Genomics exemplifies the infrastructure-heavy archetype through its Shenzhen and Tianjin genomics centers. WuXi AppTec occupies the integrated CRO position anchoring companion diagnostic development partnerships. Berry Genomics represents the specialized testing model extending reach through direct provincial maternity hospital partnerships. These three patterns illustrate how vendor positioning aligns with reimbursement channel access and regulatory pathway expertise.
| Leading Market Players |
|---|
| F Hoffmann-La Roche AG |
| BGI Genomics |
| Amoy Diagnostics |
| Berry Genomics |
| WuXi AppTec |
| New Horizon Health Ltd |
| Zhongyuan Union Stem Cell Bioengineering |
| Thermo Fisher Scientific |
| Illumina |
| Others |
Pricing and Supply Chain Analysis
The Beijing-Shanghai-Tianjin freight corridor carries sequencing reagents and consumables at rates that compress margins for inland laboratories while coastal genomics centers exploit port-proximity cost advantages to sustain three-tier pricing stratification across NMPA-registered, provincial-lab-grade, and research-use-only product tiers.
Pricing Analysis
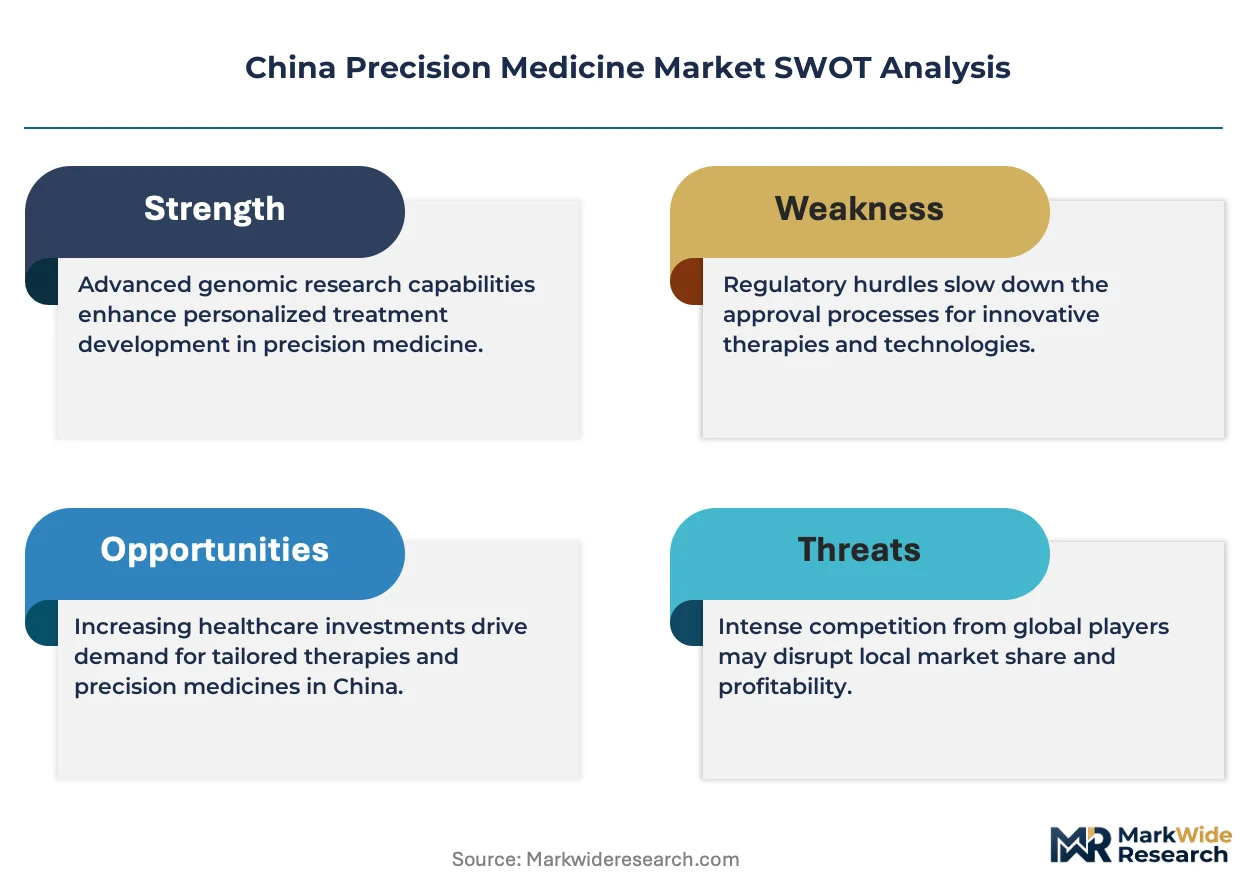
Certification level (NMPA Class III versus Class II versus research-grade) creates the primary spread between premium companion diagnostic kits and economy-tier screening panels. Pricing stratifies across premium, standard, and economy tiers based on registration status, after-sales bioinformatics bundling, and volume commitment scale. Cost compression in economy-tier genetic testing intensifies because provincial maternity hospital tendering mandates 30-40% year-on-year price reductions. Pharmaceutical sponsors exhibit the lowest price sensitivity given co-development timeline pressures, while independent reference laboratories face severe margin squeeze from centralized procurement.
Supply Chain Analysis
Extended payment terms from 90 to 180 days dominate supplier-financing arrangements as domestic distributors absorb working capital strain to maintain Illumina and MGI instrument inventory. Sequencing hardware supply concentrates in the United States and China, while library preparation reagents draw from Singapore and Germany manufacturing bases. Single-source vulnerability pervades flow-cell production, where one California-based supplier anchors global clinical-grade output. Distribution runs through provincial procurement consortia that negotiate directly with manufacturers, marginalizing traditional distributor networks in Zhejiang and Jiangsu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as western province hospital decentralization unlocks molecular pathology infrastructure buildout previously concentrated in coastal megacities.
For Market Incumbents: Pre-empt CRISPR diagnostic convergence by anchoring point-of-care development partnerships with Beijing biotech clusters before regulatory pathways solidify. Secure NMPA registration velocity advantage through early biomarker panel submissions, as 18-24 month approval timelines create defensive moats against late entrants. Deepen backward integration into cloud bioinformatics pipelines to reduce third-party variant interpretation costs. For New Entrants and Emerging Players: Establish a beachhead in Sichuan-Chongqing tertiary centers where molecular pathology infrastructure gaps create first-mover equipment installation opportunities. Target companion diagnostic co-development for domestic oncology agents, as multinational pharmaceutical sponsors require NMPA-registered pathways. Deploy direct hospital contracting models that bypass distributor intermediaries already squeezed by provincial procurement consortia. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational diagnostic divisions seeking to monetize non-core assay portfolios amid China localization mandates. Long-term viability hinges on regulatory pathway expertise and reimbursement channel access rather than pure technology differentiation. Watch municipal basic medical insurance catalog expansions for whole-exome sequencing as the signal for patient access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Pathway | Companion diagnostic approval unlocks pharmaceutical co-development revenue streams under National Health Commission guidelines. |
| Western Province Hospital Partnership | Sichuan and Shaanxi infrastructure gaps create equipment installation first-mover advantage for platform providers. |
| Cloud Bioinformatics Pipeline Integration | Variant interpretation automation compresses clinical report turnaround from weeks to days across Beijing hospital networks. |
| Direct Procurement Consortium Engagement | Zhejiang and Jiangsu volume pricing negotiations displace distributor intermediaries for high-throughput sequencing instruments. |
| CRISPR Diagnostic Platform Development | Beijing biotech clusters integrate gene editing with point-of-care platforms for infectious disease screening beyond oncology. |
Research Methodology
Desk research of NMPA registration databases, National Health Commission reimbursement circulars, and provincial procurement consortium tender documents preceded structured interviews with hospital pathology directors, pharmaceutical regulatory affairs leads, companion diagnostic development executives, and independent reference laboratory operators. Primary fieldwork with tertiary oncology center procurement committees and CRO platform managers was cross-validated against customs trade data for sequencing instrument imports and genomics center capacity disclosures. Bottom-up patient volume modeling and top-down pharmaceutical pipeline alignment were triangulated to anchor market sizing.
Assumptions held fixed across the modeling period include NMPA regulatory framework continuity, municipal basic medical insurance catalog expansion trajectory, and dual carbon goal compliance timelines for laboratory energy standards. Segmentation dimensions encompassed product type, delivery mode, end user category, and technology platform, with regional regulatory cluster variations incorporated for western province penetration modeling. CAGRs were derived from patient access expansion curves and pharmaceutical sponsor pipeline conversion rates, calibrated against historical NGS adoption patterns in tertiary hospital networks.
Stress conditions across reimbursement exclusion risk, sequencing reagent import tariff exposure, and bioinformatics talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory velocity and provincial procurement decentralization. Macroeconomic contraction, NMPA classification disputes, or CRISPR diagnostic platform disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market