
 Single-Room Proton Therapy Systems Market | 2026-2036
Single-Room Proton Therapy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Room Proton Therapy Systems Market Analytics
The capital-intensity divergence between single-room proton therapy developers is reorganizing competitive tiers across the installed base. IBA leverages its cyclotron manufacturing depth to control component sourcing for compact gantries. Mevion Medical Systems anchors its position through superconducting synchrocyclotron specialization that shrinks vault footprints.
Single-room proton therapy systems integrate proton accelerators, beam delivery nozzles, and patient positioning hardware within shielded vaults requiring roughly 30% less construction volume than multi-room facilities. These systems direct Bragg peak energy deposition to spare healthy tissue during radiation oncology treatment. Compact systems occupy the fastest-growing product tier as hospital real estate constraints intensify in urban cores. Gantry-based configurations still dominate existing revenue pools because rotational beam angles support complex pediatric and cranial-spinal protocols that command premium reimbursement.
FDA 510(k) and de novo pathways govern radiation therapy device clearance, while state-level Certificate of Need regulations in New York, Illinois, and Washington constrain where proton centers deploy. The Nuclear Regulatory Commission oversees radioactive material licensing for cyclotron isotope production, adding compliance layers that shape site selection timelines. Stakeholders must monitor how CMS proton therapy reimbursement coding revisions affect hospital capital committee prioritization relative to photon-based alternatives.
Market Dynamics
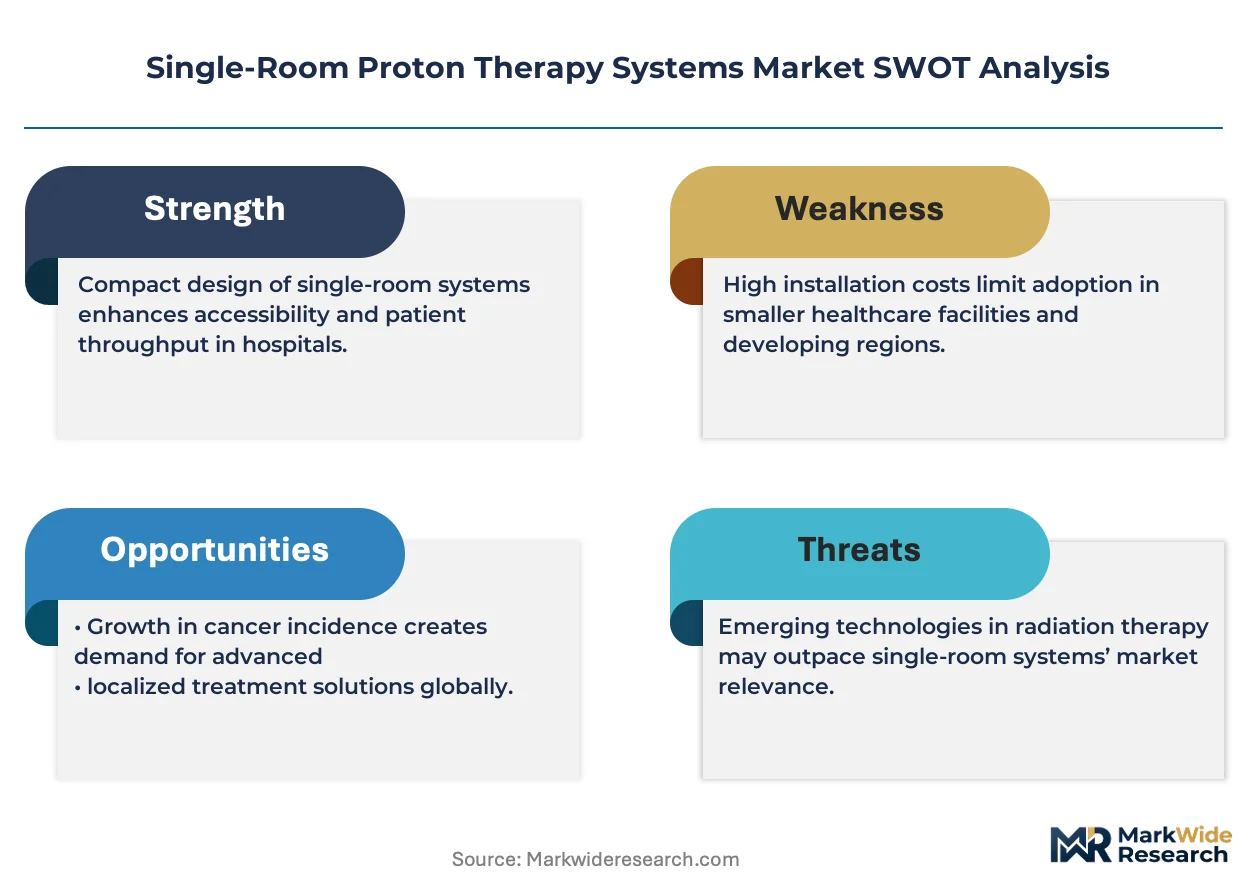
Hospital real estate constraints in dense urban cores are compressing proton therapy deployment timelines and forcing vendors to compete on vault footprint reduction rather than beam energy specifications alone. This spatial pressure is reorganizing capital committee priorities across the installed base.
Growth Catalysts
- Certificate of Need deregulation:Texas, Florida, and California have accelerated proton center construction permitting, removing bureaucratic bottlenecks that previously delayed single-room system commissioning by 18-24 months.
- Bragg peak tissue sparing:Pediatric oncology protocols increasingly specify proton therapy for cranial-spinal irradiation, creating clinical pull for compact systems that integrate with existing hospital radiation oncology departments.
- Cyclotron isotope production:The Nuclear Regulatory Commission's streamlined radioactive material licensing pathways are reducing site certification timelines for facilities seeking dual-use proton therapy and radiopharmaceutical manufacturing capabilities.
Market Restraints
- Superconducting magnet supply concentration:Niobium-titanium wire production concentrates among a handful of Japanese and European specialty metal suppliers, exposing system manufacturers to input cost volatility and extended lead times.
- Vault construction cost escalation:Reinforced concrete and radiation shielding material expenses have outpaced general construction inflation, compressing project IRRs for hospital capital committees evaluating proton versus photon alternatives.
- Photon therapy advancement:MR-guided linear accelerators and adaptive radiotherapy algorithms are narrowing the dosimetric gap for certain indications, threatening proton therapy's reimbursement justification in select clinical scenarios.
Strategic Opportunities
- Community hospital penetration:Secondary and tertiary markets in the US Mountain West and Upper Midwest remain underpenetrated, presenting whitespace for single-room deployments that bypass multi-room center economics.
- FLASH therapy convergence:Ultra-high dose rate delivery protocols are converging with compact proton system architectures, potentially opening curative applications for previously radioresistant tumor histologies.
- CMS reimbursement recalibration:Proposed coding revisions for proton therapy under the Hospital Outpatient Prospective Payment System could create tailwinds for capital investment if finalized with favorable relative weight adjustments.
Industry Challenges
- Medical physicist specialization gap:Proton therapy commissioning and quality assurance require expertise distinct from photon-based practice, creating talent scarcity that extends site readiness timelines by 6-12 months.
- Legacy EMR integration friction:Single-room systems must interface with hospital information systems designed around linear accelerator workflows, forcing costly custom middleware development for treatment planning data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Room Proton Therapy Systems Market |
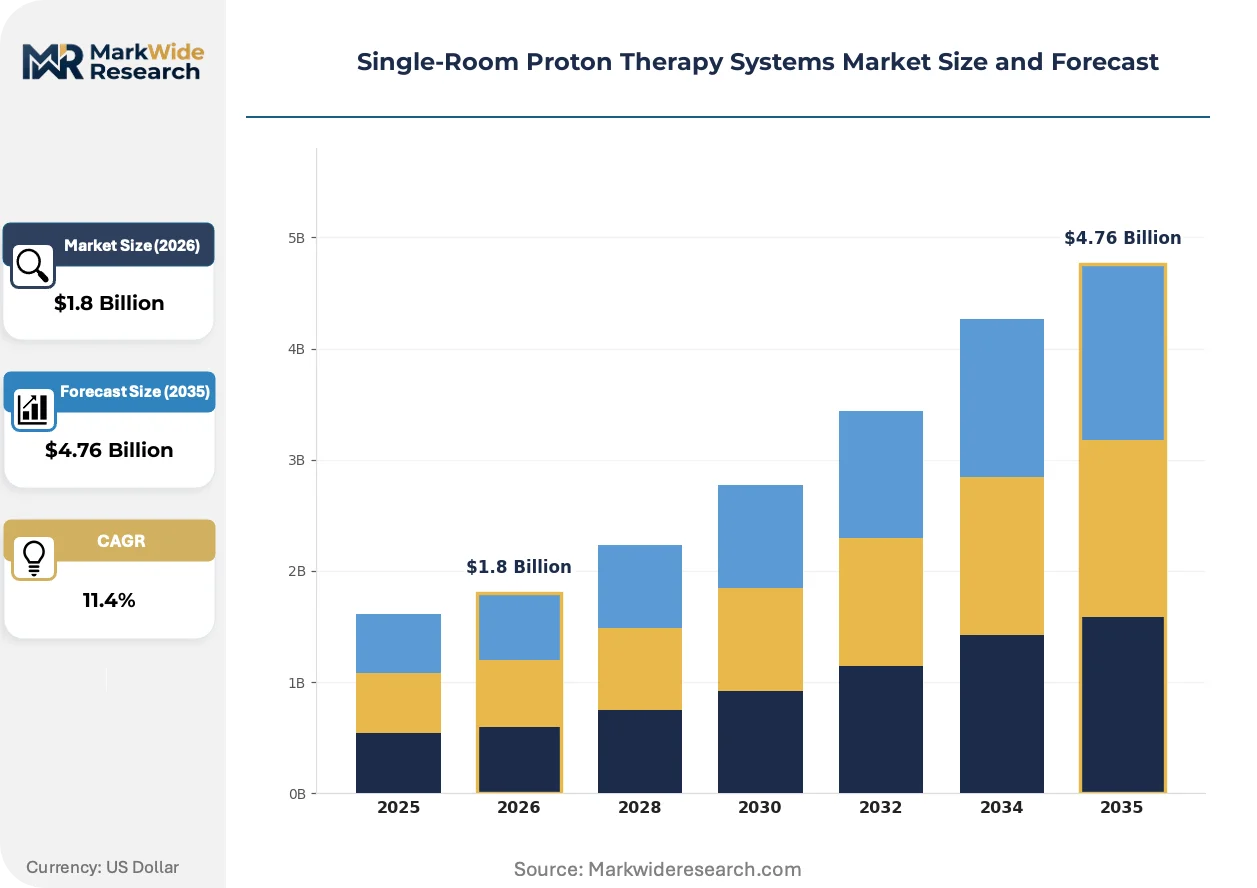
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Systems, Gantry-Based Systems, Fixed Beam Systems, Modular Systems End User: Hospitals, Cancer Treatment Centers, Research Institutions, Academic Facilities Technology: Magnetic Proton Accelerators, Pulsed Proton Beams, Continuous Wave Technology, Electron-Driven Systems Application: Oncology Treatment, Pediatric Therapy, Brain Tumor Treatment, Non-Small Cell Lung Cancer |
| Companies Covered | Ion Beam Applications (IBA), Hitachi Ltd., Varian Medical Systems (Siemens Healthineers), Mevion Medical Systems, Sumitomo Heavy Industries, Mitsubishi Electric, ProTom International, ProNova Solutions, Optivus Proton Therapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Room Proton Therapy Systems Market Evolving Landscape
Proton beam delivery architectures are fragmenting into competing technical philosophies, with superconducting synchrocyclotron designs challenging conventional cyclotron dominance and reshaping vendor competitive moats.
Superconducting synchrocyclotron technology is bifurcating the compact system landscape. Mevion's S250 series employs niobium-tin magnets to achieve 250 MeV proton energy within a vault footprint roughly one-third that of conventional isochronous cyclotron installations. Academic medical centers in Boston and Philadelphia are adopting these systems for pediatric neuro-oncology protocols where space constraints previously prohibited proton capability. The technology is compressing the addressable market for multi-room centers by enabling high-energy proton delivery within existing hospital radiation oncology departments.
FDA 510(k) and de novo premarket review pathways for radiation therapy devices are tightening evidentiary requirements for beam modeling software and patient-specific quality assurance systems. The agency's 2023 guidance on artificial intelligence-enabled treatment planning has introduced additional validation documentation burdens for proton system vendors seeking clearance. Pediatric and cranial-spinal indication expansions face extended review timelines as the FDA's Center for Devices and Radiological Health applies enhanced scrutiny to algorithms governing beam range compensation and organ-at-risk sparing.
Hospital procurement committees are unbundling equipment acquisition from service contracts, compressing vendor margin structures. Texas-based cancer centers have pioneered competitive bidding for proton system maintenance separate from capital purchase, forcing original equipment manufacturers to defend aftermarket revenue through remote monitoring subscriptions rather than captive service agreements. This disaggregation is most visible in the Southwest, where independent service organizations have secured proton accelerator maintenance contracts previously held by manufacturers.
Single-Room Proton Therapy Systems Market Segmentation
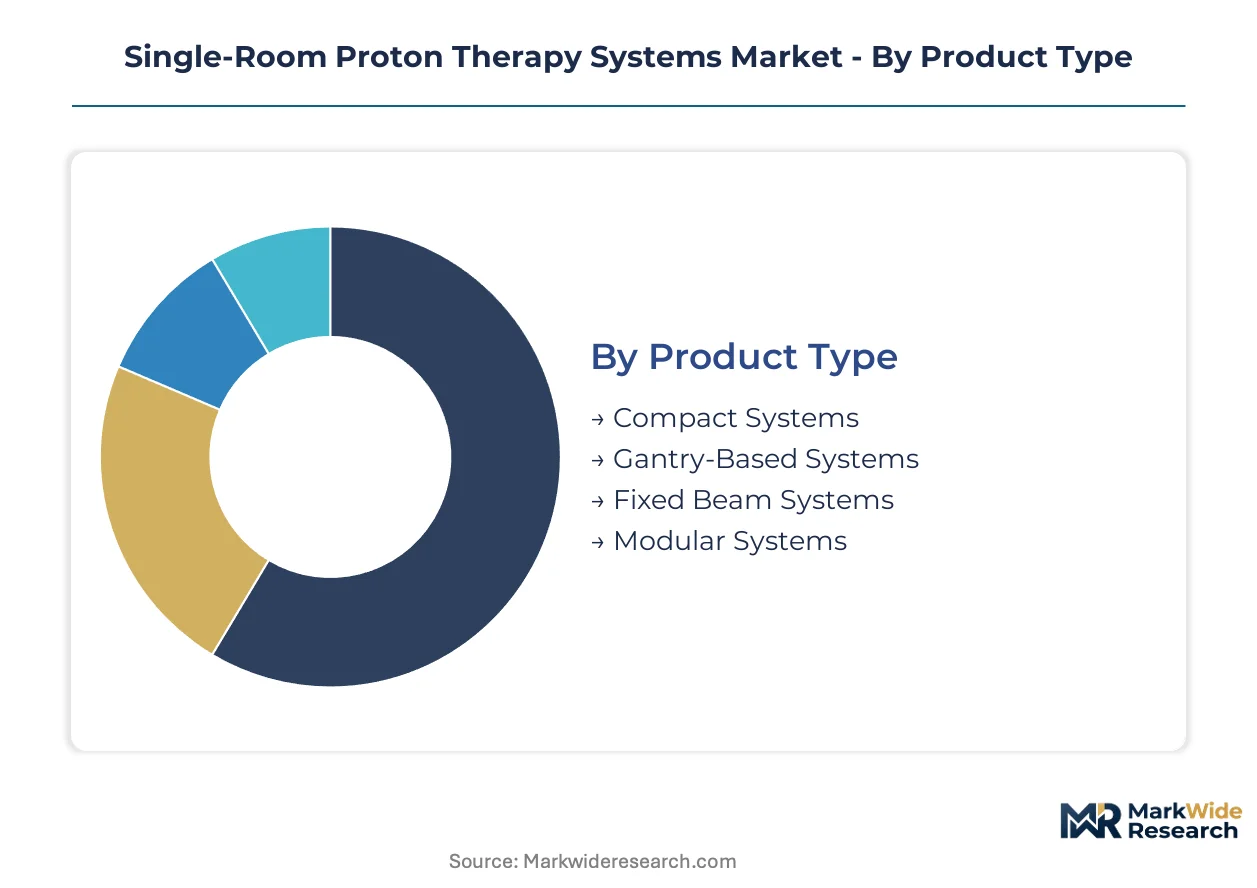
Segmentation in single-room proton therapy systems reveals how clinical requirements, site constraints, and reimbursement economics fragment demand across distinct technical configurations. Understanding these divides exposes where photon-based alternatives threaten proton adoption and where compact architectures defend their position.
Product Type:
Substitution pressure from MR-guided linear accelerators falls hardest on fixed-beam configurations, while gantry-based systems maintain defensive moats through rotational dosing capabilities that photon platforms cannot replicate.
- Compact Systems:Superconducting synchrocyclotron designs compress vault footprints to roughly 30% of conventional installations. Demand concentrates in urban hospital radiation oncology departments where real estate constraints previously excluded proton capability.
- Gantry-Based Systems:Rotational beam delivery supports complex cranial-spinal and pediatric protocols requiring multi-angle treatment fields. Texas and Florida cancer centers prioritize these configurations for their ability to command premium reimbursement codes.
- Fixed Beam Systems:Stationary nozzle architectures suit ocular and shallow tumor sites with simpler beam path requirements.
- Modular Systems:Expandable vault designs allow phased capacity additions without full construction restart.
Compact systems anchor the volume base while modular configurations gain share at the steepest rate as hospital capital committees prioritize deployment flexibility.
End User:
Capital availability and patient throughput economics stratify sharply across institutional categories, with freestanding cancer centers facing distinct reimbursement pressures compared to integrated hospital systems.
- Hospitals:Integrated delivery networks in California leverage existing radiation oncology infrastructure to absorb single-room proton systems without standalone facility construction. CMS outpatient payment classifications shape their equipment replacement cycles.
- Cancer Treatment Centers:Specialized oncology networks in Texas pursue competitive differentiation through proton capability, driving concentrated demand for compact systems with rapid commissioning timelines.
- Research Institutions:FLASH therapy and ultra-high dose rate protocols require beam architectures distinct from clinical treatment systems.
- Academic Facilities:Training programs for medical physicists and radiation oncologists create demand for systems with comprehensive quality assurance toolsets.
Hospitals dominate installed capacity while cancer treatment centers expand most aggressively as Certificate of Need deregulation accelerates in the Southeast.
Technology:
Accelerator physics choices determine vault scale, energy range, and maintenance complexity, creating divergent total cost of ownership profiles that reshape competitive tiers among equipment suppliers.
- Magnetic Proton Accelerators:Superconducting magnet configurations achieve therapeutic energies within radically compressed footprints. Niobium-titanium wire supply constraints from Japanese and European specialty metal producers extend lead times for these systems.
- Pulsed Proton Beams:Time-structured delivery enables FLASH therapy dose rates exceeding 40 Gy per second, opening curative applications for radioresistant tumors.
- Continuous Wave Technology:Steady-state beam production suits high-throughput clinical environments with stable dose delivery requirements.
- Electron-Driven Systems:Laser-plasma acceleration approaches remain experimental but promise future footprint reduction beyond current superconducting limits.
Magnetic proton accelerators anchor the revenue base while pulsed proton beams climb the fastest as FLASH protocols advance through clinical trials.
Application:
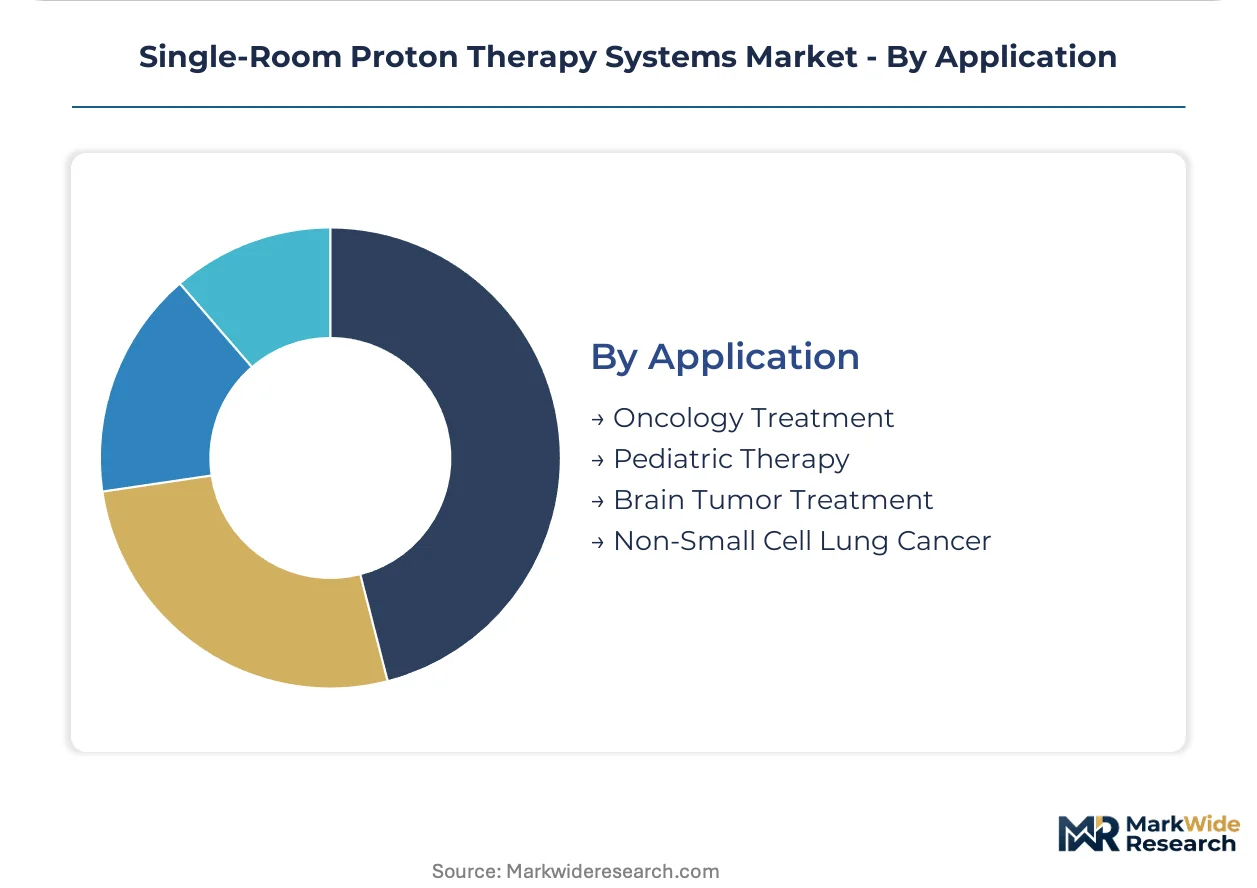
Clinical indication expansion determines reimbursement sustainability, with pediatric and central nervous system protocols defending proton therapy's value proposition against advancing photon techniques.
- Oncology Treatment:Broad solid tumor applications face intensifying competition from MR-guided linear accelerators and adaptive radiotherapy algorithms that narrow dosimetric advantages for certain histologies.
- Pediatric Therapy:Cranial-spinal irradiation for medulloblastoma and other childhood cancers specifies proton delivery to spare developing tissues. Academic medical centers in Boston and Philadelphia prioritize single-room systems for these protocols.
- Brain Tumor Treatment:Proximity to critical neural structures makes range precision essential for glioma and meningioma cases.
- Non-Small Cell Lung Cancer:Motion management and range uncertainty present technical challenges that photon-based stereotactic body radiotherapy increasingly addresses.
Oncology treatment anchors procedure volume while pediatric therapy commands the steepest expansion trajectory as long-term survival data reinforces tissue-sparing benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Florida proton centers, where Certificate of Need deregulation compresses commissioning timelines, while California facilities absorb margin pressure from stricter state environmental review processes that extend vault construction schedules.
United States
Texas cancer centers in Houston and Dallas lead single-room proton deployments, driven by pediatric neuro-oncology demand and streamlined state permitting. FDA 510(k) pathways govern device clearance, while the Nuclear Regulatory Commission oversees cyclotron licensing. Florida's Miami and Tampa clusters expand fastest as Certificate of Need removal attracts private capital.
Germany
Academic medical centers in Heidelberg and Munich prioritize superconducting synchrocyclotron integration for FLASH therapy research. EMA medical device regulations align with MDR requirements for beam delivery software validation. Bavaria's hospital networks concentrate procurement authority, compressing vendor negotiation cycles.
Japan
Tokyo and Osaka metropolitan hospitals face extreme real estate constraints that favor compact vault footprints. METI funding programs support domestic proton accelerator development, reducing import dependency. Hitachi and Mitsubishi Electric anchor manufacturing clusters in Kansai and Kanto regions.
United Kingdom
NHS England's specialized commissioning framework restricts proton therapy to designated centers in London and Manchester. MHRA post-Brexit regulatory autonomy introduces divergence from EU MDR timelines. The Christie Hospital in Manchester anchors pediatric cranial-spinal treatment capacity.
Switzerland
Swissmedic's streamlined device approval attracts proton system vendors seeking European market entry validation. Zurich and Geneva university hospitals integrate compact systems with existing radiation oncology infrastructure. Paul Scherrer Institute research programs drive FLASH protocol development.
Single-Room Proton Therapy Systems Market Competitive Landscape
Concentration sits with cyclotron specialists and superconducting magnet fabricators who control critical component supply chains. The vendor base stratifies across three tiers: integrated radiation therapy conglomerates with multi-modality portfolios, pure-play proton system developers with compact architecture specialization, and regional equipment distributors with service contract capabilities. Dominant competitive moves include vertical integration into superconducting wire supply and strategic partnerships with academic medical centers for FLASH therapy validation.
Among integrated radiation therapy conglomerates, Ion Beam Applications (IBA) and Varian Medical Systems exemplify scale-driven archetypes with cyclotron manufacturing depth and multi-room installation heritage. Mevion Medical Systems occupies the pure-play compact system tier, representing superconducting synchrocyclotron specialization. Hitachi Ltd. and Sumitomo Heavy Industries anchor Japanese industrial conglomerate participation, with Mitsubishi Electric and ProTom International occupying mid-tier positions focused on regional market penetration.
| Leading Market Players |
|---|
| Ion Beam Applications (IBA) |
| Hitachi Ltd. |
| Varian Medical Systems (Siemens Healthineers) |
| Mevion Medical Systems |
| Sumitomo Heavy Industries |
| Mitsubishi Electric |
| ProTom International |
| ProNova Solutions |
| Optivus Proton Therapy |
| Others |
Value Network & Pricing Analysis
Cyclotron manufacturing scale economies concentrate among a handful of specialized producers, compressing component pricing for smaller system developers while elevating vault construction costs as the dominant price floor determinant across single-room proton therapy deployments.
Pricing Analysis
The customization-premium spread separates standard gantry configurations from site-adapted installations requiring modified shielding specifications or integrated isotope production capabilities. Three-tier pricing structure across premium, standard, and economy levels reflects beam energy range, superconducting magnet complexity, and after-sales service bundling. Cost compression in the standard tier is intensifying because hospital procurement committees now unbundle equipment acquisition from maintenance contracts. Cancer treatment centers in Texas exhibit the highest price sensitivity due to competitive bidding pressures, while academic medical centers in Boston and Philadelphia accept premium pricing for pediatric protocol customization.
Supply Chain Analysis
Strategic stockpiling of niobium-titanium superconducting wire dominates inventory strategy as Japanese and European specialty metal suppliers extend lead times beyond eighteen months for critical magnet components. Manufacturing concentration centers on Belgium, Japan, and the United States for cyclotron core assemblies, with shielding concrete and radiation-grade steel sourcing from regional construction material suppliers. Supply chain risk hinges on single-source vulnerability for superconducting wire production, where three specialty metallurgy houses control global output. Distribution runs through direct OEM-hospital contracting with limited independent distributor participation, though independent service organizations are securing aftermarket maintenance contracts in the Southwest United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-room proton therapy system demand fragments across urban hospital radiation oncology departments and community cancer centers, creating multiple entry niches as Certificate of Need deregulation accelerates site deployment timelines.
For Market Incumbents: Fortify cyclotron manufacturing depth through captive supply arrangements for niobium-titanium wire, insulating against Japanese and European specialty metal supplier concentration. Expand FLASH therapy validation partnerships with academic medical centers in Boston and Philadelphia to defend against MR-guided linear accelerator substitution in cranial-spinal protocols. Secure remote monitoring subscription revenue as hospital procurement committees disaggregate equipment acquisition from service contracts in Texas and Florida markets. For New Entrants and Emerging Players: Remote service capabilities for proton accelerator maintenance represent the most significant service-layer gap, as incumbent OEMs lose aftermarket contracts to independent service organizations in the Southwest United States. Target secondary and tertiary markets in the US Mountain West and Upper Midwest where multi-room center economics previously excluded proton capability. Pursue community hospital penetration through rapid-commissioning compact systems with simplified vault specifications and streamlined Nuclear Regulatory Commission licensing pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play compact system developers with superconducting synchrocyclotron specialization and installed base remote monitoring penetration. Five-to-ten year viability favors vendors controlling upstream magnet supply chains or securing exclusive isotope production licensing. Acquisition priority targets superconducting wire fabricators with medical-grade niobium-titanium capacity and proton system OEMs with FLASH therapy clinical validation. Watch FDA 510(k) clearance timelines for ultra-high dose rate beam delivery software as the inflection signal for FLASH protocol commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Superconducting Magnet Supply Integration | Captive niobium-titanium wire production insulates against Japanese and European supplier concentration. |
| FLASH Therapy Clinical Validation Partnership | Academic medical center collaboration in Boston and Philadelphia accelerates ultra-high dose rate protocol adoption. |
| Remote Monitoring Platform Development | Subscription-based service contracts defend aftermarket revenue as hospital procurement unbundles equipment from maintenance. |
| Certificate of Need Deregulation Response | Accelerated sales deployment in Texas and Florida captures construction permitting timeline compression. |
| Dual-Use Cyclotron Licensing Strategy | Nuclear Regulatory Commission radiopharmaceutical manufacturing approvals expand site revenue beyond clinical treatment. |
Research Methodology
Desk research of FDA 510(k) filings, Nuclear Regulatory Commission licensing databases, hospital procurement records, and state Certificate of Need regulatory frameworks preceded structured interviews with radiation oncology department heads, medical physicists, hospital capital committee members, and proton system service engineers. Primary fieldwork combined with secondary validation against CMS reimbursement coding revisions, cyclotron manufacturing trade data, and construction permit filings in Texas, Florida, and California. Bottom-up unit deployment tracking triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Variance decomposition across product type, end user, accelerator technology, and clinical application segments structured the analytical framework throughout the projection horizon. CAGRs derived from logistic adoption curves fitted to hospital capital expenditure cycles and proton center commissioning timelines. Modeled inputs incorporated vault construction cost escalation indices, superconducting magnet lead time fluctuations, and FLASH therapy protocol advancement through clinical trials.
Underlying assumptions cover Certificate of Need deregulation continuation in target states, niobium-titanium supply stability, and CMS outpatient reimbursement maintenance for proton therapy indications, with deviation risk concentrated in photon therapy technological advancement and superconducting wire supply disruption. Revision becomes warranted when MR-guided linear accelerator dosimetric performance crosses tissue-sparing equivalence thresholds for pediatric cranial-spinal protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Oncology Apoptosis Modulators Market
Oncology
Precision Oncology Market
Oncology
Immuno-Oncology Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Stomach Cancer Treatment Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
US Veterinary Oncology Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Germany Radiotherapy Market
Oncology
Laser Cancer Therapy Market
Oncology
Interventional Oncology Ablation Market
Oncology
Radiation Oncology Market