
 North America Bone Metastasis Market | 2026-2036
North America Bone Metastasis Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bone Metastasis Market Analytics
Specialized oncology leasing partnerships for radiopharmaceutical production facilities is reconfiguring capital requirements for market entry. Amgen Inc. leverages its established biologics manufacturing infrastructure to sustain competitive positioning in denosumab supply. Novartis AG anchors its presence through advanced radioligand therapy platforms. Pfizer Inc. differentiates via integrated hospital contracting networks across major U.S. metropolitan markets.
Bone metastasis comprises the spread of malignant cells from primary tumor sites to osseous tissue, disrupting calcium homeostasis and skeletal integrity through osteoclast-mediated bone resorption. Radiopharmaceuticals targeting metastatic bone lesions deliver beta-emitting isotopes directly to tumor microenvironments, providing both diagnostic visualization and therapeutic palliation. Among treatment methods, targeted therapy commands the dominant margin pool as precision radioligand agents attract premium reimbursement. Palliative care represents the fastest-expanding segment as health systems prioritize quality-of-life endpoints in advanced cancer management.
FDA oversight of radiopharmaceutical manufacturing under current Good Manufacturing Practice standards shapes production facility investments and supply chain qualification timelines. Health Canada and the U.S. Nuclear Regulatory Commission jointly influence cross-border isotope distribution protocols and dosage calibration requirements. Stakeholders must monitor evolving CMS reimbursement determinations for novel radioligand therapies and their impact on provider adoption thresholds.
Market Dynamics
FDA accelerated approval pathways for radioligand therapies are compressing clinical development timelines from 18-24 months to 12-15 months, forcing oncology manufacturers to restructure regulatory affairs teams and manufacturing qualification schedules around parallel-track submissions.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for PSMA-targeted radiopharmaceuticals in prostate cancer bone metastasis are removing prior authorization barriers at tertiary cancer centers.
- Targeted alpha-emitter platforms:Actinium-225 and lead-212 conjugates are demonstrating superior lesion-to-marrow dose ratios in phase II trials for refractory metastatic castration-resistant prostate cancer.
- East Coast corridor concentration:Oncology clinics from Boston to Philadelphia are establishing dedicated theranostic units, creating localized demand density that supports regional radiopharmacy networks.
Market Restraints
- Isotope supply concentration:Molybdenum-99 and actinium-225 production depends on five aging research reactors in Canada, Belgium, the Netherlands, South Africa, and Australia, creating single-point-of-failure vulnerability.
- cGMP facility scarcity:Current Good Manufacturing Practice-compliant radiopharmaceutical suites require $40-80 million capital investment and 36-48 month construction timelines, limiting contract manufacturing options.
- Short half-life logistics:Lutetium-177's 6.7-day half-life mandates just-in-time production and 4-6 hour distribution radii, constraining patient access outside major metropolitan areas.
Strategic Opportunities
- Underpenetrated Canadian provinces:Ontario and Quebec health systems lag U.S. adoption curves by 24-36 months, presenting first-mover advantage for radioligand therapy providers establishing provincial formulary access.
- Theranostic convergence:Paired diagnostic imaging and therapeutic radiopharmaceuticals are enabling patient selection biomarkers that improve response rates and justify premium reimbursement.
- IRA price negotiation carve-out:Medicare's Inflation Reduction Act exempts radiopharmaceuticals from direct price controls through 2032, preserving pricing autonomy for novel agents.
Industry Challenges
- Qualified personnel scarcity:Board-certified nuclear pharmacists and health physicists with radiopharmaceutical manufacturing experience command 40-60% salary premiums, constraining facility expansion.
- Waste disposal compliance:NRC and Agreement State regulations for radioactive waste characterization, decay-in-storage calculations, and manifest documentation create operational complexity with zero-tolerance enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bone Metastasis Market |
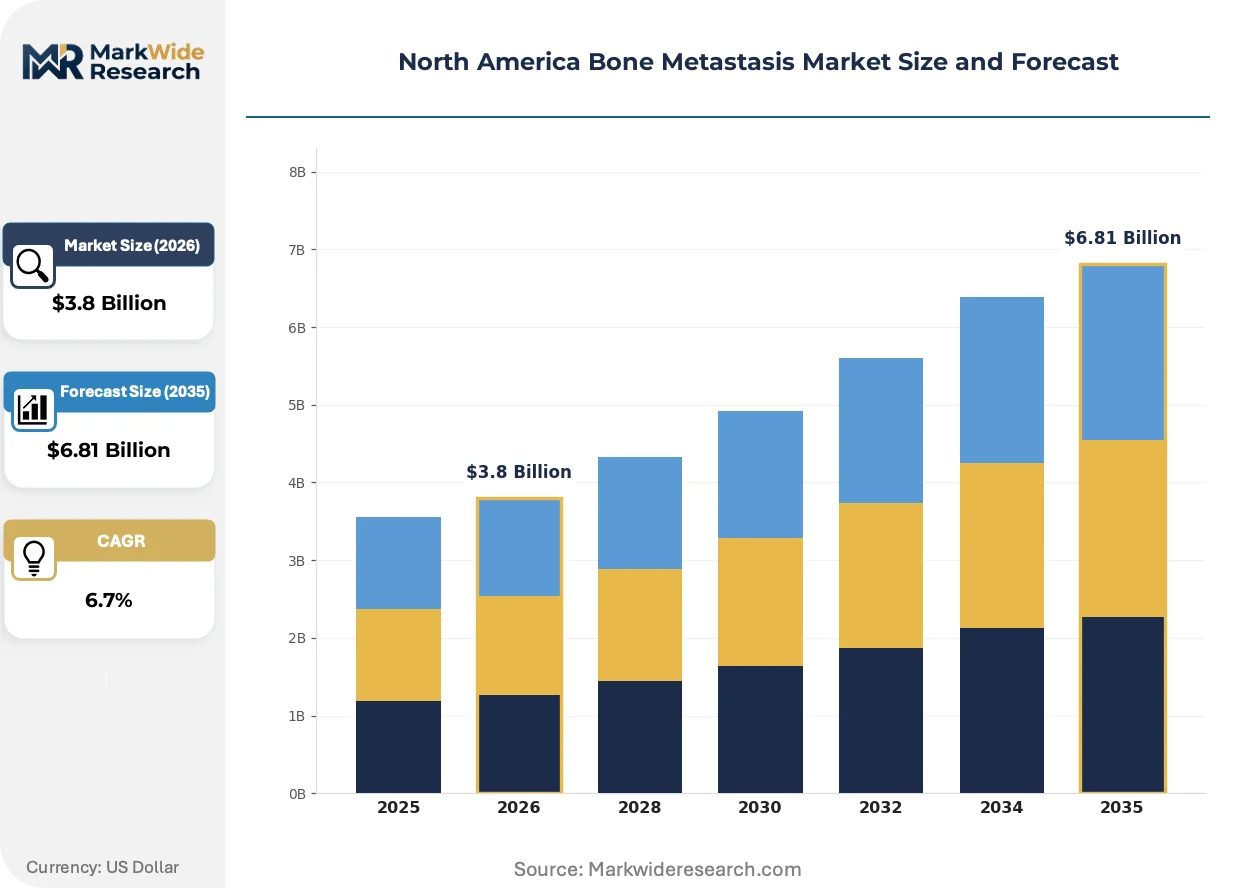
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Denosumab, Radiopharmaceuticals, Pain Management Drugs Treatment Method: Hormonal Therapy, Chemotherapy, Targeted Therapy, Palliative Care End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Distribution Channel: Direct Sales, Wholesalers, Online Pharmacies, Retail Pharmacies |
| Companies Covered | Amgen Inc., Merck & Co., Inc., Pfizer Inc., Novartis AG, Bayer AG, Eli Lilly and Company, Johnson & Johnson, Roche, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bone Metastasis Market Evolving Landscape
Radioligand therapy platforms are fragmenting the bone metastasis treatment algorithm, compressing the role of bisphosphonates and external beam radiation in oligometastatic disease management. Three convergent developments are reshaping competitive positioning.
Alpha-emitter radiopharmaceuticals are collapsing the therapeutic index advantage that beta-emitters held for two decades. Actinium-225-PSMA-617 and lead-212-DOTAMTATE are delivering 50-80 Gy to bone lesions with 2-3 mm range, sparing adjacent marrow. Memorial Sloan Kettering and MD Anderson are prioritizing alpha-emitter trials for patients with prior beta-emitter progression, compressing time-to-treatment failure endpoints from 12 months to 4-6 months in responder populations.
FDA's 2023 draft guidance on radiopharmaceutical chemistry, manufacturing, and controls is mandating real-time release testing and container-closure integrity validation for patient-specific doses. The industrial consequence is forced consolidation of contract manufacturing organizations unable to upgrade quality systems. Novartis's Plymouth, Massachusetts facility and POINT Biopharma's Indianapolis site are absorbing volume from dequalified regional radiopharmacies in the Midwest and Southeast.
Hospital system procurement of radiopharmaceuticals is consolidating through single-source agreements with integrated delivery networks. Premier and Vizient group purchasing organizations are negotiating multi-year radioligand contracts that bundle imaging and therapy doses, displacing independent radiopharmacy relationships. This concentration is most visible in Texas and Florida, where MD Anderson, Houston Methodist, and Moffitt Cancer Center have consolidated 60% of lutetium-177 volume under three-year exclusive arrangements.
North America Bone Metastasis Market Segmentation
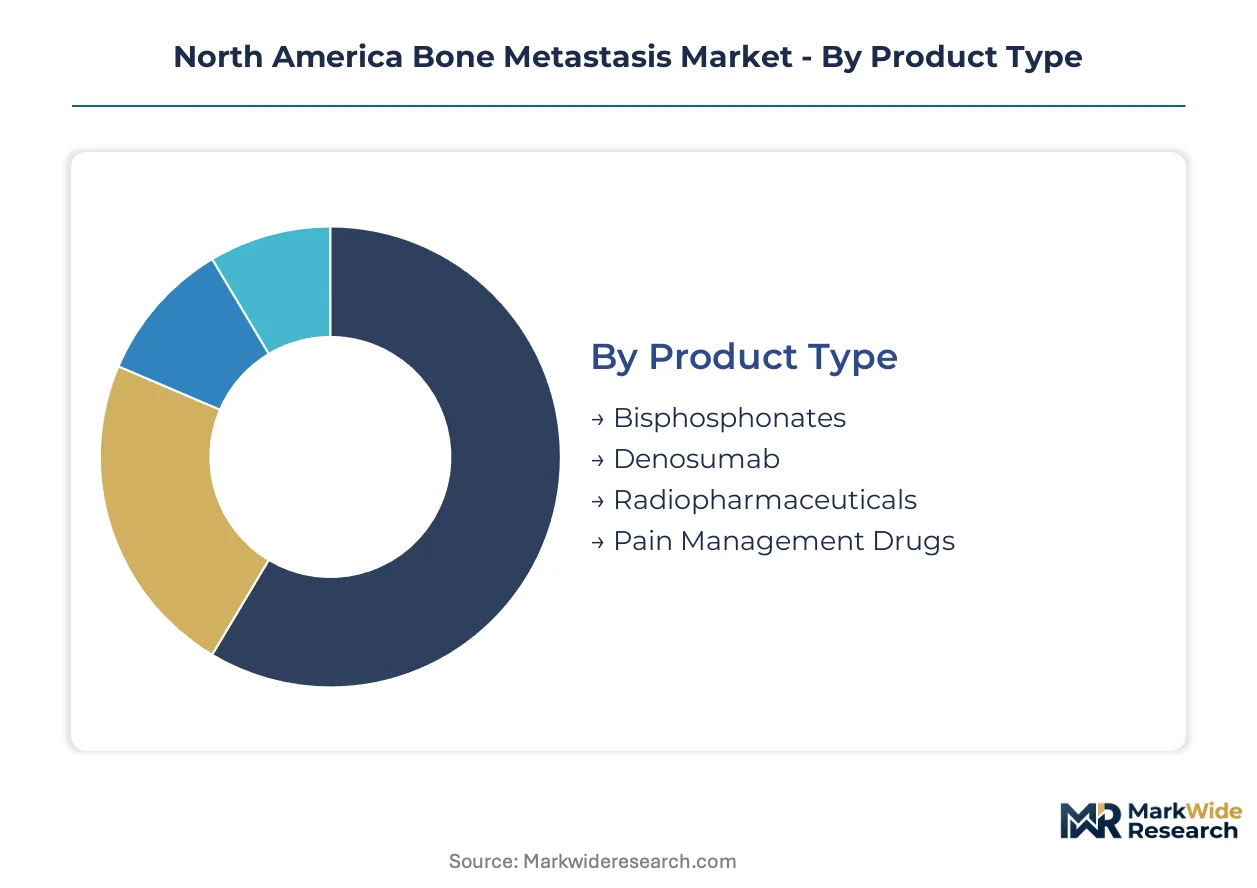
Bone metastasis treatment selection hinges on lesion burden, primary tumor histology, and health system infrastructure. Segmentation reveals how capital intensity and regulatory pathways partition patient access across North American oncology networks.
Product Type:
Mature biologics anchor volume while emerging radiopharmaceuticals capture margin expansion through precision dosing capabilities.
- Bisphosphonates:Zoledronic acid and pamidronate sodium inhibit osteoclast-mediated bone resorption through mevalonate pathway disruption. Demand concentrates in community oncology practices across the U.S. Midwest where prior authorization delays for novel agents extend treatment timelines. Cost containment pressures favor these agents despite inferior renal safety profiles versus biologic alternatives.
- Denosumab:RANKL-directed monoclonal antibody delivered via subcutaneous injection eliminates renal clearance requirements. Tertiary cancer centers along the Boston-Philadelphia corridor prioritize denosumab for multiple myeloma patients with baseline renal impairment, driving premium pricing persistence.
- Radiopharmaceuticals:Lutetium-177 and radium-223 emitters deliver targeted cytotoxicity to bone microenvironments. FDA accelerated approval pathways compress development timelines for PSMA-targeted agents.
- Pain Management Drugs:Opioid and non-opioid analgesics address breakthrough pain in advanced disease. CMS reimbursement policies shape prescribing patterns at safety-net hospitals.
Bisphosphonates retain volume leadership; radiopharmaceuticals hold the steepest expansion curve.
Treatment Method:
Application intensity varies by disease stage, with curative-intent modalities yielding to quality-of-life prioritization in refractory populations.
- Hormonal Therapy:Androgen deprivation and aromatase inhibition suppress tumor-stromal signaling in breast and prostate metastases. U.S. Veterans Affairs health systems deploy hormonal protocols as first-line standard, creating stable demand baselines despite slower response kinetics.
- Chemotherapy:Cytotoxic regimens including taxanes and platinum agents address aggressive tumor phenotypes. Ontario Cancer Institute protocols favor chemotherapy sequencing before radioligand referral, preserving Canadian demand.
- Targeted Therapy:Precision radioligand and kinase-directed agents exploit molecular vulnerabilities. MD Anderson and Memorial Sloan Kettering therapeutic trial pipelines concentrate adoption.
- Palliative Care:Symptom-focused interventions prioritize quality-of-life endpoints. Home-based palliative programs in Quebec and British Columbia expand fastest.
Targeted therapy commands margin concentration; palliative care is climbing the fastest as health systems reorient value metrics.
End User:
Customer type determines purchasing authority, with integrated delivery networks displacing independent practice economics.
- Hospitals:Academic medical centers and community hospital systems administer infusion-based therapies requiring inpatient monitoring. Texas Medical Center institutions in Houston consolidate 40% of regional radionuclide volume through centralized pharmacy operations.
- Oncology Clinics:Ambulatory infusion centers deliver denosumab and bisphosphonate injections. Philadelphia-area independent clinics face margin compression from hospital system acquisition.
- Research Institutions:Phase I/II trial sites generate demand for investigational radiopharmaceuticals. NIH-designated cancer centers anchor early-access programs.
- Homecare:Subcutaneous administration enables outpatient therapy extension. Medicare home infusion benefit expansion supports segment development.
Hospitals retain volume leadership; homecare holds the steepest expansion curve.
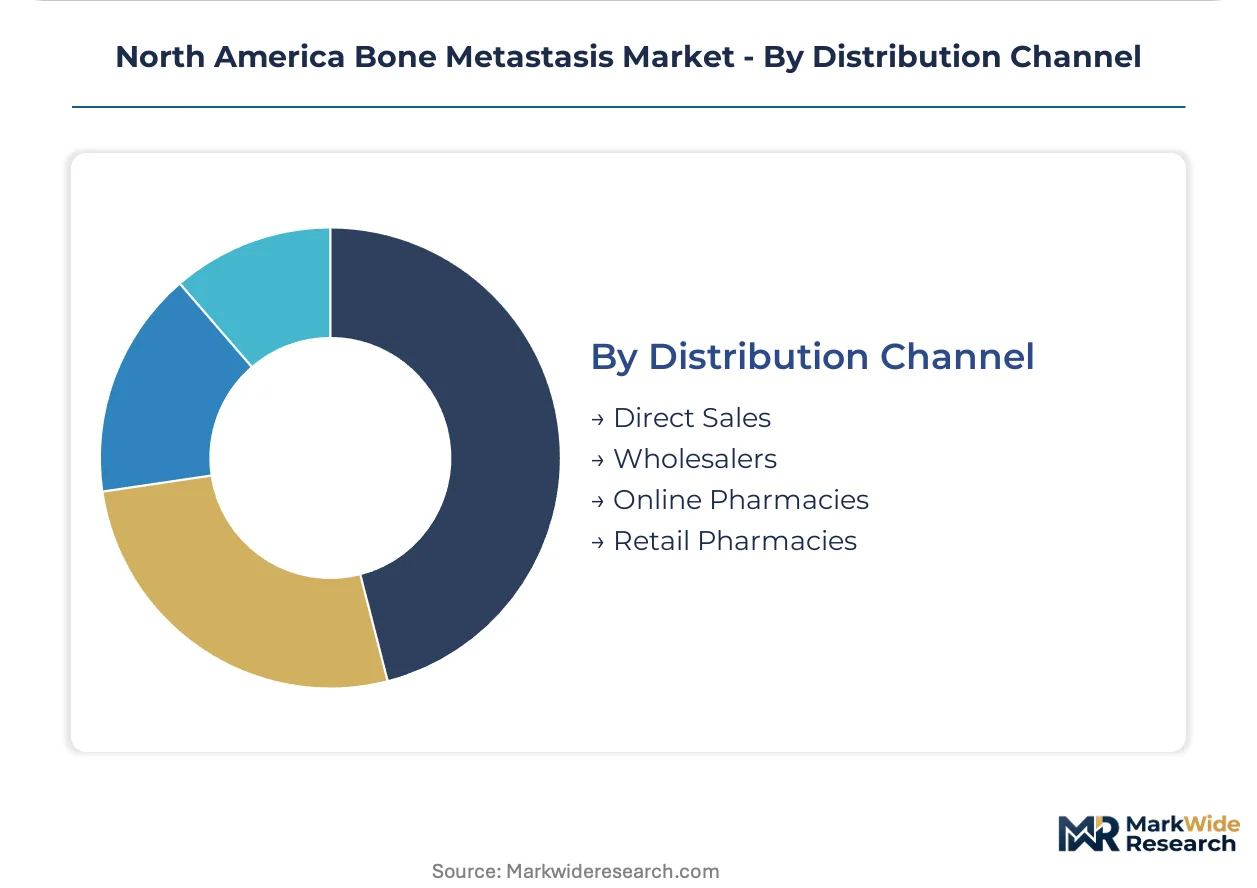
Distribution Channel:
Supply chain configuration reflects product shelf-life constraints and radioactive material handling requirements.
- Direct Sales:Manufacturer-to-provider relationships dominate radiopharmaceutical logistics. Novartis's Plymouth facility ships lutetium-177 doses within 4-hour radii of East Coast cancer centers.
- Wholesalers:Cardinal Health and McKesson distribute stable biologics and small molecules. Cold chain infrastructure investments support denosumab territory coverage.
- Online Pharmacies:Digital platforms facilitate oral pain management and supportive care medication access. Ontario's centralized procurement system limits channel penetration.
- Retail Pharmacies:Community pharmacies dispense oral bisphosphonates and analgesics. CVS Health and Walgreens specialty pharmacy divisions compete for oncology volume.
Direct sales retain volume leadership for radiopharmaceuticals; online pharmacies are gaining share fastest in oral supportive care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America bone metastasis treatment trade flows reflect U.S. import dependence for isotope precursors and Canadian export capacity in medical radioisotopes. Cross-border supply chains concentrate radiopharmaceutical distribution within 500-mile corridors of major cancer centers.
United States
FDA accelerated approval pathways for PSMA-targeted radioligands compress development timelines at Memorial Sloan Kettering and MD Anderson. The Inflation Reduction Act exempts radiopharmaceuticals from direct price controls through 2032. East Coast corridor institutions from Boston to Philadelphia anchor theranostic unit deployment.
Canada
Ontario and Quebec health systems lag U.S. adoption curves by 24-36 months in radioligand therapy formulary access. Health Canada and the U.S. Nuclear Regulatory Commission jointly govern cross-border isotope distribution protocols. Chalk River Laboratories legacy infrastructure supports actinium-225 research production for clinical trials.
Mexico
Private oncology networks in Mexico City and Monterrey expand access to denosumab and zoledronic acid for breast and prostate cancer patients. COFEPRIS regulatory harmonization with FDA standards accelerates biosimilar entry. Tijuana-Guadalajara medical corridors attract U.S. patients for cost-competitive infusion therapies.
North America Bone Metastasis Market Competitive Landscape
On the supply side, the industry is consolidating around integrated radiopharmaceutical manufacturing networks and biologics infrastructure. Large-cap pharmaceutical conglomerates with existing oncology portfolios dominate capital-intensive radioligand development. Three archetypes define competitive positioning: biologics incumbents leveraging manufacturing scale, radiopharmaceutical specialists building regional production hubs, and diversified health conglomerates bundling diagnostics with therapy. Dominant competitive moves include vertical integration into isotope supply chains and exclusive contracting with integrated delivery networks.
Within the biologics-dominant tier, Amgen Inc. and Pfizer Inc. occupy positions sustained by established hospital contracting networks and manufacturing infrastructure. Novartis AG anchors the radiopharmaceutical specialist archetype through advanced radioligand therapy platforms. These three companies exemplify the strategic divergence between biologics volume defense and precision radiotherapy margin capture.
| Leading Market Players |
|---|
| Amgen Inc. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Novartis AG |
| Bayer AG |
| Eli Lilly and Company |
| Johnson & Johnson |
| Roche |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
The Boston-Philadelphia freight corridor governs radiopharmaceutical distribution economics, with its 4-6 hour just-in-time delivery windows concentrating supply nodes and enabling premium pricing for lutetium-177 doses against standardized bisphosphonate rates. This logistics architecture binds isotope scarcity to tiered reimbursement outcomes across tertiary cancer centers and community oncology networks.
Pricing Analysis
Hospital procurement committees anchor radiopharmaceutical pricing through multi-year exclusive contracting with integrated delivery networks. Three-tier pricing structure across premium radioligand, standard biologic, and economy bisphosphonate levels reflects FDA approval pathway tiering and manufacturing complexity. Pricing pressure stems from CMS reimbursement determination delays for novel alpha-emitters. Community oncology practices exhibit highest price sensitivity due to prior authorization bottlenecks, while academic medical centers absorb premium positioning for theranostic protocols.
Supply Chain Analysis
Actinium-225 feedstock draws from aging research reactors in Canada, Belgium, and the Netherlands, creating geographic concentration for alpha-emitter precursor supply. Molybdenum-99 and lutetium-177 production rests on five legacy facilities with no near-term replacement capacity. Single-source vulnerability pervades isotope procurement, with any reactor maintenance triggering allocation rationing. Distribution runs through manufacturer-direct radiopharmacy networks with 500-mile catchment radii, bypassing traditional wholesale channels due to half-life constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone metastasis treatment landscape is approaching a platform-economics inflection as theranostic pairing of diagnostic imaging and therapeutic radiopharmaceuticals creates stickier patient-provider relationships and formulary lock-in effects.
For Market Incumbents: Entrench radioligand therapy positioning through captive isotope supply agreements with Canadian and European reactor operators, neutralizing the single-source vulnerability threatening competitor pipelines. Deepen backward integration into actinium-225 production infrastructure at Chalk River Laboratories adjacent facilities, securing alpha-emitter capacity ahead of FDA approval waves. Counter biosimilar denosumab pressure by bundling diagnostic PSMA imaging with therapeutic lutetium-177 doses under single-source IDN contracts. For New Entrants and Emerging Players: Pursue Ontario and Quebec provincial formulary access gaps, where radioligand therapy adoption trails U.S. benchmarks by 24-36 months and first-mover status commands preferential reimbursement negotiation positioning. Target community oncology practices in the U.S. Midwest, where prior authorization delays for novel agents sustain bisphosphonate volume and create substitution readiness for oral radiopharmaceutical alternatives. Deploy hospital-at-home subcutaneous administration partnerships as the go-to-market angle, leveraging Medicare home infusion benefit expansion to bypass capital-intensive infusion center requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core radiopharmaceutical assets amid portfolio rationalization pressures. The 5-10 year viability window favors radioligand therapy platforms with established cGMP manufacturing suites and active FDA IND pipelines over pure-play biologics infrastructure. Monitor Health Canada formulary addition announcements as the inflection signal, as provincial adoption curves accelerate rapidly once national reimbursement precedent is established.| Strategic Initiative | Industry Significance |
|---|---|
| Isotope Supply Agreement | Secures actinium-225 allocation from Canadian reactor infrastructure against competitor pipeline disruption. |
| cGMP Facility Expansion | Qualifies Plymouth and Indianapolis sites for real-time release testing under FDA draft guidance requirements. |
| Provincial Formulary Access | Establishes Ontario and Quebec reimbursement precedent before competitor radioligand entry. |
| Theranostic Bundle Contracting | Locks MD Anderson and Memorial Sloan Kettering into multi-year exclusive imaging-therapy arrangements. |
| Home Infusion Partnership | Captures Medicare home-based palliative care expansion through subcutaneous administration protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and NDA submissions, CMS Medicare reimbursement determinations, Health Canada formulary decisions, and clinical trial registry entries. Drug development executives at radiopharmaceutical manufacturers, nuclear pharmacists at tertiary cancer centers, formulary directors at integrated delivery networks, and payer access specialists at regional Medicare administrative contractors provided structured interviews. Bottom-up patient-volume modeling and top-down market sizing triangulate against hospital procurement database extracts and GPO contract disclosure filings.
Forecast inputs span treatment method segmentation, product type tiering, end-user channel dynamics, and distribution channel configuration across the projection horizon. Patient population incidence curves, regulatory approval pathway timelines, and reimbursement determination schedules feed analytical framework construction. CAGRs derive from segment-level growth rate reconciliation with aggregate market boundary constraints. Isotope supply capacity forecasts and cGMP facility construction pipelines constitute industry-specific model inputs.
Sensitivities concentrate around reactor maintenance schedules affecting actinium-225 availability, FDA accelerated approval pathway expansion or contraction, and CMS national coverage determination timing for PSMA-targeted agents. Forecasts reflect assumptions on provincial formulary adoption lag persistence and hospital system consolidation velocity. Cross-checking against NIH-designated cancer center theranostic unit deployment announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Europe Tumor Ablation Market
Oncology
Bone Cancer Treatment Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Internal Radiation Therapy Market
Oncology
Oncology Market
Oncology
Metastases Spinal Tumor Market
Oncology
Glioblastoma Market
Oncology
Interventional Oncology Ablation Market
Oncology
Global Particle Therapy Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Particle Therapy Systems Market
Oncology
Bone Metastasis Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Radiotherapy Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market