
 South Korea Radiotherapy Market | 2026-2036
South Korea Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Radiotherapy Market Insights
University-affiliated cancer centers is bifurcating from general hospital radiation departments as the dominant procurement archetype for advanced systems. Varian Medical Systems Inc leverages its installed base of linear accelerators to sustain service contract renewal rates across Seoul National University Hospital and Asan Medical Center. Elekta AB anchors its Korean position through Gamma Knife specialization in stereotactic radiosurgery, while Hitachi High Tech Corporation competes in proton therapy with heavy-ion system differentiation at the National Cancer Center.
Radiotherapy encompasses external beam radiation delivered by linear accelerators generating 6-25 MV X-rays, internal brachytherapy using sealed radioactive sources, and particle therapy employing proton or carbon-ion beams to deposit dose with Bragg peak precision for tumor ablation with reduced collateral tissue damage. Linear accelerators occupy the largest installed base among technology segments due to reimbursement accessibility and clinical versatility across solid tumors. Proton therapy represents the fastest-growing technology category as MFDS accelerates novel device reviews and Samsung Medical Center expands treatment capacity, while radiation therapy planning systems capture concentrated margin pools through software subscription models tied to hardware ecosystems.
MFDS regulates radiotherapy device licensing under the Medical Device Act with mandatory clinical trial requirements for Class IV high-risk equipment, while the Ministry of Health and Welfare sets reimbursement tariffs that directly influence hospital capital allocation cycles. The Korean Ministry of Food and Drug Safety aligns with international standards through MDSAP recognition, streamlining market access for multinationals with existing FDA or CE certifications. Stakeholders must monitor whether the Health Insurance Review and Assessment Service expands proton therapy reimbursement beyond designated pilot institutions to broader oncology networks.
Market Dynamics
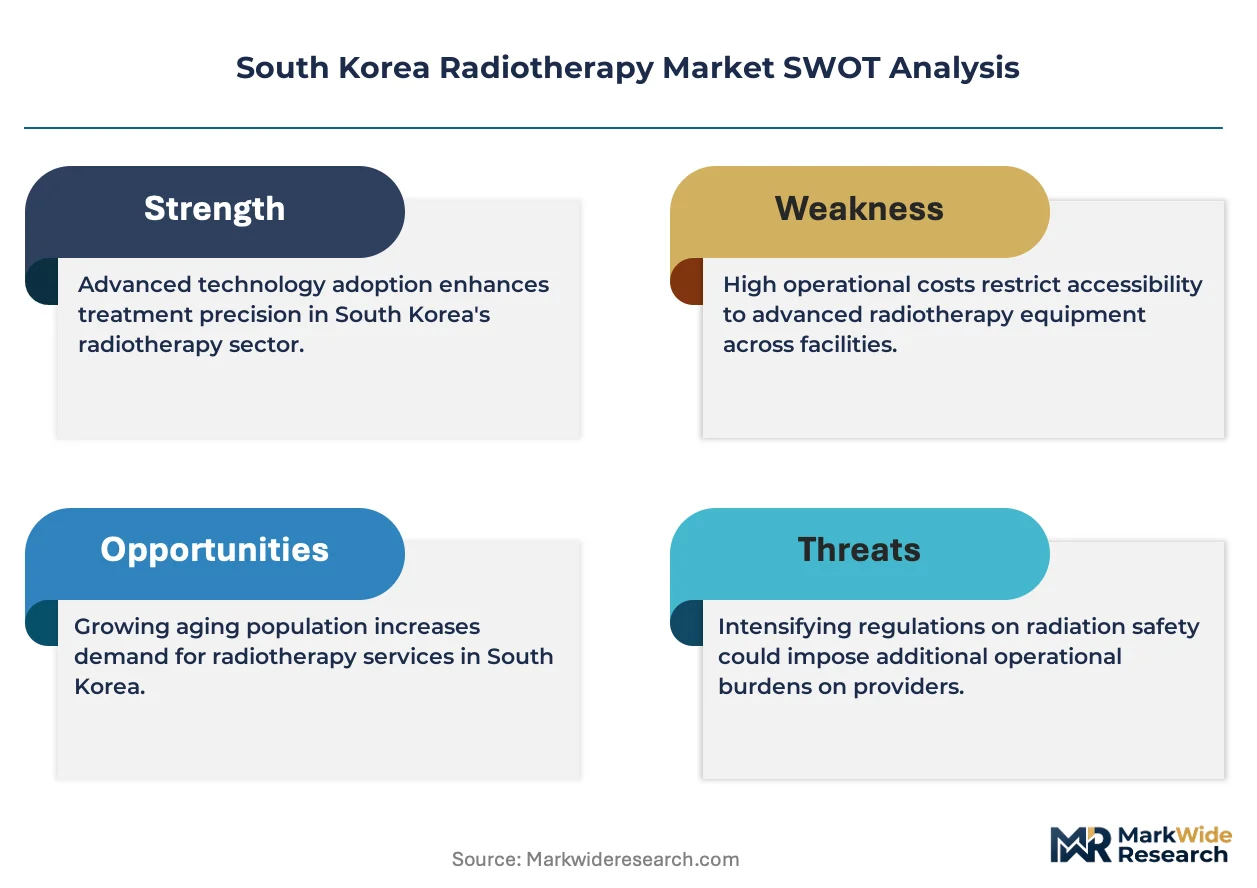
Proton therapy infrastructure expansion is compressing capital allocation cycles across Seoul's tertiary cancer centers, as MFDS accelerates Class IV device reviews and university hospitals compete for referral networks based on beam precision capabilities.
Growth Catalysts
- MFDS Streamlined Review Pathways:The Korean Ministry of Food and Drug Safety has shortened evaluation cycles for innovative radiotherapy devices, enabling faster commissioning of particle therapy systems at National Cancer Center and Samsung Medical Center.
- Seoul Metropolitan Corridor Clustering:Tertiary oncology hospitals in the capital region concentrate patient volumes and procurement budgets, creating dense installed bases that support service contract ecosystems and training infrastructure.
- Heavy-Ion Differentiation:Carbon-ion beam capabilities at specialized centers attract complex case referrals from across Northeast Asia, positioning select Korean institutions as regional destinations for pediatric and ocular malignancies.
Market Restraints
- Reimbursement Asymmetry:Health Insurance Review and Assessment Service tariffs favor conventional linear accelerator treatments, limiting proton therapy access to pilot-designated institutions and constraining capital recovery timelines for heavy-ion installations.
- Supply-Side Concentration:Cyclotron and synchrotron components for particle therapy systems depend on a narrow base of European and Japanese precision manufacturers, exposing procurement timelines to single-source bottlenecks.
- Facility Footprint Requirements:Shielding specifications for proton and heavy-ion gantries demand dedicated bunker construction with 3-4 year lead times, compressing site availability in dense urban hospital campuses.
Strategic Opportunities
- Busan-Ulsan Medical Hub Expansion:Secondary metropolitan areas in southeastern Korea currently lack proton capacity, presenting whitespace for satellite centers serving Gyeongsang province patient flows.
- Artificial Intelligence Planning Integration:Machine learning auto-contouring and adaptive replanning algorithms are converging with existing linear accelerator fleets, opening software subscription revenue streams independent of hardware replacement cycles.
- Teletherapy Network Extension:Remote treatment planning and physics support services enable smaller regional hospitals to maintain linear accelerator operations without captive dosimetry staffing.
Industry Challenges
- Medical Physics Talent Scarcity:Board-certified radiation oncologists and medical physicists with proton commissioning experience remain concentrated at Seoul's five major cancer centers, constraining expansion into provincial markets.
- Legacy Linear Accelerator Integration:Hospitals with 10-15 year installed bases face complex interoperability requirements when overlaying modern imaging-guidance and respiratory-tracking upgrades onto Varian and Elekta control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Radiotherapy Market |
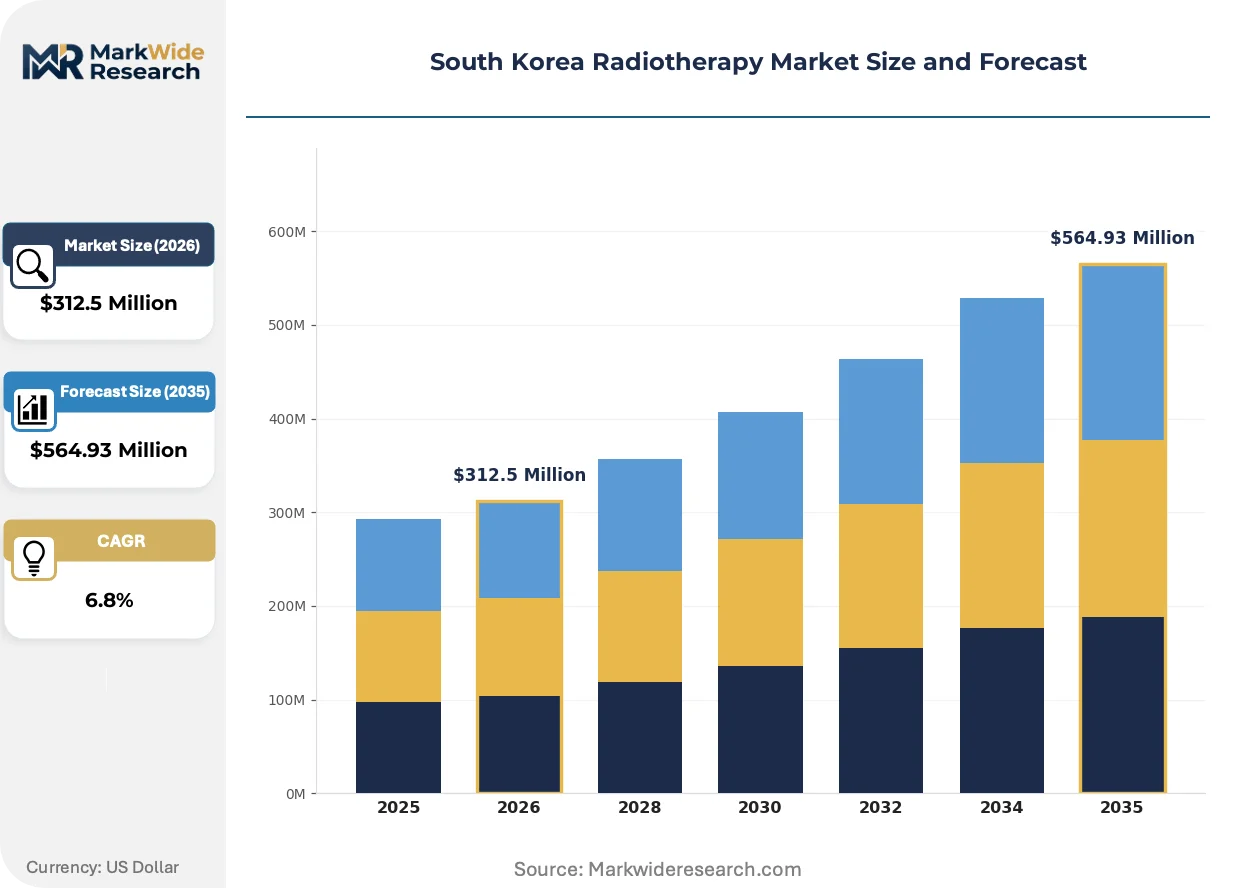
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Linear Accelerators, Brachytherapy, Radiation Therapy Planning Systems, Proton Therapy Application: Cancer Treatment, Palliative Care, Preoperative Therapy, Intraoperative Radiation Therapy End User: Hospitals, Oncology Centers, Research Institutions, Private Clinics Service Type: Treatment Service, Consultation Service, Equipment Maintenance, Training |
| Companies Covered | Elekta AB, Varian Medical Systems Inc, Accuray Inc, Siemens Healthineers AG, IBA Worldwide, ViewRay, Hitachi High Tech Corporation, RaySearch Laboratories, Carl Zeiss Meditec AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Radiotherapy Market Trends and Innovations
Adaptive radiotherapy workflows are compressing treatment margins and enabling hypofractionation protocols, while artificial intelligence reshapes planning efficiency and regulatory frameworks accelerate novel device categories.
Magnetic resonance-guided linear accelerator systems are miniaturizing the integration footprint between diagnostic imaging and treatment delivery. Asan Medical Center and Yonsei Severance Hospital are deploying these hybrid platforms for real-time soft-tissue tracking during abdominal and pelvic irradiation. The technology is miniaturizing the historical separation between simulation and treatment rooms, enabling single-room workflows that compress facility capital requirements and patient throughput times.
MFDS alignment with MDSAP recognition standards is streamlining market access for multinationals holding FDA or CE certifications. This regulatory convergence reduces redundant clinical trial requirements for Class IV radiotherapy equipment, compressing time-to-revenue for proton therapy and stereotactic radiosurgery platforms. Seoul National University Hospital and affiliated centers leverage this pathway to commission systems ahead of domestic-only competitors.
Service contract unbundling is fragmenting the traditional hardware-software-service bundle that anchored linear accelerator vendor relationships. Procurement teams at mid-sized regional hospitals now separate physics support, maintenance, and software licensing into discrete vendor relationships, compressing margins for original equipment manufacturers while opening niche opportunities for independent service organizations and cloud-based planning vendors. This pattern concentrates in Gyeonggi province facilities outside the Seoul core.
South Korea Radiotherapy Market Segmentation
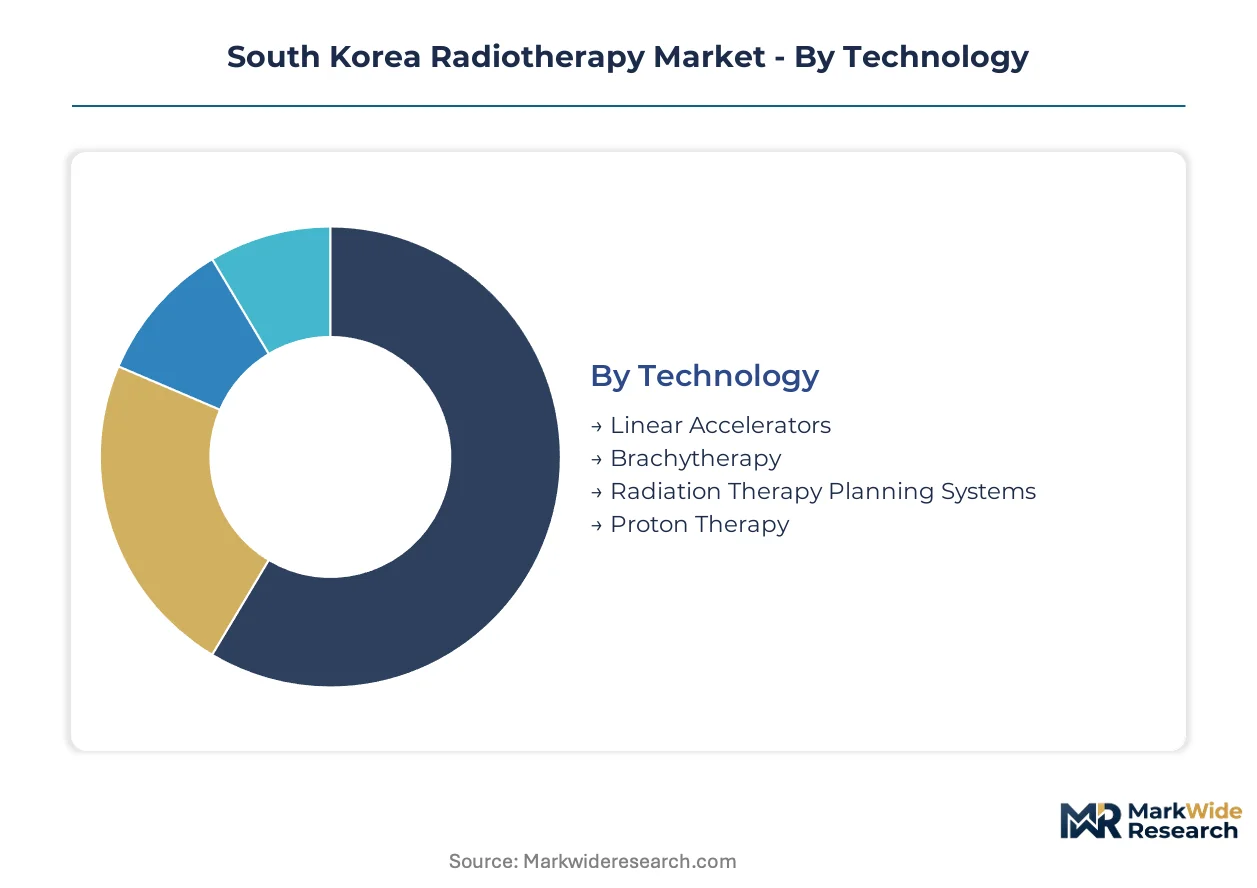
South Korea's radiotherapy market segments along technology platforms, clinical applications, and service delivery models that channel through distinct procurement pathways. Understanding these divisions reveals where MFDS regulatory pathways, reimbursement tiers, and capital allocation cycles concentrate value capture across Seoul's tertiary corridors versus provincial networks.
Technology:
Technology segments flow through divergent channel strategies: linear accelerators distribute via established vendor service contracts with university hospitals, while proton therapy systems require direct manufacturer partnerships for bunker construction and commissioning.
- Linear Accelerators:These systems generate 6-25 MV X-rays through microwave-accelerated electron beams, delivering external beam radiation across solid tumor indications. Demand clusters at Asan Medical Center and Seoul National University Hospital where high patient volumes justify multi-gantry installations and premium service tiers.
- Proton Therapy:Particle beam systems exploit the Bragg peak to deposit dose with millimeter precision, sparing adjacent healthy tissue. Samsung Medical Center and the National Cancer Center anchor installed capacity as MFDS accelerates Class IV reviews for novel beam delivery architectures.
- Brachytherapy:Sealed radioactive source placement enables dose escalation for cervical and prostate malignancies through interstitial or intracavitary delivery.
- Radiation Therapy Planning Systems:Software platforms for dose calculation and contouring increasingly deploy via cloud subscription models independent of hardware replacement cycles.
Linear accelerators dominate installed base. Proton therapy is where expansion concentrates.
Application:
Application segments map to reimbursement intensity tiers set by the Health Insurance Review and Assessment Service, with curative protocols commanding superior tariff structures versus supportive care indications.
- Cancer Treatment:Curative-intent radiotherapy for solid tumors represents the revenue core, with hypofractionated regimens and stereotactic ablative protocols gaining protocol adoption at Severance Hospital and Gangnam Severance Hospital.
- Palliative Care:Symptom-directed irradiation for bone metastases and superior vena cava syndrome addresses quality-of-life endpoints with compressed fractionation schedules.
- Preoperative Therapy:Neoadjuvant protocols for rectal and esophageal malignancies integrate with surgical oncology workflows at comprehensive cancer centers.
- Intraoperative Radiation Therapy:Single-dose delivery during surgical resection remains confined to specialized abdominal oncology units with dedicated mobile linear accelerator capabilities.
Cancer treatment commands the largest reimbursement pool. Preoperative protocols are climbing the fastest as multidisciplinary tumor boards expand integration.
End User:
End user concentration reflects patient referral hierarchies that concentrate complex cases at designated tertiary institutions while routing routine fractionation to regional networks.
- Hospitals:University-affiliated general hospitals with dedicated radiation oncology departments capture the majority of proton therapy and stereotactic radiosurgery referrals.
- Oncology Centers:Standalone cancer specialty facilities concentrate linear accelerator fleets and clinical trial access for novel fractionation protocols.
- Research Institutions:National Cancer Center and Korea Institute of Radiological and Medical Sciences anchor translational research and heavy-ion development.
- Private Clinics:Smaller radiation practices in Gyeonggi province and Busan metropolitan area handle routine external beam cases with limited stereotactic capability.
Hospitals anchor proton and advanced modality procurement. Oncology centers are gaining share fastest through focused service line development.
Service Type:
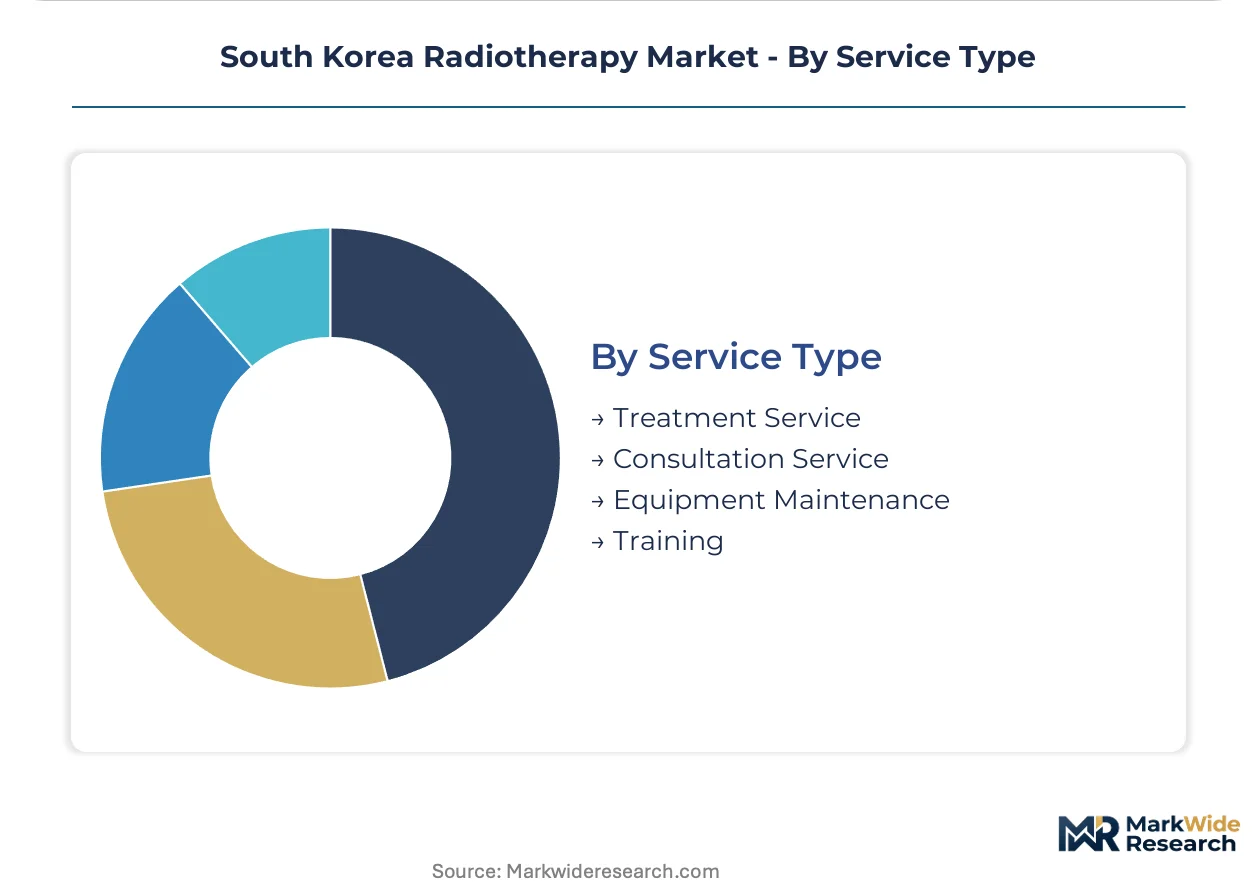
Service type segmentation reveals unbundling trends that fragment traditional vendor bundles into discrete procurement categories with independent margin structures.
- Treatment Service:Direct patient care delivery including simulation, planning, and fractionation administration generates recurring revenue tied to patient volume and reimbursement tariffs.
- Consultation Service:Multidisciplinary tumor board participation and second opinion workflows concentrate at Seoul metropolitan tertiary centers with subspecialty depth.
- Equipment Maintenance:Service contracts for linear accelerator uptime guarantee and parts replacement increasingly compete with independent service organizations.
- Training:Medical physics residency programs and proton therapy commissioning education remain concentrated at National Cancer Center and Samsung Medical Center.
Treatment service dominates revenue composition. Equipment maintenance is where vendor margin pressure concentrates most intensely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Particle therapy system suppliers concentrate commissioning resources across Seoul's tertiary corridor, while provincial cities face extended procurement timelines due to medical physics talent scarcity and bunker construction lead times.
Seoul Capital Area
Seoul National University Hospital and Asan Medical Center anchor the nation's largest linear accelerator installed bases, driving service contract ecosystems for precision beam delivery systems. MFDS Class IV device reviews accelerate commissioning cycles at Samsung Medical Center's expanding proton facility. The Gangnam district clusters Gamma Knife specialization and stereotactic radiosurgery referral networks.
Busan-Ulsan
Gyeongsang province's southeastern hub currently lacks proton therapy capacity, creating whitespace for satellite centers serving metastatic and pediatric case flows. Regional hospitals rely on conventional linear accelerator fleets with limited adaptive planning capabilities. The Ulsan University Hospital corridor concentrates radiation oncology training for the Yeongnam region.
Daegu-Gyeongbuk
Kyungpook National University Hospital anchors radiation oncology service for the inland southeast, with patient volumes split between curative and palliative protocols. The region's manufacturing base generates occupational exposure monitoring demand alongside clinical radiotherapy procurement. Daegu Catholic University Medical Center maintains the area's sole stereotactic body radiotherapy program.
Daejeon-Sejong
The Korea Institute of Radiological and Medical Sciences anchors translational research and heavy-ion development in this central corridor. National Cancer Center II facilities in Sejong expand proton and carbon-ion treatment capacity beyond the Seoul core. Government research funding concentrates here, separating clinical service delivery from capital procurement cycles.
Gwangju-Honam
Chonnam National University Hospital and Chosun University Hospital serve the southwestern region with conventional external beam capacity, routing complex cases to Seoul referral networks. The Honam corridor faces the nation's most acute medical physics staffing gaps, constraining adaptive radiotherapy adoption. Private clinic consolidation in Gwangju metro is fragmenting equipment maintenance contract structures.
South Korea Radiotherapy Market Competitive Landscape
Concentration sits with multinational linear accelerator and particle therapy system manufacturers that anchor hospital procurement through integrated service contracts. The vendor base stratifies across three tiers: precision beam delivery specialists with proton and heavy-ion capabilities, conventional linear accelerator providers with broad installed bases, and software-focused planning system vendors. Competitive positioning hardens around bunker commissioning speed, medical physics training ecosystems, and MFDS regulatory navigation support.
Among precision beam delivery specialists, Varian Medical Systems Inc and Hitachi High Tech Corporation occupy positions exemplifying contrasting technology vectors—microwave linear acceleration versus synchrotron-based particle therapy. Elekta AB represents the stereotactic radiosurgery specialization archetype through Gamma Knife system concentration. These three manufacturers anchor the premium tier where procurement decisions hinge on referral network prestige and clinical trial access rather than equipment pricing alone.
| Leading Market Players |
|---|
| Elekta AB |
| Varian Medical Systems Inc |
| Accuray Inc |
| Siemens Healthineers AG |
| IBA Worldwide |
| ViewRay |
| Hitachi High Tech Corporation |
| RaySearch Laboratories |
| Carl Zeiss Meditec AG |
| Others |
Pricing and Supply Chain Analysis
Carbon-ion gantries replacing conventional linear accelerator bunkers in Seoul's tertiary corridor simultaneously shift procurement geography toward Japanese synchrotron suppliers and compress capital recovery timelines through MFDS accelerated review pathways. This substitution dynamic concentrates pricing power with heavy-ion component manufacturers while forcing domestic hospitals to absorb extended commissioning cycles and specialized shielding costs.
Pricing Analysis
MFDS Medical Device Act tariff schedules dictate the pricing tier structure across South Korea's radiotherapy market, separating proton therapy pilot institutions from conventional linear accelerator networks. Health Insurance Review and Assessment Service reimbursement bands create three-tier pricing structure across premium particle systems, standard image-guided platforms, and economy-tier legacy equipment. Price differentiation rests on MFDS Class IV certification status and bunker commissioning complexity. Cost compression in the standard tier is intensifying because service contract unbundling allows mid-sized hospitals to source maintenance from independent organizations rather than original equipment manufacturers. Regional oncology centers in Gyeonggi province exhibit the highest price sensitivity, while Seoul National University Hospital and Samsung Medical Center prioritize beam precision capabilities over capital expenditure constraints.
Supply Chain Analysis
Busan port congestion on European trade lanes intermittently delays cyclotron and synchrotron component deliveries from Germany and Switzerland, extending bunker construction timelines for proton therapy installations. Geographic supply concentration centers on Japan for heavy-ion beam delivery systems, Germany for precision magnet assemblies, and the United States for radiation therapy planning software. Raw material dependencies include superconducting niobium-titanium wire, high-purity copper for RF cavities, and radiation-hardened electronic control systems. Single-source vulnerability pervades the synchrotron magnet supplier base, where two European manufacturers dominate global capacity. Distribution runs through direct manufacturer partnerships for particle therapy systems, contrasting with distributor-mediated linear accelerator sales to provincial hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's radiotherapy market is navigating a cyclical recovery anchored to MFDS regulatory streamlining that compresses device approval timelines and unlocks pent-up capital expenditure at university-affiliated cancer centers.
For Market Incumbents: Shield installed base positions at Asan Medical Center and Seoul National University Hospital by embedding AI planning modules into existing linear accelerator service contracts before independent software vendors capture that upgrade cycle. Deepen backward integration into proton therapy commissioning education to constrain medical physics talent migration toward emerging competitors. Vertical control over training pipelines represents the critical defensive lever against Hitachi's heavy-ion expansion and IBA's proton system penetration. For New Entrants and Emerging Players: MFDS MDSAP recognition fast-track offers the most penetrable entry vector for European and North American device manufacturers holding existing CE or FDA certifications, enabling accelerated market access without redundant domestic clinical trials. Target Busan-Ulsan corridor whitespace where zero proton capacity creates unserved demand for satellite particle therapy centers serving Gyeongsang province referrals. Go-to-market positioning should emphasize teletherapy physics support to offset regional medical physics staffing gaps and differentiate from Seoul-centric incumbent service models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed independent service organizations that have unbundled linear accelerator maintenance contracts from Varian and Elekta original equipment ecosystems. Long-term viability across the projection horizon favors acquisition targets with captive proton therapy commissioning expertise and established training relationships with National Cancer Center. The signal to monitor is Health Insurance Review and Assessment Service expansion of proton therapy reimbursement beyond pilot-designated institutions, which would inflect capital allocation cycles across provincial hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS MDSAP Fast-Track Utilization | Compresses Class IV device approval timelines for manufacturers with existing FDA or CE certifications. |
| AI Planning Module Integration | Enables software subscription revenue independent of hardware replacement cycles at mid-sized hospitals. |
| Proton Therapy Satellite Expansion | Captures unserved Gyeongsang province demand currently routing to Seoul metropolitan referral networks. |
| Teletherapy Physics Network Buildout | Addresses acute medical physics scarcity in Honam corridor without captive staffing requirements. |
| Heavy-Ion Differentiation Investment | Positions select institutions as regional destinations for pediatric and ocular malignancy referrals from Northeast Asia. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiation oncologists at Samsung Medical Center and Asan Medical Center, medical physicists with proton commissioning experience, hospital procurement committees, and MFDS regulatory affairs specialists. Secondary validation drew from MFDS medical device registration databases, Health Insurance Review and Assessment Service reimbursement tariff schedules, hospital capital expenditure disclosures, and Korea Institute of Radiological and Medical Sciences research publications. Bottom-up installed base enumeration across Seoul metropolitan and provincial hospital networks was triangulated against top-down market sizing derived from equipment manufacturer shipment data.
Across the analysis window, the quantitative framework modeled value trajectories through technology platform segmentation, end-user concentration tiers, and service delivery model unbundling. CAGRs were derived from equipment replacement cycle analysis, reimbursement expansion scenarios, and bunker construction pipeline tracking. Industry-specific forecast inputs included MFDS Class IV review velocity metrics and medical physics residency graduation rates from National Cancer Center training programs.
Underlying assumptions cover stable MFDS regulatory convergence with MDSAP standards, continued Health Insurance Review and Assessment Service reimbursement asymmetry favoring conventional linear accelerators, and persistent medical physics talent concentration at Seoul's five major cancer centers, with deviation risk concentrated in proton therapy tariff expansion timing and cyclotron component supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Glottic Cancer Treatment Market
Oncology
Thymus Cancer Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
AI in Oncology Market
Oncology
Metastatic Melanoma Market
Oncology
Cancer Supportive Care Products Market
Oncology
Global Genomics in Cancer Care Market
Oncology
Internal Radiation Therapy Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Breast Cancer Therapy Market
Oncology
North America Tumor Ablation Market
Oncology
Pituitary Cancer Market
Oncology
Thyroid Cancer Market