
 Global Human Embryonic Stem Cells Market | 2026-2036
Global Human Embryonic Stem Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Embryonic Stem Cells Market Foresight
The sourcing of human embryonic stem cell lines is shifting from single-source academic repositories toward multi-source commercial catalogs with certified provenance. Thermo Fisher Scientific leverages its Gibco brand heritage and global distribution infrastructure to dominate research-grade cell supply. STEMCELL Technologies competes through specialized feeder-free culture systems that reduce batch-to-batch variability. Lonza anchors its position via in-house production of clinical-grade hESC banks compliant with stringent pharmacopeial standards.
Human embryonic stem cells are pluripotent cells derived from the inner cell mass of blastocyst-stage embryos, capable of indefinite self-renewal in vitro and differentiation into all three germ layers under defined cytokine signaling. These properties position hESCs as foundational tools for regenerative medicine grafts, disease-in-a-dish modeling, and high-fidelity toxicity prediction. Frozen stem cells occupy the largest value share due to cryopreservation logistics and biobank infrastructure investments, while differentiated cells represent the fastest-expanding margin pool as pharmaceutical developers outsource specialized lineage production. Gene editing technology commands premium positioning within the technology dimension, with CRISPR-modified hESC lines displacing wild-type substrates in target validation workflows.
FDA oversight through the Center for Biologics Evaluation and Research shapes demand by mandating current Good Manufacturing Practice compliance for hESC-derived therapeutic candidates entering Phase I trials. EMA's Committee for Advanced Therapies and Japan's PMDA impose parallel quality benchmarks that filter market access to sponsors with documented cell lineage traceability and viral safety dossiers. Stakeholders must monitor evolving pluripotency marker standards and cross-border material transfer agreements as regulatory divergence between jurisdictions threatens to fragment supply chain interoperability.
Market Dynamics
CRISPR-modified human embryonic stem cell lines are absorbing procurement budgets from wild-type substrates as pharmaceutical developers prioritize precision-edited substrates for target validation workflows. This technological pivot compresses development timelines while elevating quality benchmarks across the value chain.
Growth Catalysts
- FDA Pathway Refinements:The Center for Biologics Evaluation and Research has streamlined investigational new drug applications for hESC-derived therapies, reducing sponsor entry barriers into Phase I trials.
- Regenerative Medicine Procurement:Hospital networks across the United States have expanded dedicated budgets for cell-based therapeutic sourcing, anchoring demand concentration in clinical-grade material.
- Gene Editing Convergence:CRISPR-Cas9 integration with hESC platforms enables high-fidelity disease modeling that accelerates pharmaceutical toxicity prediction cycles.
Market Restraints
- Ethical Sourcing Constraints:Blastocyst destruction requirements trigger restrictive legislation in multiple jurisdictions, fragmenting material transfer agreements across borders.
- Clinical-Grade Production Costs:Current Good Manufacturing Practice compliance for pharmacopeial-grade cell banks demands capital-intensive cleanroom infrastructure and viral safety dossiers.
- Allogeneic Immunogenicity:Host-versus-graft responses limit therapeutic durability, constraining first-generation hESC-derived products to immunoprivileged anatomical sites.
Strategic Opportunities
- Japan's PMDA Accelerated Pathways:Sakigake designation for regenerative medicines offers priority review and early reimbursement dialogue for hESC-derived therapeutic candidates.
- Disease-in-a-Dish Contract Manufacturing:Pharmaceutical developers are outsourcing specialized lineage production to certified biobanks, creating margin expansion in differentiated cell services.
- Feeder-Free Culture Standardization:Chemically defined media systems eliminate batch-to-batch variability from animal-derived components, opening premium positioning for quality-certified suppliers.
Industry Challenges
- Pluripotency Marker Standardization:Divergent immunophenotyping protocols across regulatory jurisdictions complicate cross-border cell line qualification and comparability studies.
- Cryopreservation Logistics:Maintaining viable post-thaw recovery rates during international shipment requires validated cold-chain infrastructure that few logistics providers possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Embryonic Stem Cells Market |
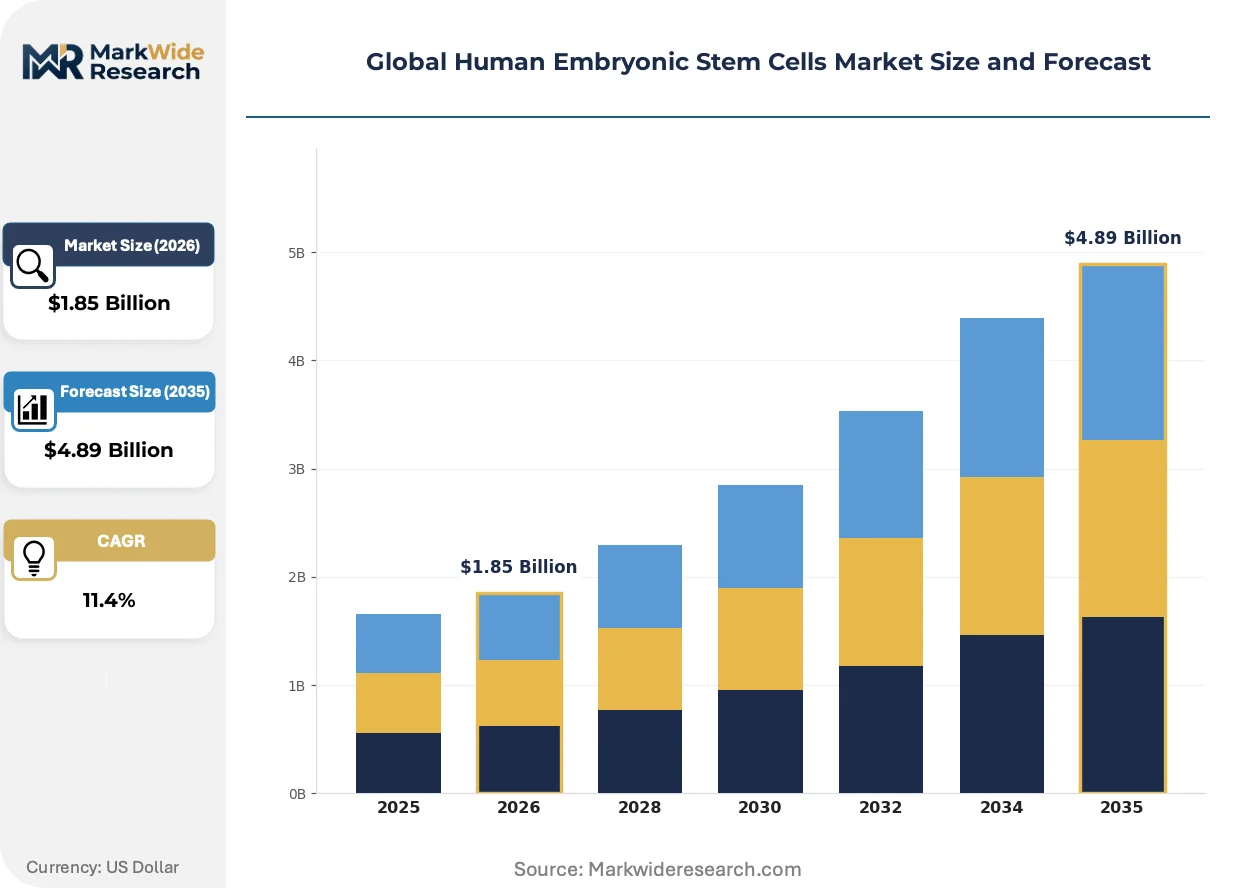
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Stem Cells, Cultured Stem Cells, Differentiated Cells, Specialized Lineages Application: Regenerative Medicine, Drug Discovery, Toxicology Testing, Disease Modeling, Cell Therapy End User: Biotechnology Firms, Academic Research Institutes, Contract Research Organizations, Pharmaceutical Developers Technology: Immunocytochemistry, Gene Editing, Cell Sorting, High-Throughput Screening, Microfluidics |
| Companies Covered | Thermo Fisher Scientific Inc., STEMCELL Technologies Inc., Merck KGaA, Lonza, PromoCell GmbH, CellGenix GmbH, Takara Bio, Vertex Pharmaceuticals, Lineage Cell Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Embryonic Stem Cells Market Shifts & Advancements
Gene editing platforms are rewriting competitive positioning in human embryonic stem cell supply. Three distinct vectors—technological capability, regulatory adaptation, and procurement sophistication—are restructuring how value flows through this market.
Synthetic mRNA reprogramming is absorbing development resources from traditional viral transduction methods for induced pluripotency applications. Contract research organizations in Germany and Japan are adopting footprint-free reprogramming to eliminate residual vector sequences from master cell banks. This transition is absorbing quality assurance budgets previously allocated to extensive viral clearance documentation.
EMA's Committee for Advanced Therapies has tightened traceability requirements for hESC-derived investigational medicinal products entering European trials. Sponsors must now document cell lineage provenance from blastocyst isolation through final therapeutic formulation. Clinical-stage biotechnology firms are responding by investing in blockchain-enabled chain-of-custody systems for their German and Swiss manufacturing sites.
Consolidated procurement through multi-source commercial catalogs is displacing fragmented sourcing from single academic repositories. Pharmaceutical developers in the United States now require certified provenance documentation and batch consistency guarantees as table stakes for vendor qualification. This behavioral shift concentrates contract value with suppliers maintaining in-house clinical-grade production capabilities rather than research-grade distributors.
Global Human Embryonic Stem Cells Market Segmentation
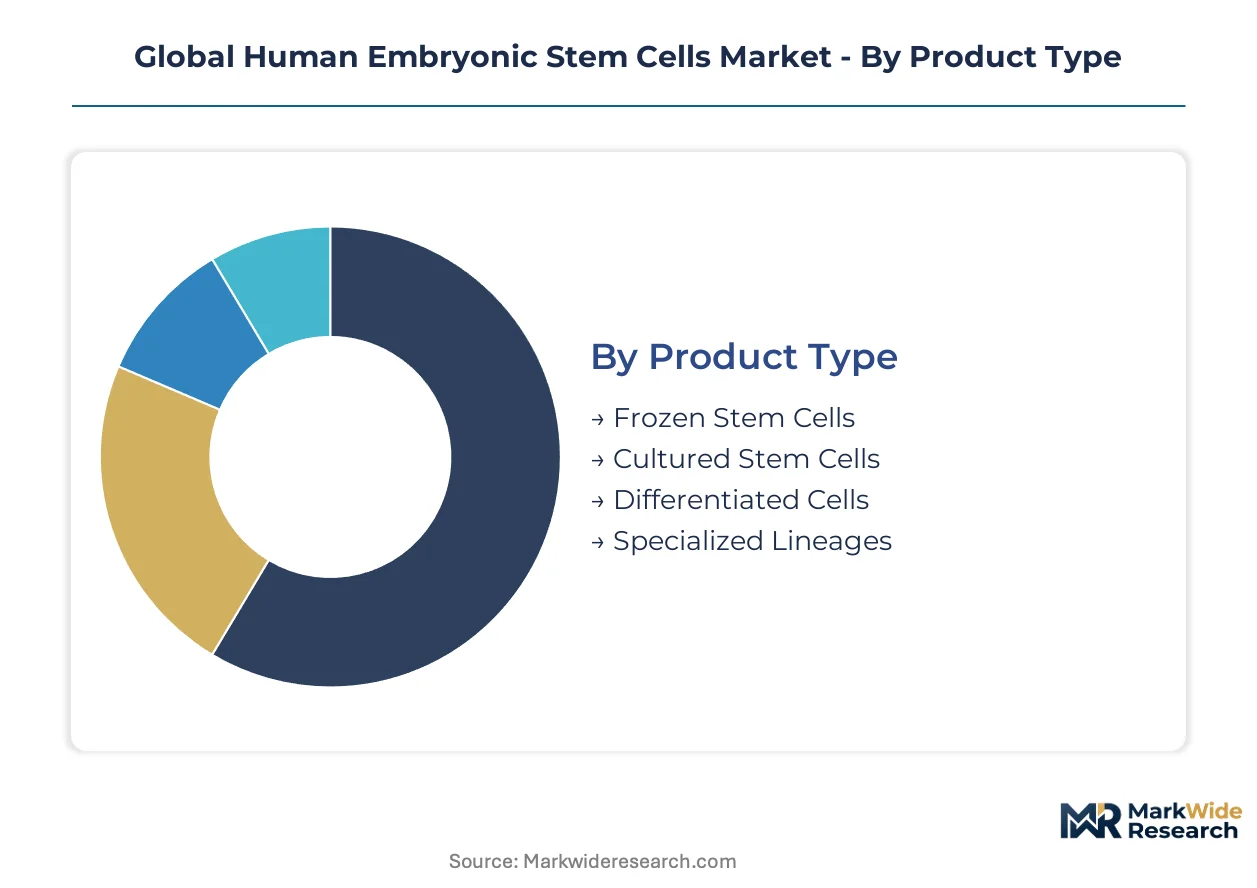
Segmentation in the human embryonic stem cell market reveals distinct procurement patterns between research-grade and clinical-grade material. Supply chain configuration varies sharply across product formats, with cryopreserved inventories demanding specialized logistics infrastructure that cultured preparations bypass entirely.
Product Type:
Integration depth separates segments that function as standalone research substrates from those embedded within downstream therapeutic manufacturing workflows.
- Frozen Stem Cells:Cryopreserved blastocyst-derived lines maintained in vapor-phase nitrogen storage enable indefinite archival with post-thaw viability rates dictating procurement premiums. Hospital networks in the United States anchor demand for GMP-certified frozen banks, though validated cold-chain infrastructure scarcity constrains international distribution.
- Differentiated Cells:Lineage-committed derivatives—cardiomyocytes, neural progenitors, hepatocytes—absorb expanded outsourcing budgets as pharmaceutical developers eliminate in-house differentiation capabilities. Germany's contract manufacturing clusters capture the steepest volume expansion in this segment.
- Cultured Stem Cells:Actively propagating hESC colonies in feeder-dependent or feeder-free conditions serve immediate experimental consumption with shorter procurement cycles than frozen alternatives.
- Specialized Lineages:Rare or complex derivatives—pancreatic beta cells, retinal pigment epithelium—command scarcity premiums from targeted therapeutic developers.
Frozen stem cells lead volumes today; differentiated cells are gaining share fastest.
Application:
Cost tier stratification separates capital-intensive therapeutic development from research-tool procurement with vastly different margin structures and qualification requirements.
- Regenerative Medicine:Clinical-grade hESC-derived grafts for tissue repair demand pharmacopeial compliance, viral safety dossiers, and documented lineage traceability from blastocyst isolation. Japan's PMDA Sakigake designation accelerates sponsor entry, concentrating trial activity in Tokyo-Osaka corridors.
- Disease Modeling:Patient-mimetic in vitro systems for mechanistic study and target validation absorb CRISPR-modified line procurement as pharmaceutical developers prioritize precision-edited substrates over wild-type.
- Drug Discovery:Primary screening cascades leverage hESC platforms for target deconvolution with lower regulatory burden than therapeutic applications.
- Toxicology Testing:Hepatocyte and cardiomyocyte derivatives replace animal models in early safety pharmacology with regulatory acceptance expanding under FDA and EMA validation frameworks.
- Cell Therapy:Allogeneic hESC-derived cellular products face immunogenicity constraints limiting first-generation deployment to immunoprivileged anatomical sites.
Regenerative medicine dominates value capture; disease modeling shows the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with commercial developers demanding certified provenance documentation that academic repositories historically failed to provide.
- Pharmaceutical Developers:Integrated biopharma sponsors with internal cell therapy pipelines source clinical-grade master cell banks with batch consistency guarantees as vendor qualification table stakes. United States-based sponsors concentrate procurement through multi-source commercial catalogs displacing fragmented academic sourcing.
- Biotechnology Firms:Venture-backed cell therapy developers outsource specialized lineage production to certified biobanks, creating margin expansion opportunities in differentiated cell services.
- Academic Research Institutes:Basic science investigators prioritize cost-minimized research-grade material with less stringent documentation requirements than commercial counterparts.
- Contract Research Organizations:Service providers in Germany and Japan adopt footprint-free reprogramming methods to eliminate residual vector sequences from client deliverables.
Pharmaceutical developers anchor procurement volumes; biotechnology firms are expanding procurement most aggressively.
Technology:
Maturity gradients separate established analytical methods from emerging platforms still navigating standardization and regulatory acceptance.
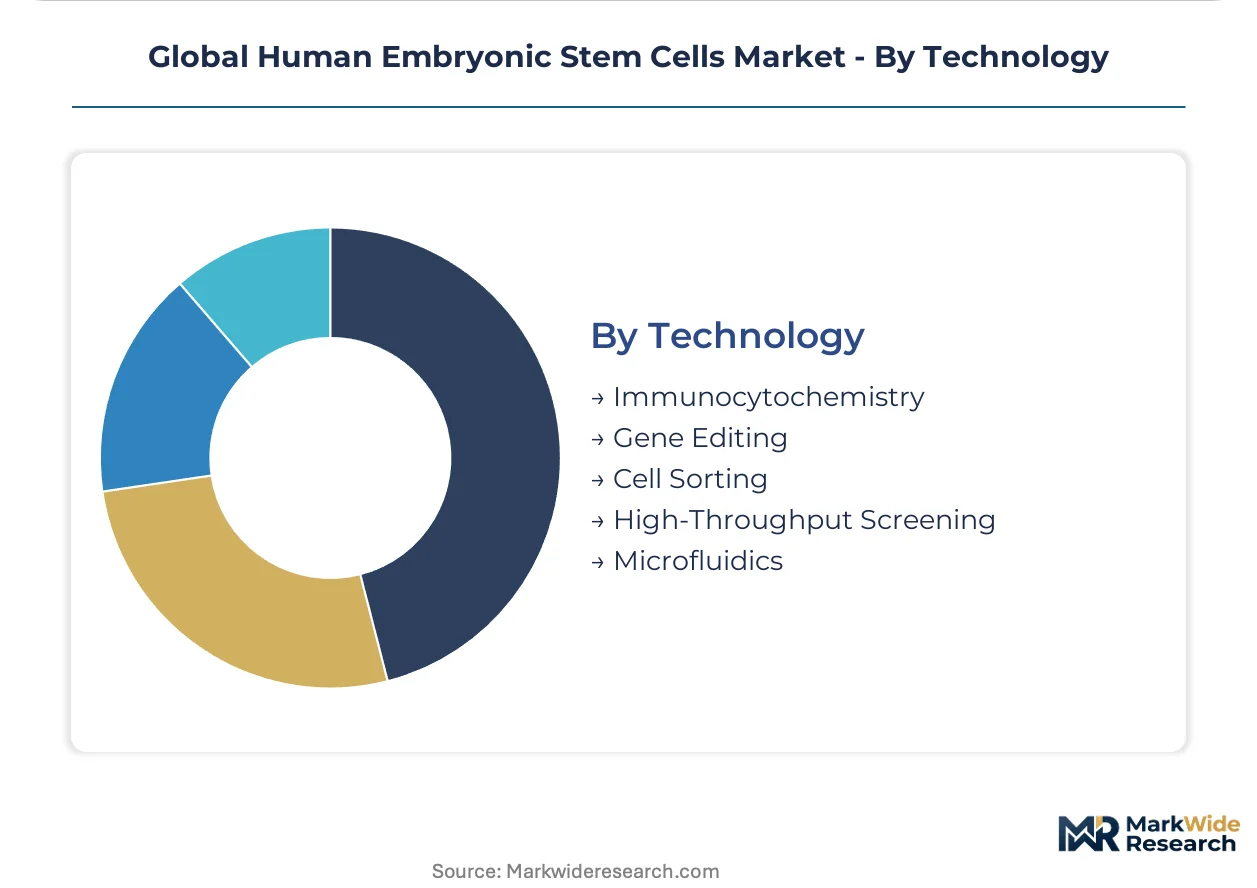
- Gene Editing:CRISPR-Cas9 and base editing platforms enable high-fidelity disease modeling with modified hESC lines displacing wild-type substrates in target validation workflows. EMA traceability requirements for edited lines intensify documentation burdens.
- Immunocytochemistry:Antibody-based pluripotency marker detection remains standard for cell line qualification despite divergent protocols complicating cross-border comparability studies.
- Cell Sorting:Fluorescence-activated and magnetic-activated separation purifies differentiated subpopulations for therapeutic formulation.
- High-Throughput Screening:Automated imaging and assay platforms scale disease-model deployment across pharmaceutical discovery organizations.
- Microfluidics:Organ-on-chip and single-cell analysis systems represent emerging integration architectures with standardization still developing.
Gene editing commands premium positioning; microfluidics is climbing the fastest despite nascent standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors global demand concentration for human embryonic stem cell procurement, with hospital networks and pharmaceutical developers clustering procurement through certified commercial catalogs.
United States
FDA pathway refinements through the Center for Biologics Evaluation and Research compress investigational new drug timelines for hESC-derived therapies. The agency mandates current Good Manufacturing Practice compliance for Phase I trial entry. Boston-Cambridge and San Diego biotech corridors concentrate contract manufacturing and master cell bank production.
Germany
EMA's Committee for Advanced Therapies tightened traceability requirements for hESC-derived investigational medicinal products entering European trials. Sponsors must document cell lineage provenance from blastocyst isolation through final formulation. Heidelberg and Munich clusters capture expanding differentiated cell outsourcing contracts.
Japan
PMDA Sakigake designation offers priority review and early reimbursement dialogue for regenerative medicine candidates. Tokyo-Osaka corridors anchor clinical trial activity for hESC-derived therapeutic development. Contract research organizations in Kansai adopt footprint-free reprogramming methods for client deliverables.
Switzerland
Swissmedic imposes parallel quality benchmarks to EMA standards, filtering market access to sponsors with documented viral safety dossiers. Basel and Zurich manufacturing sites invest in blockchain-enabled chain-of-custody systems. Clinical-grade cell bank production concentrates around pharmaceutical hub infrastructure.
United Kingdom
The Medicines and Healthcare products Regulatory Agency aligns post-Brexit with EMA advanced therapy frameworks while maintaining distinct batch release procedures. London-Oxford-Cambridge golden triangle concentrates disease-in-a-dish modeling contracts. Academic research institutes prioritize cost-minimized research-grade material procurement.
Global Human Embryonic Stem Cells Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and clinical-grade production capabilities. The vendor base organizes around three tiers: diversified life science conglomerates with global logistics networks, specialized cell culture technology firms, and clinical-stage biotechnology developers with captive manufacturing. Consolidation pressures favor suppliers with in-house pharmacopeial-grade cell banking capabilities over research-grade distributors. Strategic moves concentrate on feeder-free culture system standardization and gene editing platform integration.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify scale-driven positioning through global distribution infrastructure and brand heritage in research reagents. Lonza occupies a distinct position bridging research-grade supply and clinical-grade manufacturing compliance. Specialized players including STEMCELL Technologies Inc. and PromoCell GmbH represent regional champions competing through culture system innovation and European market proximity. Takara Bio anchors Asia-Pacific supply chain presence. Clinical-stage developers Lineage Cell Therapeutics Inc. and Vertex Pharmaceuticals exemplify vertical integration into therapeutic manufacturing rather than external cell supply.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| STEMCELL Technologies Inc. |
| Merck KGaA |
| Lonza |
| PromoCell GmbH |
| CellGenix GmbH |
| Takara Bio |
| Vertex Pharmaceuticals |
| Lineage Cell Therapeutics Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between clinical-grade and research-grade human embryonic stem cell tiers manifests in pricing premiums of 3-5x for GMP-compliant banks, while supply chain configurations bifurcate between validated cold-chain biobank infrastructure and ambient logistics for cultured preparations. FDA-mandated viral safety dossiers and EMA lineage traceability requirements concentrate procurement power with suppliers maintaining in-house pharmacopeial production capabilities, forcing research-grade distributors into margin-compressed catalog positions.
Pricing Analysis
Input-cost pass-through from cryopreservation logistics and cleanroom infrastructure runs through clinical-grade tier pricing, with vapor-phase nitrogen storage and validated cold-chain transport commanding substantial premiums over ambient-cultured alternatives. Price differentiation hinges on GMP certification tier and batch consistency guarantees, with pharmaceutical developers absorbing premium positioning while academic institutes drive standard-tier procurement. Pricing pressure stems from feeder-free culture media standardization reducing proprietary formulation premiums. Biotechnology firms exhibit highest price sensitivity due to venture-capital budget constraints, whereas integrated pharmaceutical sponsors prioritize quality assurance over unit economics.
Supply Chain Analysis
Reverse-logistics for cryopreserved hESC inventories demands specialized return-to-bank protocols for temperature-excursion events, with damaged shipments requiring complete replacement rather than refurbishment due to cellular viability thresholds. Supply concentrates in the United States, Germany, and Japan where clustered research institutes and biotechnology firms anchor translational pipelines. Raw material dependencies include recombinant cytokines, chemically defined media substrates, and blastocyst sourcing agreements. Single-source vulnerability permeates master cell bank production, with limited GMP-certified cleanroom capacity constraining sponsor access. Distribution runs through multi-source commercial catalogs displacing fragmented academic repository sourcing.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchets, with FDA pathway refinements for cell-based therapies compressing development timelines and accelerating procurement budget expansion across hospital networks.
For Market Incumbents: Acquire feeder-free culture system IP to eliminate batch-to-batch variability from animal-derived components. Consolidate GMP-certified cleanroom capacity in Boston-Cambridge and Heidelberg corridors to defend against emerging contract manufacturing entrants. Gene editing platform integration represents the critical lever for displacing wild-type substrate procurement. For New Entrants and Emerging Players: PMDA Sakigake designation in Japan opens a window for priority review positioning in regenerative medicine candidates. Target differentiated cell contract manufacturing for pharmaceutical developers eliminating in-house lineage production capabilities. Disease-in-a-dish outsourcing contracts in Germany's Heidelberg-Munich clusters offer the most penetrable entry point, with blockchain-enabled chain-of-custody documentation as the qualifying go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with clinical-grade cell banking specialists possessing documented viral safety dossiers and blastocyst-to-therapeutic traceability systems. Long-term viability over the analysis window favors suppliers with backward integration into GMP infrastructure rather than research-grade distribution assets. Monitor EMA pluripotency marker standardization harmonization as the inflection signal for cross-border supply chain interoperability.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | FDA mandates current Good Manufacturing Practice compliance for Phase I trial entry, filtering market access. |
| Feeder-Free Culture Standardization | Chemically defined media systems eliminate animal-derived variability, opening premium supplier positioning. |
| Blockchain Traceability Implementation | EMA tightened lineage documentation requirements, driving investment in chain-of-custody systems at German and Swiss sites. |
| Gene Editing Platform Integration | CRISPR-modified hESC lines displace wild-type substrates in pharmaceutical target validation workflows. |
| Regional Manufacturing Footprint | Cold-chain infrastructure scarcity constrains international distribution, favoring proximal production in United States, Germany, and Japan. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined through structured interviews with cell therapy development executives, regulatory affairs leads at biotechnology firms, hospital procurement managers, and contract research organization directors. Secondary validation drew from FDA Center for Biologics Evaluation and Research filings, EMA Committee for Advanced Therapies submissions, PMDA Sakigake designation records, and clinical trial registries. Bottom-up segmentation modeling and top-down market sizing triangulated demand estimates across product tiers and application categories.
Granularity-level modeling addressed frozen versus differentiated versus cultured stem cell formats, regenerative medicine versus disease modeling versus toxicology testing applications, and gene editing versus immunocytochemistry versus cell sorting technology platforms. CAGRs were derived through trend extrapolation of procurement budget expansion and regulatory pathway acceleration across the projection horizon. Forecast inputs incorporated hospital network cell therapy sourcing commitments, pharmaceutical developer outsourcing patterns, and biobank infrastructure investment cycles.
Revisions become necessary when pluripotency marker standardization diverges across regulatory jurisdictions, cryopreservation logistics capacity fails to match international shipment demand, or ethical sourcing legislation fragments material transfer agreements. Practitioners should monitor FDA-EMA-PMDA regulatory harmonization progress and blockchain traceability adoption rates for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Global Mrna Vaccine Market