
 Albendazole Drugs Market | 2026-2036
Albendazole Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Albendazole Drugs Market Outlook
Buyer concentration across national deworming programs is broadening as more ministries of health shift from donor-funded vertical campaigns to domestically financed procurement systems. GlaxoSmithKline leverages its established cold-chain logistics and prequalified status to sustain large-volume tenders in endemic regions. Cipla anchors the competitive landscape through backward integration into active pharmaceutical ingredient production, which controls cost structures for tablet and suspension formulations. Lupin differentiates by navigating complex bioequivalence requirements across multiple regulatory jurisdictions.
Albendazole drugs are benzimidazole anthelmintic agents with a broad spectrum of activity against nematode and cestode parasites, typically formulated as 400mg tablets or 100mg/5ml oral suspensions for human use and varying dosages for veterinary applications. The compounds function by inhibiting tubulin polymerization in parasitic cells, thereby disrupting glucose uptake and causing parasite death. Tablet formulations dominate procurement volumes due to stability advantages and compliance with WHO mass drug administration protocols, while suspension formats serve pediatric populations where swallowing capacity is limited. The anthelmintic treatment application commands the largest revenue pool, though veterinary medicine represents the fastest-growing segment as livestock producers intensify parasite control programs. Granule formulations remain a niche margin category, primarily positioned for companion animal markets in developed economies.
FDA bioequivalence standards and WHO prequalification requirements shape market access for generic albendazole manufacturers, with EMA inspections adding compliance costs for European-bound exports. India's CDSCO enforces mandatory stability testing and dissolution specifications that align with ICH guidelines, creating regulatory convergence for export-oriented producers. China's NMPA maintains separate pharmacopoeial standards that require additional local clinical validation for market entry. Stakeholders must monitor evolving impurity profiling requirements under ICH M7 guidelines, as regulatory agencies tighten genotoxic impurity thresholds that could force reformulation investments or supplier changes.
Market Dynamics
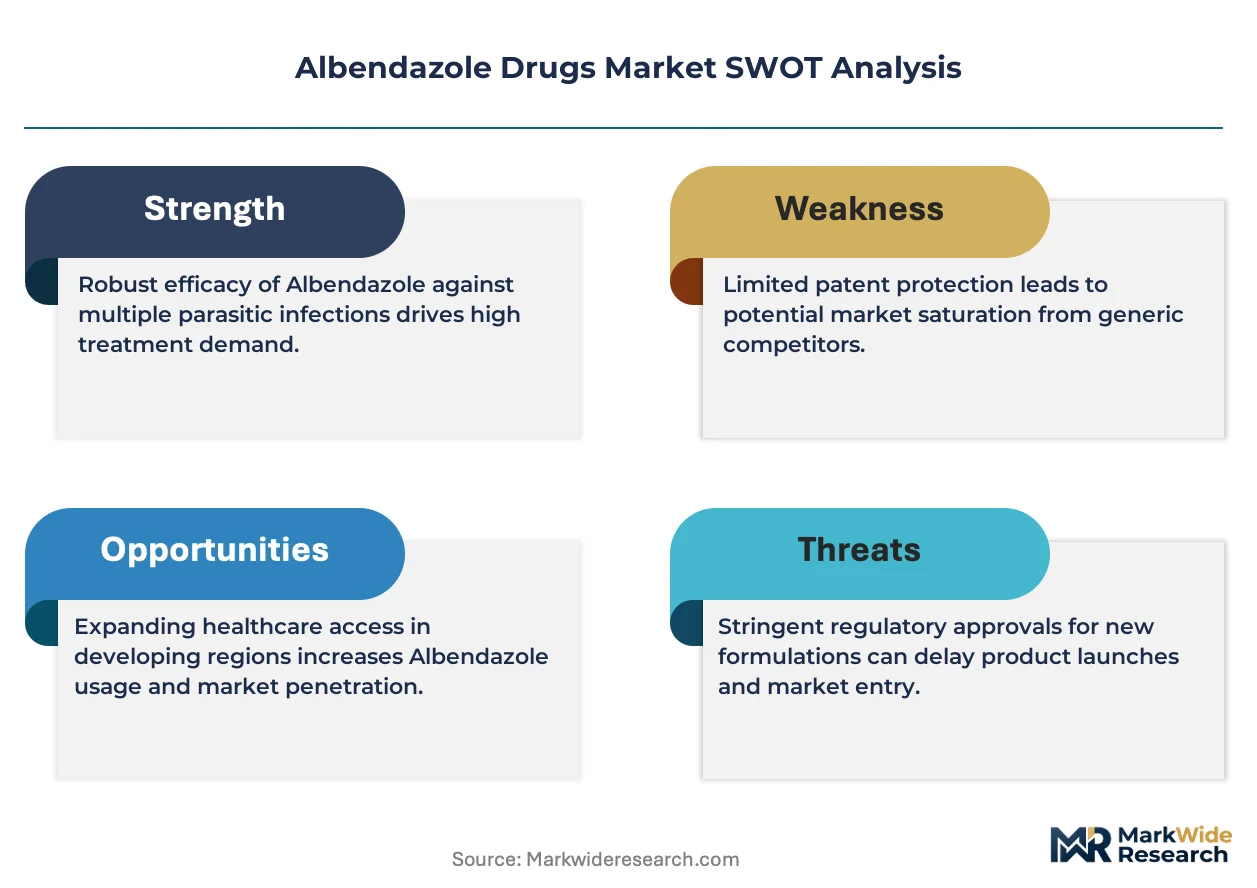
Generic manufacturers face intensifying WHO prequalification standards that demand tighter impurity thresholds and extended stability documentation, compressing margins for non-integrated producers while rewarding backward-integrated API suppliers with tender access.
Growth Catalysts
- India's PLI scheme for pharmaceuticals:Domestic API production incentives are expanding captive manufacturing capacity for export-oriented albendazole tablet and suspension formulations.
- Mass drug administration protocols:WHO-directed deworming campaigns in sub-Saharan Africa and South Asia are institutionalizing annual procurement cycles for 400mg tablet volumes.
- Livestock intensification:Veterinary anthelmintic programs across Brazil and Vietnam are broadening demand for granule and pour-on formulations in commercial cattle operations.
Market Restraints
- API supply concentration:Over 70% of albendazole active pharmaceutical ingredient originates from Zhejiang and Shandong manufacturing clusters, creating single-geography disruption risk.
- ICH M7 compliance costs:Genotoxic impurity profiling requirements are forcing reformulation investments for legacy generic portfolios.
- Substitution by ivermectin combinations:Fixed-dose anthelmintic therapies are displacing standalone albendazole in select veterinary protocols.
Strategic Opportunities
- Indonesia's domestic procurement transition:Ministry of Health decentralization is creating entry points for prequalified suppliers outside traditional donor channels.
- Pediatric suspension demand:WHO guidelines for preschool deworming are expanding addressable volume for 100mg/5ml oral suspension formats.
- Continuous manufacturing adoption:FDA quality guidance on process analytical technology is enabling real-time release for high-volume tablet production.
Industry Challenges
- Bioequivalence study complexity:EMA and FDA divergence on fasting versus fed-state protocols is extending approval timelines for generic submissions.
- Cold-chain integrity in last-mile distribution:Suspension formulations require validated storage below 30°C through humid tropical corridors where infrastructure gaps persist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Albendazole Drugs Market |
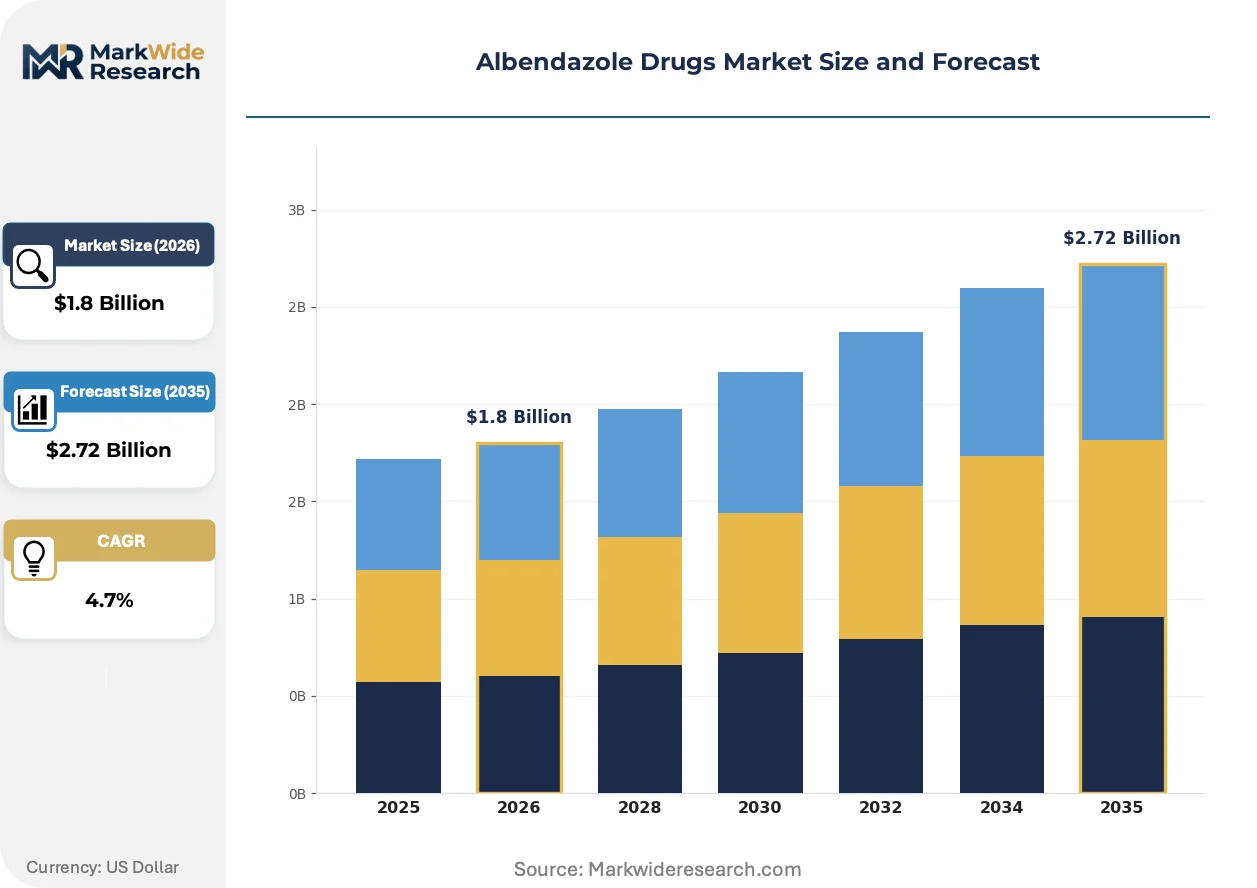
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Suspension, Injectable, Granules End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Direct Sales, Wholesalers, Retail Pharmacies, Online Application: Anthelmintic Treatment, Zoonotic Infections, Veterinary Medicine, Others |
| Companies Covered | GlaxoSmithKline, Cipla, Lupin, Amneal Pharmaceuticals, Sequent Scientific, Fredun Pharmaceuticals, Salius Pharma, Lasa Supergenerics Limited, Huazhong Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Albendazole Drugs Market Strategic Shifts
Formulation science and regulatory chemistry are converging to reshape competitive access in anthelmintic manufacturing, with purity analytics and process control emerging as the decisive capability differentiators.
Process analytical technology is unifying real-time dissolution monitoring with continuous tablet compression lines. Contract manufacturers serving WHO prequalification tenders are adopting PAT-enabled production to reduce batch rejection rates and accelerate stability data generation. This technology compression is collapsing the traditional 24-month validation timeline for generic albendazole submissions.
EMA inspections under the revised GMP framework for active substances are tightening documentation requirements for starting material provenance. European-bound API producers must now demonstrate genotoxic impurity controls across three synthesis steps rather than one. Indian and Chinese manufacturers are responding by consolidating supplier audits and investing in captive intermediate production.
Buyer consolidation through pooled procurement mechanisms is displacing fragmented national tendering. East African Community joint pharmaceutical purchasing is aggregating demand from Kenya, Tanzania, and Uganda into single-source contracts with prequalified suppliers. This mechanism shift favors manufacturers with established cold-chain logistics and multi-country registration portfolios over smaller national licensees.
Albendazole Drugs Market Segmentation
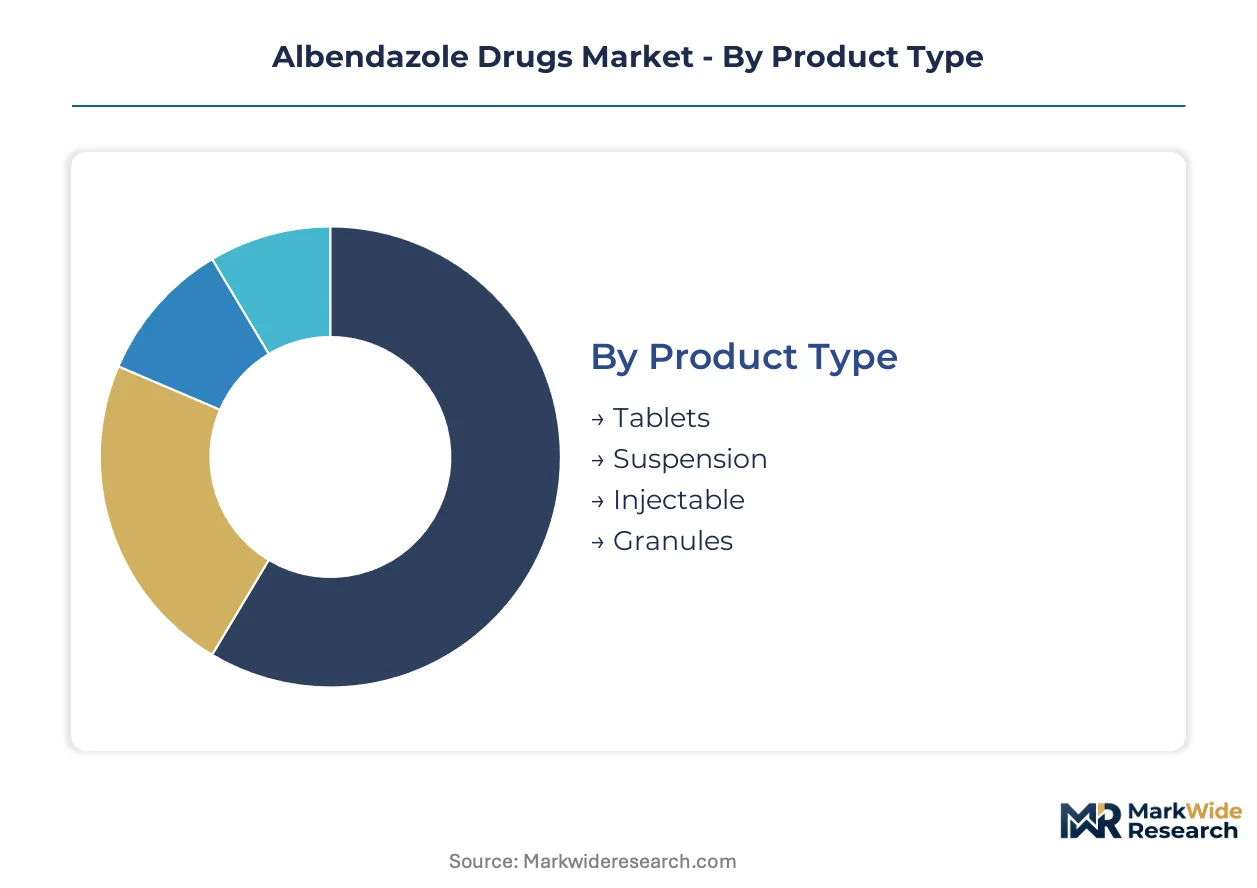
Albendazole procurement patterns diverge sharply across formulation types and patient settings, with WHO mass drug administration protocols favoring stable tablet formats while veterinary and pediatric channels demand specialized delivery systems. Understanding these segment boundaries reveals where formulation investments align with volume concentration versus margin capture.
Product Type:
Standardization dominates tablet production for donor-funded programs, while suspension and granule formats require customization for viscosity specifications and palatability profiles.
- Tablets:400mg solid oral dosage forms manufactured to USP dissolution specifications with 24-month shelf stability. Demand concentrates in India's contract manufacturing sector serving WHO prequalification tenders for sub-Saharan African national deworming programs, where CDSCO-aligned stability documentation accelerates regulatory approvals.
- Suspension:Aqueous 100mg/5ml formulations with preserved rheological properties for pediatric populations. Procurement volumes are climbing fastest in Indonesia's decentralized Ministry of Health system, where preschool deworming guidelines expand addressable need beyond school-age tablet campaigns.
- Injectable:Parenteral formulations for veterinary applications requiring sterile manufacturing suites and pyrogen-controlled production environments.
- Granules:Dry powder blends for companion animal markets in developed economies, positioned as niche margin products with specialized flavor masking requirements.
Leading the category by volume: Tablets. Growing fastest: Suspension.
End User:
Cost tiers separate institutional procurement from retail channels, with hospitals and clinics operating on tender-based volume pricing while homecare commands premium per-unit economics.
- Hospitals:Inpatient settings managing severe parasitic infections with controlled administration protocols. India's public health infrastructure anchors procurement through state-level centralized purchasing, where backward-integrated manufacturers capture tender access via CDSCO-compliant API documentation.
- Clinics:Outpatient facilities serving peri-urban populations with diagnostic capacity for targeted anthelmintic therapy. Brazil's municipal health networks are expanding clinic-based dispensing as ANVISA streamlines registration pathways for essential medicines.
- Pharmacies:Retail distribution points for self-pay patients and prescription fulfillment.
- Homecare:Direct-to-patient administration settings for chronic parasitic management.
Volume leadership: Hospitals. Steepest expansion trajectory: Clinics.
Distribution Channel:
Channel selection tracks regulatory maturity, with direct sales penetrating prequalified institutional markets while wholesale networks fragment across informal retail layers.
- Direct Sales:Manufacturer-to-procurement-agency relationships for WHO prequalified tenders. GlaxoSmithKline leverages established cold-chain logistics to sustain large-volume contracts across endemic regions, bypassing intermediary margin extraction.
- Wholesalers:Aggregators serving fragmented pharmacy networks in secondary cities. Vietnam's pharmaceutical distribution consolidation is compressing wholesaler counts while elevating documentation requirements for temperature-validated storage.
- Retail Pharmacies:Point-of-sale channels for individual prescription fulfillment.
- Online:E-commerce platforms for veterinary and companion animal product segments.
Dominant by volume: Direct Sales. Gaining share fastest: Online.
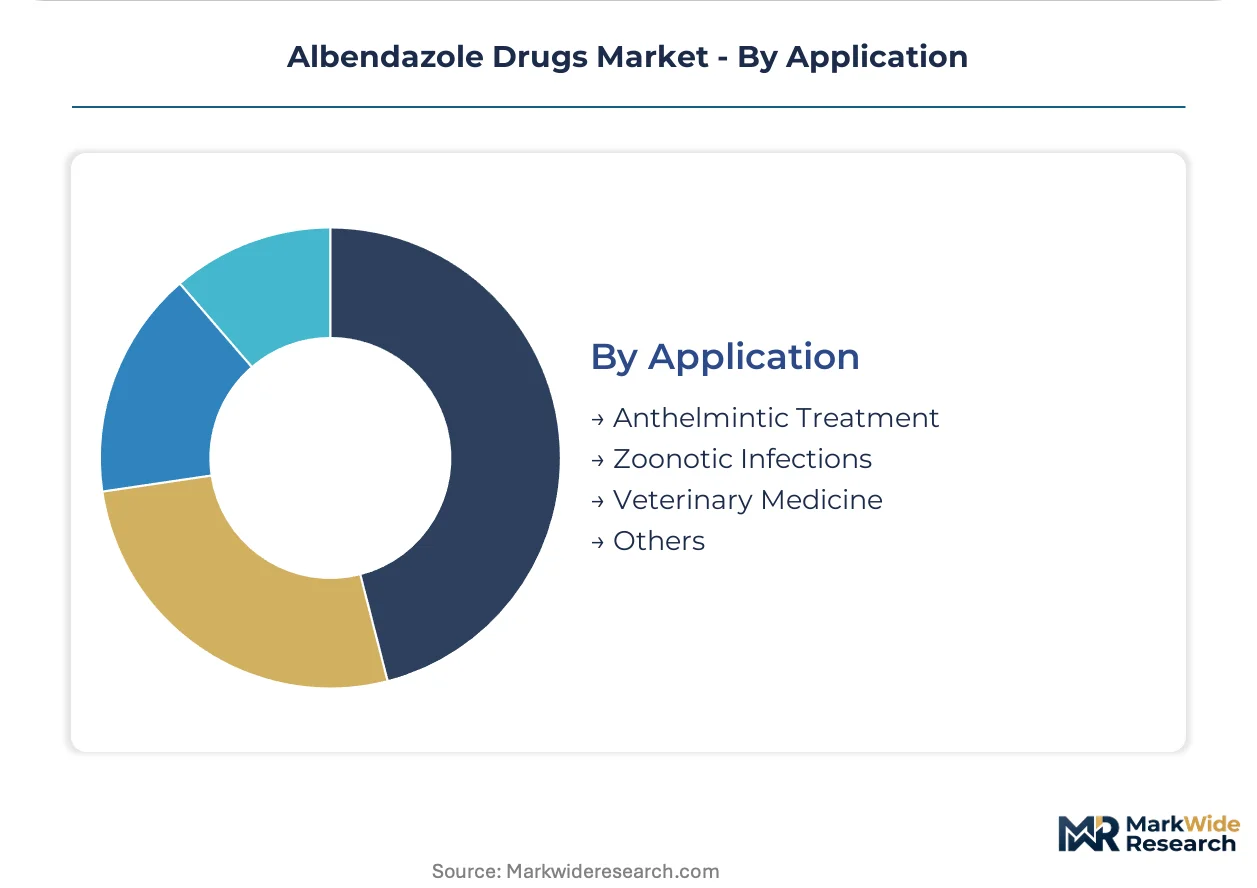
Application:
Margin structures invert across human and animal health, with anthelmintic treatment operating on thin tender economics while veterinary applications support formulation premiums.
- Anthelmintic Treatment:Human nematode and cestode infection management through mass drug administration. WHO-directed campaigns in Kenya, Tanzania, and Uganda institutionalize annual procurement cycles, with East African Community pooled purchasing favoring suppliers with multi-country registration portfolios.
- Veterinary Medicine:Livestock and companion animal parasite control programs. Brazil's cattle intensification and Vietnam's aquaculture expansion are broadening demand for species-specific formulations, where pour-on and granule delivery systems command premium positioning.
- Zoonotic Infections:Cross-species parasitic disease protocols at human-animal interfaces.
- Others:Off-label and investigational applications outside standard anthelmintic indications.
Volume concentration: Anthelmintic Treatment. Margin expansion: Veterinary Medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for albendazole concentrates in procurement systems transitioning from donor dependence to domestic financing, with manufacturing gravity shifting toward API-integrated production hubs in South Asia and East Asia.
India
State-level centralized purchasing through Tamil Nadu and Maharashtra health departments anchors tablet procurement volumes for national deworming programs. CDSCO enforces mandatory stability testing aligned with ICH guidelines, accelerating regulatory approvals for export-oriented manufacturers. Hyderabad and Ahmedabad clusters house backward-integrated API producers serving WHO prequalification tenders.
China
Zhejiang and Shandong manufacturing clusters supply over 70% of global albendazole active pharmaceutical ingredient, creating geographic concentration risk for formulation producers. NMPA maintains separate pharmacopoeial standards requiring additional local clinical validation for market entry. Qingdao-based intermediates producers are consolidating supplier audits under revised GMP frameworks.
Indonesia
Ministry of Health decentralization is expanding preschool deworming guidelines beyond school-age tablet campaigns, driving suspension format demand. The national procurement transition creates entry points for prequalified suppliers outside traditional donor channels. Java-based distributors are building temperature-validated storage capacity for humid tropical corridors.
Brazil
ANVISA streamlines registration pathways for essential medicines, expanding clinic-based dispensing through municipal health networks. Cattle intensification in São Paulo and Minas Gerais states broadens veterinary anthelmintic demand for pour-on formulations. Domestic granule producers are capturing companion animal market premiums through specialized flavor masking.
Kenya
East African Community pooled purchasing aggregates demand from Kenya, Tanzania, and Uganda into single-source contracts favoring multi-country registration holders. WHO-directed mass drug administration institutionalizes annual procurement cycles for 400mg tablet volumes. Nairobi serves as the regional logistics hub for cold-chain distribution into humid tropical last-mile corridors.
Albendazole Drugs Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue veterinary specialization and pediatric formulation niches. The vendor base stratifies across three tiers: multinational pharmaceuticals with prequalified status, mid-cap Indian generics with captive API supply, and regional specialists focused on single-format production. Two strategic archetypes dominate competitive positioning: backward-integrated cost leaders and regulatory-specialized tender navigators. Capacity expansion and multi-country registration portfolio building represent the dominant competitive moves.
Within the multinational tier, GlaxoSmithKline leverages established cold-chain logistics to sustain large-volume contracts across endemic regions. Among Indian integrated producers, Cipla anchors competitive positioning through in-house production of active pharmaceutical ingredients, while Lupin occupies a position navigating complex bioequivalence requirements across multiple regulatory jurisdictions. These three exemplify how regulatory capability and supply chain control separate tender winners from price-takers.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Cipla |
| Lupin |
| Amneal Pharmaceuticals |
| Sequent Scientific |
| Fredun Pharmaceuticals |
| Salius Pharma |
| Lasa Supergenerics Limited |
| Huazhong Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Backward integration into active pharmaceutical ingredient production anchors both supply security and margin protection for albendazole manufacturers, with Indian and Chinese producers leveraging captive synthesis capacity to buffer against raw material volatility while commanding tender access through cost discipline.
Pricing Analysis
Volume leadership in 400mg tablet procurement for WHO mass drug administration programs operates on thin tender economics, while pediatric suspension and veterinary granule formats capture margin premiums through specialized formulation requirements. Price differentiation hinges on WHO prequalification status and backward-integrated API supply, with certified manufacturers extracting modest premiums over non-integrated competitors. Cost compression in the standard tablet tier is intensifying as Indonesia and Kenya shift procurement toward domestic financing, squeezing intermediaries. National deworming programs exhibit acute price sensitivity, whereas companion animal veterinary channels in Brazil tolerate higher per-unit costs for palatability-engineered granules.
Supply Chain Analysis
Regional distribution centers in Nairobi, Jakarta, and São Paulo orchestrate hub-and-spoke patterns into humid tropical last-mile corridors where cold-chain integrity for suspension formulations remains problematic. API supply concentrates in Zhejiang and Shandong province manufacturing clusters in China, with secondary formulation capacity anchored in Hyderabad and Ahmedabad production hubs in India. Raw material dependencies span benzimidazole intermediates, tubulin-binding precursors, and excipient-grade polymers. Single-source vulnerability in Chinese API supply creates structural exposure to geographic disruption. Distribution runs through direct sales channels for prequalified institutional tenders, supplemented by temperature-validated wholesaler networks for fragmented retail pharmacy penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API supply concentration in Chinese manufacturing clusters props pricing power for backward-integrated producers, with capacity bottlenecks in genotoxic impurity testing infrastructure sustaining margin premiums for compliant manufacturers.
For Market Incumbents: To counter displacement by ivermectin combination therapies in veterinary protocols, GlaxoSmithKline and Cipla should deepen captive intermediate production to satisfy EMA's revised GMP documentation requirements for starting material provenance. Cold-chain logistics investment in East African Community distribution corridors protects tender access against regional specialists with inferior last-mile capabilities. For New Entrants and Emerging Players: The price-point gap between premium veterinary granules and economy tablet tenders creates entry space for mid-tier suspension specialists targeting Indonesia's decentralized preschool deworming expansion. Veterinary aquaculture applications in Vietnam represent the most penetrable white-space segment, accessible through ANVISA-aligned regulatory consulting partnerships and species-specific formulation development. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational pharmaceuticals seeking prequalified status and multi-country registration portfolios. Long-term viability over the coming decade favors targets with demonstrated ICH M7 compliance and continuous manufacturing adoption. The signal to watch is East African Community joint purchasing aggregation favoring suppliers with validated tropical distribution infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| API Backward Integration | Captive benzimidazole intermediate production secures margin control against Zhejiang supply disruptions. |
| WHO Prequalification Pursuit | Certification unlocks large-volume tenders in Kenya, Tanzania, and Uganda national deworming programs. |
| Pediatric Suspension Expansion | 100mg/5ml format development captures Indonesia Ministry of Health decentralized procurement growth. |
| Continuous Manufacturing Adoption | FDA process analytical technology guidance enables real-time release collapsing validation timelines. |
| Veterinary Granule Specialization | Flavor-masked companion animal formulations command premium positioning in São Paulo retail channels. |
Study Parameters
Document review covered WHO prequalification registers, CDSCO stability testing guidelines, and EMA GMP inspection reports, complemented by interviews with regulatory affairs directors at Indian generic manufacturers, procurement managers at East African Community health ministries, and veterinary product specialists at Brazilian distributors. Secondary validation drew from FDA bioequivalence study databases, ICH M7 impurity profiling standards, and national pharmaceutical tender announcements. Bottom-up tablet and suspension volume estimates were triangulated against top-down API production capacity assessments from Zhejiang and Shandong manufacturing clusters.
Segment-level outputs across formulation type, end user channel, and application category were generated through multi-dimensional modeling of procurement cycle timing, regulatory approval trajectories, and livestock intensification patterns. CAGRs were derived from trend extrapolation of mass drug administration protocol expansion, veterinary program adoption curves, and contract manufacturing capacity buildouts. Forecast inputs incorporated CDSCO-aligned dissolution specifications, cold-chain infrastructure investment pipelines, and pooled purchasing mechanism adoption rates.
Inputs from WHO Essential Medicines List updates and national procurement agency disclosures were available through the study window; gaps in real-time tender award pricing introduce uncertainty bands around volume-to-value conversion assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Fetal Valproate Syndrome Market