
 Glioblastoma Multiforme (GBM) Market | 2026-2036
Glioblastoma Multiforme (GBM) Market Size, Share, and Industry Trends Forecast 2026-2036
Glioblastoma Multiforme (GBM) Market Foresight
Project finance for late-stage oncology trials is rewriting competitive entry conditions in GBM therapeutics. F. Hoffmann-La Roche Ltd leverages its diagnostic-therapeutic integration to anchor clinical trial recruitment across European sites. Merck & Co., Inc. sustains leadership in checkpoint inhibitor combinations through dedicated neuro-oncology research funding. Novocure differentiates with device-drug pairing models that extend its electric field therapy into adjuvant settings.
Glioblastoma multiforme constitutes a grade IV astrocytoma characterized by pseudopalisading necrosis, microvascular proliferation, and EGFR amplification, with median survival of fifteen months despite maximal surgical resection followed by chemoradiation. The condition demands multimodal management combining gross total resection, temozolomide chemotherapy, and tumor-treating fields. Therapeutic drugs command the largest revenue share as novel small-molecule inhibitors and antibody-drug conjugates enter Phase II programs. Immunotherapy represents the fastest-expanding technology segment, though checkpoint inhibitors face blood-brain barrier penetration challenges that gene therapy approaches aim to circumvent.
FDA orphan drug designation and EMA PRIME eligibility schemes compress development timelines while mandating rigorous survival endpoints that shape Phase III trial design. WHO classification updates for central nervous system tumors redefine enrollment criteria and reimbursement coding across Health Canada and PMDA jurisdictions. Stakeholders must monitor biomarker-driven patient stratification as IDH mutation status and MGMT methylation testing become gatekeepers for protocol eligibility and payer coverage decisions.
Market Dynamics
The glioblastoma multiforme market pivots on blood-brain barrier penetration failures that have stalled checkpoint inhibitor efficacy, forcing investment into gene therapy vectors and focused ultrasound delivery systems as the primary competitive battleground.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-III transitions for orphan oncology indications, reducing capital requirements for novel small-molecule developers targeting recurrent GBM populations.
- MGMT Methylation Testing:Biomarker stratification expands addressable patient pools by identifying temozolomide-responsive subpopulations, improving payer coverage rates for adjuvant protocols.
- Japan Neuro-Oncology Infrastructure:Dedicated PMDA consultation pathways and university hospital network expansion concentrate clinical trial recruitment in Tokyo, Osaka, and Nagoya clusters.
Market Restraints
- Avastin Biosimilar Erosion:Bevacizumab price compression in European markets squeezes margin structures for anti-angiogenic maintenance therapy, pressuring originator revenue retention.
- CNS Penetration Limitations:Large-molecule biologics face efflux transporter exclusion at the neurovascular interface, restricting therapeutic index expansion for antibody-drug conjugates.
- EMA PRIME Eligibility Barriers:Stringent survival endpoint requirements for conditional marketing authorization extend development timelines beyond typical oncology venture capital horizons.
Strategic Opportunities
- Device-Drug Pairing Models:Tumor-treating fields combined with alkylating agents create reimbursement advantages through bundled coding mechanisms in US Medicare and German statutory health insurance.
- IDH Wild-Type Stratification:WHO classification updates enable precision trial designs that exclude lower-grade gliomas, improving signal detection in primary GBM cohorts.
- Focused Ultrasound Blood-Brain Barrier Disruption:Temporary tight-junction opening enables chemotherapy dose escalation and immunotherapy access previously blocked by endothelial barriers.
Industry Challenges
- Neuro-Oncology Trial Design Complexity:Pseudoprogression confounds radiographic response assessment, requiring centralized review and delaying regulatory submissions.
- Gross Total Resection Standardization:Intraoperative imaging and fluorescence-guided techniques demand capital-intensive OR upgrades that fragment surgical quality across treatment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glioblastoma Multiforme (GBM) Market |
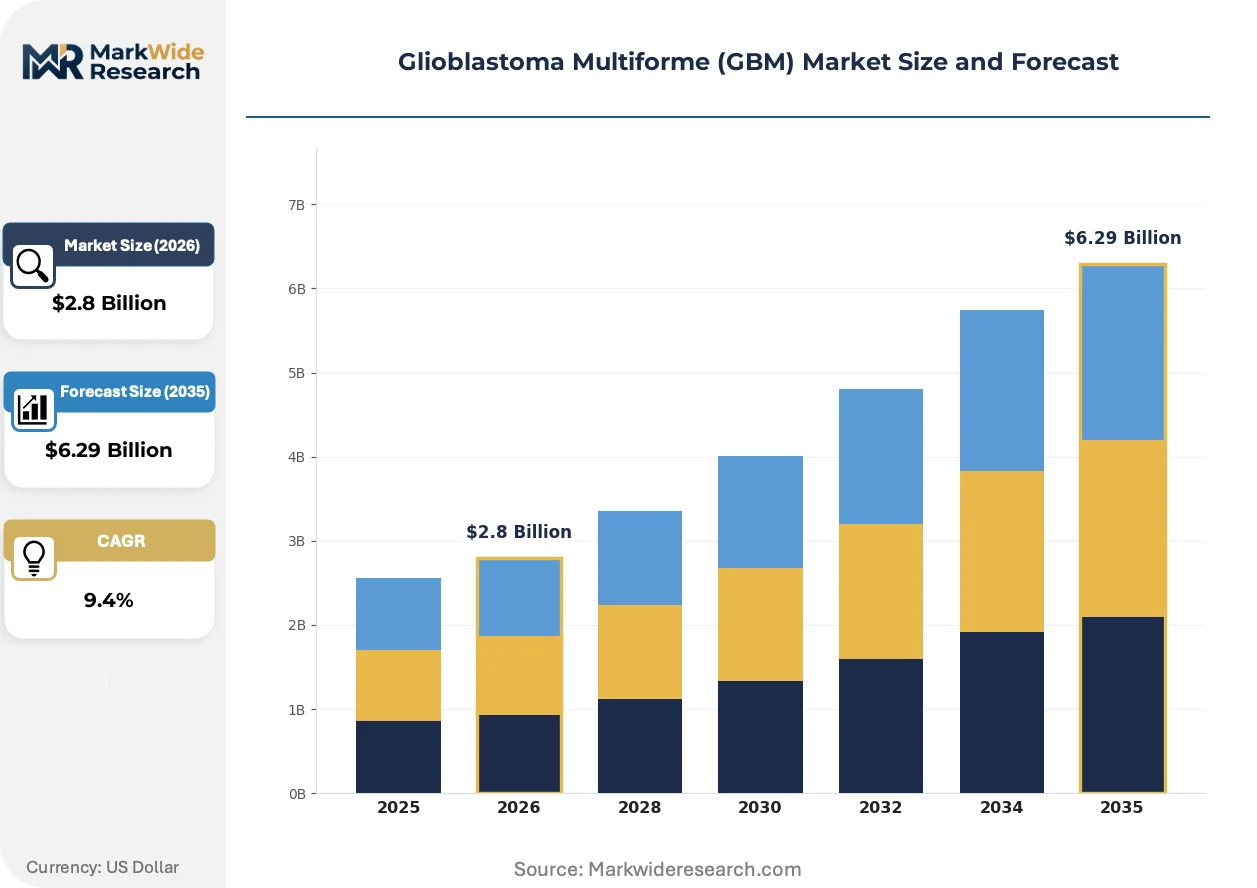
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging, Surgical Instruments, Therapeutic Drugs, Treatment Devices Application: Recurrence Prevention, Tumor Reduction, Symptom Management, Survival Extension, Quality of Life Improvement End User: Specialized Cancer Centers, Neurosurgery Clinics, Research Institutes, Rehabilitation Facilities Technology: MRI, Radiation Therapy, Immunotherapy, Targeted Drug Delivery, Gene Therapy |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Amgen, Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Bristol Myers Squibb Company, AbbVie Inc., Novocure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glioblastoma Multiforme (GBM) Market Shifts & Advancements
Digital pathology and artificial intelligence are compressing diagnostic timelines while liquid biopsy platforms enable treatment monitoring without repeated surgical intervention, fundamentally restructuring how GBM care pathways are orchestrated.
CAR-T cell therapy is virtualizing adoptive immunotherapy for GBM through locoregional delivery systems that circumvent systemic cytokine release syndrome. Academic medical centers in Boston and Heidelberg are piloting intracavitary infusion protocols. This delivery innovation is virtualizing the competitive landscape by enabling autologous cell therapies previously excluded from CNS indications.
EMA's PRIME eligibility scheme mandates rigorous survival data for accelerated access, forcing sponsors to power Phase III trials for overall survival rather than progression-free survival endpoints. German and French reimbursement authorities now require mature survival curves prior to temporary funding decisions. Biotech developers are responding by embedding European sites earlier in global development programs.
Patient advocacy organizations are consolidating procurement influence through centralized referral networks that direct cases toward trial-enrolling centers. US-based National Brain Tumor Society and German Brain Tumor Association now publish treatment facility ratings based on molecular profiling availability. This concentration is most visible in metropolitan corridors connecting Baltimore, Philadelphia, and New York, where competing health systems vie for neuro-oncology volume through specialized multidisciplinary programs.
Glioblastoma Multiforme (GBM) Market Segmentation
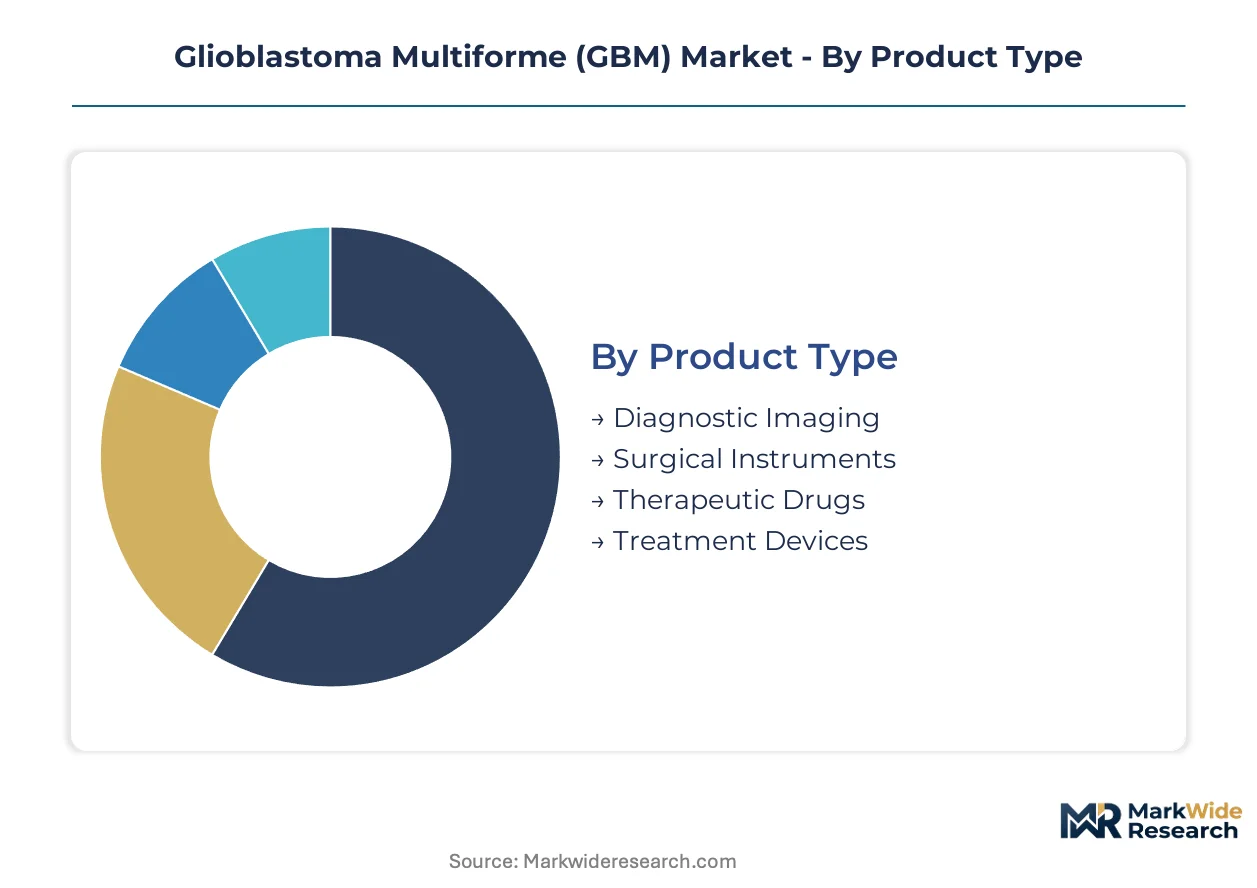
GBM treatment pathways fragment across diagnostic, surgical, pharmaceutical, and device modalities. Each segment carries distinct reimbursement codes and regulatory approval timelines that shape competitive entry strategies.
Product Type:
The use-case spectrum spans detection through chronic management, with capital equipment and consumable drugs occupying different margin structures.
- Therapeutic Drugs:Novel small-molecule inhibitors and antibody-drug conjugates dominate revenue concentration. Temozolomide anchors adjuvant protocols while investigational agents target recurrent populations in United States and German trial sites.
- Diagnostic Imaging:Advanced MRI sequences with perfusion and spectroscopy capabilities enable pseudoprogression differentiation. Demand clusters at academic medical centers in Baltimore, Philadelphia, and New York corridors where multidisciplinary programs compete for neuro-oncology volume.
- Surgical Instruments:Fluorescence-guided resection systems and intraoperative imaging platforms support gross total resection standards.
- Treatment Devices:Tumor-treating field arrays and focused ultrasound systems create bundled reimbursement opportunities in Medicare and German statutory health insurance.
Established volume favors therapeutic drugs; emerging adoption favors treatment devices.
Application:
Cost tier stratification separates curative-intent interventions from palliative protocols with divergent payer willingness-to-pay.
- Tumor Reduction:Gross total resection combined with chemoradiation constitutes the foundational curative approach. United States and Japanese centers concentrate adoption of intraoperative imaging and fluorescence-guided techniques.
- Survival Extension:Maintenance temozolomide and tumor-treating fields target fifteen-month median survival benchmarks. Payer coverage decisions hinge on MGMT methylation status testing availability.
- Recurrence Prevention:Adjuvant protocols and experimental immunotherapy combinations occupy clinical trial settings.
- Symptom Management:Corticosteroid and anti-epileptic regimens address edema and seizure control.
- Quality of Life Improvement:Supportive care integration shapes multidisciplinary program ratings from patient advocacy organizations.
Margin concentration sits with tumor reduction; fastest volume expansion tracks survival extension protocols.
End User:
Customer type fragmentation reflects capital intensity and regulatory sophistication requirements across the care continuum.
- Specialized Cancer Centers:Comprehensive neuro-oncology programs integrate surgical, medical, and radiation oncology with dedicated molecular pathology. These sites anchor FDA and EMA accelerated approval trial recruitment.
- Neurosurgery Clinics:Focused resection volume drives instrument and imaging platform procurement. German university hospital networks and Japanese metropolitan clusters concentrate this segment.
- Research Institutes:Academic medical centers in Boston and Heidelberg pilot locoregional CAR-T delivery and gene therapy vectors.
- Rehabilitation Facilities:Post-acute care addresses neurological deficit recovery following definitive treatment.
Procurement authority concentrates at specialized cancer centers; research institutes command protocol innovation influence.
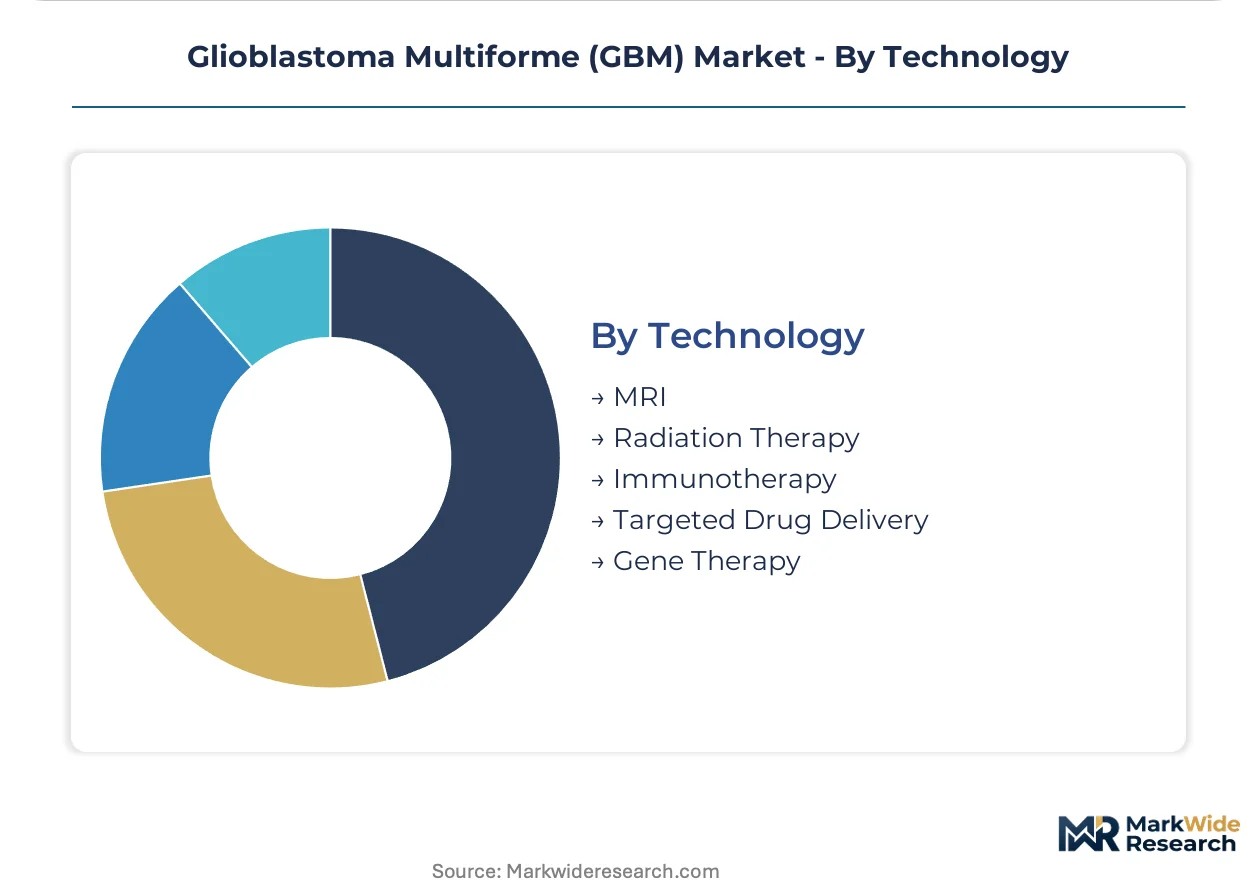
Technology:
Maturity gradients separate decades-old modalities from experimental platforms still navigating blood-brain barrier penetration challenges.
- Immunotherapy:Checkpoint inhibitors face CNS penetration limitations that gene therapy approaches aim to circumvent. CAR-T cell platforms are virtualizing adoptive immunotherapy through intracavitary delivery systems.
- Targeted Drug Delivery:Focused ultrasound blood-brain barrier disruption enables chemotherapy dose escalation and large-molecule access previously blocked by endothelial tight junctions.
- MRI:Advanced sequences support treatment response assessment and pseudoprogression differentiation.
- Radiation Therapy:Fractionated external beam protocols remain standard-of-care following maximal resection.
- Gene Therapy:Viral vector delivery systems target recurrent populations with localized transgene expression.
Clinical penetration favors MRI and radiation therapy; steepest expansion trajectory tracks immunotherapy despite biological barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and EMA PRIME eligibility schemes compress development timelines for orphan oncology indications, concentrating clinical trial recruitment and neuro-oncology infrastructure investment in specific national markets.
United States
Specialized cancer centers in Baltimore, Philadelphia, and New York corridors anchor FDA accelerated approval trial recruitment through dedicated molecular pathology programs. The National Brain Tumor Society publishes treatment facility ratings that concentrate patient referral networks toward trial-enrolling sites. Boston academic medical centers pilot locoregional CAR-T delivery systems for recurrent GBM populations.
Germany
University hospital networks in Heidelberg, Munich, and Hamburg integrate fluorescence-guided resection systems with statutory health insurance reimbursement for bundled device-drug protocols. EMA PRIME eligibility mandates rigorous survival endpoints that extend Phase III trial timelines beyond typical venture capital horizons. German Brain Tumor Association ratings drive patient concentration toward molecular profiling-capable centers.
Japan
PMDA consultation pathways and dedicated neuro-oncology infrastructure in Tokyo, Osaka, and Nagoya clusters concentrate clinical trial recruitment for adjuvant tumor-treating field protocols. Metropolitan hospital networks compete for neuro-oncology volume through multidisciplinary program development. Japanese reimbursement authorities require mature survival curves prior to temporary funding decisions for novel therapeutics.
United Kingdom
London and Cambridge academic medical centers leverage NHS specialized commissioning frameworks to integrate advanced MRI perfusion sequences into pseudoprogression differentiation protocols. MHRA alignment with EMA accelerated access pathways enables parallel regulatory submissions for gene therapy vectors. UK patient advocacy networks coordinate centralized referral toward molecular stratification-capable treatment facilities.
Switzerland
Swissmedic orphan drug designation procedures and Basel-Zurich pharmaceutical research corridors support diagnostic-therapeutic integration for clinical trial recruitment across European sites. Swiss university hospitals anchor collaborative networks extending into neighboring German and French neuro-oncology centers. The country's regulatory framework enables early access programs for recurrent GBM populations failing standard chemoradiation protocols.
Glioblastoma Multiforme (GBM) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across diagnostic-therapeutic integration, device-drug pairing, and biomarker-driven stratification vectors. The market structure concentrates around multinational pharmaceutical conglomerates with diagnostic capabilities, dedicated oncology biotech developers, and device manufacturers with reimbursement bundling expertise. Three strategic archetypes dominate: integrated diagnostic-therapeutic platforms, checkpoint inhibitor combination sponsors, and electric field therapy device specialists. Competitive moves center on strategic partnerships for blood-brain barrier penetration technologies and geographic expansion into Japanese and German neuro-oncology clusters.
Within the integrated diagnostic-therapeutic tier, F. Hoffmann-La Roche Ltd anchors clinical trial recruitment across European sites through diagnostic-therapeutic integration capabilities. Merck & Co., Inc. occupies a position exemplifying checkpoint inhibitor combination development through dedicated neuro-oncology research funding. Novocure represents the device-drug pairing archetype, extending electric field therapy into adjuvant settings through bundled reimbursement mechanisms. These three companies collectively illustrate the competitive convergence around blood-brain barrier penetration solutions and precision patient stratification.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Amgen, Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Bristol Myers Squibb Company |
| AbbVie Inc. |
| Novocure |
| Others |
Supply & Pricing Matrix
Single-source dependency on US-manufactured temozolomide API concentrates pricing power among three contract manufacturers, compressing margin structures for finished dose formulators while simultaneously forcing supply chain consolidation toward FDA-inspected sites with dedicated containment capacity.
Pricing Analysis
Certification level creates the primary spread across the GBM therapeutics landscape, with FDA-breakthrough-designated assets commanding premium positioning against standard-of-care alkylating agents. Three-tier pricing structure across premium, standard, and economy levels segments the market: novel small-molecule inhibitors with orphan exclusivity anchor the premium tier, branded temozolomide generics occupy the standard tier, and compounding pharmacy formulations serve price-sensitive recurrent populations. Pricing pressure stems from bevacizumab biosimilar erosion in European markets, where German and French statutory payers now reference-price anti-angiogenic maintenance therapy. Research institutes and academic medical centers exhibit highest price sensitivity due to fixed grant funding, while specialized cancer centers demonstrate willingness to absorb premium pricing for biomarker-stratified protocols with survival endpoint advantages.
Supply Chain Analysis
Tariff exposure between United States and Chinese heparin-derived excipient suppliers dominates supply chain risk planning for parenteral formulation developers. Active pharmaceutical ingredient production concentrates in United States, India, and Italy, with sterile manufacturing capacity tethered to FDA and EMA-inspected facilities in these jurisdictions. Raw material dependencies include platinum-based catalysts for synthetic chemistry routes, high-purity solvents for chromatographic purification, and borosilicate vials for sterile finished goods. Single-source vulnerability persists in focused ultrasound transducer arrays and tumor-treating field generator components, where Novocure maintains captive manufacturing. Distribution runs through specialized oncology distributors with cold-chain capabilities, anchored by AmerisourceBergen and McKesson in US markets and regional hospital purchasing cooperatives in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GBM market rewards service-attach models where molecular profiling and treatment response monitoring generate recurring revenue streams expanding faster than device hardware sales, particularly in US and German centers where bundled reimbursement codes now cover longitudinal biomarker testing.
For Market Incumbents: Entrench diagnostic-therapeutic integration capabilities by acquiring liquid biopsy platforms with CNS-specific methylation detection, countering the threat of decentralized pathology entrants. Deepen backward integration into viral vector manufacturing for gene therapy pipelines, securing captive supply of AAV serotypes with demonstrated blood-brain barrier tropism. Anchor capacity in Heidelberg and Boston academic corridors where EMA and FDA accelerated approval trial recruitment concentrates. For New Entrants and Emerging Players: Establish a beachhead in focused ultrasound blood-brain barrier disruption systems, the most penetrable segment where no incumbent dominates temporary tight-junction opening technology. Target Japanese metropolitan hospital networks in Tokyo and Osaka, where PMDA consultation pathways and dedicated neuro-oncology infrastructure create faster regulatory feedback loops. Pursue go-to-market angles pairing device placement with chemotherapy dose-escalation service contracts. For Investors and Strategic Acquirers: Device-drug pairing specialists with bundled reimbursement expertise represent the highest-conviction acquisition archetype, given Medicare and German statutory health insurance coding advantages. Long-term viability across the analysis window hinges on blood-brain barrier penetration solutions displacing failed checkpoint inhibitor approaches. Watch for inflection signals in locoregional CAR-T delivery readouts from Boston and Heidelberg pilot programs, which would validate intracavitary infusion as a scalable modality.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Compresses Phase II-to-III timelines for recurrent GBM small-molecule developers, reducing capital requirements. |
| Diagnostic-Therapeutic Integration | Roche anchors European trial recruitment by pairing IDH mutation testing with investigational drug protocols. |
| Device-Drug Bundled Reimbursement | Novocure extends electric field therapy into adjuvant settings through Medicare and German statutory insurance coding. |
| Locoregional CAR-T Delivery Pilot | Boston and Heidelberg academic centers virtualize adoptive immunotherapy through intracavitary infusion protocols. |
| MGMT Methylation Testing Expansion | Biomarker stratification identifies temozolomide-responsive subpopulations, improving payer coverage rates. |
Research Methodology
Cross-validation between primary interviews with neuro-oncology division heads, regulatory affairs leads at biotech developers, hospital formulary directors, and payer access specialists anchors the qualitative findings, supplemented by secondary analysis of FDA orphan drug designations, EMA PRIME eligibility submissions, ClinicalTrials.gov protocol registries, and CMS Medicare reimbursement coding decisions. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation reconcile volume and value estimates across the analysis window.
Calibration against historical approval timelines for CNS oncology assets informs the projection framework, with segmentation across therapeutic drug class, device modality, diagnostic technology, and regional regulatory cluster. CAGRs derive from modeled patient incidence, treatment penetration rates, and pricing trajectory assumptions. Forecast inputs include MGMT methylation testing adoption curves, focused ultrasound blood-brain barrier disruption clinical readout timelines, and Japanese PMDA consultation pathway utilization rates.
Stress conditions across regulatory approval delays, biosimilar entry acceleration, and blood-brain barrier penetration trial failures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from biomarker-driven protocol redesigns or reimbursement policy shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market