
 Fluorescence-Activated Cell Sorting Market | 2026-2036
Fluorescence-Activated Cell Sorting Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescence-Activated Cell Sorting Market Foresight
The fluorescence-activated cell sorting equipment landscape is consolidating around a sharp split between premium high-speed systems and commoditized benchtop units. BD leverages its installed base in clinical diagnostics to sustain pricing power for validated GMP-compliant sorters. Miltenyi Biotec GmbH specializes in magnetic-integrated workflows that anchor its position in cell therapy manufacturing. Thermo Fisher Scientific Inc. competes through channel breadth and service density across research institutions.
Fluorescence-activated cell sorting is a cytometric technique that separates heterogeneous cell populations into distinct subsets based on light scatter and fluorescence emission signatures, typically operating at pressures of 4-70 psi and droplet frequencies exceeding 100,000 events per second for clinical-grade instruments. Its primary purpose is to isolate pure target cell populations for downstream therapeutic, diagnostic, or research applications. High-speed sorters command the largest revenue share due to their irreplaceable role in chimeric antigen receptor T-cell manufacturing workflows. Benchtop sorters are gaining traction among academic centers with limited capital budgets and lower throughput demands. Acoustic sorting represents the fastest-emerging technology segment as manufacturers seek gentler cell handling alternatives to electrostatic deflection.
The FDA enforces current Good Manufacturing Practice standards that mandate extensive instrument qualification for cell sorting used in licensed therapeutic products, directly elevating total cost of ownership for end users. ISO 13485 certification and the EU Medical Device Regulation impose parallel quality system burdens on manufacturers seeking access to European clinical laboratories. Stakeholders must weigh the trade-off between capital investment in premium validated platforms and operational risk in an environment where regulatory scrutiny of cell therapy manufacturing continues to intensify.
Market Dynamics
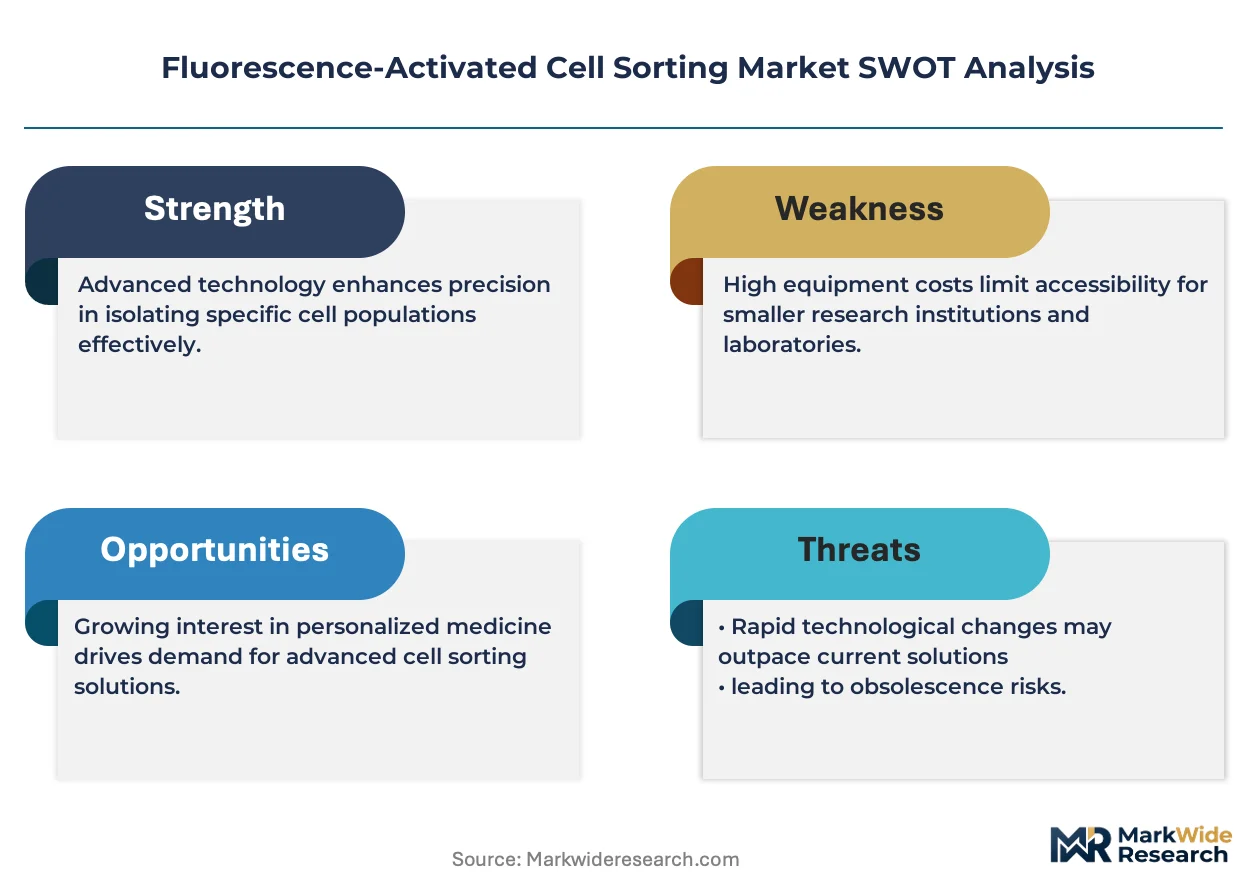
The fluorescence-activated cell sorting market is consolidating around a bifurcation between clinical-grade validated systems and research-grade instruments, driven by the FDA's tightening cell therapy manufacturing guidance and the capital intensity of GMP compliance.
Growth Catalysts
- Cell Therapy Manufacturing Surge:Chimeric antigen receptor T-cell production pipelines are scaling across academic medical centers and contract development organizations, creating sustained demand for high-throughput sterile sorting workflows.
- EMA's Advanced Therapy Medicinal Products Framework:The European regulatory pathway for gene and cell therapies is harmonizing quality standards across member states, reducing market fragmentation for instrument vendors seeking CE marking under MDR.
- Acoustic Sorting Technology Maturation:Microfluidic acoustic focusing systems are reducing shear stress on delicate primary cells, expanding addressable applications in induced pluripotent stem cell-derived therapies.
Market Restraints
- Laser and Optical Component Supply Concentration:Solid-state laser sources and precision flow cells rely on concentrated German and Japanese component suppliers, exposing lead times to geopolitical friction.
- Sheath Fluid Cost Volatility:Phosphate-buffered saline and proprietary sheath formulations face input cost pressure from pharmaceutical-grade chemical supply chains.
- ISO 13485 Certification Burden:The quality management system standard for medical devices imposes documentation and audit costs that disproportionately constrain mid-tier instrument developers.
Strategic Opportunities
- India's Biologics Manufacturing Expansion:The country's production-linked incentive scheme for pharmaceuticals is attracting contract manufacturing investment that will require localized sorting capacity.
- Point-of-Care Cell Processing:Miniaturized closed-system sorters are enabling decentralized manufacturing models that reduce cold chain logistics burdens for autologous therapies.
- Japan's Regenerative Medicine Safety Act:The PMDA's accelerated approval pathways for cell-based products are shortening validation timelines for instrument vendors with established Japanese distributor networks.
Industry Challenges
- Cytometry Specialist Talent Scarcity:The intersection of flow cytometry expertise and GMP manufacturing compliance represents a narrow labor pool that constrains facility expansion timelines.
- Legacy System Integration Complexity:Research-grade sorters retrofitted for clinical use face software validation gaps that complicate 21 CFR Part 11 compliance for electronic records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescence-Activated Cell Sorting Market |
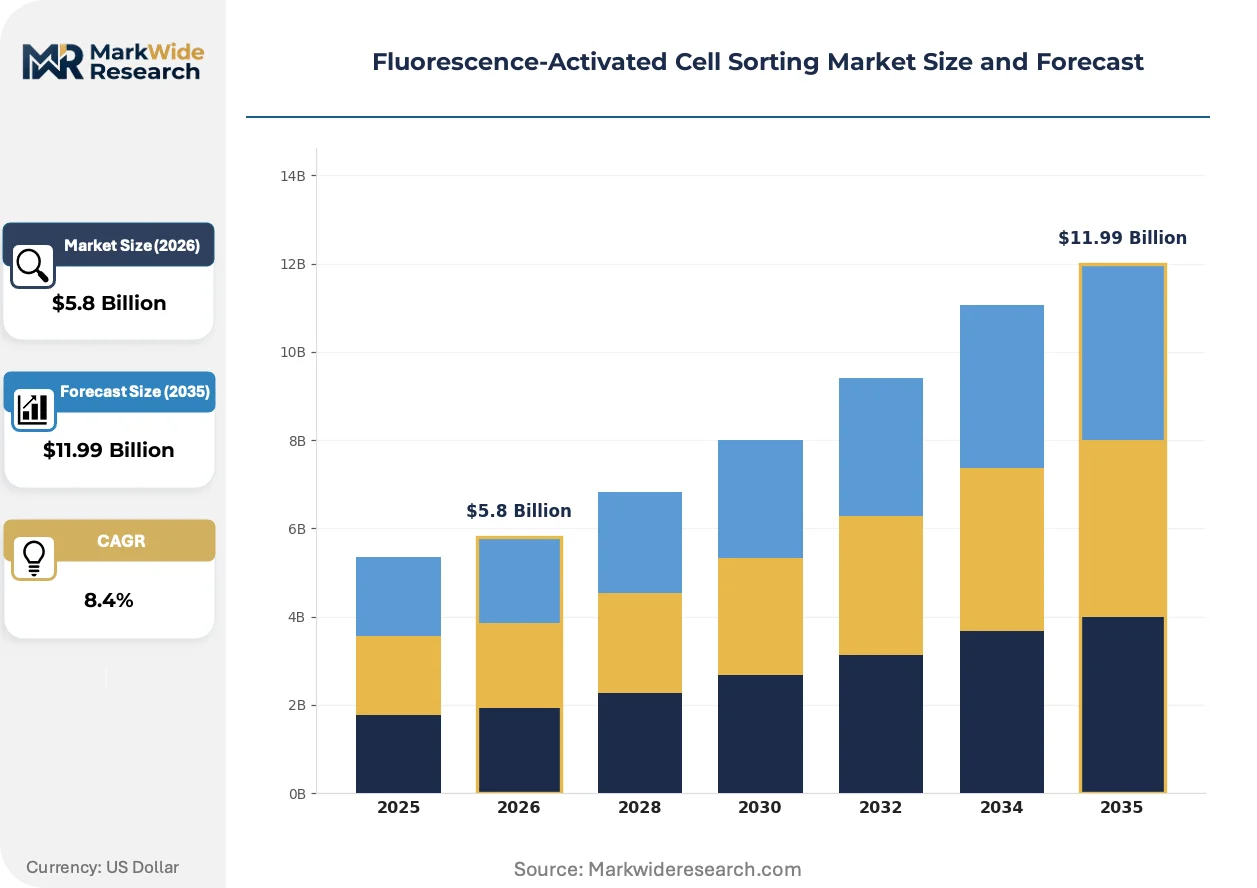
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Sorters, High-Speed Sorters, Research Sorters, Clinical Sorters, Portable Sorters Technology: Hydrodynamic Focusing, Electrostatic Deflection, Acoustic Sorting, Magnetic Sorting, Image-Based Sorting Application: Immunology, Stem Cell Research, Microbiology, Oncology, Neuroscience End User: Research Institutions, Biopharmaceutical Companies, Diagnostic Laboratories, Academic Centers, Government Agencies |
| Companies Covered | Beckman Coulter, Inc., Sony Biotechnology Inc., BD, Merck KGaA, Danaher Corporation, Thermo Fisher Scientific Inc., Miltenyi Biotec GmbH, Sysmex Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescence-Activated Cell Sorting Market Shifts & Advancements
Instrument architectures are fragmenting as end-users demand modular platforms that bridge research flexibility with clinical traceability, while regulatory pressure accelerates validation protocol standardization.
Microfluidic chip-based sorting is decentralizing cell processing workflows by eliminating the hydraulic complexity of traditional droplet deflection systems. Academic spinouts and niche vendors are adopting these platforms for low-volume precision applications. The structural consequence is compressing the addressable market for conventional electrostatic sorters in sub-clinical throughput segments.
The FDA's evolving guidance on co-manufacturing arrangements for cell and gene therapies is forcing instrument vendors to pre-validate software configurations for multi-site quality audits. This regulatory friction elevates switching costs for installed base customers. High-speed sorter manufacturers are responding by embedding audit trail automation and remote diagnostic capabilities as standard features.
Service contract unbundling is reshaping how research institutions acquire sorting capacity. Core facility managers are separating hardware leases from application support and consumable supply agreements. This pattern is most visible in United States academic medical centers, where shared instrumentation models face budget pressure from declining indirect cost recovery rates.
Fluorescence-Activated Cell Sorting Market Segmentation
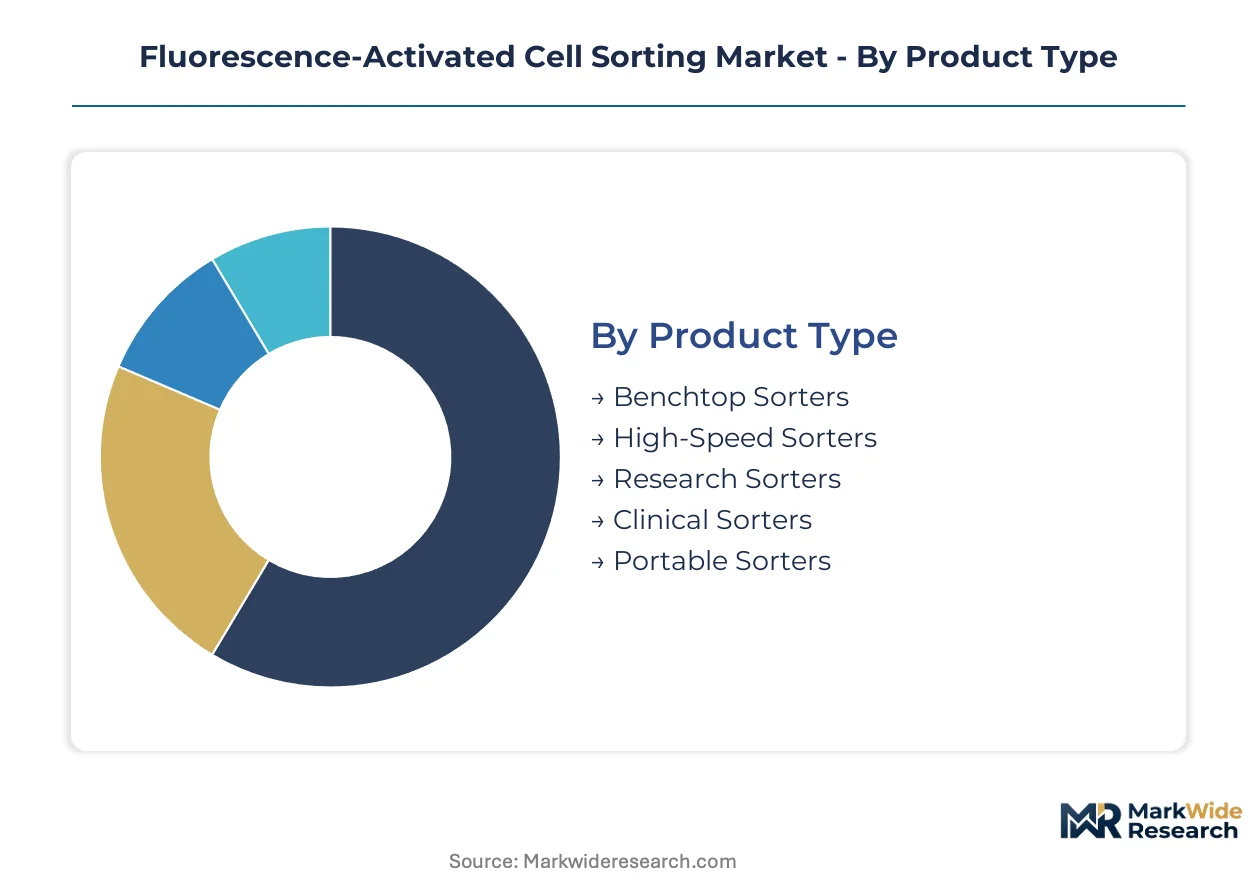
Segmentation in fluorescence-activated cell sorting reveals how capital allocation, regulatory compliance requirements, and application complexity fragment purchasing decisions across end users. Equipment specifications diverge sharply between research environments and GMP manufacturing floors.
Product Type:
Capital intensity varies by an order of magnitude across product tiers, with clinical validation requirements driving the widest investment spreads.
- High-Speed Sorters:These systems operate at droplet frequencies exceeding 100,000 events per second with sterile fluidics architectures. Demand concentrates at contract development organizations in the United States where chimeric antigen receptor T-cell manufacturing workflows require validated throughput.
- Clinical Sorters:FDA 21 CFR Part 11 compliant platforms with embedded audit trails and electronic signature capture. Academic medical centers in Boston and San Francisco are scaling installed capacity to support in-house cell therapy production pipelines.
- Benchtop Sorters:Compact footprint units with reduced optical channel counts serve core facilities with constrained capital budgets.
- Research Sorters:Flexible configuration platforms dominate basic science departments where protocol diversity outweighs standardization needs.
- Portable Sorters:Battery-operated microfluidic units are emerging for decentralized manufacturing models requiring point-of-care cell processing.
Most installed capacity flows through High-Speed Sorters. Expansion is steepest in Clinical Sorters.
Technology:
Technology selection hinges on cell viability requirements, with shear-sensitive primary cells driving adoption of gentler separation mechanisms.
- Acoustic Sorting:Microfluidic acoustic focusing eliminates electrostatic charging by using standing wave pressure nodes for cell manipulation. Stem cell research facilities in Singapore and California are adopting these platforms for induced pluripotent stem cell-derived therapy development where membrane integrity preservation is critical.
- Electrostatic Deflection:Traditional droplet-based sorting with charged deflection plates remains the throughput benchmark. Biopharmaceutical manufacturing sites in Germany and Switzerland maintain this technology for licensed therapeutic production where regulatory precedent reduces validation risk.
- Hydrodynamic Focusing:Core flow cytometry principle using sheath fluid to center cells in the interrogation point.
- Magnetic Sorting:Antibody-conjugated bead separation integrated with fluorescence detection for pre-enrichment workflows.
- Image-Based Sorting:High-speed camera systems capturing morphometric parameters alongside fluorescence signatures.
Electrostatic Deflection retains the largest installed base. Acoustic Sorting is climbing the fastest as manufacturers commercialize clinical-grade platforms.
Application:
Application segmentation tracks the migration of cell sorting from basic research tool to therapeutic manufacturing enabler.
- Oncology:Chimeric antigen receptor T-cell isolation and quality control represent the highest-value use case. Manufacturing facilities in Maryland and North Carolina are expanding sorting capacity to support commercial pipeline scale-up.
- Stem Cell Research:Pluripotent cell line derivation and differentiation monitoring require gentle handling protocols. Research consortia in Japan and the United Kingdom are driving instrument specifications through regenerative medicine safety frameworks.
- Immunology:Rare population isolation for mechanistic studies of immune cell subsets.
- Microbiology:Bacterial and yeast strain isolation for synthetic biology applications.
- Neuroscience:Neural progenitor and glial cell sorting from dissociated tissue.
Oncology commands the dominant share of capital deployment. Stem Cell Research is gaining share fastest as regulatory pathways mature.
End User:
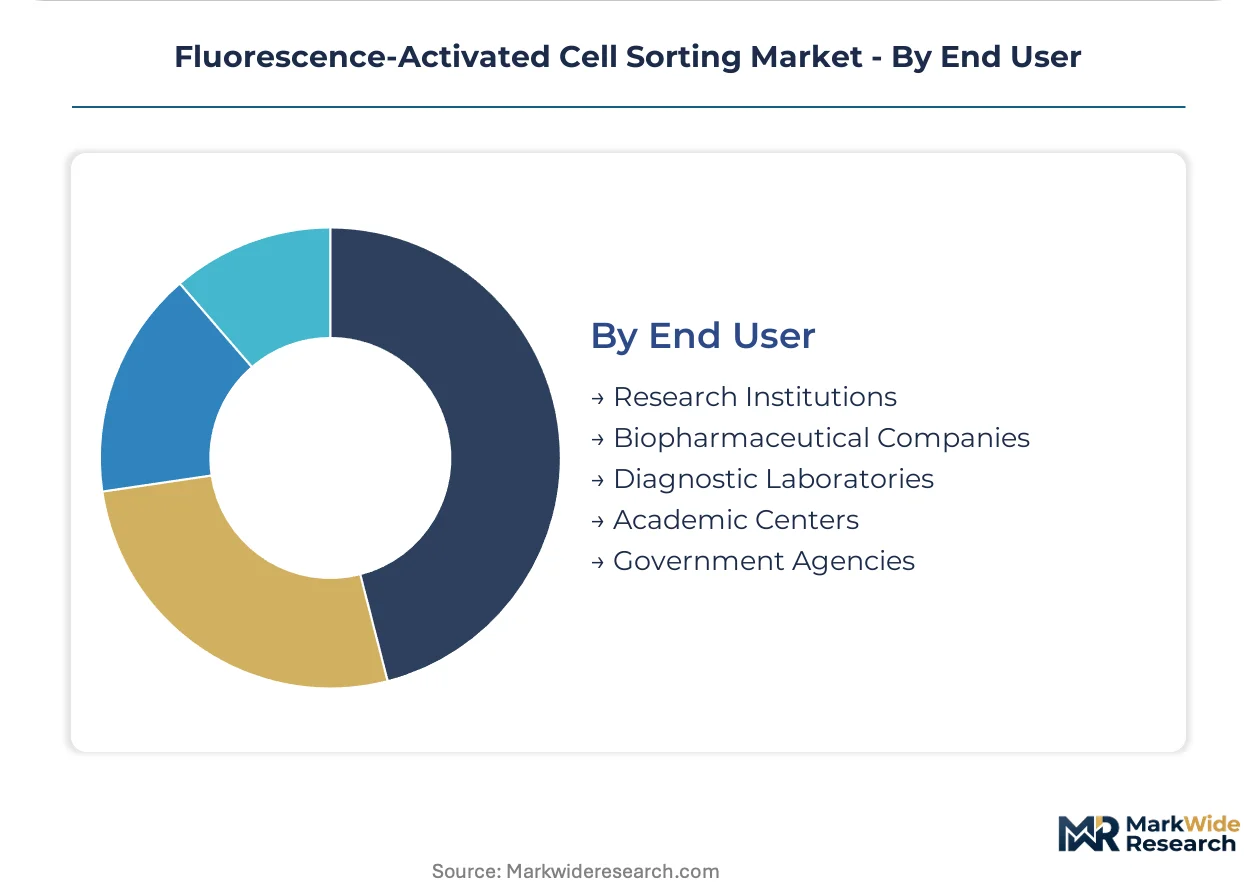
End user segmentation reflects divergent procurement authority, with biopharmaceutical companies consolidating purchasing decisions at enterprise level.
- Biopharmaceutical Companies:Integrated manufacturing organizations with dedicated GMP suites and validation teams. Facilities in Massachusetts and California are standardizing on single-vendor platforms to simplify multi-site audit protocols.
- Research Institutions:Shared core facilities serving multiple principal investigators with diverse application requirements. The National Institutes of Health-funded centers are facing indirect cost recovery pressures that compress equipment replacement cycles.
- Academic Centers:Individual laboratory purchases with departmental budget authority.
- Diagnostic Laboratories:Clinical reference labs with moderate throughput and regulatory compliance needs.
- Government Agencies:Public health and defense research facilities with specialized biosafety requirements.
Biopharmaceutical Companies account for the largest revenue concentration. Research Institutions are expanding most quickly in cell therapy-adjacent applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more GMP-validated sorting capacity than Japan, yet the United States deploys capital faster for cell therapy manufacturing scale-up. Regulatory divergence between FDA and EMA pathways shapes where vendors prioritize instrument qualification resources.
United States
Academic medical centers in Boston and San Francisco are expanding sterile sorting suites for in-house CAR-T production pipelines. The FDA's evolving guidance on co-manufacturing arrangements mandates pre-validated software configurations for multi-site quality audits. Maryland and North Carolina manufacturing clusters are absorbing the highest concentration of high-speed sorter deployments.
Germany
Precision component suppliers in Baden-Württemberg and Bavaria dominate solid-state laser and flow cell fabrication for instrument OEMs. The EU Medical Device Regulation imposes parallel quality system burdens that extend CE marking timelines for clinical-grade platforms. Heidelberg and Munich research consortia are driving specifications for acoustic sorting technology in stem cell applications.
Japan
The PMDA's accelerated approval pathways under the Regenerative Medicine Safety Act are shortening validation timelines for instrument vendors with established distributor networks. Kanto and Kansai regions host the densest concentration of induced pluripotent stem cell research facilities. Osaka-based manufacturing sites are retrofitting electrostatic deflection systems for licensed therapeutic production.
India
The production-linked incentive scheme for pharmaceuticals is attracting contract manufacturing investment that will require localized sorting capacity. CDSCO's evolving biologics oversight framework is tightening instrument qualification expectations for export-oriented facilities. Maharashtra and Telangana are emerging as the primary clusters for biologics manufacturing infrastructure expansion.
Singapore
Stem cell research facilities are adopting microfluidic acoustic focusing platforms for membrane-sensitive primary cell handling. The national pharmaceutical regulator harmonizes quality standards with ASEAN member states to reduce market fragmentation for instrument vendors. Biopolis and one-north research hubs are concentrating demand for gentle cell separation technologies.
Fluorescence-Activated Cell Sorting Market Competitive Landscape
Top-tier vendors anchor the premium validated-system tier, while mid-scale specialists and regional fabricators compete on price and application flexibility. The market structure reflects heavy consolidation around clinical-grade platforms with embedded compliance architectures. Strategic archetypes include integrated life science conglomerates, magnetic workflow specialists, and acoustic technology disruptors. Dominant competitive moves encompass backward integration into precision optical components and technology licensing partnerships for microfluidic chip architectures.
Among diversified life science conglomerates, Danaher Corporation and Thermo Fisher Scientific Inc. exemplify scale-driven positioning through channel breadth and service density across research institutions. Miltenyi Biotec GmbH occupies a distinct position within the magnetic-integrated workflow archetype, anchoring its market presence in cell therapy manufacturing environments where pre-enrichment protocols reduce downstream sorting burden. Beckman Coulter, Inc. and Bio-Rad Laboratories, Inc. represent the analytical instrumentation heritage tier, leveraging decades of cytometry expertise to sustain installed base loyalty amid platform transition cycles.
| Leading Market Players |
|---|
| Beckman Coulter, Inc. |
| Sony Biotechnology Inc. |
| BD |
| Merck KGaA |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Miltenyi Biotec GmbH |
| Sysmex Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Supply & Pricing Matrix
Clinical-research grade bifurcation in fluorescence-activated cell sorting equipment manifests in both pricing stratification and supply chain configuration, with FDA 21 CFR Part 11 compliant platforms commanding fivefold premiums over benchtop units while drawing from entirely different component supplier networks in Germany and Japan.
Pricing Analysis
Capacity additions in Baden-Württemberg and Bavaria are reshaping price floors for precision optical subassemblies, compressing margins for mid-tier instrument developers unable to achieve ISO 13485 certification economies. Three-tier pricing structure across GMP-validated, research-grade, and portable microfluidic levels separates biopharmaceutical manufacturers from academic core facilities from point-of-care deployers. Price differentiation hinges on electronic signature capture capabilities and sterile fluidics architectures. Cost compression in research-grade segments is intensifying because declining NIH indirect cost recovery rates compress equipment replacement cycles. Academic medical centers exhibit highest price sensitivity; contract development organizations least.
Supply Chain Analysis
Specialized photonics engineers in Germany, Japan, and the United States constrain production scaling for solid-state laser modules and precision flow cells. Manufacturing draws from concentrated German optical glass suppliers, Japanese semiconductor laser foundries, and Swiss precision machining houses for deflection plates. Single-source vulnerability pervades flow cell fabrication, where three vendors supply clinical-grade quartz components to the entire industry. Distribution runs through direct OEM sales forces for GMP-validated platforms and distributor networks for research-grade instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescence-activated cell sorting operates as a regulatory compounder, where each FDA guidance revision on cell therapy manufacturing multiplies validation requirements and extends replacement cycles for installed base equipment.
For Market Incumbents: Cement GMP-compliant installed base loyalty by embedding remote diagnostic capabilities and audit trail automation as standard features. Deepen backward integration into solid-state laser sources to insulate margin structures from German and Japanese component supply friction. Prioritize channel control through unbundled service contracts that separate hardware leases from application support.
For New Entrants and Emerging Players: Academic core facilities with declining indirect cost recovery represent the most penetrable buyer archetype for microfluidic acoustic sorting platforms. India's contract manufacturing organizations under the PLI scheme offer white-space expansion with localized instrument qualification requirements. Stem cell research consortia in Singapore and Japan present entry points through membrane-sensitive primary cell handling specifications. Deploy application-specific consumable bundling to offset capital equipment price resistance.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification burdens disproportionately constrain mid-tier developers without enterprise service density. Five-to-ten year viability favors magnetic-integrated workflow specialists and acoustic technology disruptors with clinical-grade platform roadmaps. Acquisition target archetype: niche vendors with microfluidic chip architectures and established Japanese distributor networks. Monitor PMDA accelerated approval pathway utilization rates as inflection signal for regenerative medicine manufacturing capacity deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Software Pre-validation | FDA co-manufacturing guidance mandates embedded audit trails for multi-site quality protocols. |
| Acoustic Sorting Platform Launch | Standing wave pressure nodes reduce shear stress for iPSC-derived therapy developers in California. |
| Backward Integration into Lasers | In-house solid-state laser production insulates margins from German component supply concentration. |
| Point-of-Care System Miniaturization | Battery-operated microfluidic units enable decentralized autologous therapy manufacturing. |
| Regional Service Density Expansion | Localized validation support accelerates CDSCO qualification for India's export-oriented biologics facilities. |
Research Methodology
Direct dialogue with GMP manufacturing directors, cytometry core facility managers, regulatory affairs leads at instrument vendors, and cell therapy process development scientists grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, EMA CE marking databases, NIH instrumentation grant awards, and GPO contract repositories. Bottom-up and top-down triangulation cross-checked vendor shipment data against end-user capacity expansion announcements.
Bottom-up modeling aggregated installed base estimates by product tier and end-user segment, while top-down analysis calibrated aggregate market size against biopharmaceutical capital expenditure disclosures. Segmentation dimensions spanned equipment grade, cell handling technology, therapeutic application, and regional regulatory cluster. CAGRs derived from slope-log regression across the projection horizon, with cell therapy pipeline expansion rates and instrument replacement cycles as primary forecast inputs.
Underlying measurement precision varies by segment; GMP-validated system deployments carry tighter precision than research-grade estimates due to mandatory regulatory filings. Forecasts reflect assumptions regarding FDA guidance stability, laser component supply continuity, and cell therapy commercialization timelines. Material deviation in PMDA accelerated approval utilization or EMA MDR enforcement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market