
 Global Home Services Market | 2026-2036
Global Home Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Services Market Analysis
REACH compliance is rebalancing the cost-of-entry calculus for European home service providers who must now certify chemical handling in cleaning operations. Amazon.com Inc. leverages its logistics density to bundle home services with retail deliveries, while The Home Depot Inc. anchors its position through in-store contractor desk networks that convert foot traffic into booked jobs. Angi Inc. competes by sustaining a dual-sided marketplace that matches homeowner demand with vetted trade professionals across fragmented local markets.
Home services encompass scheduled and on-demand maintenance, repair, and improvement work performed at residential and commercial properties, typically requiring licensed technicians, specialized tools, and adherence to local building codes. The sector functions through platform-mediated dispatch systems that algorithmically match service requests with available contractors based on proximity, skill certification, and customer ratings. Cleaning services within the service type dimension dominate transaction volume due to recurring household need, while subscription models in the service model category capture superior lifetime value by locking in repeat bookings. Mobile app technology leads the technology segment as the primary customer acquisition channel, though IoT integration is gaining structural importance through predictive maintenance alerts that preemptively generate service calls.
The EU Green Deal and REACH framework tighten chemical disclosure and energy-efficiency standards for renovation work across France, Germany, and Italy, while the US EPA and OSHA govern contractor safety protocols and hazardous material handling in American jurisdictions. India's BIS certification requirements for electrical and plumbing contractors create compliance barriers that favor organized platform players over informal operators. Stakeholders must monitor how building decarbonization mandates in multiple jurisdictions will reshape skill requirements and pricing power for certified trades.
Market Dynamics
Subscription-based service models are compressing customer acquisition costs while locking contractors into platform-dependent revenue streams that reshape pricing power across the value chain.
Growth Catalysts
- EU Green Deal renovation mandates:Building decarbonization targets in France, Germany, and Italy are generating certified retrofit demand that platforms capture through pre-vetted contractor networks.
- Mobile app dispatch infrastructure:Algorithmic matching technology reduces idle contractor time and enables real-time pricing adjustments based on localized demand spikes.
- India's metropolitan corridor expansion:Urban density in Mumbai, Bangalore, and Delhi concentrates serviceable households within 30-minute dispatch radii.
Market Restraints
- REACH chemical compliance costs:European cleaning operators face elevated certification expenses for chemical handling documentation and safety training protocols.
- Licensed technician supply bottlenecks:Germany and the United States report shortages of certified HVAC and electrical contractors that limit platform scaling velocity.
- Platform commission compression:Aggregator fees of 20-30 percent squeeze independent contractor margins and accelerate informal market retention.
Strategic Opportunities
- IoT-enabled predictive maintenance:Smart home sensor networks in US and German households preemptively generate service calls before system failures occur.
- India's BIS certification consolidation:Electrical and plumbing compliance requirements favor organized platforms over informal operators in tier-1 and tier-2 cities.
- Retail-service bundling channels:Logistics density from e-commerce fulfillment networks enables same-day installation and repair scheduling at point-of-purchase.
Industry Challenges
- Skill certification pipeline gaps:HVAC and heat pump installation training programs in Germany and France lag behind EU Green Deal retrofit targets.
- Multi-jurisdiction compliance complexity:Contractors operating across US state lines navigate divergent OSHA, EPA, and local building code requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Services Market |
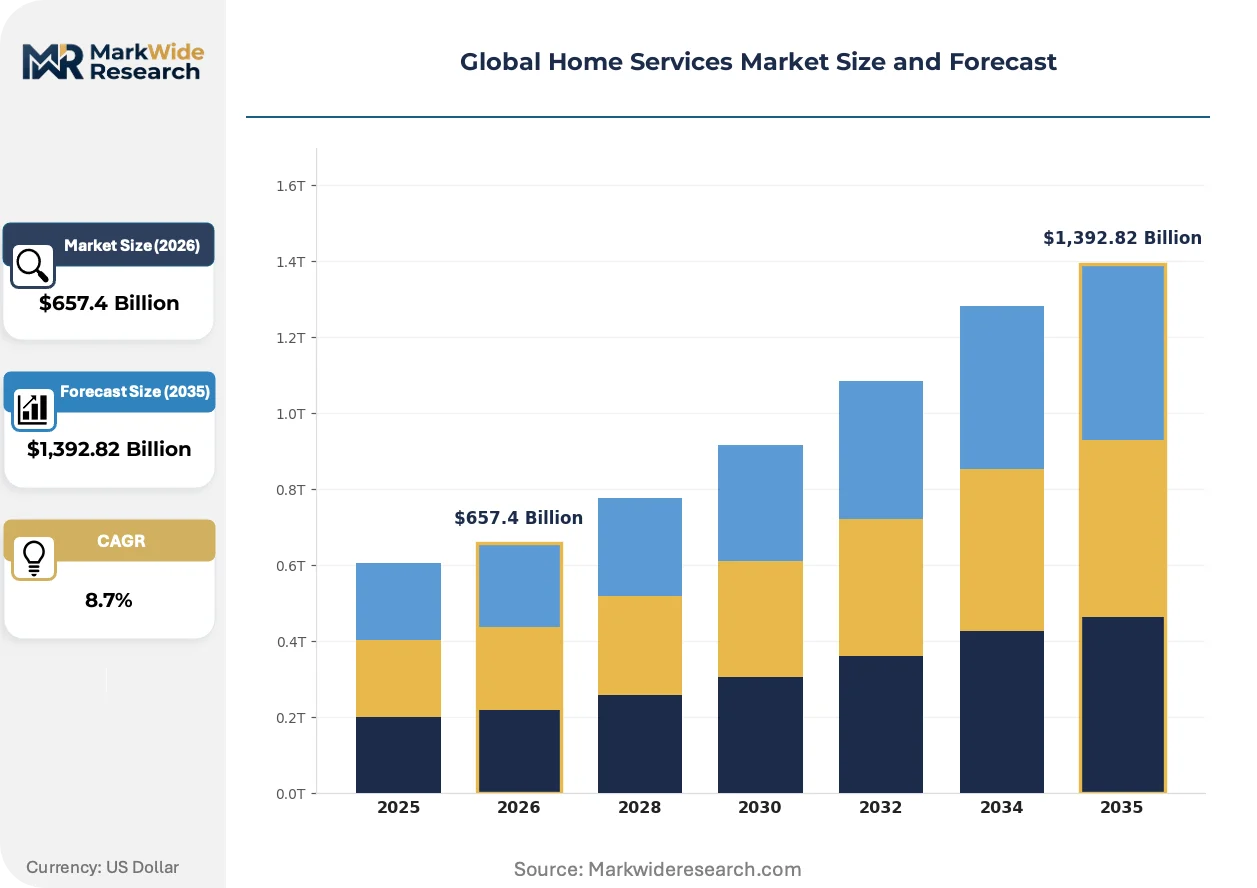
| Market Size in 2026 | $657.4 Billion |
| Market Size in 2035 | $1,392.82 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Plumbing, Electrical, Landscaping Customer Type: Residential, Commercial, Industrial, Institutional Service Model: On-Demand, Subscription, Hourly, Contract-Based Technology: Mobile App, Online Platform, IoT Integration, Automation |
| Companies Covered | Amazon.com Inc., The Home Depot Inc., Angi Inc., Lowe's Companies Inc., TaskRabbit Inc., Helpling GmbH & Co. KG, Urban Company, Thumbtack Inc., HomeAdvisor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Services Market Emerging Trajectories
Algorithmic dispatch systems and connected hardware are converging to transform reactive repair models into anticipatory service relationships that reshape contractor economics.
IoT sensor networks embedded in HVAC systems and water heaters are decentralizing service call generation away from homeowner-initiated requests. US and German property managers deploying predictive maintenance suites report 40 percent reduction in emergency dispatch frequency. This compression of reactive demand is reallocating contractor capacity toward scheduled retrofit and upgrade work.
REACH chemical disclosure requirements and the EU Green Deal's building renovation targets are tightening contractor certification standards across France, Italy, and Germany. Operators must now document energy-efficiency compliance and hazardous material handling protocols to bid on publicly funded retrofit projects. Residential property managers in Berlin and Milan are prioritizing certified contractors in procurement decisions.
Subscription pricing models are displacing transactional booking patterns among US and German residential property managers. Fixed monthly fees covering cleaning, maintenance, and emergency repair convert volatile demand into predictable revenue streams. This shift concentrates most visibly in multifamily housing portfolios where facility managers seek budget certainty over spot-market rate shopping.
Global Home Services Market Segmentation
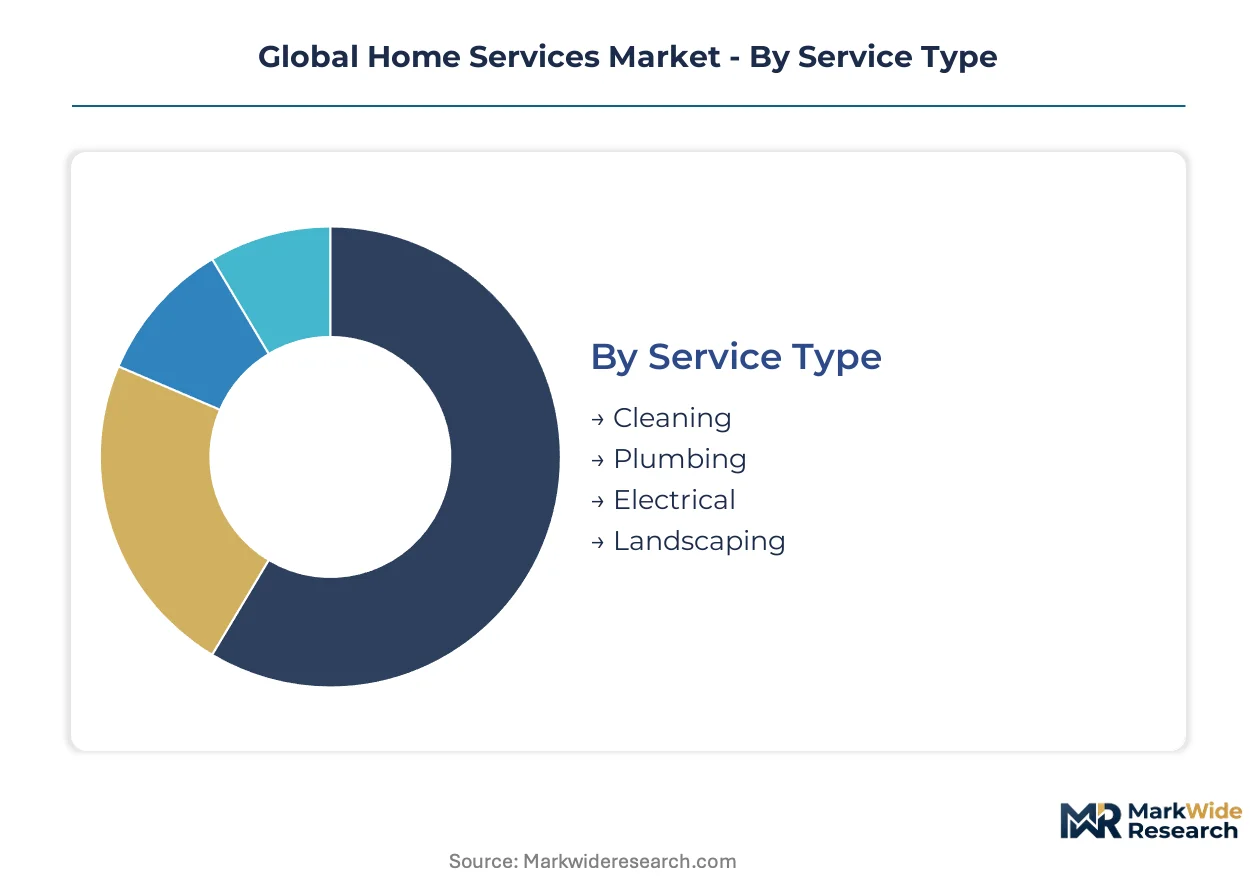
Home services fragmentation demands precise segmentation to capture how service frequency, buyer sophistication, and dispatch technology reshape contractor economics across distinct demand clusters. Platform operators calibrate pricing algorithms and certification requirements differently for each category intersection.
Service Type:
Buyers differentiate primarily by recurrence predictability and emergency tolerance, with routine maintenance commanding lower per-visit premiums than reactive failure response.
- Cleaning:Scheduled surface sanitation and deep-cleaning protocols generate the highest transaction frequency in residential portfolios. Demand concentrates in Germany's multifamily housing stock and India's metropolitan corridors, where Urban Company and similar platforms lock households into recurring schedules through subscription pricing.
- Plumbing:Pipe installation, drainage repair, and fixture maintenance require licensed technician verification and emergency dispatch capability. Germany's KBA-equivalent plumbing certification requirements and India's BIS standards create compliance barriers that favor organized platform networks over informal operators in Berlin and Mumbai.
- Electrical:Wiring repair, panel upgrades, and code-compliant installations carry liability exposure that drives buyer preference toward bonded contractors with documented OSHA or EU-equivalent safety training.
- Landscaping:Seasonal lawn maintenance, irrigation installation, and hardscaping projects exhibit pronounced demand cyclicality tied to climate patterns and property management budgeting cycles.
Volume sits with Cleaning; growth tilts toward Plumbing as building decarbonization mandates expand retrofit certification requirements.
Customer Type:
Contractor utilization rates and pricing power diverge sharply based on whether buyers prioritize budget predictability or spot-market flexibility.
- Residential:Single-family homeowners and apartment dwellers initiate the majority of platform-mediated service requests through mobile app interfaces. US and German property managers are expanding subscription-based cleaning and maintenance packages to compress customer acquisition costs.
- Commercial:Office buildings, retail spaces, and hospitality properties demand standardized service level agreements with penalty clauses for missed windows. This segment captures superior lifetime value through multi-year facility management contracts.
- Industrial:Manufacturing facilities and warehouses require specialized heavy equipment maintenance with extended technician training cycles.
- Institutional:Schools, hospitals, and government buildings impose stringent background check and insurance requirements that elevate vendor qualification costs.
Residential generates the deepest volume pools; Institutional climbs fastest as public building renovation targets expand certified contractor procurement.
Service Model:
Revenue predictability and contractor margin compression trade off differently across pricing structures, with locked-in schedules reducing idle capacity but capping rate negotiation leverage.
- On-Demand:Immediate dispatch for emergency repairs commands premium pricing but suffers from demand volatility that strains contractor income stability. Algorithmic matching technology reduces idle contractor time through real-time pricing adjustments based on localized demand spikes.
- Subscription:Fixed monthly fees covering bundled services convert volatile demand into predictable revenue streams. Residential property managers in Germany and the United States are displacing transactional booking patterns with these arrangements.
- Hourly:Time-based billing persists for specialized diagnostics and consulting work where scope uncertainty prevents fixed pricing.
- Contract-Based:Multi-year facility management agreements with defined service catalogs dominate commercial and institutional procurement.
On-Demand retains the widest addressable base; Subscription gains share fastest as property managers seek budget certainty over spot-market rate shopping.
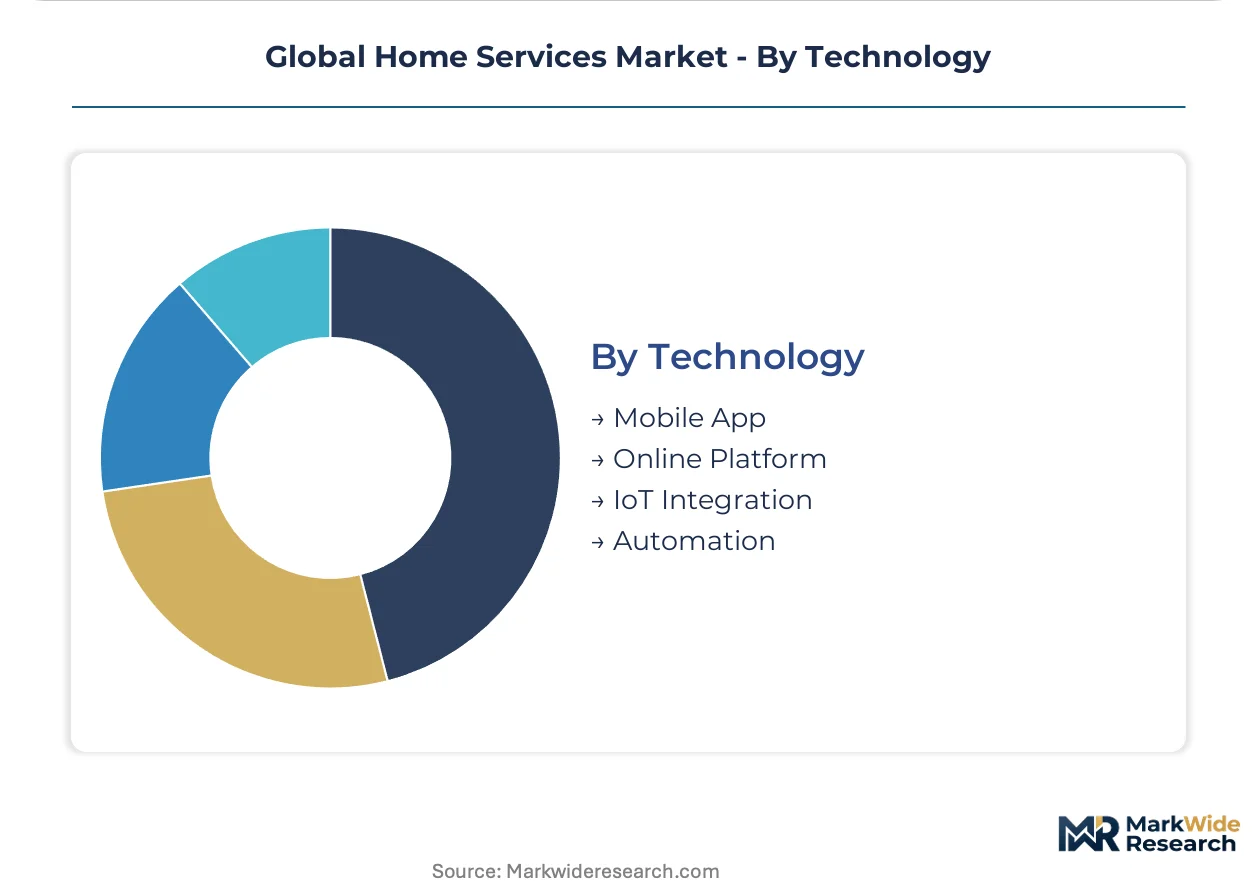
Technology:
Customer acquisition cost and service call generation mechanics diverge based on whether platforms rely on proactive homeowner initiation or sensor-triggered dispatch.
- Mobile App:Smartphone-based booking interfaces dominate customer acquisition channels through algorithmic matching of service requests with available contractors. Proximity, skill certification, and customer ratings determine dispatch priority.
- IoT Integration:Smart home sensor networks in HVAC systems and water heaters preemptively generate service calls before system failures occur. US and German property managers deploying predictive maintenance suites report reduced emergency dispatch frequency.
- Online Platform:Web-based portals persist for commercial buyers with centralized procurement workflows and invoice reconciliation requirements.
- Automation:Robotic cleaning systems and drone-enabled inspection tools are gaining structural importance for standardized, repeatable maintenance tasks.
Mobile App anchors current transaction volume; IoT Integration expands most quickly as connected hardware penetrates middle-income housing stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's special economic zones for platform enterprises concentrate venture deployment in Mumbai, Bangalore, and Delhi, where Urban Company scales technician networks under BIS certification requirements.
United States
Subscription-based cleaning and maintenance packages spread among residential property managers seeking budget predictability. OSHA and EPA regulations govern contractor safety protocols and hazardous material handling across state lines. Platform density concentrates in major metropolitan corridors where algorithmic dispatch reduces contractor idle time.
Germany
EU Green Deal renovation mandates generate certified retrofit demand for HVAC and electrical contractors. REACH chemical disclosure requirements elevate documentation costs for cleaning operators. Berlin property managers prioritize pre-vetted contractor networks for publicly funded building efficiency projects.
India
Urban density in Mumbai, Bangalore, and Delhi concentrates serviceable households within 30-minute dispatch radii. BIS certification requirements for electrical and plumbing contractors favor organized platform players over informal operators. Urban Company scales rapidly through mobile-first technician onboarding in tier-1 and tier-2 cities.
France
Building decarbonization targets drive demand for certified heat pump installation and energy-efficiency retrofit work. EU Green Deal standards tighten contractor qualification requirements for publicly funded renovation projects. Milan and Paris property managers shift procurement toward certified contractors with documented compliance protocols.
United Kingdom
Platform-mediated service requests flow through mobile app interfaces dominating residential customer acquisition. Local building code variations across England, Scotland, and Wales create multi-jurisdiction compliance complexity for cross-border contractors. London's multifamily housing stock leads adoption of subscription pricing for bundled maintenance services.
Global Home Services Market Vendor Landscape
United States platforms anchor one tier; German and Indian specialists hold regional density advantages through localized technician certification. The market structures around three archetypes: retail-service bundlers leveraging logistics networks, pure-play digital marketplaces matching demand with vetted trades, and vertically integrated property management platforms. Consolidation pressures intensify as M&A activity absorbs regional technician networks and technology licensing agreements spread algorithmic dispatch infrastructure.
Within the retail-service bundler tier, Amazon.com Inc. exemplifies logistics-density advantage, while The Home Depot Inc. anchors the in-store conversion model through contractor desk networks. Angi Inc. occupies the digital marketplace archetype, sustaining dual-sided platform economics across fragmented local markets in the United States.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| The Home Depot Inc. |
| Angi Inc. |
| Lowe's Companies Inc. |
| TaskRabbit Inc. |
| Helpling GmbH & Co. KG |
| Urban Company |
| Thumbtack Inc. |
| HomeAdvisor Inc. |
| Others |
Supply Flow & Price Mechanics
Algorithmic dispatch infrastructure simultaneously compresses contractor idle time and reconfigures cost economics across platform-mediated service networks. Real-time pricing adjustments based on localized demand spikes concentrate margin leverage with aggregator platforms in Germany, India, and the United States while fragmenting pricing power among independent technicians.
Pricing Analysis
Short lead-time premiums dominate emergency plumbing and electrical dispatch, while subscription models lock in discounted rates for scheduled maintenance windows. Price differentiation separates BIS-certified contractors in Mumbai from informal operators, with REACH compliance costs elevating European cleaning service tiers. Pricing pressure stems from platform commission compression of 20-30 percent squeezing independent margins. Residential property managers in Berlin and Dallas exhibit lowest price sensitivity through locked-in facility management contracts, whereas spot-market Indian households drive hardest rate negotiations.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United States anchor spare parts and equipment logistics for technician networks. Supply chains draw from Chinese-manufactured IoT sensors, German HVAC components, and Indian electrical fittings. Single-source vulnerability concentrates in smart home hardware procurement for predictive maintenance suites. Distribution runs through platform-controlled inventory pools that allocate tools and replacement parts based on algorithmic demand forecasting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Home Services Market functions as a vertical-integration race where control over certified technician supply chains determines platform pricing power. Players are pursuing backward integration into training academies to lock in scarce HVAC and electrical skills.
For Market Incumbents: To counter informal operator retention in India's tier-2 cities, Amazon and The Home Depot should deepen captive supply of pre-certified contractor networks through acquisition of regional technician cooperatives. Angi must anchor channel control by embedding subscription pricing into property management software workflows to neutralize spot-market competitors. For New Entrants and Emerging Players: Enter via predictive maintenance white space in German multifamily housing, where IoT sensor penetration lags behind US adoption curves. Target BIS certification consolidation in Bangalore and Delhi plumbing segments, deploying mobile-first technician onboarding to bypass legacy platform infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in retail-service bundler acquisitions by logistics-dense e-commerce platforms. Long-term viability hinges on technician network density rather than algorithmic sophistication alone. Watch EU Green Deal retrofit target acceleration as inflection indicator for certified HVAC demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Network Acquisition | Consolidates scarce certified HVAC and electrical capacity under platform control in Germany and the United States. |
| IoT Platform Integration | Transforms reactive repair models into anticipatory service relationships through predictive maintenance alert systems. |
| Subscription Model Rollout | Converts volatile spot-market demand into predictable revenue streams for residential property managers. |
| Certification Pipeline Investment | Addresses EU Green Deal skill gaps by accelerating heat pump installation training programs in France and Italy. |
| Retail-Service Bundling | Leverages e-commerce logistics density to capture installation demand at point-of-purchase in US metropolitan corridors. |
Methodological Framework
Independent corroboration across platform operations executives, facility management procurement directors, certified trade contractors, and regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from EU Green Deal implementation reports, BIS certification databases, OSHA safety protocol filings, and SEC disclosures by retail-service bundlers. Bottom-up technician network sizing triangulates against top-down property management spending estimates.
Rate-of-change decomposition separates volume growth from pricing evolution across the analysis window. Segmentation dimensions span service type, customer category, pricing model, and technology integration tier. CAGRs derive from technician utilization rate trajectories and subscription penetration curves. Forecast inputs incorporate REACH compliance cost pass-through assumptions and IoT sensor deployment timelines in US and German housing stock.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Green Deal retrofit target revisions or BIS certification enforcement shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Home Warranty Service Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Property Tax Services Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Warehousing Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
US Home Service Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Green Lease Market
Real Estate Services
Singapore Self-Storage Market