
 ASEAN Manufactured Homes Market | 2026-2036
ASEAN Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Manufactured Homes Market Outlook
CIDB IBS certification is reorganizing competitive access across the ASEAN manufactured homes sector, elevating compliance costs for new entrants while rewarding incumbents with pre-certified production lines. Sekisui Chemical Co. Ltd leverages its Japanese parent company's precision engineering protocols to dominate premium modular exports into Thailand and Vietnam. Axtrada (Malaysia) Sdn Bhd anchors its position through backward integration into lightweight steel frame manufacturing at its Johor facility. Moderna Homes Pte Ltd differentiates via direct sales channels that bypass traditional distributor markups in Singapore's high-cost housing market.
ASEAN manufactured homes are factory-built residential structures assembled from prefabricated modules or panels, typically incorporating steel or composite frames with insulation ratings between R-13 and R-30, then transported to sites for final installation. These units serve primarily as permanent or semi-permanent dwellings where conventional on-site construction faces cost, speed, or labor constraints. Modular Homes command the deepest margin pools due to customization premiums and developer-scale contracts, while Tiny Homes represent the fastest-growing category driven by solo-occupant urban migration across Jakarta, Manila, and Ho Chi Minh City. Steel-framed units lead in flood-prone geographies, whereas wood-composite hybrids sustain appeal in Malaysia's mid-density townships where aesthetic flexibility matters.
Thailand's Department of Public Works and Town & Country Planning enforces seismic and wind-load standards that effectively filter out uncertified imports from neighboring producers. Malaysia's CIDB IBS scoring system mandates minimum prefabrication percentages for government-subsidized housing projects, directly steering procurement toward established modular suppliers. Vietnam's Ministry of Construction is developing national technical codes for factory-built housing that will determine which foreign manufacturers qualify for state-backed affordable housing tenders. Stakeholders must monitor whether Indonesia's upcoming building efficiency regulations will recognize ASEAN-harmonized certifications or maintain country-specific approval pathways that fragment market access.
Market Dynamics
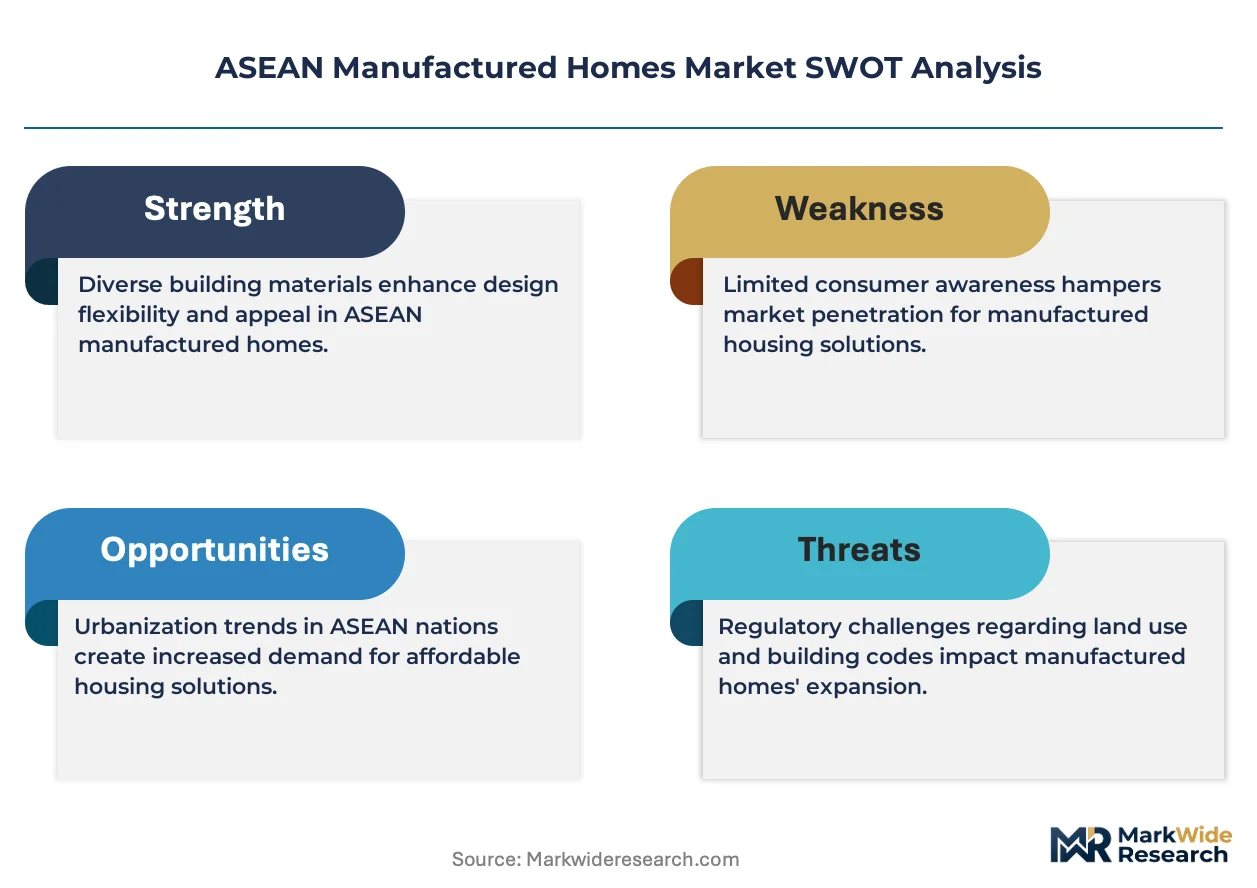
Malaysia's CIDB Industrialized Building System certification is compressing competitive access timelines across ASEAN, forcing manufacturers to retool production lines or exit government procurement channels entirely. This regulatory pivot rewards pre-certified incumbents while elevating capital barriers for new factory entrants.
Growth Catalysts
- Urbanization pressure in Thailand's peri-urban corridors:Bangkok's land scarcity and flood-risk zoning push developers toward elevated modular solutions that compress construction schedules by half relative to conventional methods.
- CIDB IBS scoring mandates:Malaysia's minimum prefabrication percentages for subsidized housing projects steer procurement toward established modular suppliers with certified production lines.
- Lightweight steel framing advances:Johor-based manufacturing clusters now supply corrosion-resistant frames that withstand tropical humidity, opening export pathways into Vietnam and Indonesia.
Market Restraints
- Steel price volatility:Input cost swings for galvanized steel coil destabilize manufacturer margins, particularly for mid-tier producers lacking long-term supply contracts with Chinese mills.
- Import certification friction:Thailand's Department of Public Works seismic and wind-load standards filter out uncertified modules from neighboring producers, fragmenting regional supply chains.
- Site-built construction persistence:Informal labor markets in Indonesia and the Philippines sustain cost advantages for conventional masonry in rural districts, limiting factory-built penetration.
Strategic Opportunities
- Vietnam's affordable housing tender pipeline:The Ministry of Construction's developing national technical codes for factory-built housing will determine foreign manufacturer eligibility for state-backed projects.
- Tiny Home category expansion:Solo-occupant urban migration across Jakarta, Manila, and Ho Chi Minh City creates demand for sub-400-square-foot units optimized for rental yield.
- Direct sales channel development:Singapore's high-cost housing market rewards manufacturers bypassing traditional distributor markups through owned retail showrooms and digital configurators.
Industry Challenges
- Certification timeline compression:Vietnam's pending technical code finalization leaves manufacturers guessing at testing protocols, freezing capital allocation decisions for new production capacity.
- Installation workforce gaps:Shortages of certified crane operators and module-sealing specialists in Thailand's secondary cities delay project handovers and trigger liquidated damages clauses.
- Legacy foundation incompatibility:Existing site-prep standards across ASEAN assume conventional load-bearing walls, forcing modular developers to renegotiate geotechnical specifications with local authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Manufactured Homes Market |
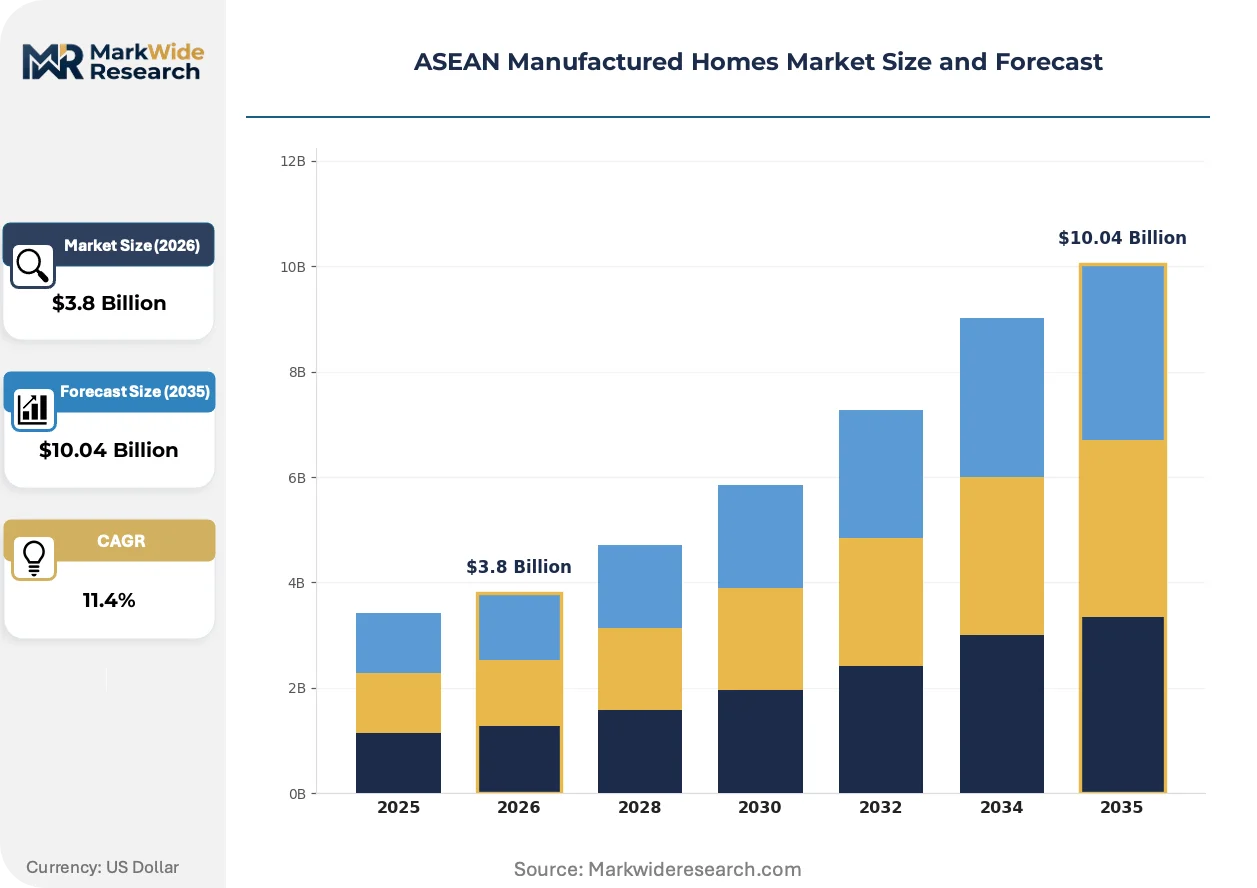
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Prefabricated Houses, Tiny Homes, Mobile Units End User: Residential Buyers, Developers, Government Projects, Commercial Use Material: Wood, Steel, Composite, Concrete Distribution Channel: Retail, Direct Sales, Online Platforms, Distributors |
| Companies Covered | Moderna Homes Pte Ltd, DTH PREFAB, Axtrada (Malaysia) Sdn Bhd, Karmod, Sekisui Chemical Co. Ltd, ModularCraft, AMD Modular, ROOM+ Design & Build, Bahay Makabayan Modular Homes, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Manufactured Homes Market Strategic Shifts
Factory automation and material science advances are compressing module production cycles while regulatory harmonization efforts attempt to unify certification pathways across Thailand, Malaysia, and Vietnam. These forces are reshaping competitive positioning around speed-to-site and compliance agility rather than scale alone.
Lightweight composite wall panels integrating aerated concrete cores with magnesium oxide facings are miniaturizing structural footprints without sacrificing thermal performance. Indonesian developers targeting Jakarta's vertical infill sites specify these panels to maximize rentable floor area on constrained lots. The technology is miniaturizing the minimum viable module size, enabling single-staircase walk-up configurations previously uneconomical for factory production.
Malaysia's CIDB IBS scoring system now mandates minimum prefabrication percentages for government-subsidized housing projects, directly steering procurement toward suppliers with certified production lines. Manufacturers without CIDB accreditation face automatic disqualification from federal tenders worth hundreds of millions in annual volume. Thai and Vietnamese producers are responding by licensing Malaysian certification protocols rather than pursuing bilateral equivalence agreements.
Buyer preferences across Bangkok and Ho Chi Minh City are hardening around turnkey delivery models that bundle module transport, crane rental, and utility connection into single-contractor responsibility. Traditional fragmented procurement—separate factory, logistics, and site contractors—is losing share to integrated providers willing to absorb interface risk. This consolidation is most visible in Thailand's peri-urban corridors, where flood-risk zoning elevates the premium on guaranteed completion timelines.
ASEAN Manufactured Homes Market Segmentation
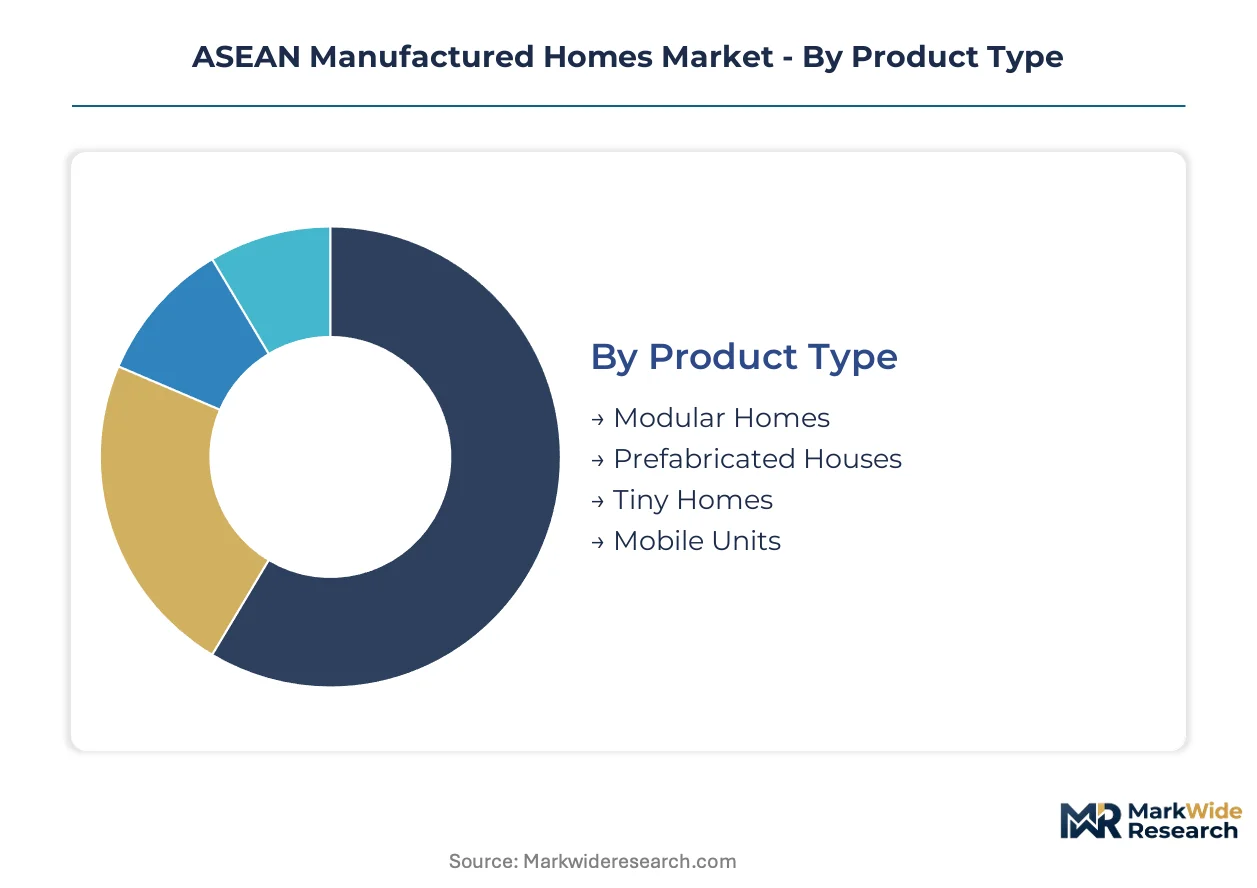
Segmentation in the ASEAN manufactured homes market reveals distinct procurement pathways and margin structures. Each dimension—product format, buyer type, material specification, and channel access—carries different compliance burdens and capital requirements that reshape competitive positioning.
Product Type:
Channel mix varies sharply by product complexity, with developer-scale contracts flowing through direct sales while consumer-facing units move via retail showrooms and digital configurators.
- Modular Homes:Factory-built units assembled from steel or composite frames with R-13 to R-30 insulation ratings, typically 800-2,500 square feet. Demand concentrates in Thailand's peri-urban corridors around Bangkok and Chiang Mai, where flood-risk zoning and land scarcity compress construction timelines and elevate premiums for guaranteed completion.
- Tiny Homes:Sub-400-square-foot units optimized for solo-occupant urban migration. Expansion concentrates across Jakarta, Manila, and Ho Chi Minh City, where rental yield optimization on constrained lots drives specification for lightweight composite panels and vertical infill configurations.
- Prefabricated Houses:Panel-based systems offering mid-range customization for Malaysia's CIDB IBS-compliant townships.
- Mobile Units:Transportable dwellings serving semi-permanent and disaster-relief applications across flood-prone geographies.
Modular Homes dominate installed base through developer-scale contracts. Tiny Homes represent where expansion concentrates most steeply.
End User:
Cost tier segmentation separates premium turnkey buyers from price-sensitive procurement officers managing federal tender pipelines.
- Residential Buyers:Individual purchasers seeking permanent or semi-permanent dwellings, typically low-to-mid income households priced out of conventional construction in urbanizing corridors. Demand clusters where informal labor markets lose cost advantage and factory-built speed commands premium pricing.
- Developers:Real estate firms procuring at scale for multi-unit projects, particularly in Vietnam's emerging affordable housing pipeline and Thailand's elevated modular solutions for flood-prone zones. Malaysia's CIDB IBS scoring mandates steer this segment toward pre-certified suppliers exclusively.
- Government Projects:State-backed affordable housing tenders requiring compliance with evolving national technical codes.
- Commercial Use:Hospitality, remote workforce accommodation, and institutional applications.
Developers command volume concentration. Government Projects represent the steepest expansion trajectory as technical codes finalize.
Material:
Supply concentration and corrosion resistance requirements divide procurement between tropical-humidity specifications and aesthetic-flexibility priorities.
- Steel:Galvanized and lightweight steel framing dominates flood-prone geographies across Thailand and Vietnam, with Johor-based manufacturing clusters now supplying corrosion-resistant frames that withstand tropical humidity and open export pathways into Indonesia.
- Composite:Aerated concrete cores with magnesium oxide facings miniaturize structural footprints without sacrificing thermal performance. Indonesian developers targeting Jakarta's vertical infill sites specify these panels to maximize rentable floor area on constrained lots.
- Wood:Wood-composite hybrids sustain appeal in Malaysia's mid-density townships where aesthetic flexibility matters.
- Concrete:Precast concrete systems for heavy-load and permanent foundation applications.
Steel dominates installed base in flood-prone specifications. Composite is where expansion concentrates for vertical infill optimization.
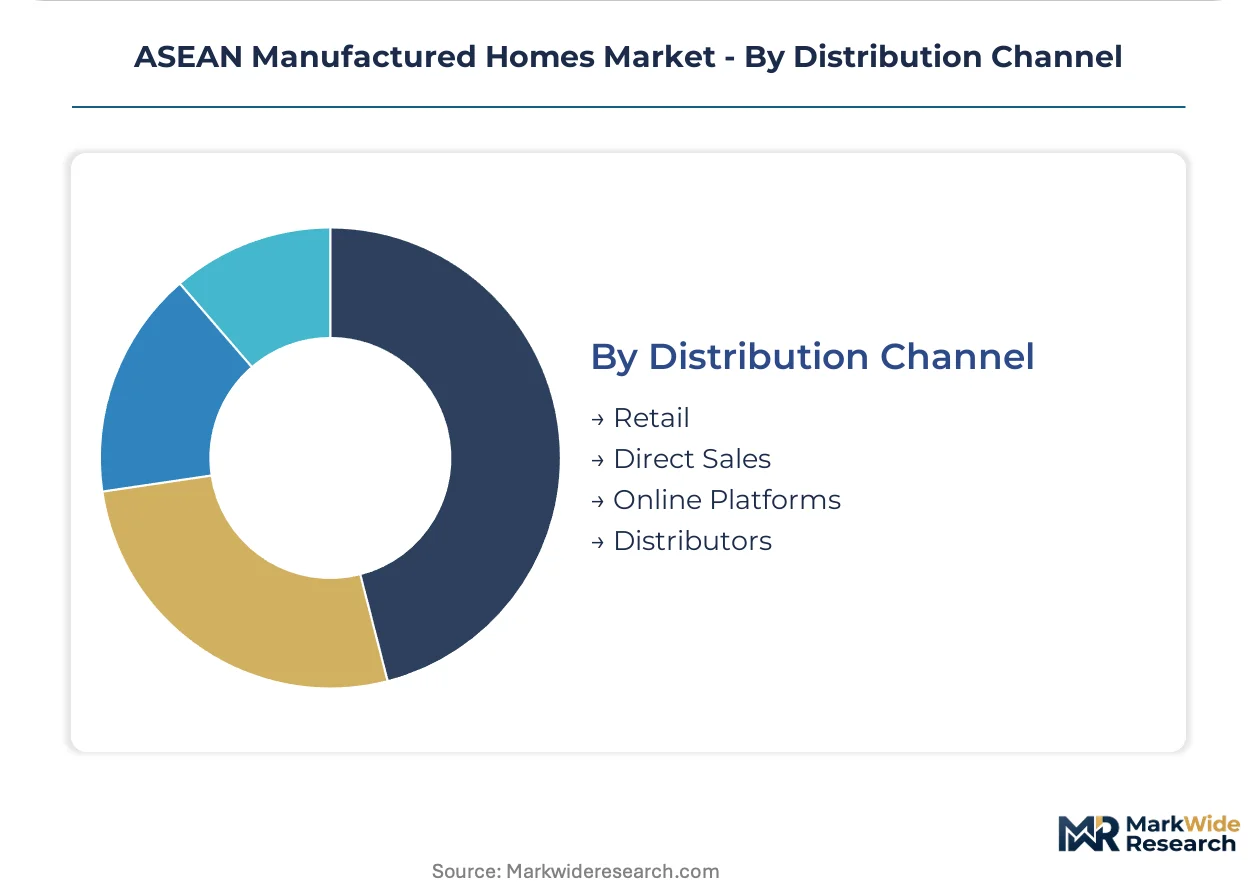
Distribution Channel:
Margin compression and interface risk allocation determine whether buyers accept distributor markups or demand integrated turnkey responsibility.
- Direct Sales:Manufacturer-owned channels bypassing traditional distributor markups, particularly effective in Singapore's high-cost housing market and Thailand's peri-urban corridors where flood-risk zoning elevates premium on guaranteed completion timelines and single-contractor responsibility.
- Retail:Showroom-based purchasing for consumer-facing segments, concentrated in urban centers with established manufactured housing display infrastructure.
- Online Platforms:Digital configurators enabling specification and pricing transparency for standardized module lines.
- Distributors:Third-party logistics and sales intermediaries serving fragmented rural markets.
Direct Sales dominates margin capture in high-cost urban markets. Online Platforms represent where expansion concentrates for specification transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's CIDB Industrialized Building System certification is reorganizing procurement standards across ASEAN, with neighboring producers licensing Malaysian protocols to maintain tender eligibility for government-subsidized housing pipelines.
Thailand
Peri-urban corridors around Bangkok and Chiang Mai are driving demand for elevated modular solutions as flood-risk zoning and land scarcity compress construction timelines. The Department of Public Works and Town & Country Planning enforces seismic and wind-load standards that filter out uncertified imports. Rayong and Chonburi host manufacturing clusters supplying corrosion-resistant steel frames for domestic and export markets.
Malaysia
CIDB IBS scoring mandates minimum prefabrication percentages for federal housing tenders, steering procurement exclusively toward certified suppliers. Johor anchors regional production through backward-integrated lightweight steel frame manufacturing. Penang and Selangor concentrate mid-density township developments specifying wood-composite hybrids for aesthetic flexibility.
Vietnam
Affordable housing tender pipelines in Ho Chi Minh City and Hanoi are accelerating as the Ministry of Construction develops national technical codes for factory-built housing. Foreign manufacturers await protocol finalization to determine eligibility for state-backed projects. Da Nang emerges as a testing ground for turnkey delivery models bundling transport and installation.
Indonesia
Jakarta's vertical infill sites drive specification for lightweight composite panels maximizing rentable floor area on constrained lots. Informal labor markets in rural districts sustain cost advantages for conventional masonry, limiting factory-built penetration outside major metros. Surabaya and Bandung concentrate early modular adoption for remote workforce accommodation.
Singapore
High-cost housing conditions reward manufacturers bypassing traditional distributor markups through direct sales channels and digital configurators. The city-state's density constraints favor compact module specifications optimized for rapid site assembly. Jurong hosts display infrastructure for consumer-facing retail showrooms.
ASEAN Manufactured Homes Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with captive materials capabilities and specialist modular fabricators with certified production lines. Japanese and Malaysian entities dominate premium and mid-market tiers respectively, leveraging parent-company engineering protocols and backward-integrated steel framing. Strategic moves concentrate on certification licensing to access cross-border tender pipelines and capacity expansion in Johor-based manufacturing clusters.
Within the precision-engineering tier, Sekisui Chemical Co. Ltd exemplifies conglomerate-backed market presence through Japanese parent-company protocols. Axtrada (Malaysia) Sdn Bhd anchors the mid-market certified-supplier segment with Johor-based production integration. Moderna Homes Pte Ltd occupies the direct-sales specialist position in Singapore's high-cost housing channel. These three entities represent distinct competitive archetypes: engineering-heritage conglomerate, regionally certified fabricator, and channel-integrated specialist.
| Leading Market Players |
|---|
| Moderna Homes Pte Ltd |
| DTH PREFAB |
| Axtrada (Malaysia) Sdn Bhd |
| Karmod |
| Sekisui Chemical Co. Ltd |
| ModularCraft |
| AMD Modular |
| ROOM+ Design & Build |
| Bahay Makabayan Modular Homes |
| Others |
Value Chain & Pricing Dynamics
Malaysia's CIDB Industrialized Building System certification gates both supply qualification and price differentiation simultaneously, creating a bifurcated market where certified incumbents capture premium developer contracts while uncertified producers compete on thinner margins in informal channels.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers in ASEAN manufactured housing. CIDB IBS-accredited suppliers command project-based pricing with customization premiums for turnkey delivery, while uncertified competitors rely on per-unit transactional models with compressed margins. Steel price volatility is intensifying cost pressure across mid-tier producers lacking long-term Chinese mill contracts. Government procurement officers managing Vietnam's affordable housing pipeline exhibit highest price sensitivity, whereas Singaporean direct-to-consumer buyers prioritize guaranteed completion over unit cost.
Supply Chain Analysis
Port congestion along the Singapore-Johor trade lane elevates inbound logistics costs for galvanized steel coil and magnesium oxide panel imports. Manufacturing gravity centers on Malaysia's Johor corridor, Thailand's Rayong-Chonburi cluster, and Vietnam's emerging Da Nang assembly nodes. Raw material dependencies draw from Chinese steel mills, Korean insulation suppliers, and Thai aluminum extruders. Single-source vulnerability concentrates in corrosion-resistant coating formulations. Distribution runs through manufacturer-direct channels for developer-scale contracts and third-party logistics networks for rural retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN manufactured housing incumbents must defend against conventional masonry substitution sustained by Indonesia's and the Philippines' informal labor cost advantages, which threaten factory-built penetration outside urban cores.
For Market Incumbents: Secure CIDB IBS certification licensing across Thai and Vietnamese production lines to maintain tender eligibility as Malaysia's scoring mandates expand regionally. Anchor backward integration into lightweight steel frame manufacturing at Johor-based facilities to offset galvanized coil price volatility. Channel control through owned retail showrooms in Singapore and Bangkok's peri-urban corridors defends margin position against distributor markup compression.
For New Entrants and Emerging Players: Certification fast-track partnerships with Malaysian technical institutes offer the lowest-friction path to government procurement eligibility. White-space concentrates in Vietnam's affordable housing tender pipeline ahead of Ministry of Construction code finalization, and in Jakarta's vertical infill segment specifying sub-400-square-foot composite panel configurations. Go-to-market through digital configurators targeting solo-occupant urban migrants bypasses established distributor relationships.
For Investors and Strategic Acquirers: Vietnam's pending technical code finalization reshapes the acquisition landscape by determining which foreign manufacturers qualify for state-backed volume. Long-term viability favors targets with captive steel framing capabilities and pre-certified production lines across multiple ASEAN jurisdictions. The signal to watch is bilateral equivalence agreements between Vietnamese and Malaysian regulators, which would accelerate cross-border tender access for consolidated players.
| Strategic Initiative | Industry Significance |
|---|---|
| CIDB IBS Certification Licensing | Malaysian protocol adoption unlocks Thai and Vietnamese government tender pipelines. |
| Backward Integration into Steel Framing | Johor-based captive production hedges galvanized coil price volatility from Chinese mills. |
| Direct Sales Channel Development | Singapore showroom ownership bypasses distributor markups in high-cost housing markets. |
| Turnkey Delivery Model Expansion | Single-contractor responsibility for transport, crane rental, and utility connection captures Bangkok flood-zone premiums. |
| Lightweight Composite Panel R&D | Aerated concrete-magnesium oxide cores maximize rentable floor area on Jakarta's constrained infill lots. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with modular home developers, CIDB certification officers, steel frame plant managers, and government housing procurement directors. Secondary validation drew from Malaysia's CIDB IBS scoring databases, Thailand's Department of Public Works seismic standards filings, Vietnamese Ministry of Construction technical code drafts, and customs records tracking galvanized steel coil imports. Bottom-up module production capacity estimates were triangulated against top-down government tender pipeline values.
Across the analysis window, forecasts were constructed by modeling product type segmentation across modular, tiny, prefabricated, and mobile units; end-user categories spanning residential buyers, developers, government projects, and commercial use; material specifications including steel, composite, wood, and concrete; and distribution channel splits between direct sales, retail, online platforms, and distributors. CAGRs were derived from installed base growth trajectories and replacement cycle analysis, with inputs from urbanization rate projections and flood-risk zoning expansion in Thailand's peri-urban corridors.
Decision-makers should treat outputs as directional under assumptions of regulatory code finalization timelines and steel price stabilization; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as Indonesia's building efficiency regulations evolve and Vietnam's technical code protocols crystallize.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
South Korea Residential Real Estate Market