
 Second-Hand Housing Trading Platform Market | 2026-2036
Second-Hand Housing Trading Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Second-Hand Housing Trading Platform Market Insights
Asset-light franchise financing is fragmenting competitive barriers in second-hand housing platforms, enabling regional operators to scale without balance-sheet property risk. Ke Holdings leverages its proprietary Beike network to control offline agent integration across tier-one Chinese cities. Zillow sustains brand dominance in North American digital search traffic through algorithmic pricing tools. Rightmove anchors the United Kingdom's portal economy by concentrating estate agency subscriptions in London commuter belts.
Second-hand housing trading platforms are digital intermediaries that match existing residential property sellers with buyers through searchable databases, typically incorporating automated valuation models, mortgage pre-qualification APIs, and electronic document execution to compress closing timelines from weeks to days. Web-based platforms still capture the majority of listing volume, though mobile applications represent the fastest-growing engagement channel as younger cohorts complete entire transactions on smartphones. AI-powered recommendations now sit at the core margin pool, since matching algorithms reduce agent hours per transaction and enable platform fee compression that undercuts traditional brokerage.
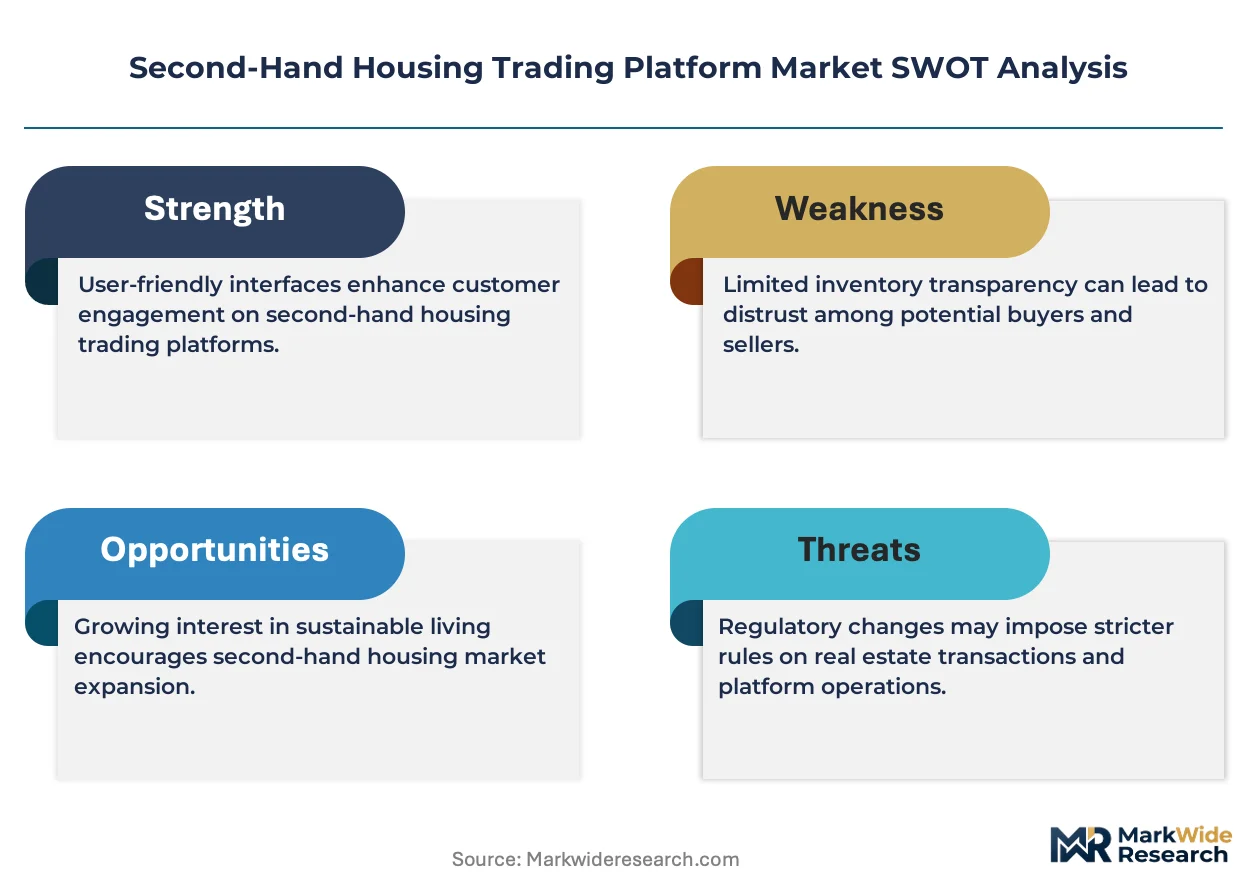
China's SAMR enforces real-time listing verification and anti-monopoly provisions that prevent dominant platforms from exclusive agent contracts, while the U.S. Department of Justice scrutinizes cooperative compensation rules through NAR-affiliated multiple listing services. The EU's Digital Services Act imposes transparency obligations on property portals operating cross-border. Stakeholders must monitor whether regulator-mandated fee unbundling transforms platform economics from subscription models toward per-transaction micro-commissions.
Market Dynamics
Real-time transaction disclosure mandates from China's SAMR are compressing platform economics toward per-transaction micro-commissions, eroding subscription-based revenue models that historically sustained digital intermediaries.
Growth Catalysts
- Mobile-first closing workflows:First-time millennial buyers now execute entire transactions on smartphones, compressing closing timelines from weeks to days and expanding addressable user bases.
- SAMR real-time disclosure rules:China's State Administration for Market Regulation mandates instantaneous listing verification, accelerating platform legitimacy and reducing fraud-driven transaction abandonment.
- Algorithmic valuation penetration:Automated pricing models reduce agent hours per transaction, enabling fee compression that undercuts traditional brokerage and expands price-sensitive demand.
Market Restraints
- Cooperative compensation scrutiny:The U.S. Department of Justice examines NAR-affiliated multiple listing service rules, creating regulatory friction that threatens platform access to consolidated inventory data.
- Exclusive agent contract prohibitions:SAMR anti-monopoly provisions prevent dominant platforms from locking in agent exclusivity, fragmenting supply-side control and intensifying customer acquisition costs.
- Legacy system integration costs:Electronic document execution requires capital-intensive middleware development to interface with county recorder databases and title insurance workflows.
Strategic Opportunities
- Tier-two Chinese city expansion:Ke Holdings' Beike network infrastructure enables rapid deployment into underserved urban clusters beyond Beijing, Shanghai, Shenzhen, and Guangzhou.
- EU Digital Services Act compliance:Transparency obligations on cross-border property portals create first-mover advantages for platforms investing in standardized disclosure architectures.
- Mortgage API convergence:Integration of pre-qualification algorithms with digital closing workflows opens white space in financial services bundling.
Industry Challenges
- Agent workforce retention:Commission compression from platform fee reduction threatens experienced broker migration, degrading transaction quality in high-value segments.
- Data standardization fragmentation:Inconsistent municipal recording formats across U.S. counties impede seamless electronic document execution and extend technical integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second-Hand Housing Trading Platform Market |
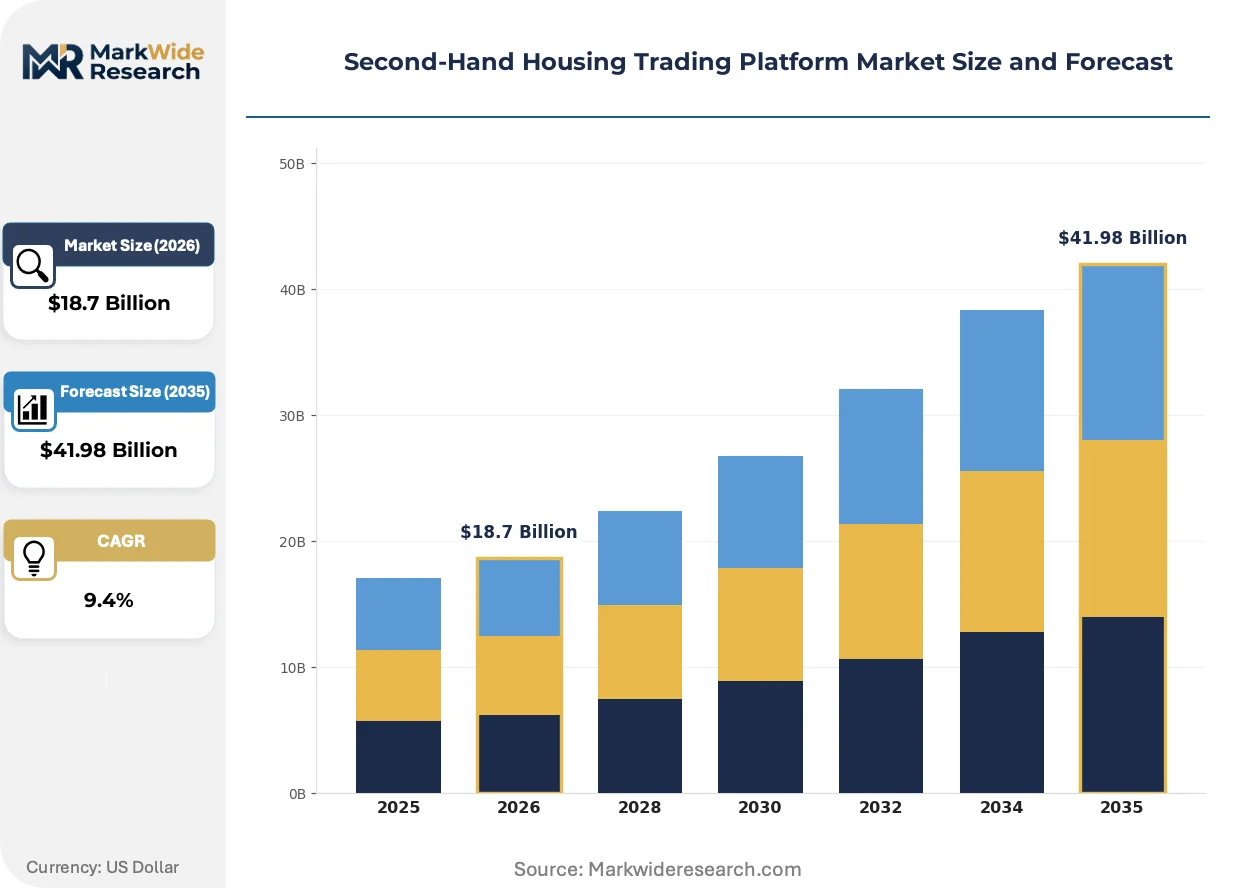
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Listing Services, Transaction Facilitation, Property Valuation, Mortgage Assistance, Legal Advisory Customer Type: Individual Buyers, Property Investors, Real Estate Agencies, Corporate Buyers, Relocation Firms Technology: Web-Based Platforms, Mobile Applications, Virtual Tours, AI-Powered Recommendations, Blockchain Integration Distribution Channel: Online Portals, Mobile Apps, Referral Networks, Partner Agencies, Direct Seller Listings |
| Companies Covered | Ke Holdings Inc., 58.com, SouFun (Fang Holdings Limited), Anjuke, Lianjia, Rightmove, Zillow, Redfin, ImmobilienScout24, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second-Hand Housing Trading Platform Market Trends and Innovations
Artificial intelligence is restructuring how property-matching algorithms allocate buyer attention, compressing the traditional agent-mediated search process into automated recommendation engines that reshape platform economics.
Automated valuation models are collapsing the information asymmetry that historically sustained traditional brokerage commissions. These algorithms ingest municipal tax records, recent comparable sales, and building permit data to generate instant price estimates. First-time buyers in metropolitan U.S. corridors now expect algorithmic pricing as a baseline service. This compression of valuation expertise into code-enabled platforms is collapsing the rationale for percentage-based agent fees and accelerating flat-fee platform adoption.
China's SAMR enforcement of real-time listing verification is tightening platform accountability for data accuracy. The regulation requires instantaneous disclosure of transaction status changes, eliminating stale inventory that previously distorted buyer search economics. Licensed platforms in Beijing and Shanghai face the steepest compliance burdens. Operators are responding by deploying blockchain-anchored timestamping to demonstrate regulatory adherence.
Entire transaction completion on smartphones is displacing web-based search-and-switch patterns among younger cohorts. Mobile applications now handle document execution, earnest money transfer, and notarization scheduling without desktop intervention. This channel shift is most visible in tier-one Chinese cities where mobile payment infrastructure matured earliest. Platform development priorities are reorienting toward native app feature depth rather than responsive web parity.
Second-Hand Housing Trading Platform Market Segmentation
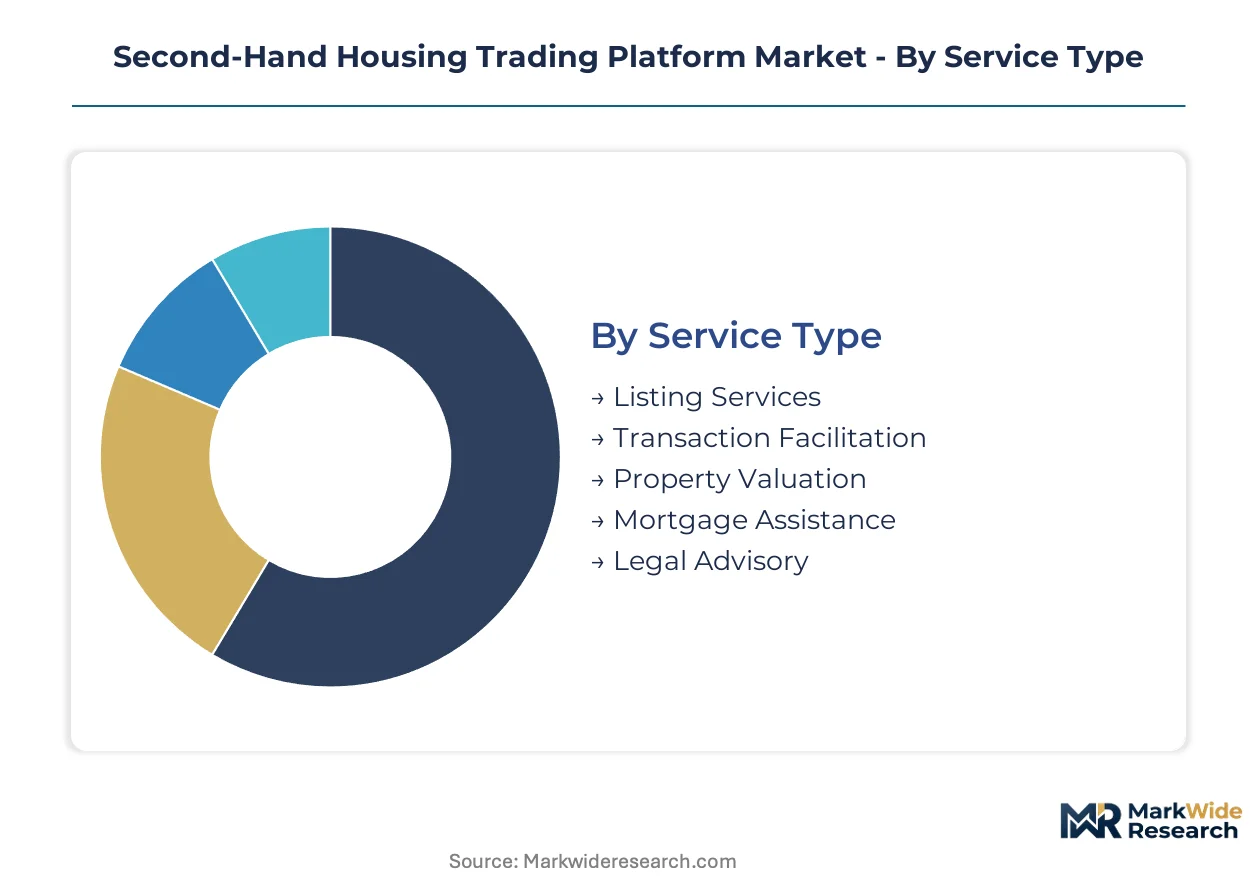
Segmentation in second-hand housing platforms reveals how service intensity, technology adoption, and buyer sophistication create divergent margin pools. Each category exposes distinct operational requirements that reshape platform architecture and customer acquisition economics.
Service Type:
After-sales service intensity varies dramatically across service categories, with transaction-heavy offerings demanding persistent agent engagement while valuation tools require continuous algorithmic refinement.
- Listing Services:Database ingestion and standardized photography packages dominate this foundational tier. Tier-one Chinese cities and metropolitan U.S. corridors concentrate demand here, driven by inventory turnover velocity that outpaces new construction pipelines.
- Transaction Facilitation:End-to-end closing coordination compresses timelines from weeks to days through electronic document execution and earnest money escrow. This segment absorbs the highest customer support burden as document exceptions multiply in high-value transactions.
- Property Valuation:Automated pricing models reduce agent hours per transaction.
- Mortgage Assistance:Pre-qualification API integration opens financial services bundling opportunities.
- Legal Advisory:Title clearance and contract review services carry elevated malpractice exposure.
By volume, Listing Services leads. By growth pace, Transaction Facilitation is gaining share fastest.
Customer Type:
Cost tier stratification separates price-sensitive individual participants from institutional buyers absorbing platform fees as operational overhead.
- Individual Buyers:First-time millennial purchasers complete entire transactions on smartphones, driving mobile-first platform development priorities. This cohort exhibits highest price elasticity and lowest loyalty to any single intermediary.
- Property Investors:Portfolio acquirers demand bulk analytics and off-market deal flow access. Their transaction frequency justifies premium subscription tiers that individual buyers reject.
- Real Estate Agencies:Traditional brokerages license platform technology to maintain competitiveness against digital-native entrants.
- Corporate Buyers:Relocation departments and employer housing programs prioritize standardized reporting and compliance documentation.
- Relocation Firms:Cross-border mobility specialists require multi-jurisdictional legal coordination and currency hedging tools.
Individual Buyers generate the highest transaction count. Property Investors deliver the steepest revenue per user expansion.
Technology:
Application maturity separates legacy web infrastructure from emerging immersive and distributed systems reshaping buyer discovery patterns.
- Web-Based Platforms:Responsive portals still capture majority listing volume through desktop search workflows. Established user habits in older demographics sustain this channel despite mobile migration trends.
- Mobile Applications:Native smartphone experiences now handle document execution, payment transfer, and notarization scheduling without desktop intervention. Younger cohorts in tier-one Chinese cities exhibit complete transaction abandonment of web channels.
- Virtual Tours:3D property scanning reduces physical showing requirements and expands geographic search radius.
- AI-Powered Recommendations:Matching algorithms sit at the core margin pool by reducing agent hours per transaction.
- Blockchain Integration:Timestamped transaction records demonstrate regulatory adherence to SAMR real-time disclosure mandates.
Web-Based Platforms retain the largest installed base. Mobile Applications are climbing the fastest as smartphone-native buyers enter prime homeownership years.
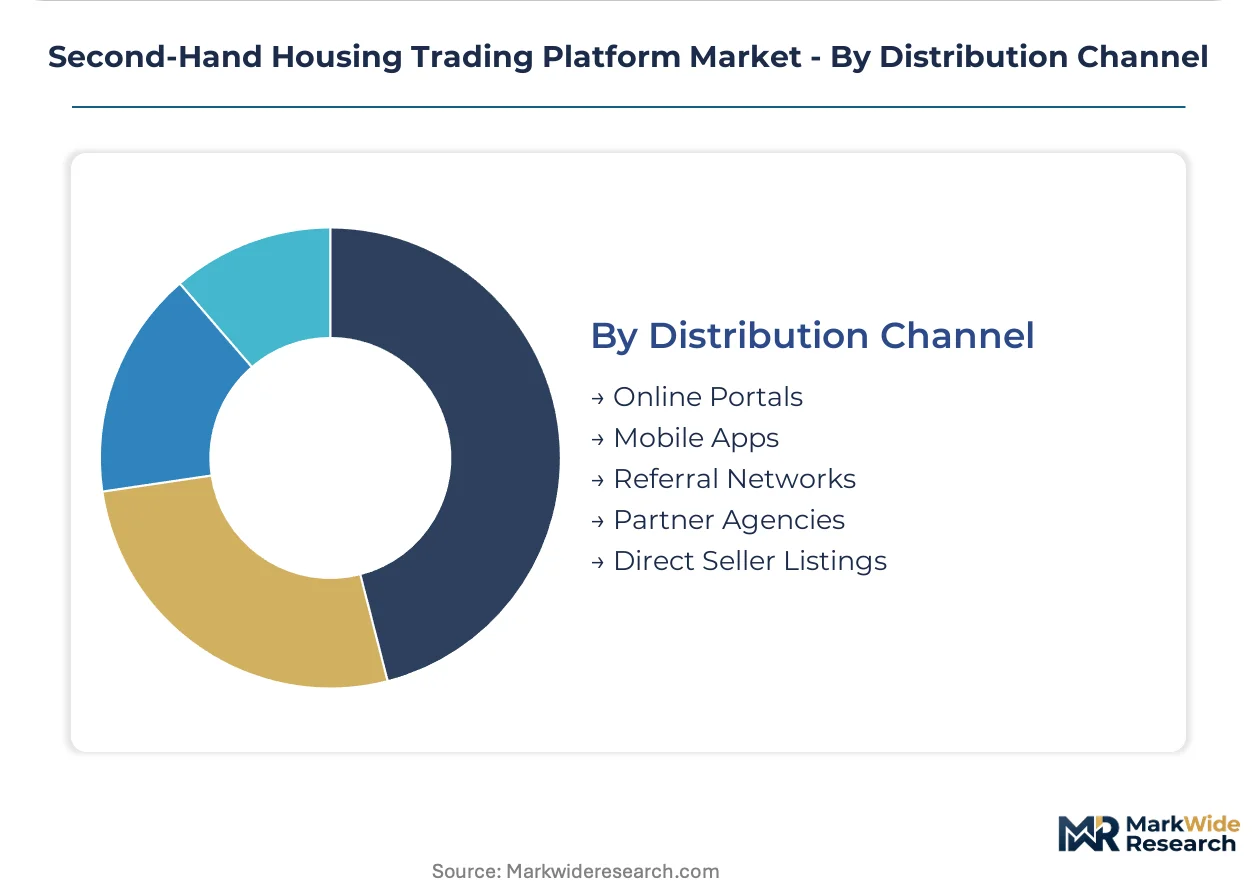
Distribution Channel:
Supply concentration patterns determine whether platforms control inventory directly or intermediate through fragmented agent networks.
- Online Portals:Centralized search destinations aggregate inventory across multiple listing sources. Algorithmic pricing tools and mortgage pre-qualification APIs differentiate portal economics from basic classified advertising.
- Mobile Apps:Native distribution bypasses browser friction and enables push notification re-engagement. This channel captures the fastest-growing engagement share as younger cohorts complete transactions without desktop intervention.
- Referral Networks:Agent-to-agent fee splitting extends platform reach into offline relationship channels.
- Partner Agencies:Exclusive or non-exclusive contracts with traditional brokerages provide inventory access.
- Direct Seller Listings:For-sale-by-owner postings reduce commission burden but increase fraud risk and transaction abandonment.
Online Portals command the broadest inventory aggregation. Mobile Apps show the steepest adoption trajectory as smartphone transaction completion normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border capital flows in second-hand housing platforms remain asymmetric, with Chinese outbound investment into Western property portals outpacing reverse flows. The United States absorbs the largest share of foreign platform technology licensing, while European markets export regulatory compliance frameworks to Asia-Pacific operators.
United States
Metropolitan corridor inventory turnover in cities like Austin, Phoenix, and Nashville drives platform adoption as supply constraints intensify. The Department of Justice scrutinizes NAR-affiliated multiple listing service cooperative compensation rules, creating regulatory uncertainty for data access. Silicon Valley and Seattle clusters concentrate AI-powered valuation algorithm development, attracting venture capital toward automated pricing tools.
China
First-time millennial buyers in Beijing, Shanghai, Shenzhen, and Guangzhou complete entire transactions on smartphones, compressing closing timelines dramatically. SAMR mandates real-time transaction disclosure and prohibits exclusive agent contracts, fragmenting supply-side control. The Yangtze River Delta and Pearl River Delta urban clusters generate the steepest platform revenue per user as mobile payment infrastructure matures.
United Kingdom
Estate agency subscription concentration in London commuter belts sustains portal economics despite Brexit-related transaction volatility. The EU Digital Services Act imposes transparency obligations on cross-border property portals operating from British bases. Manchester and Birmingham secondary markets exhibit faster platform growth rates than the capital as remote work patterns redistribute housing demand.
Germany
Regulatory preference for tenant protections slows speculative second-hand trading velocity compared to Anglo-Saxon markets. The Federal Cartel Office examines platform data aggregation practices under national competition law. Berlin and Munich metropolitan regions concentrate proptech startup formation, particularly around blockchain-anchored transaction verification systems.
Australia
Chinese diaspora investment sustains premium segment platform activity in Sydney and Melbourne despite foreign buyer tax restrictions. The Australian Competition and Consumer Commission monitors portal market concentration effects on agent commission structures. Brisbane and Perth markets demonstrate faster mobile transaction completion adoption as younger cohorts enter prime homeownership years.
Second-Hand Housing Trading Platform Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in valuation algorithms and mortgage API development. The vendor structure concentrates around three strategic archetypes: asset-light franchise networks, proprietary agent-integrated ecosystems, and algorithmic search aggregators. Consolidation pressure intensifies as dominant players acquire regional operators to secure inventory access. Competitive moves center on middleware development for electronic document execution and cross-border compliance architecture investment.
Within the integrated ecosystem tier, Ke Holdings exemplifies proprietary offline agent control through network infrastructure deployment. Zillow and Rightmove occupy positions as algorithmic pricing and search aggregation anchors in their respective North American and European markets. Redfin represents the hybrid archetype combining salaried agent employment with technology platform economics. These operators illustrate how geography-specific regulatory adaptation separates scalable platforms from regionally constrained competitors.
| Leading Market Players |
|---|
| Ke Holdings Inc. |
| 58.com |
| SouFun (Fang Holdings Limited) |
| Anjuke |
| Lianjia |
| Rightmove |
| Zillow |
| Redfin |
| ImmobilienScout24 |
| Others |
Pricing and Supply Chain Analysis
Agent network concentration in tier-one Chinese cities and metropolitan U.S. corridors determines where platform margin pools accumulate downstream. Ke Holdings' proprietary Beike infrastructure and Zillow's algorithmic pricing engines extract differential rents from supply-side fragmentation that prevents unified pricing power.
Pricing Analysis
Individual buyers anchor platform pricing through their price elasticity and low switching costs. Three-tier pricing structure across premium, standard, and economy levels segments by service intensity: full closing coordination commands premium fees, while listing-only access sits at economy tiers. Cost compression in transaction facilitation is intensifying because AI-powered matching algorithms reduce agent hours per deal. Property investors exhibit lowest price sensitivity, absorbing subscription premiums for bulk analytics and off-market deal flow.
Supply Chain Analysis
Tariff exposure between U.S. and Chinese technology licensing agreements dominates supply chain risk for platform middleware development. Software development draws from India, China, and the United States; cloud infrastructure rests on hyperscaler concentration in Virginia, Frankfurt, and Singapore; payment processing hinges on banking partnerships in domestic jurisdictions. Single-source vulnerability in electronic document execution middleware extends technical integration timelines. Distribution runs through online portals and mobile app stores to fragmented agent networks and direct seller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among first-time millennial purchasers completing smartphone-native transactions, fragmenting platform loyalty and intensifying price competition for acquisition.
For Market Incumbents: Pre-empt SAMR-mandated fee unbundling by diversifying revenue toward mortgage API bundling and financial services integration. Defend against asset-light franchise networks by deepening proprietary agent control in tier-two Chinese city expansion corridors. Investment in blockchain-anchored timestamping demonstrates regulatory adherence before compliance deadlines tighten. For New Entrants and Emerging Players: Pursue white space in tier-two Chinese cities beyond Beijing, Shanghai, Shenzhen, and Guangzhou where Ke Holdings' Beike infrastructure remains underdeployed. Target EU Digital Services Act compliance architecture as a first-mover wedge for cross-border property portal transparency obligations. Go-to-market through mortgage pre-qualification API partnerships opens financial services bundling without balance-sheet property risk. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional operators scaling through asset-light franchise financing without inventory risk. Long-term viability centers on platforms controlling offline agent integration or algorithmic pricing data moats. Watch SAMR enforcement intensity as the signal for whether subscription models survive transition to per-transaction micro-commissions.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Development for Electronic Document Execution | Capital-intensive integration with county recorder databases compresses closing timelines from weeks to days. |
| Blockchain-Anchored Transaction Timestamping | Demonstrates SAMR real-time disclosure compliance in Beijing and Shanghai licensing jurisdictions. |
| Mortgage Pre-Qualification API Integration | Opens financial services bundling revenue streams adjacent to core platform transaction fees. |
| Tier-Two Chinese City Network Expansion | Deploys Ke Holdings' Beike infrastructure into underserved urban clusters beyond four tier-one metros. |
| EU Digital Services Act Compliance Architecture | Creates first-mover advantage for cross-border property portals facing transparency obligations. |
Research Methodology
A spread of perspectives from platform engineering directors, real estate brokerage operations heads, regulatory compliance officers, and mortgage API product managers converged on the working assumptions. Primary fieldwork combined with secondary validation from SAMR enforcement bulletins, U.S. Department of Justice antitrust filings, SEC 10-K disclosures from listed platform operators, and EU Digital Services Act implementation guidance. Bottom-up transaction volume modeling and top-down market sizing triangulated across data sources.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include service type intensity, customer tier stratification, technology application maturity, and distribution channel concentration. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs incorporated mobile payment infrastructure penetration curves and algorithmic valuation adoption rates by metropolitan corridor.
Sensitivities concentrate around SAMR enforcement intensity, NAR-affiliated MLS cooperative compensation rule changes, and mobile-first transaction completion adoption velocity. Forecasts reflect documented assumptions on agent workforce retention and data standardization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Warehousing Services Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
US Home Service Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Latin America Coworking Spaces Market