
 Asia-Pacific Self Storage Market | 2026-2036
Asia-Pacific Self Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Self Storage Market Outlook
Third-party affiliate networks is tilting toward direct digital leasing across the Asia-Pacific Self Storage Market. Extra Space Asia leverages its Singapore hub to anchor premium site selection across Southeast Asian metros. Storage King Pty Ltd dominates Australian franchise operations through controlled territory mapping. Quraz Co., Ltd. specializes in compact urban formats that navigate Tokyo's restrictive zoning codes.
Asia-Pacific self storage denotes leased enclosed space ranging from 25 to 300 square feet, constructed with corrugated steel partitions, climate-moderated HVAC systems, and electronic access control for temporary goods custody. These facilities serve residential decluttering, commercial inventory overflow, and specialized asset preservation. Climate-Controlled Units command premium pricing due to humidity-sensitive electronics and document storage demand across tropical Southeast Asia. Standard Units sustain volume leadership in Australia's suburban corridors where seasonal household rotation drives occupancy. Mobile Storage extends fastest in Japan's earthquake-preparedness segment where relocatable modules address disaster contingency planning.
Australia's state planning authorities, Japan's METI building codes, and Singapore's URA zoning frameworks collectively shape facility siting, fire safety standards, and permissible floor-area ratios. TRAI's digital infrastructure mandates in India indirectly accelerate online rental channel penetration for tier-1 city operators. Stakeholders must monitor evolving municipal density rules and building energy efficiency standards that will determine viable expansion corridors.
Market Dynamics
Direct digital leasing platforms are compressing traditional affiliate commission structures across Asia-Pacific self storage, forcing operators to reallocate marketing spend toward proprietary booking engines and automated unit allocation systems.
Growth Catalysts
- Australia's mixed-use zoning reforms:State planning authorities now permit self-storage facilities in previously restricted commercial-residential zones, unlocking infill development opportunities in Sydney and Melbourne corridors.
- Small business inventory overflow:Urban commercial rent escalation in Australian state capitals drives SMEs toward flexible storage solutions rather than warehouse leases.
- Mobile storage modules:Japan's earthquake-preparedness protocols mandate relocatable asset protection, creating institutional demand for containerized storage systems.
Market Restraints
- Steel input volatility:Corrugated partition manufacturing faces raw material cost pressure from regional steel supply concentration.
- Tokyo zoning density limits:METI building codes restrict floor-area ratios for storage facilities in central wards, constraining urban expansion.
- Climate control energy costs:HVAC system operation in tropical Southeast Asian facilities consumes disproportionate operating expenditure versus temperate markets.
Strategic Opportunities
- India's tier-1 digital infrastructure:TRAI mandates for broadband penetration enable online-first rental channels in underserved metropolitan markets.
- Compact urban format proliferation:Multi-story automated storage systems address land scarcity in Singapore's URA-designated high-density zones.
- Document preservation specialization:Humidity-sensitive archival storage serves legal and financial services verticals across Southeast Asian commercial hubs.
Industry Challenges
- Fire safety compliance timelines:Australia's state-level building certification processes delay facility commissioning by six to twelve months in suburban corridors.
- Legacy access control integration:Biometric and mobile credential systems require capital-intensive retrofits at existing facilities with mechanical lock infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Self Storage Market |
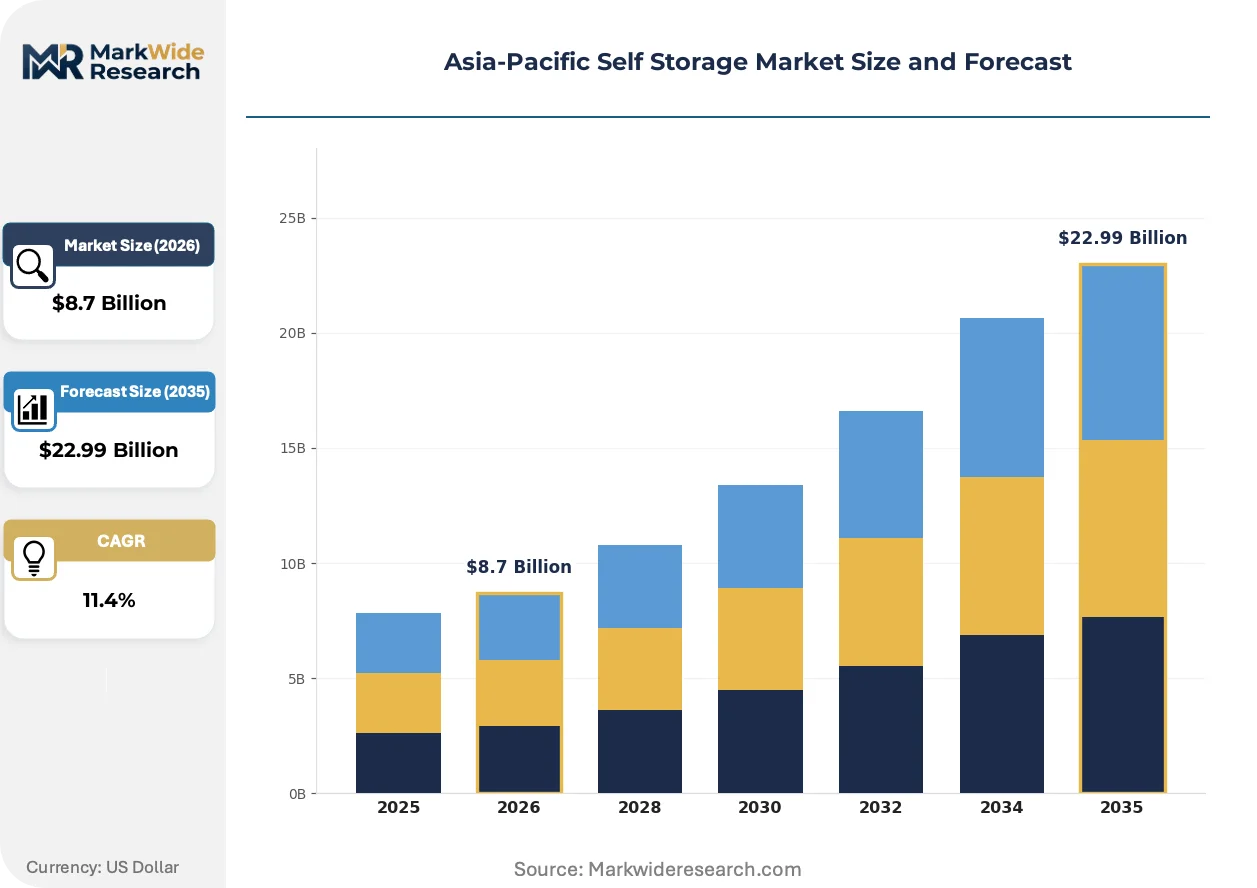
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Climate-Controlled Units, Standard Units, Mobile Storage, Container Storage Application: Residential, Commercial, Business Inventory, Wine Storage End User: Individuals, Small Businesses, Corporations, Non-Profit Organizations Distribution Channel: Online Rental, Direct Sales, Third-Party Affiliates, Auctions |
| Companies Covered | CubeSmart LP, Boxful Holdings Limited, Extra Space Asia, General Storage Co., Quraz Co., Ltd., Store Friendly Self-storage Group Ltd, Storage King Pty Ltd, Far East Organization, StorHub Self-storage, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Self Storage Market Strategic Shifts
Facility automation and climate adaptation technologies are restructuring capital deployment patterns across Asia-Pacific self storage, with operators prioritizing digital customer acquisition over physical site expansion.
Automated unit retrieval systems utilizing vertical carousel storage is collapsing floor-space requirements for urban facilities in Tokyo and Singapore. Japanese operators deploy these systems in sub-500 square meter footprints previously considered economically unviable. The technology is collapsing minimum viable site thresholds and enabling premium-location penetration where conventional warehouse layouts fail.
Singapore's URA zoning framework now mandates building energy efficiency standards for new commercial developments including self-storage facilities. The regulation requires minimum Green Mark certification levels for permits in designated growth corridors. Operators respond by integrating solar photovoltaic arrays and smart HVAC controls into facility designs, particularly affecting climate-controlled unit economics in tropical markets.
Small business procurement of storage services has shifted from annual contract negotiation toward month-to-month digital subscription models. Australian SME customers now expect real-time availability visibility and immediate move-in capability through mobile applications. This pattern is most pronounced in Melbourne and Sydney, where commercial tenant turnover accelerates facility switching behavior and rewards operators with frictionless onboarding systems.
Asia-Pacific Self Storage Market Segmentation
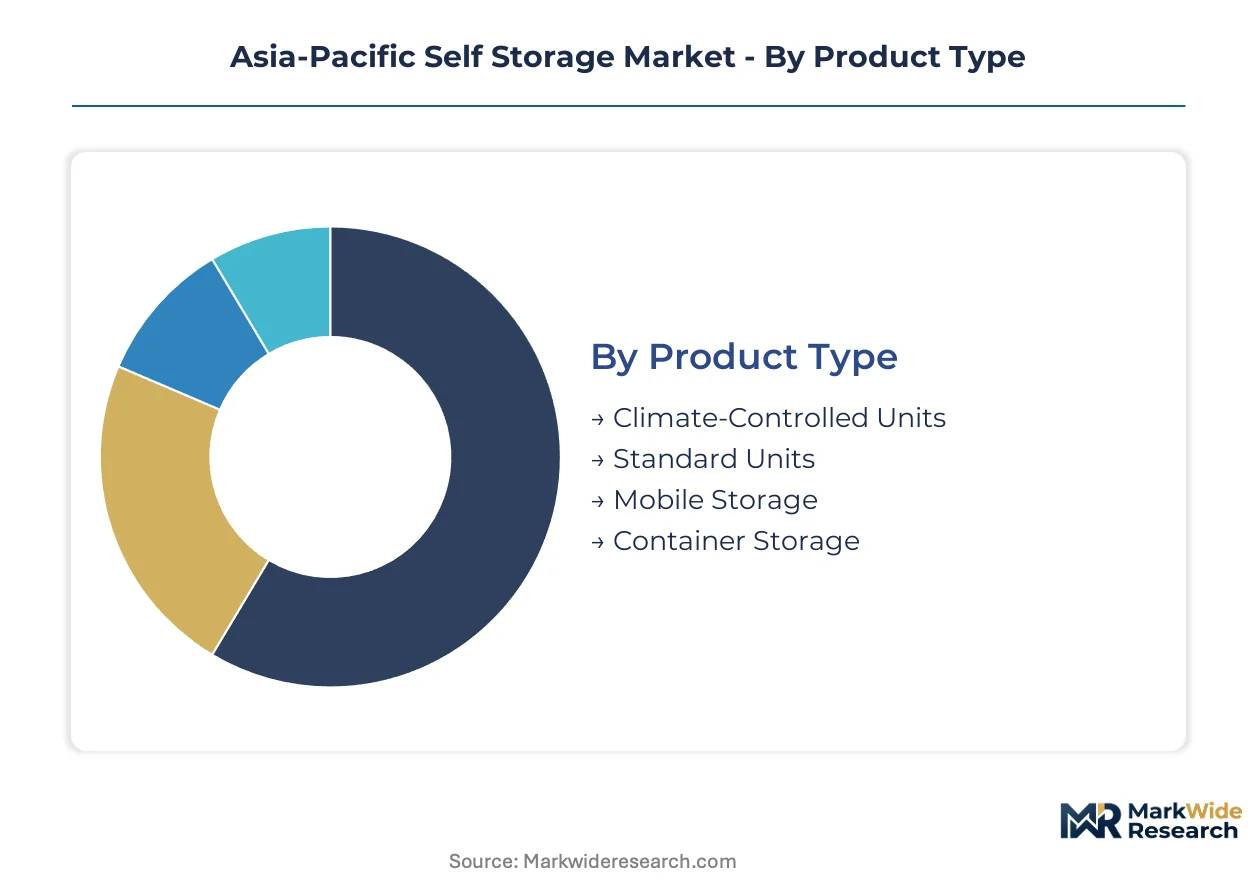
Segmentation in Asia-Pacific self storage reveals how facility operators balance capital intensity against revenue per square foot across divergent climate zones and customer lifecycles. Product configuration decisions directly determine HVAC load profiles, insurance premiums, and permitted zoning classifications in each metropolitan market.
Product Type:
Mature formats dominate Australian suburban corridors while emerging automated systems penetrate Tokyo and Singapore land-constrained districts.
- Climate-Controlled Units:Enclosed spaces maintain 50-55% relative humidity and 18-24°C through precision HVAC systems with redundant cooling loops. Demand concentrates in Singapore and Bangkok commercial districts where legal document preservation and electronics storage face tropical degradation risks. Premium pricing offsets 40-60% higher energy operating expenditure versus standard alternatives.
- Standard Units:Corrugated steel partitions without active climate management serve seasonal household rotation and construction material staging. Australia's southeastern corridor from Brisbane to Adelaide sustains volume leadership where temperate climates reduce asset deterioration concerns. Lower capital requirements enable rapid suburban rollout following state-level mixed-use zoning reforms.
- Mobile Storage:Relocatable container modules address Japan's earthquake-preparedness protocols and institutional disaster contingency planning.
- Container Storage:Modular steel units support construction site logistics and temporary commercial overflow across Australian mining and infrastructure corridors.
Standard units handle the majority of throughput; mobile storage is the fastest mover on share.
Application:
Commercial use cases command higher revenue per transaction while residential demand provides occupancy stability through economic cycles.
- Residential:Decluttering and life-transition storage during relocation, divorce, or estate settlement drives consistent baseline occupancy. Melbourne and Sydney residential customers exhibit highest facility-switching propensity where month-to-month digital subscription models displace annual contracts.
- Commercial:Professional service firms store inactive files and equipment overflow in climate-controlled configurations. Singapore's URA-designated high-density zones concentrate legal and financial services verticals with humidity-sensitive archival requirements.
- Business Inventory:SME overflow from urban commercial rent escalation in Australian state capitals accelerates flexible storage adoption over warehouse leases.
- Wine Storage:Specialized temperature and vibration control serves collector and hospitality verticals in premium Australian and Japanese metropolitan markets.
Residential applications anchor baseline occupancy; commercial inventory storage is expanding most quickly as urban rents climb.
End User:
Customer scale determines contract structure complexity and facility service tier requirements across the region.
- Individuals:Single-unit renters drive digital-first booking expectations and immediate move-in capability through mobile applications. Australian metropolitan markets exhibit highest individual customer acquisition cost due to fragmented competitor density.
- Small Businesses:Multi-unit commercial accounts provide revenue concentration and longer average tenancy duration. Sydney and Melbourne SME segments demonstrate strongest growth correlation with central business district commercial rent indices.
- Corporations:Enterprise accounts require dedicated account management and customized access protocols across distributed facility networks.
- Non-Profit Organizations:Mission-driven storage needs include archival preservation and event equipment staging with constrained procurement budgets.
Individual end users generate the highest transaction frequency; small business accounts deliver the steepest expansion trajectory in revenue contribution.
Distribution Channel:
Channel economics are restructuring as commission-based affiliate networks compress under direct digital platform investment.
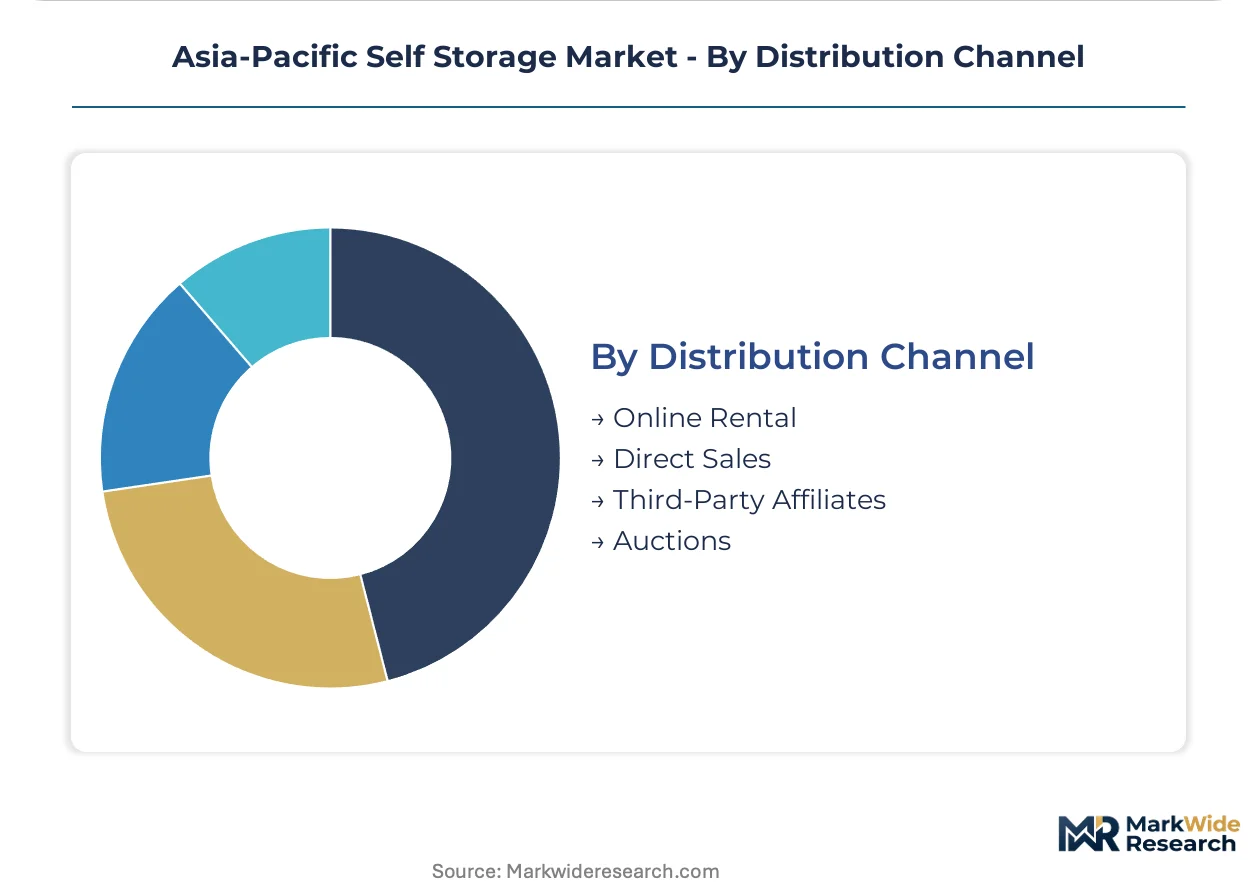
- Online Rental:Proprietary booking engines with real-time availability visibility and automated unit allocation capture preference among Australian SME customers. TRAI's digital infrastructure mandates in India accelerate channel penetration in underserved tier-1 metropolitan markets.
- Direct Sales:Facility walk-ins and telephone inquiries persist among older demographic segments and complex multi-unit commercial negotiations.
- Third-Party Affiliates:Comparison websites and relocation service partnerships face margin pressure as operators reallocate marketing spend toward owned digital channels.
- Auctions:Lien sale liquidations of abandoned units generate ancillary revenue and occupancy turnover in regulated foreclosure processes.
Online rental channels handle the majority of new customer acquisition; direct sales retains importance in commercial account development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Sydney and Melbourne exceeds that in Bangkok and Manila by roughly 40-60% for equivalent climate-controlled square footage. This asymmetry reflects divergent zoning flexibility, commercial rent trajectories, and SME density across the Asia-Pacific corridor.
Australia
Small business inventory overflow and residential decluttering drive demand across Sydney and Melbourne corridors. State-level planning reforms under various state authorities now permit self-storage in mixed-use zones previously restricted to pure commercial or residential use. The southeastern corridor from Brisbane to Adelaide concentrates facility development where temperate climates reduce climate-control capital requirements.
Japan
Earthquake-preparedness protocols and urban land scarcity create institutional demand for mobile storage modules and automated vertical systems. METI building codes restrict floor-area ratios for storage facilities in Tokyo's central wards, pushing operators toward compact multi-story formats. Osaka and Nagoya operators deploy carousel retrieval systems in sub-500 square meter footprints previously deemed economically unviable.
Singapore
Legal and financial services verticals generate premium demand for humidity-sensitive document preservation in URA-designated high-density zones. The national urban planning authority mandates Green Mark certification for new commercial developments including self-storage facilities. Jurong and Tampines clusters integrate solar photovoltaic arrays and smart HVAC controls to meet energy efficiency standards.
India
Tier-1 metropolitan markets accelerate online-first rental channel penetration following TRAI digital infrastructure mandates for broadband penetration. The national telecommunications regulator's connectivity requirements enable real-time availability platforms in underserved Delhi-Mumbai-Bangalore corridors. Gurgaon and Hyderabad sub-markets exhibit strongest facility switching behavior among SME customers.
Thailand
Tropical humidity drives electronics and document storage demand toward climate-controlled configurations in Bangkok commercial districts. National building energy efficiency standards shape HVAC system specifications for new facility construction. The Bangkok-Chonburi corridor concentrates premium-format development serving regional headquarters operations.
Asia-Pacific Self Storage Market Competitive Environment
Franchise-network operators and automated-format specialists split the market into distinct competitive spheres. The vendor base clusters around three strategic archetypes: territory-mapped franchise systems, compact-urban automation providers, and premium-location hub operators. Consolidation pressure favors operators with proprietary digital leasing platforms over third-party affiliate-dependent models. Geographic expansion through controlled territory mapping and technology licensing for automated retrieval systems represent the dominant competitive vectors.
Within the franchise-network tier, Storage King Pty Ltd exemplifies territory-controlled expansion across Australian suburban corridors. Extra Space Asia anchors premium site selection capabilities from its Singapore hub across Southeast Asian metros. Quraz Co., Ltd. occupies the compact-urban automation position, navigating Tokyo's restrictive zoning environment through multi-story vertical formats. These three operators represent the strategic archetype diversity shaping competitive dynamics across the region.
| Leading Market Players |
|---|
| CubeSmart LP |
| Boxful Holdings Limited |
| Extra Space Asia |
| General Storage Co. |
| Quraz Co., Ltd. |
| Store Friendly Self-storage Group Ltd |
| Storage King Pty Ltd |
| Far East Organization |
| StorHub Self-storage |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Singapore maritime corridor's freight cost volatility transmits directly into corrugated steel partition pricing across Asia-Pacific self storage, compressing margins for climate-controlled unit operators while amplifying regional price differentiation between Australian temperate-zone facilities and Southeast Asian humidity-managed configurations.
Pricing Analysis
The customization-premium spread between configured-to-order climate-controlled units and standard corrugated steel configurations spans subscription-based monthly pricing models across the region. Price differentiation drivers center on Green Mark certification tiers in Singapore and HVAC redundancy specifications in Bangkok commercial districts, with pricing pressure intensifying in Australian standard units due to state-level zoning reform-driven supply influx. Small business inventory overflow customers in Sydney exhibit lowest price sensitivity for immediate move-in capability, while residential decluttering segments in Melbourne demonstrate highest switching propensity toward digital-native competitors.
Supply Chain Analysis
Extended payment terms from Chinese steel mills and supply-chain finance facilities anchored in Singaporean trade credit networks shape procurement economics for facility developers. Geographic supply concentration rests on China for corrugated partition manufacturing, South Korea for precision HVAC components, and Australia for domestic steel sourcing serving southeastern corridor projects. Raw material dependencies span galvanized steel coils, refrigerant gases, and electronic access control modules. Single-source vulnerability concentrates in semiconductor-dependent biometric lock systems. Distribution runs through direct mill relationships for greenfield developments and regional distributor networks for retrofit expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection demands interoperability investment as Australia's state-level digital leasing mandates and Singapore's URA energy certification databases converge into unified tenant-facing interfaces.
For Market Incumbents: Build data-network moats through proprietary availability APIs that lock in small business multi-unit accounts. Defensive consolidation moves center on acquiring automated retrieval technology licenses for Tokyo-density formats and securing exclusive territory mapping in Adelaide-Brisbane corridor expansion zones. Direct digital platform investment displaces third-party affiliate dependence as the primary margin defense against emerging automated-format specialists. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia with underutilized floorplates represent the most penetrable entry point for compact-urban automated systems. White-space targets include Gurgaon flex-office conversions and Bangkok-Chonburi logistics-adjacent infill. Go-to-market execution should anchor on month-to-month digital subscription models with real-time HVAC performance visibility to differentiate against legacy annual-contract incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified real estate investment trusts with non-core self-storage portfolios in Australian mixed-use zones. Long-term viability frames facility automation as essential for land-constrained Asian metros versus suburban rollouts in temperate corridors. The signal to watch is TRAI-mandated broadband penetration velocity in Indian tier-1 cities as proxy for digital-first rental channel scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Digital Leasing Platform Development | Direct booking engines capture Australian SME preference for immediate move-in capability. |
| Automated Vertical Storage System Deployment | Carousel retrieval collapses minimum viable footprints in Tokyo's METI-restricted central wards. |
| Green Mark Certification Integration | Singapore's URA mandates solar photovoltaic arrays for new commercial development permits. |
| Mobile Storage Module Manufacturing Scale-Up | Earthquake-preparedness protocols in Japan institutionalize containerized disaster contingency demand. |
| State-Level Territory Mapping Acquisition | Controlled franchise expansion in Adelaide-Brisbane corridor captures zoning reform timing. |
Study Parameters
Desk research of customs trade databases, state planning authority filings, and METI building code registries preceded structured interviews with self-storage facility operators, commercial real estate developers, HVAC system procurement managers, and digital platform engineering leads. Primary fieldwork across Sydney, Singapore, and Tokyo markets combined with secondary validation from URA development permit records and TRAI infrastructure disclosure filings. Bottom-up unit economics modeling triangulated against top-down regional market sizing.
Assumption sets held steel input cost trajectories and zoning reform implementation timelines fixed while varying SME commercial rent escalation rates and digital adoption curves across the projection horizon. Segmentation dimensions modeled include product type configuration, application vertical, end-user scale tier, and distribution channel mix. CAGRs derived from facility development pipeline tracking and occupancy rate trajectories in identified growth corridors, with climate-control energy cost differentials and automated system capital intensity as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Australian commercial property yields, Japanese yen-denominated construction finance costs, or Indian broadband penetration velocity would shift the trajectory. Regulatory acceleration in state-level planning reforms or METI floor-area ratio adjustments could revise facility economics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Warehousing Services Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
Global Home Services Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
Vietnam Self-Storage Market