
 Europe Real Estate Brokerage Market | 2026-2036
Europe Real Estate Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Real Estate Brokerage Market Insights
The gap between trophy asset advisory and mid-market transaction services is consolidating as commission compression hits standardized deals while bespoke investment advisory commands premium fees. CBRE Group leverages its pan-European investment platform to capture cross-border capital deployment mandates. JLL sustains competitive position through technology-integrated lease administration and occupier services across major metropolitan nodes. Savills differentiates via specialized rural and prime residential networks that resist digitization pressure.
Real estate brokerage encompasses intermediary services facilitating property transactions through valuation, marketing, negotiation, and closing coordination, typically operating on commission structures tied to transaction value with fiduciary obligations to clients. The field serves capital allocation efficiency by matching asset owners with qualified buyers, lessees, or investors across risk-return profiles. Residential brokerage retains volume dominance across European markets though margin pools increasingly concentrate in investment advisory serving institutional capital deployment. Commercial brokerage segments exhibit structural bifurcation where logistics and life sciences specialization commands pricing power against generalized office leasing services. Leasing services for corporate occupiers are accelerating as hybrid work patterns drive portfolio restructuring mandates across transaction size tiers.
EU Green Deal building performance standards and national energy certification regimes are elevating due diligence complexity and reshaping broker competency requirements across member states. ESG disclosure frameworks including CSRD are forcing transaction documentation to incorporate sustainability metrics that influence pricing and liquidity. National regulators in France, Germany, and the Netherlands enforce anti-money laundering protocols through notary and broker verification chains that extend transaction timelines. Stakeholders must monitor how evolving climate risk disclosure obligations will redistribute advisory value toward technical asset repositioning expertise.
Market Dynamics
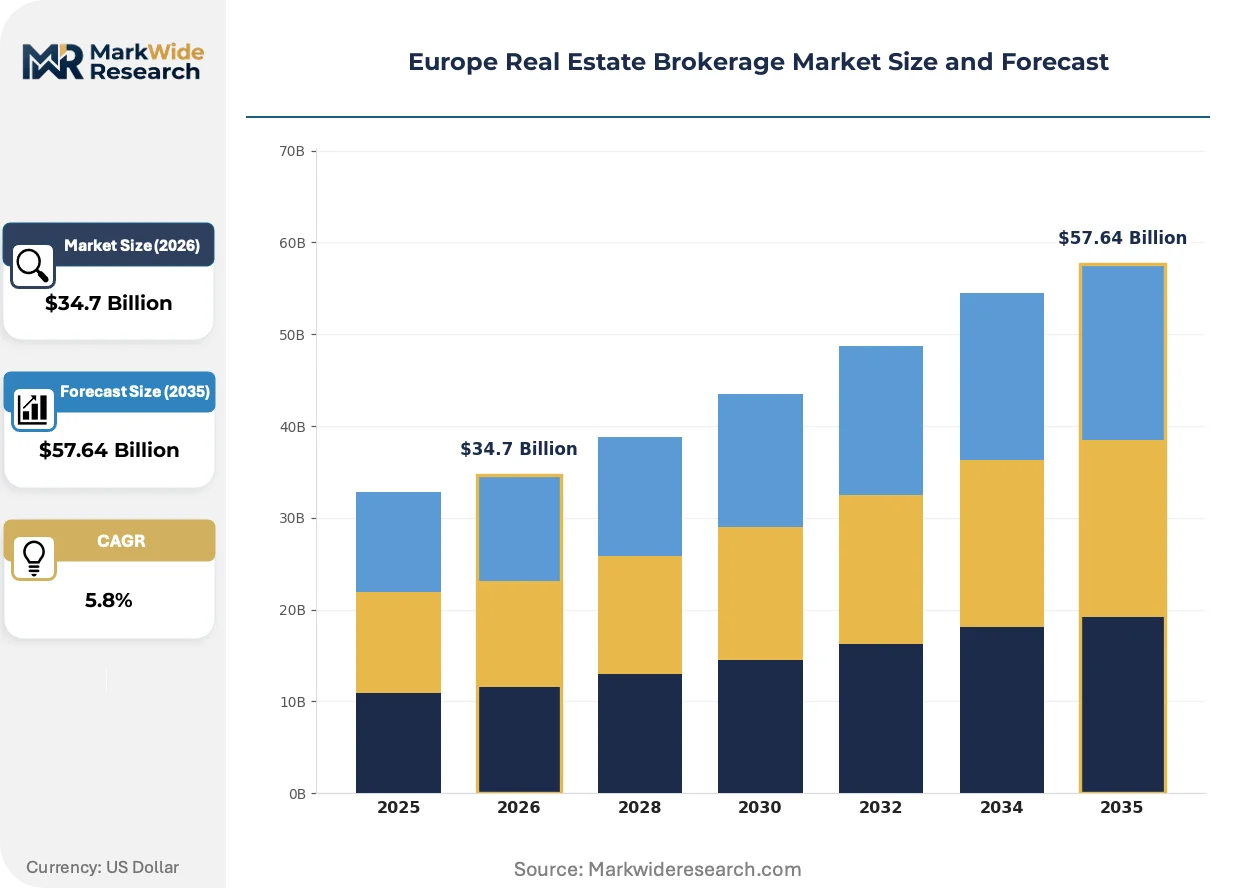
Commission compression on standardized transactions is consolidating advisory value toward technical repositioning expertise as EU Green Deal building performance standards reshape asset valuations across member states.
Growth Catalysts
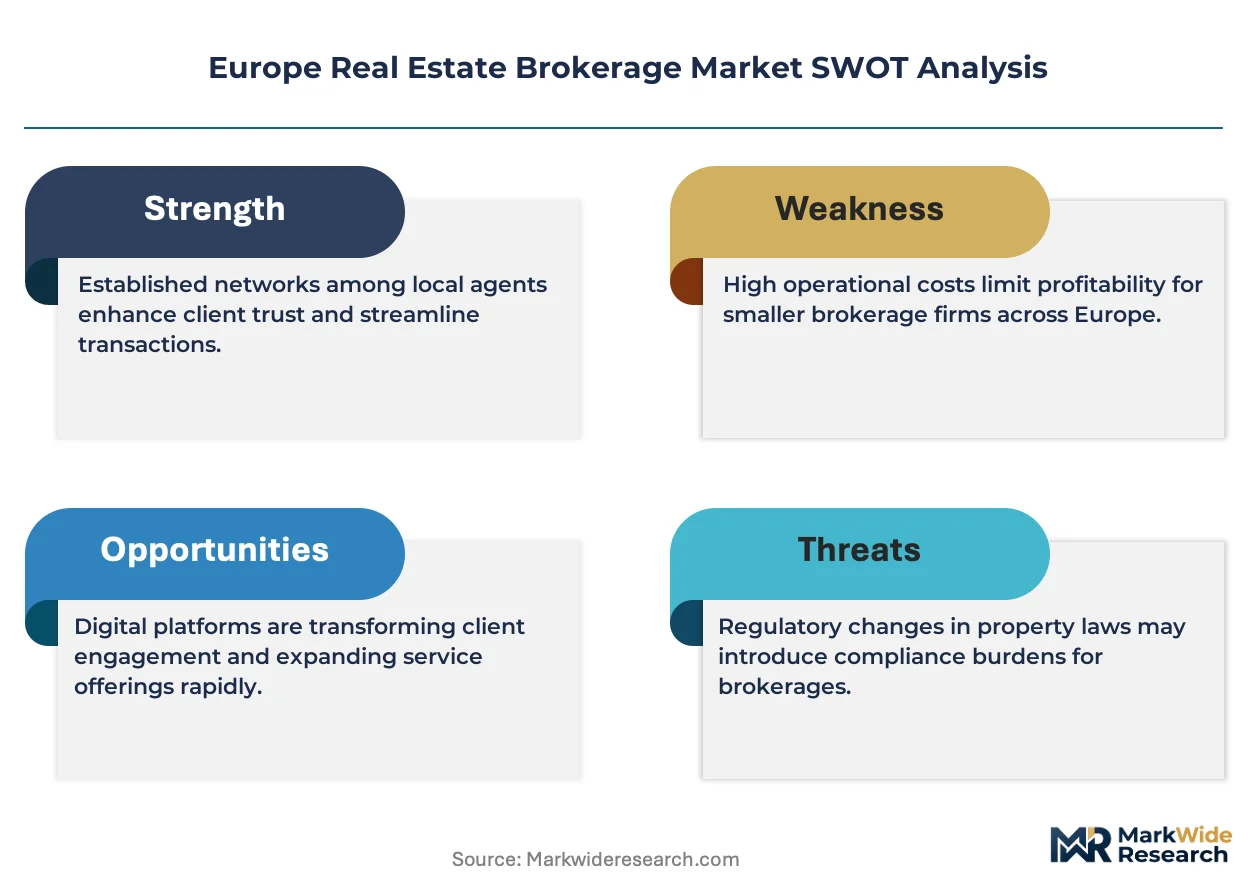
- CSRD disclosure mandates:Corporate Sustainability Reporting Directive requirements are elevating demand for ESG-integrated transaction documentation and sustainability-linked valuation services.
- Logistics corridor development:Germany's Rhine-Ruhr and Netherlands Randstad freight networks are generating concentrated demand for industrial asset advisory and last-mile facility brokerage.
- PropTech integration:AI-powered valuation engines and digital twin technologies are compressing due diligence timelines and expanding transaction throughput capacity.
Market Restraints
- Notary verification chains:France, Germany, and Netherlands anti-money laundering protocols extend transaction timelines through multi-layered identity verification requirements.
- Energy retrofit cost volatility:Building performance standard upgrades impose capital requirements that compress seller pricing power and extend marketing periods.
- Mid-market commission compression:Standardized residential and office transactions face fee erosion as digital platforms disintermediate traditional brokerage functions.
Strategic Opportunities
- Spain residential recovery markets:Underserved secondary cities and coastal regeneration zones present white space for valuation and transaction advisory expansion.
- Life sciences specialization:Laboratory and R&D facility expertise commands premium fees as pharmaceutical and biotech occupiers expand manufacturing footprints.
- EU Green Deal technical advisory:Energy performance contracting and retrofit financing advisory represents emerging fee pools as building standards tighten.
Industry Challenges
- ESG competency gaps:Shortage of brokers qualified to assess climate risk exposure and energy performance trajectories limits advisory capacity on complex assets.
- Legacy system integration:Established firms face friction merging traditional client relationship databases with automated valuation and marketing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Real Estate Brokerage Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Brokerage, Commercial Brokerage, Leasing Services, Investment Advisory Customer Type: Individual Buyers, Real Estate Investors, Corporations, Government Entities Property Type: Residential Properties, Commercial Properties, Industrial Spaces, Mixed-Use Developments Transaction Size: Small Transactions, Medium Transactions, Large Transactions, High-Value Deals |
| Companies Covered | CBRE Group, Jones Lang LaSalle (JLL), Savills, Knight Frank, BNP Paribas Real Estate, Cushman & Wakefield, Colliers International, Engel & Völkers, RE/MAX Europe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Real Estate Brokerage Market Trends and Innovations
Digital infrastructure and regulatory complexity are bifurcating the brokerage field between automated transaction processing and high-touch technical advisory services.
Automated valuation models leveraging machine learning and comparable sales databases are automating residential price estimation and initial marketing pricing strategies. Mid-tier brokerages across Spain and Poland are adopting these platforms to reduce manual appraisal labor and accelerate listing preparation. The compression of routine valuation work is automating fee structures toward flat-rate subscription models and away from percentage-based commissions.
EU Green Deal building performance standards and national energy certification regimes are mandating sustainability disclosures in transaction documentation. CSRD alignment requirements force sellers to provide operational carbon data and retrofit cost projections that influence pricing negotiations. Commercial assets in France and Germany face the steepest compliance burdens as regulators enforce stricter energy performance certificates and renovation roadmaps.
Corporate occupiers are unbundling traditional full-service brokerage relationships into specialized mandates for lease administration, portfolio restructuring, and flexible workspace sourcing. Large enterprises across the Netherlands and UK are contracting directly with technology platforms for transaction execution while retaining bespoke advisors for complex repositioning projects. This bifurcation is most pronounced in logistics and life sciences verticals where technical facility requirements exceed standardized platform capabilities.
Europe Real Estate Brokerage Market Segmentation
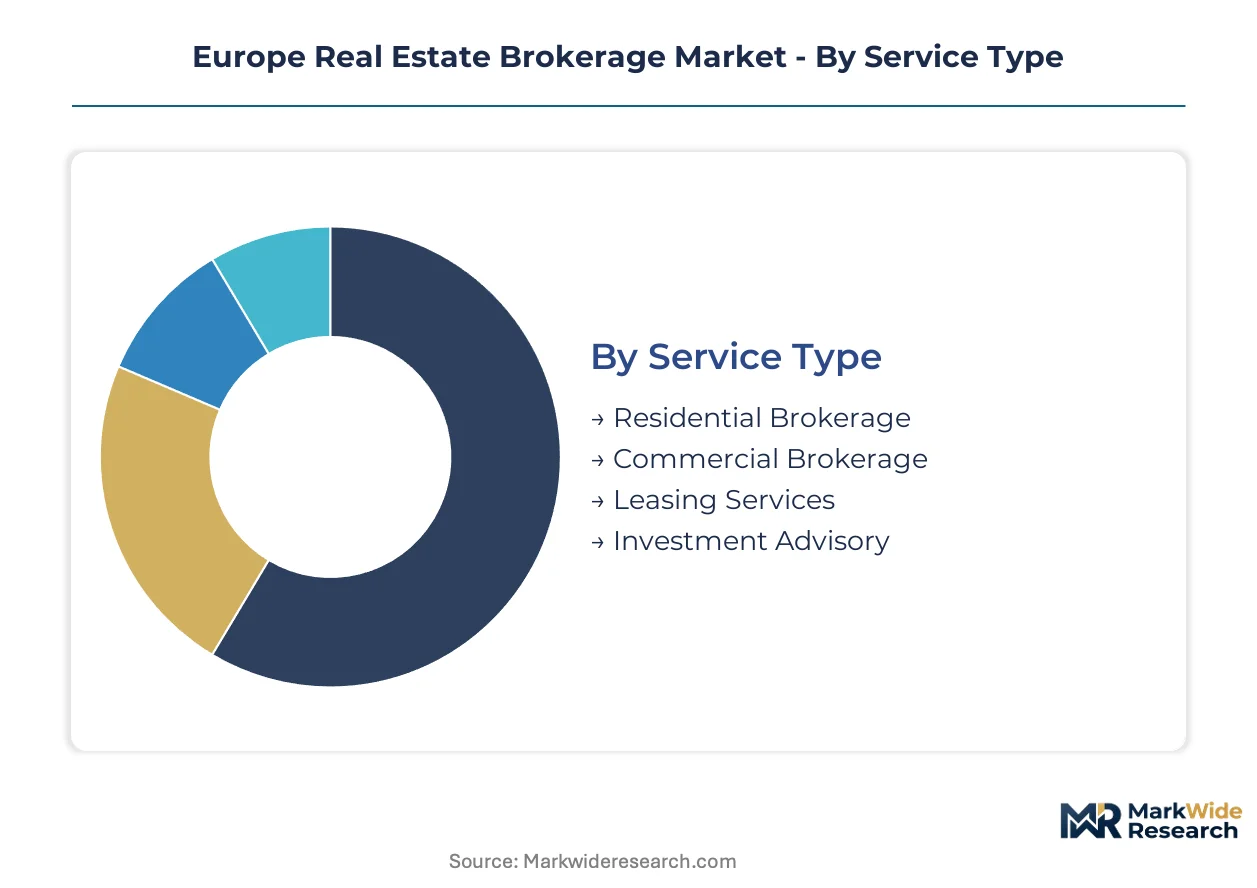
Brokerage revenue pools fragment across service specializations as commission structures diverge between automated transaction processing and technical advisory mandates. Customer sophistication and asset complexity determine fee retention, with institutional mandates commanding premium pricing against standardized retail services.
Service Type:
Advisory upgrade cycles accelerate as regulatory complexity and ESG disclosure requirements force clients toward specialized expertise over commoditized transaction support.
- Residential Brokerage:Volume-dominant segment spanning primary home sales, secondary market transactions, and rental placement services. Transaction activity concentrates in Spain's coastal regeneration zones and Germany's urban infill corridors as interest rate sensitivity reshapes buyer affordability thresholds.
- Commercial Brokerage:Office, retail, and hospitality asset advisory requiring lease structure analysis and tenant credit assessment. Demand clusters in Netherlands Randstadt logistics nodes and French life sciences clusters where technical facility requirements exceed standardized platform capabilities.
- Leasing Services:Tenant representation and landlord advisory for lease negotiation, renewal, and restructuring.
- Investment Advisory:Institutional capital deployment, portfolio strategy, and asset repositioning mandates.
Volume placements concentrate in Residential Brokerage; the faster expansion belongs to Investment Advisory.
Customer Type:
Fee structures diverge sharply across client sophistication tiers, with institutional mandates supporting dedicated advisory teams while individual transactions face platform disintermediation.
- Real Estate Investors:Institutional and private equity capital deploying across risk-return profiles and holding period strategies. Advisory mandates intensify in Germany's logistics corridors and Nordic residential platforms as cross-border capital flows accelerate deployment timelines.
- Corporations:Occupier clients restructuring portfolios around hybrid work patterns and supply chain regionalization. Demand concentrates in Netherlands and UK markets where lease administration unbundling creates specialized mandate opportunities.
- Individual Buyers:First-time purchasers and residential investors utilizing brokerage for search, valuation, and negotiation support.
- Government Entities:Public sector leasing, disposition, and development partnership advisory.
Revenue concentration sits with Real Estate Investors; Corporate mandates are climbing the fastest as portfolio restructuring accelerates.
Property Type:
Asset complexity determines advisory pricing power, with specialized property categories resisting digitization pressure against standardized residential workflows.
- Industrial Spaces:Warehouse, distribution, and manufacturing facility brokerage requiring loading specifications, ceiling heights, and transportation access analysis. Germany's Rhine-Ruhr freight networks and Poland's central European distribution hubs generate concentrated demand for last-mile and bulk logistics advisory.
- Mixed-Use Developments:Integrated residential, commercial, and hospitality assets with layered ownership structures and phased delivery timelines. Development activity clusters in Spanish secondary cities and Portuguese urban regeneration districts as planning frameworks accommodate densification.
- Residential Properties:Single-family, multifamily, and condominium assets for owner-occupancy or investment holding.
- Commercial Properties:Office, retail, and hospitality assets with income-focused valuation methodologies.
Transaction flow concentrates in Residential Properties; Industrial Spaces are gaining share fastest on logistics corridor development.
Transaction Size:
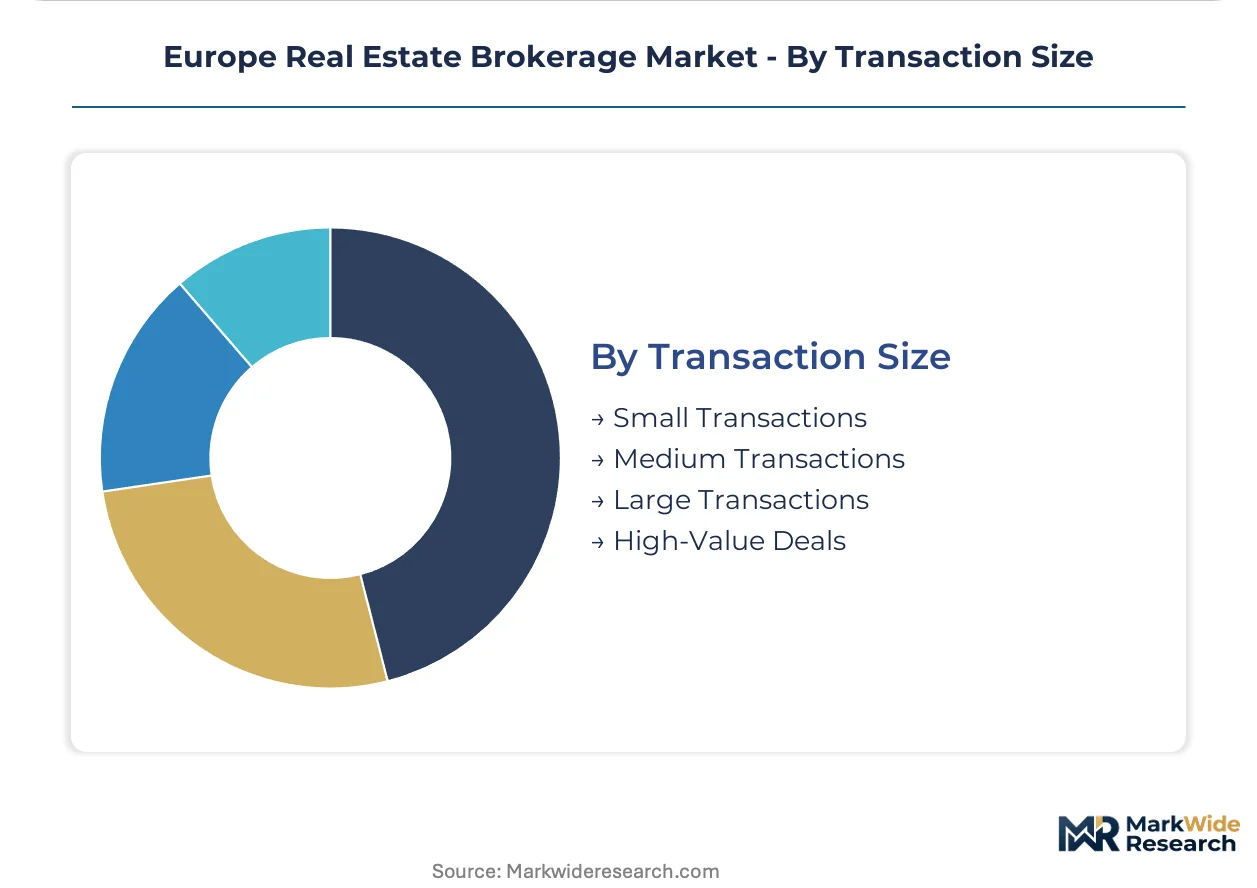
Deal scale determines advisory team structure and fee negotiation leverage, with mid-market transactions facing the steepest commission compression.
- High-Value Deals:Trophy assets and portfolio transactions requiring cross-border capital matching and complex structuring. Advisory mandates concentrate in London, Paris, and Frankfurt as institutional investors compete for prime logistics and residential platforms.
- Large Transactions:Single-asset institutional sales and corporate lease commitments with dedicated advisory coverage.
- Medium Transactions:Regional commercial assets and multi-unit residential properties with standardized due diligence.
- Small Transactions:Individual residential sales and small commercial leases facing platform disintermediation pressure.
Fee pool concentration rests with High-Value Deals; Large Transactions show the steepest expansion trajectory on institutional capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors European real estate brokerage activity through its concentration of trophy asset advisory and cross-border capital matching, while Frankfurt, Paris, and Amsterdam compete for institutional mandate volume through specialized logistics and life sciences expertise.
Germany
Rhine-Ruhr logistics corridors and Berlin-Brandenburg residential platforms drive concentrated advisory demand as institutional capital targets last-mile distribution assets. The Federal Financial Supervisory Authority (BaFin) enforces anti-money laundering verification chains that extend commercial transaction timelines. Munich and Hamburg sustain premium fee pools through specialized office repositioning mandates serving corporate occupiers.
United Kingdom
London's prime residential and commercial markets generate high-value deal flow despite post-Brexit regulatory friction affecting cross-border capital deployment. The Financial Conduct Authority maintains oversight of property investment vehicles while lease administration unbundling accelerates across corporate portfolios. Manchester and Birmingham emerge as secondary market growth nodes as hybrid work patterns redistribute occupier demand.
France
Paris Île-de-France logistics clusters and Lyon life sciences corridors attract specialized brokerage expertise as technical facility requirements exceed standardized platform capabilities. The Autorité des Marchés Financiers implements CSRD-aligned disclosure frameworks that reshape transaction documentation standards. Notary verification protocols under national anti-money laundering regulations extend marketing periods for commercial assets.
Spain
Coastal regeneration zones and secondary cities including Valencia and Málaga present white space for residential valuation expansion as interest rate sensitivity reshapes buyer affordability thresholds. The General Directorate for the Regulation of Gambling enforces consumer protection standards affecting property marketing practices. Barcelona maintains commercial advisory concentration through mixed-use development and hospitality asset specialization.
Netherlands
Randstad freight networks generate industrial asset advisory demand as distribution occupiers expand manufacturing footprints around Rotterdam and Amsterdam port complexes. The Dutch Authority for the Financial Markets supervises investment fund structures affecting institutional capital deployment timelines. Eindhoven's technology corridor sustains specialized leasing services for R&D facility requirements.
Europe Real Estate Brokerage Market Competitive Landscape
Premium-margin players sit above commodity-margin players across advisory complexity tiers, with trophy asset and technical repositioning specialists commanding dedicated fee structures while standardized transaction processors face platform disintermediation. The market structure concentrates around pan-European investment platforms, specialized residential networks, and technology-integrated occupier service providers. Three archetypes dominate: cross-border capital deployment advisors, rural and prime residential specialists, and corporate lease administration unbundlers. Competitive moves center on PropTech integration for throughput expansion and ESG competency development for regulatory compliance differentiation.
Within the pan-European platform tier, CBRE Group and JLL anchor institutional advisory capacity through investment matching and occupier service integration, while Savills occupies a position exemplifying specialized residential network resilience against digitization pressure. These entities represent the structural bifurcation between automated transaction processing and high-touch technical advisory that defines current competitive positioning.
| Leading Market Players |
|---|
| CBRE Group |
| Jones Lang LaSalle (JLL) |
| Savills |
| Knight Frank |
| BNP Paribas Real Estate |
| Cushman & Wakefield |
| Colliers International |
| Engel & Völkers |
| RE/MAX Europe |
| Others |
Pricing and Supply Chain Analysis
PropTech integration across automated valuation engines and digital twin platforms is compressing due diligence labor costs while concentrating advisory value toward ESG-technical specialists. This technology shift simultaneously erodes commission structures on standardized residential transactions and expands fee pools for repositioning expertise tied to EU Green Deal compliance.
Pricing Analysis
Outcome-linked fee structures anchor advisory pricing to transaction completion and asset performance benchmarks rather than percentage-based commissions. Three-tier pricing stratifies across trophy asset mandates, mid-market standardized deals, and automated platform services. Commission compression runs through residential and small commercial tiers as digital platforms disintermediate traditional brokerage functions. Institutional investors show lowest price sensitivity due to fiduciary obligations and mandate complexity, while individual buyers in secondary markets exhibit highest elasticity.
Supply Chain Analysis
Regional distribution of brokerage talent clusters through London, Paris, and Frankfurt as hub nodes with satellite coverage in Madrid, Amsterdam, and Milan. Advisory capacity draws from licensed professional pools, PropTech development ecosystems, and institutional investor relationship networks. Single-source vulnerability concentrates in ESG-technical expertise as CSRD disclosure mandates outpace qualified broker supply. Distribution runs through pan-European platform partnerships, specialized boutique networks, and direct corporate occupier contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Green Deal building performance standards and CSRD disclosure mandates erect regulatory moats favoring brokers with certified ESG-technical capabilities.
For Market Incumbents: Acquire specialized life sciences and logistics advisory teams to consolidate premium fee pools. Defensive positioning requires backward integration into PropTech valuation platforms to capture automated transaction volume. Threat of platform disintermediation in residential tiers demands channel control through exclusive data partnerships. For New Entrants and Emerging Players: Capture white space in Spain's coastal regeneration zones and secondary city residential recovery markets. Underserved valuation demand in Portuguese urban densification corridors presents penetrable entry points. Go-to-market positioning should lead with EU Green Deal technical advisory bundles rather than commoditized transaction support. For Investors and Strategic Acquirers: Exit pathways concentrate in platform roll-ups of ESG-certified boutique advisors. Long-term viability favors firms with captive energy performance contracting expertise and institutional capital deployment relationships. Monitor CSRD enforcement intensity across France and Germany as inflection indicator for advisory value migration.| Strategic Initiative | Industry Significance |
|---|---|
| ESG-Technical Certification Investment | CSRD-aligned disclosure capabilities differentiate advisory mandates in France and Germany. |
| PropTech Platform Integration | Automated valuation engines compress residential transaction timelines across Spain and Poland. |
| Life Sciences Specialization Acquisition | Laboratory facility expertise commands premium fees in Lyon and Netherlands corridors. |
| Logistics Corridor Network Expansion | Rhine-Ruhr and Randstad freight nodes concentrate industrial advisory demand. |
| Corporate Lease Administration Unbundling | Hybrid work restructuring creates specialized mandate opportunities in UK and Netherlands. |
Research Methodology
Regulatory filings, pan-European trade association reports, and national property transaction databases formed the secondary backbone of this analysis. Primary interviews with investment advisory directors, lease administration officers, ESG compliance leads, and PropTech platform developers triangulated against bottom-up transaction volume estimates and top-down macroeconomic indicators.
Historical trendline analysis of commission structures and advisory fee pools informed projection modeling across the analysis window. Segmentation dimensions encompassed service type specialization, customer sophistication tier, property complexity category, and transaction scale band. CAGRs derived from regression analysis of capital deployment velocity, regulatory implementation timelines, and technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interest rate trajectories, CSRD enforcement calibration, and PropTech platform consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
Warehousing Services Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Green Lease Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Thailand Real Estate Market