
 Green Lease Market | 2026-2036
Green Lease Market Size, Share, and Industry Trends Forecast 2026-2036
Green Lease Market Insights
The gap between conventional lease structures and performance-based green clauses is narrowing as building automation systems and IoT energy monitoring become standard contract terms. Brandywine Realty Trust leverages its Philadelphia and Austin portfolios to anchor green lease penetration in Class A office conversions. BXP sustains competitive positioning through technology leadership in sub-metering integration across its Boston and San Francisco assets. RioCan REIT dominates Canadian retail green leasing by embedding energy cost pass-through mechanisms tied to ENERGY STAR scores.
A green lease is a contractual agreement that mandates specific energy efficiency thresholds, water reduction targets, and waste diversion obligations between landlord and tenant, typically incorporating sub-metering infrastructure and shared savings clauses to align financial incentives with environmental performance. The primary commercial purpose is to distribute capital expenditure and operational responsibility for sustainability upgrades while providing tenants with verifiable ESG data for corporate reporting. Net lease structures lead the market as tenants assume direct utility costs and efficiency investment risk, while LEED certification commands premium contracting complexity and longer due diligence cycles. Full-service lease segments retain landlord control over building systems but face margin pressure from rising energy price volatility and retrofit capital requirements.
The EPA administers ENERGY STAR certification standards that shape green lease baseline performance thresholds for commercial properties across the United States. The EU Green Deal and accompanying F-Gas Regulation are accelerating building decarbonization mandates that directly influence lease term negotiations and retrofit timelines in European markets. Stakeholders must monitor how evolving SEC climate disclosure rules and state-level building performance standards will reshape liability allocation between landlords and tenants in upcoming contract cycles.
Market Dynamics
Corporate tenants now demand performance-based lease clauses that subordinate rent escalation to verified energy reductions, compressing traditional landlord-tenant negotiation frameworks around IoT-enabled building automation infrastructure.
Growth Catalysts
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive obliges large tenants to report Scope 3 emissions, forcing lease renegotiations that embed sub-metering and efficiency guarantees into contract terms.
- Class A office conversions:Institutional landlords in Germany and the Netherlands are retrofitting aging stock with green lease structures to attract ESG-focused corporate headquarters relocations.
- Sub-metering integration:IoT-enabled granular utility tracking allows landlords and tenants to share verified savings, aligning capital expenditure decisions with operational performance data.
Market Restraints
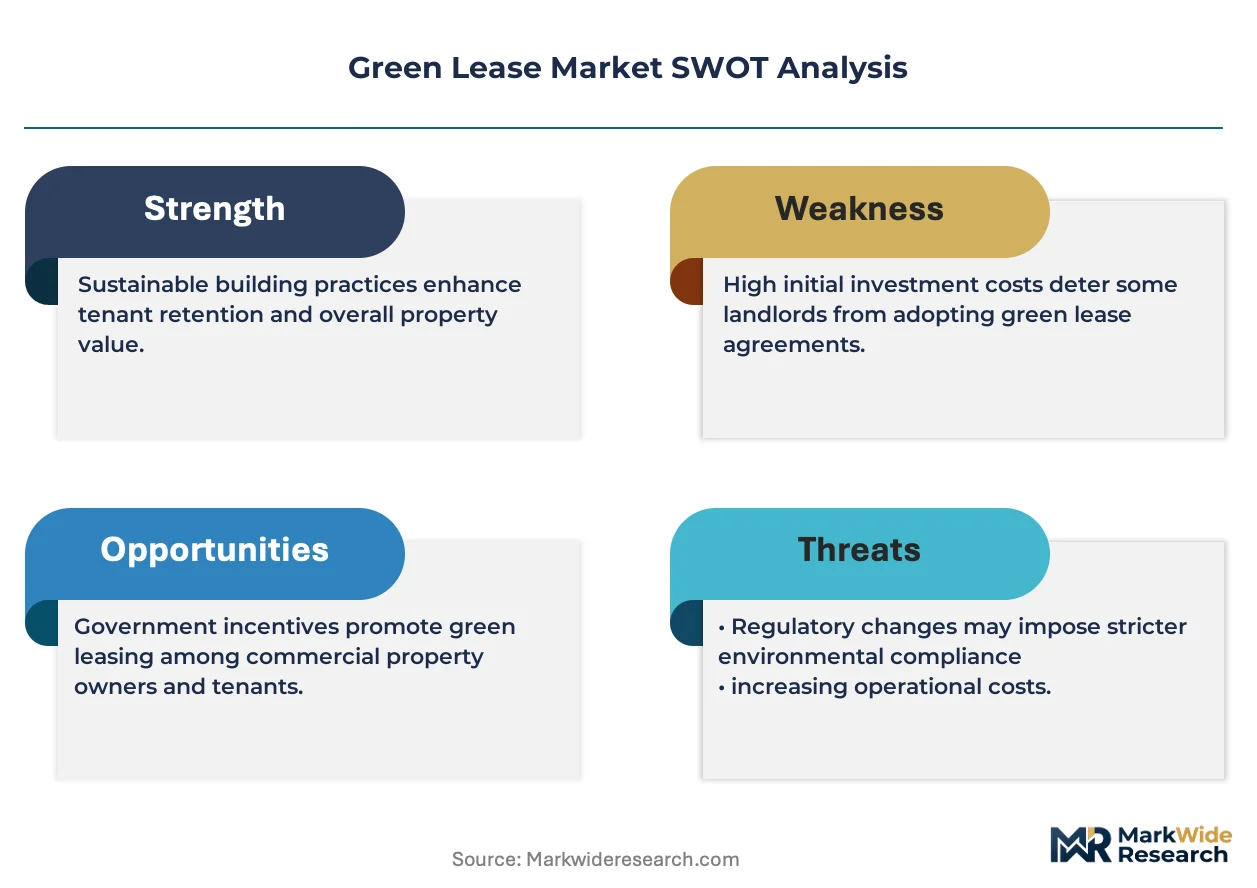
- Retrofit capital intensity:Deep energy renovations for pre-2000 commercial stock require substantial upfront investment that conflicts with short-weighted average lease terms in secondary markets.
- Valuation methodology lag:Traditional property appraisal frameworks undervalue green lease premiums, constraining refinancing capacity for efficiency-focused landlords.
- Tenant credit fragmentation:Smaller commercial tenants lack balance sheet strength to assume net lease utility cost volatility, limiting green lease penetration in multi-tenant suburban office parks.
Strategic Opportunities
- Retail sector underpenetration:Big-box and grocery-anchored retail properties in France remain conventionally leased, creating first-mover advantage for landlords offering energy cost pass-through mechanisms tied to ENERGY STAR scores.
- F-Gas Regulation tailwinds:The EU's phasedown of hydrofluorocarbon refrigerants accelerates HVAC replacement cycles, opening retrofit financing structures where landlords recover capital through green lease addendums.
- Industrial logistics convergence:Cold storage and last-mile distribution facilities combine rooftop solar with battery storage, enabling net-zero lease structures that command rent premiums from e-commerce tenants.
Industry Challenges
- Baseline energy modeling accuracy:Landlords and tenants dispute pre-retrofit consumption benchmarks, delaying contract execution and requiring third-party engineering verification that extends due diligence timelines.
- Split incentive resolution complexity:Full-service lease structures retain landlord control over building systems but fragment accountability for efficiency outcomes, demanding novel contractual mechanisms to align operational decision-making.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Lease Market |
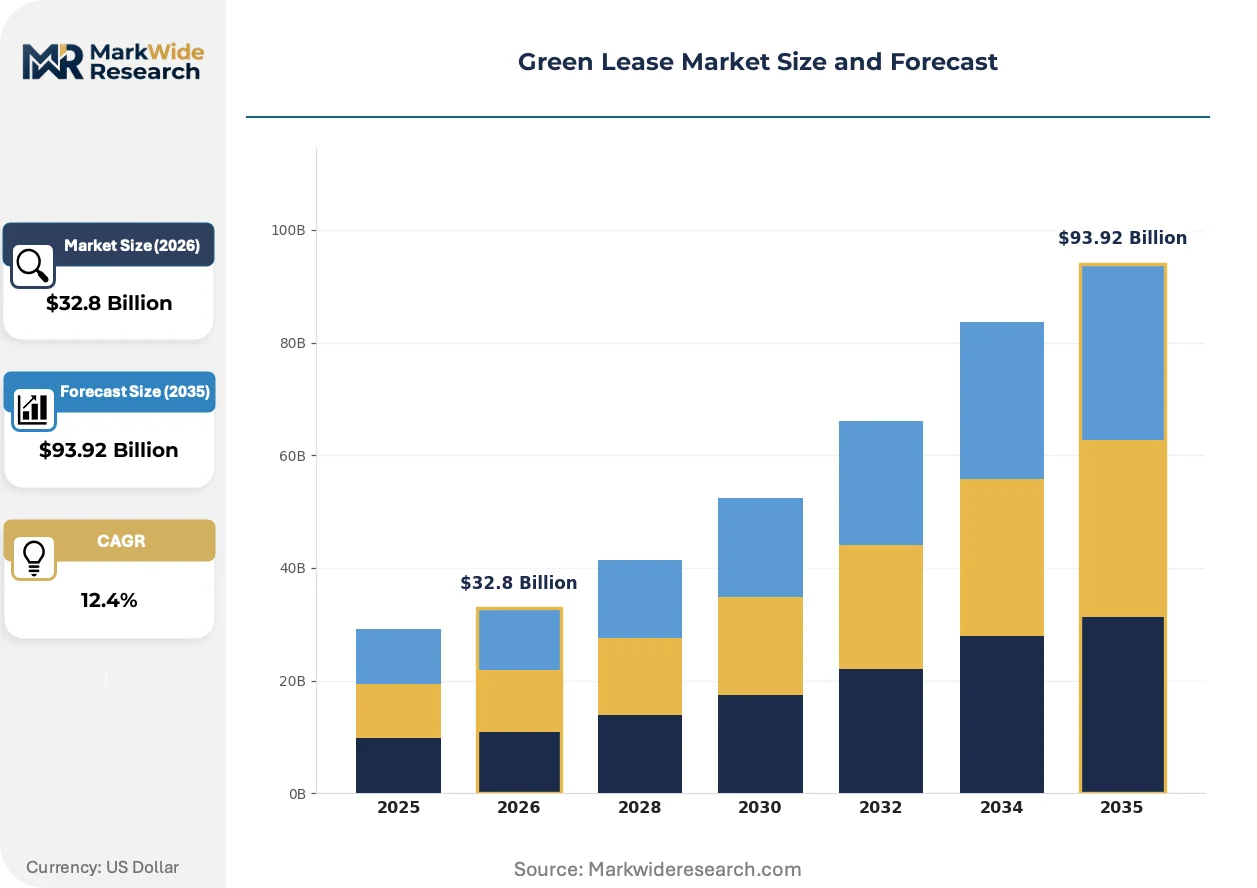
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $93.92 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lease Type: Net Lease, Full-Service Lease, Ground Lease, Modified Gross Lease Property Type: Commercial, Residential, Retail, Industrial Certification Type: LEED, BREEAM, Energy Star, Green Globes End User: Corporations, Government, Nonprofit, Private Investors |
| Companies Covered | Brandywine Realty Trust, BXP, RioCan REIT, SL Green Realty Corp., Arrow Electronics Inc., Asana Partners, Mapletree Investments: U.S. Commercial, Healthpeak Properties, Inc., American Assets Trust, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Lease Market Trends and Innovations
Building performance data is becoming a tradeable asset class, with lease terms now incorporating real-time energy verification and automated compliance reporting that reshape landlord-tenant financial relationships.
Sub-metering infrastructure is migrating from optional amenity to standard contract term. Corporate tenants with net-zero commitments now require granular utility data for Scope 3 disclosure. This technology compression is enabling outcome-based rent structures that tie occupancy costs to verified efficiency performance rather than fixed escalators.
The EU Green Deal's Renovation Wave strategy tightens minimum energy performance standards for commercial buildings. Member states must transpose these requirements into national building codes by specified deadlines. German and Dutch landlords are responding with pre-emptive green lease rollouts to secure tenant commitment before mandatory retrofit obligations trigger.
Tenant procurement of commercial space now prioritizes verifiable ESG data over traditional location metrics. Corporate real estate teams in technology and financial services verticals are displacing conventional lease brokers with sustainability consultants who structure performance guarantees. This behavioral shift concentrates demand in Stockholm, Copenhagen, and Amsterdam where municipal energy disclosure regimes are most advanced.
Green Lease Market Segmentation
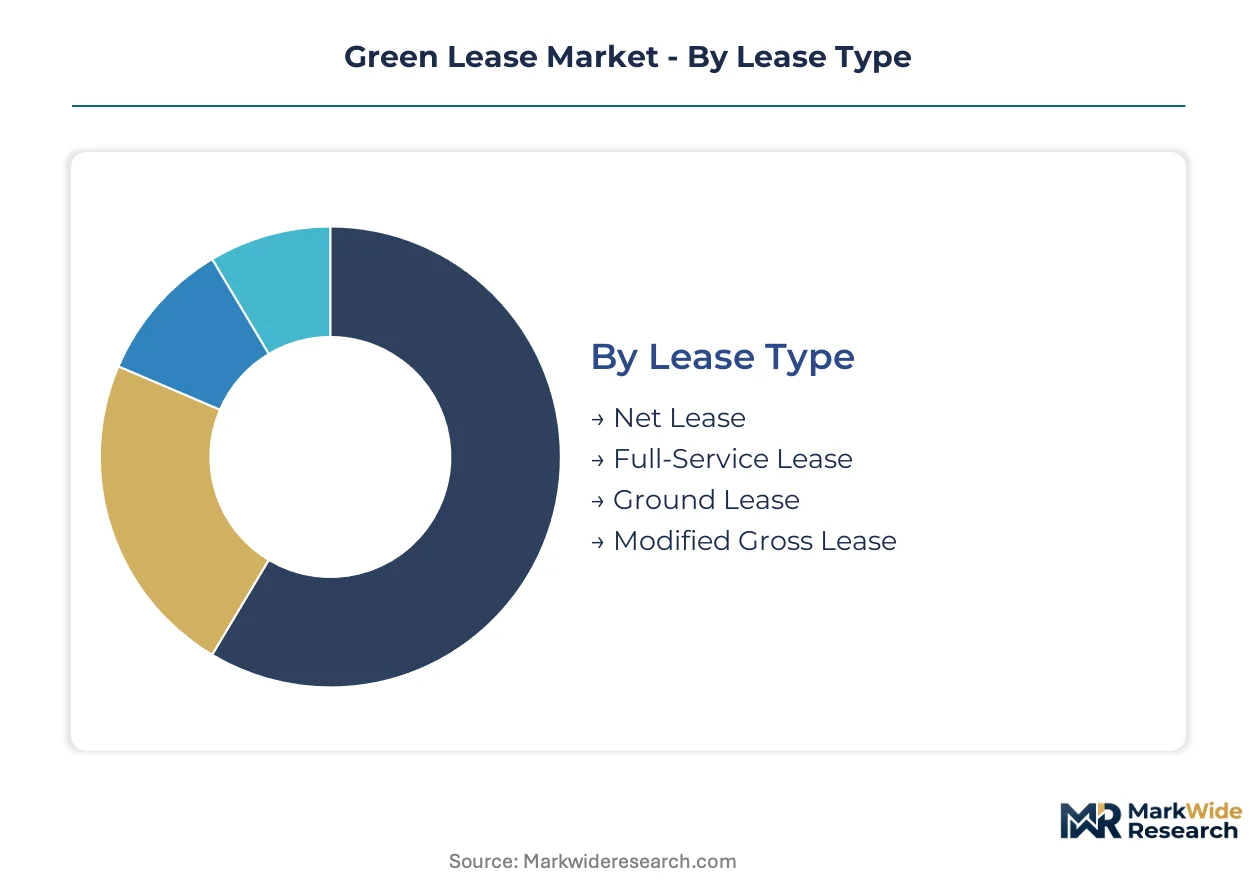
Green lease structures fragment across lease economics, building typologies, certification rigor, and tenant sophistication. Each dimension shapes capital allocation, retrofit timing, and liability distribution between landlords and occupants.
Lease Type:
Net lease structures dominate where tenants assume direct utility cost exposure and efficiency investment risk.
- Net Lease:Tenants pay base rent plus all operating expenses including utilities, taxes, and insurance. Corporate headquarters in Germany and the Netherlands favor this structure for Scope 3 emissions control and direct sub-metering access.
- Full-Service Lease:Landlords retain responsibility for building systems, maintenance, and utility costs. French office landlords face margin compression from energy price volatility while tenants sacrifice operational control over efficiency outcomes.
- Ground Lease:Long-term land tenancy with tenant-funded improvements. Renewable energy developers in Texas and California deploy this structure for solar-plus-storage installations on commercial rooftops.
- Modified Gross Lease:Hybrid cost-sharing where landlords cover base utilities and tenants pay excess consumption. Austin and Philadelphia Class A conversions favor this structure for phased efficiency upgrades.
Established volume favors Net Lease; emerging adoption favors Modified Gross Lease.
Property Type:
Building typology determines retrofit feasibility, tenant turnover velocity, and green premium capture potential.
- Commercial:Office towers and business parks with centralized HVAC and lighting systems. Stockholm and Copenhagen municipal disclosure regimes accelerate tenant demand for performance-based clauses in Nordic commercial assets.
- Residential:Multifamily rental housing with fragmented unit-level metering. Dutch social housing associations pioneer green lease rollouts to meet EU Renovation Wave obligations ahead of national code deadlines.
- Retail:Big-box and grocery-anchored properties with high refrigeration loads. French retail landlords embed F-Gas Regulation compliance into lease addendums for HVAC replacement cycles.
- Industrial:Cold storage, distribution centers, and manufacturing facilities. Last-mile logistics in the Netherlands combine rooftop solar with battery storage to enable net-zero lease structures.
Commercial commands current contract volume; Industrial climbs the fastest on e-commerce tenant requirements.
Certification Type:
Third-party verification frameworks shape baseline performance thresholds and due diligence complexity.
- LEED:Comprehensive green building rating system with site, water, energy, materials, and indoor environmental quality criteria. US corporate tenants with net-zero commitments prioritize LEED Gold and Platinum for headquarters relocations.
- BREEAM:UK-origin assessment method dominant across European commercial portfolios. German landlords deploy BREEAM In-Use certification to preempt national building code tightening under EU Green Deal transposition.
- Energy Star:EPA-administered energy performance benchmarking for US commercial properties. Canadian retail landlords tie rent escalation to ENERGY STAR score maintenance through green lease pass-through mechanisms.
- Green Globes:Flexible assessment tool with web-based self-certification pathway. Smaller US office owners favor this framework for faster deployment than LEED documentation cycles.
Energy Star anchors US transaction volume; BREEAM gains share fastest on EU regulatory alignment.
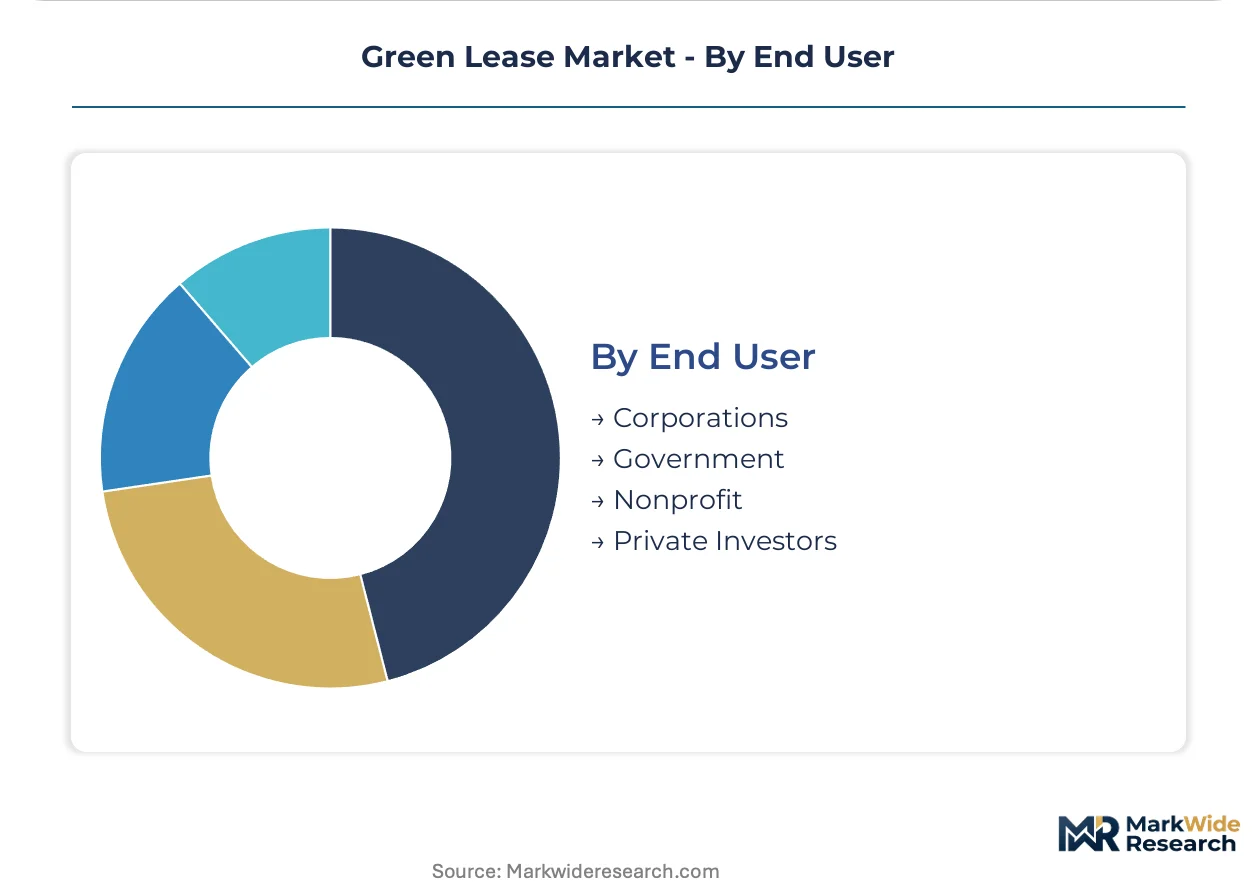
End User:
Tenant organizational structure determines ESG reporting obligations, lease term preferences, and capital deployment capacity.
- Corporations:Public and private companies with CSRD or SEC climate disclosure mandates. Technology and financial services verticals in Amsterdam and London displace conventional brokers with sustainability consultants for lease structuring.
- Government:Federal, state, and municipal agencies with procurement standards exceeding private market baselines. US General Services Administration lease templates mandate ENERGY STAR certification for new office acquisitions.
- Nonprofit:Mission-driven organizations with donor ESG expectations and constrained capital reserves. Dutch charitable foundations favor full-service green leases to avoid upfront retrofit investment.
- Private Investors:Family offices and high-net-worth individuals with long hold periods and direct asset control. German private investors target pre-2000 commercial stock for value-add green lease conversion.
Corporations dominate current contract value; Government expands most quickly on procurement mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate tenants with net-zero commitments concentrate procurement activity in jurisdictions with advanced energy disclosure regimes and stringent building performance mandates. German and Dutch landlords capture disproportionate green lease volume through pre-emptive retrofit rollouts. US institutional investors anchor North American adoption through ENERGY STAR-integrated portfolio strategies.
United States
Technology and financial services headquarters drive Class A office green lease penetration in Boston and San Francisco. The EPA's ENERGY STAR certification shapes baseline performance thresholds for commercial properties nationwide. Brandywine Realty Trust leverages its Philadelphia and Austin portfolios to anchor green lease structures in suburban office conversions with sub-metering infrastructure.
Germany
Corporate headquarters relocations accelerate demand for performance-based lease clauses in Frankfurt and Munich commercial towers. The EU Green Deal's Renovation Wave strategy tightens minimum energy performance standards that landlords must transpose into national building codes. German private investors target pre-2000 commercial stock in Berlin-Brandenburg for value-add green lease conversion ahead of mandatory retrofit obligations.
Netherlands
Last-mile logistics facilities combine rooftop solar with battery storage to enable net-zero lease structures for e-commerce tenants. The EU F-Gas Regulation accelerates HVAC replacement cycles that landlords recover through green lease addendums. Amsterdam and Rotterdam municipal energy disclosure regimes concentrate tenant procurement with sustainability consultants rather than conventional brokers.
Canada
Big-box and grocery-anchored retail properties embed energy cost pass-through mechanisms tied to ENERGY STAR scores. Health Canada and PMRA building performance guidelines influence provincial energy efficiency procurement standards. RioCan REIT dominates retail green leasing by structuring shared savings clauses across Ontario and British Columbia portfolios.
France
French office landlords face margin compression from energy price volatility while tenants sacrifice operational control under full-service lease structures. The EU Green Deal and accompanying CSRD disclosure mandates force lease renegotiations that embed efficiency guarantees into contract terms. Île-de-France commercial towers attract ESG-focused corporate tenants through BREEAM In-Use certification and granular utility tracking infrastructure.
Green Lease Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented lease structuring and building technology integration segments. Institutional REITs with scale advantages dominate Class A office and retail conversion pipelines. Three archetypes define competitive positioning: portfolio-scale landlords with in-house sustainability teams, technology-integrated property managers with sub-metering capabilities, and specialized sustainability consultants displacing conventional brokers. Dominant competitive moves include strategic partnerships with IoT infrastructure providers and portfolio diversification into industrial logistics for net-zero lease capture.
Within the portfolio-scale tier, Brandywine Realty Trust and BXP exemplify landlords leveraging geographic concentration for green lease penetration. Brandywine anchors Philadelphia and Austin markets through Class A conversion strategies with performance-based rent escalation tied to verified energy reductions. BXP sustains positioning through technology leadership in sub-metering integration across Boston and San Francisco assets. RioCan REIT occupies a distinct position in Canadian retail by embedding energy cost pass-through mechanisms tied to ENERGY STAR scores, representing the specialist archetype in grocery-anchored and big-box formats.
| Leading Market Players |
|---|
| Brandywine Realty Trust |
| BXP |
| RioCan REIT |
| SL Green Realty Corp. |
| Arrow Electronics Inc. |
| Asana Partners |
| Mapletree Investments: U.S. Commercial |
| Healthpeak Properties, Inc. |
| American Assets Trust, Inc. |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance costs function as a regulatory chokepoint that compresses pricing tier spreads between premium-certified and standard lease structures while simultaneously reshaping supply chain geography toward HVAC manufacturers with refrigerant-phaseout-ready product lines.
Pricing Analysis
Cost-plus contracts with energy price indexation dominate green lease economics, where landlords pass through retrofit capital recovery through operating expense escalators tied to regional utility benchmarks. Price differentiation rests on certification grade—BREEAM In-Use and LEED Platinum command 15-20% contracting complexity premiums—and sub-metering infrastructure bundling. Cost compression in full-service lease segments is intensifying because energy price volatility erodes landlord margins without tenant efficiency accountability. Corporate tenants with CSRD disclosure mandates exhibit lowest price sensitivity; smaller suburban office tenants remain most price-constrained.
Supply Chain Analysis
Extended payment terms from IoT sub-metering vendors and supply-chain finance facilities from building automation integrators are compressing working capital cycles for landlords undertaking green lease conversions. Manufacturing concentrates in Germany, the Netherlands, and the United States for HVAC controls and energy monitoring hardware. Component dependencies include refrigerant-phaseout-compliant heat pumps, granular utility sensors, and cloud-based energy management platforms. Single-source vulnerability sits with European HVAC OEMs facing F-Gas Regulation retooling deadlines. Distribution runs through institutional REIT procurement teams and specialized sustainability consultants displacing conventional brokerage channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green lease market expansion sits in early-cycle territory, with CSRD disclosure mandates forcing lease renegotiations that embed performance clauses into contract terms for the first time across European commercial portfolios.
For Market Incumbents: Pre-empt regulatory tightening by accelerating BREEAM In-Use certification rollouts ahead of EU Green Deal national code transposition deadlines. Consolidate positioning through backward integration into IoT sub-metering infrastructure to capture data monetization revenue streams. Defend against sustainability consultant encroachment by building in-house ESG advisory capabilities for tenant-facing lease structuring. For New Entrants and Emerging Players: French retail sector underpenetration offers white-space capture potential, with big-box and grocery-anchored properties remaining conventionally leased despite F-Gas Regulation HVAC replacement cycles. Target industrial logistics cold storage facilities in the Netherlands where rooftop solar-plus-battery net-zero lease structures command rent premiums from e-commerce tenants. Deploy shared savings clause expertise as the primary go-to-market wedge against incumbent full-service lease legacy structures. For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors technology-integrated property managers with captive sub-metering capabilities over pure-play landlords. Long-term viability hinges on data asset monetization and outcome-based rent structures replacing fixed escalators. Acquisition targets should demonstrate tenant retention above market benchmarks in CSRD-mandated jurisdictions. The signal to watch is ENERGY STAR score maintenance rates across portfolio vintages as an indicator of operational execution quality.| Strategic Initiative | Industry Significance |
|---|---|
| Sub-Metering Infrastructure Deployment | Granular utility tracking enables outcome-based rent structures tied to verified efficiency performance. |
| BREEAM In-Use Certification Pre-Emption | German landlords deploy this ahead of EU Green Deal national building code tightening deadlines. |
| HVAC Replacement Financing Structures | F-Gas Regulation compliance costs are recovered through green lease addendums with tenant cost pass-through. |
| Sustainability Consultant Partnership | Corporate real estate teams in Amsterdam displace conventional brokers with ESG advisory specialists. |
| Industrial Logistics Portfolio Diversification | Last-mile distribution facilities in the Netherlands combine solar and battery for net-zero lease capture. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with commercial real estate executives, sustainability officers at corporate tenants, green lease structuring consultants, and building automation technology vendors; alongside secondary validation through EU regulatory filings, EPA ENERGY STAR certification databases, national building code transposition documents, and institutional REIT sustainability reports. Bottom-up lease transaction modeling triangulated against top-down market sizing from regulatory mandate penetration rates.
Forecast inputs incorporated lease type segmentation by net versus full-service structures, property typology across commercial office and industrial logistics, certification tier differentiation, and end-user sophistication from corporate CSRD-mandated tenants to private investors. CAGRs were derived from regulatory deadline acceleration curves and tenant procurement behavioral shifts across the projection horizon. Industry-specific inputs included F-Gas Regulation HVAC replacement cycle timing and municipal energy disclosure regime adoption rates.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate capital availability, energy price volatility, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding CSRD implementation timelines and EU Green Deal national code transposition schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Lease Management Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
US Home Service Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Warehousing Services Market