
 Warehousing Services Market | 2026-2036
Warehousing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Warehousing Services Market Insights
Third-party logistics providers across North America and Asia-Pacific is realigning capacity toward automated fulfillment centers to match e-commerce velocity. Amazon.com leverages proprietary warehouse management systems to control last-mile density. DHL Supply Chain anchors European contract warehousing through pharmaceutical and automotive vertical specialization. GXO Logistics differentiates via robotics integration and AI-driven labor optimization in multi-client facilities.
Warehousing services encompass the physical storage, inventory management, and value-added handling of goods within dedicated facilities, typically operating across ambient, refrigerated, or climate-controlled environments with racking densities of 30-50 feet clear height and throughput measured in pallet positions per hour. These services enable supply chain continuity by buffering production against demand variability and consolidating distribution flows. Contract warehousing captures stable margin pools through long-term dedicated agreements with manufacturing and retail clients, while automated warehousing represents the fastest-growing warehouse type as capital expenditure shifts toward autonomous mobile robots and goods-to-person systems. Climate-controlled facilities command premium pricing due to stringent pharmaceutical and food safety requirements.
FDA regulations on pharmaceutical traceability, OSHA warehouse safety standards, and EPA refrigerant management rules under the AIM Act collectively shape facility design, worker training protocols, and cold chain infrastructure investment across the United States. The EU Green Deal and CSRD disclosure requirements are extending carbon accounting obligations to logistics real estate and transport operations in Europe. Stakeholders must monitor how automation capital cycles and energy efficiency mandates reshape facility economics and tenant requirements across major logistics corridors.
Market Dynamics
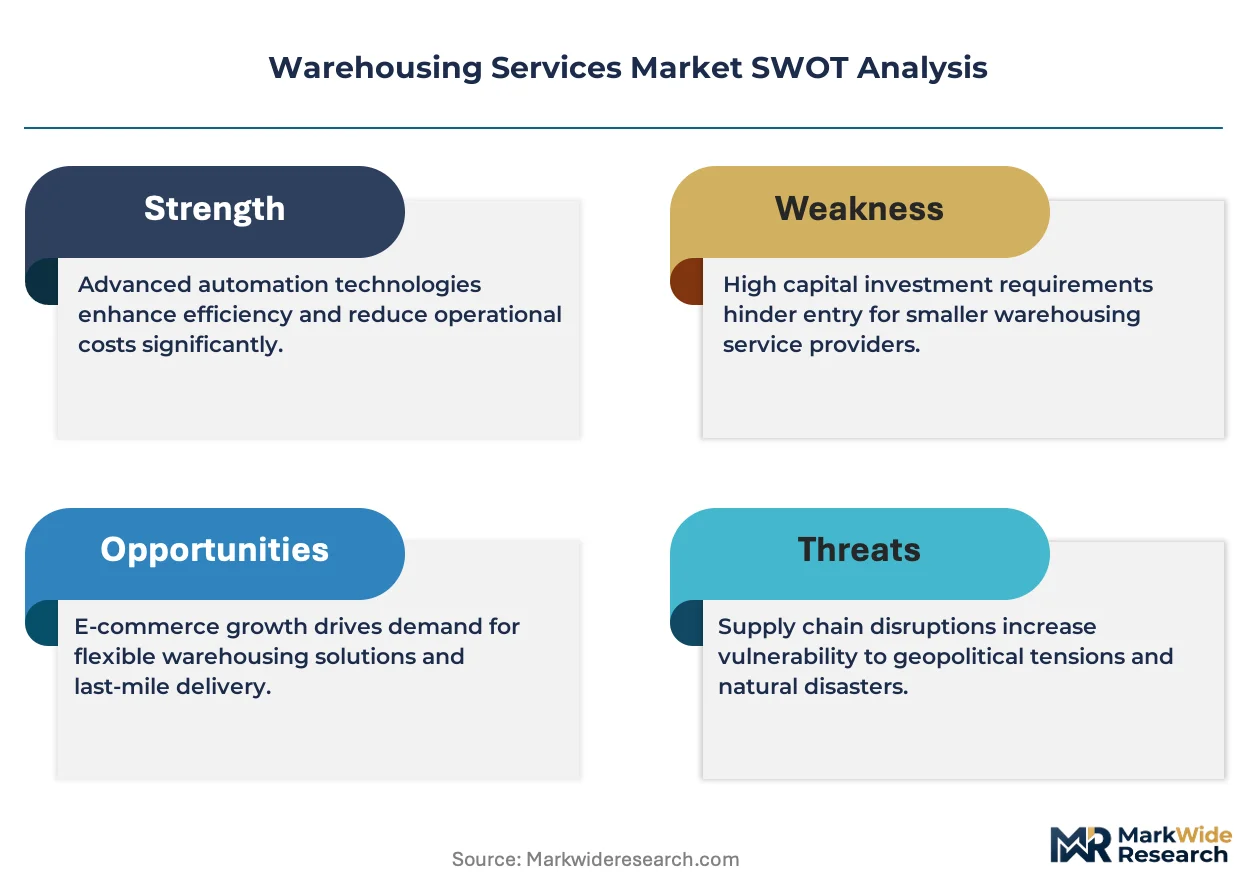
Automation capital cycles and energy efficiency mandates are compressing facility economics across major logistics corridors, forcing asset owners to rebalance racking density against robotics integration costs.
Growth Catalysts
- EU Green Deal carbon accounting:Logistics real estate operators in Germany and the Netherlands are retrofitting facilities to meet CSRD disclosure requirements, accelerating demand for climate-controlled warehousing with energy-efficient refrigeration systems.
- Pharmaceutical cold chain expansion:FDA traceability regulations under the Drug Supply Chain Security Act are mandating serialized inventory tracking, driving investment in automated pharmaceutical storage facilities across the United States.
- Robotics integration:Autonomous mobile robots and goods-to-person systems are expanding throughput capacity in multi-client fulfillment centers, enabling third-party logistics providers to handle higher SKU velocity without proportional labor expansion.
Market Restraints
- Steel and concrete input volatility:Warehouse construction costs fluctuate with regional commodity pricing, squeezing development margins for speculative build-to-suit facilities in high-demand corridors.
- Refrigerant phase-down requirements:EPA AIM Act restrictions on hydrofluorocarbon refrigerants are forcing cold storage operators to retrofit or replace cooling infrastructure, creating capital deployment friction for aging facilities.
- Labor availability constraints:Material handling equipment operators and certified cold chain technicians remain scarce in dense logistics clusters, limiting operational ramp speed for new facility openings.
Strategic Opportunities
- India contract warehousing penetration:PLI scheme incentives for manufacturing localization are creating demand for dedicated storage facilities near automotive and electronics production zones, with limited established third-party capacity.
- AI-driven labor optimization:Machine vision and predictive analytics convergence is enabling dynamic slotting and pick-path optimization, reducing fulfillment cost per unit in high-velocity e-commerce operations.
- Last-mile micro-fulfillment:Urban infill locations with sub-50,000 square foot footprints are capturing grocery and consumer electronics fulfillment demand, bypassing traditional regional distribution center models.
Industry Challenges
- Automation technician scarcity:Maintenance and programming expertise for autonomous mobile robot fleets and warehouse management system integration remains concentrated among specialized integrators, creating operational dependency risks.
- Legacy WMS migration friction:Multi-decade-old inventory management platforms in established facilities resist seamless integration with modern robotics control systems, complicating phased automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehousing Services Market |
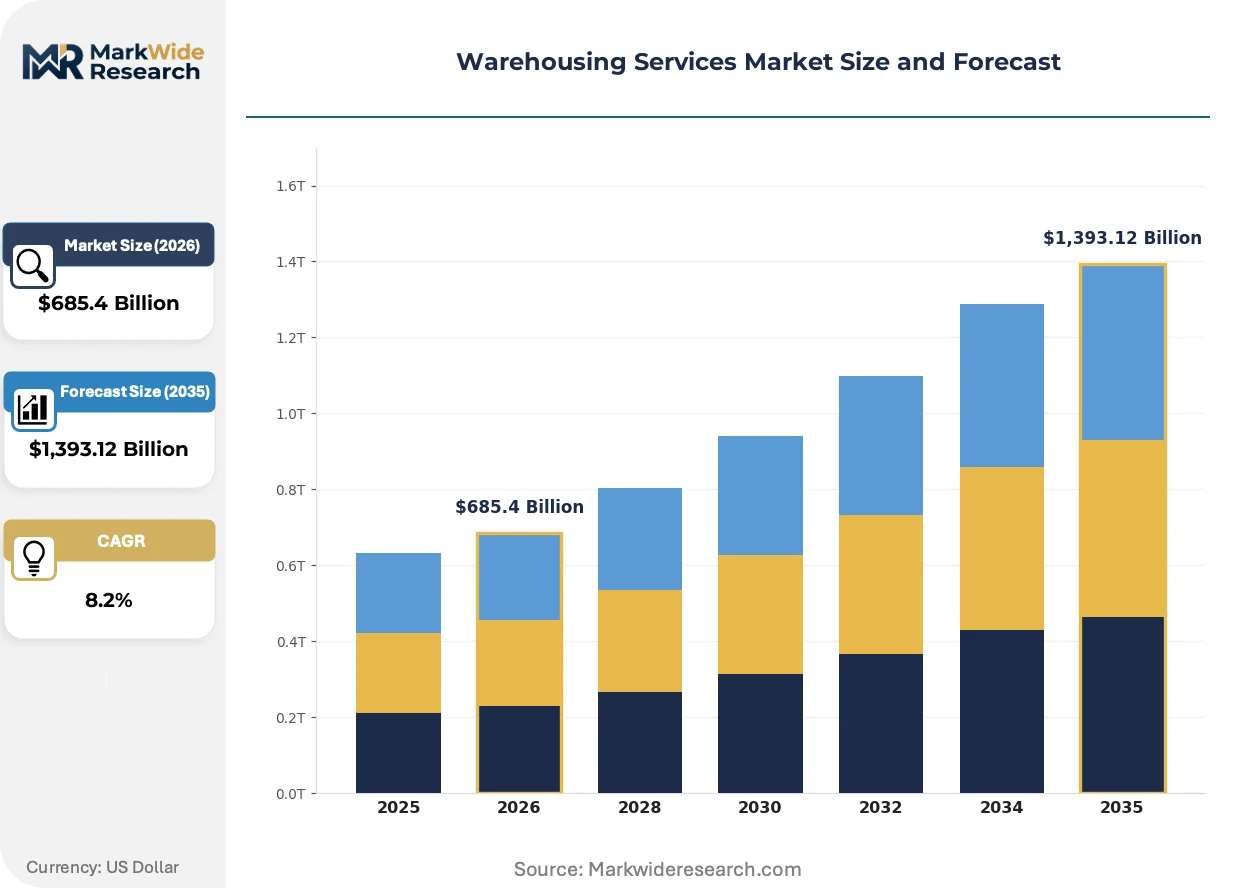
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,393.12 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Warehousing, Contract Warehousing, Dedicated Warehousing, Distribution Services Warehouse Type: Bulk Storage, Climate-Controlled, Automated Warehousing, Cross-Docking End User: E-commerce, Retail, Manufacturing, Automotive Technology: Warehouse Management Systems, RFID, Automation Technology, IoT Solutions |
| Companies Covered | Amazon.com, DHL Supply Chain, GXO Logistics, Nippon Express, Lineage Logistics, GEODIS, Kuehne+Nagel, XPO Logistics, Americold Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehousing Services Market Trends and Innovations
Operational technology convergence is rewriting facility design standards, with hardware-software integration replacing siloed equipment procurement as the dominant capital allocation logic.
Autonomous mobile robots are expanding into ambient and chilled warehouse environments, handling case picking and pallet transport functions previously executed by forklift operators. Pharmaceutical distributors and grocery retailers are deploying these systems at accelerated pace to compress order cycle times. The technology is expanding into mid-market third-party logistics facilities that previously lacked capital scale for automation, democratizing throughput advantages once concentrated at largest operators.
EPA refrigerant management rules under the AIM Act are mandating leak detection systems and phased HFC reduction schedules for cold storage facilities. Industrial consequence includes accelerated capital obsolescence for ammonia and legacy synthetic refrigeration plants. Pharmaceutical and frozen food verticals in the United States are responding with facility renovation timelines compressed to avoid regulatory non-compliance penalties.
Buyer consolidation among omnichannel retailers is compressing contract warehousing negotiation cycles, with annual rate revisions replacing multi-year fixed agreements. Regional grocery chains and direct-to-consumer brands are displacing traditional replenishment models with demand-driven micro-fulfillment networks. This pattern is most visible in Germany and the United Kingdom, where urban logistics real estate commands rental premiums against regional distribution alternatives.
Warehousing Services Market Segmentation
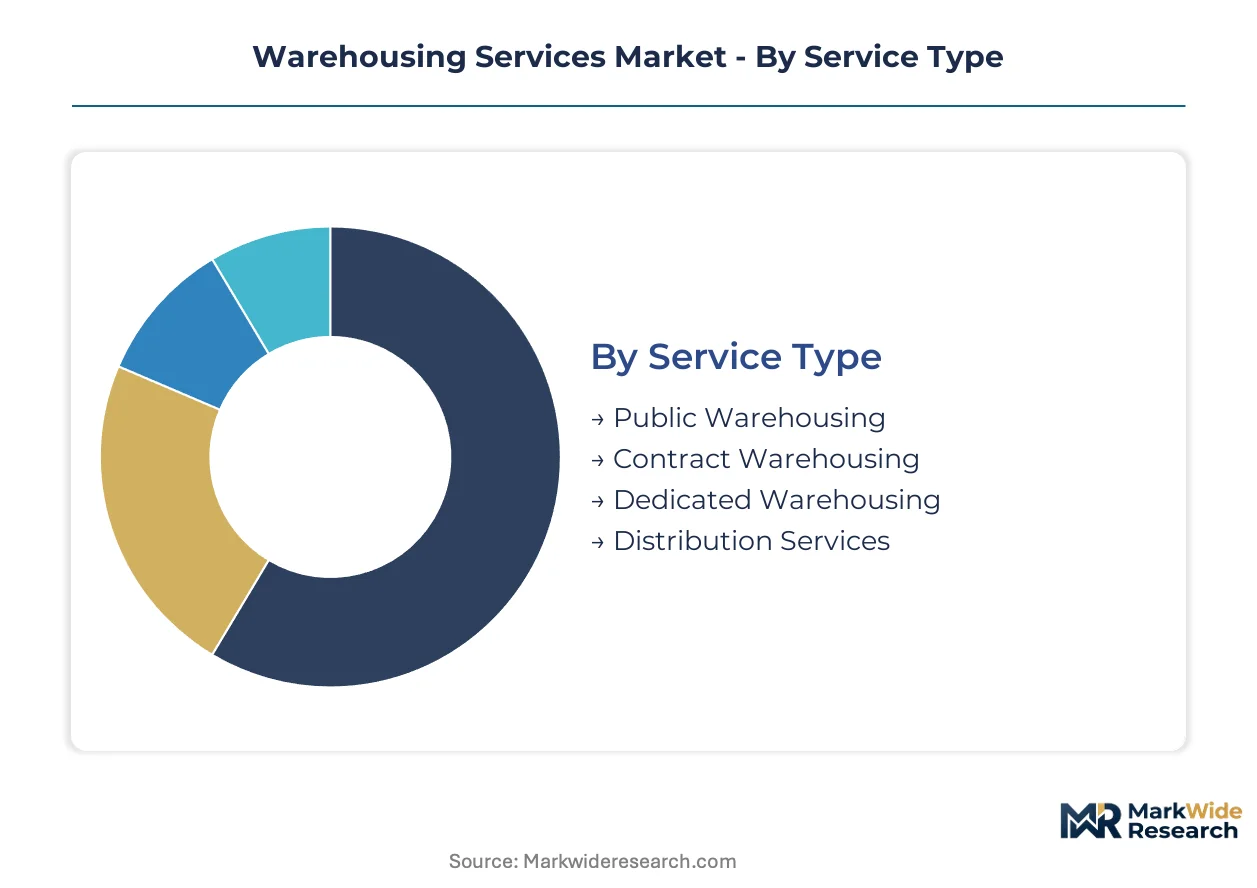
Warehousing services fragment across operational models that determine capital intensity, margin stability, and customer lock-in duration. Service type selection dictates facility ownership structures, while warehouse technology tiers separate legacy operators from automation-forward competitors. End-user verticals impose divergent throughput requirements and regulatory compliance burdens.
Service Type:
Standalone service arrangements dominate long-term supply chain planning, while embedded distribution partnerships reshape inventory velocity expectations for integrated clients.
- Contract Warehousing:Long-term dedicated agreements with single clients under fixed-rate structures provide margin stability. Automotive and pharmaceutical manufacturers in Germany and the United States anchor demand through multi-year commitments requiring specialized racking configurations and serialized inventory tracking.
- Public Warehousing:Multi-client facilities offer flexible space allocation with short-term lease structures. E-commerce sellers and seasonal retailers in China utilize these arrangements to buffer demand spikes without fixed overhead, though per-pallet pricing compresses margins during capacity gluts.
- Dedicated Warehousing:Exclusive facilities built to client specifications transfer operational control while retaining third-party management. Food and beverage distributors favor this model for allergen segregation requirements.
- Distribution Services:Value-added bundling of storage with transportation management and last-mile coordination. Omnichannel retailers in the United Kingdom deploy these integrated offerings to collapse order cycle times.
Volume placements concentrate in Contract Warehousing; the faster expansion belongs to Distribution Services.
Warehouse Type:
Cost tier separation between ambient bulk facilities and precision-controlled environments drives divergent capital deployment timelines and tenant qualification standards.
- Automated Warehousing:Autonomous mobile robots and goods-to-person systems compress pick-path distances while elevating throughput per labor hour. E-commerce fulfillment networks in the United States and China are retrofitting existing facilities or constructing greenfield sites with vertical racking densities exceeding 40 feet clear height to maximize robot deployment efficiency.
- Climate-Controlled:Refrigerated and frozen environments maintaining precise temperature bands for pharmaceutical and food safety compliance. FDA Drug Supply Chain Security Act serialization mandates and EPA AIM Act refrigerant phase-down rules are accelerating facility renovation cycles across the United States.
- Bulk Storage:Ambient racking configurations for non-perishable goods with minimal handling complexity. Commodity chemical and building materials distributors favor these low-overhead structures.
- Cross-Docking:Minimal-dwell transfer facilities consolidating inbound freight for immediate outbound dispatch. Grocery retailers in Germany utilize these nodes to bypass regional distribution center inventory holding.
Revenue concentration sits with Climate-Controlled facilities; Automated Warehousing claims the steepest expansion trajectory.
End User:
Application-specific throughput requirements and order profile complexity separate high-velocity fulfillment operations from predictable replenishment cycles.
- E-commerce:Direct-to-consumer fulfillment demanding same-day or next-day delivery windows with extreme SKU proliferation. Urban micro-fulfillment centers in the United Kingdom and Germany are displacing traditional regional distribution models for this vertical.
- Manufacturing:Production-line feeding and work-in-process buffering with just-in-time delivery constraints. Automotive suppliers in Germany and the United States require sequenced parts delivery synchronized to assembly schedules.
- Retail:Store replenishment and seasonal inventory pre-positioning for brick-and-mortar networks. Fashion and home goods chains favor flexible contract structures to accommodate promotional calendars.
- Automotive:Specialized handling for hazardous materials, oversized components, and reverse logistics for parts returns. Battery electric vehicle supply chains are creating demand for hazardous materials-certified facilities.
Facility utilization peaks with Manufacturing contracts; E-commerce is climbing the fastest.
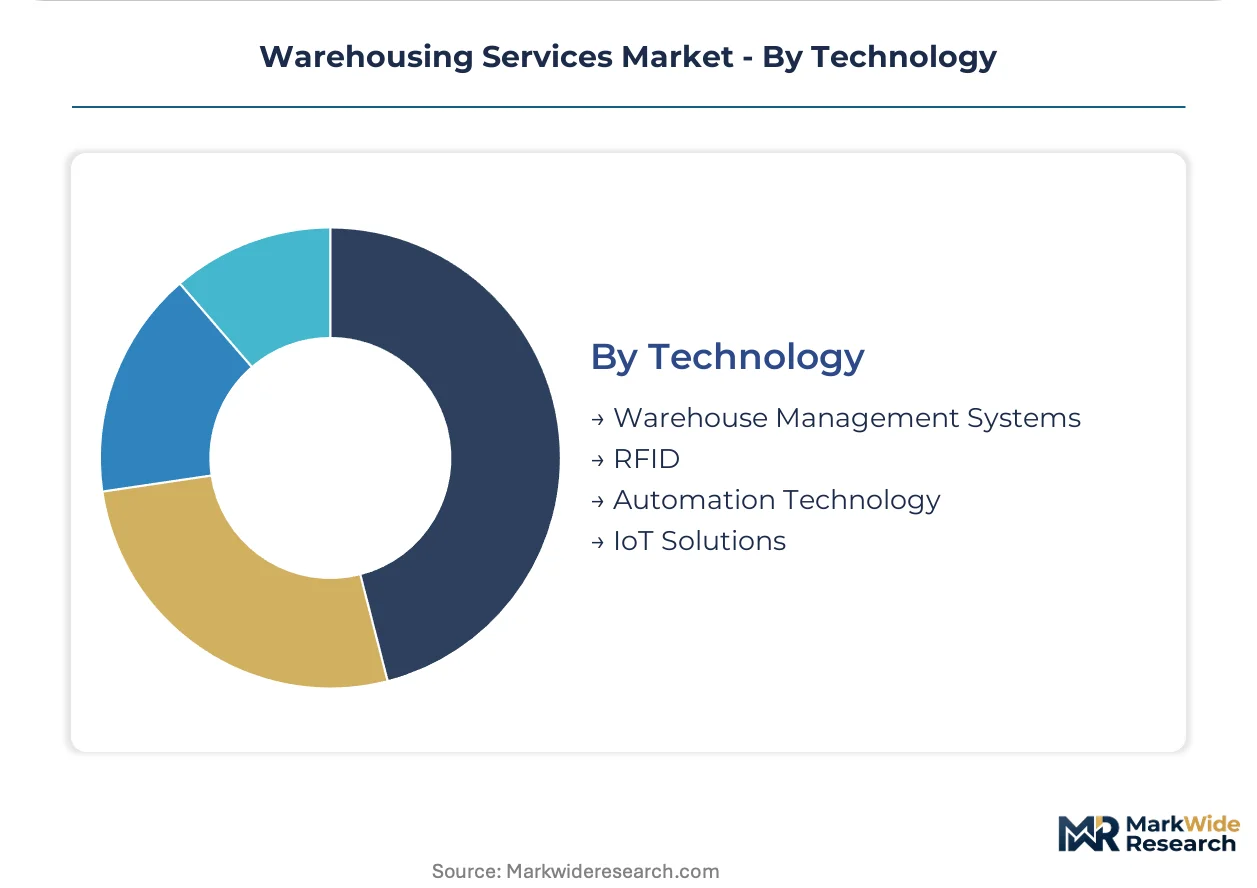
Technology:
Maturity curves separate established software platforms from emerging hardware-software convergence points reshaping capital allocation logic.
- Automation Technology:Autonomous mobile robots, automated storage and retrieval systems, and robotic piece-picking integrating with warehouse control layers. Third-party logistics providers in the United States and China are deploying these systems to handle SKU velocity expansion without proportional labor growth.
- Warehouse Management Systems:Core software platforms governing inventory tracking, labor allocation, and facility optimization. Legacy WMS migration friction complicates phased automation deployments in established multi-client facilities.
- RFID:Item-level and pallet-level radio frequency identification for real-time location tracking and cycle count automation. Pharmaceutical distributors favor serialized RFID for DSCSA compliance.
- IoT Solutions:Sensor networks monitoring equipment health, environmental conditions, and energy consumption. Cold storage operators deploy these systems to satisfy EPA leak detection mandates under AIM Act requirements.
Deployment scale favors Warehouse Management Systems; Automation Technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and concrete feedstock availability near the Great Lakes industrial corridor anchors North American warehouse development velocity. Labor pool depth and intermodal connectivity separate high-throughput markets from secondary locations.
United States
E-commerce fulfillment networks and pharmaceutical cold chain expansion drive warehouse demand. FDA Drug Supply Chain Security Act serialization mandates require specialized inventory tracking infrastructure. The Inland Empire in Southern California concentrates automated fulfillment centers serving West Coast consumer markets.
Germany
Automotive sequenced parts delivery and pharmaceutical distribution anchor contract warehousing demand. EU Green Deal CSRD disclosure requirements accelerate facility energy retrofits. The Rhine-Ruhr metropolitan region hosts multi-client logistics parks integrating rail and barge freight connections.
China
Consumer electronics manufacturing localization and cross-border e-commerce fulfillment expand warehouse footprints. SAMR warehouse safety standards and dual carbon goals shape facility design specifications. The Yangtze River Delta cluster around Shanghai dominates automated storage and retrieval system deployments.
India
PLI scheme manufacturing incentives create demand for dedicated storage near automotive and electronics production zones. BIS warehousing standards and state-level logistics policies influence facility permitting timelines. The Delhi-Mumbai Industrial Corridor attracts third-party logistics investment for contract warehousing development.
United Kingdom
Omnichannel retail consolidation and urban micro-fulfillment networks reshape last-mile logistics real estate. REACH chemical storage regulations and building safety codes govern hazardous materials facilities. The Midlands logistics triangle around Birmingham concentrates regional distribution center capacity serving national grocery and fashion retail networks.
Warehousing Services Market Competitive Landscape
Global majors compete with regional champions across automation technology deployment and vertical specialization depth. The market structures around three tiers: integrated logistics conglomerates with proprietary technology stacks, specialized cold chain operators with regulatory expertise, and technology-forward contract logistics providers. Strategic moves concentrate on robotics integration partnerships and multi-year dedicated facility agreements.
Within the integrated logistics tier, Amazon.com exemplifies captive fulfillment network scale, while DHL Supply Chain anchors European contract warehousing through pharmaceutical and automotive vertical depth. GXO Logistics occupies a position at the technology-forward end, representing the robotics integration archetype in multi-client facility management. These three entities illustrate divergent capital allocation logics: captive vertical integration, regulated vertical specialization, and automation-as-differentiation.
| Leading Market Players |
|---|
| Amazon.com |
| DHL Supply Chain |
| GXO Logistics |
| Nippon Express |
| Lineage Logistics |
| GEODIS |
| Kuehne+Nagel |
| XPO Logistics |
| Americold Logistics |
| Others |
Pricing and Supply Chain Analysis
Buyer consolidation among omnichannel retailers is compressing contract warehousing negotiation cycles, forcing asset owners to absorb automation capital costs while maintaining rate competitiveness against regional distribution alternatives.
Pricing Analysis
Service bundling separates contract warehousing from public warehousing tiers, with dedicated facilities including WMS integration and labor management while multi-client arrangements unbundle value-added services. Three-tier pricing structure across premium climate-controlled, standard automated, and economy bulk storage levels reflects certification grade and energy efficiency compliance costs. Pricing pressure stems from steel and concrete input volatility squeezing development margins for speculative facilities. Seasonal e-commerce sellers exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium rates for serialized inventory tracking infrastructure.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's dual carbon goals are reshaping equipment sourcing for automated storage and retrieval systems toward regional integrators. Warehouse construction materials draw from steel production in China, concrete supply in the United States, and refrigeration equipment manufacturing in Germany. Single-source vulnerability concentrates in autonomous mobile robot fleets from specialized integrators. Distribution runs through third-party logistics providers operating multi-client facilities with flexible capacity allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The warehousing services market functions as a cost-of-compliance arena where EPA AIM Act refrigerant phase-down rules and FDA Drug Supply Chain Security Act serialization mandates create regulatory moats favoring operators with capital reserves for facility retrofitting.
For Market Incumbents: Cement market position through accelerated climate-controlled facility renovation timelines ahead of EPA enforcement deadlines. Anchor long-term contract warehousing agreements with automotive and pharmaceutical manufacturers requiring specialized racking configurations. Threat substitution from autonomous mobile robot fleet operators demands proprietary WMS integration capabilities as defensive leverage. For New Entrants and Emerging Players: Launch via dedicated warehousing arrangements serving PLI scheme manufacturing zones in India where established third-party capacity remains limited. Target contract warehousing penetration near automotive and electronics production clusters. White-space exists in urban micro-fulfillment networks bypassing traditional regional distribution center models for grocery and consumer electronics verticals. For Investors and Strategic Acquirers: The window for entry favors technology-forward contract logistics providers with robotics integration capabilities and multi-client facility management expertise. Long-term viability centers on automation capital deployment scale and vertical specialization depth in pharmaceutical cold chain or automotive sequenced parts delivery. Watch EPA refrigerant retrofit acceleration and CSRD disclosure compliance timelines as inflection indicators for facility valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Integration Partnership | Autonomous mobile robot deployment compresses pick-path distances in e-commerce fulfillment centers across the United States. |
| Climate-Controlled Facility Retrofit | EPA AIM Act compliance drives capital redeployment toward energy-efficient refrigeration systems in pharmaceutical cold chain infrastructure. |
| Multi-Year Dedicated Agreement | Automotive manufacturers in Germany anchor contract warehousing demand through sequenced parts delivery commitments. |
| AI-Driven Labor Optimization | Machine vision convergence enables dynamic slotting in high-velocity SKU environments without proportional workforce expansion. |
| Urban Micro-Fulfillment Expansion | Sub-50,000 square foot infill locations capture grocery fulfillment demand in the United Kingdom bypassing regional distribution models. |
Research Methodology
Document review covered SEC 10-K filings, customs and trade data, and logistics real estate transaction records, complemented by interviews with third-party logistics executives, warehouse automation integrators, pharmaceutical distribution compliance officers, and cold chain facility operators. Secondary validation drew from EPA regulatory filings, EU CSRD disclosure frameworks, FDA Drug Supply Chain Security Act guidance documents, and SAMR warehouse safety standards. Bottom-up facility capacity modeling and top-down market sizing triangulated volume estimates.
Cross-referencing historical automation capital expenditure patterns against industry panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, warehouse technology tier, end-user vertical, and regional regulatory cluster. CAGRs were derived from facility throughput expansion rates and automation penetration curves. Forecast inputs incorporated e-commerce order velocity trends and pharmaceutical cold chain compliance investment cycles.
Steel and concrete commodity volatility, refrigerant phase-down enforcement acceleration, and autonomous mobile robot fleet deployment delays are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about regulatory timeline adherence and capital availability for facility retrofitting. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Global Home Services Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Green Lease Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Second-Hand Housing Trading Platform Market