
 United States Self Storage Market | 2026-2036
United States Self Storage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Self Storage Market Intelligence
Texas-based REIT development is decoupling from traditional urban density models. Public Storage sustains national footprint dominance through standardized facility formats. Extra Space Storage leverages technology-enabled access systems to differentiate in competitive submarkets. CubeSmart anchors portfolio strategy around infill locations near population corridors.
United States self storage encompasses leased individual compartments within purpose-built facilities, typically constructed with steel partitioning, roll-up doors, and concrete slab flooring designed for household goods, business inventory, or vehicle containment. Climate-controlled segments command premium rate structures due to humidity regulation and HVAC infrastructure requirements. Residential customer types generate baseline occupancy, while military and student categories provide seasonal demand elasticity. Small and medium unit sizes absorb the majority of move-in volume, though large formats capture disproportionate revenue per square foot from commercial clients.
FAA regulations govern drone-based facility security systems, while local zoning boards and municipal planning commissions dictate setback requirements and maximum building heights. OSHA standards apply to facility maintenance operations and employee safety protocols. State insurance commissioners regulate tenant protection products offered at point of lease. Stakeholders must monitor evolving municipal climate mandates that could retrofit requirements onto existing building stock.
Market Dynamics
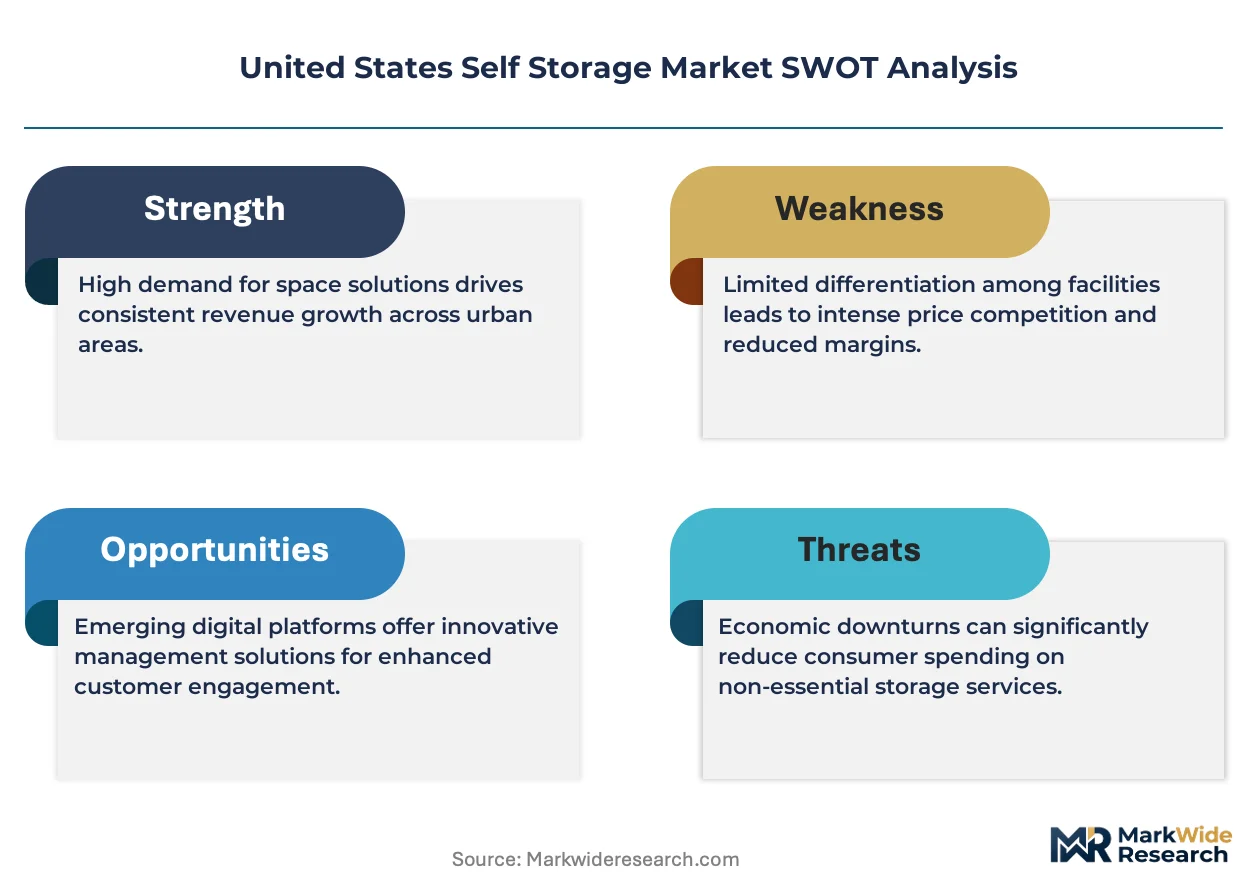
Small business inventory overflow and Sun Belt population migration are compressing residential square footage, forcing household goods into leased compartments while suburban zoning reforms accelerate facility permitting velocity.
Growth Catalysts
- Texas and Florida zoning reforms:Municipal planning commissions in these states have relaxed setback requirements and maximum building height restrictions, cutting facility approval timelines by half in major metropolitan corridors.
- Climate-controlled HVAC infrastructure:Humidity regulation systems now command premium rate structures as commercial clients seek protected environments for sensitive inventory, expanding revenue per square foot.
- Military and student seasonal elasticity:Cyclical relocation patterns from base reassignments and academic calendars create predictable demand spikes that stabilize occupancy through traditional low seasons.
Market Restraints
- Steel input cost volatility:Roll-up door and steel partitioning materials face commodity price swings that compress development margins on new facility construction.
- OSHA facility maintenance standards:Employee safety protocols for elevated maintenance operations add operational overhead and training requirements that slow expansion velocity.
- Residential square footage substitution:Accessory dwelling unit construction in some Sun Belt municipalities offers competing space solutions for household overflow.
Strategic Opportunities
- Drone-based security integration:FAA regulatory frameworks for unmanned aerial surveillance create pathways for technology-enabled facility monitoring that differentiates competitive positioning.
- Vehicle containment formats:Large unit configurations for commercial fleet storage remain underpenetrated relative to household goods saturation, offering disproportionate revenue capture potential.
- State insurance commissioner tenant protection products:Point-of-lease protection offerings regulated at state level create ancillary revenue streams with minimal incremental facility investment.
Industry Challenges
- Climate mandate retrofit timelines:Evolving municipal energy efficiency standards threaten capital requirements for existing building stock upgrades.
- Technology-enabled access integration:Legacy facility management systems face friction when interfacing with smartphone-based entry and billing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Self Storage Market |
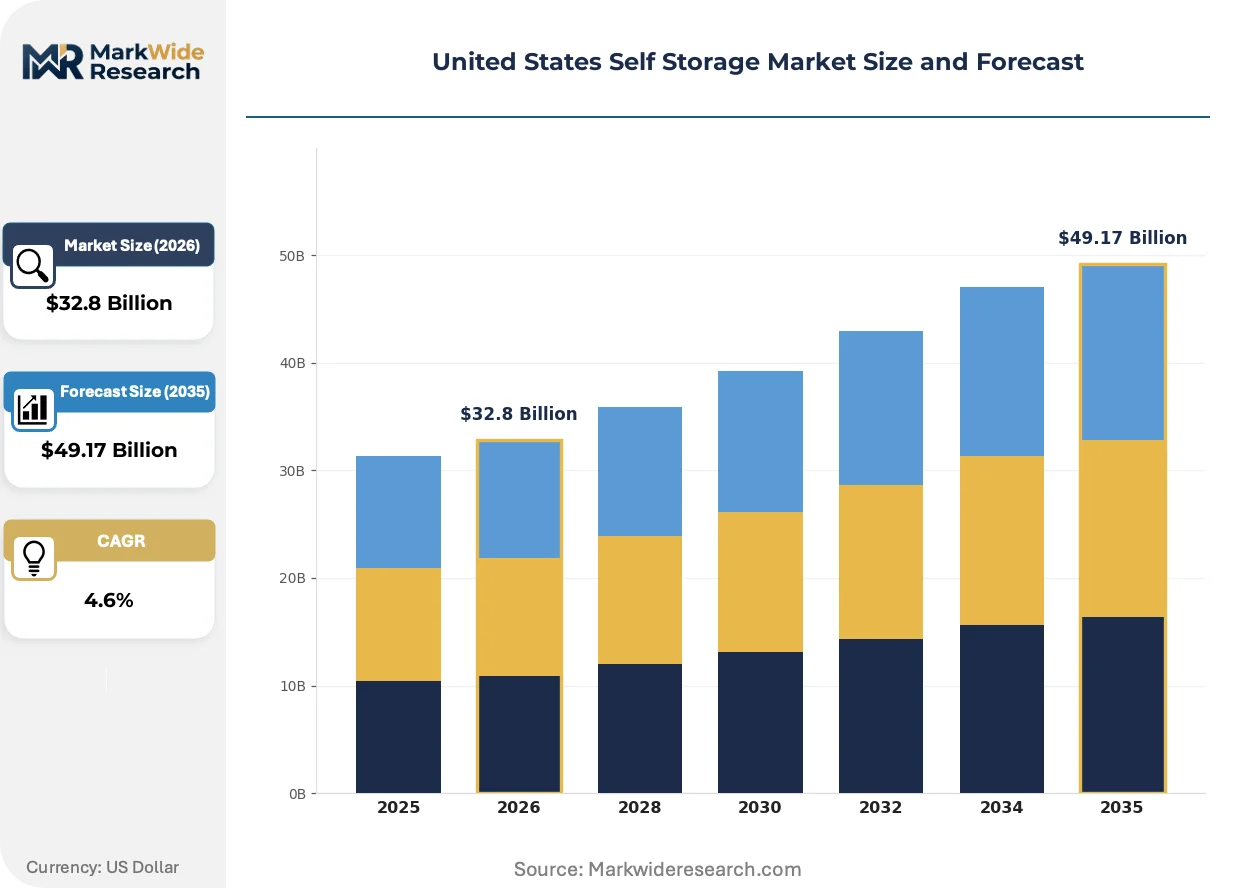
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Climate-Controlled, Drive-Up Access, Indoor, Outdoor Customer Type: Residential, Business, Student, Military Unit Size: Small, Medium, Large, Extra Large Occupancy Rate: Above 90%, 80-89%, 70-79%, Below 70% |
| Companies Covered | National Storage Affiliates, LifeStorage, Public Storage, SmartStop Self Storage, StorageMart, Extra Space Storage, CubeSmart, Absolute Storage Management, U-Haul Holding Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Self Storage Market Strategic Shifts & Innovations
Technology-enabled access systems and automated facility management platforms are compressing operational overhead while regulatory pressure on building efficiency reshapes capital deployment priorities.
Smartphone-based entry and billing platforms are consolidating tenant interaction into single-interface ecosystems. Small and medium unit renters now expect frictionless move-in and autopay functionality as baseline. Facility operators are consolidating multiple vendor relationships into unified property management stacks, reducing software licensing complexity.
OSHA standards for employee safety protocols in elevated maintenance operations are tightening inspection frequency and documentation requirements. Facility operators face expanded training mandates for boom lift and scaffolding work. Sun Belt metropolitan developments absorb the most immediate compliance cost pressure as these markets build fastest.
Commercial procurement of storage services is fragmenting across decentralized decision-makers rather than centralized facilities management. Small business owners now source units through digital marketplace comparison rather than legacy broker relationships. This pattern concentrates in Texas and Florida suburban corridors where new facility supply outpaces traditional channel control.
United States Self Storage Market Segmentation
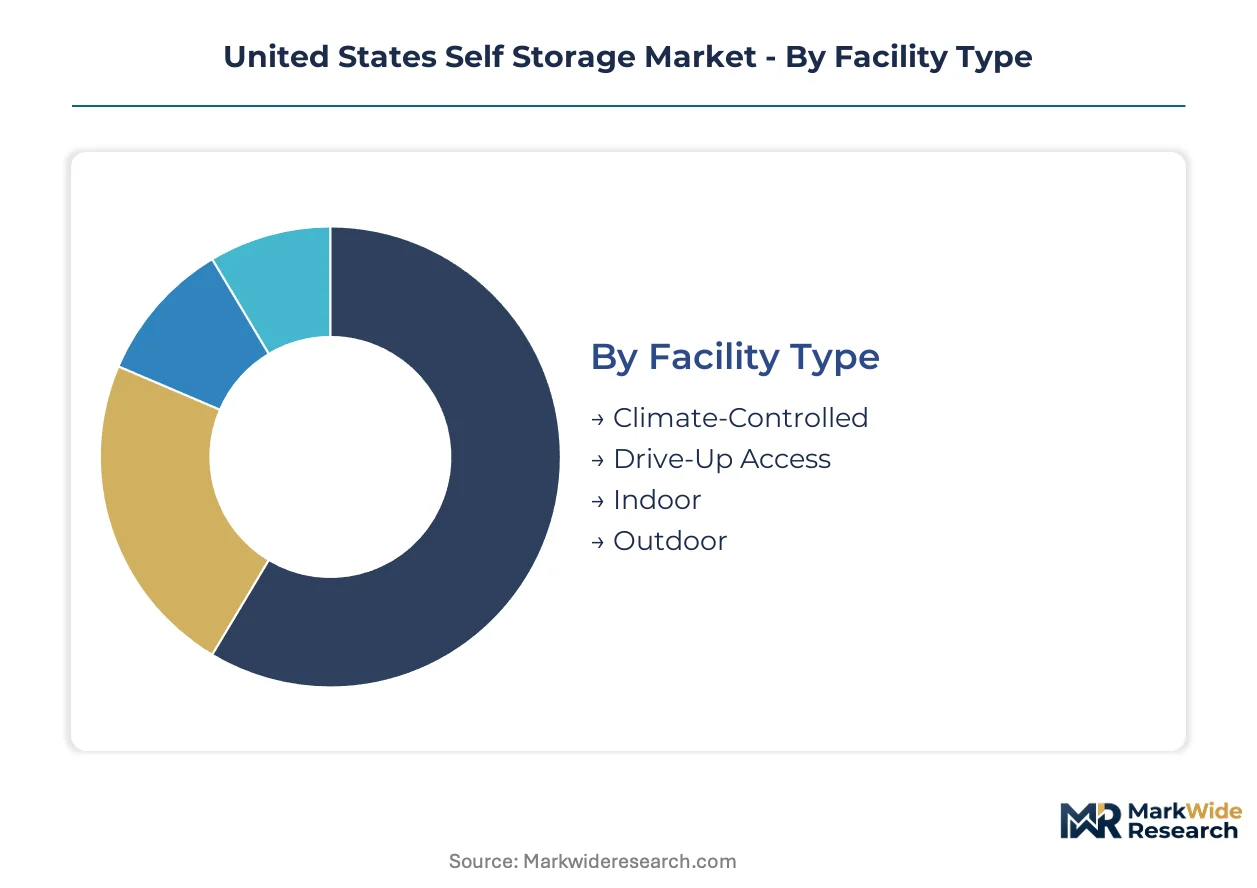
Self storage segmentation reveals how facility operators align capital deployment with distinct demand profiles and regulatory exposure. Each dimension carries different municipal compliance burdens and revenue elasticity characteristics.
Facility Type:
Climate-controlled facilities face HVAC permitting complexity under local building codes and EPA refrigerant regulations. Drive-up and outdoor formats navigate simpler zoning pathways but encounter stormwater management scrutiny.
- Climate-Controlled:Humidity regulation systems with HVAC infrastructure maintain temperature bands for sensitive inventory. Demand concentrates in Sun Belt metropolitan areas where heat damage risk drives commercial client premiums. Local building departments enforce energy efficiency compliance that extends approval timelines.
- Drive-Up Access:Ground-level roll-up door configurations enable vehicle-direct loading without corridor navigation. Suburban corridors in Texas and Florida absorb the majority of new supply as zoning reforms accelerate permitting velocity for low-rise construction.
- Indoor:Multi-level corridor facilities with elevator access and interior climate buffering. Upper Midwest markets favor this format for weather protection despite higher per-square-foot construction costs.
- Outdoor:Unenclosed vehicle and equipment storage with minimal structural overhead. Rural exurbs and agricultural zones generate baseline demand for commercial fleet containment.
Drive-Up Access sits at the top of the volume ranking, with Climate-Controlled climbing the fastest.
Customer Type:
Customer segments diverge sharply in lease duration predictability and seasonal volatility. Residential and military categories generate contrasting cash flow profiles that shape operator marketing spend allocation.
- Residential:Household goods storage during relocation, downsizing, or life transitions. Sun Belt in-migration corridors in Arizona, Nevada, and Georgia sustain occupancy through persistent square footage compression.
- Business:Small and medium enterprises storing inventory overflow, documents, and equipment. E-commerce fulfillment fragmentation across suburban Texas and Florida drives decentralized procurement patterns.
- Military:Service members requiring temporary storage during base reassignments and deployments. Cyclical demand spikes align with permanent change-of-station calendars that concentrate in San Antonio, Norfolk, and San Diego metro areas.
- Student:Academic calendar-driven storage between semesters and summer breaks. University towns with limited dormitory capacity generate predictable seasonal occupancy troughs.
Residential commands the largest revenue base, though Business applications are expanding most quickly as inventory management practices fragment.
Unit Size:
Size segmentation determines revenue per square foot and facility layout efficiency. Small formats maximize door count on constrained parcels while large configurations capture commercial yield premiums.
- Small:Locker-style compartments under 50 square feet for documents and minimal household goods. Urban infill locations near apartment concentrations absorb disproportionate move-in volume.
- Medium:Standard 5x10 to 10x10 configurations accommodating one to two rooms of furniture. This tier generates the majority of new lease signings across suburban development corridors.
- Large:10x15 to 10x20 units serving full household contents or substantial business inventory. Commercial procurement concentrates here for construction equipment and retail stock overflow.
- Extra Large:Vehicle bays and oversized compartments exceeding 300 square feet. Fleet operators and recreational vehicle owners in exurban Florida and Texas markets sustain premium rate structures.
Medium units dominate transaction volume, while Extra Large formats deliver the steepest expansion trajectory in commercial vehicle containment.
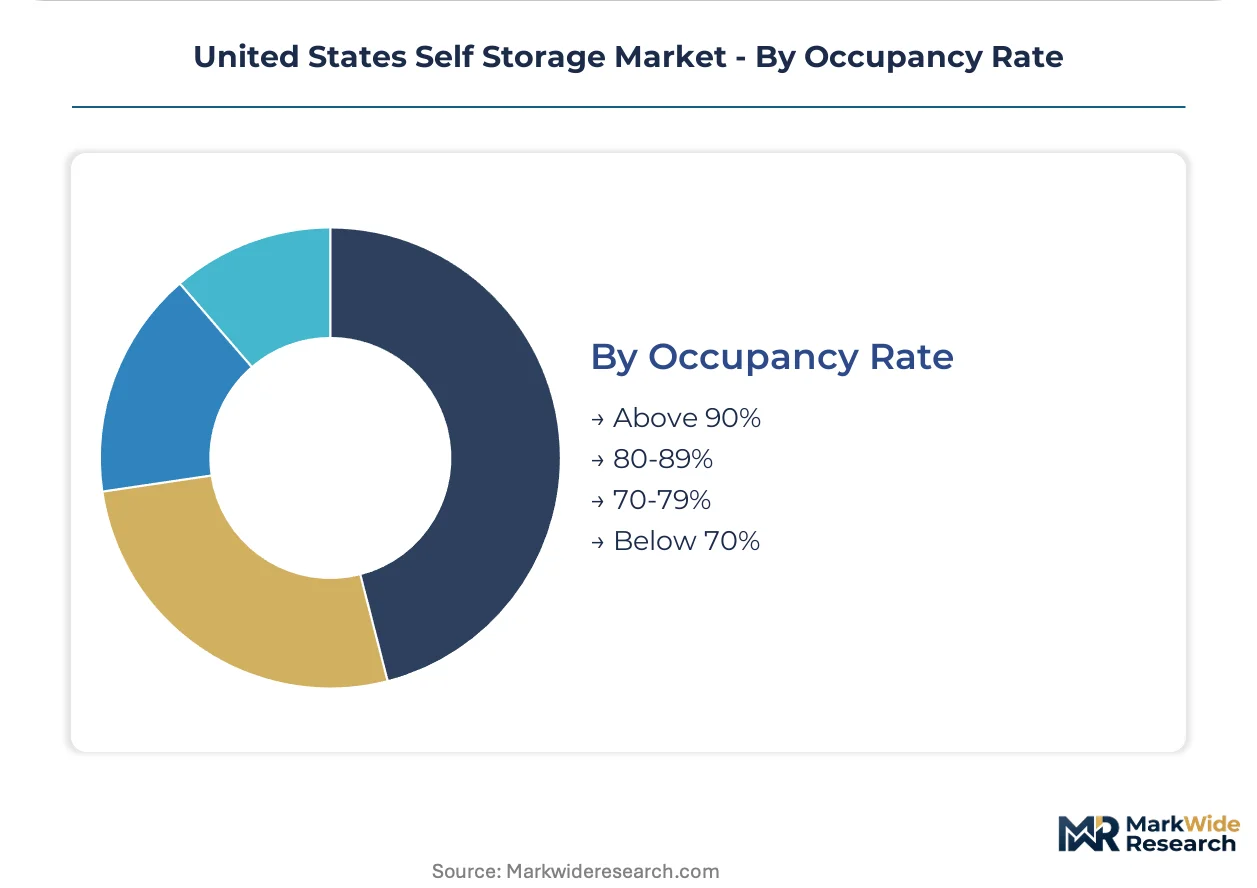
Occupancy Rate:
Occupancy segmentation functions as a performance metric rather than a product category, guiding operator pricing discipline and expansion timing. Rate tiers correlate directly with local supply-demand balance and competitive intensity.
- Above 90%:Tight supply conditions enabling rate increases and waitlist management. Sun Belt metros with constrained zoning approval velocity sustain these levels.
- 80-89%:Stabilized operations with pricing power intact. Most established facilities target this band for optimal revenue yield.
- 70-79%:Competitive pressure requiring promotional concessions. New supply waves in overheated submarkets push operators into this range.
- Below 70%:Distressed positioning demanding operational intervention or capital repositioning. Oversaturated corridors with simultaneous facility deliveries experience this threshold.
Above 90% occupancy defines the Sun Belt benchmark, with Below 70% clusters expanding fastest in markets with synchronized development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Sun Belt states with streamlined permitting and coastal markets with restrictive zoning is reshaping facility development patterns. Texas and Florida municipal planning commissions have compressed approval timelines by half, drawing capital away from Northeast and West Coast corridors where environmental review extends construction starts.
Texas
Houston and Dallas-Fort Worth metropolitan corridors absorb the majority of new climate-controlled supply as small business inventory overflow strains suburban square footage. Municipal planning commissions in Harris and Dallas counties have relaxed setback requirements and maximum building height restrictions, cutting facility approval timelines substantially. San Antonio anchors military demand elasticity from base reassignments at Joint Base San Antonio, generating cyclical occupancy spikes.
Florida
Miami-Dade and Tampa Bay submarkets face acute residential square footage compression from sustained population inflows, pushing household goods into leased compartments. State-level zoning reforms have eased facility permitting velocity for low-rise drive-up construction in suburban corridors. Orlando concentrates student demand from University of Central Florida enrollment expansion, creating predictable seasonal troughs between academic calendars.
California
Bay Area and Los Angeles Basin infill locations command premium rate structures for climate-controlled units protecting sensitive commercial inventory. California Energy Commission building efficiency standards extend HVAC permitting complexity, stretching development timelines relative to Sun Belt competitors. Sacramento and Inland Empire submarkets absorb overflow demand from coastal price escalation, though CEQA environmental review adds procedural friction.
Arizona
Phoenix metropolitan expansion generates persistent demand from retirees downsizing into smaller residential footprints, releasing household contents into storage. Maricopa County zoning boards maintain moderate permitting velocity between Sun Belt streamlining and California restrictiveness. Tucson anchors military demand from Davis-Monthan Air Force Base rotations, contributing seasonal occupancy elasticity.
Georgia
Atlanta metropolitan corridors absorb business inventory overflow from e-commerce fulfillment fragmentation across suburban nodes. Georgia Department of Community Affairs coordinates statewide zoning guidelines that moderate local permitting variance. Savannah and Augusta submarkets generate baseline military demand from Fort Stewart and Fort Gordon personnel movements, stabilizing occupancy through traditional low seasons.
United States Self Storage Market Key Industry Players
Sun Belt REITs anchor the national tier; regional specialists hold infill positions in coastal and Midwest markets. The vendor base concentrates around three dominant public REITs with standardized facility formats, while mid-cap operators fragment across secondary metros with localized development expertise. Strategic archetypes separate into scale-driven national platforms, technology-enabled access differentiators, and infill location specialists. Competitive moves center on portfolio acquisition velocity and technology platform integration rather than greenfield development races.
Among national-scale REITs, Public Storage, Extra Space Storage, and CubeSmart occupy positions across distinct strategic vectors. Public Storage exemplifies footprint dominance through standardized facility formats replicated across metropolitan corridors. Extra Space Storage represents technology-enabled access differentiation with smartphone-based entry systems. CubeSmart anchors infill portfolio strategy around population corridor proximity. National Storage Affiliates and LifeStorage sit within regional consolidation archetypes, aggregating third-party management contracts into scaled platforms. SmartStop Self Storage and StorageMart exemplify mid-cap development specialists with concentrated Sun Belt exposure. U-Haul Holding Company occupies a hybrid position leveraging moving services integration with storage capacity. Absolute Storage Management represents third-party management specialization without owned real estate exposure.
| Leading Market Players |
|---|
| National Storage Affiliates |
| LifeStorage |
| Public Storage |
| SmartStop Self Storage |
| StorageMart |
| Extra Space Storage |
| CubeSmart |
| Absolute Storage Management |
| U-Haul Holding Company |
| Others |
Cost & Logistics Intelligence
Steel partitioning and roll-up door materials cascade through facility construction costs into climate-controlled rate premiums, with commodity volatility compressing development margins while zoning velocity in Texas and Florida accelerates absorption of higher-priced inventory.
Pricing Analysis
Direct-to-tenant lease structures bypass traditional distribution layers, capturing full rate realization at the facility level. Three-tier pricing structure across climate-controlled, drive-up access, and outdoor formats separates premium HVAC-equipped units from standard roll-up configurations. Pricing pressure stems from steel input cost volatility and synchronized supply waves in overheated Sun Belt submarkets. Small business inventory clients demonstrate highest price sensitivity, while commercial fleet operators absorbing extra-large vehicle bays show lowest elasticity.
Supply Chain Analysis
Refurbishment flows for climate-controlled HVAC systems and elevator components create secondary parts markets that extend equipment lifecycle and moderate capital replacement cycles. Steel coil supply concentrates in domestic mills across Indiana, Ohio, and Pennsylvania, with roll-forming operations regionalized to construction corridors. HVAC equipment draws from compressor manufacturers in Tennessee and Texas. Single-source vulnerability sits with specialized roll-up door spring mechanisms from concentrated Midwest fabricators. Distribution runs through direct procurement relationships between REIT development teams and regional construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas and Florida's compressed permitting timelines against California's CEQA friction create a 12-18 month development velocity differential that rewards capital deployment in streamlined jurisdictions.
For Market Incumbents: Hedge against steel commodity exposure through forward contracting with domestic mills ahead of facility development cycles. Consolidate third-party management contracts in Georgia and Arizona submarkets where regional specialists face succession-driven exit pressure. Channel control through smartphone-based access platform standardization defends against technology-enabled entrants.
For New Entrants and Emerging Players: Digital marketplace aggregation routes bypass legacy broker relationships that national REITs dominate, enabling direct tenant acquisition in suburban Texas corridors. Target extra-large vehicle containment formats in exurban Florida where commercial fleet penetration lags household goods saturation. White-space exists in third-party management specialization for mid-cap owners lacking operational scale.
For Investors and Strategic Acquirers: Roll-up economics work for regional Sun Belt portfolios because municipal zoning variance creates localized moats that national platforms cannot easily replicate. Five-to-ten year viability hinges on climate mandate retrofit exposure in existing building stock. Monitor municipal energy efficiency standard adoption velocity as the inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Controlled Format Expansion | HVAC infrastructure commands premium rate structures in Sun Belt heat corridors. |
| Technology-Enabled Access Integration | Smartphone-based entry systems compress operational overhead and differentiate tenant experience. |
| Suburban Infill Portfolio Acquisition | Population corridor proximity anchors occupancy stability through residential square footage compression. |
| Drone-Based Security Deployment | FAA regulatory pathways for unmanned aerial surveillance create competitive differentiation in facility monitoring. |
| Tenant Protection Product Expansion | State insurance commissioner-regulated point-of-lease offerings generate ancillary revenue with minimal facility investment. |
Research Approach
Coverage spans Texas, Florida, California, Arizona, and Georgia metropolitan corridors, with primary inputs from each. Facility development executives, municipal planning commissioners, HVAC equipment procurement managers, and third-party management operators provided ground-level intelligence. Secondary validation drew from SEC REIT filings, municipal zoning board records, EIA energy consumption data, and steel commodity trade publications. Bottom-up unit absorption models triangulated against top-down market sizing across facility type, customer segment, and unit size dimensions.
Rate-of-change decomposition separated occupancy velocity from pricing power trajectories across the projection horizon. Segmentation modeling captured facility type, customer category, unit size tier, and regional regulatory cluster variations. CAGRs derived from rolling average absorption rates applied to supply-constrained submarket definitions. Forecast inputs incorporated military permanent change-of-station calendars, student academic cycle patterns, and small business inventory fragmentation indices.
The model assumes a particular technology adoption path for smartphone-based access and automated facility management; alternative pathways for legacy system integration would alter the outlook. Forecasts reflect assumptions about sustained Sun Belt population in-migration and continued municipal zoning reform momentum. Practitioners should monitor steel commodity price volatility, municipal climate mandate adoption timelines, and FAA drone regulation finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Warehousing Services Market