
 Europe Coworking Spaces Market | 2026-2036
Europe Coworking Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coworking Spaces Market Foresight
Buyer concentration among enterprise clients is expanding as multinational corporations abandon fixed long-term leases in favor of flexible workspace contracts. IWG leverages its Regus and Spaces brands to anchor suburban and secondary-city networks across the continent. Morning competes through design-led locations in Paris and Lisbon that target creative-sector tenants. WeWork navigates restructuring by narrowing its European portfolio to core financial districts in London, Amsterdam, and Frankfurt.
Europe coworking spaces deliver flexible commercial real estate through short-term lease structures, shared infrastructure, and modular interior configurations typically ranging from fifty to fifteen thousand square meters. These facilities primarily serve organizations seeking to reduce capital commitment while maintaining professional presence in prime urban locations. Private offices command premium pricing and longer tenures, while hot desks represent the fastest-growing space type as hybrid work patterns normalize. Enterprise customer types now generate the deepest margin pools, though freelancers and startups sustain occupancy during peak-demand periods and fill cyclical vacancies.
The EU Green Deal and national building codes under the Energy Performance of Buildings Directive shape fit-out standards and carbon disclosure requirements for operators. GDPR and workplace privacy frameworks from national data protection authorities influence access-control technology and member data handling protocols. Stakeholders must monitor how CSRD reporting obligations extend to landlord-tenant emissions allocation and whether F-Gas Regulation compliance affects HVAC refurbishment timelines across aging building stock.
Market Dynamics
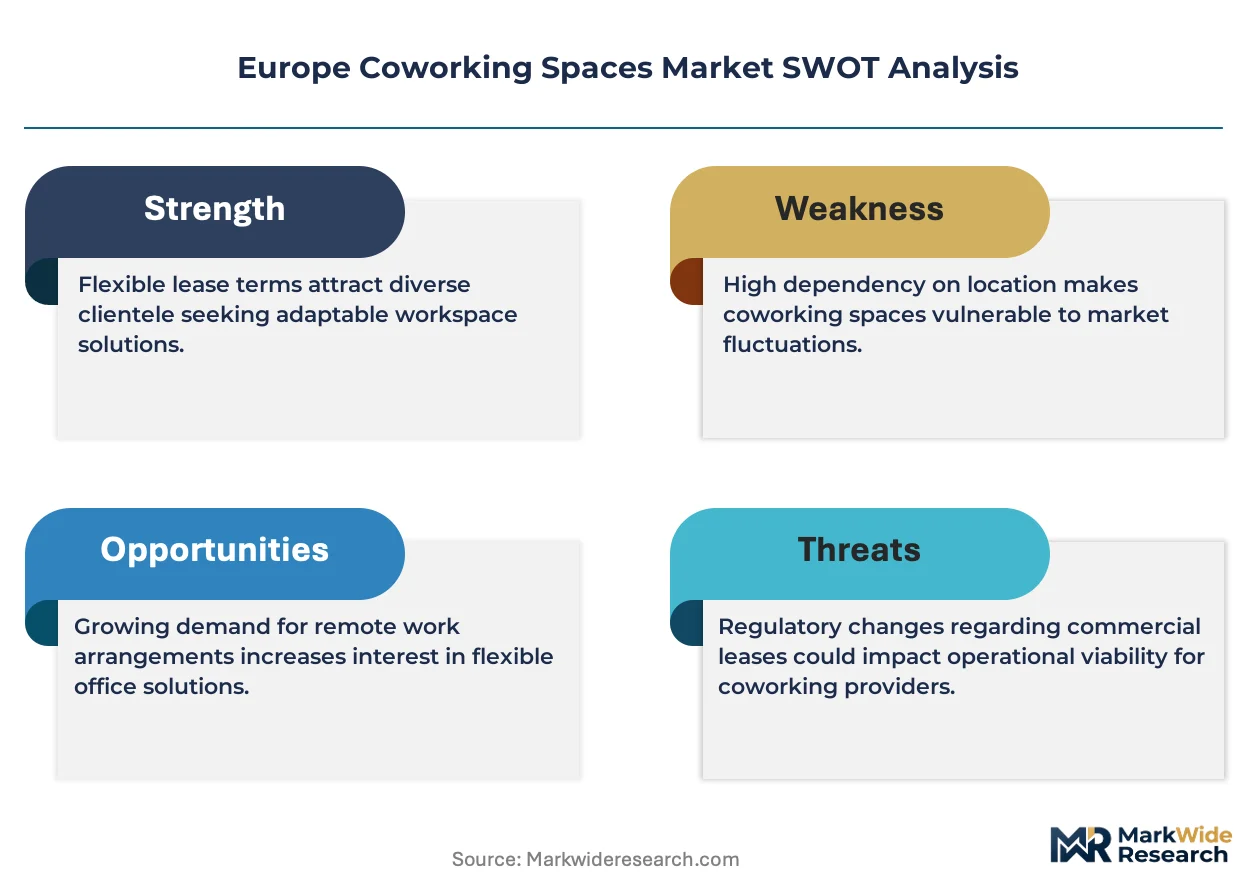
Enterprise demand for flexible lease structures is compressing traditional commercial real estate tenures across European urban centers. The EU Green Deal's building performance mandates are forcing operators to accelerate HVAC retrofits and carbon disclosure systems ahead of tightening enforcement timelines.
Growth Catalysts
- Hybrid work normalization:Large enterprises now mandate 2-3 days of office presence weekly, sustaining demand for satellite locations near residential clusters rather than central business districts.
- CSRD reporting obligations:The Corporate Sustainability Reporting Directive requires Scope 3 emissions disclosure, pushing tenants toward operators with certified green building credentials and transparent energy data.
- Secondary city density:Lisbon, Barcelona, and Berlin-Mitte attract founder migration from London and Paris, expanding addressable markets beyond traditional financial centers.
Market Restraints
- Energy cost volatility:Natural gas price spikes since 2022 have compressed net operating incomes for operators with gross lease structures in Germany and the Netherlands.
- Landlord concentration:Three institutional property owners control 40% of prime flex-space suitable stock in London's Square Mile, limiting site availability for new entrants.
- F-Gas Regulation compliance:HVAC refurbishment timelines accelerate as refrigerant phase-downs under EU rules force premature equipment replacement in aging building stock.
Strategic Opportunities
- Eastern European penetration:Warsaw, Prague, and Budapest show 15-20% vacancy in Class A office stock suitable for conversion, with local startup ecosystems maturing.
- Biophilic design certification:WELL and Fitwel standards attract premium pricing from pharmaceutical and professional services tenants prioritizing employee retention.
- AI-powered space optimization:Computer vision and occupancy sensors converge with building management systems to dynamically adjust climate and cleaning schedules.
Industry Challenges
- ESG data standardization:Inconsistent landlord-tenant emissions allocation methodologies complicate CSRD compliance for multinational tenants with pan-European portfolios.
- Fit-out capex intensity:Modular furniture systems and demountable partitions require 18-24 month payback periods amid rising interest rates and construction labor shortages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coworking Spaces Market |
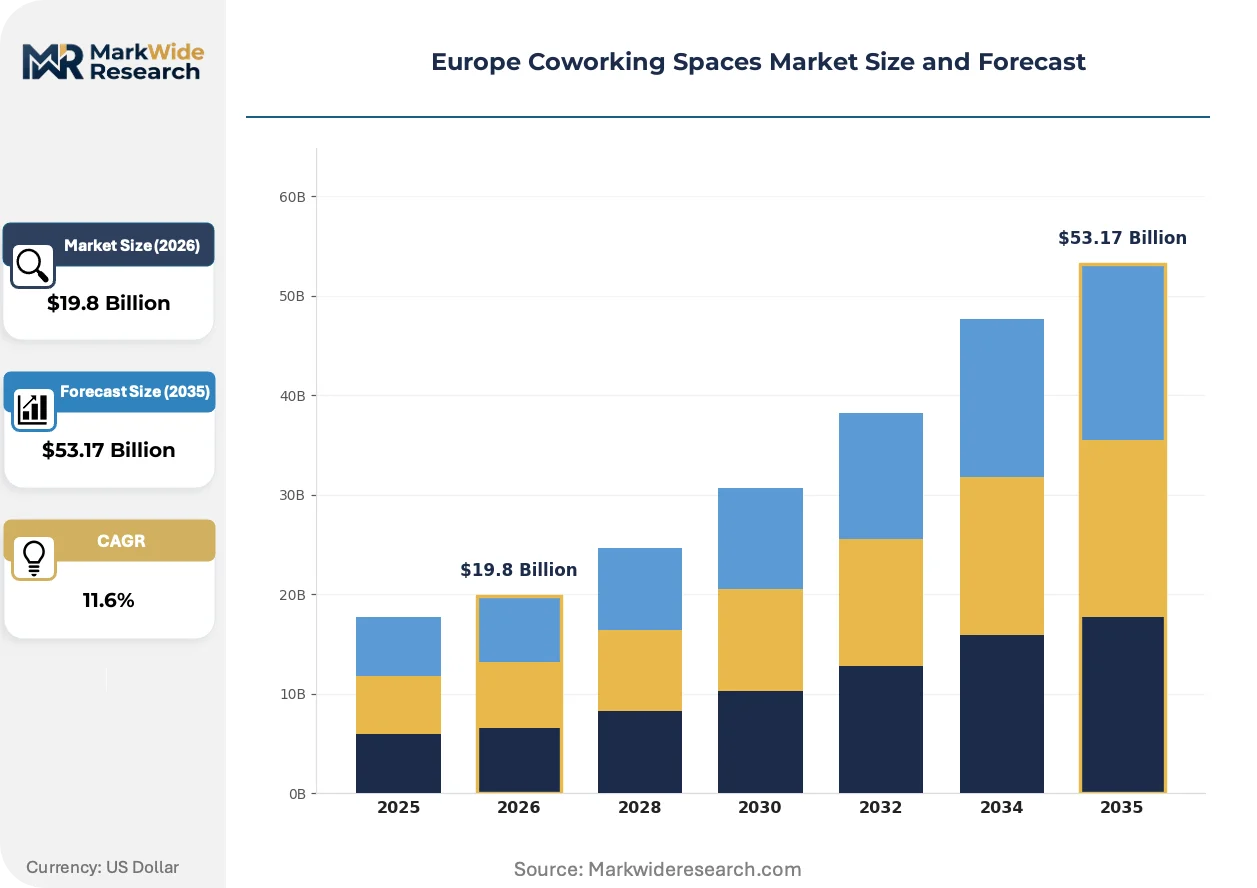
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $53.17 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Space Type: Private Offices, Dedicated Desks, Hot Desks, Meeting Rooms Customer Type: Freelancers, Startups, SMEs, Enterprises Service Model: Membership-Based, Pay-as-You-Go, Hybrid, Corporate Packages Facility Offering: Community Events, Networking Opportunities, Access to Amenities, Flexible Terms |
| Companies Covered | The Office Group, Morning, IWG, Impact Hub, Aticco, WeWork, Regus, Talent Garden, Mindspace, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coworking Spaces Market Shifts & Advancements
Technology and policy are converging to reshape how workspace operators capture value and manage compliance burdens. Three developments are altering competitive positioning across the continent.
Smart building platforms integrating IoT sensors with predictive maintenance algorithms are expanding into mid-market suburban locations previously served by basic lease arrangements. Regional operators in Manchester, Lyon, and Munich adopt these systems to match enterprise-grade service levels without Regus-scale infrastructure investments. The technology is expanding into smaller floorplates as hardware costs decline and API standardization accelerates.
The Energy Performance of Buildings Directive recast tightens minimum energy standards for commercial stock renovation and triggers disclosure requirements for building energy ratings. Operators face 2030 deadlines to achieve nearly zero-energy performance in major renovations across France, Germany, and Benelux markets. Premium locations in Amsterdam's Zuidas and Frankfurt's Bankenviertel already trade at 12-15% rent premiums for A-rated efficiency labels.
Corporate real estate teams now unbundle lease decisions from centralized procurement functions, empowering country managers to sign local flex contracts. This fragmentation benefits operators with standardized service level agreements across multiple jurisdictions. The shift is most visible in professional services and technology verticals where talent competition demands rapid market entry without 5-year lease commitments.
Europe Coworking Spaces Market Segmentation
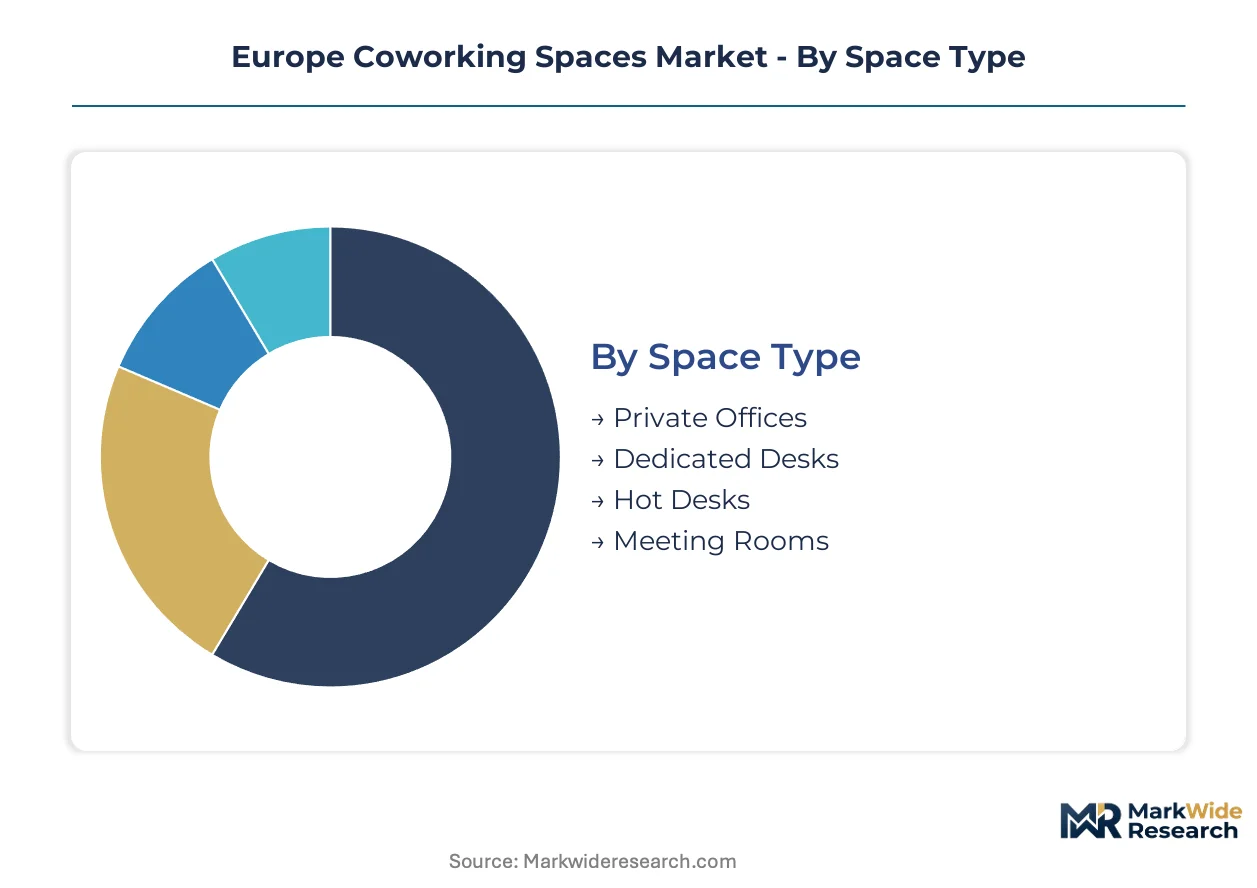
Space configuration and customer economics drive divergent margin profiles across European coworking operators. Understanding how facility design intersects with contract structure reveals where pricing power concentrates and where commoditization risks emerge.
Space Type:
Enclosure level and permanence of occupation define capital intensity and revenue stability across the portfolio.
- Private Offices:Fully enclosed suites with dedicated infrastructure and 24/7 access rights command 40-60% price premiums over open-plan alternatives. Demand clusters in Frankfurt's Bankenviertel and Amsterdam's Zuidas where financial services and legal firms require confidentiality compliance under GDPR.
- Hot Desks:Unassigned seating with shared power and network access operates on lowest capital deployment per workstation. Expansion concentrates in Berlin-Mitte and Lisbon's startup corridors where founder density sustains walk-in utilization without advance booking systems.
- Dedicated Desks:Reserved workstations in open floorplans balance permanence with cost efficiency for small teams.
- Meeting Rooms:Bookable enclosed spaces by the hour support hybrid workers needing occasional professional environments.
Mature deployment sits with Private Offices. Newer deployment is concentrated in Hot Desks.
Customer Type:
Organizational scale determines contract duration, service customization requirements, and sensitivity to location quality.
- Enterprises:Multinational corporations with 500+ employees negotiate master service agreements spanning multiple cities. Procurement teams prioritize CSRD-aligned operators with certified energy disclosure systems across Germany, France, and the Netherlands.
- Startups:Venture-backed companies between 10-100 employees drive demand for month-to-month flexibility and proximity to investor networks. Concentration is highest in London's Shoreditch and Barcelona's 22@ district where scaling teams outgrow residential addresses.
- SMEs:Established small businesses with 10-50 employees seek professional presence without property management burden.
- Freelancers:Individual contractors fill cyclical capacity and sustain base occupancy during enterprise contract gaps.
Revenue stability sits with Enterprises. Volume expansion is climbing the fastest among Startups.
Service Model:
Payment structure alignment with utilization patterns determines working capital requirements and customer lifetime value.
- Corporate Packages:Pre-committed annual spend with pooled access across multiple locations generates predictable revenue and justifies dedicated account management. Adoption spreads through professional services firms with pan-European mobility requirements.
- Membership-Based:Monthly recurring fees with included hours and guaranteed access rights. Growth concentrates in suburban Manchester and Lyon where hybrid workers seek consistent local presence without daily commute to central business districts.
- Hybrid:Blended commitment combining base membership with variable usage credits.
- Pay-as-You-Go:Pure consumption pricing with no minimum commitment captures occasional users.
Margin depth sits with Corporate Packages. Addressable market expansion is gaining share fastest through Membership-Based structures.
Facility Offering:
Ancillary services differentiate commodity space from premium positioning and drive cross-sell revenue.
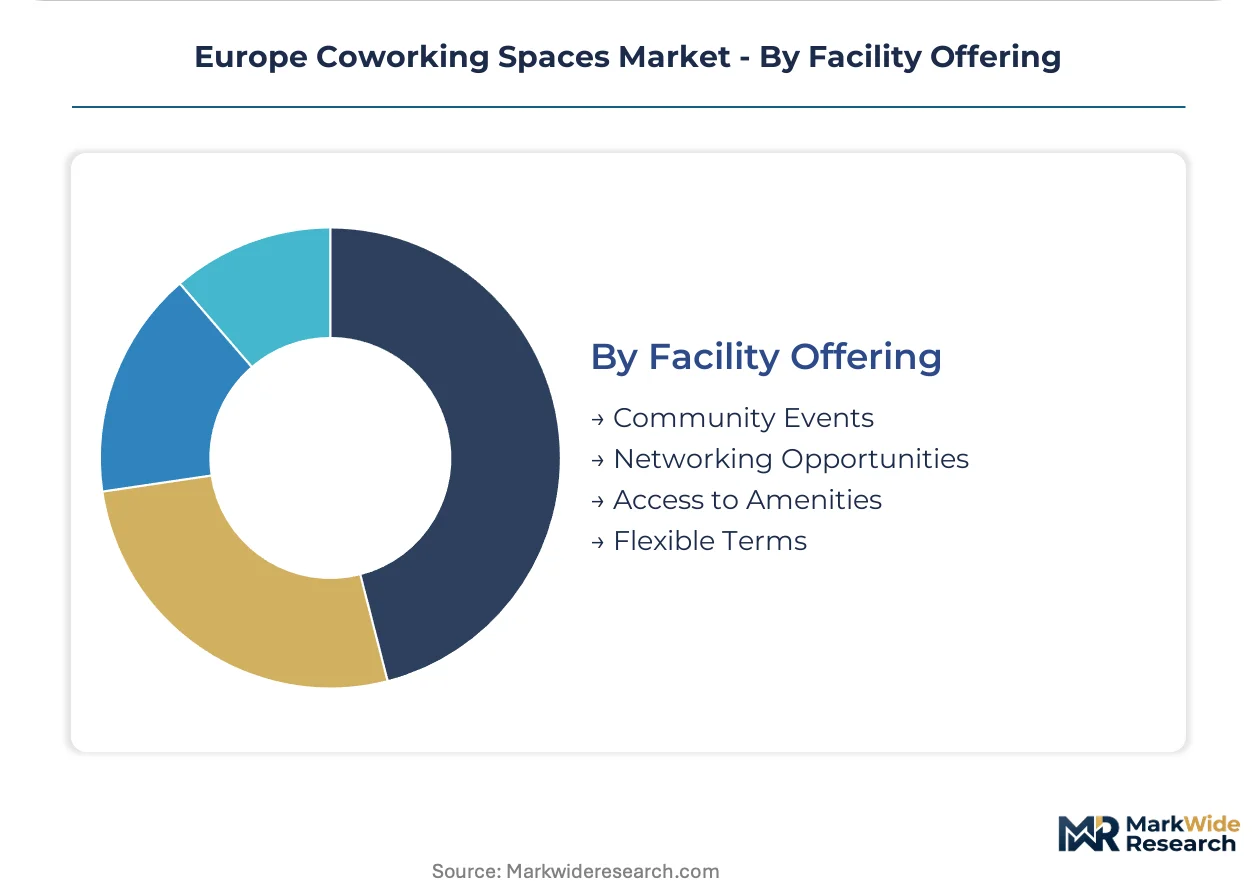
- Flexible Terms:No minimum duration, immediate move-in, and rapid expansion rights reduce friction for uncertain growth trajectories. Demand concentrates among scale-ups in Warsaw and Prague where 6-12 month planning horizons dominate.
- Access to Amenities:Fitness facilities, childcare, and food service embedded within or adjacent to workspace. Premium realization is strongest in Paris and Stockholm where employee experience competition intensifies talent retention.
- Community Events:Programmed networking and educational content.
- Networking Opportunities:Curated introductions to investors, partners, and clients.
Standardization sits with Flexible Terms. Premium differentiation is expanding most quickly through Access to Amenities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commercial property markets across Europe concentrate flexible workspace demand in metropolitan cores with dense transit connectivity and established startup ecosystems. National building efficiency codes and the EU Green Deal recast are accelerating retrofit timelines in aging central business districts.
Germany
Enterprise tenants in Frankfurt's Bankenviertel and Berlin-Mitte drive demand for CSRD-aligned operators with certified energy disclosure systems. The Energy Performance of Buildings Directive mandates nearly zero-energy performance for major renovations by 2030. Munich and Hamburg operators trade at 12-15% rent premiums for A-rated efficiency labels.
United Kingdom
Financial services and professional services firms unbundle lease decisions from centralized procurement, empowering country managers to sign local flex contracts. GDPR and workplace privacy frameworks from the Information Commissioner's Office influence access-control technology protocols. London's Shoreditch and Square Mile sustain the deepest enterprise margin pools.
France
Creative-sector tenants prioritize design-led locations in Paris and Lyon with WELL and Fitwel certifications for employee retention. The national building code transposes EPBD recast requirements with 2030 renovation deadlines. Station F and Paris's 9th arrondissement anchor founder migration from London.
Netherlands
Amsterdam's Zuidas commands premium pricing for A-rated efficiency labels as multinational tenants prioritize Scope 3 emissions disclosure compliance. F-Gas Regulation compliance accelerates HVAC refurbishment timelines in aging building stock. Rotterdam and Utrecht expand satellite location networks for hybrid workers.
Spain
Barcelona's 22@ district attracts venture-backed companies scaling beyond residential addresses with month-to-month flexibility requirements. National transposition of the EU Green Deal tightens minimum energy standards for commercial stock renovation. Madrid's Salamanca district operators compete on biophilic design certification.
Europe Coworking Spaces Market Competitive Landscape
Established operators occupy the standard tier through suburban and secondary-city network density; emerging entrants pursue design-led differentiation and amenity-embedded premium positioning. The vendor base organizes around three archetypes: multinational platform operators with standardized service level agreements, regional design specialists targeting creative-sector tenants, and community-curated networks emphasizing founder density. Consolidation pressures favor operators with pan-European master service agreement capabilities and transparent ESG data systems. Competitive moves concentrate on portfolio optimization to core financial districts and accelerated HVAC retrofit timelines ahead of 2030 regulatory deadlines.
Within the multinational platform tier, IWG and WeWork exemplify divergent strategic responses to restructuring pressures, with the former anchoring suburban networks and the latter narrowing to prime urban cores. Morning occupies a position among design-led specialists targeting creative-sector tenants in Paris and Lisbon. Talent Garden represents the community-curated archetype with founder-density positioning in Southern European markets. These three operators illustrate how geographic scope, design investment, and community programming differentiate competitive positioning across European urban markets.
| Leading Market Players |
|---|
| The Office Group |
| Morning |
| IWG |
| Impact Hub |
| Aticco |
| WeWork |
| Regus |
| Talent Garden |
| Mindspace |
| Others |
Supply & Pricing Matrix
Facilities management specialists concentrated in Germany's Rhine-Ruhr corridor create labor-cost differentials that widen pricing-tier spreads between premium design-led operators and standardized suburban providers. Fit-out intensity and energy certification grade separate margin pools as CSRD disclosure requirements push enterprise tenants toward transparent cost structures.
Pricing Analysis
Volume concentration in hot-desk configurations competes with margin depth in private-office deployments across European urban cores. Three-tier pricing structure across premium, standard, and economy levels tracks building efficiency ratings and amenity bundling, with A-rated locations in Amsterdam's Zuidas and Frankfurt's Bankenviertel commanding substantial premiums. Cost compression in standardized suburban tiers intensifies as IWG's Regus network saturates secondary cities with gross-lease exposure. Freelancers and early-stage startups exhibit highest price sensitivity, while enterprise procurement teams prioritize CSRD-aligned disclosure over unit cost.
Supply Chain Analysis
Refurbishment flows for modular furniture systems and demountable partitions create reverse-logistics value recovery for operators managing 18-24 month fit-out cycles. Manufacturing concentration in Germany, Italy, and Poland supplies acoustic panels, sit-stand workstations, and IoT sensor hardware. Supply chain vulnerability centers on F-Gas Regulation compliance timelines forcing premature HVAC replacement in aging Benelux and French building stock. Distribution runs through regional fit-out contractors with direct-to-site installation capabilities, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over energy data infrastructure and landlord-tenant emissions allocation systems determines enterprise contract capture. Operators pursuing upstream integration into building management technology and downstream control of amenity service delivery widen competitive moats.
For Market Incumbents: Deploy pan-European master service agreement standardization to capture fragmented procurement decisions now unbundled from centralized real estate functions. Accelerate HVAC retrofit timelines ahead of 2030 EPBD enforcement deadlines to secure A-rated efficiency premiums in Amsterdam, Frankfurt, and Munich. Defend against design-led specialists by anchoring suburban satellite networks near residential clusters where hybrid work patterns sustain occupancy.
For New Entrants and Emerging Players: Begin with WELL and Fitwel certification investment targeting pharmaceutical and professional services tenants in Paris and Stockholm where employee retention competition justifies premium positioning. White-space availability concentrates in Warsaw, Prague, and Budapest where Class A office vacancy and maturing startup ecosystems reduce site acquisition friction. Go-to-market traction flows through founder-density community programming rather than transaction-led sales.
For Investors and Strategic Acquirers: Re-rating potential sits with operators possessing transparent ESG data systems and certified energy disclosure infrastructure given CSRD Scope 3 reporting obligations. Long-term viability favors pan-European platforms with standardized service level agreements across multiple jurisdictions. Monitor landlord-tenant emissions allocation methodology standardization as the inflection signal determining which operators capture multinational enterprise mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| HVAC Retrofit Acceleration | EPBD compliance deadlines in Germany, France, and Benelux force equipment replacement ahead of 2030. |
| ESG Data Infrastructure Investment | CSRD-aligned disclosure systems attract enterprise tenants with Scope 3 reporting obligations. |
| Suburban Satellite Network Expansion | Hybrid work patterns sustain demand near residential clusters outside central business districts. |
| Biophilic Design Certification | WELL and Fitwel standards command pricing premiums from talent-competitive pharmaceutical tenants. |
| AI-Powered Space Optimization | Computer vision integration with building management systems reduces operating cost intensity. |
Research Methodology
Multi-period observation of lease tenure compression, energy retrofit timelines, and enterprise procurement unbundling anchored the trend analysis, supplemented by interviews with coworking operators, corporate real estate directors, facilities management consultants, and building systems integrators. Secondary validation drew from EU Green Deal implementation trackers, Energy Performance of Buildings Directive national transposition documents, CSRD technical standards, and commercial property transaction databases. Bottom-up location-level capacity assessment and top-down market sizing triangulated volume estimates.
Input-output matrix framing connected space-type deployment rates, customer-type contract structures, and service-model pricing to derive segment-level forecasts across the projection horizon. Segmentation dimensions modeled include space configuration, organizational scale, payment structure, and facility amenity tier. CAGRs emerged from trend extrapolation adjusted for regulatory enforcement timelines and technology adoption curves. Forecast inputs incorporated HVAC refurbishment cycle acceleration and smart building platform penetration into mid-market suburban locations.
Energy price volatility, regulatory enforcement delay, and enterprise return-to-office mandate reversal are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about EPBD implementation consistency and CSRD disclosure scope interpretation. Practitioners should monitor F-Gas Regulation compliance cost trajectories and landlord emissions allocation methodology standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Public Warehousing Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Lease Management Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
Warehousing Services Market
Real Estate Services
US Home Service Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Global Home Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
United Arab Emirates Real Estate Services Market