
 Facility Management Services Market | 2026-2036
Facility Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Facility Management Services Market Intelligence
EU Green Deal compliance is restructuring capital deployment across European facility portfolios, forcing owners to bundle decarbonization with traditional service contracts. Sodexo S.A. leverages its energy services division to capture integrated contracts that combine cleaning with carbon reporting. Emcor Group anchors its position through in-house mechanical expertise that reduces subcontractor reliance on complex infrastructure projects. CBRE Group competes via its technology platform that consolidates work orders, energy data, and vendor performance into single-dashboard visibility for multinational occupiers.
Facility management services encompass the coordinated planning, operation, and maintenance of built environments through integrated hard services (mechanical, electrical, plumbing) and soft services (cleaning, security, groundskeeping), typically governed by SLAs measuring response times, uptime percentages, and energy intensity per square meter. The primary purpose is to preserve asset value, ensure occupant safety, and optimize lifecycle costs across commercial, industrial, and institutional property portfolios. Cleaning and Maintenance command the largest revenue share within Service Type due to their non-discretionary nature and recurring billing structures. Building Automation and IoT Solutions within Technology represent the fastest-expanding margin pools as owners shift from preventive to predictive maintenance models. Corporate Offices and Healthcare Facilities within Customer Type generate the most complex contract structures, often requiring 24/7 staffing, specialized waste protocols, and regulatory audit trails.
OSHA workplace safety mandates, EPA energy benchmarking rules for large buildings, and local fire and accessibility codes collectively shape staffing levels, training investments, and technology procurement across the US facility management sector. In Europe, REACH chemical restrictions affect cleaning product formulations while the F-Gas Regulation drives HVAC service specialization. Stakeholders must monitor how converging ESG disclosure requirements and minimum energy performance standards are rewriting contract specifications and vendor qualification criteria before the next procurement cycle.
Market Dynamics
EU Green Deal mandates are forcing facility owners to bundle decarbonization retrofits with traditional service contracts, reshaping vendor selection criteria and contract structures across commercial portfolios.
Growth Catalysts
- Healthcare outsourcing surge:Hospital systems in the United States are expanding facility management contracts to reduce operational overhead and redirect capital toward clinical priorities.
- Building energy performance standards:The EU Green Deal and national retrofit mandates are compelling owners to modernize legacy assets through integrated service agreements.
- Predictive maintenance adoption:IoT sensor networks and AI-driven analytics are displacing scheduled maintenance with condition-based interventions that reduce downtime.
Market Restraints
- Skilled technician scarcity:HVAC and building automation specialists command premium wages, compressing margins on labor-intensive contracts.
- Subcontractor dependency:Complex infrastructure projects in Germany and France require specialized mechanical expertise that few integrated providers maintain in-house.
- REACH compliance costs:European chemical restrictions force reformulation of cleaning products, raising procurement expenses and training requirements.
Strategic Opportunities
- Carbon reporting integration:The CSRD disclosure framework creates demand for facility managers that can bundle energy data collection with traditional soft services.
- Small and mid-size building penetration:Underpenetrated commercial stock in Spain and Italy presents white space for technology-enabled service models.
- Convergence of digital twins and asset management:Real-time building simulation platforms enable predictive lifecycle planning that extends contract durations.
Industry Challenges
- Multi-site integration complexity:Multinational occupiers demand single-dashboard visibility across heterogeneous building systems and vendor networks.
- 24/7 staffing requirements:Healthcare and data center contracts mandate round-the-clock coverage that strains workforce scheduling and retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facility Management Services Market |
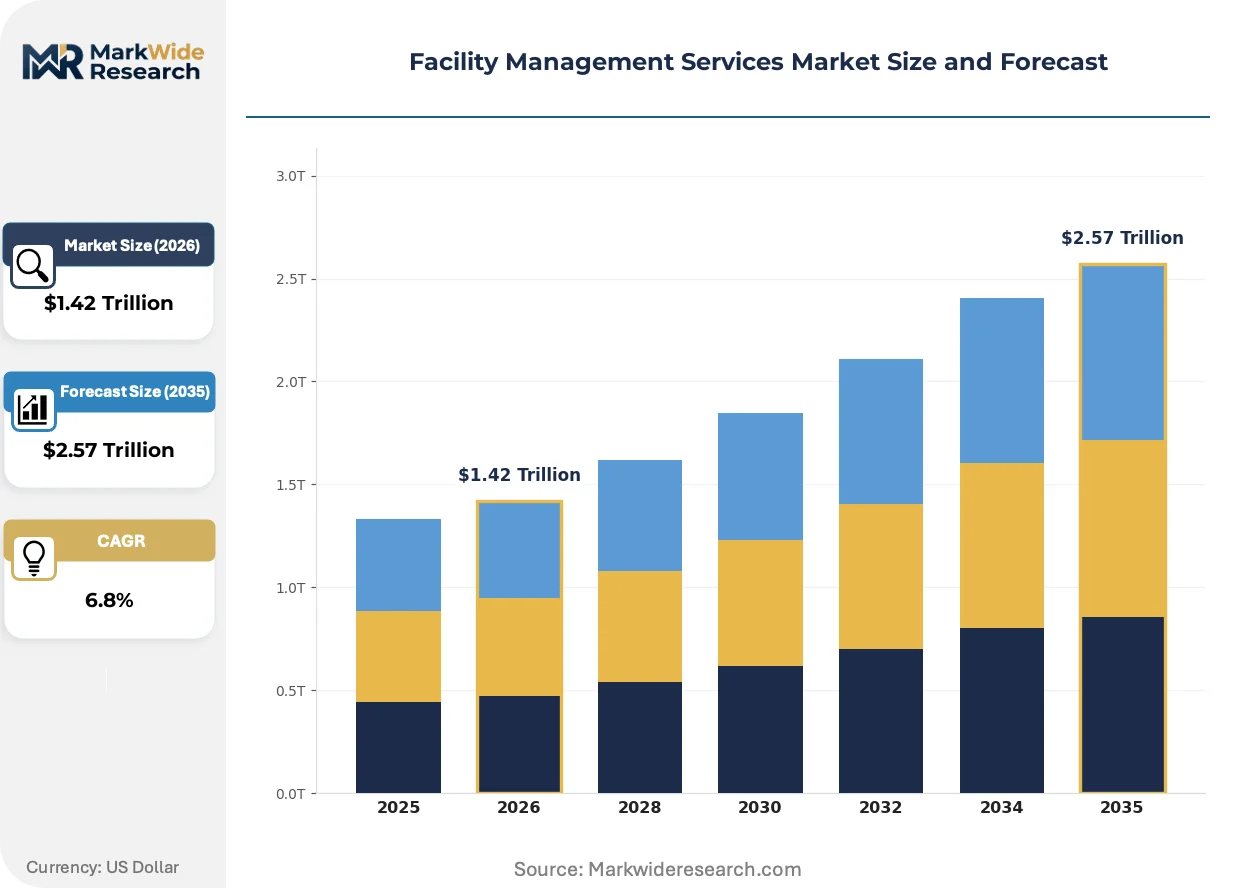
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.57 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping Customer Type: Corporate Offices, Educational Institutions, Healthcare Facilities, Retail Spaces Technology: Building Automation, Energy Management, IoT Solutions, Computer-Aided Facility Management End Use: Commercial Buildings, Industrial Facilities, Residential Complexes, Government Organizations |
| Companies Covered | Sodexo S.A., Emcor Group, CBRE Group, Aramark Corporation, Cushman & Wakefield, ISS A/S, ABM Industries Incorporated, Mitie Group, JLL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facility Management Services Market Strategic Shifts & Innovations
Digital infrastructure is reconfiguring how facility services are delivered, measured, and priced. Three developments are compressing traditional boundaries between hard services, soft services, and energy management.
Building automation systems are electrifying facility operations by replacing pneumatic controls with networked sensors and actuators. Corporate office portfolios in the United States are adopting these platforms fastest, driven by LEED certification requirements and utility rebate programs. The technology is electrifying competitive positioning by enabling providers to guarantee energy outcomes rather than simply execute maintenance tasks.
The EU F-Gas Regulation is accelerating HVAC service specialization across European markets. Equipment containing high-global-warming-potential refrigerants faces phasedown timelines, forcing service contractors to certify technicians on alternative chemistries and recovery protocols. Industrial facilities with extensive cooling loads are responding by consolidating contracts with vendors holding advanced refrigerant credentials.
Integrated service agreements are displacing siloed procurement of cleaning, security, and maintenance. Multinational occupiers in the United Kingdom and Netherlands are bundling these categories under single providers that can report unified performance metrics. This consolidation is most visible in financial services, where real estate teams face pressure to demonstrate operational efficiency to central procurement functions.
Facility Management Services Market Segmentation
Facility management services fragment across operational dimensions that determine contract economics and technology requirements. Service type dictates labor intensity, customer type shapes compliance obligations, technology investments separate premium from commodity providers, and end use defines asset complexity and risk profiles.
Service Type:
Capital intensity varies sharply across service categories, with technology-integrated offerings requiring sensor networks and platform investments while labor-heavy segments demand workforce management systems.
- Cleaning:Labor-intensive operations covering disinfection protocols, waste management, and consumables replenishment. Demand concentrates in United States healthcare facilities where Joint Commission audits and infection control mandates drive specialized staffing requirements. OSHA bloodborne pathogen standards and EPA chemical disclosure rules elevate training costs and liability exposure.
- Security:Personnel-based and technology-augmented protection services encompassing access control, surveillance monitoring, and emergency response coordination. Corporate offices in financial districts generate the most complex contract structures, requiring 24/7 coverage, background-checked personnel, and integration with tenant visitor management systems.
- Maintenance:Hard services spanning HVAC, electrical, plumbing, and structural repairs.
- Landscaping:Exterior grounds management including irrigation, seasonal planting, and snow removal.
Cleaning absorbs the bulk of installed capacity; Maintenance is expanding most quickly as predictive technologies displace scheduled service models.
Customer Type:
Contract sophistication escalates with regulatory burden and operational criticality, creating tiered pricing structures across customer categories.
- Healthcare Facilities:24/7 operations requiring Joint Commission compliance, specialized waste protocols, and emergency preparedness drills. United States hospital systems are consolidating vendor relationships to reduce procurement overhead and standardize infection control across multi-site portfolios.
- Corporate Offices:Class A commercial buildings demanding LEED-aligned energy performance, flexible space reconfiguration, and hospitality-grade amenity services. Financial services tenants in London and New York drive integrated service agreements that bundle cleaning, security, and concierge functions under single accountability.
- Educational Institutions:Seasonal demand patterns tied to academic calendars and state-funded capital renewal cycles.
- Retail Spaces:High-frequency service requirements aligned with foot traffic patterns and brand presentation standards.
Corporate Offices generate the highest contract values per square foot; Healthcare Facilities command the longest average contract durations due to credentialing complexity.
Technology:
Technology segmentation separates providers capable of outcome-based energy guarantees from those executing task-based maintenance contracts.
- Building Automation:Integrated control systems managing HVAC, lighting, and access through centralized platforms. United States commercial portfolios are retrofitting pneumatic controls with networked sensors to capture utility rebate programs and meet city-level benchmarking mandates.
- IoT Solutions:Sensor networks enabling condition-based maintenance through vibration analysis, thermal imaging, and air quality monitoring. Industrial facilities in Germany are deploying these systems to satisfy EU Green Deal energy performance requirements and avoid carbon penalties.
- Energy Management:Analytics platforms optimizing consumption patterns and renewable integration.
- Computer-Aided Facility Management:Work order dispatch, asset registry, and vendor coordination software.
Building Automation captures the largest installed base; IoT Solutions are gaining share fastest as predictive models displace preventive maintenance schedules.
End Use:
Asset complexity and regulatory exposure create distinct service requirements across property categories.
- Commercial Buildings:Multi-tenant properties requiring tenant coordination, base building system optimization, and landlord-allocated service charge management. Aging stock in United States central business districts drives intensive modernization programs combining HVAC replacement with building automation retrofits.
- Industrial Facilities:Manufacturing and logistics assets with specialized environmental controls, heavy equipment maintenance, and safety-critical protocols. REACH chemical restrictions and EU F-Gas Regulation compliance elevate contractor qualification requirements across European industrial zones.
- Residential Complexes:Multi-family properties with amenity maintenance and resident service coordination.
- Government Organizations:Public buildings subject to procurement regulations, prevailing wage requirements, and security clearance protocols.
Commercial Buildings represent the largest addressable market; Industrial Facilities are climbing the fastest as manufacturing reshoring expands facility footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in the United States concentrate facility management demand through tax-advantaged redevelopment districts. European energy performance mandates and Middle Eastern smart-city investments are redistributing service contract volumes across distinct regulatory environments.
United States
Hospital systems and aging commercial stock in Manhattan, Chicago, and Los Angeles drive outsourced facility contracts. OSHA workplace safety mandates and EPA energy benchmarking rules for large buildings shape staffing and technology procurement. Texas Medical Center in Houston anchors healthcare facility management concentration with 24/7 operational requirements.
Germany
Industrial facilities with extensive cooling loads and EU F-Gas Regulation phasedown timelines consolidate HVAC service contracts. REACH chemical restrictions force cleaning product reformulation across commercial portfolios. Rhine-Ruhr industrial corridor demands specialized mechanical expertise for complex infrastructure maintenance.
United Kingdom
Financial services tenants in London bundle cleaning, security, and concierge functions under integrated agreements. Minimum energy performance standards and CSRD disclosure frameworks rewrite vendor qualification criteria. Canary Wharf estate exemplifies single-dashboard visibility demands across heterogeneous building systems.
France
Public buildings and healthcare facilities subject to procurement regulations drive standardized service specifications. EU Green Deal retrofit mandates compel owners to modernize legacy assets through bundled contracts. Paris La Défense business district concentrates Class A commercial demand for LEED-aligned energy performance.
United Arab Emirates
Smart-city investments and hospitality-grade amenity requirements in Dubai and Abu Dhabi attract technology-enabled service providers. NEOM Northwest development creates demand for predictive maintenance platforms and real-time building simulation. Dubai International Financial Centre exemplifies multinational occupier requirements for unified performance metrics.
Facility Management Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered contract value bands. The vendor base organizes around three strategic archetypes: integrated full-service providers, technology-anchored platform operators, and specialized hard-services contractors. Consolidation pressure intensifies as multinational occupiers reduce vendor counts to simplify procurement overhead. M&A activity targets mechanical expertise capabilities and IoT platform assets.
Within the integrated services tier, Sodexo S.A., Emcor Group, and CBRE Group exemplify distinct positioning vectors. Sodexo S.A. represents the energy-services-integrated archetype through its carbon reporting bundling. Emcor Group anchors the in-house mechanical expertise model that reduces subcontractor reliance. CBRE Group occupies the technology-platform position consolidating work orders and vendor performance into unified visibility systems.
| Leading Market Players |
|---|
| Sodexo S.A. |
| Emcor Group |
| CBRE Group |
| Aramark Corporation |
| Cushman & Wakefield |
| ISS A/S |
| ABM Industries Incorporated |
| Mitie Group |
| JLL |
| Others |
Cost & Logistics Intelligence
Skilled technician wages cascade through contract pricing tiers, with premium labor rates for HVAC and building automation specialists in Germany and the United States translating into higher service charges for healthcare and data center clients, while standardized cleaning contracts absorb compressed margins through volume scaling.
Pricing Analysis
Short lead-time premiums for emergency mechanical repairs command 40-50% markups over scheduled maintenance slots, reflecting scarcity of certified F-Gas technicians under EU phasedown timelines. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed response-time contracts from flexible scheduling agreements. Cost compression in standard-tier cleaning services is intensifying because REACH compliance reformulation raises procurement overhead. Mid-size commercial buildings in Spain and Italy exhibit highest price sensitivity; healthcare systems in Texas and London demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in France and Germany for public building contracts are reshaping sourcing patterns, forcing facility managers to certify local workforce quotas and regional supplier networks. Equipment and chemical inputs concentrate in Germany, the United States, and China. Supply chains draw from refrigerant manufacturers, IoT sensor producers, and specialized cleaning chemical formulators. Single-source vulnerability runs through F-Gas-certified HVAC component suppliers facing phasedown disruptions. Distribution runs through direct national account teams for multinational occupiers and regional service branches for mid-market portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility management services are becoming a vertical-integration race, with control over in-house mechanical expertise and captive energy analytics capabilities determining margin capture in bundled contracts.
For Market Incumbents: Hedge against pure-play IoT platform entrants by acquiring predictive maintenance software assets and embedding carbon reporting into existing service agreements. Consolidate subcontractor networks in the Rhine-Ruhr corridor to reduce exposure to German technician scarcity. Prioritize CSRD-ready data infrastructure to defend against ESG-specialist competitors.
For New Entrants and Emerging Players: Technology-enabled service platforms offer the lowest barrier entry point, leveraging cloud-based work order systems to penetrate underrepresented mid-size commercial stock in Italy and Spain. Target small multi-tenant office buildings lacking dedicated facility staff. Deploy subscription pricing with energy benchmarking dashboards to displace incumbent cleaning-only providers.
For Investors and Strategic Acquirers: Consolidation of hospital system vendor relationships in the United States is the leading indicator that scale advantages are concentrating in integrated providers. Five-to-ten year viability favors firms with bundled hard-soft service capabilities and proprietary technician training academies. Monitor EU Green Deal retrofit contract awards as inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Academy Buildout | Captures scarce HVAC and F-Gas talent pools before EU phasedown deadlines tighten supply. |
| Carbon Reporting Platform Integration | Aligns service delivery with CSRD disclosure mandates reshaping European contract specifications. |
| Predictive Maintenance Software Acquisition | Displaces scheduled service models with IoT-enabled condition monitoring for industrial clients. |
| Regional Service Branch Expansion | Penetrates underrepresented mid-market commercial stock in Spain and Italy through local presence. |
| Energy Performance Guarantee Structuring | Converts maintenance contracts into outcome-based agreements with LEED-aligned energy commitments. |
Research Approach
Multi-period observation of contract renewal rates, technician wage indices, and energy retrofit permit filings anchored the trend analysis, supplemented by interviews with facility directors at hospital systems, corporate real estate heads, HVAC service contractors, and procurement officers at multinational occupiers. Secondary validation drew from EPA energy benchmarking databases, EU ETS emissions registries, OSHA incident reports, and trade association workforce surveys. Bottom-up service revenue estimates triangulated against top-down building stock modernization spending projections.
Segment-weighting approaches applied differential growth assumptions across service type, customer category, technology adoption stage, and end-use asset class throughout the forecast period. Hard services maintenance modeled separately from soft services cleaning based on predictive technology penetration curves. Healthcare and corporate office contract durations were calibrated against regulatory audit cycle frequencies. CAGRs derived from rolling average investment intentions across facility owner surveys.
Inputs from EPA benchmarking filings and EU Green Deal national implementation plans were available through the study window; gaps in real-time subcontractor pricing transparency introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding F-Gas phasedown adherence and REACH compliance cost pass-through rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Europe Hard Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Kuwait Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Oman Facility Management Market