
 United States Real Estate Services Market | 2026-2036
United States Real Estate Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Real Estate Services Market Analytics
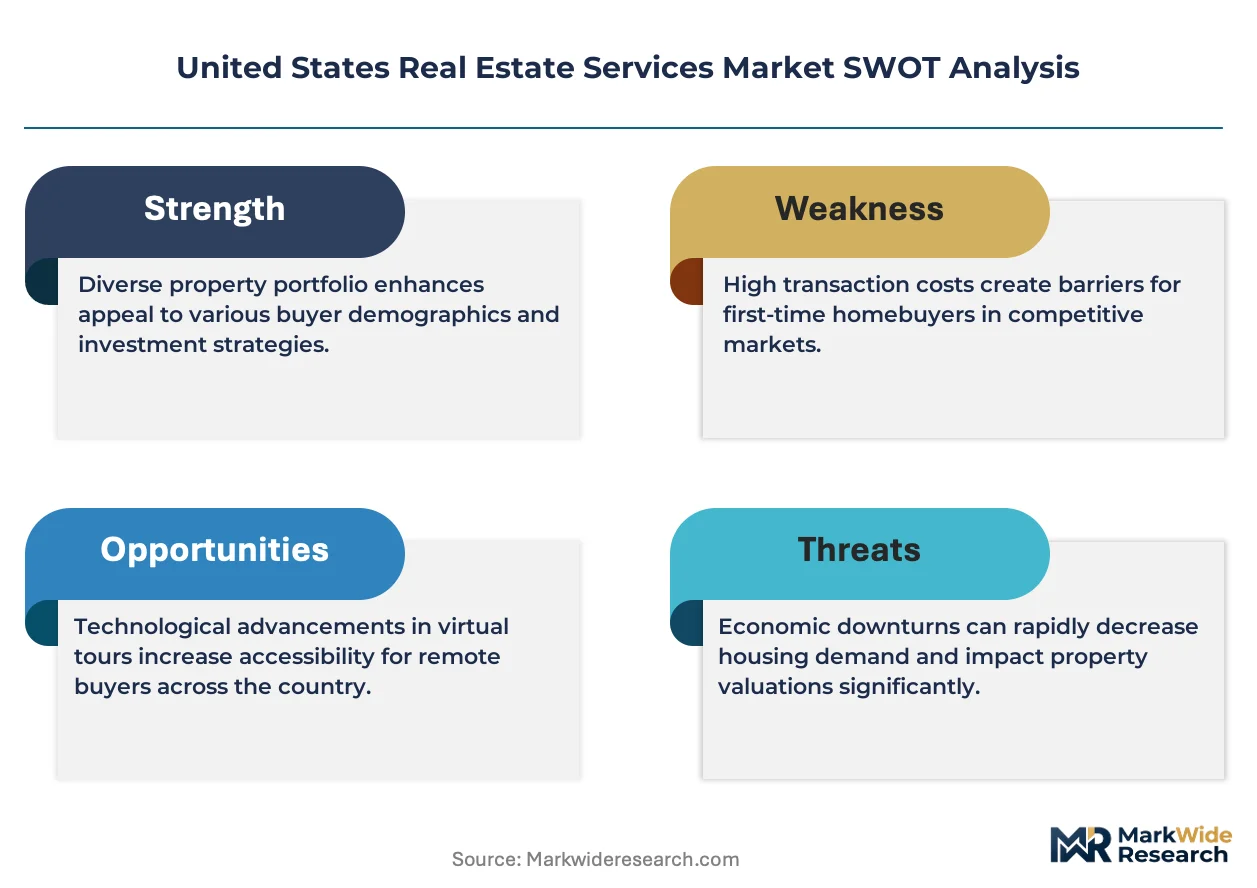
Brokerage commission structures is reconfiguring as technology-enabled platforms erode traditional fee models. CBRE Group dominates institutional commercial mandates through its global tenant representation network. Compass differentiates via proprietary mobile tools that streamline agent workflows. eXp Realty operates a cloud-based model that eliminates physical office overhead and attracts independent agents.
United States Real Estate Services encompasses transaction facilitation, asset management, valuation, and advisory functions performed by licensed professionals on residential and commercial properties. The field requires compliance with state-level licensing standards, multiple listing service protocols, and fiduciary duty obligations that vary by jurisdiction. Residential brokerage remains the largest revenue pool though property management generates steadier recurring income. Commercial brokerage commands premium fees but faces cyclical sensitivity to office occupancy rates. Flat-fee engagement models are gaining traction among cost-conscious sellers in high-volume markets.
The Department of Housing and Urban Development enforces fair housing standards that shape broker training and marketing compliance. State real estate commissions set continuing education requirements and disciplinary frameworks that affect market access. The SEC regulates real estate investment trusts and crowdfunding platforms that channel capital into property assets. Stakeholders must monitor how artificial intelligence tools for automated valuation and predictive pricing reshape licensing boundaries and professional liability standards.
Market Dynamics
Technology-enabled platforms are compressing traditional brokerage fee structures while institutional capital reallocates toward property management platforms. The SEC's investment adviser rules and HUD's fair housing enforcement are tightening compliance obligations across broker-dealer operations.
Growth Catalysts
- Sun Belt Migration:Population inflows into Austin, Nashville, and Phoenix sustain transaction velocity and property management demand. These metropolitan clusters attract both residential buyers and commercial developers.
- IRA Clean Energy Provisions:Tax incentives for energy-efficient building retrofits stimulate commercial property advisory services. Property owners seek valuation expertise to capture green building premiums.
- Cloud-Based Operating Models:Remote infrastructure eliminates physical office overhead for independent agents. Virtual platforms reduce fixed costs and expand geographic coverage without brick-and-mortar investment.
Market Restraints
- Interest Rate Sensitivity:Federal Reserve policy tightening elevates mortgage costs and compresses residential transaction volumes. Rate volatility creates pricing uncertainty that stalls buyer commitment.
- Office Occupancy Cyclicality:Commercial brokerage fees depend on lease renewal rates and tenant mobility. Hybrid work patterns reduce space requirements in central business districts.
- State Licensing Fragmentation:Jurisdiction-specific continuing education requirements create compliance complexity for multi-state operators. Reciprocity limitations restrict agent mobility across state lines.
Strategic Opportunities
- PropTech-Enabled Valuation:Automated valuation models and predictive pricing tools reshape appraisal workflows. Firms integrating AI-driven analytics capture institutional mandates requiring speed and scale.
- Build-to-Rent Residential:Institutional investors deploy capital into single-family rental platforms. Property management contracts for these portfolios generate recurring revenue streams insulated from transaction cyclicality.
- Opportunity Zone Structuring:Federal tax deferral incentives attract capital into designated distressed areas. Advisory services for compliance and asset placement command premium fees.
Industry Challenges
- Professional Liability Exposure:Automated valuation tools blur licensing boundaries between appraisers and automated systems. State real estate commissions struggle to define scope-of-practice standards for algorithmic outputs.
- Agent Retention Friction:Low barriers to platform switching enable independent contractors to migrate between brokerages. Commission splits and technology access drive churn that destabilizes revenue pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Real Estate Services Market |
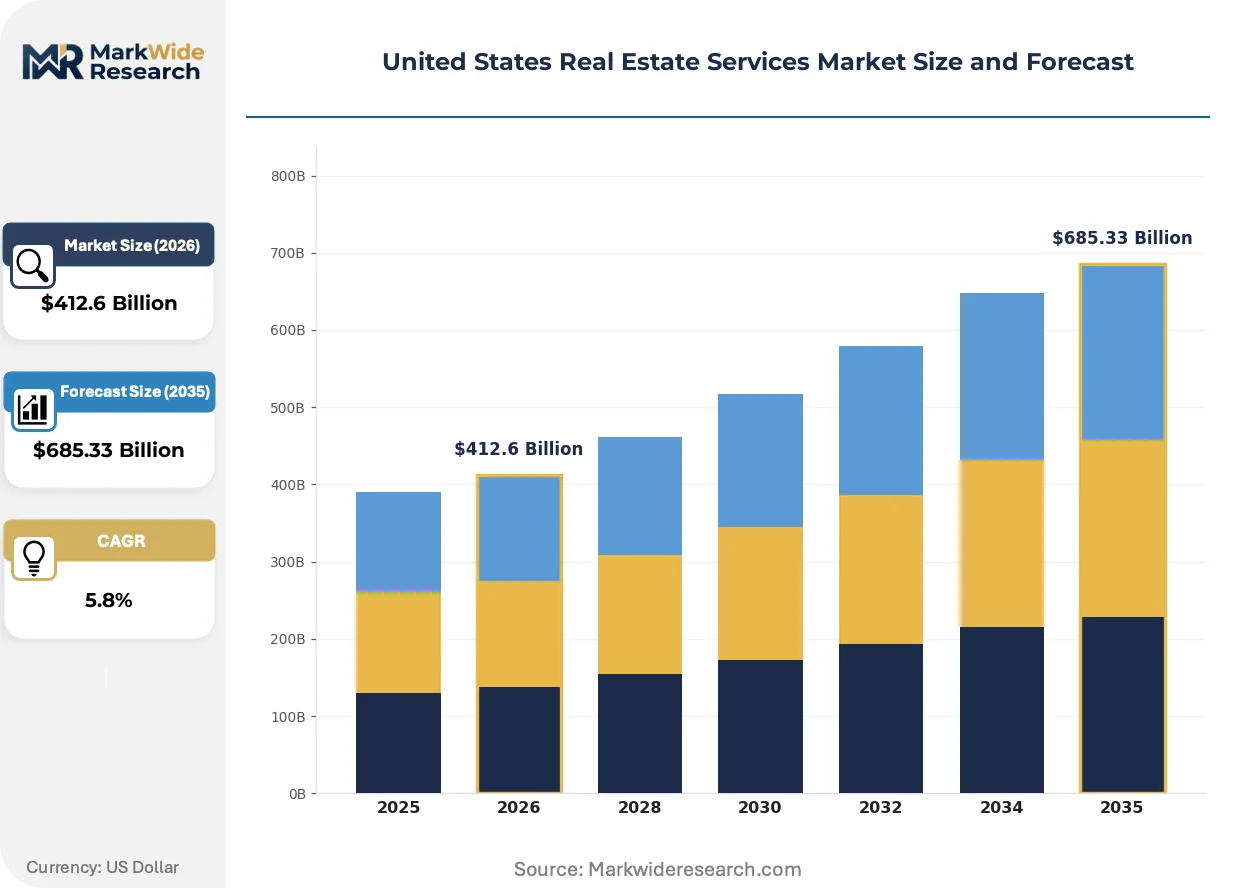
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $685.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Brokerage, Commercial Brokerage, Property Management, Appraisal Client Type: First-time Buyers, Investors, Sellers, Real Estate Agents Property Type: Single-family Homes, Multi-family Units, Retail Spaces, Office Buildings Engagement Type: Full-service, Flat Fee, Commission-based, Limited Service |
| Companies Covered | CBRE Group, Cushman & Wakefield, Jones Lang LaSalle, Berkshire Hathaway HomeServices, RE/MAX Holdings, Compass, eXp Realty, Anywhere Advisors, Brookfield Properties, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Real Estate Services Market Evolving Landscape
Distributed ledger infrastructure and predictive analytics are reconfiguring how property data flows between buyers, sellers, and intermediaries. Regulatory scrutiny of algorithmic decision-making is intensifying across federal agencies.
Blockchain-based title registries are virtualizing property record verification and reducing title insurance friction. Title companies and county recorders in Texas and Arizona pilot distributed ledger systems to compress closing timelines. This technology is virtualizing the due diligence phase that traditionally required physical document review and notarization.
The SEC's investment adviser custody rule revisions impose stricter asset segregation requirements on real estate crowdfunding platforms. Platform operators must restructure fund administration and investor reporting workflows. Crowdfunding vehicles targeting retail investors face compliance costs that favor larger platform scale.
Flat-fee listing services are displacing percentage-based commission structures in high-volume residential markets. Sellers in Phoenix and Nashville increasingly select à-la-carte marketing packages over traditional full-service representation. This behavior shift concentrates in markets with high price appreciation where absolute commission dollars appear disproportionate to service intensity.
United States Real Estate Services Market Segmentation
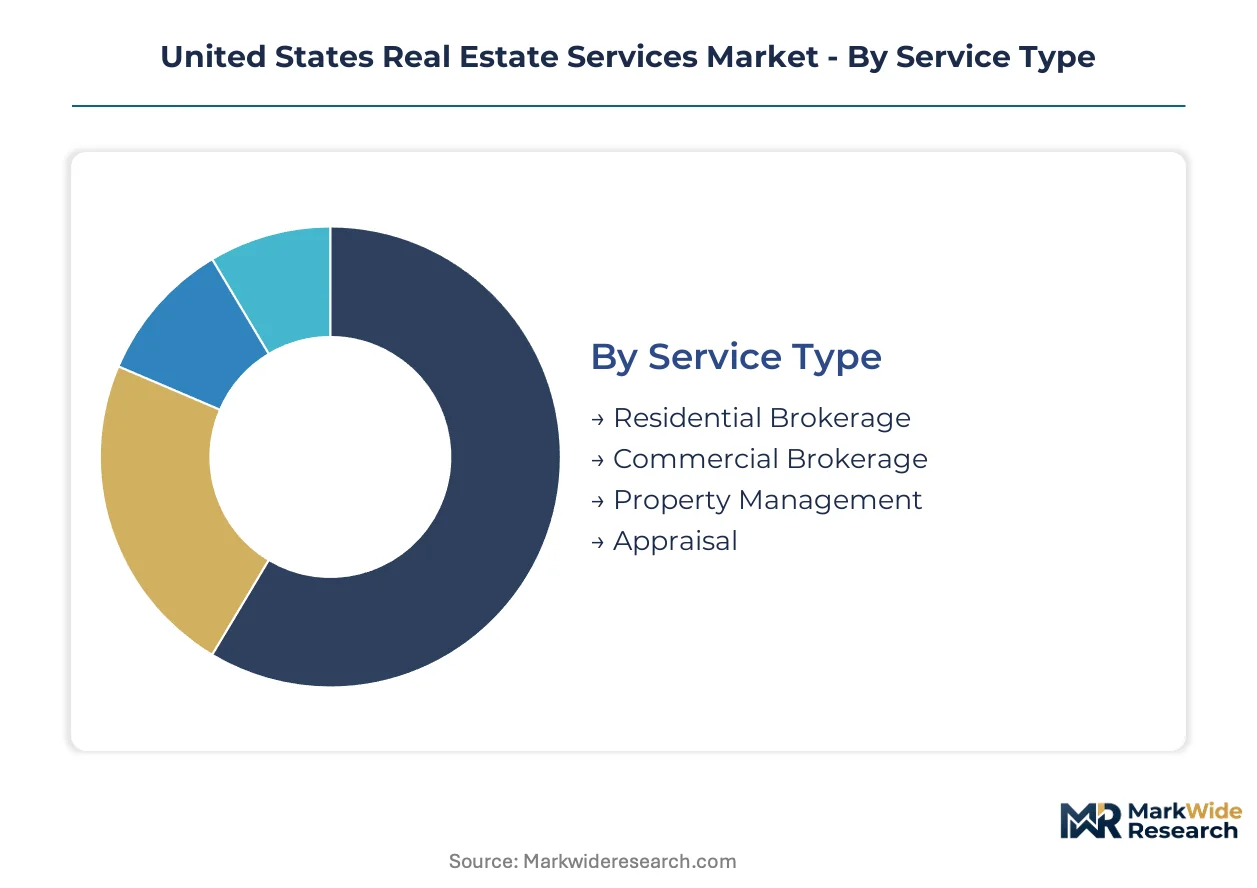
Service differentiation across the United States Real Estate Services Market determines fee structures, compliance obligations, and technology adoption patterns. Each segmentation axis reveals distinct margin profiles and competitive dynamics that shape operator strategy.
Service Type:
Client needs span discrete functional requirements from transaction execution through ongoing asset oversight.
- Residential Brokerage:Transaction facilitation for single-family and condominium sales generates volume-dependent revenue tied to mortgage rate cycles. Demand concentrates in Sun Belt metropolitan areas including Austin, Nashville, and Phoenix where population migration sustains deal flow despite interest rate volatility.
- Commercial Brokerage:Tenant representation and lease negotiation for office, retail, and industrial assets command premium fees but face cyclical sensitivity to occupancy rates. Institutional investors in major metropolitan clusters drive mandate volume for investment sales and capital markets advisory.
- Property Management:Recurring fee structures for tenant placement, maintenance coordination, and rent collection provide revenue stability insulated from transaction cyclicality. Build-to-rent residential platforms generate portfolio-scale contracts.
- Appraisal:Valuation services for mortgage origination, tax assessment, and investment due diligence face regulatory scrutiny over automated valuation model integration. State licensing requirements create jurisdictional barriers to practice mobility.
The dominant share belongs to Residential Brokerage, while Property Management is closing the gap fastest as institutional capital reallocates toward recurring revenue models.
Client Type:
Cost sensitivity and service complexity vary sharply across buyer sophistication levels and transaction frequency.
- First-time Buyers:Education-intensive segment requiring mortgage pre-qualification guidance and neighborhood orientation. Fee compression pressure intensifies as technology platforms disintermediate traditional hand-holding functions.
- Investors:Sophisticated clients prioritize portfolio analytics, 1031 exchange structuring, and property management integration. Institutional investors deploy capital into single-family rental platforms and opportunity zone vehicles.
- Sellers:Price-conscious participants increasingly select flat-fee listing services over percentage-based commission structures in high-appreciation markets. Phoenix and Nashville exhibit strongest displacement of traditional full-service representation.
- Real Estate Agents:Independent contractors broker platform access and commission splits, driving churn between cloud-based brokerages and traditional brick-and-mortar operations. Technology access and lead generation capabilities determine affiliation decisions.
Investors command the highest service premiums per transaction, though First-time Buyers generate the largest absolute headcount.
Property Type:
Physical asset characteristics dictate valuation methodologies, marketing channels, and buyer pool composition.
- Single-family Homes:Standardized product type with deep comparable sales data enabling algorithmic pricing models. Sun Belt migration patterns concentrate demand in suburban clusters around Austin, Nashville, and Phoenix.
- Multi-family Units:Apartment buildings and condominium developments attract institutional capital seeking yield compression in supply-constrained markets. Property management integration is essential for investor retention.
- Retail Spaces:Strip centers and standalone storefronts face demand disruption from e-commerce penetration. Lease structure complexity requires specialized tenant representation expertise.
- Office Buildings:Central business district assets suffer occupancy pressure from hybrid work normalization. Suburban office and life science facilities attract repositioning capital.
Single-family Homes maintain volume leadership, though Multi-family Units are expanding most quickly as rental demand outpaces homeownership affordability.
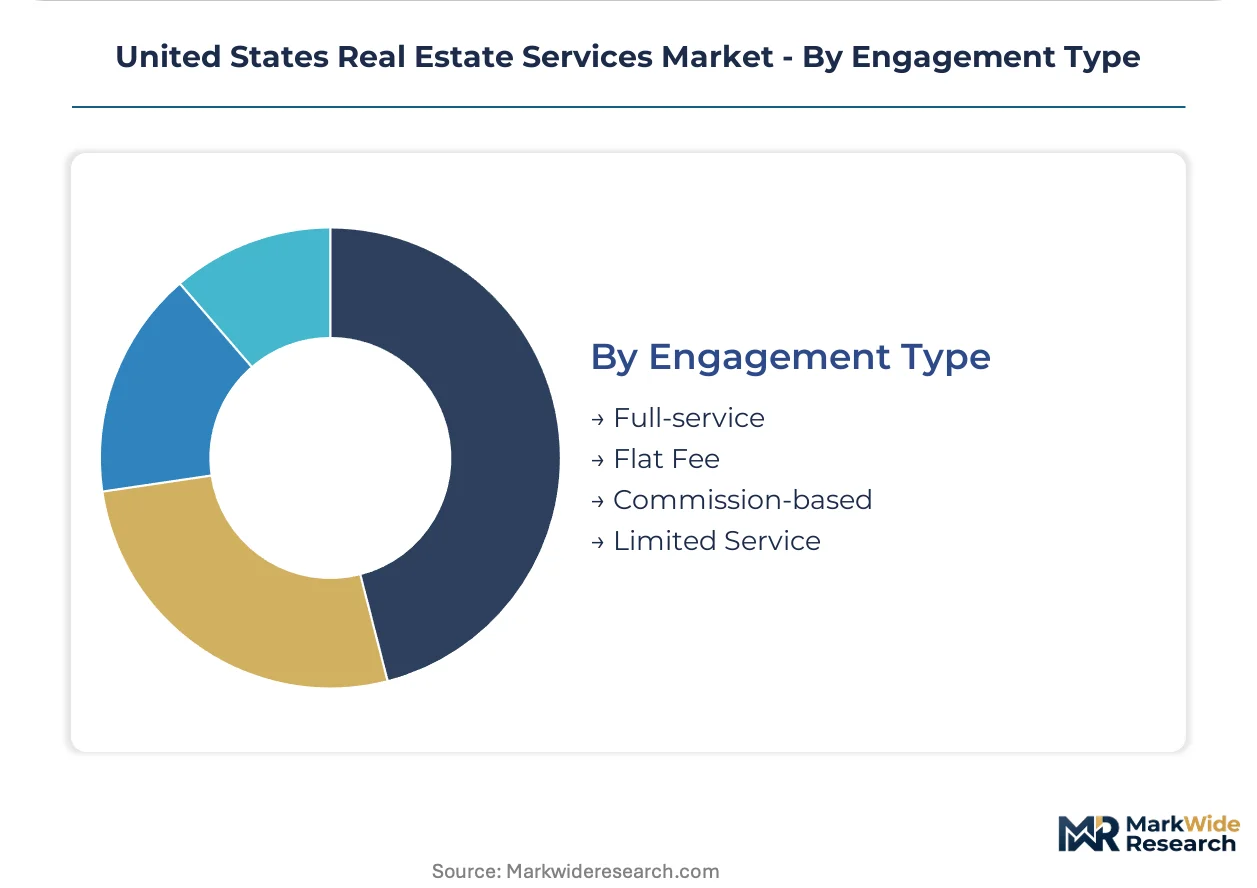
Engagement Type:
Fee structure innovation is fragmenting traditional commission models across service unbundling spectrum.
- Full-service:Comprehensive representation including pricing strategy, marketing, negotiation, and closing coordination. Traditional model faces displacement in high-volume markets where absolute commission dollars appear disproportionate to service intensity.
- Flat Fee:Fixed-price listing packages for sellers seeking cost certainty and à-la-carte service selection. Phoenix and Nashville exhibit strongest adoption among price-conscious market participants.
- Commission-based:Percentage-of-transaction compensation tied to closing price, aligning agent incentives with seller proceeds. Regulatory scrutiny of cooperative compensation structures intensifies across state real estate commissions.
- Limited Service:Discrete task engagement for document preparation or transaction facilitation without ongoing advisory support. Technology platforms enable self-directed sellers to unbundle specific functions.
Commission-based structures retain transaction value leadership, while Flat Fee models are gaining share fastest among cost-conscious sellers in high-appreciation markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transaction velocity in Austin commands fee premiums that Phoenix brokerage operations struggle to match despite comparable population inflows. This pricing-power asymmetry reflects divergent inventory constraints and institutional capital deployment patterns across Sun Belt metropolitan clusters.
Texas Triangle
Austin and Dallas-Fort Worth absorb technology sector relocations and energy corporate headquarters migrations. The Department of Housing and Urban Development's fair housing enforcement shapes broker training protocols across the state. Houston's medical center corridor attracts build-to-rent institutional investment requiring property management scale.
Southeast Atlantic
Nashville and Atlanta benefit from financial services back-office expansion and music industry consolidation. Tennessee and Georgia real estate commissions enforce distinct continuing education reciprocity limitations. Charlotte's banking sector concentration drives commercial tenant representation demand for suburban office repositioning.
Southwest Desert
Phoenix and Las Vegas experience sustained seller migration from California coastal markets seeking cost arbitrage. Arizona's Department of Real Estate administers licensing standards that restrict multi-state operator compliance efficiency. Scottsdale luxury corridors command premium appraisal workflows for jumbo mortgage origination.
Mountain West
Denver and Salt Lake City attract outdoor recreation industry employment and remote-work household formation. Colorado's energy retrofit incentive programs stimulate commercial property advisory services for green building valuation. Boise's constrained developable land sustains pricing power for listing services despite smaller absolute transaction volumes.
Pacific Northwest
Seattle and Portland face office occupancy pressure from technology sector remote-work normalization. Washington State's real estate commission scrutinizes automated valuation model integration within appraisal licensing boundaries. Bellevue's life science facility development attracts institutional capital requiring specialized investment sales expertise.
United States Real Estate Services Market Competitive Landscape
Institutional platforms and technology-enabled independents split the market between recurring-fee asset management and transaction-velocity brokerage operations. The vendor base concentrates around four archetypes: global full-service conglomerates, cloud-based agent networks, flat-fee unbundled platforms, and single-family rental operators. Consolidation through property management portfolio acquisitions and PropTech licensing partnerships dominates competitive maneuvering.
Within the institutional tier, CBRE Group and Cushman & Wakefield occupy positions anchoring global tenant representation networks. Compass exemplifies the technology-integrated brokerage archetype through proprietary mobile infrastructure deployment. eXp Realty represents the cloud-based operating model that eliminates physical office overhead to attract independent agent migration.
| Leading Market Players |
|---|
| CBRE Group |
| Cushman & Wakefield |
| Jones Lang LaSalle |
| Berkshire Hathaway HomeServices |
| RE/MAX Holdings |
| Compass |
| eXp Realty |
| Anywhere Advisors |
| Brookfield Properties |
| Others |
Value Network & Pricing Analysis
Independent agent networks in cloud-based brokerages concentrate upstream service provision, directing margin capture toward technology platform operators rather than traditional brick-and-mortar operators. This structural shift compresses commission splits while elevating software licensing fees as the primary cost anchor.
Pricing Analysis
The customization-premium spread between full-service representation and flat-fee à-la-carte packages widens in high-appreciation Sun Belt markets. Commission-based percentage structures dominate transaction value, though price differentiation stems from service bundling intensity and agent experience tier. Pricing pressure intensifies in residential brokerage as technology platforms disintermediate traditional advisory functions. First-time buyers exhibit highest price sensitivity, while institutional investors prioritize portfolio analytics over absolute fee levels.
Supply Chain Analysis
Third-party technology vendors and multiple listing service operators hold concentrated upstream capacity in real estate data infrastructure. Supply draws from specialized PropTech developers, cloud infrastructure providers, and title insurance underwriters concentrated in Texas, Arizona, and Florida. Single-source vulnerability sits with dominant MLS data aggregators controlling listing distribution. Distribution runs through licensed agent networks and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real estate services operate through a cyclical recovery phase as interest rate stabilization restores transaction velocity. Federal Reserve policy trajectory serves as the primary cyclical driver shaping buyer commitment timelines.
For Market Incumbents: Harden proprietary data assets against platform disintermediation by deepening integration with automated valuation tools. Consolidate property management portfolios to capture recurring revenue insulated from transaction cyclicality. Agent retention friction from low switching barriers threatens revenue pipeline stability.
For New Entrants and Emerging Players: Build-to-rent residential platforms in Nashville and Phoenix represent the most penetrable entry point for institutional capital deployment. Flat-fee listing services in high-appreciation suburban clusters offer secondary white-space opportunity. A technology-enabled agent productivity platform serves as the optimal go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed property management roll-ups seeking geographic density. Long-term viability across a decade-long window favors operators with recurring-fee revenue models over transaction-dependent brokerages. The signal to watch is institutional capital allocation shifts between commercial office repositioning and residential rental platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| PropTech Platform Integration | Cloud-based infrastructure from eXp Realty eliminates physical office overhead and attracts agent migration. |
| Property Management Portfolio Acquisition | Build-to-rent contracts with institutional investors generate recurring revenue insulated from transaction cyclicality. |
| Automated Valuation Model Deployment | AI-driven analytics reshape appraisal workflows and capture institutional mandates requiring speed and scale. |
| Flat-Fee Service Unbundling | À-la-carte pricing packages in Phoenix and Nashville displace traditional percentage-based commission structures. |
| Opportunity Zone Advisory Expansion | Federal tax deferral incentives attract capital into distressed areas, commanding premium compliance fees. |
Research Methodology
The analysis maps residential brokerage, commercial brokerage, property management, and appraisal segments, each validated through managing brokers, institutional asset managers, MLS administrators, and state real estate commission officials. Primary interviews with property technology executives and investment sales directors combined with secondary validation from HUD enforcement records, SEC investment adviser filings, and state licensing databases. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchored the market sizing framework.
Assumptions held fixed include state-level licensing reciprocity limitations and fair housing enforcement intensity, while interest rate trajectories and Sun Belt migration patterns varied across scenarios. Segmentation dimensions modeled encompass service type, client sophistication tier, property physical characteristics, and engagement fee structure. CAGRs derived from historical transaction velocity correlation with mortgage rate cycles and population flow data. Green building retrofit incentive utilization and hybrid work normalization served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in mortgage rate volatility and technology sector employment concentration would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and PropTech adoption curves. Quarterly review of Federal Reserve policy signals and institutional capital allocation flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
US Home Service Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
Green Lease Market