
 Home Warranty Service Market | 2026-2036
Home Warranty Service Market Size, Share, and Industry Trends Forecast 2026-2036
Home Warranty Service Market Foresight
Modular plan bundling is pivoting how consumers evaluate protection options. American Home Shield leverages its scale to offer tiered combinations of appliance and system coverage. Liberty Home Guard competes through flexible add-on structures that accommodate smart device integration. Cinch Home Services anchors its positioning around streamlined digital claims workflows.
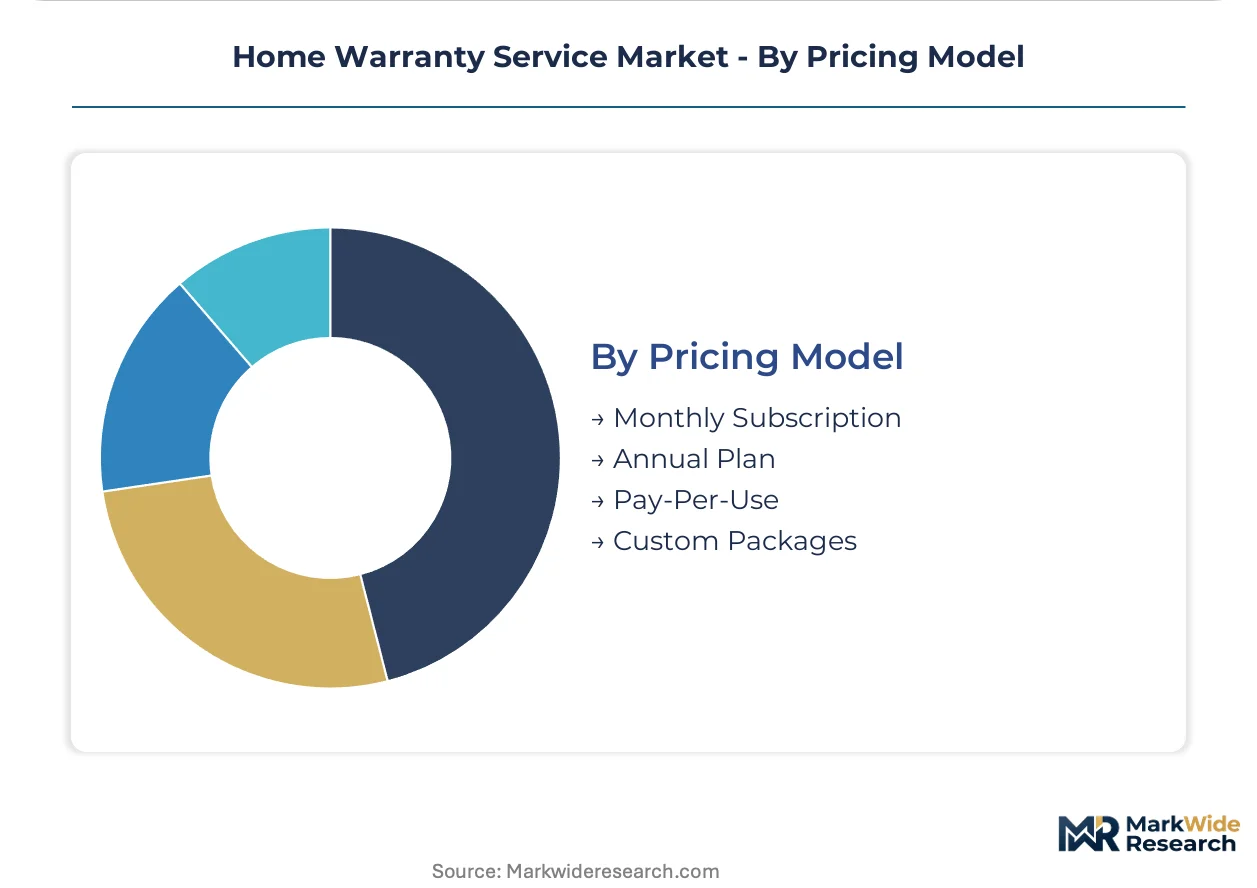
Home warranty service constitutes a contractual repair and replacement agreement covering major household systems and appliances against normal wear failure, typically spanning HVAC, electrical, plumbing, and kitchen equipment with defined coverage caps and service fee structures. The primary commercial purpose centers on transferring unpredictable maintenance cost risk from property owners to underwritten service providers in exchange for fixed periodic premiums. Appliance Coverage dominates transaction volume among service type segments due to universal household penetration of refrigerators, dishwashers, and laundry equipment. Combination Plans capture expanding margin pools as real estate agents bundle closing incentives with multi-year protection terms. Monthly Subscription pricing is accelerating fastest among models as younger homeowners prioritize cash-flow flexibility over annual commitments.
State insurance commissioners across California, Texas, and Florida enforce solvency and contract disclosure standards that shape provider operating requirements and consumer recourse pathways. The Federal Trade Commission monitors marketing representations and cancellation practices under broad consumer protection authority. Service contract legislation in Arizona and Nevada imposes specific reserve and claim-response timing mandates. Stakeholders must monitor evolving state-level regulatory divergence and smart home data privacy obligations as connected device integration deepens.
Market Dynamics
Smart home device proliferation is forcing warranty providers to retool coverage frameworks around connected HVAC, water heaters, and security systems rather than standalone mechanical failure models.
Growth Catalysts
- First-Time Buyer Protection Mandates:Several US states now require disclosure of home warranty availability at closing, converting passive awareness into active evaluation moments.
- FTC Marketing Oversight:The Federal Trade Commission's intensified scrutiny of cancellation practices and claim denial transparency is elevating trust metrics among skeptical consumers.
- Contractor Cost Escalation:Skilled trade labor shortages in Texas and Florida are amplifying the value proposition of fixed-fee repair coverage against volatile market-rate technician dispatch.
Market Restraints
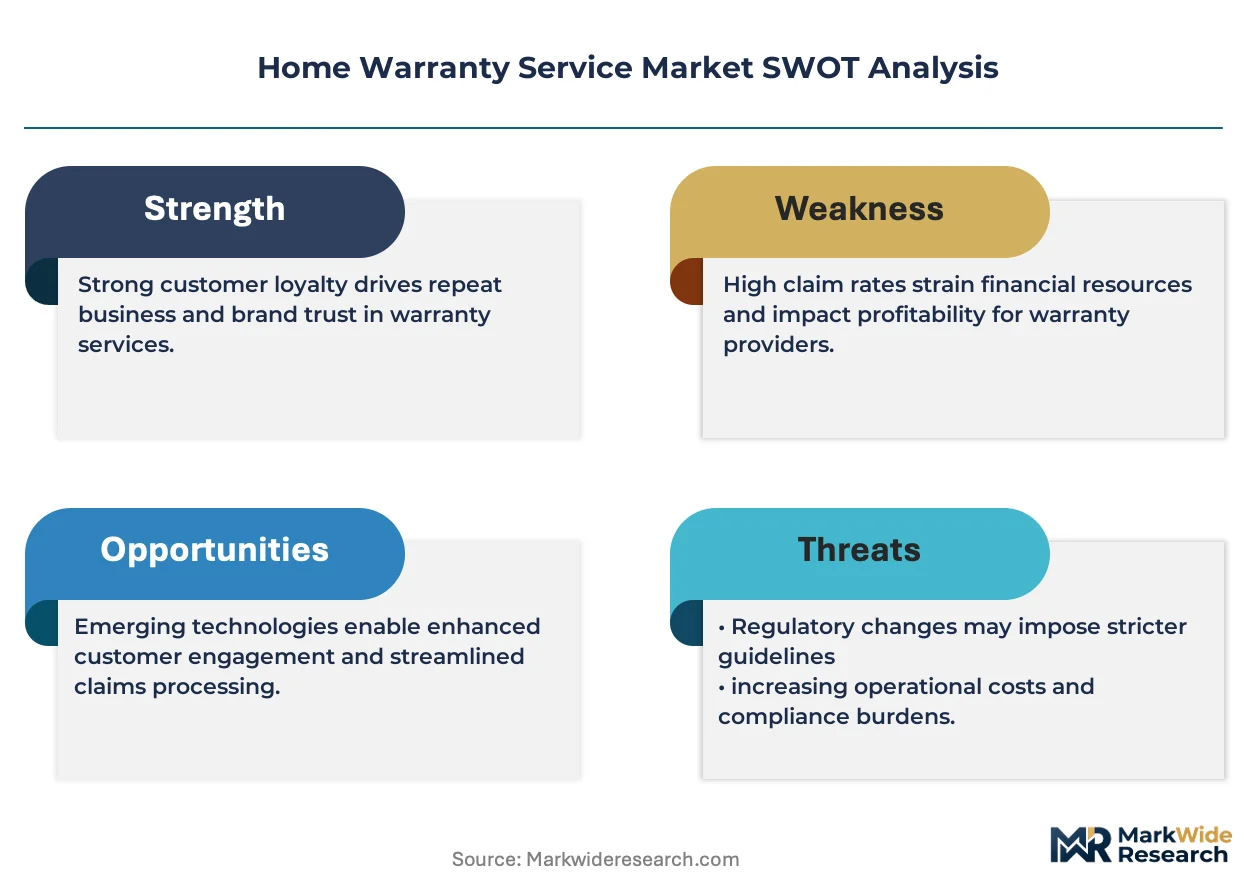
- Reserve Solvency Requirements:Arizona and Nevada impose minimum capital reserve ratios that constrain smaller entrants' geographic expansion capacity.
- Claim Cost Volatility:Refrigerant phase-down regulations under EPA mandates are compressing HVAC replacement margins as R-410A equipment sunsets.
- DIY Repair Substitution:YouTube-tutorial-enabled homeowners in sub-10-year housing stock increasingly self-remediate minor appliance failures.
Strategic Opportunities
- Smart-Home Data Monetization:Predictive maintenance algorithms using IoT sensor feeds from water heaters and HVAC units enable pre-failure intervention.
- Multi-Year Real Estate Bundles:Combination plans attached to mortgage closing packages in California and Texas lock in extended customer lifecycles.
- State-Level Regulatory Arbitrage:Service contract legislation gaps in Midwestern states permit faster product iteration than coastal compliance environments.
Industry Challenges
- Legacy System Integration:Older claims management platforms require costly API development to connect with smart device telemetry feeds.
- Licensed Technician Scarcity:HVAC and electrical certification pipelines in Sun Belt markets cannot match dispatch volume demands during peak seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Warranty Service Market |
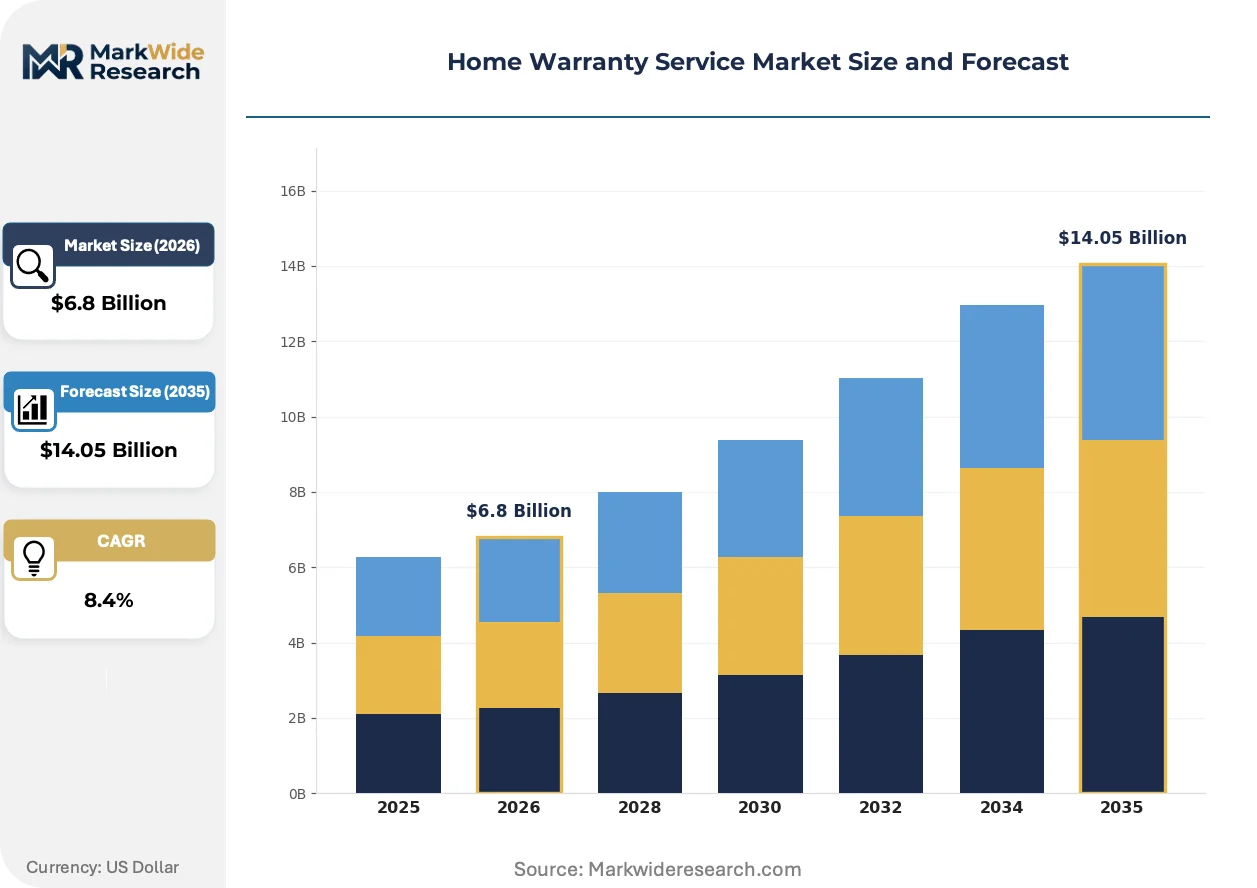
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Appliance Coverage, System Coverage, Combination Plans, Additional Services Customer Type: Homeowners, Real Estate Agents, Property Managers, Investors Distribution Channel: Online Sales, Direct Sales, Brokers, Retail Pricing Model: Monthly Subscription, Annual Plan, Pay-Per-Use, Custom Packages |
| Companies Covered | Liberty Home Guard, 2-10 Home Buyers Warranty, American Home Shield, Select Home Warranty, AFC Home Warranty, Cinch Home Services, Old Republic Home Protection, Choice Home Warranty, First American Home Warranty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Warranty Service Market Shifts & Advancements
Digital claims infrastructure is compressing resolution timelines from days to hours. Providers are racing to embed predictive analytics and automated contractor dispatch into core service delivery.
Artificial intelligence-driven diagnostic tools are integrating remote troubleshooting capabilities into standard warranty workflows. First-time homebuyers in Texas and Florida now expect chatbot-initiated claims and photo-based damage assessment. This technology is integrating self-service portals with live technician dispatch, reducing call center dependency.
The Federal Trade Commission's 2024 guidance on subscription cancellation transparency is reshaping contract term structures. Providers must now offer prorated refund mechanisms and single-click termination portals. Monthly subscription models in California are adapting fastest to these disclosure mandates.
Millennial and Gen Z homeowners are abandoning annual prepaid contracts for month-to-month flexibility. Digital-native buyers in Arizona and Nevada prioritize cash-flow management over bulk discount incentives. This behavioral pivot is forcing incumbents to restructure pricing architectures around subscription retention metrics rather than upfront premium collection.
Home Warranty Service Market Segmentation
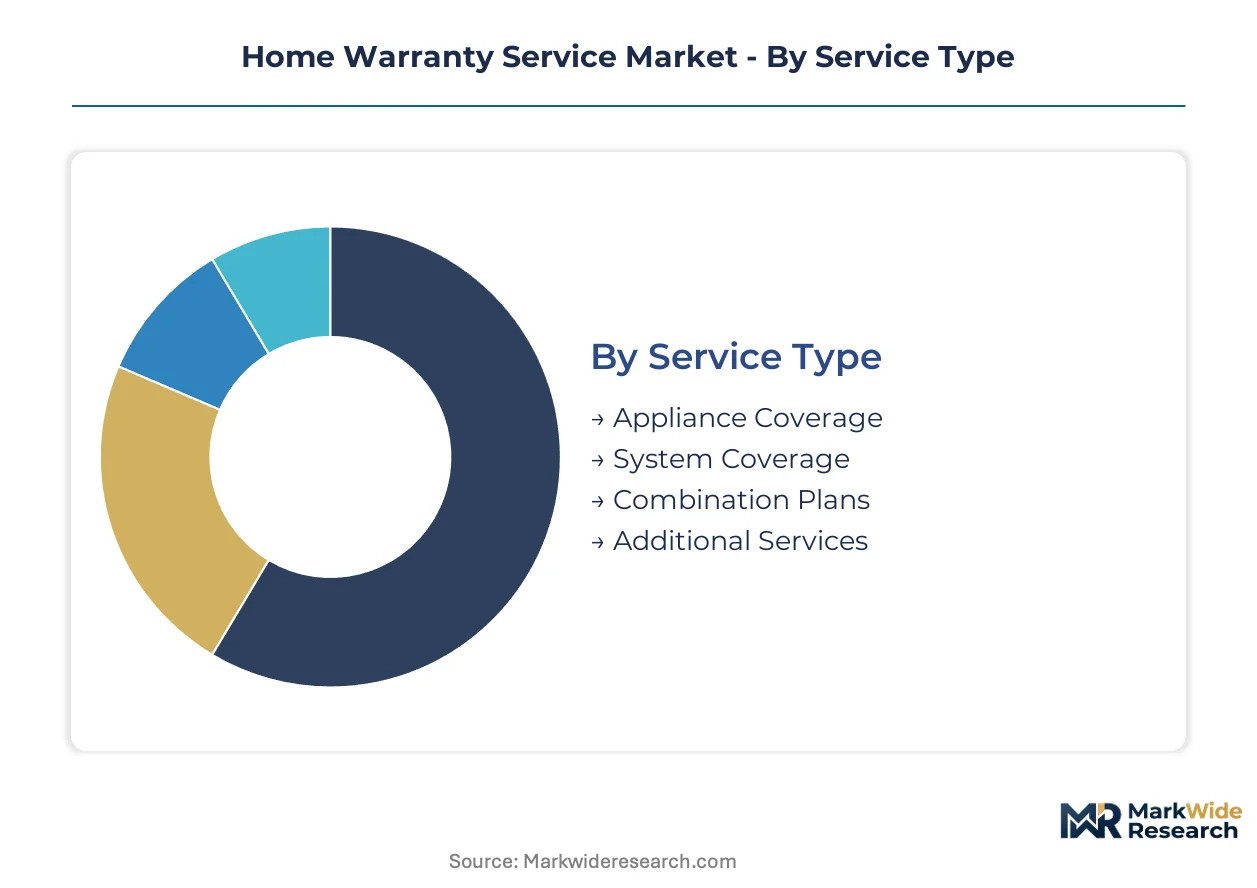
Home warranty segmentation reveals how protection products align with distinct risk-transfer needs and purchasing contexts. Structural differences in coverage scope, buyer sophistication, and transaction mechanics create four parallel category systems that providers must navigate simultaneously.
Service Type:
Standalone coverage products serve discrete protection needs while bundled configurations embed warranty value into broader property transactions.
- Appliance Coverage:Protection contracts for refrigerators, dishwashers, laundry equipment, and cooking appliances against mechanical and electrical failure. Demand clusters among first-time homebuyers in Texas and Florida seeking predictable replacement costs for high-frequency-use equipment. The FTC's intensified marketing oversight has elevated disclosure standards for appliance-specific claim limits.
- System Coverage:Contracts addressing HVAC, electrical, plumbing, and water heater failures arising from normal wear. Arizona and Nevada contractors report accelerating dispatch volumes for system coverage holders facing refrigerant phase-down cost spikes. Skilled technician scarcity in Sun Belt markets compresses resolution timelines for these high-complexity repairs.
- Combination Plans:Bundled appliance and system protection with unified service fee structures and coverage caps.
- Additional Services:Optional riders covering pools, spas, septic systems, and smart home devices beyond standard contract terms.
Volume placements concentrate in Appliance Coverage; the faster expansion belongs to Combination Plans.
Customer Type:
Purchasing sophistication varies sharply across buyer categories, from individual risk-averse homeowners to institutional portfolio managers seeking operational cost predictability.
- Homeowners:Individual property occupants purchasing direct-to-consumer protection for primary residences. California and Texas millennials are migrating this segment toward monthly subscription structures that preserve cash-flow flexibility over annual prepaid commitments.
- Real Estate Agents:Licensed professionals bundling warranty contracts into closing packages as buyer incentives. Several states now mandate warranty availability disclosure at closing, converting agent-driven placements from discretionary add-ons to transaction-standard expectations.
- Property Managers:Multi-unit operators securing portfolio-level coverage for rental property maintenance cost control.
- Investors:Single-family rental and fix-and-flip operators using warranty protection to reduce holding-period capital exposure.
Transaction frequency peaks with Real Estate Agents; margin sustainability favors Property Managers.
Distribution Channel:
Channel selection determines customer acquisition economics and claims servicing infrastructure requirements.
- Online Sales:Direct digital enrollment through provider websites and comparison platforms. Arizona and Nevada digital-native buyers expect chatbot-initiated claims and photo-based damage assessment workflows.
- Direct Sales:Provider-controlled telephone and field sales operations targeting renewal and upgrade conversions.
- Brokers:Independent intermediaries aggregating multiple carrier offerings for consumer comparison.
- Retail:Point-of-sale placements through home improvement retailers and appliance dealers.
Customer lifetime value concentrates in Direct Sales; channel cost efficiency is climbing fastest in Online Sales.
Pricing Model:
Payment structure preferences reflect demographic cash-flow priorities and risk tolerance variations.
- Monthly Subscription:Recurring billing with cancellation flexibility and no long-term commitment. The FTC's 2024 subscription transparency guidance is forcing prorated refund mechanisms and single-click termination portals for this fastest-climbing model.
- Annual Plan:Prepaid twelve-month contracts with modest premium discounts over monthly equivalents.
- Pay-Per-Use:Per-incident service fees without ongoing premium obligations.
- Custom Packages:Negotiated terms for high-value properties or multi-unit portfolios with non-standard coverage requirements.
Revenue predictability concentrates in Annual Plans; subscriber growth velocity is expanding most quickly in Monthly Subscription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home warranty service provision concentrates in consumer markets with aging housing stock and elevated repair labor costs. Demand generation flows through real estate transaction channels and direct-to-consumer digital enrollment. Regulatory frameworks vary sharply across state-level jurisdictions.
United States
California, Texas, and Florida dominate transaction volume through first-time homebuyer protection mandates and aging residential infrastructure. The Federal Trade Commission enforces subscription cancellation transparency and marketing disclosure standards. Phoenix and Las Vegas anchor Sun Belt growth corridors where contractor scarcity amplifies fixed-fee coverage value.
Canada
Ontario and British Columbia concentrate demand among condominium owners seeking protection against shared-system failures. Provincial consumer protection statutes govern contract cancellation rights and cooling-off periods. Toronto's competitive real estate market embeds warranty offerings into standard closing documentation.
United Kingdom
England's new-build sector drives structural warranty adoption through developer-mandated coverage periods. The Financial Conduct Authority oversees insurance-backed product distribution and disclosure requirements. London's property transaction volume sustains broker-intermediated placement channels.
Australia
New South Wales and Victoria exhibit elevated uptake among strata-titled apartment owners facing collective maintenance liabilities. State-level building commission regulations enforce warranty provider financial capacity standards. Sydney's high property turnover sustains real estate agent-driven bundling practices.
Germany
Bavaria and North Rhine-Westphalia concentrate demand among rental property investors seeking operational cost predictability. The Federal Financial Supervisory Authority monitors insurance-linked product structures. Munich's premium housing market supports extended warranty terms for high-value appliance portfolios.
Home Warranty Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. National-scale providers leverage brand recognition and contractor network density against regional challengers emphasizing localized service responsiveness. Two strategic archetypes dominate: integrated real estate service platforms and standalone warranty underwriters. Consolidation through acquisition and technology platform modernization represent the primary competitive vectors.
Among scale-driven national providers, American Home Shield, Liberty Home Guard, and Cinch Home Services occupy positions exemplifying divergent strategic postures. American Home Shield represents the diversified service conglomerate archetype with broad contractor network infrastructure. Liberty Home Guard exemplifies flexible product architecture accommodating smart home integration. Cinch Home Services anchors the digital-native positioning vector emphasizing streamlined claims workflow automation.
| Leading Market Players |
|---|
| Liberty Home Guard |
| 2-10 Home Buyers Warranty |
| American Home Shield |
| Select Home Warranty |
| AFC Home Warranty |
| Cinch Home Services |
| Old Republic Home Protection |
| Choice Home Warranty |
| First American Home Warranty |
| Others |
Supply & Pricing Matrix
EPA refrigerant phase-down mandates gate qualified HVAC technician supply and premium-tier pricing access for R-410A replacement coverage. Service providers absorbing elevated equipment costs must recalibrate tiered pricing structures or cede margin to compliant competitors with forward-contracted refrigerant inventories.
Pricing Analysis
Margin tightening in standard-tier plans reflects contractor labor scarcity across Texas and Florida Sun Belt corridors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by claim-response speed and coverage cap generosity. Certification-grade differentiation separates American Home Shield's master technician network from discount competitors relying on generalist dispatch pools. DIY-enabled millennials in sub-10-year housing stock exhibit highest price sensitivity; institutional property managers purchasing portfolio-level coverage show lowest.
Supply Chain Analysis
Direct-to-homeowner digital channels handle fastest-growing subscription volumes in Arizona and Nevada. Licensed technician supply concentrates in California, Texas, and Florida where state certification pipelines face Sun Belt demand surges. Raw material dependencies span copper refrigerant lines, compressor motors, and smart sensor arrays. Single-source vulnerability sits with EPA-regulated refrigerant suppliers facing phasedown deadlines. Distribution runs through captive contractor networks, broker intermediaries, and real estate closing bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FTC subscription transparency mandates and state-level reserve requirements erect barrier-to-entry moats for capitalized incumbents.
For Market Incumbents: Deepen predictive maintenance algorithm development using IoT telemetry from water heaters and HVAC units to compress claim frequency. Fortify captive technician networks in Phoenix and Las Vegas corridors where dispatch scarcity threatens service-level agreements. Acquire distressed regional underwriters in Midwestern states with lighter service contract legislation to secure regulatory arbitrage positioning. For New Entrants and Emerging Players: AI-driven remote diagnostic platforms offer technology-first wedge into millennial homeowner segments abandoning annual prepaid contracts. White-space concentrates in month-to-month subscription models with single-click cancellation portals mandated by FTC guidance. Target Arizona and Nevada digital-native buyers through chatbot-initiated claims workflows absent from legacy provider infrastructure. For Investors and Strategic Acquirers: FTC enforcement actions against cancellation-practice violators are the leading indicator that compliant subscriber bases command valuation premiums. Long-term viability favors underwriters with state-level reserve adequacy across California, Texas, and Florida rather than thinly capitalized discount competitors. Monitor EPA refrigerant inventory positions as inflection signal for HVAC replacement margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | IoT sensor integration enables pre-failure intervention, reducing claim severity for water heater and HVAC coverage. |
| Multi-Year Real Estate Bundle Expansion | California and Texas mortgage closing packages lock in extended customer lifecycles beyond direct-to-consumer churn. |
| Smart Home Device Rider Introduction | Connected security and climate system coverage captures younger homeowners prioritizing technology protection. |
| Licensed Technician Network Acquisition | Captive HVAC and electrical certification pipelines in Sun Belt markets secure dispatch capacity during peak seasons. |
| State Regulatory Arbitrage Positioning | Midwestern service contract legislation gaps permit faster product iteration than coastal compliance environments. |
Research Methodology
SEC 10-K filings, state insurance commissioner solvency reports, and FTC consumer protection enforcement records formed the secondary backbone. Primary interviews with home warranty underwriters, licensed HVAC contractors, real estate closing coordinators, and property management executives combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated state-level transaction volumes, premium pricing tiers, and claim frequency data across the projection horizon. Segmentation dimensions spanned service type, customer archetype, distribution channel, and pricing model. CAGRs derived from fitted growth curves incorporating first-time homebuyer transaction flows and smart home device penetration trajectories. Contractor cost escalation indices and refrigerant phase-down regulatory schedules served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including catastrophic weather event frequency, federal preemption of state service contract legislation, and macroeconomic housing turnover collapse. Forecasts reflect documented assumptions about regulatory stability and labor market tightness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Global Home Services Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Green Lease Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
US Home Service Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Latin America Coworking Spaces Market