
 Canada Real Estate Services Market | 2026-2036
Canada Real Estate Services Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Real Estate Services Market Outlook
Multi-source brokerage engagement is repositioning how Canadian institutional clients procure real estate advisory. Colliers International Group leverages its integrated valuation and investment management platform to anchor large-format commercial mandates. Royal LePage sustains nationwide residential coverage through its franchise network, while Altus Group differentiates via proprietary data analytics serving pension fund due diligence.
Real estate services encompass transaction brokerage, asset valuation, property management, and development advisory delivered across physical asset classes with fiduciary duty standards and appraisal methodology governed by the Appraisal Institute of Canada. These functions enable capital allocation, occupancy optimization, and risk-adjusted returns for owners and occupiers. Residential sales and property management command the deepest revenue pools, while commercial leasing generates premium fee structures in gateway cities. Land development services attract specialized demand as municipalities intensify zoning approvals for mixed-use projects.
The Office of the Superintendent of Financial Institutions shapes mortgage qualification thresholds that directly filter transaction volumes into residential sales channels. The Canada Mortgage and Housing Corporation influences liquidity conditions and multi-unit development financing, while provincial real estate councils enforce licensing standards that govern market access for brokerage professionals. Stakeholders must track how coordinated federal-provincial housing supply targets recalibrate development service demand across metropolitan planning boundaries.
Market Dynamics
The Office of the Superintendent of Financial Institutions stress-test mortgage rules are compressing residential transaction volumes and redirecting capital flows toward commercial leasing and property management services. Institutional investors are reallocating portfolios into income-generating assets as yield-seeking behavior intensifies across Canadian metropolitan corridors.
Growth Catalysts
- Institutional capital reallocation:Pension funds and insurance asset managers are expanding direct property management mandates to capture stabilized cash flows from multi-unit residential and logistics facilities.
- Federal housing supply targets:Coordinated provincial-municipal zoning intensification programs are accelerating land development advisory demand for mixed-use projects in transit-oriented corridors.
- Technology-enabled valuation platforms:Automated valuation models integrated with municipal assessment databases are compressing due diligence timelines for commercial mortgage underwriting.
Market Restraints
- Interest rate sensitivity:Bank of Canada policy rate adjustments directly filter through to mortgage qualification thresholds, constraining first-time buyer participation in residential sales channels.
- Interprovincial licensing friction:Provincial real estate councils maintain non-reciprocal licensing standards that limit brokerage professional mobility between Ontario, British Columbia, and Alberta markets.
- Construction cost volatility:Lumber and concrete input price fluctuations are compressing development pro forma margins and delaying project financing commitments.
Strategic Opportunities
- Secondary market penetration:Calgary and Edmonton office-to-residential conversion pipelines present untapped demand for specialized repositioning advisory as remote work patterns stabilize.
- Environmental certification integration:Canada Green Building Council Zero Carbon Building standards are creating premium fee structures for sustainability consulting tied to asset valuation and disclosure requirements.
- PropTech-enabled tenant experience platforms:Smart building systems convergence with lease administration software is opening recurring revenue streams in property management beyond traditional percentage-based fees.
Industry Challenges
- Appraiser credential scarcity:Accredited Appraisal Institute of Canada designations require multi-year experience thresholds that lag current demand for commercial valuation expertise in gateway cities.
- Legacy system integration costs:Brokerage back-office migration from on-premise transaction management to cloud-based customer relationship platforms demands capital outlays that strain mid-size franchise operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Real Estate Services Market |
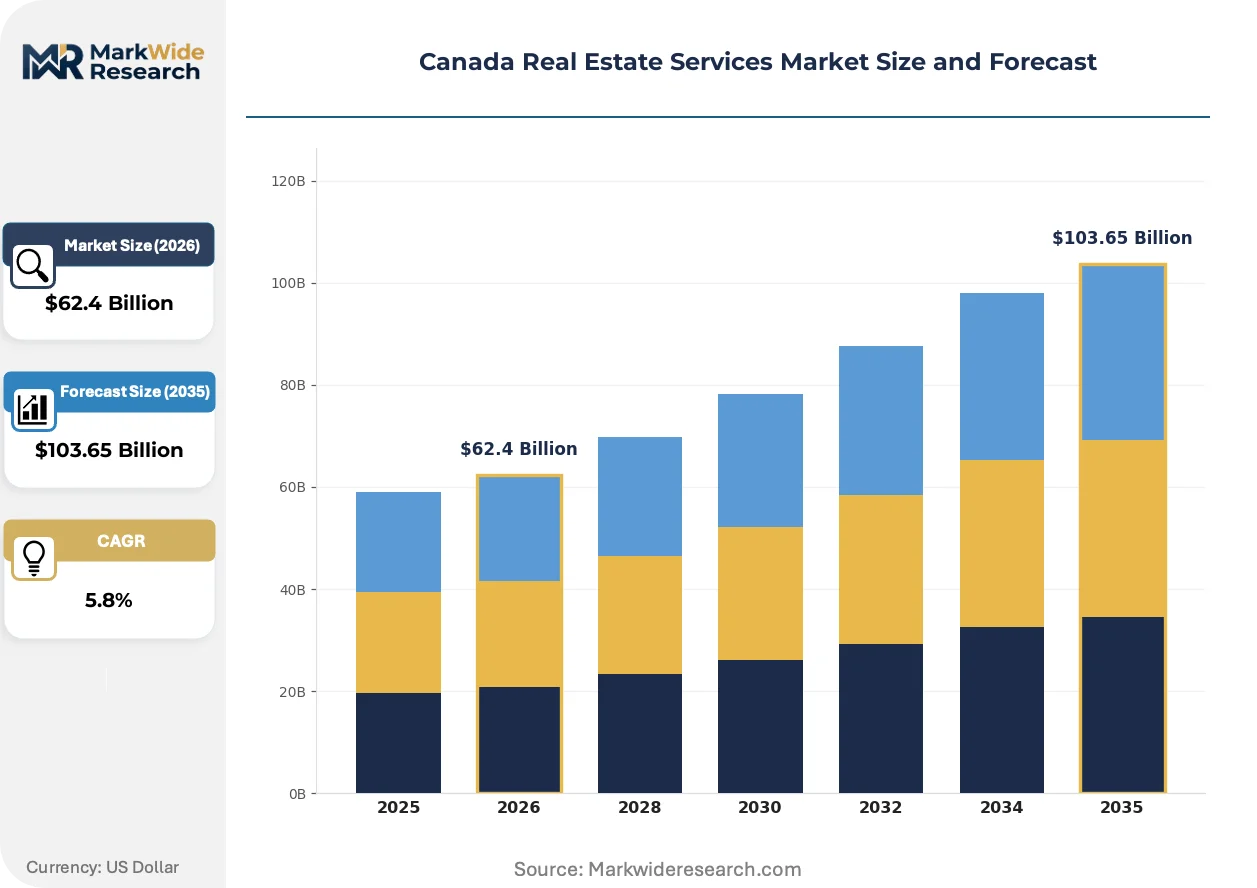
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Sales, Commercial Leasing, Property Management, Land Development Client Type: First-Time Buyers, Investors, Corporations, Non-Profits Property Type: Single-Family Homes, Condominiums, Office Buildings, Retail Spaces Market Segment: Urban Areas, Suburban Developments, Rural Properties, Luxury Estates |
| Companies Covered | Altus Group, Royal LePage, FirstService Corporation, Choice Properties Real Estate Investment Trust, QuadReal Property Group, Colliers International Group, RE/MAX Canada, Chartwell Retirement Residences, Brookfield Office Properties, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Real Estate Services Market Strategic Shifts
Digital transaction infrastructure and data-centric advisory models are compressing traditional service timelines while elevating transparency expectations among institutional clients. Three convergent developments are restructuring competitive positioning across brokerage, valuation, and property management functions.
Artificial intelligence-powered comparable analysis tools are overtaking manual market research workflows in commercial investment sales. Pension fund acquisition teams are adopting these platforms for preliminary underwriting, compressing the traditional broker-led information asymmetry that historically anchored fee premiums. The structural consequence is fee compression in standard lease and sale transactions while specialized advisory around complex assets commands widening premiums.
Canada Mortgage and Housing Corporation enhanced disclosure requirements for multi-unit residential financing are elevating energy performance data in loan approval criteria. Developers must now integrate utility benchmarking into pro forma submissions, accelerating demand for building performance consultants alongside traditional quantity surveyors. British Columbia and Ontario projects with embedded carbon accounting are securing preferential financing terms, reshaping pre-construction advisory service bundles.
Institutional buyers are consolidating vendor relationships through single-source property management and leasing mandates rather than fragmented local brokerage panels. This concentration pattern is displacing transaction-based fee structures with multi-year service contracts incorporating performance benchmarks for occupancy and net operating income. The shift is most visible in Toronto and Vancouver industrial and multi-residential assets where ownership has concentrated among REITs and sovereign wealth vehicles.
Canada Real Estate Services Market Segmentation
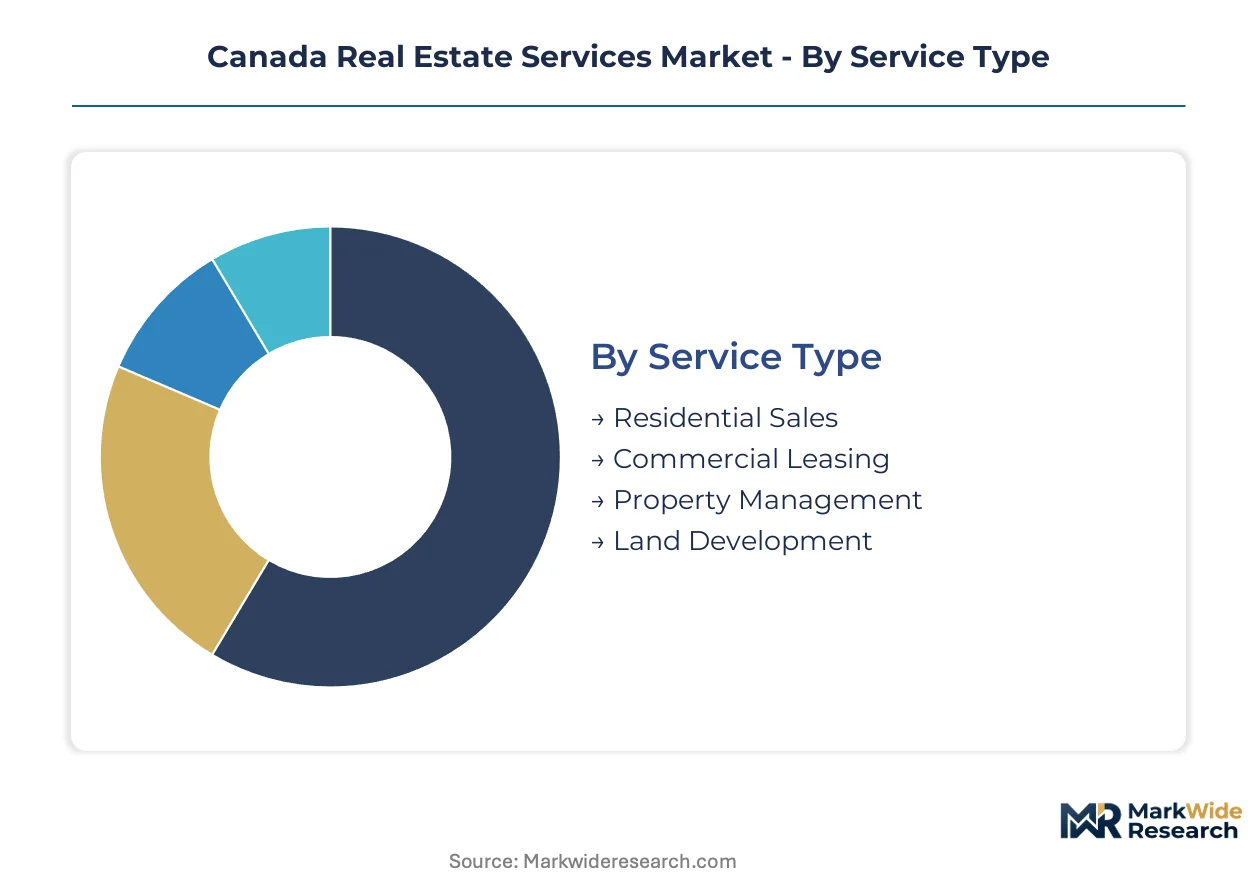
Segmentation reveals how capital allocation patterns and regulatory pressures fragment the Canadian real estate services landscape across distinct service lines, client risk profiles, and asset classes. Understanding these divisions exposes where fee compression intensifies and where specialized advisory commands premium pricing.
Service Type:
Supply concentration among integrated national platforms shapes competitive intensity across service categories, with scale advantages clustering in property management and commercial leasing functions.
- Residential Sales:Transaction brokerage for single-family and condominium transfers governed by provincial licensing standards. Demand concentrates in the Greater Toronto Area and Vancouver corridors where Office of the Superintendent of Financial Institutions mortgage stress-test rules filter buyer qualification volumes.
- Commercial Leasing:Tenant representation and landlord advisory for office, retail, and industrial assets. Toronto and Vancouver gateway markets generate premium fee structures as institutional owners consolidate vendor relationships into multi-year mandates.
- Property Management:Ongoing operations oversight for multi-unit residential and commercial assets. Pension fund direct ownership models are expanding internalized property management capacity to capture stabilized cash flows.
- Land Development:Advisory on zoning, entitlements, and construction phasing for greenfield and intensification projects. Federal-provincial housing supply targets are accelerating demand in transit-oriented Ontario and British Columbia corridors.
Property Management absorbs the bulk of installed capacity; Land Development is expanding most quickly.
Client Type:
Cost tier differentiation separates transaction-based retail brokerage from retainer-based institutional advisory, with fee structures diverging sharply across risk tolerance and asset scale.
- First-Time Buyers:Entry-level residential purchasers navigating mortgage qualification thresholds and down payment assistance programs. Bank of Canada rate adjustments directly constrain participation volumes in Ontario and British Columbia entry markets.
- Investors:Individual and small-scale portfolio owners seeking yield through rental properties or value-add repositioning. Calgary and Edmonton office-to-residential conversion pipelines attract specialized repositioning advisory demand.
- Corporations:Occupier clients and institutional owners with complex lease administration and portfolio optimization requirements. REITs and sovereign wealth vehicles are consolidating vendor relationships through single-source property management mandates.
- Non-Profits:Affordable housing developers and community land trusts accessing subsidized financing and municipal incentive programs. Canada Mortgage and Housing Corporation multi-unit financing criteria shape service demand for this segment.
Corporations command the deepest fee pools; Investors are gaining share fastest as yield-seeking behavior intensifies.
Property Type:
Application-specific valuation methodologies and leasing protocols create distinct competency requirements across physical asset categories, with credential scarcity most acute in complex commercial segments.
- Single-Family Homes:Detached and semi-detached residential assets transacted through multiple listing service platforms. Franchise brokerage networks sustain nationwide coverage through localized agent relationships.
- Condominiums:Stratified ownership structures requiring specialized status certificate review and corporation governance advisory. Toronto and Vancouver high-rise concentrations drive transaction velocity in this segment.
- Office Buildings:Class A, B, and C commercial assets facing occupancy pressure from remote work normalization. Secondary market repositioning opportunities in Calgary and Edmonton are attracting development advisory demand.
- Retail Spaces:Street-front and enclosed mall assets adapting to e-commerce disruption and experiential tenant mix strategies. Urban intensification policies are accelerating mixed-use retail-residential project approvals.
Single-Family Homes sustain the highest transaction frequency; Office Buildings face the steepest repricing pressure.
Market Segment:
Geographic stratification across metropolitan density gradients determines regulatory exposure and development service demand, with municipal zoning authority fragmenting market conditions provincially.
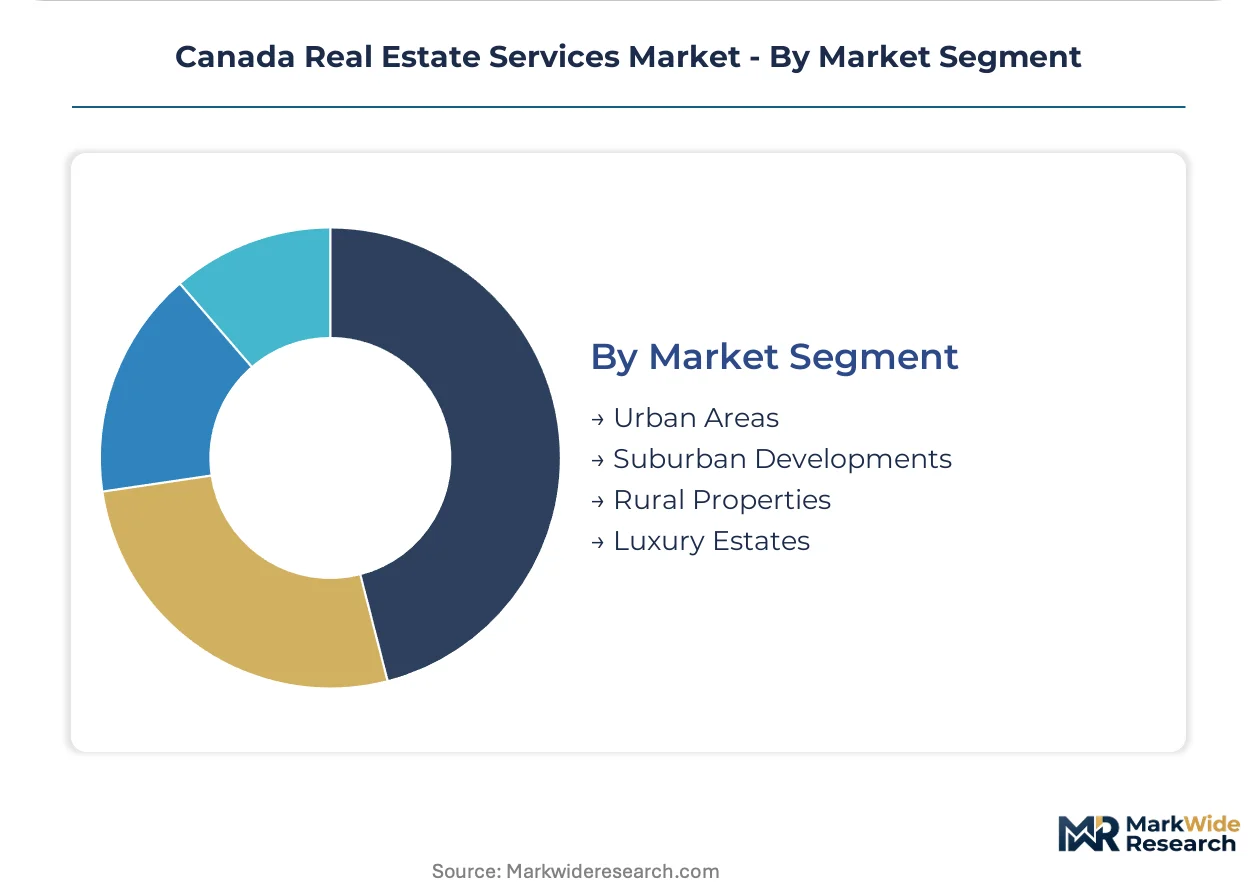
- Urban Areas:Core metropolitan zones with intensification mandates and transit-oriented development priorities. Vancouver and Toronto municipal zoning approvals are accelerating land development advisory for mixed-use projects.
- Suburban Developments:Greenfield and infill residential expansion corridors beyond core city boundaries. Provincial growth plans in Ontario and British Columbia are redirecting development activity to designated settlement areas.
- Rural Properties:Agricultural, recreational, and remote residential assets with limited transaction liquidity and specialized valuation requirements. Interprovincial licensing friction constrains brokerage professional mobility in these markets.
- Luxury Estates:High-value residential assets requiring privacy-focused marketing and cross-border buyer networks. British Columbia speculation and vacancy taxes have altered demand composition in this segment.
Urban Areas concentrate institutional capital deployment; Suburban Developments are climbing the fastest on housing supply target alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Ontario and British Columbia metropolitan corridors where institutional capital deployment and federal housing policy intersect. Provincial growth plans and municipal zoning authority fragment service demand across distinct regulatory environments.
Ontario
The Greater Toronto Area anchors transaction velocity for residential sales and commercial leasing services. The provincial growth plan redirects development activity to designated settlement areas outside core boundaries. Toronto's transit-oriented intensification mandates accelerate land development advisory for mixed-use projects along commuter rail corridors.
British Columbia
Vancouver's high-rise condominium concentration drives specialized strata governance advisory and status certificate review demand. The speculation and vacancy tax alters demand composition in luxury residential segments. Metro Vancouver municipal zoning approvals for density bonusing reshape developer service procurement patterns.
Alberta
Calgary and Edmonton office-to-residential conversion pipelines attract repositioning advisory as remote work patterns stabilize. The provincial energy sector downturn redirects commercial brokerage focus toward industrial logistics and multi-residential assets. Downtown Calgary vacancy rates compress leasing fee structures while creating value-add opportunities.
Quebec
Montreal's institutional ownership concentration expands property management mandates among pension fund direct investment platforms. The provincial language charter influences brokerage professional licensing and service delivery standards. Greater Montreal's industrial land scarcity elevates development advisory fees for infill logistics projects.
Atlantic Canada
Halifax population growth outpaces historical migration patterns, intensifying residential sales channel demand. Federal immigration targets redirect housing supply planning toward multi-unit rental construction. The interprovincial licensing friction limits brokerage professional mobility from Ontario and Quebec into these markets.
Canada Real Estate Services Market Competitive Environment
Portfolio diversification dominates the current landscape as integrated platforms absorb specialized advisory functions. The market structures around three tiers: national integrated platforms with valuation and investment management capabilities, franchise brokerage networks with localized agent relationships, and specialized property management operators serving institutional direct ownership models. Strategic archetypes include scale-driven full-service providers, technology-enabled data analytics specialists, and yield-focused income property operators. M&A activity and vertical integration into adjacent advisory functions represent the dominant competitive moves reshaping vendor relationships.
Among national integrated platforms, Colliers International Group and Altus Group exemplify the convergence of transaction brokerage with proprietary data infrastructure. Royal LePage occupies a position within the franchise-network tier, sustaining coverage through localized agent relationships rather than centralized service delivery. These three anchors illustrate how scale advantages cluster in property management and commercial leasing while residential sales channels fragment across regional operators.
| Leading Market Players |
|---|
| Altus Group |
| Royal LePage |
| FirstService Corporation |
| Choice Properties Real Estate Investment Trust |
| QuadReal Property Group |
| Colliers International Group |
| RE/MAX Canada |
| Chartwell Retirement Residences |
| Brookfield Office Properties |
| Others |
Value Chain & Pricing Dynamics
Pension-fund-rolled-up property management platforms anchor both supply discipline and fee compression resistance across Canadian metropolitan corridors. Their consolidated ownership of income-generating assets creates captive demand for specialized advisory functions while limiting pricing power for fragmented regional competitors.
Pricing Analysis
Volume concentration in residential sales channels competes against margin preservation in institutional property management mandates. Transaction brokerage for single-family homes operates on percentage-based commission structures that compress under multiple-listing-service competition, while commercial leasing and development advisory command retainer-plus-performance pricing tied to asset scale. Fee pressure intensifies in standard lease transactions as artificial intelligence-powered valuation tools erode information asymmetry premiums. First-time buyers exhibit acute price sensitivity to commission rates, whereas REITs and sovereign wealth vehicles prioritize service integration over marginal fee reductions.
Supply Chain Analysis
Accredited Appraisal Institute of Canada designations function as supply gates that constrain valuation service capacity in gateway cities. Credential scarcity concentrates qualified commercial appraisers in Toronto and Vancouver, while interprovincial licensing friction limits professional mobility into Calgary and Edmonton markets. Raw material dependencies include municipal assessment database access, proprietary comparable transaction feeds, and energy performance benchmarking tools from Canada Mortgage and Housing Corporation. Single-source vulnerability sits with centralized data providers whose platform outages disrupt underwriting timelines. Distribution runs through integrated national platforms, franchise brokerage networks, and specialized boutique advisory firms serving institutional direct ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Appraiser credential scarcity props fee premiums in commercial valuation segments, constraining supply expansion even as pension fund direct investment accelerates. This bottleneck sustains pricing power for qualified specialists while creating acquisition opportunities for platforms with captive training pipelines.
For Market Incumbents: Extend proprietary data infrastructure advantages by integrating automated valuation models with municipal assessment databases, compressing due diligence timelines that fragmented competitors cannot match. Acquire specialized sustainability consulting capabilities to capture Canada Green Building Council Zero Carbon Building certification demand. Vertical integration into building performance analytics offsets fee compression in standard lease transactions.
For New Entrants and Emerging Players: The mid-market price-point gap between premium institutional advisory and economy residential brokerage creates entry space for technology-enabled hybrid models. Target secondary-market repositioning advisory in Calgary and Edmonton office-to-residential conversions where incumbent coverage remains thin. Deploy PropTech-enabled tenant experience platforms as a differentiated go-to-market wedge against percentage-based property management incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale commercial valuation specialists with Accredited Appraisal Institute of Canada credential pipelines in Toronto and Vancouver corridors. Long-term viability hinges on exposure to transit-oriented intensification mandates rather than interest-rate-sensitive residential transaction volumes. Watch Bank of Canada policy rate trajectory as the inflection signal for residential sales channel recovery timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Integration | Automated valuation models compress due diligence timelines for commercial mortgage underwriting. |
| Sustainability Certification Buildout | Canada Green Building Council standards create premium fee structures for carbon accounting advisory. |
| Secondary Market Geographic Expansion | Calgary and Edmonton repositioning pipelines attract specialized development advisory demand. |
| Credential Pipeline Investment | Accredited Appraisal Institute of Canada designation programs address commercial appraiser scarcity. |
| Institutional Mandate Consolidation | Multi-year service contracts displace transaction-based fees among REIT and pension fund clients. |
Study Parameters
Multi-period observation of transaction velocity, mortgage qualification volumes, and institutional capital deployment anchored the trend analysis, supplemented by interviews with commercial brokerage executives, property management operators, pension fund acquisition directors, and municipal planning officers. Secondary validation drew from Canada Mortgage and Housing Corporation housing data, Office of the Superintendent of Financial Institutions regulatory filings, provincial real estate council licensing records, and municipal zoning approval databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to ensure consistency across service line projections.
Input-output matrices mapped service type demand to client segment growth rates, property type transaction frequencies, and metropolitan regulatory exposure across the analysis window. Segmentation dimensions included service category, client risk profile, asset class, and geographic density gradient. CAGRs derived from historical trajectory analysis adjusted for policy intervention effects, with forecast inputs incorporating Bank of Canada rate sensitivity and federal-provincial housing supply target implementation timelines.
Underlying measurement precision varies by segment; commercial leasing and property management carry tighter precision than rural property transactions where data latency extends reporting cycles. Forecasts reflect assumptions regarding regulatory stability and credential supply elasticity. A model refresh is warranted upon material change in Office of the Superintendent of Financial Institutions mortgage qualification thresholds or coordinated federal-provincial zoning intensification pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
US Home Service Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Property Tax Services Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Co-Working Space Services Market