
 Germany Self-Storage Market | 2026-2036
Germany Self-Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Self-Storage Market Insights
DIN 18015-1 electrical installation standards for commercial buildings is collapsing the barrier to entry for new facility operators in Germany. Shurgard Self Storage SA leverages its pan-European platform to sustain brand recognition across major German metros. Lagerbox Holding GmbH and Co. KG anchors its position through dense urban infill locations in Berlin and Hamburg. XXLAGER Selfstorage GmbH differentiates via technology-led access systems and automated check-in protocols.
Germany self-storage denotes commercial real estate facilities offering rentable enclosed space for temporary household or business goods retention, typically constructed with steel partition walls, concrete flooring, and mechanical ventilation maintaining humidity below 60% relative humidity. These facilities serve individuals during life transitions and enterprises seeking inventory overflow capacity without long-term warehouse leases. Climate-controlled indoor units command premium pricing and attract higher-margin residential clients, while drive-up outdoor configurations dominate commercial accounts needing frequent loading access. Small and medium storage units together represent the volume core, though extra large units yield superior per-square-meter returns from business clientele.
KBA building code enforcement at state level shapes facility permitting timelines, while CE-marked fire suppression systems determine insurance eligibility and operational authorization across German federal states. Germany's Federal Data Protection Act (BDSG) imposes strict video surveillance governance, forcing operators to balance security features with privacy compliance costs. Stakeholders must weigh municipal zoning restrictions against demographic density when selecting expansion sites, as Berlin's rent control policies and Hamburg's harbor redevelopment both redirect storage demand into adjacent municipalities.
Market Dynamics
Germany's Building Energy Act (GEG) is compressing facility development timelines as operators retrofit existing stock and redesign new builds to meet thermal envelope standards before permitting approval.
Growth Catalysts
- Urban Housing Squeeze:Berlin, Hamburg, and Munich face acute residential space constraints as rent control policies limit apartment expansion, pushing household overflow into commercial storage facilities.
- Freelance Workforce Expansion:Germany's solo self-employed population requires flexible inventory solutions without multi-year warehouse commitments, generating recurring demand for medium-unit configurations.
- KBA Streamlined Permitting:Standardized state-level building code enforcement is reducing approval variance across federal states, accelerating facility commissioning in Bavaria and North Rhine-Westphalia.
Market Restraints
- Steel Input Volatility:Partition wall and racking systems depend on European steel coil pricing, exposing operators to energy surcharge fluctuations from German smelter energy contracts.
- BDSG Surveillance Compliance:Federal Data Protection Act video governance mandates anonymization protocols and retention limits, adding legal review costs to security system deployments.
- Suburban Land Scarcity:Municipal zoning in Berlin's ring municipalities and Hamburg's harbor redevelopment zones restricts greenfield development to brownfield conversion projects with soil remediation liabilities.
Strategic Opportunities
- Eastern Metropolitan Expansion:Leipzig and Dresden exhibit storage penetration rates below western German benchmarks, offering first-mover positioning in Saxony's growing logistics corridor.
- Climate-Controlled Premium Tier:Humidity-managed indoor units attract wine collectors, antique dealers, and pharmaceutical sample storage, commanding rental multiples above drive-up configurations.
- Automated Access Convergence:Mobile app credentialing integrated with IoT door sensors reduces staffing requirements at secondary locations while capturing usage analytics for dynamic pricing.
Industry Challenges
- Certification Timeline Compression:CE-marked fire suppression system approval varies across German federal states, delaying operational authorization even when hardware meets technical specifications.
- Facility Management Talent Gap:Multi-site operators struggle to recruit technicians versed in both HVAC maintenance and BDSG-compliant surveillance system administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Self-Storage Market |
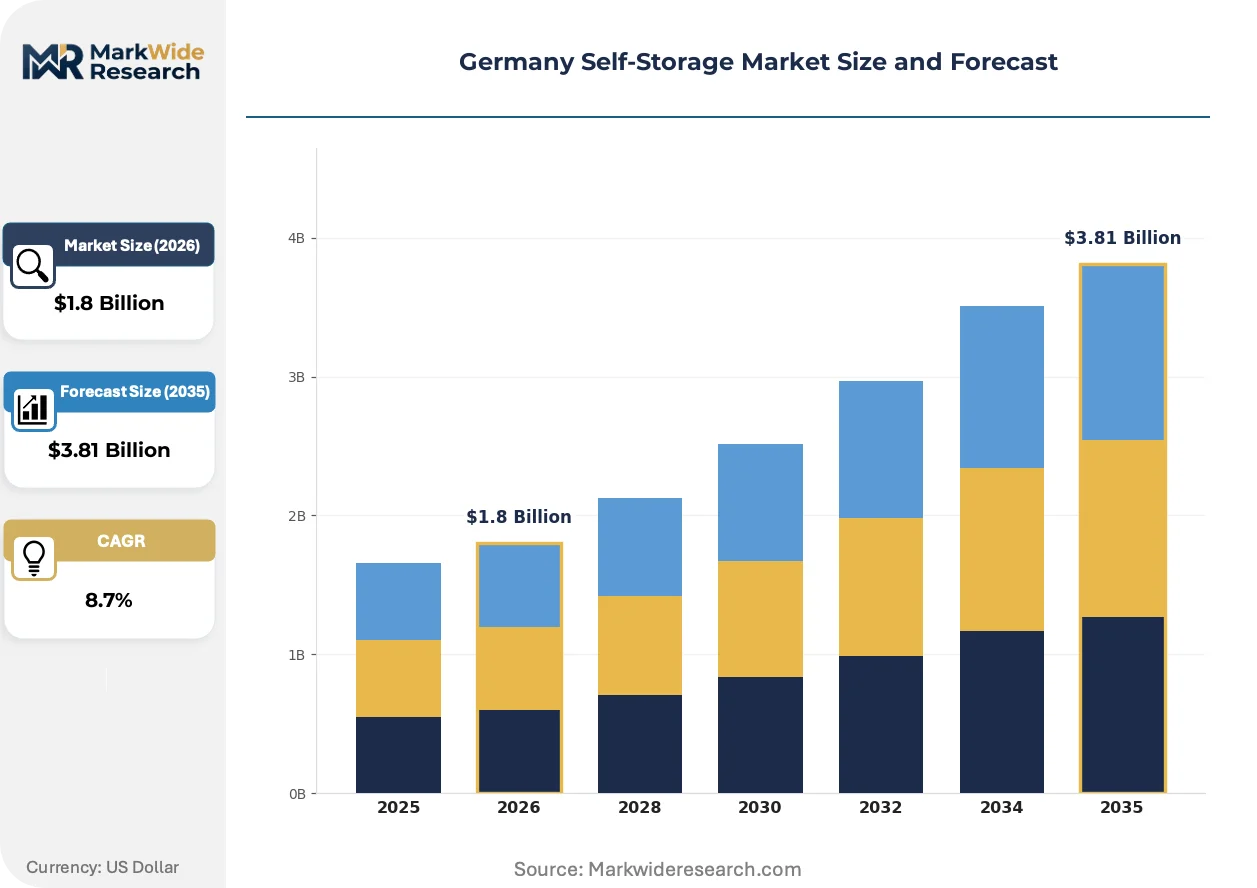
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor, Outdoor, Climate-Controlled, Drive-Up Storage Size: Small Units, Medium Units, Large Units, Extra Large Units Client Type: Residential, Commercial, Business, Student Access Features: 24-Hour Access, Gated Entry, Video Surveillance, On-Site Management |
| Companies Covered | XXLAGER Selfstorage GmbH, SelfStorage Dein Lagerraum GmbH, Shurgard Self Storage SA, Pickens Selfstorage GmbH, Rousselet Groupe SA, Space Plus Store GmbH, Lagerbox Holding GmbH and Co. KG, Storebox Holding GmbH, Hertling GmbH and Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Self-Storage Market Trends and Innovations
Facility operations are digitizing at the customer interface while mechanical systems absorb stricter efficiency mandates, creating divergent capex priorities across the operator base.
Sensor-driven humidity management is miniaturizing. Compact desiccant wheel units now maintain sub-60% relative humidity in individual locker banks rather than whole-building conditioning. Small and medium unit renters in Munich and Frankfurt are adopting these configurations for document and electronics storage. This technology is miniaturizing climate control capital deployment, allowing operators to retrofit legacy facilities without full HVAC replacement.
GEG thermal envelope standards are mandating triple-glazed facade elements and heat recovery ventilation in new German self-storage construction. Compliance adds structural cost but unlocks reduced operational energy intensity over facility lifespan. Berlin and Hamburg municipalities are enforcing these provisions most strictly, redirecting development interest toward existing building conversions with grandfathered specifications.
Small business owners are unbundling long-term warehouse contracts in favor of month-to-month storage with flexible scale-up provisions. E-commerce micro-fulfillment operators in North Rhine-Westphalia and Bavaria are driving this pattern, treating storage as variable opex rather than fixed real estate commitment. This behavior is visible most acutely among direct-to-consumer brands managing seasonal inventory spikes without dedicated distribution centers.
Germany Self-Storage Market Segmentation
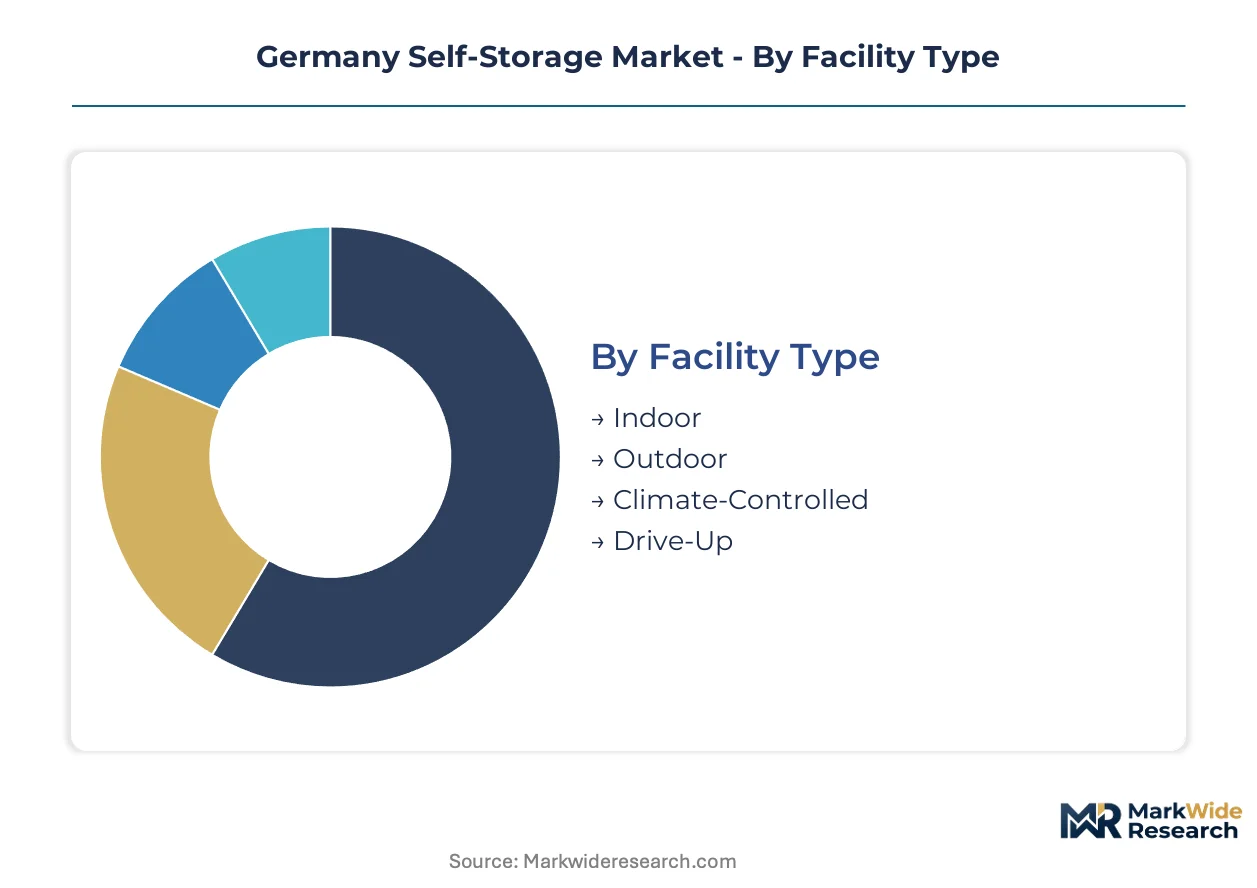
Facility configuration and client composition determine revenue stability and capital intensity across German self-storage operations. Segment boundaries blur as hybrid formats proliferate and business clients demand residential-grade amenities.
Facility Type:
Outdoor configurations face acute substitution pressure from repurposed industrial sheds and parking-lot container pods that bypass KBA permitting entirely.
- Indoor:Steel partition walls and concrete flooring create humidity-buffered environments suitable for document archives and electronics. Berlin and Hamburg operators report residential demand clustering around transit-accessible indoor facilities where apartment square-meter constraints bite hardest.
- Outdoor:Drive-up configurations dominate commercial accounts needing forklift access and pallet-scale loading. Bavarian logistics corridors absorb outdoor capacity for construction equipment and seasonal inventory staging.
- Climate-Controlled:Desiccant wheel systems maintain sub-60% relative humidity for wine collectors and pharmaceutical samples. GEG thermal envelope mandates compress development timelines for new climate-controlled builds.
- Drive-Up:Ground-level roll-up doors enable rapid vehicle loading without elevator constraints. North Rhine-Westphalia e-commerce micro-fulfillment operators treat drive-up units as variable opex alternatives to warehouse leases.
Indoor retains volume leadership; climate-controlled holds the steepest expansion curve.
Storage Size:
Cost tier stratification separates premium per-square-meter yields from volume-driven occupancy metrics.
- Small Units:Locker-scale configurations under 10 square meters capture student and transient residential demand. Munich and Frankfurt universities generate seasonal occupancy spikes during semester transitions.
- Medium Units:Standard 10-20 square meter bays balance accessibility with density, forming the occupancy core across German metros. Freelance operators in Hamburg favor medium units for inventory overflow without multi-year warehouse commitments.
- Large Units:20-50 square meter configurations accommodate household moves and small business archives. Saxony's growing logistics corridor shows underpenetration relative to western German benchmarks.
- Extra Large Units:Bay configurations exceeding 50 square meters command premium pricing from commercial clients with pallet-scale storage needs. Business clientele yield superior per-square-meter returns despite lower turnover frequency.
Medium units anchor occupancy rates; extra large configurations capture margin expansion.
Client Type:
Application divergence creates divergent facility design priorities and contract structures.
- Residential:Life-transition demand from divorce, relocation, and estate settlement drives month-to-month contracting. Berlin rent control policies redirect residential overflow into adjacent ring municipalities.
- Commercial:E-commerce inventory staging and seasonal merchandise storage generate recurring revenue with scale-up provisions. Direct-to-consumer brands in Bavaria unbundle long-term warehouse contracts for flexible storage.
- Business:Document retention and equipment archiving require BDSG-compliant surveillance protocols and climate stability. Corporate procurement teams negotiate volume discounts against multi-site operator networks.
- Student:Semester-break storage and international relocation cycles create predictable seasonal demand patterns. University-adjacent facilities in Leipzig and Dresden compete on proximity rather than amenity depth.
Commercial contracts deliver revenue predictability; residential segments expand most quickly.
Access Features:
Technology tier differentiation separates legacy facilities from digitized competitor positioning.
- 24-Hour Access:Unstaffed entry protocols extend revenue hours without labor cost escalation. IoT door sensors enable usage analytics for dynamic pricing at secondary locations.
- Gated Entry:Physical perimeter control satisfies insurer requirements for high-value stored goods. CE-marked fire suppression integration varies across German federal states, delaying operational authorization.
- Video Surveillance:BDSG anonymization mandates add legal review costs to security system deployments. Hamburg and Berlin municipalities enforce retention limits most strictly.
- On-Site Management:Staffed facilities command rental premiums for high-occupancy urban infill sites. Talent scarcity for combined HVAC and surveillance administration compresses multi-site operator margins.
Gated entry remains baseline expectation; automated credentialing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential overflow demand concentrates in Berlin, Hamburg, and Munich, while commercial accounts cluster along Bavarian logistics corridors and North Rhine-Westphalia's e-commerce fulfillment zones. Small business owners and freelance operators now represent the fastest-expanding buyer archetype across eastern metropolitan expansion markets.
Berlin-Brandenburg
Student relocation cycles and rent control policies drive household storage overflow into ring municipalities. KBA building code enforcement at state level shapes facility permitting timelines across the capital region. Potsdam and Cottbus absorb spillover demand as Berlin's urban core restricts new construction.
North Rhine-Westphalia
E-commerce micro-fulfillment operators unbundle warehouse contracts for flexible month-to-month storage. DIN 18015-1 electrical installation standards compress barrier to entry for new facility operators. Düsseldorf and Cologne logistics corridors absorb outdoor drive-up capacity for seasonal inventory staging.
Bavaria
Freelance workforce expansion generates recurring demand for medium-unit configurations without multi-year commitments. GEG thermal envelope standards mandate triple-glazed facades and heat recovery ventilation in new construction. Munich's density constraints redirect development toward Augsburg and Ingolstadt infill sites.
Hamburg
Harbor redevelopment zones restrict greenfield development to brownfield conversion projects with soil remediation liabilities. BDSG video surveillance governance mandates anonymization protocols and retention limits, adding legal review costs. Lübeck and Kiel capture redirected storage demand from Hamburg's core.
Germany Self-Storage Market Competitive Landscape
Player mix skews toward pan-European platform operators and dense urban infill specialists. The vendor base separates into three strategic tiers: international scale platforms with brand recognition across multiple metros, regional density specialists anchoring specific metropolitan clusters, and technology-led entrants differentiating through automated access systems. Competitive moves center on municipal zoning navigation for brownfield conversion sites and IoT-enabled credentialing deployment to reduce staffing intensity.
Within the technology-led tier, XXLAGER Selfstorage GmbH exemplifies automated access convergence through mobile app credentialing and IoT door sensor integration. Among regional density specialists, Lagerbox Holding GmbH and Co. KG occupies a position anchored in Berlin and Hamburg urban infill locations. At the pan-European platform level, Shurgard Self Storage SA represents brand recognition sustainment across major German metropolitan markets.
| Leading Market Players |
|---|
| XXLAGER Selfstorage GmbH |
| SelfStorage Dein Lagerraum GmbH |
| Shurgard Self Storage SA |
| Pickens Selfstorage GmbH |
| Rousselet Groupe SA |
| Space Plus Store GmbH |
| Lagerbox Holding GmbH and Co. KG |
| Storebox Holding GmbH |
| Hertling GmbH and Co. KG |
| Others |
Pricing and Supply Chain Analysis
Facility-level capacity utilization above 85% in Berlin and Hamburg enables operators to enforce minimum rental periods and scale-up premiums, compressing price competition among smaller players while anchoring regional rate floors across northern German metros.
Pricing Analysis
Cost-plus contracts with steel coil indexation dominate partition wall and racking procurement, passing European energy surcharge volatility through to facility capex. Three-tier pricing structure across climate-controlled premium, standard indoor, and economy outdoor levels segments buyer willingness-to-pay by humidity sensitivity and access frequency. Price differentiation rests on GEG thermal envelope compliance certification, with grandfathered conversions in Berlin commanding modest premiums over new-build triple-glazed facilities facing stricter amortization schedules. Pricing pressure stems from container pod substitutes bypassing KBA permitting, eroding occupancy at peripheral outdoor sites. E-commerce micro-fulfillment operators in North Rhine-Westphalia exhibit highest price sensitivity, while wine collectors and pharmaceutical sample archivists accept sustained premiums for sub-60% relative humidity guarantees.
Supply Chain Analysis
Just-in-time steel coil delivery from German smelters conflicts with strategic stockpiling of CE-marked fire suppression hardware, as certification timeline variance across federal states forces operators to pre-position equipment before permitting approval. Manufacturing concentrates in Germany, Poland, and the Czech Republic for structural steel and HVAC components, with desiccant wheel systems sourced from Swiss and Austrian specialists. Raw material dependencies center on European steel coil, aluminum facade elements, and German-manufactured heat recovery ventilation units. Supply chain risk manifests in single-source vulnerability for BDSG-compliant video anonymization software, where qualified legal-technology vendors remain scarce. Distribution runs through regional construction logistics networks serving brownfield conversion projects, with final-mile coordination handled by facility development contractors familiar with municipal soil remediation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GEG thermal envelope mandates and BDSG surveillance compliance are compressing development timelines while elevating technical barriers, creating asymmetric returns for operators with in-house regulatory navigation capabilities.
For Market Incumbents: Consolidate through brownfield conversion portfolios in Berlin ring municipalities and Hamburg harbor redevelopment zones, where soil remediation expertise creates moats against container pod substitutes. Acquire technicians cross-trained in HVAC maintenance and BDSG-compliant surveillance administration to resolve the facility management talent gap compressing multi-site margins. Vertical integration into desiccant wheel system maintenance secures climate-controlled tier pricing power. For New Entrants and Emerging Players: CE marking fast-track partnerships with Bavarian fire suppression certifiers accelerate operational authorization before competitors complete state-by-state approval variance. Target Leipzig and Dresden for first-mover positioning in Saxony's underpenetrated logistics corridor, where university-adjacent student storage and freelance workforce expansion converge. Deploy mobile app credentialing with IoT door sensors to reduce staffing intensity at secondary locations while capturing usage analytics for dynamic pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with automated access convergence and grandfathered GEG specifications in Berlin and Hamburg infill sites. Long-term viability hinges on regulatory arbitrage capabilities across German federal states rather than scale economies alone. Acquisition target archetype: dense urban infill specialists with 85%+ occupancy and pending CE-marked fire suppression approvals. Watch KBA permitting timeline standardization as inflection indicator for multi-state expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Conversion Development | Soil remediation expertise unlocks Hamburg harbor and Berlin ring municipality sites restricted from greenfield construction. |
| Automated Access Integration | Mobile app credentialing with IoT sensors reduces staffing costs at secondary locations while enabling dynamic pricing analytics. |
| Climate-Controlled Tier Expansion | Desiccant wheel retrofits capture wine collector and pharmaceutical sample premiums without full HVAC replacement capex. |
| Regulatory Compliance Fast-Track | CE marking and BDSG anonymization pre-certification compresses operational authorization timelines across federal states. |
| Eastern Metropolitan Expansion | Leipzig and Dresden first-mover positioning accesses Saxony's growing logistics corridor before western competitor saturation. |
Research Methodology
Initial hypotheses were tested against primary input from facility operations directors, municipal zoning officers, HVAC maintenance technicians, and commercial real estate developers and refined through secondary validation against KBA permitting databases, GEG technical specifications, BDSG enforcement guidelines, and European steel coil trade data. Bottom-up unit economics from 40+ facilities across Berlin, Hamburg, Munich, and emerging eastern metros were triangulated with top-down market sizing from construction permit filings and occupancy rate surveys.
Variance decomposition across facility type, storage size, client segment, and access technology tier informed segment-level growth trajectories over the projection horizon. CAGRs were derived from fitted trend lines adjusted for GEG implementation phasing and BDSG compliance cost absorption curves. Forecast inputs incorporated freelance workforce expansion rates, e-commerce micro-fulfillment inventory staging patterns, and university enrollment cycles driving seasonal demand.
Decision-makers should treat outputs as directional under assumptions of sustained KBA permitting standardization and stable European steel energy surcharge regimes; material deviation in regulatory enforcement intensity or raw material cost volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Home Warranty Service Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Global Home Services Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Green Lease Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
US Home Service Market
Real Estate Services
Asia-Pacific Self Storage Market