
 US Home Service Market | 2026-2036
US Home Service Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Service Market Outlook
Buyer concentration across the US Home Service Market is broadening as property management companies and institutional landlords expand portfolios while single-family rental platforms fragment traditional homeowner demand. Angi Inc. leverages its two-sided marketplace model to connect verified contractors with digital-native consumers seeking transparent pricing. Lowe's Companies Inc. sustains competitive advantage through in-store service desks and installation partnerships that convert retail foot traffic into booked home improvement jobs. TaskRabbit competes on speed and flexibility, targeting urban millennials who prioritize same-day furniture assembly and minor repair fulfillment over established trade relationships.
US Home Services encompass skilled trade work performed on residential structures, spanning mechanical systems installation, building envelope repair, and interior finishing tasks that require licensed technician certification or specialized equipment competency. The sector functions as critical infrastructure upkeep for the nation's residential housing stock, with service quality directly tied to occupant safety, energy consumption, and property value retention. HVAC and plumbing command the largest share of maintenance spending as aging systems fail and efficiency standards tighten across climate zones. Smart Home technology represents the fastest-growing service attachment, with electricians and automation specialists capturing premium pricing for integrated thermostat, security, and lighting control installations.
EPA regulations on refrigerant phase-downs and energy conservation standards reshape HVAC contractor training requirements and equipment inventory decisions. State-level licensing boards and OSHA workplace safety rules govern technician credentialing and liability exposure for service firms operating across multiple jurisdictions. Stakeholders must monitor how municipal electrification mandates and building code updates redirect demand from gas-fired systems toward heat pump and solar-ready electrical infrastructure.
Market Dynamics
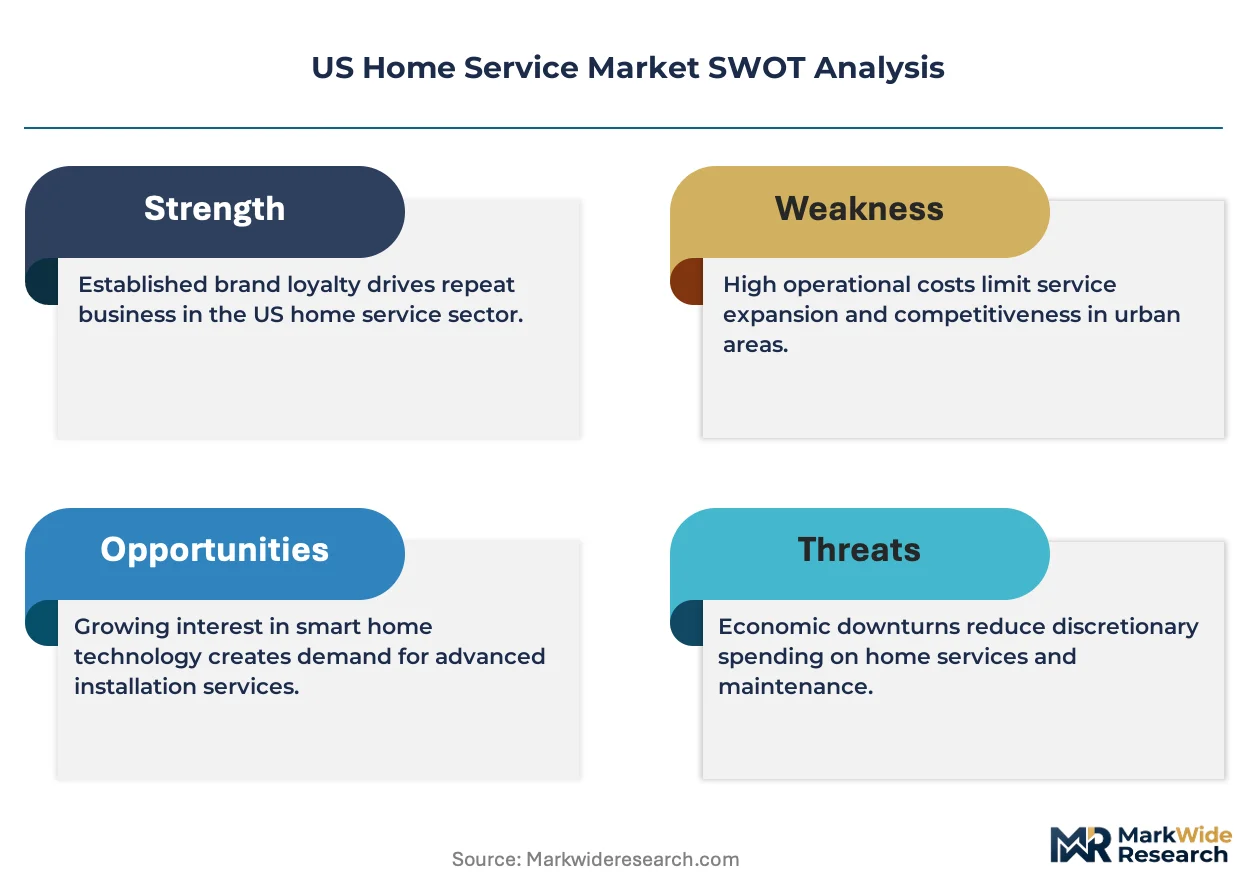
Aging residential housing stock across Sun Belt metros is compressing maintenance cycles and forcing HVAC, plumbing, and electrical contractors to scale technician capacity faster than training pipelines allow. EPA refrigerant phase-downs and state electrification mandates are simultaneously rewiring equipment inventories and service skill requirements.
Growth Catalysts
- EPA Energy Conservation Standards:Mandated efficiency upgrades are accelerating replacement demand for gas-fired furnaces and conventional air conditioning units across climate zones with extreme temperature volatility.
- Smart Home Technology Attachment:Electricians and low-voltage specialists are capturing premium installation work for integrated thermostat, security, and lighting control systems that require certified automation competency.
- Sun Belt Metro Concentration:Phoenix, Dallas, and Atlanta are generating disproportionate service call volumes from new construction defects and in-migration-driven housing density.
Market Restraints
- Licensed Technician Scarcity:State-level contractor licensing boards and OSHA workplace safety rules create multi-year credentialing pipelines that throttle firm expansion across jurisdictions.
- Equipment Inventory Stranding:Municipal electrification mandates are devaluing gas-fired system components before depreciation cycles complete, compressing contractor working capital efficiency.
- Refrigerant Supply Volatility:EPA-mandated hydrofluorocarbon phase-downs are disrupting HVAC parts availability and pricing predictability for service firms maintaining legacy installations.
Strategic Opportunities
- Heat Pump Infrastructure Conversion:State-level electrification incentives and building code updates are redirecting demand toward solar-ready electrical infrastructure that requires specialized installation certification.
- Single-Family Rental Platform Integration:Institutional landlords and property management companies are consolidating maintenance spend and seeking preferred contractor networks with guaranteed response-time service level agreements.
- Energy Audit Attachment Services:EPA efficiency standards are creating compliance-driven demand for blower door testing, duct leakage assessment, and whole-home performance verification bundled with mechanical system work.
Industry Challenges
- Cross-Jurisdictional Licensing Complexity:Technicians operating across state lines face fragmented reciprocity agreements and continuing education requirements that extend deployment timelines.
- Legacy System Integration Friction:Smart home retrofits require compatibility bridging with aging electrical panels and analog climate controls that lack standardized communication protocols.
- Workforce Pipeline Compression:Trade school graduation rates and apprenticeship completions lag replacement demand for retiring baby-boomer technicians in specialized mechanical disciplines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Service Market |
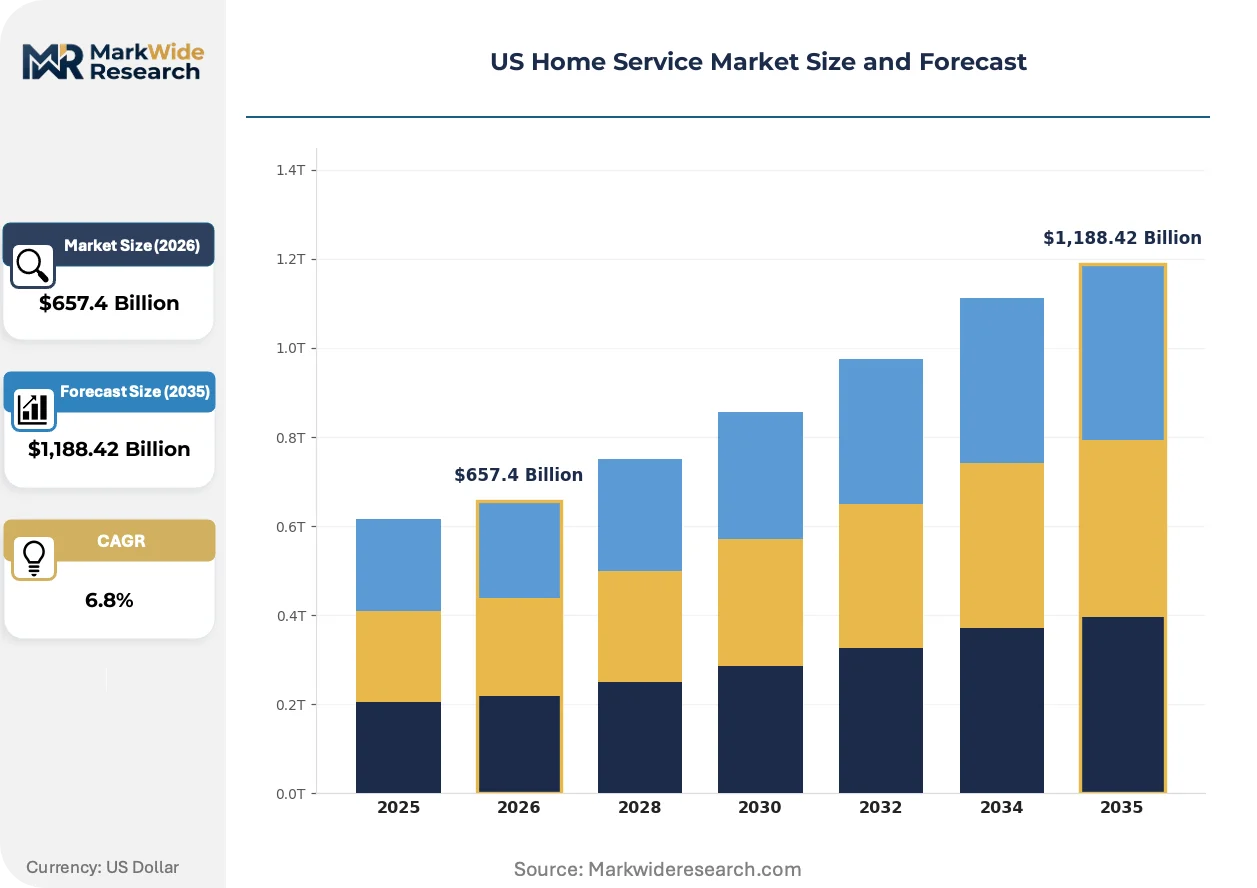
| Market Size in 2026 | $657.4 Billion |
| Market Size in 2035 | $1,188.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Plumbing, Electrical, HVAC, Cleaning Client Type: Residential Owners, Renters, Property Managers, Builders Market Segment: Maintenance, Repair, Installation, Customization Technology: Smart Home, Traditional Tools, Eco-Friendly Solutions, Automation |
| Companies Covered | Angi Inc., Thumbtack Inc., Handy Technologies Inc., Rollins Inc., Chemed Corporation, The Home Depot Inc., TaskRabbit, Porch Group Inc., Lowe's Companies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Service Market Strategic Shifts
Digital dispatch platforms and connected diagnostic equipment are compressing response times and enabling predictive maintenance models that shift revenue from emergency repair to subscription monitoring. Contractor business models are bifurcating between high-volume platform-integrated operators and specialized premium-service firms.
Heat pump technology is electrifying residential HVAC infrastructure by enabling dual-mode heating and cooling from single electrical systems. Sun Belt builders and retrofit contractors are specifying variable-speed compressors and cold-climate-rated units at accelerating rates. This electrification is compressing demand for gas line installation services and rewiring contractor equipment supplier relationships toward electrical distributors.
EPA refrigerant management regulations under Section 608 are mandating enhanced leak detection, repair, and disposal documentation for technicians handling hydrofluorocarbon blends. Service firms must now deploy certified recovery equipment and maintain transaction records that state environmental agencies audit. HVAC contractors in California and New York are responding fastest with technician retraining investments and inventory tracking software upgrades.
Millennial and Gen-Z homeowners are abandoning established trade relationships in favor of app-mediated service matching that prioritizes transparent upfront pricing and same-day availability. Digital-native consumers are displacing traditional yellow-page contractors and word-of-mouth referrals with platform-verified reviews and automated scheduling. This behavioral shift concentrates fastest in urban coastal markets where housing density supports technician route optimization.
US Home Service Market Segmentation
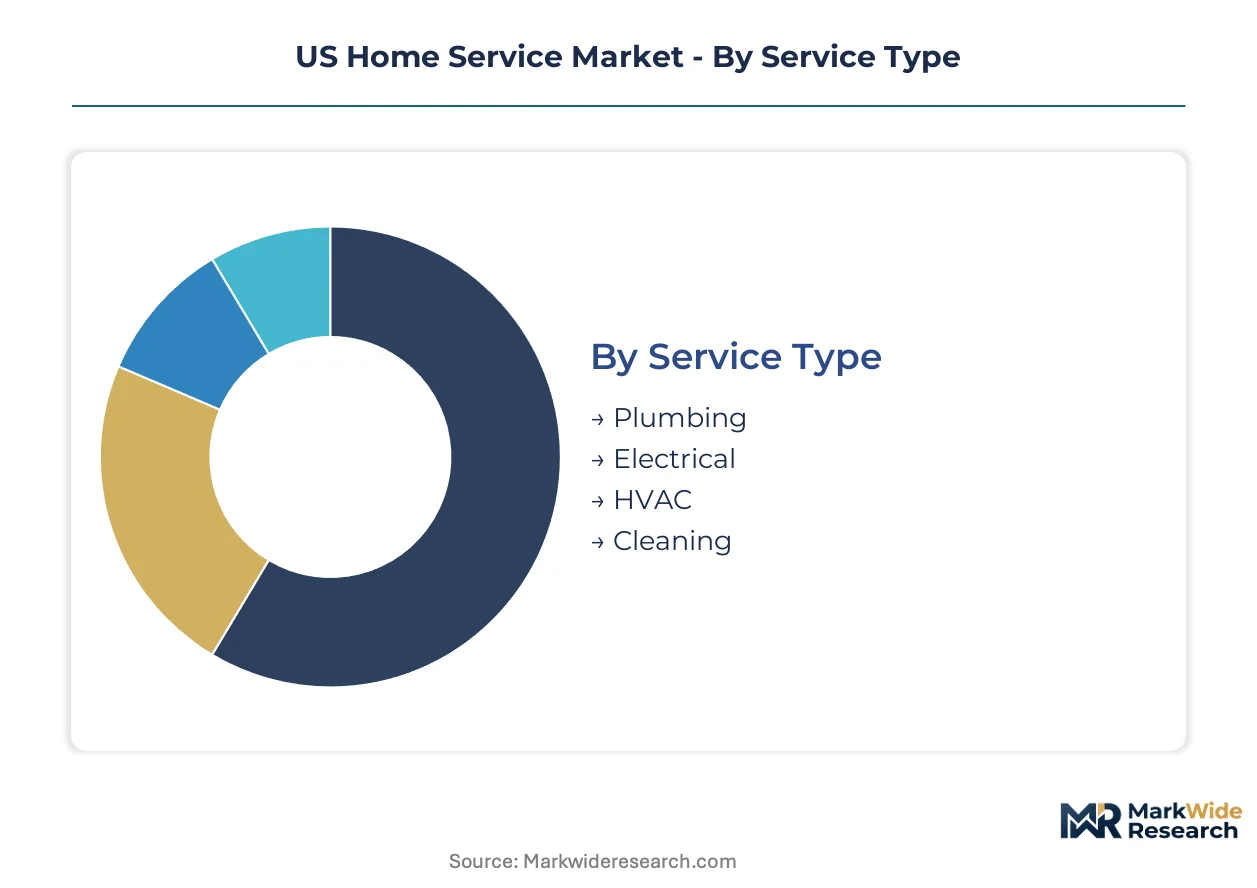
Service segmentation in the US Home Service Market reveals how contractor capabilities, client procurement patterns, and technology specifications intersect to create distinct competitive arenas. Understanding these divisions exposes where pricing power concentrates and which skill investments yield sustainable margin protection.
Service Type:
Technical certification requirements and equipment specialization define competitive boundaries across trade disciplines, with EPA and OSHA regulations creating divergent compliance cost structures.
- Plumbing:Licensed technicians handle pressurized water distribution, sanitary drainage, and gas line infrastructure that intersects with municipal building codes and cross-connection control ordinances. Demand clusters in Sun Belt metros where slab foundation leaks and hard-water scaling accelerate replacement cycles in Phoenix and Dallas housing stock.
- Electrical:NEC code compliance and arc-fault protection mandates drive panel upgrade demand as electrification incentives redirect homeowner investment from gas infrastructure toward solar-ready circuits and EV charging infrastructure.
- HVAC:EPA Section 608 certification governs refrigerant handling for climate system installation and repair across extreme temperature zones.
- Cleaning:Low-barrier entry and minimal licensing requirements attract platform-integrated gig operators targeting same-day booking convenience.
Mature deployment sits with Plumbing and Electrical. Newer deployment is concentrated in HVAC as heat pump conversions accelerate.
Client Type:
Procurement authority and contract scale reshape how service firms structure pricing, scheduling, and technician deployment across household and institutional demand pools.
- Residential Owners:Aging housing stock in owner-occupied single-family homes generates discretionary maintenance spending with price sensitivity moderated by property value protection motives. Sun Belt in-migration corridors concentrate highest per-capita service call frequency.
- Property Managers:Institutional landlords and single-family rental platforms consolidate maintenance spend through preferred contractor networks with guaranteed response-time SLAs, compressing margins in exchange for volume predictability.
- Renters:Landlord-mediated service access limits direct contractor relationships, with demand filtered through property owner approval workflows and deposit recovery incentives.
- Builders:New construction defect liability periods and warranty obligations create concentrated installation demand with compressed timelines and penalty clauses.
Volume concentration sits with Property Managers. Margin protection is strongest with Residential Owners.
Market Segment:
Service lifecycle positioning determines revenue predictability, with emergency response commanding premium pricing against scheduled maintenance.
- Maintenance:Preventive service agreements and seasonal tune-up programs generate recurring revenue streams that smooth technician utilization across weather-driven demand cycles.
- Repair:Emergency response to system failures captures highest hourly rates but suffers from dispatch inefficiency and callback liability exposure.
- Installation:Equipment replacement and new construction rough-in work ties revenue to permitting timelines and supplier delivery reliability.
- Customization:Aesthetic and functional upgrades including smart home integration and energy efficiency retrofits attract premium pricing from digitally native consumers.
Recurring revenue sits with Maintenance. Steepest expansion trajectory is concentrated in Customization as smart home attachment rates climb.
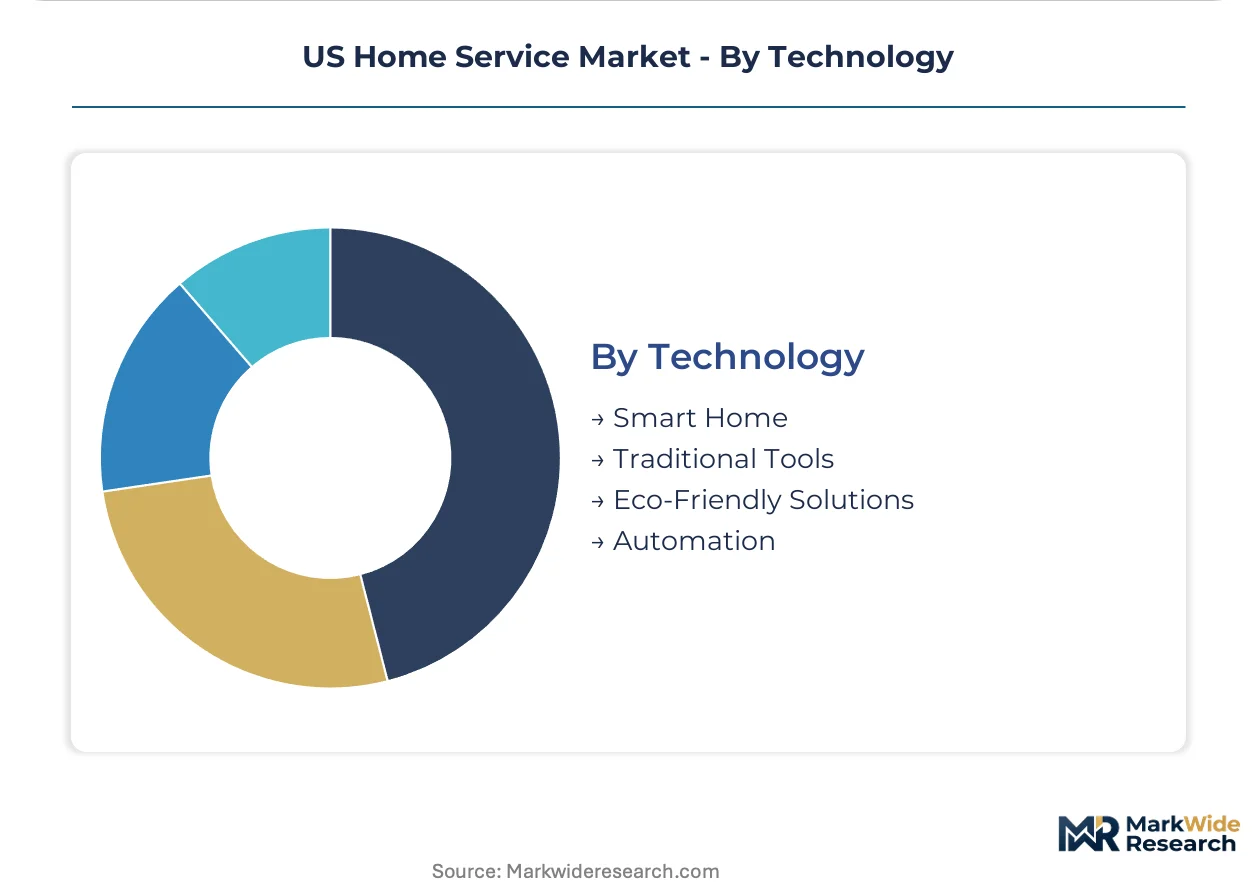
Technology:
Equipment sophistication and certification requirements segment contractor capabilities between commodity tool deployment and integrated system engineering.
- Smart Home:Low-voltage wiring, wireless protocol integration, and cloud-connected device commissioning require electricians and automation specialists to maintain manufacturer certification programs. Demand concentrates in coastal metros where millennial homeowners prioritize app-controlled climate, security, and lighting systems.
- Eco-Friendly Solutions:Heat pump installation, solar thermal systems, and greywater recovery equipment align with state electrification incentives and EPA efficiency mandates, requiring specialized training pipelines that lag deployment demand.
- Traditional Tools:Hand tools and conventional diagnostic equipment dominate plumbing and general repair work where technology substitution remains limited.
- Automation:Robotic cleaning systems and automated HVAC zoning reduce labor content per service event while shifting contractor value toward programming and calibration expertise.
Certification complexity sits with Smart Home. Regulatory tailwinds are strongest with Eco-Friendly Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Sun Belt metros where aging housing stock and in-migration accelerate service call volumes. EPA energy-efficiency standards and state electrification mandates reshape contractor requirements across climate zones. Municipal building codes and licensing boards govern technician deployment in high-growth corridors.
California
Silicon Valley and Los Angeles Basin homeowners drive smart home integration demand for electricians and automation specialists. California Energy Commission Title 24 mandates heat pump readiness in new construction and major renovations. San Diego contractors face compressed timelines for solar-ready electrical panel upgrades tied to net metering transitions.
Texas
Dallas-Fort Worth and Houston metroplexes generate highest per-capita HVAC replacement demand from extreme temperature volatility and slab foundation plumbing failures. Texas Department of Licensing and Regulation maintains reciprocity gaps with neighboring states that complicate technician deployment across the Dallas-Austin-San Antonio triangle. Houston Gulf Coast humidity accelerates corrosion cycles in outdoor condensing units.
Florida
Miami-Dade and Tampa Bay corridors concentrate emergency repair demand from hurricane-season system failures and salt-air equipment degradation. Florida Building Code wind-load requirements govern outdoor unit anchoring and electrical disconnect specifications. Orlando's single-family rental platform density creates preferred contractor network consolidation for institutional landlords.
Arizona
Phoenix and Tucson housing stock exhibits fastest-aging mechanical systems from continuous cooling load and hard-water scaling. Arizona Registrar of Contractors enforces solar thermal and heat pump installation certifications that lag training pipeline output. Scottsdale and Paradise Valley custom home markets drive premium pricing for integrated automation and efficiency retrofit bundling.
Georgia
Atlanta metro in-migration corridors generate new construction defect liability periods and warranty-driven installation demand. Georgia Secretary of State contractor division maintains continuing education reciprocity with South Carolina and Alabama that eases cross-border technician mobility. Savannah coastal humidity zones accelerate mold remediation and HVAC duct replacement cycles in historic housing stock.
US Home Service Market Competitive Environment
Sun Belt platform operators anchor one tier; Northeast and Midwest specialized trade contractors hold premium certification positioning. The vendor base exhibits moderate fragmentation between national marketplace aggregators and regional family-owned service firms. Two strategic archetypes dominate: high-volume platform-integrated operators optimizing route density, and specialized premium-service firms capturing complex retrofit and smart home integration work. Competitive moves concentrate on technician training pipeline investments and preferred contractor network agreements with institutional property managers.
Within the platform-aggregator tier, Angi Inc. and Thumbtack Inc. occupy positions connecting verified contractors with digital-native consumers seeking transparent pricing and same-day availability. TaskRabbit exemplifies the speed-flexibility archetype targeting urban millennials for furniture assembly and minor repair fulfillment. Lowe's Companies Inc. anchors the retail-conversion model through in-store service desks and installation partnerships that transform foot traffic into booked home improvement jobs.
| Leading Market Players |
|---|
| Angi Inc. |
| Thumbtack Inc. |
| Handy Technologies Inc. |
| Rollins Inc. |
| Chemed Corporation |
| The Home Depot Inc. |
| TaskRabbit |
| Porch Group Inc. |
| Lowe's Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Horizontal platform integration anchors supply positioning and pricing power for US home service contractors, as marketplace aggregators consolidate technician access while specialized firms retain premium-rate autonomy through certification moats. This bifurcation concentrates procurement leverage among institutional property managers while fragmenting price discovery for residential owners.
Pricing Analysis
Volume concentration among property managers compresses margins through preferred contractor networks with guaranteed response-time SLAs, while residential owners sustain premium pricing through discretionary maintenance spend. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling. Cost compression in the platform-integrated tier intensifies because gig operators compete on same-day availability. Residential owners show least price sensitivity where property value protection motives dominate; renters filtered through landlord approval workflows show highest sensitivity.
Supply Chain Analysis
Domestic-content mandates from EPA Section 608 certification requirements reshape sourcing toward US-based refrigerant recovery equipment and certified training pipelines. Equipment supply concentrates in Mexico, China, and domestic electrical distributors serving HVAC and smart home automation. Raw material dependencies span copper refrigerant lines, semiconductor components for smart thermostats, and lithium-ion cells for battery-backed systems. Single-source vulnerability runs through EPA-licensed refrigerant blend suppliers facing phase-down disruptions. Distribution runs through manufacturer-authorized dealer networks and big-box retail installation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US home service sector sits in a technology-transition phase as heat pump electrification displaces gas-fired furnace infrastructure and rewires contractor skill requirements.
For Market Incumbents: Deploy technician certification pipelines as the defensive lever against licensed-scarcity bottlenecks. Incumbents should backward integration into EPA-approved refrigerant reclamation facilities to capture margin from regulatory compliance requirements. Capacity addition in Phoenix and Dallas metros addresses Sun Belt demand concentration while building preferred-network relationships with single-family rental platforms defends share against marketplace aggregators. For New Entrants and Emerging Players: Enter via energy audit attachment services bundled with HVAC replacement work, exploiting compliance-driven demand from EPA efficiency standards. The most penetrable segment lies in smart home retrofit integration for millennial homeowners abandoning established trade relationships. A direct-to-consumer platform positioning with transparent upfront pricing and automated scheduling captures digitally native demand in urban coastal markets. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-aggregator acquisitions by retail conglomerates seeking installation-service verticals. Long-term viability favors specialized premium-service firms with heat pump certification and smart home integration capabilities over high-volume operators facing margin compression. The signal to watch is municipal electrification mandate acceleration redirecting demand from gas infrastructure toward solar-ready electrical contractors.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Certification Pipeline Investment | Section 608 credentialing creates technician scarcity moats for compliant firms. |
| Heat Pump Infrastructure Conversion | State electrification incentives redirect demand toward specialized electrical contractors. |
| Preferred Contractor Network Agreements | Institutional landlords consolidate maintenance spend through guaranteed SLA partnerships. |
| Smart Home Platform Integration | Low-voltage automation certification captures premium pricing from millennial homeowners. |
| Refrigerant Recovery Vertical Integration | EPA leak detection mandates anchor margin in compliant equipment and documentation services. |
Study Parameters
Independent corroboration across EPA regulatory filings, state licensing board records, and contractor trade association surveys underwrites the qualitative findings. Primary interviews with HVAC service firm owners, electrical contractor operations managers, property management procurement leads, and smart home automation specialists combined with secondary validation from OSHA workplace safety data, DOE energy efficiency program reports, and SEC filings from publicly traded platform operators. Bottom-up technician deployment estimates and top-down housing stock maintenance spend projections triangulate market sizing.
Comparable-period anchoring to historical EPA refrigerant phase-down impacts and state electrification incentive rollouts structured the forecast window. The analytical framework segments by service type, client procurement authority, technology certification requirements, and regional climate zone across the projection horizon. CAGRs derive from housing unit age distribution models, in-migration corridor service call frequency, and equipment replacement cycle compression. Forecast inputs include heat pump adoption curves and smart home attachment rates by homeowner demographic.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated municipal electrification mandates or refrigerant supply disruptions. The analytical envelope reflects assumptions around technician training pipeline throughput and state-level licensing reciprocity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Relocation Management Service Market
Real Estate Services
Green Lease Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
IBC Rental Business Market