
 Zellweger Spectrum Disorders Market | 2026-2036
Zellweger Spectrum Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Zellweger Spectrum Disorders Market Analytics
North America is reconfiguring its peroxisomal disorder diagnostics capacity through expanded state-level newborn screening mandates. PerkinElmer Inc. leverages its neonatal screening platform dominance to anchor supply contracts with public health laboratories. F. Hoffmann-La Roche Ltd competes through integrated mass spectrometry workflows that reduce sample-to-result time for very-long-chain fatty acid analysis. Bio-Rad Laboratories, Inc. specializes in PCR-based carrier detection kits targeting high-risk populations.
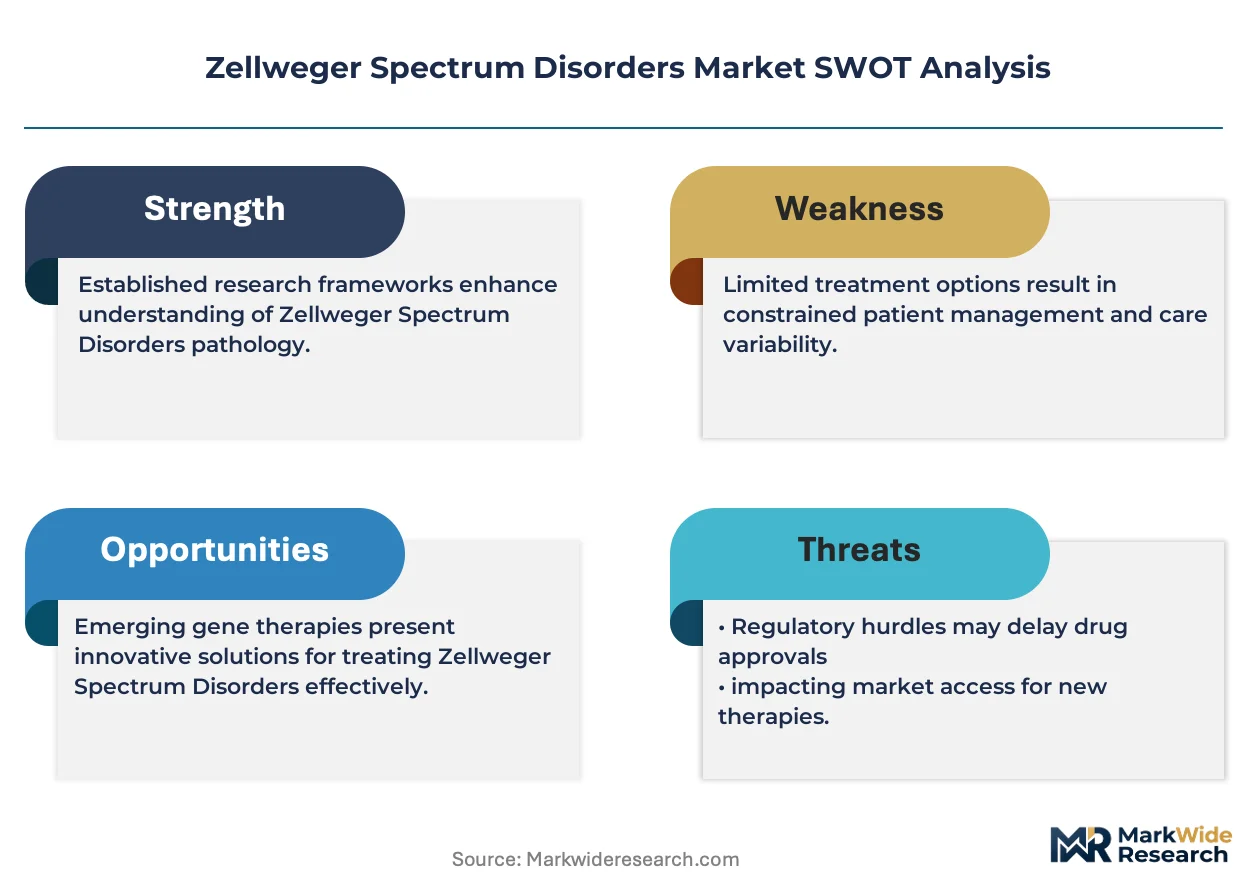
Zellweger Spectrum Disorders comprise a group of rare autosomal recessive conditions caused by mutations in PEX genes, impairing peroxisome assembly and resulting in defective beta-oxidation of very-long-chain fatty acids; diagnostic protocols measure plasma C26:0 and C26:1 levels alongside pipecolic acid quantification to confirm peroxisomal dysfunction. Diagnostic Kits currently dominate revenue as newborn screening expansion drives volume, while Gene Therapies represent the fastest-growing category as AAV-based PEX gene delivery advances through clinical trials. Next-Generation Sequencing captures expanding margin pools through panel-based PEX gene analysis that replaces sequential single-gene testing.
FDA orphan drug incentives and EMA priority medicines designation shape development economics by compressing regulatory review timelines for gene therapy candidates. The EU's Rare Disease Regulation mandates cross-border healthcare access, forcing manufacturers to establish centralized diagnostic hubs in member states with specialized metabolic centers. Stakeholders must monitor reimbursement negotiations for single-administration gene therapies against chronic enzyme replacement paradigms.
Market Dynamics
Gene therapy pipelines are compressing clinical development timelines as FDA orphan drug incentives and EMA priority medicines designations reshape investment allocation toward single-administration interventions for peroxisomal disorders.
Growth Catalysts
- Expanded Newborn Screening Mandates:State-level programs in the United States and centralized neonatal infrastructure in Germany and Japan are driving diagnostic kit volumes through systematic very-long-chain fatty acid testing protocols.
- EMA Priority Medicines Framework:The European Union's accelerated review pathway compresses regulatory timelines for PEX gene therapy candidates, attracting venture capital into rare disease development.
- AAV Vector Manufacturing Scale-Up:Contract development organizations are building dedicated peroxisomal disorder production lines, reducing cost-per-dose for investigational gene therapies entering Phase I/II trials.
Market Restraints
- Plasmalogen Synthesis Complexity:The enzymatic production of docosahexaenoic acid-precursor lipids requires specialized fermentation capacity concentrated in Switzerland and Germany, creating input bottlenecks.
- Single-Gene Testing Legacy Infrastructure:Regional diagnostic laboratories in Italy and Spain maintain sequential PEX1/PEX2/PEX6 workflows that resist panel-based next-generation sequencing conversion due to capital sunk costs.
- Reimbursement Parity Constraints:Germany's G-BA assessment framework evaluates gene therapies against chronic enzyme replacement benchmarks, compressing pricing headroom for curative interventions.
Strategic Opportunities
- Brazil's ANVISA Expedited Pathway:The Latin American regulator's rare disease designation creates first-mover positioning for newborn screening kit manufacturers before regional competitors establish distribution.
- CRISPR-Base Editing Convergence:The integration of cytosine base editors with AAV delivery vehicles enables precise PEX gene correction without double-strand breaks, opening pediatric dosing windows.
- Direct-to-Patient Genetic Counseling:Telehealth platforms are bypassing metabolic center referrals in Australia and Canada, accelerating carrier detection in high-risk Ashkenazi Jewish and Japanese populations.
Industry Challenges
- Peroxisomal Biologist Talent Scarcity:The specialized intersection of organelle biology and gene therapy vector design faces recruitment competition from oncology and immunology programs at academic medical centers.
- GMP Facility Qualification Timelines:FDA pre-approval inspections for AAV suites require 18-24 month lead times, delaying Investigational New Drug submissions for PEX gene replacement candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zellweger Spectrum Disorders Market |
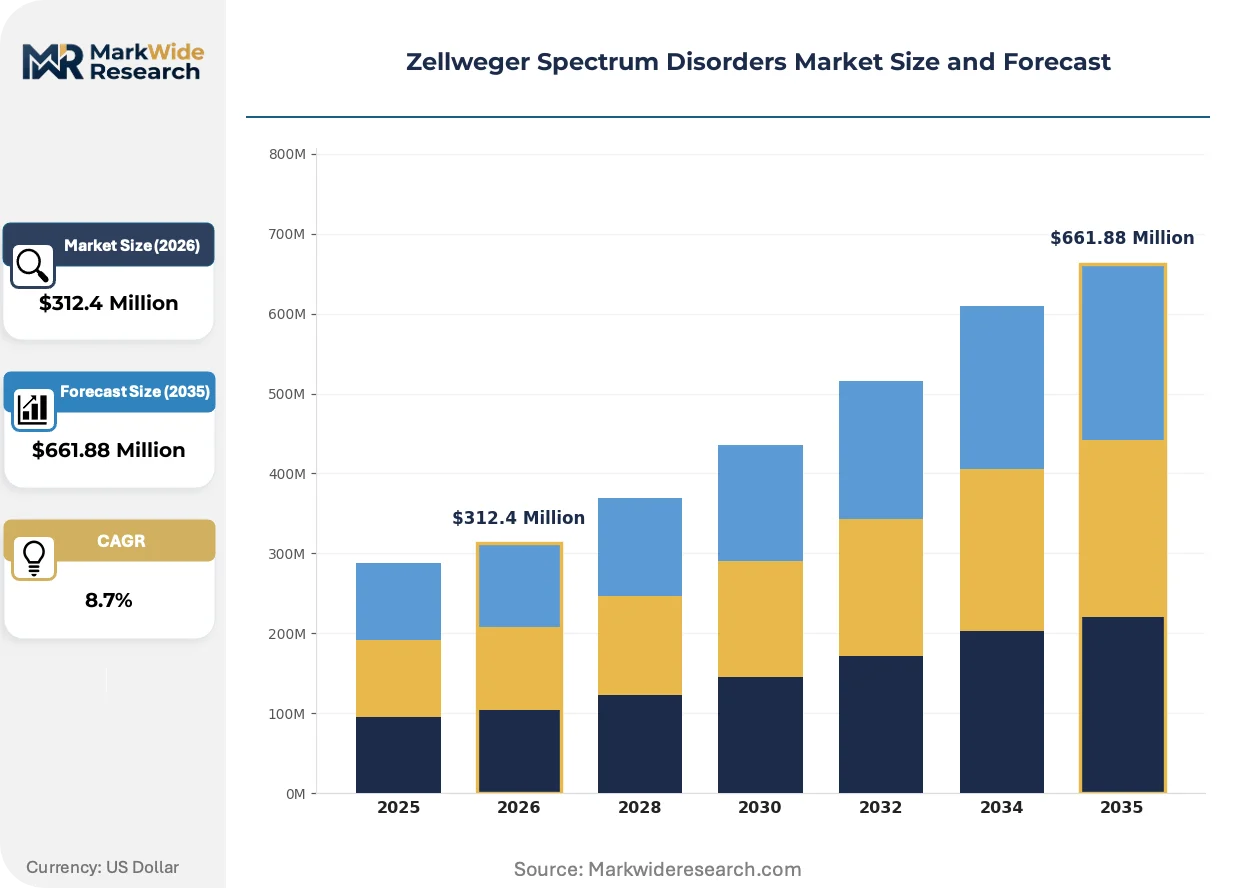
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Enzyme Replacements, Gene Therapies, Supportive Care Application: Clinical Diagnosis, Genetic Testing, Research, Patient Management Technology: Next-Generation Sequencing, Mass Spectrometry, PCR, Biochemical Assays End User: Hospitals, Clinical Laboratories, Research Institutions, Home Care |
| Companies Covered | PerkinElmer Inc., F. Hoffmann-La Roche Ltd, Bio-Rad Laboratories, Inc., Beckman Coulter, Inc., CENTOGENE N.V., Chromsystems Instruments & Chemicals GmbH, Trivitron Healthcare, Siemens, LifeCell International Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zellweger Spectrum Disorders Market Evolving Landscape
Diagnostic workflows are converging with therapeutic development as manufacturers build integrated platforms spanning biomarker detection through patient stratification for gene therapy enrollment.
Liquid chromatography-tandem mass spectrometry is hybridizing with dried blood spot automation, enabling high-throughput C26:0 and pipecolic acid quantification in public health laboratories. State newborn screening programs in Texas and California are adopting these integrated workflows, compressing sample-to-result intervals from days to hours. This hybridization is displacing gas chromatography methods and enabling real-time reflex testing for confirmatory PEX gene sequencing.
The European Union's In Vitro Diagnostic Medical Devices Regulation (IVDR) is reclassifying peroxisomal disorder biomarker assays from self-certified to notified body-reviewed devices, forcing manufacturers to rebuild technical documentation for CE marking. Diagnostic kit suppliers are responding by consolidating product portfolios and withdrawing lower-volume assays from the European market. Germany and France are experiencing the most pronounced portfolio contraction as notified body capacity concentrates in Benelux jurisdictions.
Patient advocacy networks are consolidating procurement influence through centralized tissue banking and natural history study enrollment. The Global Foundation for Peroxisomal Disorders coordinates specimen collection across 23 countries, redirecting diagnostic testing contracts toward vendors offering integrated biorepository services. This behavioral shift is most visible in the United States, where academic metabolic centers now require kit suppliers to demonstrate biobank interoperability in competitive tenders.
Zellweger Spectrum Disorders Market Segmentation
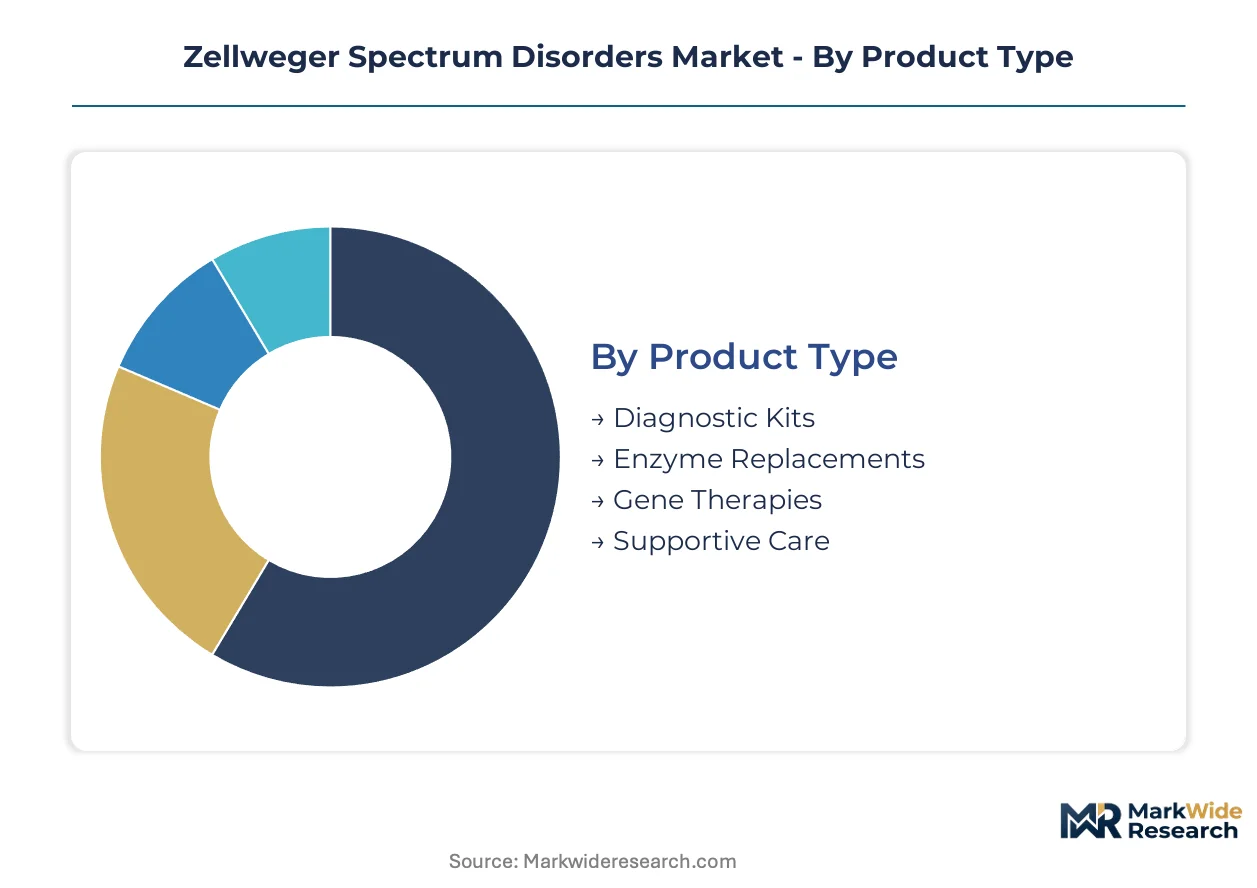
Segmentation in Zellweger Spectrum Disorders reflects the tension between acute diagnostic urgency and long-term therapeutic transformation. Product portfolios span immediate biochemical detection through curative gene delivery, while technology choices determine whether laboratories process single samples or scale to population-wide newborn screening.
Product Type:
Use-case spectrum spans confirmatory testing in symptomatic infants through prophylactic intervention in presymptomatic carriers.
- Diagnostic Kits:Plasma C26:0 and pipecolic acid quantification platforms dominate current procurement volumes. State public health laboratories in Texas and California drive demand through expanded newborn screening mandates requiring high-throughput very-long-chain fatty acid analysis.
- Gene Therapies:AAV-based PEX gene delivery candidates are climbing the fastest through clinical pipelines. EMA priority medicines designation and FDA orphan drug incentives compress regulatory timelines for single-administration interventions targeting peroxisome biogenesis restoration.
- Enzyme Replacements:Plasmalogen precursor supplementation addresses specific biochemical deficits without correcting underlying genetic defects. Swiss and German fermentation capacity constraints limit scalable production of docosahexaenoic acid-precursor lipids.
- Supportive Care:Symptom management protocols including anti-seizure regimens and nutritional optimization remain standard of care pending disease-modifying approvals. Pediatric metabolic centers in Japan and Germany anchor procurement for multidisciplinary care coordination.
Established volume favors Diagnostic Kits; emerging adoption favors Gene Therapies.
Application:
Cost tier separates reimbursed clinical workflows from grant-funded research activities.
- Clinical Diagnosis:Newborn screening reflex testing and symptomatic infant workups consume the majority of assay throughput. FDA-cleared and CE-marked devices under IVDR face notified body capacity constraints concentrating review in Benelux jurisdictions.
- Genetic Testing:Carrier detection in high-risk Ashkenazi Jewish and Japanese populations drives direct-to-consumer and telehealth channel expansion. Panel-based PEX gene analysis is displacing sequential single-gene workflows in academic medical centers.
- Research:Natural history study enrollment and biomarker qualification support regulatory submissions for gene therapy candidates. The Global Foundation for Peroxisomal Disorders coordinates specimen collection across 23 countries, redirecting contracts toward vendors with biorepository interoperability.
- Patient Management:Longitudinal monitoring of disease progression and treatment response requires integrated biochemical and functional assessment tools. Germany's G-BA assessment framework evaluates interventions against chronic care benchmarks, compressing pricing headroom for novel therapeutics.
Reimbursed clinical workflows dominate current spend; research applications capture expanding margin pools through biobank integration.
Technology:
Volume concentration favors platforms compatible with dried blood spot automation and high-throughput public health laboratory infrastructure.
- Mass Spectrometry:Liquid chromatography-tandem mass spectrometry hybridized with automated sample preparation enables C26:0 quantification in under two hours. PerkinElmer and Roche compete through integrated workflows reducing sample-to-result intervals for state screening programs.
- Next-Generation Sequencing:Panel-based PEX gene analysis replaces sequential testing, capturing margin expansion in confirmatory diagnostics. Capital sunk costs in regional Italian and Spanish laboratories resist conversion from legacy single-gene workflows.
- PCR:Targeted amplification supports rapid carrier detection and prenatal diagnostic applications. Bio-Rad specializes in kit formats for high-risk population screening with simplified workflow requirements.
- Biochemical Assays:Enzymatic activity measurement and plasmalogen synthesis assessment provide functional confirmation of peroxisomal dysfunction. Specialized substrate availability limits assay standardization across reference laboratory networks.
High-throughput platforms anchor public health contracts; NGS captures margin expansion in confirmatory testing.
End User:
Customer type determines procurement sophistication, from centralized tender processes through individual investigator grants.
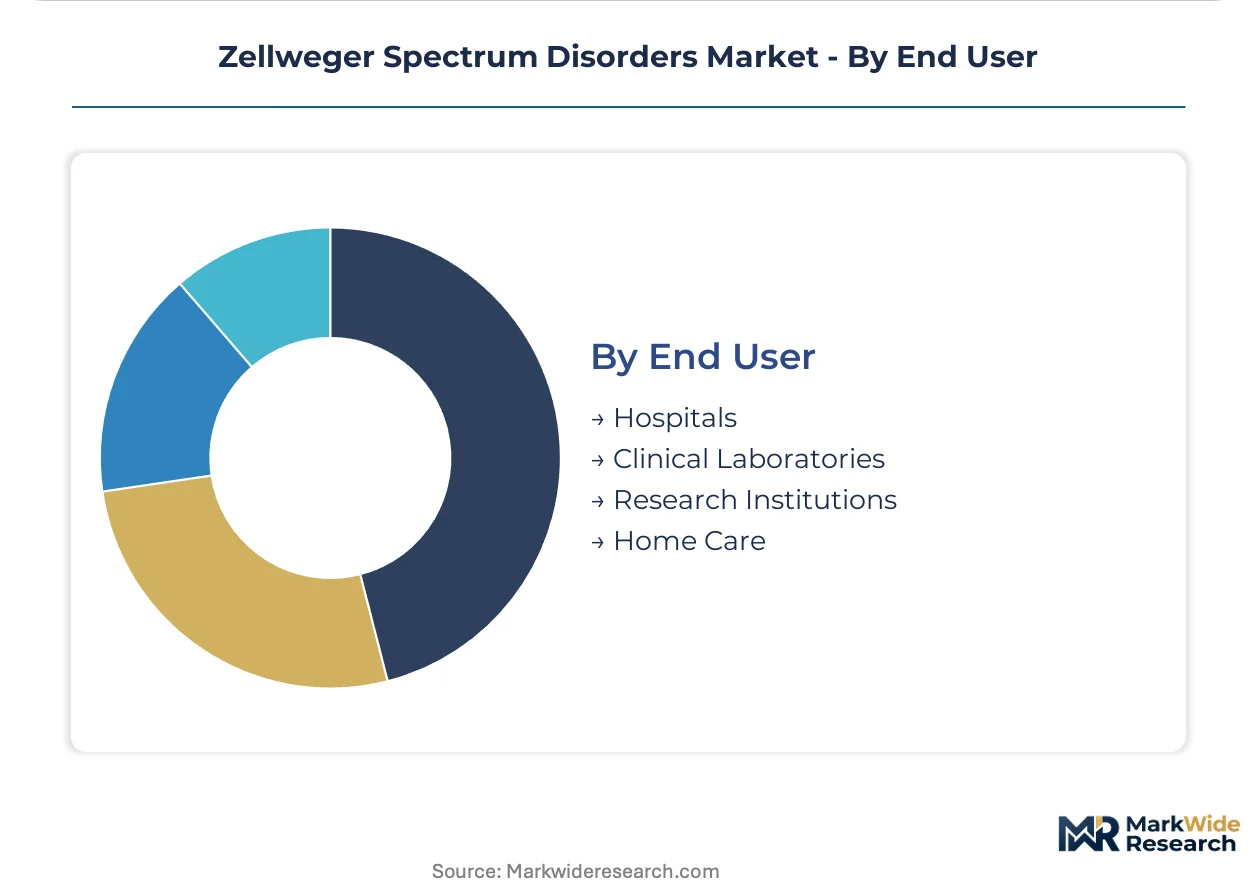
- Hospitals:Specialty pediatric hospitals and academic metabolic centers coordinate multidisciplinary care and clinical trial enrollment. Newborn screening expansion mandates in the United States, Germany, and Japan concentrate demand in centralized neonatal infrastructure.
- Clinical Laboratories:Public health reference laboratories and commercial diagnostic providers process high-volume screening with automated workflows. EU IVDR reclassification from self-certified to notified body-reviewed devices forces portfolio consolidation and market withdrawal of lower-volume assays.
- Research Institutions:Academic medical centers and contract research organizations advance gene therapy pipelines through natural history studies and biomarker qualification. Peroxisomal biologist talent scarcity creates recruitment competition from oncology and immunology programs.
- Home Care:Nutritional supplementation and symptom monitoring applications serve stable chronic patients outside acute care settings. Reimbursement parity constraints in Germany and other EU member states limit market development for non-clinical settings.
Institutional procurement dominates current revenue; home care channels await reimbursement framework evolution for chronic management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation capacity for plasmalogen precursors clusters in Switzerland and Germany, while gene therapy vector manufacturing concentrates in the United States and United Kingdom. Diagnostic kit procurement flows through centralized neonatal screening infrastructure in three dominant markets.
United States
Texas and California anchor newborn screening expansion through state-mandated very-long-chain fatty acid testing protocols. FDA orphan drug incentives compress regulatory timelines for AAV-based PEX gene delivery candidates entering Phase I/II trials. Boston and San Diego metabolic centers coordinate natural history study enrollment across 23 countries through the Global Foundation for Peroxisomal Disorders.
Germany
Bavaria and North Rhine-Westphalia host centralized diagnostic hubs serving cross-border healthcare access under EU Rare Disease Regulation. G-BA assessment frameworks evaluate gene therapies against chronic enzyme replacement benchmarks, compressing pricing headroom for curative interventions. Heidelberg and Munich academic centers maintain sequential PEX1/PEX2/PEX6 workflows that resist panel-based next-generation sequencing conversion.
Japan
PMDA priority review vouchers accelerate peroxisomal disorder therapeutic development timelines. Tokyo and Osaka pediatric metabolic centers anchor procurement for multidisciplinary care coordination and longitudinal patient management. METI funding supports domestic AAV vector manufacturing scale-up to reduce import dependence for investigational gene therapies.
Switzerland
Specialized fermentation infrastructure for docosahexaenoic acid-precursor lipids concentrates in Basel and Zurich industrial clusters. Swissmedic expedited pathways for rare disease therapeutics attract gene therapy headquarters relocations from larger EU jurisdictions. Plasmalogen synthesis complexity creates input bottlenecks that limit scalable enzyme replacement production.
Brazil
ANVISA expedited rare disease designation creates first-mover positioning for newborn screening kit manufacturers before regional competitors establish distribution. São Paulo and Rio de Janeiro public health laboratories adopt automated dried blood spot workflows for high-throughput C26:0 quantification. Federal newborn screening mandates remain under development, concentrating demand in private diagnostic channels.
Zellweger Spectrum Disorders Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagents and assay substrates. The vendor base separates into three distinct strata: multinational diagnostics conglomerates with neonatal screening platform dominance, mid-cap genetic testing specialists with PEX gene panel capabilities, and regional distributors serving emerging market access. Consolidation pressures concentrate in the middle tier as IVDR reclassification forces portfolio withdrawals. Competitive moves center on biorepository interoperability certification and AAV manufacturing capacity reservations.
Among the platform integrators, PerkinElmer Inc. and F. Hoffmann-La Roche Ltd occupy positions reflecting contrasting workflow philosophies—automated sample preparation versus integrated mass spectrometry. Bio-Rad Laboratories, Inc. exemplifies the specialist archetype with simplified PCR-based formats for high-risk population carrier detection. These three entities represent the dominant competitive anchors across diagnostic kit procurement, gene therapy development support, and research reagent supply respectively.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| F. Hoffmann-La Roche Ltd |
| Bio-Rad Laboratories, Inc. |
| Beckman Coulter, Inc. |
| CENTOGENE N.V. |
| Chromsystems Instruments & Chemicals GmbH |
| Trivitron Healthcare |
| Siemens |
| LifeCell International Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Specialized fermentation capacity for docosahexaenoic acid-precursor lipids clusters in Switzerland and Germany, concentrating margin capture upstream while diagnostic kit pricing power flows to public health laboratory procurement networks in the United States, Germany, and Japan.
Pricing Analysis
Germany's G-BA assessment framework dictates the pricing tier structure for curative interventions, compressing headroom for single-administration gene therapies against chronic enzyme replacement benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared newborn screening platforms from CE-marked diagnostic kits and research-grade reagents. Cost compression in standard-tier assays is intensifying because EU IVDR reclassification forces portfolio withdrawals and notified body capacity constraints. Public health reference laboratories exhibit the highest price sensitivity due to centralized tender processes, while academic metabolic centers prioritize biorepository interoperability over unit cost.
Supply Chain Analysis
Export controls on AAV vector manufacturing technology limit flows from United States and United Kingdom contract development organizations to emerging market gene therapy developers. Geographic supply concentration spans Switzerland and Germany for plasmalogen precursor fermentation, the United States for AAV production lines, and Japan for PMDA-registered diagnostic platforms. Raw material dependencies include very-long-chain fatty acid reference standards, PEX gene panel reagents, and specialized chromatography substrates. Single-source vulnerability in Swiss fermentation infrastructure creates input bottlenecks for enzyme replacement production. Distribution runs through centralized neonatal screening infrastructure anchored by state public health laboratories and academic metabolic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in peroxisomal disorder diagnostics is approaching an inflection as biorepository interoperability requirements redirect procurement toward vendors offering integrated specimen banking and natural history study enrollment.
For Market Incumbents: Insulate diagnostic kit margins by securing exclusive supply contracts with state newborn screening programs in Texas and California before IVDR reclassification forces mid-tier competitors to withdraw from European markets. Deepen backward integration into dried blood spot automation workflows to reduce sample-to-result intervals below two-hour thresholds demanded by high-throughput public health laboratories. For New Entrants and Emerging Players: Build out telehealth-enabled direct-to-patient genetic counseling platforms targeting high-risk Ashkenazi Jewish and Japanese populations outside traditional metabolic center referral pathways. Brazil's ANVISA expedited rare disease designation offers the most penetrable regulatory entry point for newborn screening kit manufacturers before regional competitors establish distribution networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap genetic testing specialists holding PEX gene panel capabilities but lacking biorepository interoperability certification required by academic metabolic center tenders. Long-term viability over a 5-10 year window hinges on positioning ahead of AAV-based PEX gene delivery approvals. The signal to watch is EMA priority medicines designation announcements compressing regulatory timelines for single-administration interventions.| Strategic Initiative | Industry Significance |
|---|---|
| Biorepository Interoperability Certification | The Global Foundation for Peroxisomal Disorders redirects diagnostic contracts toward vendors with certified specimen banking integration across 23 countries. |
| AAV Manufacturing Capacity Reservation | Contract development organizations building dedicated peroxisomal disorder production lines reduce cost-per-dose for investigational gene therapies entering Phase I/II trials. |
| EU IVDR Technical Documentation Rebuild | Notified body-reviewed device reclassification forces diagnostic kit suppliers to consolidate portfolios and withdraw lower-volume assays from Benelux jurisdictions. |
| Newborn Screening Mandate Expansion | State-level very-long-chain fatty acid testing protocols in Texas and California drive high-throughput diagnostic kit volumes through public health laboratory procurement. |
| Direct-to-Patient Telehealth Platform Launch | Genetic counseling bypasses metabolic center referrals in Australia and Canada, accelerating carrier detection in high-risk populations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug filings, EMA priority medicines designations, ClinicalTrials.gov entries, and state newborn screening mandate documentation. Interviews with pediatric metabolic center directors, diagnostic kit procurement managers at public health laboratories, regulatory affairs leads at gene therapy developers, and payer access specialists at Germany's G-BA anchor qualitative assessment. Bottom-up patient population estimates triangulate against top-down market size validation from biochemical assay throughput data.
Forecast inputs include newborn screening expansion trajectories, AAV manufacturing scale-up timelines, and IVDR implementation pace across EU member states. Segmentation dimensions span product type, application, technology platform, and end-user procurement sophistication. CAGRs derive from patient incidence modeling, pricing elasticity assumptions for single-administration versus chronic therapies, and capacity expansion schedules for specialized fermentation infrastructure. Industry-specific inputs incorporate PEX gene therapy clinical pipeline advancement rates and dried blood spot automation adoption curves in state public health laboratories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by contract development organizations reserving AAV manufacturing capacity ahead of clinical data readouts would shift outcomes. Material shifts in EMA priority medicines designation timelines or FDA orphan drug incentive structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Rare Diseases Treatment Market