
 Down Syndrome Market | 2026-2036
Down Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Down Syndrome Market Intelligence
Specialized therapeutic-grade biologics is bifurcating the competitive landscape into high-complexity developers and broad-platform service providers. AC Immune SA leverages its antibody discovery engine to target neurodegenerative mechanisms in Down syndrome-associated Alzheimer's. Pfizer Inc. sustains one of the industry's deepest rare-disease pipelines through dedicated R&D allocation. Roche anchors European clinical trial networks with its established diagnostic-therapeutic integration model.
Down syndrome, or trisomy 21, constitutes a genetic condition arising from a complete or partial extra copy of chromosome 21, affecting approximately 1 in 700 live births and manifesting across cognitive, cardiac, endocrine, and musculoskeletal systems. Its primary commercial purpose spans prenatal screening, postnatal diagnostic confirmation, lifelong therapeutic intervention, and supportive care services that improve functional outcomes and life expectancy. Therapeutics captures the dominant value pool as disease-modifying candidates advance through Phase II trials, while Diagnostic Tests maintains stable demand from non-invasive prenatal testing expansion across maternal-fetal medicine networks. Support Services represents the fastest-growing margin segment as payers shift toward bundled care models covering genetic counseling, occupational therapy, and behavioral therapy under single reimbursement codes.
The FDA's orphan drug program and Breakthrough Therapy designation reshape clinical development economics by granting market exclusivity and expedited review timelines for Down syndrome-targeted therapeutics. EMA's Paediatric Investigation Plan requirements and the EU's Clinical Trials Regulation standardize pediatric study protocols across member states, influencing trial design for multinational pharmaceutical sponsors including Novartis Pharmaceuticals Corporation and Roche. Stakeholders must monitor how CMS coverage determinations for cell and gene therapies will restructure reimbursement for emerging trisomy 21 interventions before committing capital to late-stage development programs.
Market Dynamics
The orphan drug designation pathway is compressing clinical development timelines for trisomy 21 therapeutics while fragmenting competitive positioning between gene therapy developers and small-molecule platforms.
Growth Catalysts
- FDA Breakthrough Therapy designation:The expedited review framework accelerates Phase II-to-III transitions for disease-modifying candidates targeting neurodegenerative progression in Down syndrome-associated Alzheimer's.
- Pediatric hospital networks:Integrated care protocols across maternal-fetal medicine centers are expanding diagnostic capture and longitudinal patient enrollment into therapeutic trials.
- Non-invasive prenatal testing:Cell-free DNA screening platforms are penetrating obstetric practices earlier in gestational windows, expanding addressable screening populations.
Market Restraints
- Specialized manufacturing capacity:Viral vector production constraints and plasmid supply bottlenecks limit gene therapy scale-up for trisomy 21 indications.
- Reimbursement uncertainty:CMS coverage determinations for cell and gene therapies remain unresolved, delaying payer commitment to novel intervention pricing.
- Clinical endpoint validation:Cognitive assessment batteries lack harmonization across trial sites, complicating regulatory submission packages for neurodevelopmental targets.
Strategic Opportunities
- EU Paediatric Investigation Plans:EMA-mandated pediatric study requirements create dedicated development pathways with protocol assistance and potential fee waivers for sponsors.
- Bundled care reimbursement:Single-code models covering genetic counseling, occupational therapy, and behavioral intervention are expanding margin capture in support services.
- Digital biomarker integration:Wearable cognitive monitoring and remote patient reporting platforms are converging with traditional clinical outcome assessments.
Industry Challenges
- Patient registry fragmentation:Down syndrome research cohorts remain siloed across academic medical centers, complicating natural history data assembly for regulatory filings.
- Trial recruitment velocity:Informed consent complexity for cognitively impaired participants extends enrollment timelines and increases site costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Down Syndrome Market |
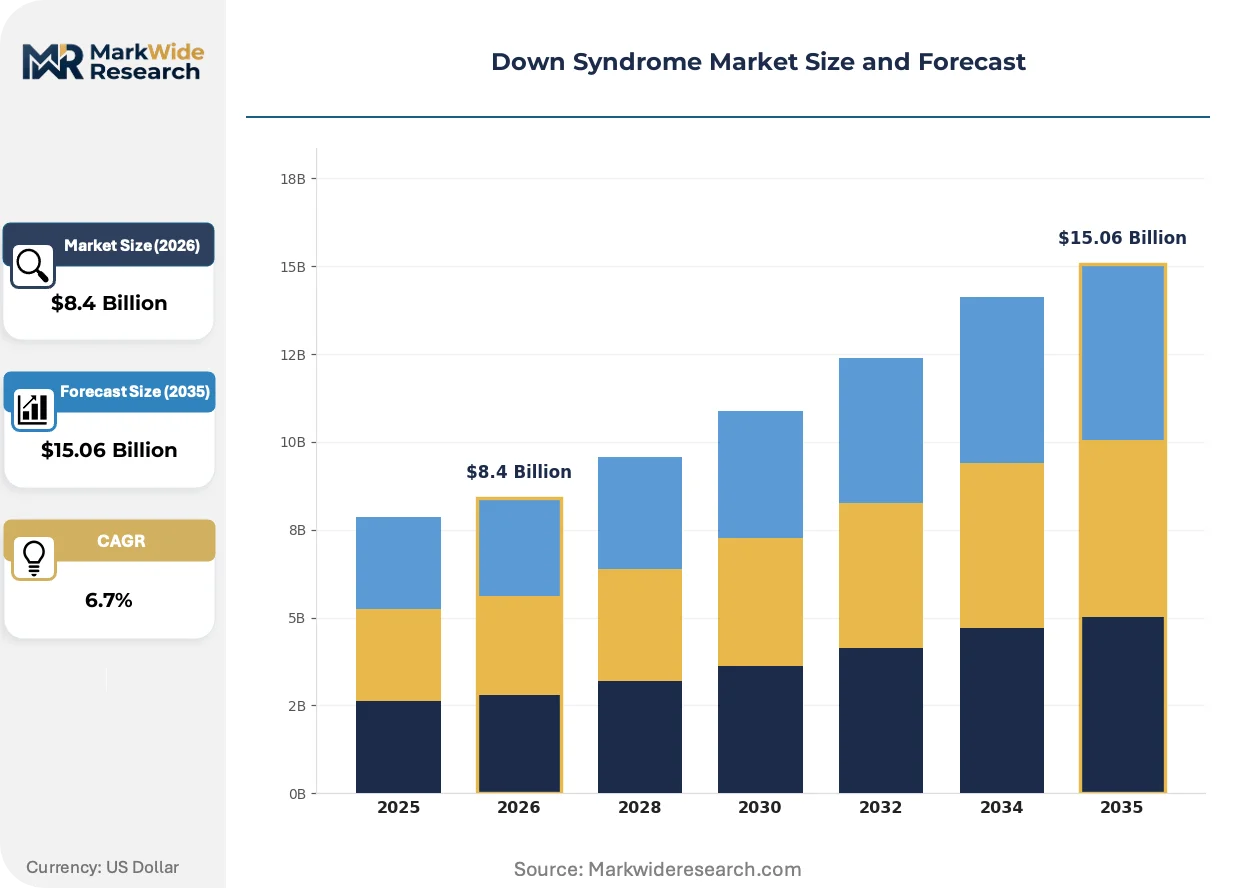
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutics, Diagnostic Tests, Educational Tools, Support Services Age Group: Infants, Children, Adolescents, Adults Care Setting: Hospitals, Clinics, Home Care, Educational Institutions Service Type: Genetic Counseling, Occupational Therapy, Speech Therapy, Behavioral Therapy |
| Companies Covered | AC Immune SA, Alzheon, Inc., Pfizer Inc., Myriad Genetics, Thermo Fisher Scientific, Roche, Annovis Bio, Inc., Natera, Novartis Pharmaceuticals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Down Syndrome Market Strategic Shifts & Innovations
Biomarker-driven trial design and decentralized clinical operations are restructuring how trisomy 21 therapeutics advance through regulatory gates.
Antibody-based neurodegenerative targeting is displacing traditional symptomatic management in Down syndrome-associated Alzheimer's development. Biologics developers are prioritizing tau and amyloid clearance mechanisms over cholinesterase inhibitors. Academic medical centers with dedicated trisomy 21 clinics are accelerating adoption of these candidates into early-phase protocols.
EMA's Clinical Trials Regulation standardization is compressing multinational protocol approval timelines across member states. The centralized submission portal and harmonized safety reporting requirements reduce administrative redundancy for sponsors running pediatric studies. Roche and Novartis are restructuring European trial footprints to exploit these procedural efficiencies.
Genetic counseling service unbundling from traditional obstetric bundles is creating direct-to-patient channels. Telehealth platforms and at-home sample collection are displacing clinic-based prenatal consultation models. Maternal-fetal medicine networks in the United States are piloting hybrid virtual-physical care pathways to extend reach into underserved catchment areas.
Down Syndrome Market Segmentation
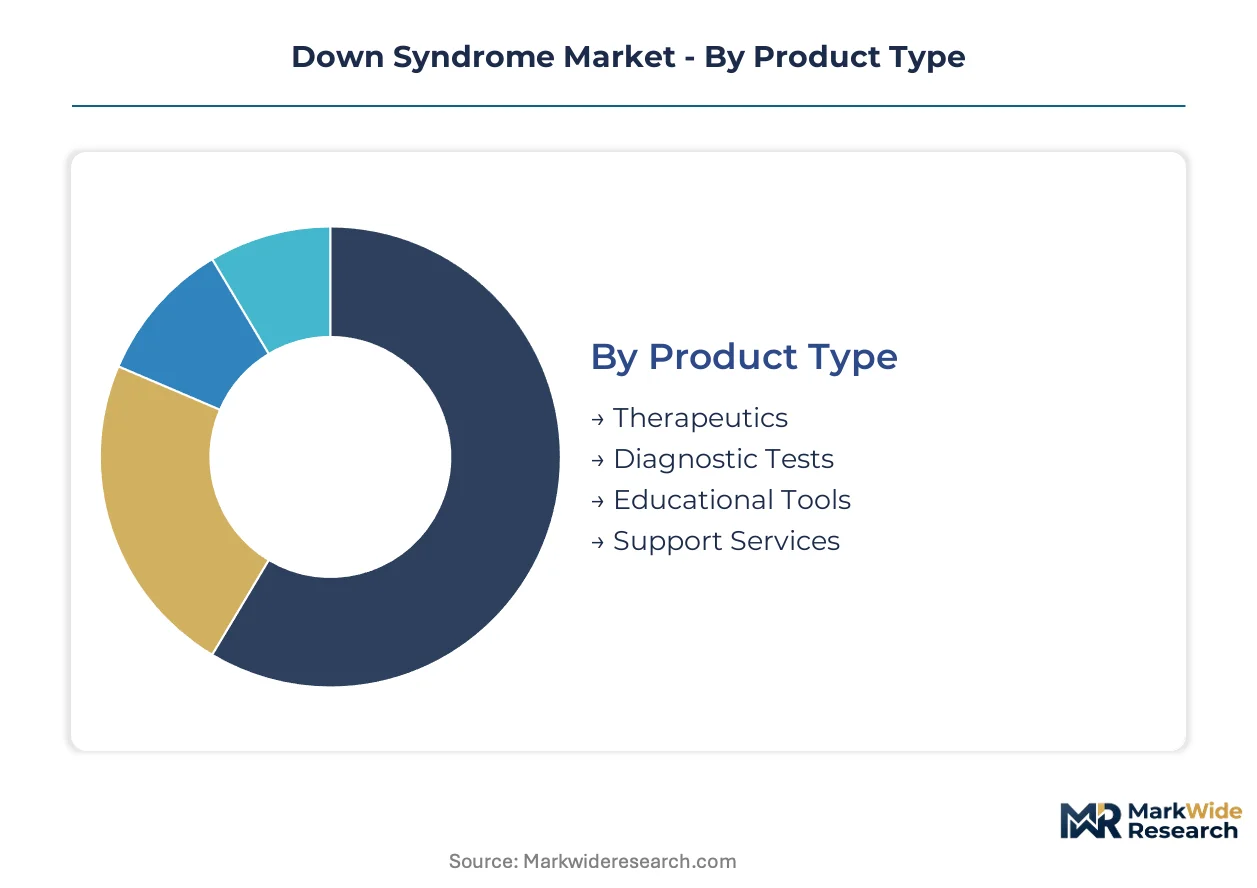
Segmentation in the Down syndrome market reveals distinct value capture mechanisms across intervention modalities and care delivery models. Understanding these divisions enables stakeholders to align R&D investments, reimbursement strategies, and distribution infrastructure with where clinical and commercial momentum concentrates.
Product Type:
Domestic demand concentrates in diagnostic and support categories, while therapeutics development attracts export-oriented biopharma investment from European and North American sponsors.
- Therapeutics:Disease-modifying candidates targeting neurodegenerative progression and cognitive enhancement dominate late-stage pipelines. FDA orphan drug designation accelerates development timelines for sponsors targeting the US market, though manufacturing scale-up constraints limit near-term volume expansion.
- Diagnostic Tests:Non-invasive prenatal testing platforms using cell-free DNA analysis command premium pricing in maternal-fetal medicine networks. Adoption concentrates in the United States and Western Europe where reimbursement infrastructure supports routine screening protocols.
- Educational Tools:Specialized learning software and adaptive communication devices serve institutional procurement channels.
- Support Services:Bundled care models covering behavioral and occupational intervention are expanding margin capture fastest.
Therapeutics holds the largest share; momentum sits with Support Services.
Age Group:
Volume concentrates in pediatric populations where diagnostic capture and early intervention protocols drive service utilization, while adult segments represent underpenetrated expansion territory.
- Infants:Newborn screening mandates and early diagnostic confirmation protocols generate immediate demand for genetic counseling and cardiac assessment services. Pediatric hospital networks in the United States and Germany anchor clinical trial enrollment for disease-modifying candidates.
- Children:Educational intervention and developmental therapy represent the most intensive resource utilization phase. School-based service delivery models in the United Kingdom and France are piloting integrated IEP-therapy coordination.
- Adolescents:Transition planning and vocational preparation services bridge pediatric and adult care systems.
- Adults:Neurodegenerative monitoring and independent living support remain structurally underdeveloped relative to clinical need.
Children generates highest service volume; adults present the steepest expansion trajectory.
Care Setting:
Cost tier stratification separates acute institutional settings from emerging home-based and virtual delivery models.
- Hospitals:Academic medical centers with dedicated trisomy 21 clinics anchor complex diagnostic workups and clinical trial access. Johns Hopkins, Boston Children's, and University College London Hospitals maintain the deepest longitudinal patient cohorts.
- Clinics:Community-based specialty practices handle routine surveillance and therapy coordination. Federally qualified health centers in the United States are expanding Down syndrome-specific service lines under HRSA funding mechanisms.
- Home Care:Remote patient monitoring and telehealth-delivered behavioral intervention are displacing clinic-based models.
- Educational Institutions:School-based therapy provision varies by district funding and special education policy implementation.
Hospitals command premium reimbursement; home care is gaining share fastest.
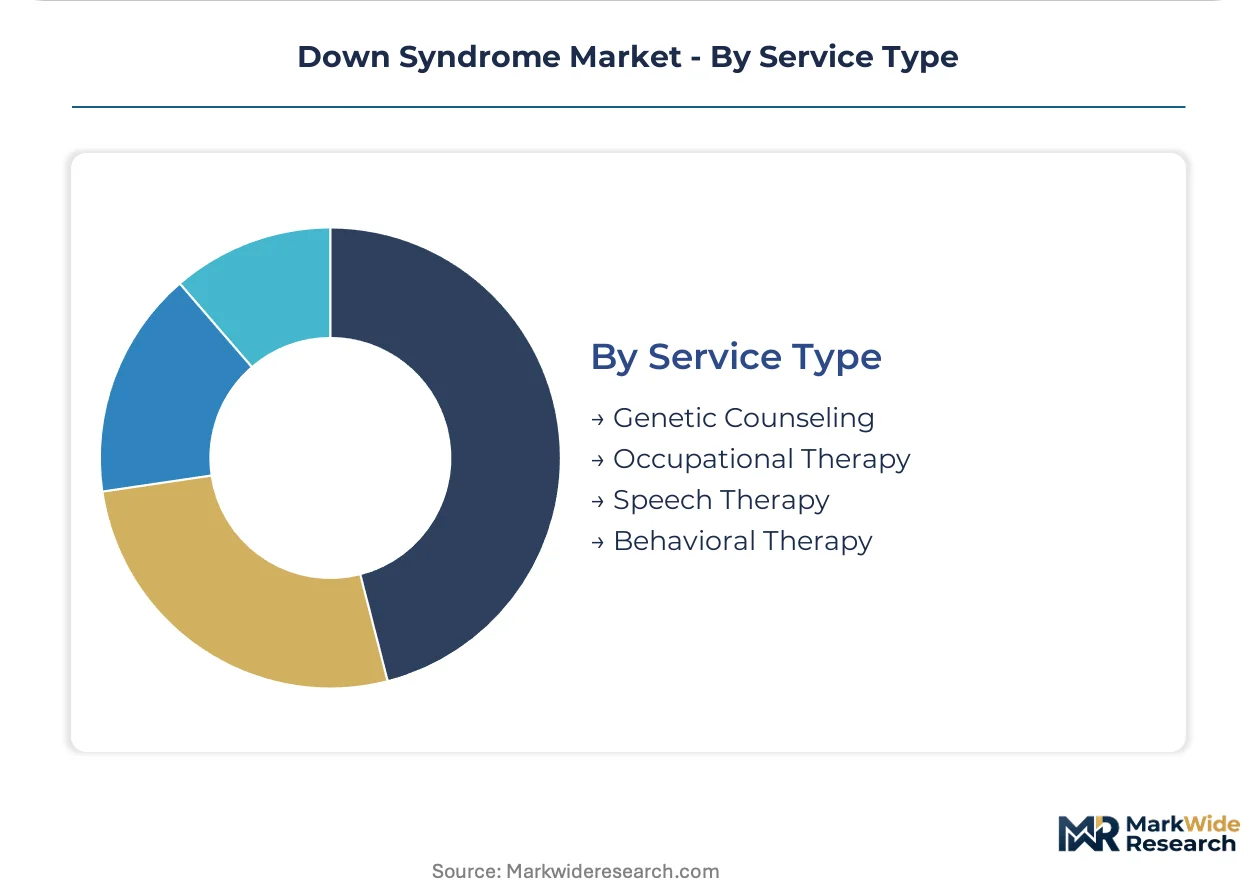
Service Type:
Application focus distinguishes preventive-genetic services from ongoing functional intervention modalities.
- Genetic Counseling:Prenatal and postnatal consultation services face margin pressure from telehealth unbundling and direct-to-consumer testing proliferation. Independent genetic counselors in the United States are capturing volume from traditional obstetric practice bundles.
- Occupational Therapy:Adaptive skill development for daily living independence represents the most standardized reimbursement category. Medicaid waiver programs in California and New York sustain highest per-capita utilization rates.
- Speech Therapy:Communication intervention spans clinical and educational delivery channels.
- Behavioral Therapy:Applied behavior analysis and mental health support are expanding fastest under autism-comorbidity recognition.
Occupational Therapy holds the largest share; Behavioral Therapy shows strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biopharma exports flow into United States clinical trial networks, while Swiss diagnostic platforms reach maternal-fetal medicine centers across Western Europe. Trade corridors concentrate high-value therapeutics and screening technologies between these established hubs.
United States
Pediatric hospital networks and specialized trisomy 21 clinics drive diagnostic capture and therapeutic trial enrollment. FDA orphan drug designation and Breakthrough Therapy pathways compress development timelines for disease-modifying candidates. Boston Children's Hospital and Johns Hopkins anchor longitudinal patient cohorts that feed multinational pharmaceutical studies.
Germany
Academic medical centers with dedicated Down syndrome service lines generate robust natural history data for regulatory submissions. EMA Paediatric Investigation Plans standardize pediatric study protocols across member states, creating procedural efficiencies. University College London Hospitals and Heidelberg University Hospital maintain deep research cohorts that attract Phase II protocol placements.
Switzerland
Diagnostic-therapeutic integration models and precision medicine infrastructure concentrate value capture. Swissmedic regulatory frameworks align with EMA standards while offering specialized pathways for rare disease candidates. Basel and Zurich anchor European clinical trial operations for multinational sponsors.
United Kingdom
NHS England's specialized commissioning frameworks fund comprehensive trisomy 21 care pathways from prenatal screening through adult transition services. MHRA post-Brexit regulatory autonomy enables streamlined protocol approvals for pediatric studies. London and Manchester academic centers pilot integrated educational-therapy coordination models.
Japan
PMDA Sakigake designation accelerates review timelines for novel neurodevelopmental therapeutics targeting Down syndrome-associated cognitive decline. METI funding mechanisms support domestic biotech development in rare disease indications. Tokyo and Osaka university hospitals expand newborn screening mandates that drive early diagnostic confirmation.
Down Syndrome Market Key Industry Players
Listed leaders compete with private specialists across therapeutic modality and diagnostic platform development. The competitive structure bifurcates between consolidated biopharma developers with rare disease pipelines and fragmented diagnostic service providers. Three archetypes dominate: antibody-based neurodegenerative developers, cell-free DNA screening platforms, and integrated care service networks. Capacity expansion into viral vector manufacturing and strategic partnerships with academic medical centers represent the dominant competitive moves.
Within the antibody-discovery archetype, AC Immune SA exemplifies specialized neurodegenerative targeting, while Pfizer Inc. occupies a position as a diversified rare disease developer with dedicated R&D allocation. Roche anchors the diagnostic-therapeutic integration tier, representing European clinical trial network consolidation.
| Leading Market Players |
|---|
| AC Immune SA |
| Alzheon, Inc. |
| Pfizer Inc. |
| Myriad Genetics |
| Thermo Fisher Scientific |
| Roche |
| Annovis Bio, Inc. |
| Natera |
| Novartis Pharmaceuticals Corporation |
| Others |
Cost & Logistics Intelligence
Cell-free DNA screening platforms displacing amniocentesis in maternal-fetal medicine networks simultaneously concentrates diagnostic supply in United States and Western European laboratory hubs while compressing reimbursement economics for legacy invasive procedures. This substitution dynamic reshapes how prenatal testing value flows through health systems and where manufacturers anchor production capacity.
Pricing Analysis
Next-generation sequencing-based non-invasive prenatal testing commands premium positioning against first-trimester combined screening and second-tier diagnostic confirmation. Three-tier pricing structure across premium cell-free DNA platforms, standard biochemical screening panels, and economy ultrasound-based protocols stratifies access by insurance coverage depth and gestational timing preferences. Pricing pressure stems from Medicaid reimbursement compression in United States state programs and NHS England's standardized commissioning tariffs. Price-sensitive buyers cluster in federally qualified health centers and developing-market public health systems, while academic medical centers with dedicated maternal-fetal medicine units exhibit lowest sensitivity due to research trial subsidies and philanthropic funding channels.
Supply Chain Analysis
Inventory cycles for viral vector gene therapy candidates extend 18-24 months from plasmid procurement through fill-finish, constraining sponsor ability to respond to accelerated FDA review timelines. Plasmid DNA manufacturing concentrates in United States contract development organizations, while sterile fill-finish capacity clusters in Switzerland and Germany under EMA-inspected facilities. Raw material dependencies span recombinant proteins from Chinese expression systems, specialized cell culture media from United States suppliers, and single-use bioreactor components from regional European distributors. Single-source vulnerability in plasmid supply chains represents the dominant structural risk following recent FDA warning letters to major contract manufacturers. Distribution runs through cold-chain logistics networks anchored by specialty pharmacy relationships with academic medical center outpatient pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Down syndrome market exhibits defensive moat characteristics rooted in regulatory entrenchment: FDA orphan drug exclusivity and EMA Paediatric Investigation Plan fee waivers create decade-long barriers to competitive entry for disease-modifying candidates. Network effects in longitudinal patient registries at Johns Hopkins, Boston Children's, and University College London Hospitals further reinforce incumbent positioning.
For Market Incumbents: Consolidate viral vector manufacturing capacity through captive production facilities or exclusive multi-year supply agreements with CDMOs holding active FDA Type II drug master files. Gene therapy developers face acute margin pressure from plasmid supply bottlenecks; backward integration into plasmid manufacturing or strategic partnerships with academic medical center cell therapy facilities represents the priority defensive lever. Second-mover biologics sponsors threaten neurodegenerative positioning; accelerate Phase II-to-III transitions through Breakthrough Therapy designation applications to compress competitive response windows.
For New Entrants and Emerging Players: Adult transition services for neurodegenerative monitoring and independent living support represent the most penetrable white-space segment, structurally underdeveloped relative to pediatric and adolescent care protocols. Telehealth-delivered behavioral therapy and remote cognitive assessment platforms offer direct-to-patient channels unencumbered by incumbent hospital network relationships. Go-to-market positioning should emphasize outcomes-based contracting with Medicaid managed care organizations seeking to reduce institutional placement costs for adult Down syndrome populations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed genetic testing platforms possessing CLIA-certified laboratory infrastructure and established payer contracts but lacking therapeutic development capabilities. Long-term viability across the analysis window hinges on successful navigation from screening commoditization toward integrated diagnostic-therapeutic service models. Acquisition targets with embedded clinical trial site networks and FDA master file documentation command premium positioning. The signal to watch is CMS national coverage determination for cell and gene therapies, which would restructure reimbursement economics and validate late-stage development program valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Expedited review compresses Phase II-to-III timelines for neurodegenerative candidates targeting Down syndrome-associated Alzheimer's progression. |
| EMA Paediatric Investigation Plan Compliance | Protocol assistance and fee waivers standardize pediatric study requirements across European member states for multinational sponsors. |
| Viral Vector Manufacturing Scale-Up | Captive production capacity insulates gene therapy developers from plasmid supply bottlenecks constraining industry-wide expansion. |
| Academic Medical Center Partnership | Longitudinal patient registry access accelerates natural history data assembly and clinical trial enrollment velocity. |
| Bundled Care Reimbursement Strategy | Single-code models covering genetic counseling, occupational therapy, and behavioral intervention expand margin capture in support services. |
Research Approach
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings against secondary validation from FDA orphan drug designations, EMA Paediatric Investigation Plan submissions, ClinicalTrials.gov protocol registrations, and CMS national coverage determination filings. Bottom-up segmentation modeling triangulates against top-down market sizing derived from pharmaceutical pipeline valuations and diagnostic platform reimbursement data.
Sensitivity analysis across patient population projections, regulatory approval probability assumptions, and reimbursement scenario weights informs the analytical framework. Segmentation dimensions span intervention modality, age group, care setting, and service type across the modeling period. CAGRs derive from normalized historical growth patterns adjusted for pipeline maturation curves and regulatory pathway acceleration effects. Forecast inputs incorporate FDA Breakthrough Therapy designation velocity, EMA centralized procedure adoption rates, and Medicaid waiver program expansion trajectories.
Material uncertainties — regulatory approval delays, manufacturing scale-up failures, and reimbursement determination reversals — sit outside the modeled envelope. Forecasts reflect assumptions regarding pipeline progression and payer policy continuity. Revision becomes warranted when CMS coverage determinations for cell and gene therapies cross thresholds that restructure commercial pricing expectations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Methylmalonic Acidemia Market