
 Andersen-Tawil Syndrome Market | 2026-2036
Andersen-Tawil Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Andersen-Tawil Syndrome Market Analytics
Rare disease project financing and milestone-based venture structures is reconfiguring how developers fund clinical programs for ultra-small patient populations. Pfizer Inc. leverages its established rare disease infrastructure to navigate regulatory pathways for ion channel therapies. Novartis AG anchors its portfolio through specialized neuromuscular research units with dedicated electrophysiology capabilities. Teva Pharmaceutical Industries competes via generic accessibility programs that broaden patient reach for chronic potassium management.
Andersen-Tawil Syndrome constitutes a rare autosomal dominant disorder characterized by periodic paralysis, cardiac arrhythmias, and dysmorphic features, stemming from mutations in the KCNJ2 gene encoding the inward rectifier potassium channel Kir2.1; diagnostic confirmation requires prolonged QT interval assessment with U-wave analysis alongside genetic testing. Therapeutics dominate the product landscape, with potassium channel modulators and antiarrhythmic agents capturing the core margin pool. Diagnostic Kits represent the fastest-growing segment as electrophysiology laboratories expand genetic screening panels for unexplained periodic paralysis presentations. Hospitals anchor end-user demand through integrated channelopathy clinics that coordinate cardiology and neurology services.
The FDA's Orphan Drug Act and breakthrough therapy designation frameworks shape development economics by granting extended exclusivity and expedited review for qualifying therapies. EMA's rare disease regulatory incentives and the EU's cross-border healthcare directives facilitate multi-national patient access and centralized marketing authorization for novel treatments. Stakeholders must monitor how evolving pharmacovigilance requirements for gene-targeted therapies reshape post-market commitment burdens and commercialization timelines.
Market Dynamics
The Andersen-Tawil Syndrome market pivots on regulatory exclusivity economics, where FDA Orphan Drug Act incentives and EMA rare disease frameworks compress development timelines for potassium channel modulators while fragmenting commercialization across ultra-small patient pools.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Expedited review pathways accelerate ion channel drug candidates through clinical phases, reducing time-to-market for novel Kir2.1-targeted therapies.
- Electrophysiology Laboratory Expansion:Academic medical centers in the United States are deploying next-generation genetic screening panels that capture unexplained periodic paralysis cases previously missed by standard cardiac workups.
- Cross-Border Healthcare Directives:EU centralized marketing authorization enables multi-national patient access, pooling ultra-rare cases across member states to sustain viable commercial populations for specialty therapies.
Market Restraints
- Ultra-Small Patient Populations:Prevalence estimates below one per million strain trial enrollment, forcing extended recruitment timelines and inflated per-patient clinical costs.
- Potassium Channel Specificity Limitations:Off-target effects of broad-acting modulators complicate dosing regimens and narrow therapeutic windows for cardiac rhythm management.
- Reimbursement Fragmentation:Payer heterogeneity across national health systems creates access barriers, with some markets requiring multiple prior authorizations for genetic confirmation and chronic therapy.
Strategic Opportunities
- Companion Diagnostic Integration:FDA-cleared genetic test kits bundled with channel modulator therapies create differentiated positioning and streamline payer coverage decisions.
- Pediatric Indication Expansion:EMA's pediatric investigation plans and US pediatric priority review vouchers reward developers addressing early-onset periodic paralysis presentations.
- Telemedicine Channel Development:Virtual neuromuscular consultations collapse geographic barriers to specialized channelopathy care, capturing patients in underserved rural and exurban regions.
Industry Challenges
- Electrophysiology Talent Scarcity:Shortages of trained genetic counselors and cardiac electrophysiologists limit diagnostic throughput and patient identification rates.
- Post-Market Surveillance Burden:EMA pharmacovigilance requirements for gene-targeted therapies mandate extended safety follow-up, inflating commercialization costs beyond traditional rare disease benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Andersen-Tawil Syndrome Market |
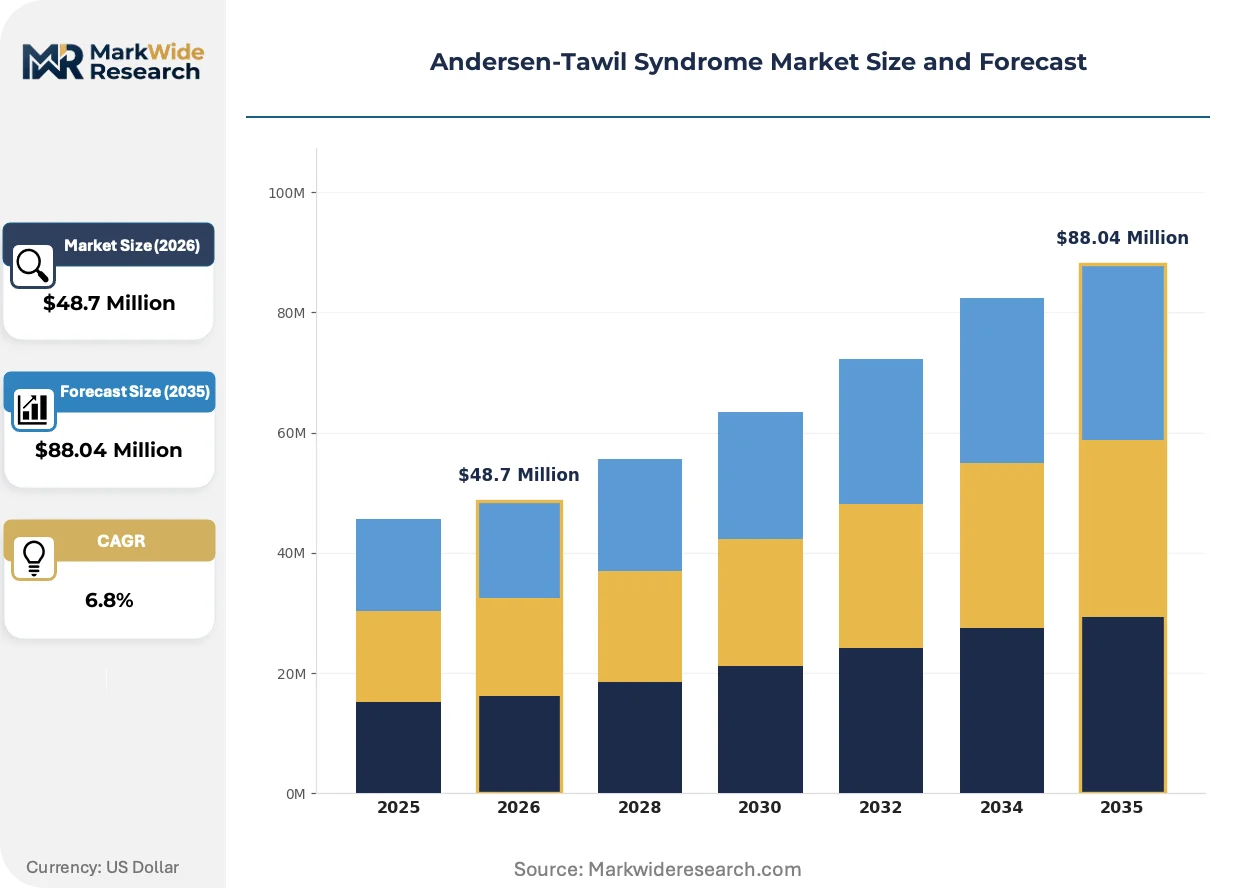
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Therapeutics, Research Tools, Treatment Monitoring Devices End User: Hospitals, Clinical Laboratories, Research Institutions, Pharmacies Therapy Area: Genetic Disorders, Rare Diseases, Cardiovascular Health, Neuromuscular Conditions Delivery Mode: Injectables, Oral Medications, Infusions, Monitoring Devices |
| Companies Covered | Merck, Teva Pharmaceutical Industries, Pfizer Inc., Novartis AG, Sun Pharmaceutical Industries, Xeris Biopharma, Hikma Pharmaceuticals, Alembic Pharmaceuticals, Advanz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Andersen-Tawil Syndrome Market Evolving Landscape
Precision medicine architectures are restructuring how ultra-rare channelopathies move from symptom management to genetic etiology targeting, compressing the gap between diagnostic confirmation and mechanism-based intervention.
Next-generation sequencing panels is collapsing the diagnostic odyssey for Andersen-Tawil Syndrome, replacing serial single-gene testing with simultaneous ion channel gene interrogation. Academic electrophysiology laboratories in the United States and Germany are adopting these platforms within 18-month procurement cycles. This compression is eliminating the historical 4-7 year delay between symptom onset and genetic confirmation that previously delayed appropriate cardiac surveillance.
EMA's adaptive licensing pathways and FDA's rare disease endpoint advancement initiatives are reshaping evidentiary standards for periodic paralysis therapies, permitting surrogate endpoints and smaller trial populations. Developers are responding with master protocol designs that test multiple potassium channel modulators against shared control arms. Cardiac safety monitoring requirements now dominate protocol development, with Holter-based arrhythmia burden replacing subjective paralysis frequency as primary endpoints.
Patient advocacy networks are consolidating procurement influence, with disease-specific foundations in the United States and France now contracting directly with specialty pharmacies to secure preferred formulary placement and adherence support services. These consolidated buying pools are displacing fragmented individual patient access programs. The National Organization for Rare Disorders and similar European federations anchor this shift, particularly for therapies requiring complex electrolyte monitoring protocols.
Andersen-Tawil Syndrome Market Segmentation
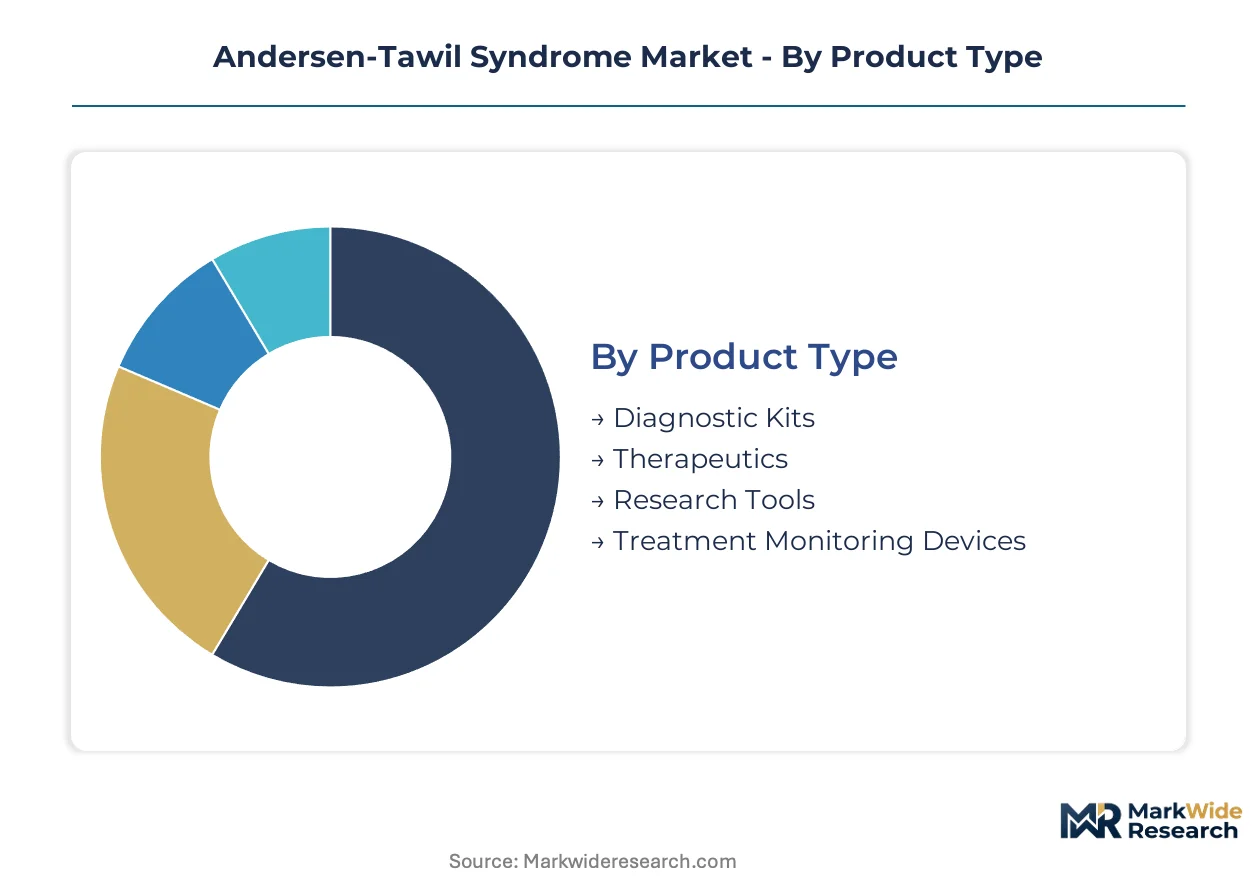
Segmentation in the Andersen-Tawil Syndrome market reveals distinct procurement cycles across product categories, with diagnostic and therapeutic segments operating on fundamentally different replenishment rhythms. Understanding these temporal patterns helps suppliers align inventory and service models with actual clinical workflows.
Product Type:
Cycle times vary dramatically across this category, spanning single-use consumables with quarterly replenishment to capital-intensive monitoring platforms with decade-long replacement horizons.
- Therapeutics:Potassium channel modulators and antiarrhythmic agents constitute the core revenue pool, with chronic administration driving predictable reorder patterns through hospital pharmacies. Academic medical centers in the United States with dedicated channelopathy programs anchor demand concentration, though EMA centralized authorization is expanding addressable populations across Germany and France.
- Diagnostic Kits:Next-generation sequencing panels for KCNJ2 mutation screening are displacing serial single-gene testing, with electrophysiology laboratories in the United States and Germany completing procurement cycles within eighteen months. This segment is expanding most quickly as unexplained periodic paralysis cases previously missed by standard cardiac workups now receive genetic confirmation.
- Research Tools:Kir2.1 channel antibodies and electrophysiology reagents support preclinical investigation, with demand clustering at NIH-funded institutions and European Research Council grantees.
- Treatment Monitoring Devices:Holter monitors and implantable loop recorders for arrhythmia surveillance carry extended replacement cycles, with procurement concentrated at quaternary care centers.
Therapeutics anchors the volume base while Diagnostic Kits gains share at the steepest rate.
End User:
Customer concentration patterns reflect the specialized infrastructure required for channelopathy diagnosis and management, creating tiered access barriers.
- Hospitals:Integrated channelopathy clinics coordinating cardiology and neurology services constitute the dominant procurement node, with rare disease specialty clinics expanding neuromuscular service lines as the primary buyer segment. These centers leverage FDA breakthrough therapy designation pathways to accelerate novel therapy access.
- Clinical Laboratories:CAP-accredited and CLIA-certified facilities performing genetic confirmation testing operate on reference lab contracting models, with electrophysiology talent scarcity limiting diagnostic throughput at secondary sites.
- Research Institutions:Academic medical centers with dedicated electrophysiology capabilities anchor preclinical demand, particularly those hosting Specialized Centers of Research Excellence.
- Pharmacies:Specialty pharmacy networks manage distribution for chronic potassium management therapies, with patient advocacy networks consolidating procurement influence through direct foundation contracting.
Hospitals command the procurement volume base while Clinical Laboratories demonstrates the steepest expansion trajectory.
Therapy Area:
Reimbursement complexity and regulatory pathway differentiation create distinct margin profiles across therapeutic classifications.
- Genetic Disorders:Etiology-targeted interventions for KCNJ2 mutations qualify for FDA Orphan Drug Act incentives and EMA rare disease frameworks, compressing development timelines while fragmenting commercialization across ultra-small patient pools.
- Cardiovascular Health:Arrhythmia management protocols dominate acute care resource allocation, with prolonged QT interval assessment and U-wave analysis constituting standard surveillance.
- Neuromuscular Conditions:Periodic paralysis symptom management requires coordinated electrolyte monitoring, with patient identification rates constrained by electrophysiology talent scarcity.
- Rare Diseases:Cross-cutting designation enabling multi-national patient access through EU cross-border healthcare directives.
Cardiovascular Health anchors the volume base while Genetic Disorders gains share at the steepest rate.
Delivery Mode:
Route-of-administration preferences reflect the tension between acute intervention requirements and chronic disease management practicality.
- Oral Medications:Chronic potassium management and antiarrhythmic maintenance therapy default to oral routes, with generic accessibility programs broadening patient reach. Teva Pharmaceutical Industries competes through this channel.
- Injectables:Acute periodic paralysis rescue protocols and emergency arrhythmia intervention require parenteral administration, with hospital-based administration capturing premium pricing.
- Infusions:Electrolyte replacement and specialized potassium repletion in monitored settings.
- Monitoring Devices:Non-invasive and implantable cardiac surveillance platforms with extended service revenue models.
Oral Medications anchors the volume base while Monitoring Devices gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare disease specialty clinics anchor procurement concentration in the United States, while academic medical centers with channelopathy programs in Germany and France pool ultra-rare cases through cross-border access frameworks.
United States
Academic medical centers with dedicated electrophysiology capabilities drive diagnostic throughput for unexplained periodic paralysis cases. FDA Orphan Drug Act incentives compress development timelines for potassium channel modulators. The Boston-Cambridge corridor anchors specialized channelopathy clinics coordinating cardiology and neurology services.
Germany
EMA centralized authorization enables multi-national patient pooling across member states to sustain viable commercial populations. The country's national pharmaceutical regulator facilitates adaptive licensing pathways for rare disease endpoints. Heidelberg and Munich host Specialized Centers of Research Excellence with dedicated Kir2.1 research programs.
France
Patient advocacy foundations contract directly with specialty pharmacies to secure preferred formulary placement for chronic potassium management therapies. ANSM rare disease frameworks streamline marketing authorization for genetic etiology-targeted interventions. The Paris-Saclay cluster concentrates electrophysiology talent for genetic counselor training programs.
Switzerland
Swissmedic regulatory incentives attract developers seeking pediatric indication expansion through priority review mechanisms. Geneva and Basel anchor preclinical ion channel research with NIH and European Research Council grant funding. Specialized neuromuscular research units with electrophysiology capabilities cluster near university hospitals.
United Kingdom
NHS specialized commissioning frameworks consolidate procurement for ultra-rare genetic disorders through designated treatment centers. MHRA recognition of FDA breakthrough therapy designations accelerates access timelines for novel arrhythmia therapies. London and Oxford anchor integrated channelopathy clinics with next-generation sequencing panel deployment.
Andersen-Tawil Syndrome Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where large-cap pharmaceutical companies leverage rare disease infrastructure against generic manufacturers broadening patient reach. The market exhibits tiered consolidation with premium innovators, mid-cap specialists, and accessibility-focused manufacturers occupying distinct margin pools. Strategic archetypes include Orphan Drug Act exploiters, generic accessibility program operators, and electrophysiology capability integrators. Dominant competitive moves encompass companion diagnostic bundling and pediatric indication expansion through regulatory incentive capture.
Within the large-cap pharmaceutical tier, Pfizer Inc. and Novartis AG occupy positions leveraging established rare disease infrastructure and specialized neuromuscular research capabilities respectively. Teva Pharmaceutical Industries exemplifies the generic accessibility archetype, broadening patient reach for chronic potassium management through differentiated distribution economics. Sun Pharmaceutical Industries represents the emerging market-anchored specialist model.
| Leading Market Players |
|---|
| Merck |
| Teva Pharmaceutical Industries |
| Pfizer Inc. |
| Novartis AG |
| Sun Pharmaceutical Industries |
| Xeris Biopharma |
| Hikma Pharmaceuticals |
| Alembic Pharmaceuticals |
| Advanz Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Single-source dependency on KCNJ2 genetic assay reagents from specialized European manufacturers determines both the premium-to-economy spread in diagnostic pricing and the elongated procurement cycles that hospitals now navigate. FDA breakthrough therapy designation pathways compress development timelines for potassium channel modulators, yet reimbursement fragmentation across national health systems forces developers to absorb extended pharmacovigilance costs that compress margins at the standard tier.
Pricing Analysis
Cost-plus contracts with raw material indexation anchor therapeutic procurement for chronic potassium management, with academic medical centers in the United States negotiating volume-based rebates that widen spreads between research-intensive and generic-accessibility programs. Price differentiation rests on FDA Orphan Drug exclusivity versus Teva Pharmaceutical Industries' broad-reach distribution economics, with the former capturing premium positioning and the latter facing compression from payer prior-authorization requirements. Pricing pressure stems from EMA pharmacovigilance mandates for gene-targeted therapies that inflate post-market commitment burdens. Hospital procurement committees demonstrate highest price sensitivity for chronic administration regimens, while rare disease specialty clinics show lowest sensitivity for companion diagnostic bundles.
Supply Chain Analysis
Tariff exposure between the United States and China for electrophysiology equipment components dominates supply chain risk planning for channelopathy diagnostic platforms. Manufacturing concentrates in Germany, Switzerland, and the United States for precision ion channel research tools, with next-generation sequencing panel assembly drawing from Taiwanese semiconductor foundries and specialized reagent production in the Netherlands. Raw material dependencies include Kir2.1 channel antibodies, CRISPR guide RNA libraries, and Holter monitor sensor arrays. Single-source vulnerability for CLIA-certified genetic confirmation kits creates procurement chokepoints at secondary clinical laboratories. Distribution runs through specialty pharmacy networks consolidated by patient advocacy foundation contracting in France and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrophysiology talent scarcity constrains diagnostic throughput and fragments patient identification rates across the treatment ecosystem, creating asymmetric capability gaps that determine competitive positioning. The shortage of trained genetic counselors and cardiac electrophysiologists limits expansion velocity for integrated channelopathy clinics.
For Market Incumbents: Harden rare disease infrastructure against emerging generic accessibility programs by deepening backward integration into companion diagnostic development and securing exclusive formulary placement through foundation contracting. Pfizer Inc. and Novartis AG should prioritize pediatric indication expansion via FDA priority review vouchers to extend exclusivity windows. Capacity addition in Germany and France through EMA centralized authorization pooling sustains viable commercial populations for ultra-small patient pools. For New Entrants and Emerging Players: Telemedicine-enabled virtual neuromuscular consultations in underserved rural United States regions represent the most penetrable entry point for channelopathy care delivery. Mid-tier clinical laboratories in the United Kingdom lacking electrophysiology capabilities offer white-space acquisition targets for next-generation sequencing panel deployment. A go-to-market angle anchored to NHS specialized commissioning frameworks accelerates procurement access without requiring quaternary care center infrastructure. For Investors and Strategic Acquirers: The market sits at a regulatory-incentive-peak phase that favors Orphan Drug Act exploiters with existing electrophysiology capabilities and companion diagnostic bundling expertise. Long-term viability over the coming decade hinges on adaptive licensing pathway navigation and post-market surveillance cost absorption. Acquisition targets should display specialized neuromuscular research units with dedicated Kir2.1 programs. The signal to watch is EMA pharmacovigilance requirement expansion for gene-targeted therapies, which would reshape commercialization economics and consolidation incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | FDA-cleared genetic test kits bundled with channel modulators streamline payer coverage decisions at academic medical centers. |
| Pediatric Indication Expansion | EMA pediatric investigation plans and US priority review vouchers reward developers addressing early-onset periodic paralysis. |
| Telemedicine Channel Development | Virtual neuromuscular consultations collapse geographic barriers to specialized channelopathy care in rural regions. |
| Foundation Contracting Consolidation | Patient advocacy networks in France and the United States displace fragmented individual patient access programs. |
| Adaptive Licensing Navigation | EMA pathways and FDA rare disease endpoint initiatives reshape evidentiary standards for periodic paralysis therapies. |
Research Methodology
A spread of perspectives from drug development executives at ion channel therapy specialists, regulatory affairs leads navigating FDA Orphan Drug pathways, formulary directors at academic medical centers, hospital procurement managers overseeing channelopathy clinics, and payer access specialists converged on the working assumptions. Primary interviews combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient population estimates triangulated against top-down pharmaceutical revenue attribution across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation modeled across therapeutics, diagnostic kits, research tools, and treatment monitoring devices, further disaggregated by delivery mode and therapy area. CAGRs derived from epidemiological prevalence projections, pricing trajectory assumptions, and penetration rate modeling for next-generation sequencing panel adoption. Industry-specific inputs included electrophysiology laboratory expansion timelines and EMA centralized authorization pooling effects.
Practitioners should monitor regulatory revision triggers including EMA pharmacovigilance expansion for gene-targeted therapies and FDA breakthrough therapy designation withdrawal criteria for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Byler Disease Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market