
 Global Hereditary Angioedema Therapeutics Market | 2026-2036
Global Hereditary Angioedema Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hereditary Angioedema Therapeutics Market Foresight
North American biologics manufacturing capacity is reconfiguring the competitive terrain for plasma-derived and recombinant C1-inhibitor supply. CSL Behring leverages its fractionation infrastructure to sustain hemophilia and rare disease product leadership across multiple continents. Takeda Pharmaceutical anchors its position through integrated plasma collection networks and established hospital pharmacy channels. BioCryst Pharmaceuticals competes with oral kallikrein inhibitor technology, differentiating from injectable prophylactic standards.
Hereditary angioedema therapeutics comprise biologic and small-molecule interventions targeting the contact activation pathway, specifically restoring or replacing functional C1-inhibitor protein or blocking bradykinin-mediated vascular permeability. These treatments prevent life-threatening laryngeal attacks and reduce the frequency of recurrent subcutaneous and abdominal swelling episodes in patients with confirmed C1-INH deficiency or dysfunction. Plasma-derived C1-inhibitors retain established reimbursement pathways but face margin pressure from recombinant alternatives with reduced viral transmission risk. Subcutaneous delivery modes are capturing fastest-growing utilization among prophylactic therapy patients seeking home administration autonomy, while intravenous formulations maintain dominance in acute hospital settings. Oral kallikrein inhibitors represent an emerging structural shift in long-term management, potentially displacing frequent injection burdens.
FDA orphan drug exclusivity and EMA's priority medicines scheme shape clinical trial investment and market access timelines for novel HAE modalities. The EU's MDR framework imposes strengthened post-market surveillance requirements on plasma-derived biologics, elevating compliance costs for European manufacturers. Japan's PMDA accelerates review pathways for rare disease therapies, creating parallel approval opportunities for companies with Asian regulatory capabilities. Stakeholders must monitor kallikrein inhibitor pipeline readouts and evolving payer criteria for prophylactic versus on-demand therapy allocation.
Market Dynamics
The transition from intravenous to subcutaneous and oral kallikrein inhibitor delivery modes is compressing hospital-centric treatment models while expanding home-based chronic management. This modality shift is redistributing value capture from acute care facilities toward specialty pharmacy networks and patient self-administration ecosystems.
Growth Catalysts
- FDA Orphan Drug Exclusivity:The designation framework compresses clinical trial timelines and extends market protection periods, accelerating capital deployment into novel contact pathway inhibitors.
- Home Administration Autonomy:Subcutaneous prophylactic formulations enable patients to bypass hospital infusion centers, reducing treatment burden while expanding addressable patient pools in rural and underserved areas.
- EMA Priority Medicines Scheme:The accelerated assessment pathway for rare disease therapies shortens regulatory lag between US and European market entry, enabling parallel revenue ramps across jurisdictions.
Market Restraints
- Plasma Supply Concentration:Fractionation capacity clusters in the United States and select European facilities, creating geographic vulnerability for plasma-derived C1-inhibitor production during collection disruptions.
- Reimbursement Compression:Payer formulary tiers impose step-therapy requirements that delay access to recombinant and novel small-molecule alternatives until failure on plasma-derived standards.
- Viral Transmission Risk Legacy:Manufacturing safeguards for plasma-derived products require extensive pathogen reduction steps, elevating cost structures relative to recombinant and synthetic alternatives.
Strategic Opportunities
- Japan PMDA Rare Disease Pathway:The accelerated review framework for ultra-orphan indications creates first-mover advantages for companies with Asian regulatory capabilities and local clinical data generation.
- Specialty Pharmacy Integration:Direct distribution partnerships with limited-distribution networks bypass traditional wholesale markups while capturing patient adherence data for outcomes contracting.
- Oral Kallikrein Convergence:Small-molecule inhibitor development combines patient preference for pill-based regimens with reduced cold-chain logistics burdens versus biologic storage requirements.
Industry Challenges
- Biologics Manufacturing Talent Scarcity:Cell culture and aseptic processing expertise concentrates at established plasma fractionators, constraining new entrant scale-up timelines for recombinant C1-inhibitor production.
- Post-Market Surveillance Burden:The EU MDR framework imposes strengthened pharmacovigilance requirements on plasma-derived products, elevating compliance headcount and system investments for European market participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hereditary Angioedema Therapeutics Market |
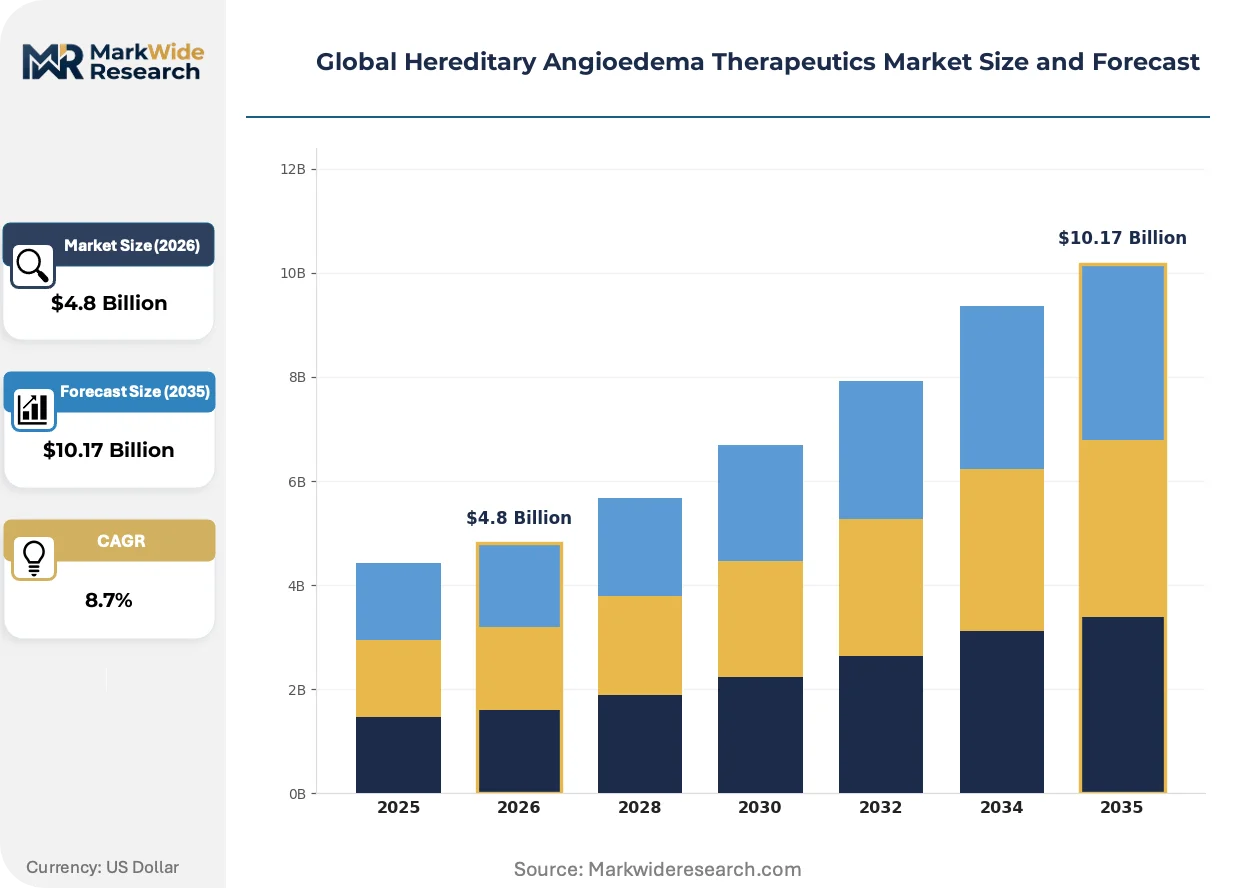
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma-Derived C1-Inhibitors, Recombinant C1-Inhibitors, Bradykinin B2 Receptor Antagonists, Kallikrein Inhibitors, Others Application: Acute Attack Treatment, Prophylactic Therapy, Long-Term Management, Emergency Care End User: Specialized Immunology Clinics, Allergy Centers, Hospital Pharmacies, Ambulatory Care Services Delivery Mode: Intravenous, Subcutaneous, Oral, Nasal Spray |
| Companies Covered | BioCryst Pharmaceuticals, Ionis Pharmaceuticals, CSL Behring, Sanofi, KalVista Pharmaceuticals, Takeda Pharmaceutical, Shire, Attune Pharmaceuticals, Pharming Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hereditary Angioedema Therapeutics Market Shifts & Advancements
Oral small-molecule kallikrein inhibitors are disrupting the prophylactic therapy landscape by eliminating injection burdens entirely. This structural shift is forcing incumbents to defend their installed base of infusion-dependent patients while repositioning around acute attack rescue indications.
Oral berotralstat and follow-on kallikrein inhibitors target the plasma kallikrein enzyme to block bradykinin generation without C1-inhibitor protein replacement. Adult patients with frequent attack histories are switching from biweekly injections to daily pill regimens at accelerating rates. Frequent dosing schedules are rendering obsolete the compliance advantages that once favored long-acting injectable prophylaxis.
The EU MDR framework imposes Unique Device Identification requirements and strengthened clinical evidence standards on combination products including auto-injector delivery systems. Manufacturers must retrofit legacy device designs or withdraw from European markets, compressing competitive margins for acute attack therapies. Subcutaneous on-demand products with integrated delivery systems face the steepest compliance cost escalations.
Hospital pharmacy procurement committees are consolidating formulary decisions into centralized immunology specialty committees, reducing individual prescriber autonomy in product selection. Integrated delivery networks in the United States are replacing independent physician preference with protocol-driven algorithms that prioritize lowest-net-cost alternatives. This concentration is most visible in Midwestern and Southern states where health system consolidation has advanced furthest.
Global Hereditary Angioedema Therapeutics Market Segmentation
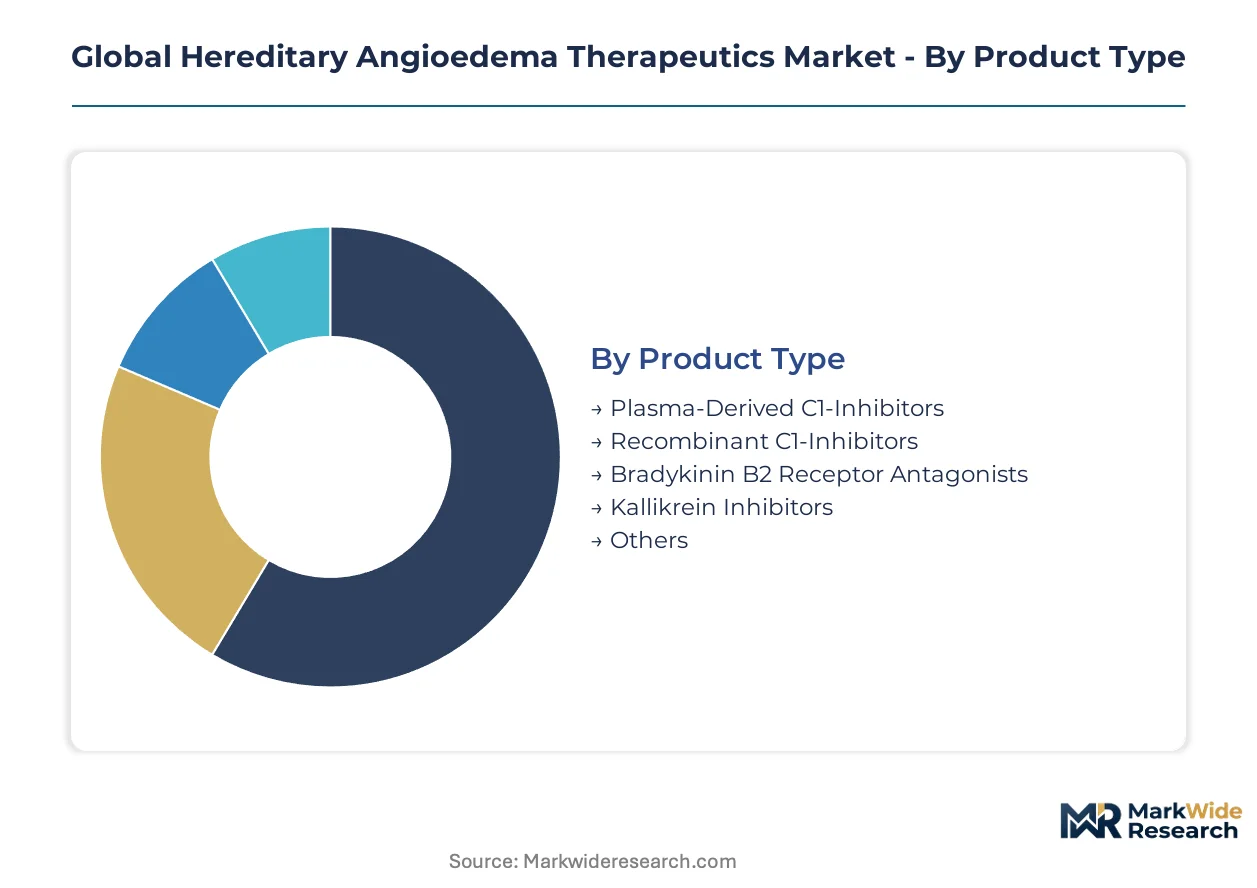
Hereditary angioedema therapeutics segment across multiple dimensions that determine prescribing patterns, reimbursement pathways, and competitive dynamics. Product type and delivery mode classifications most directly influence manufacturing investment and patient adherence outcomes. Application and end-user segments shape commercial strategy for market access and distribution channel selection.
Product Type:
Cycle times vary dramatically across protein replacement versus small-molecule modalities, with recombinant biologics requiring longer development timelines but offering extended patent protection versus rapid generic entry risk for oral agents.
- Plasma-Derived C1-Inhibitors:Concentrated plasma fractions restore functional C1-inhibitor protein in patients with quantitative or qualitative deficiencies. Demand clusters in established European markets and US academic medical centers with long-standing hemophilia and immunology expertise, constrained by plasma collection capacity limitations and viral safety validation requirements.
- Kallikrein Inhibitors:Small-molecule and monoclonal antibody approaches block plasma kallikrein enzymatic activity upstream of bradykinin generation. Prescription volume is expanding most quickly in US specialty pharmacy channels where oral berotralstat has displaced injectable prophylaxis among working-age patients prioritizing treatment autonomy.
- Recombinant C1-Inhibitors:Transgenic rabbit milk-derived or cell culture-produced C1-inhibitor protein eliminates plasma-sourced viral transmission risk.
- Bradykinin B2 Receptor Antagonists:Icatibant and follow-on peptides competitively antagonize bradykinin-mediated vascular permeability increases.
- Others:Investigational gene therapy approaches and tranexamic acid adjuncts occupy niche positioning.
Plasma-derived C1-inhibitors dominate installed base. Kallikrein inhibitors are where expansion concentrates.
Application:
Cost tier stratification separates acute rescue interventions from chronic prophylactic commitments, with annual therapy costs ranging tenfold between on-demand and preventive regimens.
- Prophylactic Therapy:Scheduled administration prevents attack occurrence in patients with frequent or severe episode histories. US integrated delivery networks and German statutory health insurance funds drive volume through prior authorization pathways favoring long-acting subcutaneous formulations.
- Acute Attack Treatment:On-demand intervention terminates progressing subcutaneous, abdominal, or laryngeal edema episodes. Demand concentrates in hospital emergency departments across France, Italy, and Spain where centralized procurement favors established plasma-derived and peptide antagonist standards.
- Long-Term Management:Coordinated care models combine prophylaxis optimization with attack rescue preparedness.
- Emergency Care:Laryngeal attack protocols require immediate airway intervention alongside pharmacologic therapy.
Acute attack treatment dominates installed base. Prophylactic therapy is climbing the fastest.
End User:
Customer type fragmentation creates divergent purchasing behaviors between centralized hospital procurement and dispersed specialty clinic prescribing.
- Hospital Pharmacies:Centralized formularies and therapeutic substitution policies govern product selection for inpatient and emergency department use. US health systems in Texas, Florida, and Ohio leverage GPO contracts to standardize across multi-hospital networks.
- Specialized Immunology Clinics:Academic and community-based immunology practices manage complex HAE patient panels with individualized prophylaxis selection. Concentrated demand in Massachusetts, California, and Pennsylvania reflects specialist density and research trial participation.
- Allergy Centers:Cross-disciplinary practices handle HAE diagnosis and initial therapy initiation.
- Ambulatory Care Services:Outpatient infusion centers and home health nursing support subcutaneous administration.
Hospital pharmacies dominate installed base. Specialized immunology clinics are gaining share fastest.
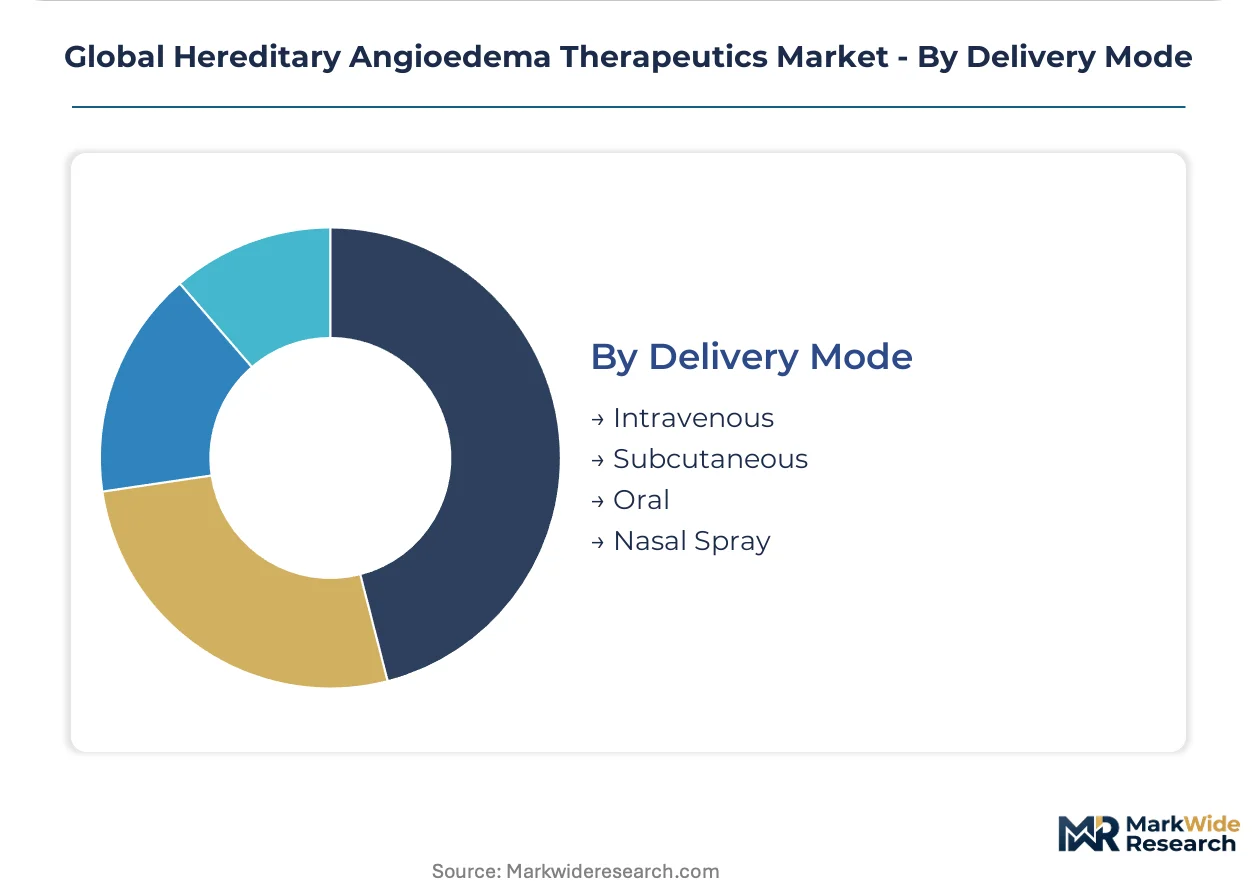
Delivery Mode:
Supply concentration in parenteral manufacturing creates margin pressure as oral alternatives eliminate cold-chain infrastructure requirements.
- Subcutaneous:Patient- or caregiver-administered injection enables home-based prophylaxis without infusion center dependency. Adoption accelerates in rural US counties and Australian regional centers distant from tertiary hospital infrastructure.
- Intravenous:Hospital and infusion center administration maintains dominance for acute attack rescue and peri-procedural prophylaxis. European hospital pharmacy procurement in France, Germany, and the United Kingdom sustains volume despite patient preference shifts.
- Oral:Daily small-molecule kallikrein inhibitor tablets eliminate injection burden and storage complexity.
- Nasal Spray:Investigational and limited-availability routes target rapid systemic absorption.
Intravenous delivery dominates installed base. Subcutaneous administration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug exclusivity anchors the United States as the dominant geography, while EMA and PMDA frameworks shape parallel market development across Europe and Japan. Plasma collection infrastructure and specialized immunology clinic density concentrate demand in specific national markets.
United States
Specialized immunology clinics in Massachusetts, California, and Pennsylvania drive prescription volumes for acute attack treatments and prophylactic therapy initiation. FDA's orphan drug designation compresses clinical trial timelines and extends market protection periods for novel contact pathway inhibitors. Hospital pharmacy procurement committees in Texas, Florida, and Ohio leverage GPO contracts to standardize formulary decisions across multi-hospital networks.
Germany
Statutory health insurance funds drive prophylactic therapy volume through prior authorization pathways favoring long-acting subcutaneous formulations. EMA's priority medicines scheme accelerates assessment timelines for rare disease therapies, shortening regulatory lag between US and European market entry. The Ruhr and Bavarian industrial clusters host plasma fractionation facilities serving Central European distribution networks.
Japan
PMDA's rare disease pathway creates first-mover advantages for companies with Asian regulatory capabilities and local clinical data generation. Accelerated review frameworks for ultra-orphan indications attract pipeline investment from multinational sponsors seeking parallel approval opportunities. The Kanto region around Tokyo concentrates specialist immunology capacity and hospital pharmacy procurement decision-making.
France
Hospital emergency departments across Île-de-France and regional centers sustain demand for acute attack rescue therapies through centralized procurement favoring established plasma-derived standards. ANSM post-market surveillance requirements align with EU MDR strengthened pharmacovigilance obligations on plasma-derived biologics. The Paris-Saclay cluster anchors immunology research trial participation and specialist training programs.
United Kingdom
NHS England specialized commissioning frameworks govern access to high-cost prophylactic therapies through designated treatment centers in London, Manchester, and Birmingham. MHRA operates parallel assessment pathways for rare disease medicines, enabling rapid adoption following EMA positive opinions. The Cambridge-Oxford-London triangle concentrates biologics manufacturing expertise and clinical research organization activity.
Global Hereditary Angioedema Therapeutics Market Competitive Landscape
Plasma fractionation specialists and small-molecule innovators split the market into distinct capability domains. Established biologics manufacturers leverage fractionation infrastructure and collection network control, while pharmaceutical developers pursue oral kallikrein inhibitor differentiation. Three archetypes dominate: integrated plasma collectors with hemophilia product synergies, recombinant protein specialists with transgenic production platforms, and oral small-molecule developers targeting patient preference shifts. Competitive moves concentrate on M&A for pipeline access and specialty pharmacy distribution partnerships for patient data capture.
Among integrated plasma collectors, CSL Behring and Takeda Pharmaceutical represent the established infrastructure archetype, anchoring positions through fractionation scale and hospital pharmacy channel relationships. BioCryst Pharmaceuticals exemplifies the oral kallikrein inhibitor developer archetype, occupying a position defined by daily pill regimen convenience versus injectable standards. These three companies collectively illustrate the strategic divergence between defending installed bases of infusion-dependent patients and capturing switching demand from patients prioritizing administration autonomy.
| Leading Market Players |
|---|
| BioCryst Pharmaceuticals |
| Ionis Pharmaceuticals |
| CSL Behring |
| Sanofi |
| KalVista Pharmaceuticals |
| Takeda Pharmaceutical |
| Shire |
| Attune Pharmaceuticals |
| Pharming Group |
| Others |
Supply & Pricing Matrix
Fractionation capacity utilization at CSL Behring's Kankakee facility and Takeda's Los Angeles plant shapes supplier pricing power across plasma-derived C1-inhibitor tiers. High utilization at these US sites compresses spot availability and reinforces long-term offtake premiums, while underutilization at European fractionators creates pricing softness for regional contract buyers.
Pricing Analysis
Geographic price spreads between US integrated delivery networks and European hospital procurement systems reach threefold multiples for identical plasma-derived C1-inhibitor doses. Three-tier pricing structure across premium recombinant, standard plasma-derived, and economy tranexamic acid adjunct levels stratifies patient access tiers. Cost compression in the plasma-derived segment intensifies as recombinant alternatives eliminate viral safety validation premiums. German statutory health insurance funds exhibit highest price sensitivity, while US specialty pharmacy channels absorb premium positioning for oral kallikrein inhibitors.
Supply Chain Analysis
Contract manufacturing concentration at Boehringer Ingelheim's Biberach facility and Lonza's Portsmouth site anchors recombinant C1-inhibitor production capacity. Supply concentrates in the United States, Germany, and Japan for fractionation and fill-finish operations. Raw material dependencies span plasma source collections, cell culture media, and single-use bioreactor components. Single-source vulnerability at plasma collection centers in the Midwestern United States threatens production continuity during donor recruitment disruptions. Distribution runs through limited-distribution specialty pharmacy networks for prophylactic therapies, while hospital pharmacy direct purchasing dominates acute attack rescue products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as plasma collection volumes rebound from pandemic-era donor shortfalls and oral kallikrein inhibitors expand the addressable prophylactic patient pool.
For Market Incumbents: Insulate plasma-derived revenue streams by deepening backward integration into captive plasma collection networks across Texas and Florida donor centers. Secure EMA MDR recertification for legacy auto-injector devices ahead of European withdrawal deadlines. Prioritize formulary defense contracts with US health systems consolidating immunology specialty committees. For New Entrants and Emerging Players: Establish a beachhead in Japanese prophylactic therapy markets through PMDA rare disease pathway submissions with local clinical data generation. Target Australian regional ambulatory care services where subcutaneous home administration penetration remains below US benchmarks. Deploy direct-to-patient specialty pharmacy partnerships to bypass entrenched hospital pharmacy procurement gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because plasma fractionation expertise concentrates at mid-cap specialists with hemophilia product synergies. Acquisition targets with transgenic production platforms or oral kallikrein inhibitor pipelines command scarcity premiums. Monitor FDA orphan drug exclusivity expiration schedules as inflection indicators for generic entry pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA rare disease designation compresses Japanese review timelines versus standard EMA procedures. |
| Manufacturing Scale-Up | Transgenic rabbit milk production at Pharming Group's Utah facility expands recombinant C1-inhibitor supply. |
| Pipeline Diversification | Oral kallikrein inhibitor development at BioCryst Pharmaceuticals displaces injectable prophylactic standards. |
| Licensing Agreement | Specialty pharmacy distribution partnerships capture patient adherence data for outcomes contracting with US payers. |
| Reimbursement Strategy | NHS England specialized commissioning frameworks govern access through designated treatment centers in London and Manchester. |
Research Methodology
Operator-level perspectives from plasma collection center directors, hospital pharmacy procurement managers, formulary directors at US integrated delivery networks, and regulatory affairs leads at EMA-designated orphan drug sponsors anchored the qualitative base. These primary interviews combined with secondary validation from FDA orphan drug designations, EMA priority medicines scheme assessments, ClinicalTrials.gov protocol registrations, and hospital GPO contract databases. Bottom-up patient population modeling and top-down revenue triangulation across the analysis window ensured cross-verification.
Scenario-bracketing framed the analytical approach across product type, application, end user, delivery mode, and regional regulatory cluster dimensions. CAGRs derived from patient volume projections, therapy switching rates, and pricing elasticity assumptions throughout the forecast period. Industry-specific inputs included plasma collection yield trends, fractionation capacity expansion announcements, and oral kallikrein inhibitor adherence data from specialty pharmacy claims.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates or biologics reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding donor recruitment sustainability and regulatory pathway timelines. Quarterly review of plasma collection volume reports, FDA approval cadence, and EMA MDR compliance announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Desmoid Tumor Market