
 Global Rare Hemophilia Factors Market | 2026-2036
Global Rare Hemophilia Factors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rare Hemophilia Factors Market Foresight
A capital-intensity divergence between plasma-derived and recombinant manufacturing platforms is redrawing competitive boundaries in rare hemophilia therapeutics. CSL Behring leverages its integrated plasma collection infrastructure to sustain steady output of high-purity Factor VIII and Factor IX concentrates. Novo Nordisk A/S anchors its position through extended half-life recombinant innovations that reduce injection frequency for hemophilia A patients. Takeda Pharmaceutical Company Limited competes via diversified geographic coverage across hemophilia treatment centers in North America, Europe, and Asia-Pacific markets.
Rare hemophilia factors comprise purified or recombinant coagulation proteins—principally Factor VIII, Factor IX, and Factor VIIa—administered intravenously or subcutaneously to restore hemostasis in patients with congenital or acquired bleeding disorders. These biologics require cold-chain distribution, viral inactivation steps, and potency assays calibrated against WHO international standards to ensure therapeutic efficacy and safety. Factor VIII dominates product type revenue due to the prevalence of hemophilia A, while activated prothrombin complex concentrate represents the fastest-expanding category driven by inhibitor patient management. Hemophilia treatment centers anchor end-user demand through centralized prophylactic protocols, though home healthcare providers are capturing incremental volume as subcutaneous delivery modes mature.
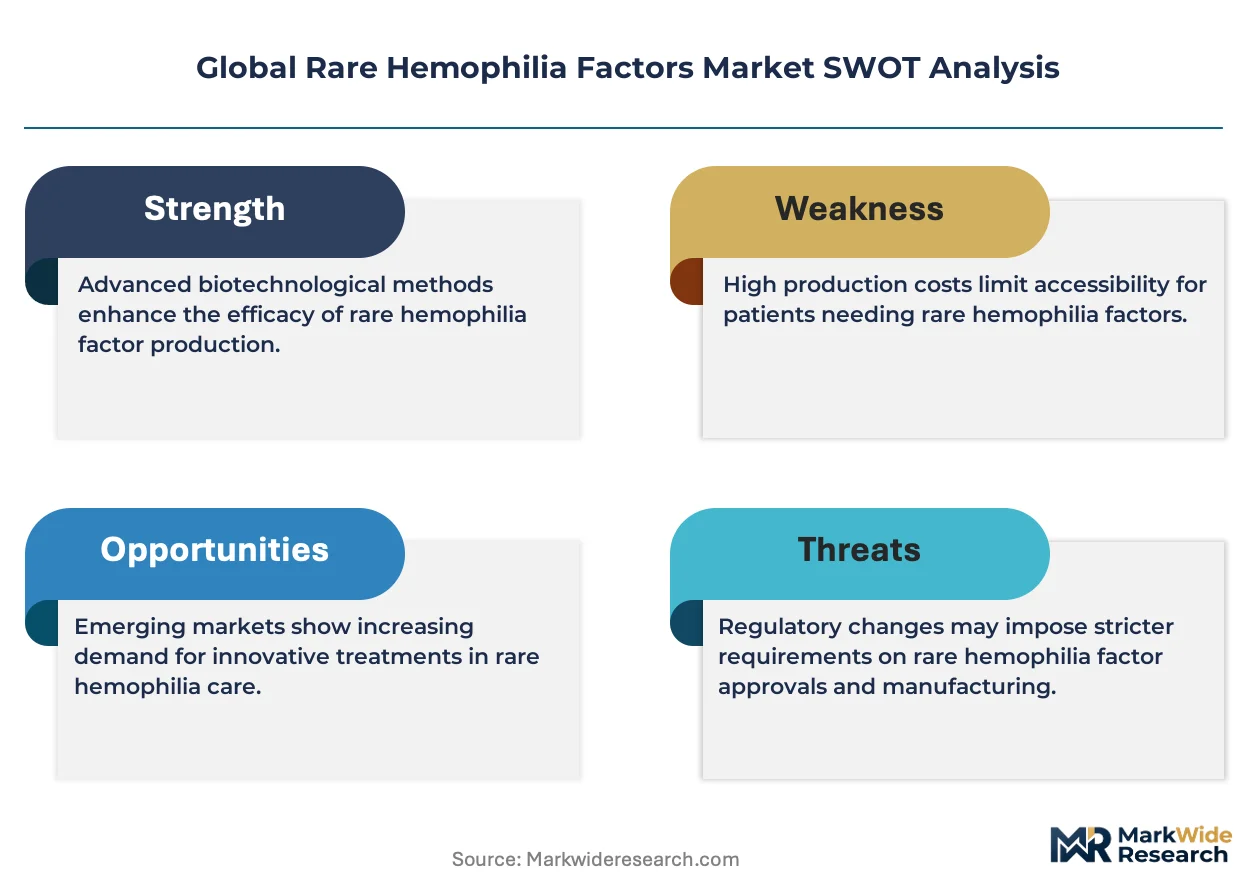
FDA, EMA, and WHO standards collectively govern viral safety testing, potency labeling, and post-market pharmacovigilance for clotting factor concentrates, creating compliance thresholds that favor manufacturers with established quality management systems. The EU F-Gas Regulation and analogous cold-chain sustainability mandates in Japan are pressuring suppliers to redesign temperature-controlled logistics without compromising protein stability. Stakeholders must monitor gene therapy pipeline readouts and their implications for long-term factor replacement demand.
Market Dynamics
Gene therapy pipeline maturation is compressing long-term demand forecasts for factor replacement products, forcing incumbent manufacturers to reposition around prophylactic therapy optimization and patient retention infrastructure.
Growth Catalysts
- FDA Accelerated Approval Pathway:Compressed development timelines for novel recombinant factor concentrates enable faster market entry for extended half-life therapies targeting severe hemophilia A populations.
- Hemophilia Treatment Center Expansion:Centralized prophylactic protocols across the United States, Germany, and Japan anchor sustained demand for high-purity Factor VIII and Factor IX concentrates.
- Subcutaneous Delivery Maturation:Home healthcare providers capture incremental volume as non-intravenous administration modes reduce treatment burden and expand patient autonomy.
Market Restraints
- Plasma Collection Concentration:Dependence on CSL Behring's integrated collection infrastructure creates supply vulnerability for plasma-derived factor concentrates.
- Cold-Chain Sustainability Mandates:EU F-Gas Regulation pressures suppliers to redesign temperature-controlled logistics without compromising protein stability.
- Gene Therapy Substitution Threat:Single-dose curative approaches for hemophilia A and B threaten long-term replacement therapy demand.
Strategic Opportunities
- Inhibitor Patient Management:Activated prothrombin complex concentrate demand expands fastest among this underserved subset requiring bypass therapy.
- Asia-Pacific Network Buildout:Underpenetrated hemophilia treatment center coverage in China and India offers white-space expansion for comprehensive care models.
- Reimbursement Framework Harmonization:Japan's universal coverage for rare disease biologics provides template for sustainable therapy access in emerging markets.
Industry Challenges
- Viral Inactivation Expertise Gap:Specialized biochemistry talent for pathogen reduction validation remains concentrated among established quality management systems.
- Potency Assay Standardization:Calibration against WHO international standards requires sustained investment in reference material production and inter-laboratory harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rare Hemophilia Factors Market |
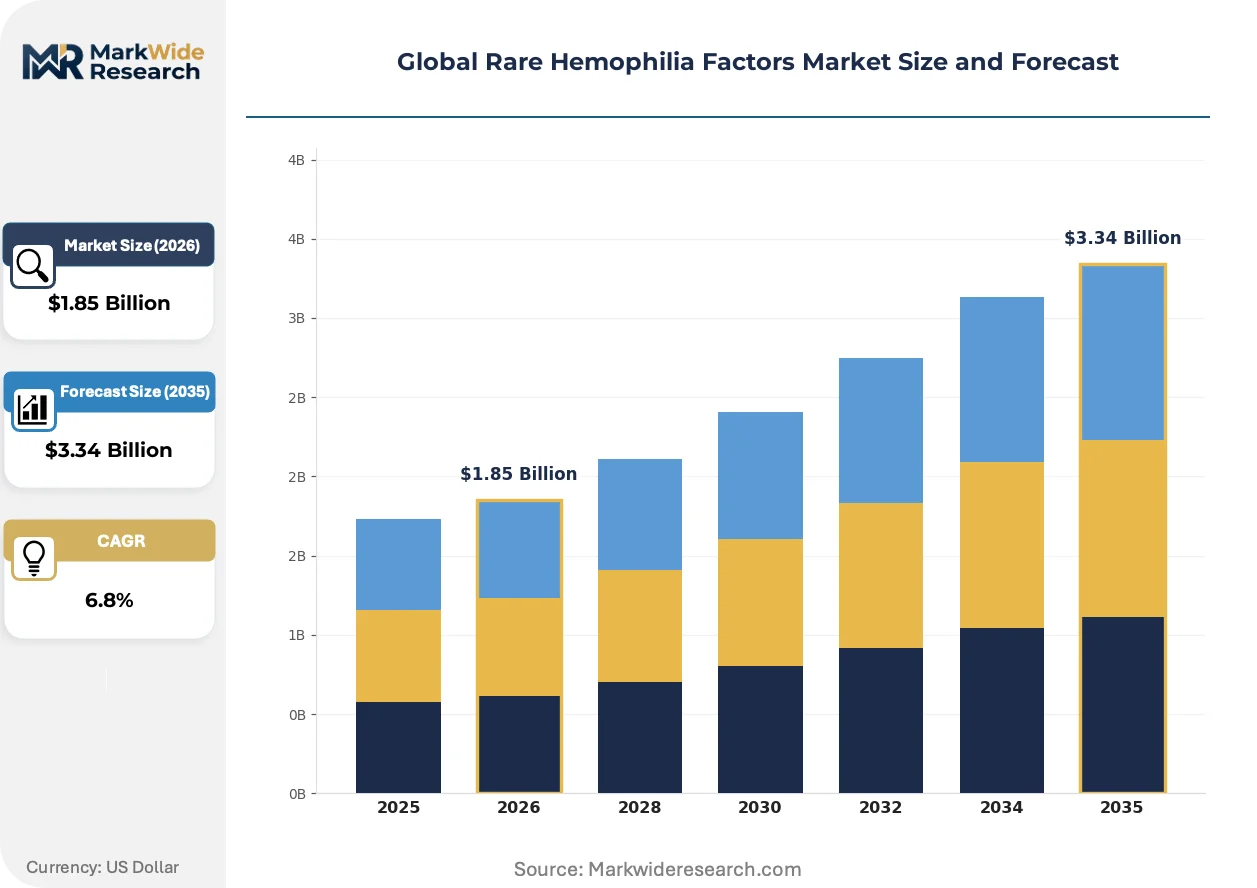
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Factor VIII, Factor IX, Factor VIIa, Activated Prothrombin Complex Concentrate, Anti-Inhibitor Coagulant Complex Therapy Area: Hemophilia A, Hemophilia B, von Willebrand Disease, Acquired Hemophilia, Platelet Function Disorders End User: Hemophilia Treatment Centers, Specialty Clinics, Diagnostic Laboratories, Home Healthcare Providers Delivery Mode: Intravenous Injection, Subcutaneous Injection, Prophylactic Therapy, On-Demand Therapy |
| Companies Covered | Takeda Pharmaceutical Company Limited, CSL Behring, Bayer AG, Pfizer Inc., BioMarin, Novo Nordisk A/S, Grifols, Octapharma AG, Bio Products Laboratory Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rare Hemophilia Factors Market Shifts & Advancements
Extended half-life recombinant engineering is displacing standard-acting concentrates across prophylactic protocols. Regulatory sustainability mandates are forcing cold-chain redesign. Patient-centered delivery models are redistributing care from treatment centers to home settings.
PEGylation and Fc-fusion technologies extend factor VIII and factor IX circulating half-life from 12 hours to 3-5 days. Hemophilia treatment centers in the United States and Germany now prioritize these formulations for severe patient prophylaxis. Standard-acting recombinant concentrates are displacing legacy plasma-derived options in markets with established reimbursement.
EMA's F-Gas Regulation and analogous Japanese cold-chain sustainability directives mandate reduction of fluorinated greenhouse gas use in temperature-controlled distribution. Manufacturers face protein stability trade-offs when substituting conventional refrigerants. European suppliers invest most heavily in passive thermal packaging and phase-change material innovation.
Home infusion training programs and subcutaneous administration options compress patient dependence on institutional care. Home healthcare providers in Japan and Germany absorb volume previously captured by hospital-based hemophilia treatment centers. This channel rotation is most visible in markets with mature patient self-management education infrastructure.
Global Rare Hemophilia Factors Market Segmentation
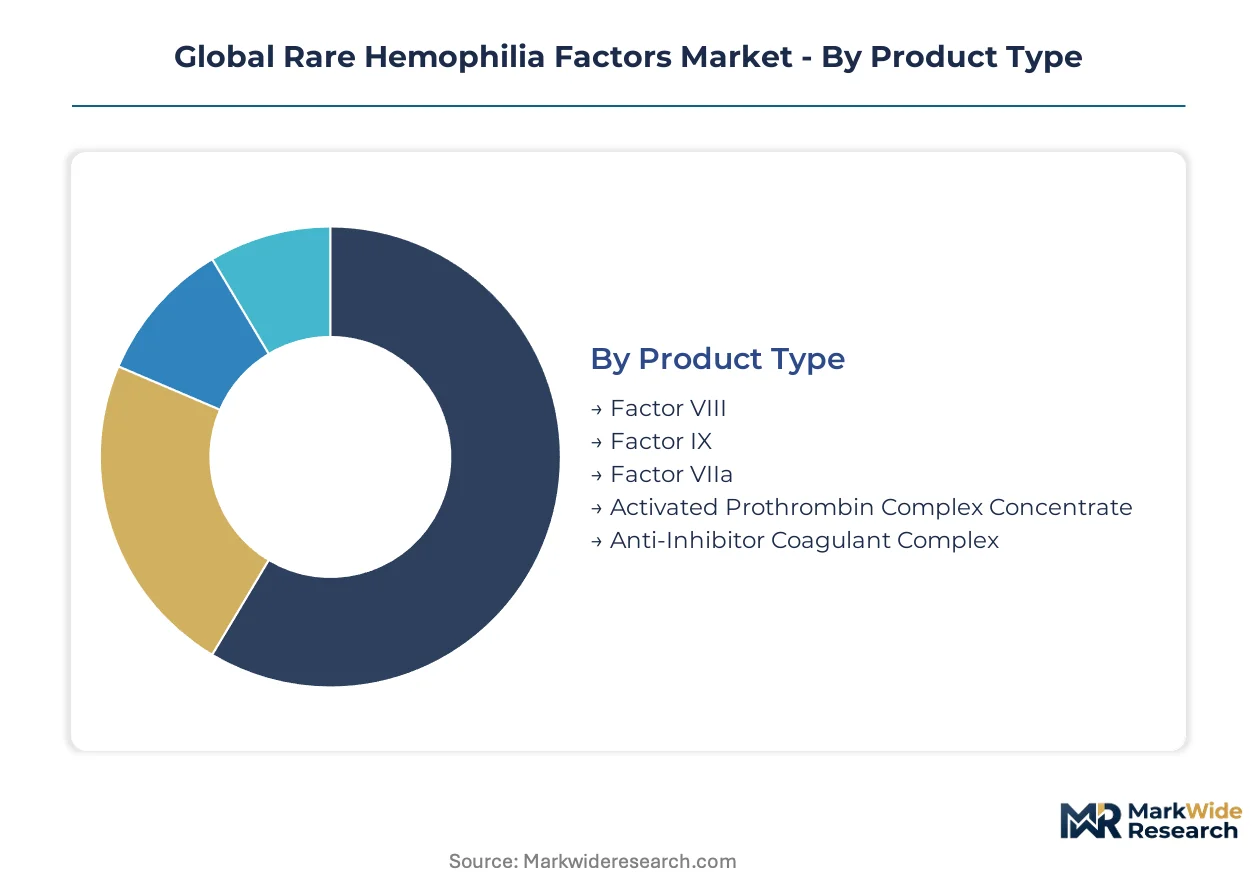
Rare hemophilia factors fragment across four distinct classification axes that govern procurement patterns, reimbursement tiers, and distribution logistics. Product type and therapy area determine clinical protocol selection, while end-user channel and delivery mode shape cold-chain requirements and patient access pathways.
Product Type:
Factor VIII concentrates dominate domestic consumption in the United States and Germany, while recombinant Factor IX and bypass agents sustain stronger export flows to Asia-Pacific markets.
- Factor VIII:Purified or recombinant coagulation protein administered intravenously to restore hemostasis in hemophilia A patients. Demand concentrates in United States hemophilia treatment centers where prophylactic protocols prioritize extended half-life formulations. PEGylation and Fc-fusion engineering now displaces standard-acting concentrates across severe patient populations.
- Activated Prothrombin Complex Concentrate:Bypass therapy containing activated Factor VII and prothrombin complex proteins for inhibitor patient management. Momentum sits with Japan and Germany where inhibitor prevalence drives fastest category expansion. Regulatory pathways through FDA and EMA accelerated approval compress development timelines for novel formulations.
- Factor IX:Recombinant or plasma-derived coagulation factor for hemophilia B replacement therapy.
- Factor VIIa:Activated recombinant factor for bypass therapy in inhibitor patients with acute bleeding episodes.
- Anti-Inhibitor Coagulant Complex:Plasma-derived concentrate containing non-activated factors for inhibitor patient prophylaxis.
Factor VIII holds the largest share; momentum sits with Activated Prothrombin Complex Concentrate.
Therapy Area:
Cost tier stratification separates high-frequency prophylactic regimens in hemophilia A from episodic management in acquired and platelet disorders.
- Hemophilia A:Congenital deficiency of Factor VIII requiring lifelong replacement therapy. United States and German treatment centers anchor volume through centralized prophylactic protocols. Gene therapy pipeline maturation threatens long-term substitution demand.
- Acquired Hemophilia:Autoimmune condition generating neutralizing antibodies against endogenous Factor VIII. Diagnosis concentrates in specialty clinics across France and Japan where rapid immunosuppression combined with bypass therapy improves outcomes. Mortality risk drives premium pricing tolerance.
- Hemophilia B:Congenital Factor IX deficiency with lower prevalence than hemophilia A.
- von Willebrand Disease:Most common inherited bleeding disorder requiring factor concentrate in severe subtypes.
- Platelet Function Disorders:Rare congenital defects in platelet adhesion or aggregation mechanisms.
Hemophilia A generates dominant volume; steepest expansion trajectory belongs to Acquired Hemophilia.
End User:
Channel maturity separates institutional procurement in established markets from home healthcare growth in patient self-management economies.
- Hemophilia Treatment Centers:Comprehensive care facilities delivering prophylactic protocols, diagnostic monitoring, and specialist consultation. United States HTCs coordinate care for over seventy percent of severe hemophilia patients through federally funded networks. Reimbursement frameworks in Germany and Japan mirror this comprehensive model.
- Home Healthcare Providers:Distributors and nursing services supporting patient-administered infusion therapy. Japan absorbs fastest volume growth as subcutaneous delivery maturation reduces institutional dependence. Training infrastructure and cold-chain direct-to-patient logistics determine competitive positioning.
- Specialty Clinics:Outpatient facilities managing mild-to-moderate cases and transition care.
- Diagnostic Laboratories:Reference centers conducting factor activity assays and inhibitor screening.
Hemophilia Treatment Centers retain procurement dominance; Home Healthcare Providers are gaining share fastest.
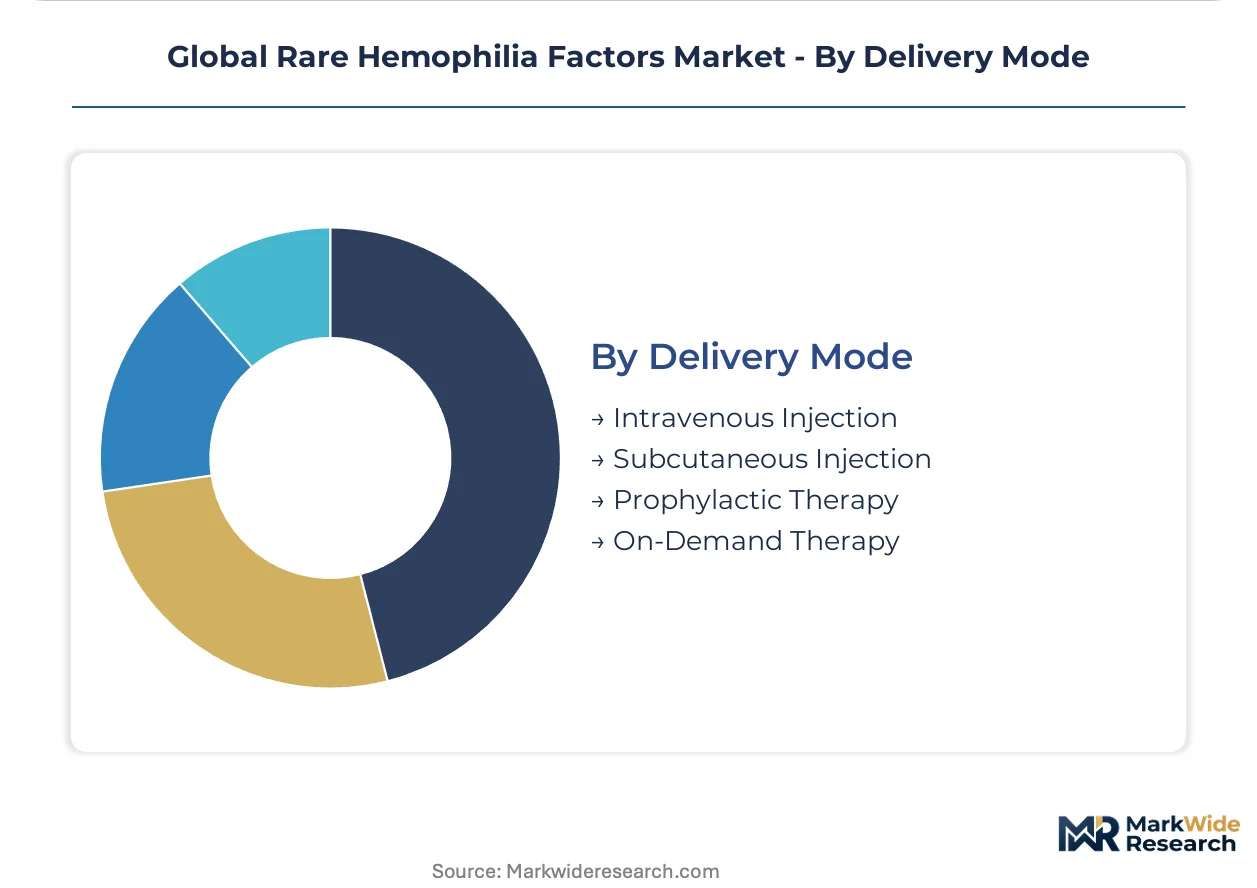
Delivery Mode:
Volume concentration favors prophylactic regimens in severe hemophilia populations, while margin concentration sits with on-demand therapies for surgical and trauma indications.
- Prophylactic Therapy:Scheduled factor administration preventing spontaneous bleeding in severe hemophilia. German and United States protocols now standardize extended half-life products for three-to-five-day dosing intervals. Patient adherence metrics and annualized bleed rates determine reimbursement tiers.
- Subcutaneous Injection:Non-intravenous administration route reducing treatment burden and expanding patient autonomy. Development pipelines in Switzerland and United States target Factor VIII and Factor IX formulations bypassing venous access requirements. Stability challenges in subcutaneous protein delivery constrain near-term commercialization.
- Intravenous Injection:Standard administration route for all current marketed factor concentrates.
- On-Demand Therapy:Episodic treatment of breakthrough bleeding or surgical prophylaxis.
Prophylactic Therapy commands the largest share; Subcutaneous Injection climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across hemophilia care networks. German and Japanese buyers absorb premium extended half-life formulations through comprehensive reimbursement, while Indian and Chinese markets remain highly sensitive to factor concentrate costs despite expanding diagnosis rates.
United States
Federally funded hemophilia treatment centers coordinate care for over seventy percent of severe patients, anchoring sustained Factor VIII demand. FDA accelerated approval pathways compress development timelines for novel recombinant therapies. Boston and San Francisco biotech clusters concentrate gene therapy pipeline activity threatening long-term replacement demand.
Germany
Centralized prophylactic protocols across university hospitals prioritize extended half-life Factor VIII and Factor IX concentrates. EMA's F-Gas Regulation pressures cold-chain logistics redesign without compromising protein stability. Munich and Frankfurt pharmaceutical hubs host specialized viral inactivation expertise concentrated among established quality management systems.
Japan
Universal coverage for rare disease biologics under national health insurance enables premium therapy access. METI sustainability directives mandate fluorinated greenhouse gas reduction in temperature-controlled distribution. Tokyo and Osaka hemophilia treatment centers absorb fastest home healthcare volume growth as subcutaneous delivery maturation reduces institutional dependence.
China
Underpenetrated hemophilia treatment center coverage in tier-two cities creates white-space expansion opportunity. The national pharmaceutical regulator tightens viral safety testing alignment with WHO international standards. Shanghai and Beijing biopharma clusters concentrate domestic recombinant factor engineering capacity.
Global Rare Hemophilia Factors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the rare hemophilia factors landscape. Plasma-derived concentrate manufacturers leverage integrated collection infrastructure for cost efficiency, while recombinant specialists command premium positioning through half-life extension engineering. Three archetypes dominate: vertically integrated plasma collectors, recombinant biotech innovators, and diversified multinational pharmaceutical groups. Competitive intensity centers on M&A consolidation of plasma collection networks and strategic partnerships for subcutaneous delivery platform access.
Among diversified pharmaceutical groups, Takeda Pharmaceutical Company Limited and Bayer AG occupy positions spanning both plasma-derived and recombinant portfolios across multiple therapy areas. CSL Behring exemplifies the vertically integrated archetype through captive plasma collection infrastructure. Novo Nordisk A/S sits within the recombinant innovation tier, with its Danish corporate structure reflecting concentrated biologics expertise.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| CSL Behring |
| Bayer AG |
| Pfizer Inc. |
| BioMarin |
| Novo Nordisk A/S |
| Grifols |
| Octapharma AG |
| Bio Products Laboratory Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between hemophilia treatment centers and plasma fractionators lock in multi-year supply access while anchoring price visibility for Factor VIII and Factor IX concentrates. These contracts bundle cold-chain distribution commitments with volume guarantees, insulating procurement officers from spot market volatility in plasma-derived products while compressing margins for recombinant suppliers competing on half-life extension premiums.
Pricing Analysis
After-sales revenue from home infusion training programs and patient adherence monitoring drives lifetime value capture for manufacturers. Three-tier pricing structure across premium extended half-life, standard recombinant, and economy plasma-derived tiers separates hemophilia A prophylaxis protocols. Price differentiation hinges on viral inactivation certification grade and geographic delivery cost to remote treatment centers. Cost compression in standard-acting concentrates is intensifying because gene therapy pipeline maturation threatens replacement therapy demand. Home healthcare providers in Japan exhibit highest price sensitivity; German university hospitals absorb premium formulations with least resistance.
Supply Chain Analysis
The United States and Germany anchor plasma collection and recombinant manufacturing capacity for rare hemophilia factors. Australia and Austria feed high-purity plasma source material into CSL Behring's fractionation network. Supply chain risk centers on single-source vulnerability for pathogen reduction biochemistry expertise concentrated among established quality management systems. Distribution runs through hemophilia treatment center procurement committees with direct-to-patient cold-chain logistics expanding fastest in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hemophilia treatment center network consolidation in the United States and Germany, with federally funded HTC coalitions now coordinating procurement for over seventy percent of severe patients and compressing supplier margins through centralized tendering.
For Market Incumbents: Secure captive plasma collection infrastructure through backward integration into source plasma networks, insulating supply from CSL Behring's collection dominance. Lock in hemophilia treatment center formulary positioning through extended half-life formulation commitments before gene therapy substitution accelerates. Priority lever: viral inactivation biochemistry talent retention against recombinant specialist poaching. For New Entrants and Emerging Players: Anchor in China and India's underpenetrated hemophilia treatment center coverage where diagnosis expansion outpaces supply infrastructure. Target inhibitor patient management with activated prothrombin complex concentrate formulations, the fastest-expanding underserved subset. Go-to-market angle: subcutaneous delivery platform partnerships bypassing intravenous administration barriers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated plasma collectors with captive source material and established FDA/EMA quality management systems. Long-term viability in the factor replacement window depends on patient retention infrastructure durability against gene therapy substitution timelines. Signal to watch: hemophilia treatment center prophylactic protocol persistence rates as gene therapy readouts mature.| Strategic Initiative | Industry Significance |
|---|---|
| Extended Half-Life Formulation Development | FDA accelerated approval compresses timelines for PEGylation and Fc-fusion engineering innovations. |
| Plasma Collection Network Expansion | CSL Behring's integrated infrastructure demonstrates cost leadership against recombinant manufacturing platforms. |
| Subcutaneous Delivery Platform Partnership | Home healthcare volume capture in Japan reduces institutional dependence and expands patient autonomy. |
| Cold-Chain Sustainability Redesign | EU F-Gas Regulation compliance forces phase-change material innovation without protein stability compromise. |
| Inhibitor Patient Management Focus | Activated prothrombin complex concentrate demand expands fastest among underserved bypass therapy populations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hemophilia treatment center procurement databases. Interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers inform demand-side validation. Bottom-up patient population modeling triangulates against top-down plasma fractionation capacity assessments.
Segmentation dimensions modeled span product type, therapy area, end-user channel, and delivery mode across the projection horizon. CAGRs derive from treatment center prophylactic protocol penetration curves and gene therapy pipeline substitution scenarios. Forecast inputs incorporate WHO international standard potency assay harmonization timelines and cold-chain sustainability compliance cost trajectories.
Material uncertainties — gene therapy clinical readouts, plasma collection yield volatility, and regulatory pathway acceleration decisions — sit outside the modeled envelope. Forecasts reflect assumptions on patient retention infrastructure durability and reimbursement framework stability. Recalibration cycles align with material shifts in hemophilia treatment center network consolidation and gene therapy commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market