
 Congenital Adrenal Hyperplasia Market | 2026-2036
Congenital Adrenal Hyperplasia Market Size, Share, and Industry Trends Forecast 2026-2036
Congenital Adrenal Hyperplasia Market Analysis
Project finance partnerships between biotech ventures and institutional investors is reconfiguring capital deployment across rare disease therapeutics. Novartis leverages its established endocrinology infrastructure to sustain commercial reach in corticosteroid replacement therapies. Diurnal Limited specializes in modified-release hydrocortisone formulations that compete on dosing convenience against conventional immediate-release options. Spruce Biosciences anchors its position through targeted development in adult CAH populations, a historically underserved segment.
Congenital adrenal hyperplasia comprises a family of autosomal recessive disorders impairing cortisol biosynthesis, most commonly from 21-hydroxylase deficiency, with patients requiring lifelong glucocorticoid and often mineralocorticoid replacement to prevent adrenal crisis and virilization. Hydrocortisone dominates current prescribing patterns as the foundational glucocorticoid replacement, though modified-release delivery systems are capturing attention from clinicians seeking circadian-matched cortisol profiles. Among end user settings, hospitals retain the highest procedure volume for acute adrenal crisis management and newborn diagnosis, while homecare channels are expanding as oral maintenance therapy stabilizes and remote monitoring technologies mature.
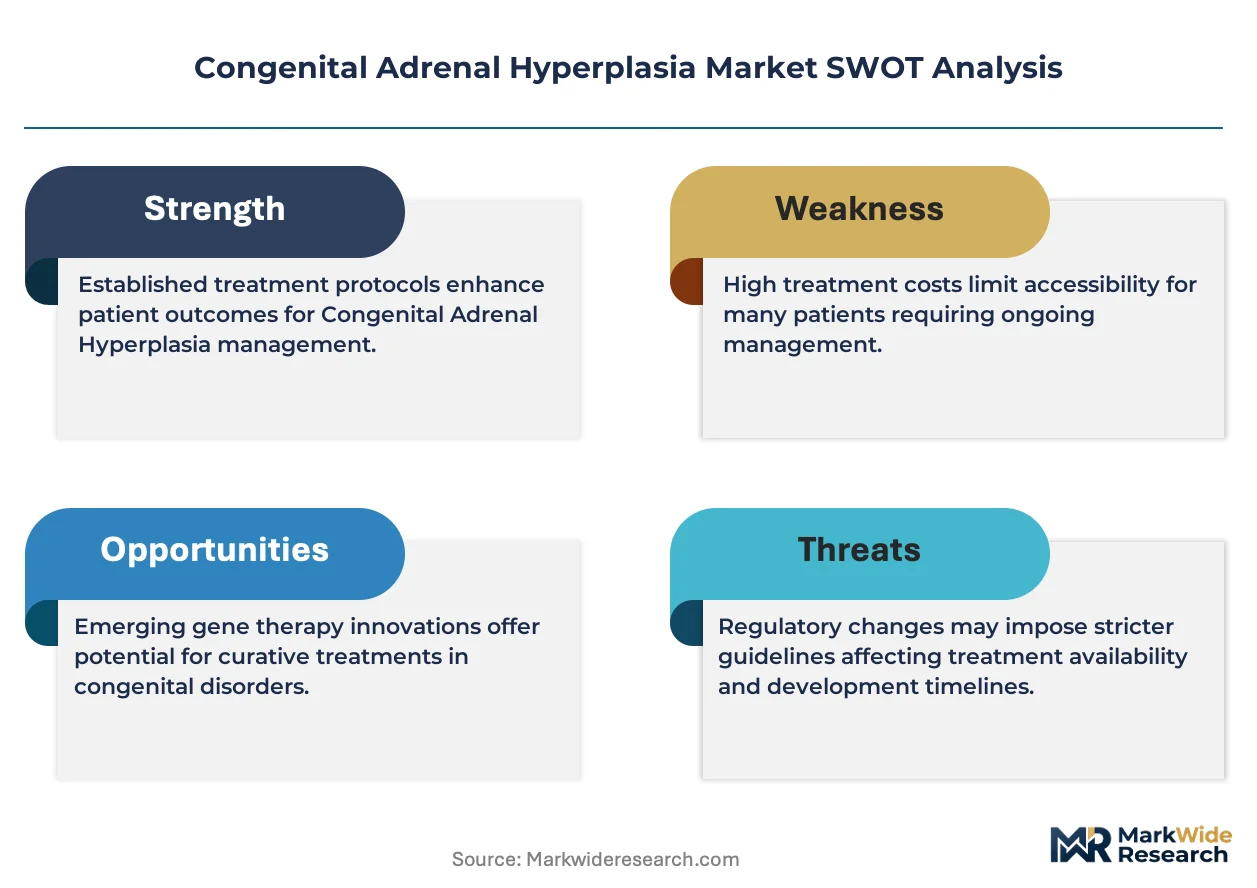
The FDA's orphan drug designation framework shapes development economics by granting market exclusivity and tax incentives for CAH-targeted therapies, while the EMA's parallel pathways in Europe create dual-continent regulatory strategies for sponsors. State-level newborn screening expansion in the United States, administered through the Department of Health and Human Services' Recommended Uniform Screening Panel, directly enlarges the diagnosed patient pool and downstream treatment demand. Stakeholders must monitor how gene therapy platforms and CRISPR-based approaches reposition the competitive boundary between chronic hormone replacement and curative intervention modalities.
Market Dynamics
The FDA's orphan drug designation framework is compressing development timelines for CAH-targeted therapies, while newborn screening mandates across multiple US states are systematically enlarging the diagnosed patient pool and downstream treatment demand.
Growth Catalysts
- Orphan Drug Incentives:The FDA grants seven-year market exclusivity and tax credits for rare disease therapies, directly accelerating sponsor investment in cortisol replacement innovations.
- Newborn Screening Expansion:State health departments are adding 21-hydroxylase deficiency to mandatory panels, creating a steady pipeline of diagnosed pediatric patients requiring lifelong management.
- Modified-Release Formulations:Hydrocortisone delivery systems that match circadian cortisol profiles are capturing clinician preference over immediate-release alternatives in maintenance therapy.
Market Restraints
- Specialized Endocrinology Concentration:CAH management requires pediatric endocrinology expertise that clusters in academic medical centers, limiting rural and community hospital access.
- Fludrocortisone Supply Vulnerability:Mineralocorticoid replacement depends on a narrow supplier base, exposing patients to shortage risks during manufacturing disruptions.
- Gene Therapy Timeline Uncertainty:Curative approaches remain in early-phase trials, perpetuating dependence on chronic hormone replacement without near-term disruption.
Strategic Opportunities
- Adult CAH Underservice:Transition programs from pediatric to adult endocrinology care are underdeveloped, creating white space for specialized clinics and patient support services.
- Homecare Channel Expansion:Remote monitoring technologies and oral maintenance therapy stability are shifting procedure volume from hospitals to home-based management.
- EMA Parallel Pathways:Sponsors pursuing dual-continent regulatory strategies can leverage European market access to amortize development costs across larger patient populations.
Industry Challenges
- Pediatric Endocrinology Workforce Gap:Fellowship-trained specialists are insufficient to serve expanding diagnosed populations, stretching clinic capacity and extending appointment wait times.
- Adrenal Crisis Prevention Complexity:Patient education and stress-dose protocol adherence require intensive nursing resources that strain outpatient program budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Congenital Adrenal Hyperplasia Market |
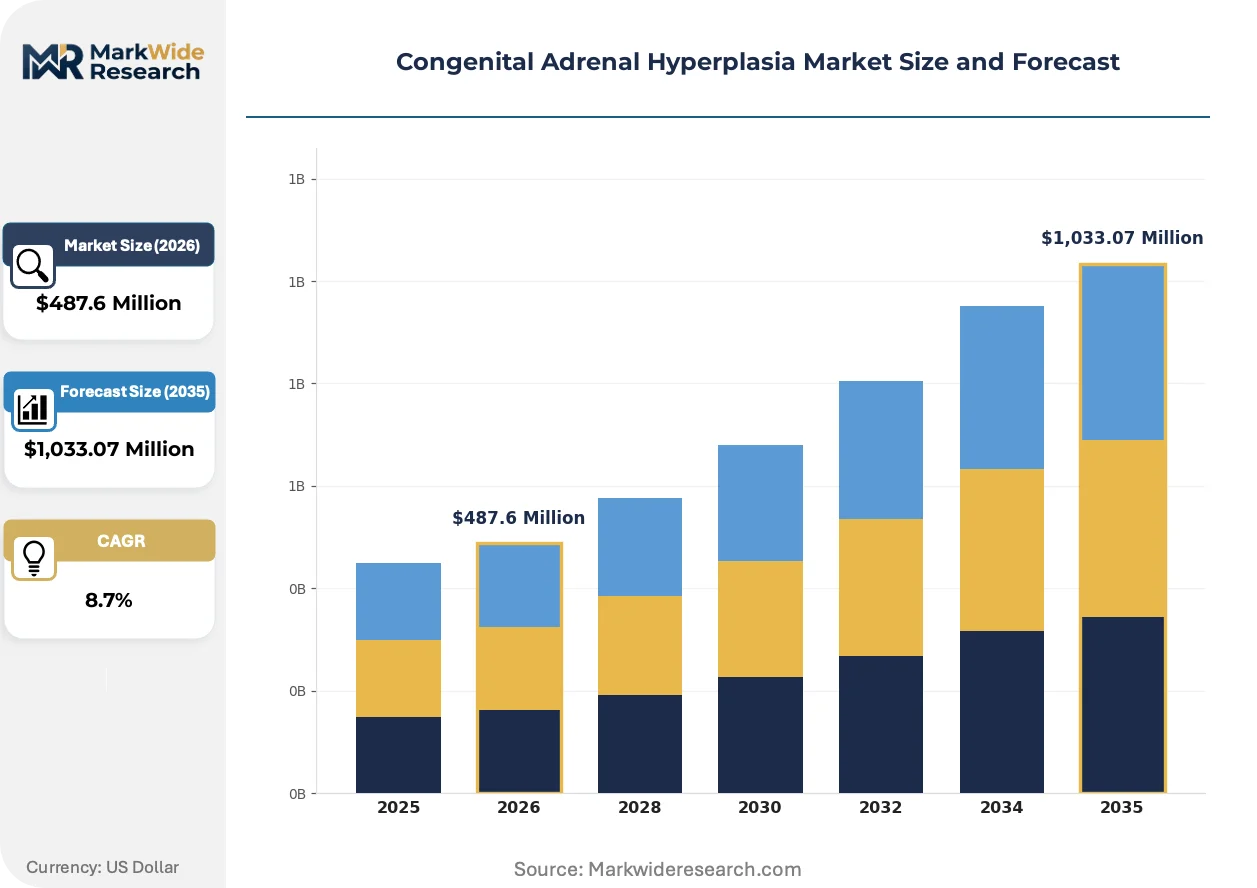
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocortisone, Fludrocortisone, Dexamethasone, Others End User: Hospitals, Clinics, Homecare, Pharmacies Indication: Salt-Wasting Form, Simple Virilizing Form, Non-Classical Form, Others Treatment Type: Hormone Replacement, Surgical Intervention, Genetic Counseling, Others |
| Companies Covered | Diurnal Limited, Novartis, Neurocrine Biosciences, Adrenas Therapeutics, Pfizer, Spruce Biosciences, Crinetics Pharmaceuticals, Millendo Therapeutics, BridgeBio Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Congenital Adrenal Hyperplasia Market Emerging Trajectories
CRISPR-based gene editing platforms and circadian-matched hormone delivery systems are converging to redefine the boundary between chronic management and curative intervention in adrenal steroidogenesis disorders.
Modified-release hydrocortisone formulations are hybridizing pharmacokinetic profiles with natural cortisol rhythms. Pediatric endocrinology clinics in academic medical centers are adopting these systems for patients struggling with conventional three-times-daily dosing. The technology is hybridizing competitive positioning by enabling product differentiation beyond bioequivalence to convenience and adherence metrics.
The FDA's orphan drug exclusivity framework is reshaping development economics for rare disease therapeutics. Sponsors now structure Phase II/III trial designs to capture pediatric exclusivity vouchers alongside standard market exclusivity. Adult CAH populations are responding with expanded clinical trial participation as sponsors seek broader label indications.
Patient advocacy organizations are consolidating purchasing influence through centralized specialty pharmacy relationships. Homecare channels are displacing hospital-based maintenance therapy dispensing as oral formulations stabilize and remote adrenal crisis prevention protocols mature. This shift is most visible in the United States, where reimbursement infrastructure supports sustained home-based patient access.
Congenital Adrenal Hyperplasia Market Segmentation
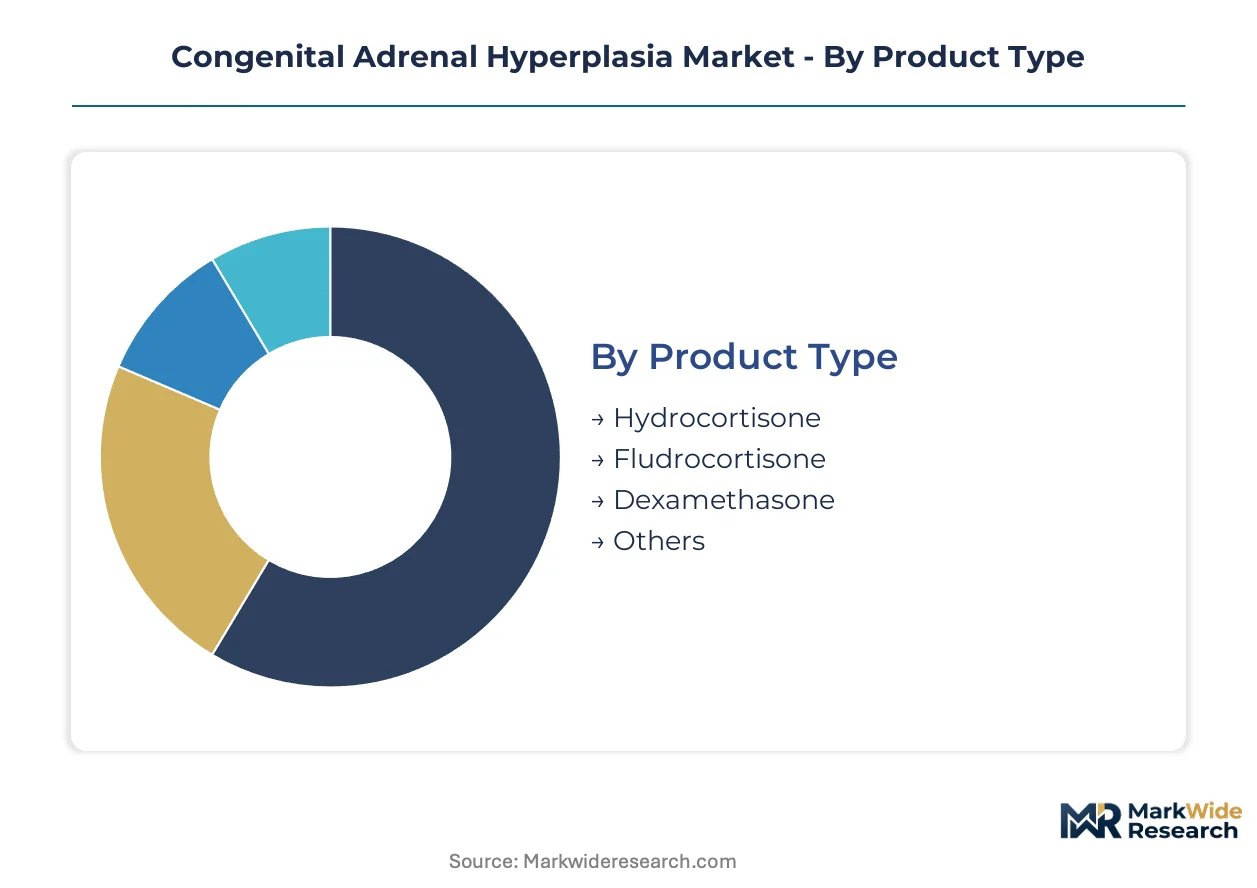
CAH therapeutic demand fragments across hormone replacement modalities, care delivery settings, disease severity phenotypes, and intervention approaches. Each segmentation axis reveals distinct reimbursement pathways, prescriber behaviors, and patient access constraints that shape commercial strategy.
Product Type:
The use-case spectrum spans acute crisis management, chronic mineralocorticoid maintenance, and off-label glucocorticoid alternatives with distinct safety profiles.
- Hydrocortisone:Immediate-release and modified-release formulations constitute the foundational glucocorticoid replacement, with circadian-matched delivery systems capturing preference in academic pediatric endocrinology centers seeking adherence optimization.
- Fludrocortisone:Mineralocorticoid replacement addresses aldosterone deficiency in salt-wasting phenotypes; supply concentration among limited manufacturers exposes patients to shortage risks during manufacturing disruptions.
- Dexamethasone:Potent long-acting glucocorticoid deployed primarily in prenatal intervention protocols and select adult cases requiring suppression of excess androgen production.
- Others:Prednisone and prednisolone serve as cost-accessible alternatives in resource-constrained settings where hydrocortisone availability remains limited.
Established volume favors hydrocortisone; emerging adoption favors modified-release circadian formulations.
End User:
Cost tier stratification separates acute intervention reimbursement from chronic maintenance dispensing economics.
- Hospitals:Academic medical centers manage adrenal crisis stabilization, newborn diagnosis confirmation, and perioperative stress-dose protocols; emergency department utilization drives highest per-episode reimbursement.
- Clinics:Pediatric endocrinology specialty practices concentrate in urban academic corridors, creating access deserts for rural diagnosed populations.
- Homecare:Remote monitoring technologies and oral maintenance stability are shifting procedure volume from institutional settings to home-based management with specialty pharmacy support.
- Pharmacies:Retail and specialty pharmacy channels handle chronic prescription fulfillment with prior authorization complexity varying by payer type.
Revenue concentration sits with hospitals; patient volume expansion is climbing the fastest in homecare channels.
Indication:
Application severity determines treatment intensity, monitoring frequency, and lifelong complication risk profiles.
- Salt-Wasting Form:Severe 21-hydroxylase deficiency presenting with neonatal adrenal crisis risk requires immediate mineralocorticoid plus glucocorticoid replacement; newborn screening mandates have expanded diagnosed prevalence.
- Simple Virilizing Form:Moderate enzyme deficiency produces virilization without salt loss; management focuses on glucocorticoid replacement and surgical consultation for ambiguous genitalia.
- Non-Classical Form:Late-onset mild deficiency often presents in adolescence or adulthood with hirsutism or infertility; diagnostic underrecognition leaves substantial undiagnosed prevalence.
- Others:Rare enzyme deficiencies including 11-beta-hydroxylase and 17-alpha-hydroxylase variants require specialized biochemical profiling and tailored hormone protocols.
Clinical attention concentrates on salt-wasting forms; diagnostic expansion is gaining share fastest in non-classical phenotypes.
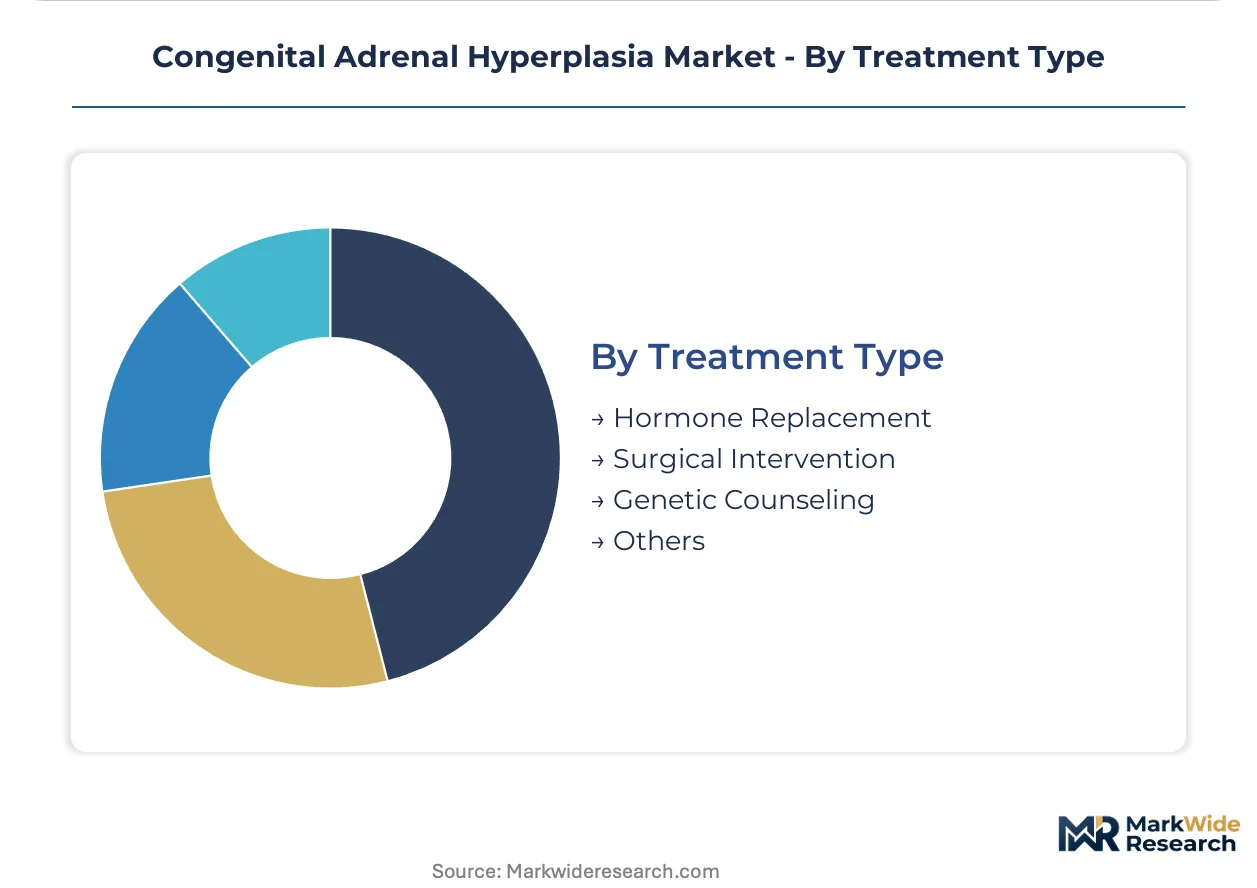
Treatment Type:
Customer type segmentation separates chronic medical management from curative aspiration and reproductive planning services.
- Hormone Replacement:Lifelong glucocorticoid and mineralocorticoid administration constitutes standard of care, with dosing optimization representing the dominant clinical activity and reimbursement category.
- Surgical Intervention:Feminizing genitoplasty and clitoral reduction procedures address virilization sequelae; timing and necessity remain contested within patient advocacy communities.
- Genetic Counseling:Autosomal recessive inheritance patterns drive family planning consultations, with carrier screening expanding among at-risk populations in high-prevalence ethnic communities.
- Others:Experimental gene therapy protocols and CRISPR-based approaches occupy early-phase clinical investigation, with curative potential threatening long-term replacement therapy economics.
Established volume favors hormone replacement; emerging adoption favors genetic counseling services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in CAH therapeutics reflect concentrated manufacturing in North America and Europe against expanding diagnostic demand in Asia-Pacific. The United States maintains a net export position in specialized hormone formulations. Import dependence persists for mineralocorticoid raw materials.
United States
Academic medical centers in Boston, New York, and San Francisco anchor specialized pediatric endocrinology capacity. The FDA's orphan drug exclusivity framework compresses development timelines for CAH-targeted therapies. Newborn screening mandates administered through the Department of Health and Human Services' Recommended Uniform Screening Panel systematically enlarge the diagnosed patient pool across all 50 states.
Germany
University hospitals in Munich, Heidelberg, and Berlin concentrate Europe's largest pediatric endocrinology research networks. The EMA's parallel regulatory pathways enable sponsors to amortize development costs across European and North American markets. Baden-Württemberg hosts multiple clinical trial sites investigating modified-release hydrocortisone formulations.
United Kingdom
The NHS's specialized commissioning framework directs CAH patients toward designated supraregional centers in London, Birmingham, and Manchester. NICE technology appraisals determine reimbursement eligibility for novel hormone replacement therapies. Diurnal Limited, a UK-based sponsor, leverages domestic regulatory familiarity to advance circadian-matched cortisol delivery systems.
Japan
PMDA's sakigake designation system accelerates review timelines for rare disease therapeutics including CAH interventions. Tokyo and Osaka medical centers lead Asia-Pacific enrollment in multinational Phase III trials. Domestic pharmaceutical manufacturers are expanding partnerships with Western sponsors to license modified-release formulation technologies.
Australia
The TGA's orphan drug program mirrors FDA incentives with market exclusivity provisions for CAH-targeted therapies. Sydney and Melbourne pediatric hospitals participate in international consortia for genotype-phenotype correlation studies. Remote monitoring infrastructure in rural Queensland and Western Australia supports homecare channel expansion for stable maintenance therapy patients.
Congenital Adrenal Hyperplasia Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and delivery mechanism innovation. Market structure concentrates around established endocrinology portfolios and rare disease-focused biotech ventures. Three archetypes dominate: multinational pharmaceutical conglomerates with metabolic franchises, orphan drug specialists leveraging regulatory incentives, and gene therapy platforms pursuing curative mechanisms. Competitive moves center on portfolio diversification into adult CAH populations and strategic partnerships to secure modified-release formulation capabilities.
Within the multinational tier, Novartis anchors metabolic and endocrine therapeutic presence through established corticosteroid infrastructure. Among orphan drug specialists, Diurnal Limited exemplifies circadian-matched formulation development, while Spruce Biosciences occupies a position targeting historically underserved adult CAH segments. These three represent distinct strategic postures: incumbent defense, delivery innovation, and population expansion.
| Leading Market Players |
|---|
| Diurnal Limited |
| Novartis |
| Neurocrine Biosciences |
| Adrenas Therapeutics |
| Pfizer |
| Spruce Biosciences |
| Crinetics Pharmaceuticals |
| Millendo Therapeutics |
| BridgeBio Pharma |
| Others |
Supply Flow & Price Mechanics
Fludrocortisone API manufacturing concentrates in a narrow base of European and North American suppliers, anchoring margin capture with finished dose formulators who command pricing power through FDA orphan exclusivity. This upstream concentration limits buyer negotiation leverage and perpetuates cost pass-through to hospital procurement and specialty pharmacy channels.
Pricing Analysis
Hospital procurement committees and specialty pharmacy buyers anchor pricing structures around value-based contracts tied to FDA orphan designation status. Pricing stratifies across premium circadian-matched formulations, standard immediate-release hydrocortisone, and economy-tier prednisone alternatives in resource-constrained settings. Cost compression in the standard tier is intensifying because of prednisone substitution pressure from Medicaid formularies. Safety-net clinics and rural health systems demonstrate highest price sensitivity; academic medical centers with dedicated pediatric endocrinology programs exhibit lowest.
Supply Chain Analysis
Single-source vulnerability for mineralocorticoid active pharmaceutical ingredients dominates supply chain risk exposure between Italian and German chemical manufacturers and North American finished dose facilities. Geographic supply concentration clusters in Switzerland, Germany, and the United States for corticosteroid APIs, with India emerging for prednisone intermediates. Raw material dependencies rest on cortisol precursor steroids, specialized coating polymers for modified-release systems, and fludrocortisone acetate base compounds. Distribution runs through specialty pharmacy networks with cold-chain requirements for certain hormone formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Purchasing influence is consolidating through centralized specialty pharmacy relationships and GPO contracting, shifting negotiating leverage toward sophisticated procurement organizations and away from fragmented individual prescriber practices.
For Market Incumbents: Pre-empt gene therapy platform entry by deepening backward integration into circadian-matched formulation technologies and securing exclusive API supply agreements with European steroid manufacturers. Orphan drug exclusivity windows face compression from curative intervention pipelines; priority levers include adult CAH label expansion and pediatric exclusivity voucher capture through accelerated clinical trial enrollment. For New Entrants and Emerging Players: Pursue white-space positioning in non-classical CAH diagnostic expansion and adult transition clinic services, the most penetrable segments where incumbent coverage remains thin. Homecare channel infrastructure offers accessible entry with lower capital requirements than hospital-based distribution. A go-to-market angle anchored in remote adrenal crisis monitoring technology differentiates against legacy hormone replacement pure-plays. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rare disease platform companies holding multiple orphan indications but subscale endocrinology infrastructure. Long-term viability over a five-to-ten year horizon hinges on whether modified-release formulation patents outlast gene therapy regulatory approval timelines. Acquisition target archetypes include circadian-delivery specialists with EMA parallel pathway progress. The signal to watch is PMDA sakigake designation acceleration for CRISPR-based adrenal interventions.| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Release Formulation Development | Diurnal Limited's circadian-matched hydrocortisone systems capture clinician preference in academic pediatric centers. |
| Adult CAH Label Expansion | Spruce Biosciences targets historically underserved adult populations with specialized clinical trial infrastructure. |
| Orphan Drug Exclusivity Capture | FDA seven-year market exclusivity and tax credits accelerate sponsor investment in cortisol replacement innovations. |
| Homecare Channel Infrastructure Buildout | Remote monitoring technologies shift procedure volume from hospitals to specialty pharmacy-supported home management. |
| EMA Parallel Pathway Execution | German and UK clinical trial sites amortize development costs across European and North American market access. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric endocrinologists, specialty pharmacy procurement directors, hospital formulary committee members, and regulatory affairs leads at orphan drug sponsors. Secondary validation drew from FDA orphan drug designation filings, EMA parallel assessment pathways, ClinicalTrials.gov CAH protocol registries, and CMS Medicare Part D utilization data. Bottom-up patient prevalence modeling and top-down therapeutic market sizing were triangulated against newborn screening mandate expansion timelines.
Calibration against historical hydrocortisone prescription volumes and modified-release formulation adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include hormone replacement modality, care delivery setting, disease severity phenotype, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for orphan drug exclusivity expiration schedules and gene therapy pipeline maturation. Forecast inputs incorporated state-level newborn screening mandate implementation rates and pediatric endocrinology fellowship graduation trajectories.
Sensitivities concentrate around gene therapy regulatory acceleration timelines and fludrocortisone supply disruption scenarios. Forecasts reflect documented assumptions regarding orphan drug incentive continuity and screening panel expansion velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Global Hemoglobinopathies Market