
 Angioedema Treatment Market | 2026-2036
Angioedema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Angioedema Treatment Market Analysis
The EU Green Deal's pharmaceutical sustainability requirements is rebalancing procurement priorities across European hospital networks, favoring manufacturers with reduced cold-chain footprints. Takeda Pharmaceutical Company Limited anchors its position through integrated plasma-derived and recombinant product portfolios spanning prophylactic and acute indications. BioCryst Pharmaceuticals, Inc. specializes in oral small-molecule kallikrein inhibition, differentiating its route of administration against injectable standards. CSL Behring leverages its plasma collection infrastructure to sustain supply security for C1-inhibitor concentrates.
Angioedema treatment encompasses pharmacological interventions targeting bradykinin-mediated and histamine-mediated vascular permeability, with biologics such as lanadelumab and berotralstat functioning as monoclonal antibodies or small molecules that modulate plasma kallikrein activity to prevent episodic swelling. These therapies serve to reduce attack frequency, severity, and hospitalization burden in hereditary, acquired, and idiopathic patient populations. Injectable medications command premium positioning due to rapid onset requirements in emergency scenarios, while biologics represent the fastest-expanding category as subcutaneous self-administration protocols shift care from hospitals toward homecare settings. Oral delivery modes retain substantial volume in allergic and idiopathic segments where antihistamines and corticosteroids remain first-line standards.
The FDA's orphan drug exclusivity framework and EMA's priority medicines scheme jointly accelerate novel therapy development timelines while tightening post-market pharmacovigilance obligations for biologic agents. REACH compliance across European manufacturing and the EPA's pharmaceutical effluent guidelines in the United States impose additional formulation and disposal standards that shape regional competitive access. Stakeholders must monitor evolving biosimilar entry pathways for C1-inhibitor products and the reimbursement negotiations that will determine commercial traction for next-generation oral prophylactics.
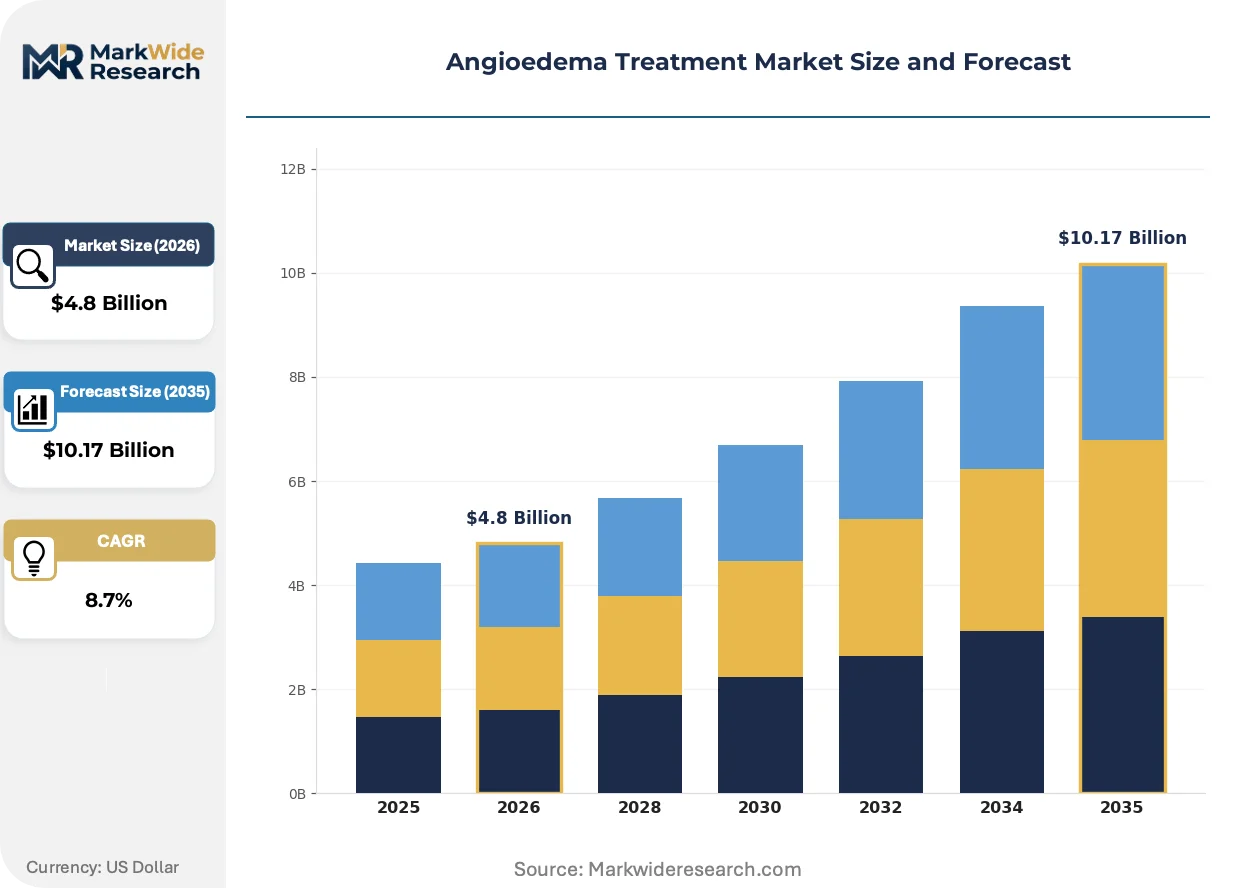
Market Dynamics
Plasma kallikrein inhibitors are compressing the treatment paradigm for hereditary angioedema, shifting acute intervention toward prophylactic self-administration and redrawing the competitive boundary between biologic and small-molecule platforms.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug exclusivity framework accelerates development timelines for novel plasma kallikrein modulators, reducing regulatory friction for sponsors targeting ultra-rare populations.
- Homecare Migration:Subcutaneous self-administration protocols are displacing hospital-based infusions, expanding addressable patient pools through reduced clinical burden and improved adherence profiles.
- Specialist Center Consolidation:United States immunology centers are standardizing protocol templates and negotiating bundled reimbursement for advanced biologics, concentrating demand around evidence-based therapeutic hierarchies.
Market Restraints
- Plasma Supply Concentration:C1-inhibitor concentrate production depends on geographically concentrated plasma collection networks, exposing manufacturers to collection disruptions and fractionation capacity constraints.
- Recombinant Manufacturing Complexity:Cell culture yields for recombinant C1-inhibitor remain suboptimal relative to plasma-derived alternatives, limiting cost competitiveness at scale.
- Diagnostic Underrecognition:Idiopathic angioedema cases frequently escape specialist referral pathways due to symptom overlap with allergic presentations, compressing addressable market boundaries.
Strategic Opportunities
- Oral Prophylactic Expansion:Small-molecule kallikrein inhibitors with daily oral dosing profiles can penetrate patient segments refusing injectable regimens due to needle aversion or travel-intensive lifestyles.
- EMA Priority Medicines Pathway:Accelerated assessment timelines for breakthrough therapies enable earlier European market entry, creating first-mover positioning before FDA orphan exclusivity periods expire.
- Allied Health Integration:Nurse educator networks and specialty pharmacy channels can capture patient onboarding and adherence monitoring functions previously performed in hospital infusion centers.
Industry Challenges
- Pharmacovigilance Scale-Up:Post-market surveillance obligations for biologic agents require substantial investment in patient registries and adverse event infrastructure, particularly for long-acting monoclonal antibodies with extended exposure windows.
- Cold-Chain Reconfiguration:REACH compliance and the EU Green Deal's pharmaceutical sustainability requirements are forcing reformulation investments to reduce temperature-controlled distribution footprints across European hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angioedema Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Biologics, Injectable Medications End User: Hospitals, Clinics, Homecare Settings, Emergency Services Therapy Area: Allergic Reactions, Genetic Conditions, Drug Reactions, Idiopathic Cases Delivery Mode: Oral, Injectable, Intravenous, Sublingual |
| Companies Covered | Pharming Group N.V., KalVista Pharmaceuticals, Inc., Takeda Pharmaceutical Company Limited, Astria Therapeutics, Sanofi, CSL Behring, Ionis Pharmaceuticals, Inc., Shire, BioCryst Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angioedema Treatment Market Emerging Trajectories
Route-of-administration innovation is fragmenting competitive positioning in angioedema prophylaxis, with oral small molecules challenging the injectable biologic standard that has dominated the category for the past decade.
Subcutaneous monoclonal antibodies targeting plasma kallikrein are overtaking intravenous C1-inhibitor concentrates as the preferred prophylactic option in specialist immunology centers. Patient populations with high attack frequency are adopting quarterly or bi-monthly injection schedules that eliminate the burden of twice-weekly infusions. This shift is compressing hospital infusion revenue streams while expanding pharmacy benefit management complexity for payers.
The EPA's pharmaceutical effluent guidelines are tightening discharge standards for active pharmaceutical ingredients across United States manufacturing facilities. Formulation scientists must redesign synthesis pathways to reduce aqueous waste streams containing biologic residuals or synthetic intermediates. Biologic manufacturers with integrated recovery systems are gaining competitive access to procurement contracts with sustainability-mandated hospital networks.
Patients and caregivers are demanding unbundled care models that separate drug acquisition from clinical monitoring services. Specialty pharmacies are capturing prescription fulfillment and adherence support functions that academic medical centers previously controlled through bundled infusion protocols. This disintermediation is most visible in the United States, where pharmacy benefit carve-outs and accumulator adjustment programs are redirecting economic flows away from provider-administered reimbursement structures.
Angioedema Treatment Market Segmentation
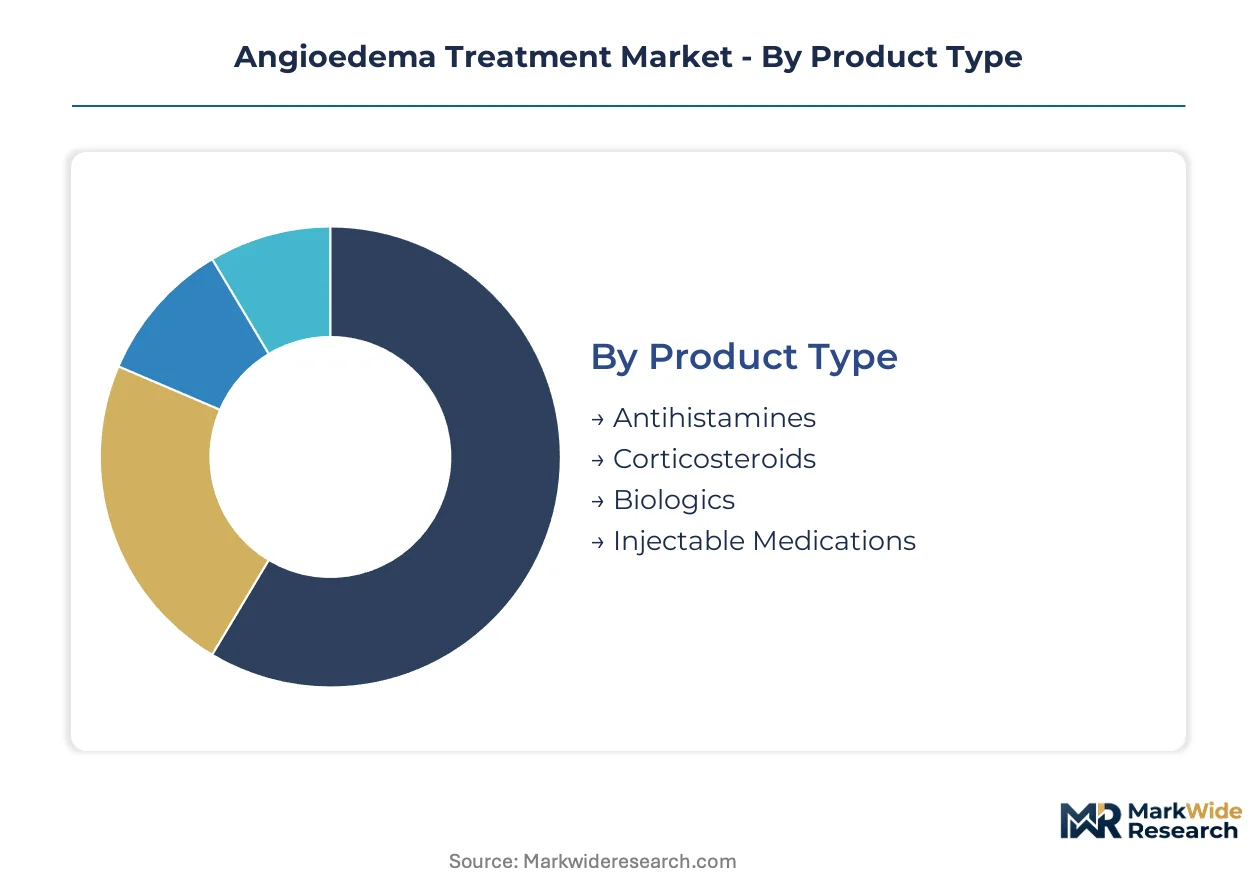
Treatment modality selection in angioedema care follows distinct clinical pathways determined by attack severity, patient autonomy preferences, and reimbursement structures. Segmentation reveals how supply concentration in plasma-derived products contrasts with emerging manufacturing approaches across therapy categories.
Product Type:
Plasma collection infrastructure and recombinant manufacturing capacity concentrate supply for advanced therapies in distinct geographic clusters.
- Antihistamines:First-line histamine receptor antagonists address allergic and idiopathic presentations through competitive H1-blockade. Primary care networks in the United States and Germany drive volume through over-the-counter availability combined with prescription-tier coverage for severe cases.
- Corticosteroids:Systemic glucocorticoids modulate immune-mediated vascular permeability in acute breakthrough episodes. Hospital emergency departments in France and Italy retain these agents for rescue protocols despite biologic displacement in prophylaxis.
- Biologics:Monoclonal antibodies and recombinant proteins targeting plasma kallikrein or bradykinin pathways command premium positioning through specialist-administered protocols.
- Injectable Medications:Subcutaneous and intravenous formulations deliver rapid onset for acute attacks and sustained prophylaxis in hereditary populations.
Biologics absorb the bulk of installed capacity; injectable medications are expanding most quickly through self-administration adoption.
End User:
Care site migration follows reimbursement redesign and patient preference for reduced clinical burden.
- Hospitals:Academic medical centers anchor acute intervention capacity with 24-hour infusion availability and specialist immunology coverage.
- Clinics:Outpatient specialist practices concentrate prophylactic monitoring and attack documentation for rare disease registries.
- Homecare Settings:Self-administered subcutaneous biologics shift economic flows toward specialty pharmacy channels and away from facility-based reimbursement.
- Emergency Services:Pre-hospital protocols incorporate plasma-derived C1-inhibitor for suspected hereditary attacks during ambulance transport.
Hospitals retain the dominant share of acute intervention volume; homecare settings are climbing the fastest as pharmacy benefit carve-outs accelerate.
Therapy Area:
Diagnostic clarity determines addressable market boundaries and treatment algorithm selection.
- Allergic Reactions:IgE-mediated histamine release responds to antihistamine and corticosteroid protocols with established efficacy profiles.
- Genetic Conditions:Hereditary angioedema with C1-inhibitor deficiency drives biologic innovation through well-defined mechanistic targets and orphan drug incentives.
- Drug Reactions:ACE inhibitor-induced angioedema requires bradykinin pathway interruption rather than histamine blockade.
- Idiopathic Cases:Symptom presentations without identifiable trigger compress specialist referral rates and delay optimal therapy initiation.
Genetic conditions command the highest per-patient investment; idiopathic cases represent the largest diagnostic gap limiting market penetration.
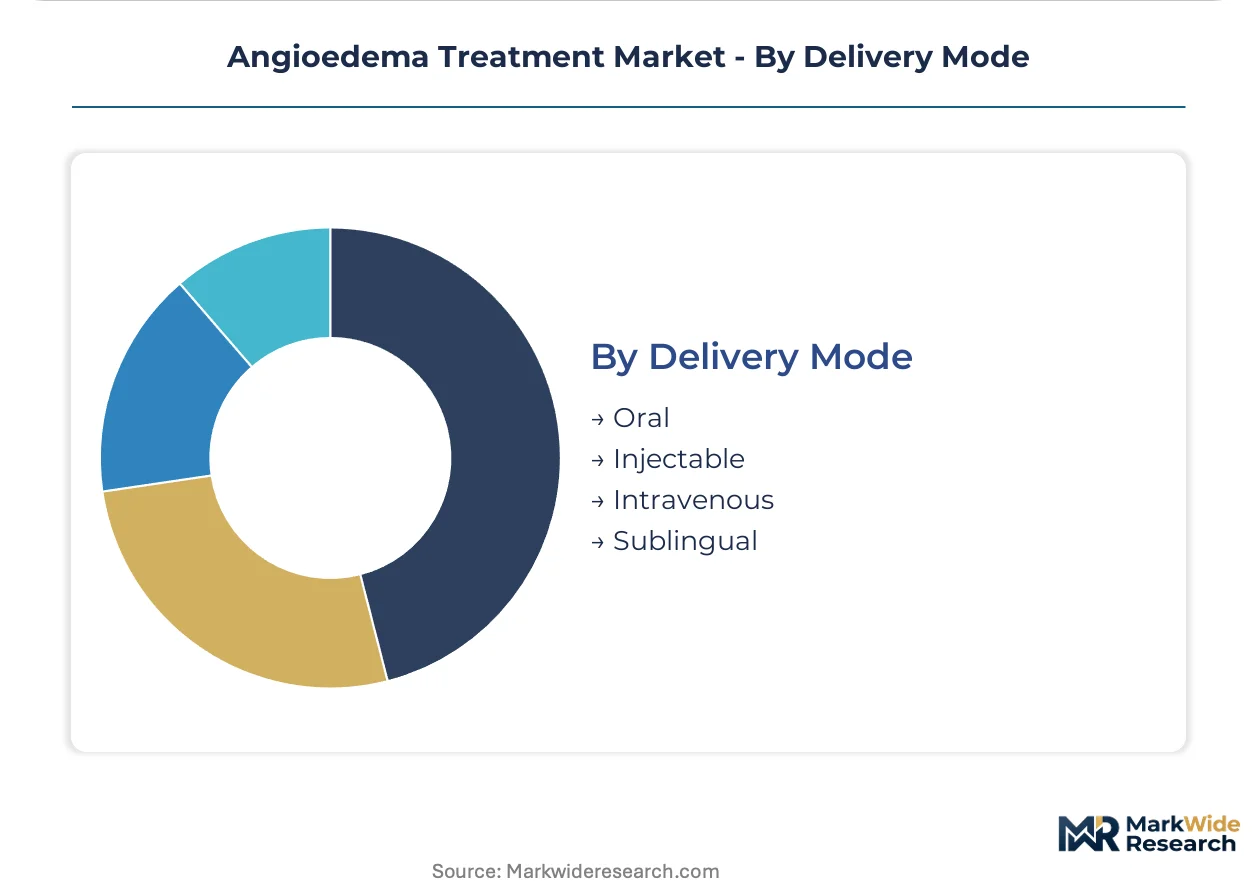
Delivery Mode:
Formulation technology and cold-chain requirements shape manufacturing investment and distribution economics.
- Oral:Small-molecule kallikrein inhibitors eliminate injection burden for prophylactic patients with needle aversion or travel-intensive lifestyles.
- Injectable:Subcutaneous monoclonal antibodies and plasma-derived concentrates balance rapid absorption with patient-administered convenience.
- Intravenous:Hospital-confused infusions of C1-inhibitor concentrate remain essential for severe acute attacks requiring immediate intervention.
- Sublingual:Dissolving film formulations address pediatric populations and patients with swallowing difficulties in select markets.
Injectable delivery absorbs the dominant share of biologic volume; oral formulations are gaining share fastest through patient preference and reduced cold-chain dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's specialist immunology corridor anchors North American demand concentration for plasma kallikrein inhibitors, while Basel and Frankfurt pharmaceutical clusters drive European biologics manufacturing scale.
United States
Specialist immunology centers in Massachusetts and North Carolina compress referral pathways for hereditary angioedema patients toward academic medical centers. The FDA's orphan drug exclusivity framework accelerates development timelines for novel plasma kallikrein modulators. Philadelphia's plasma fractionation corridor sustains C1-inhibitor concentrate supply security through vertically integrated collection networks.
Germany
Baden-Württemberg's recombinant protein manufacturing base supplies European hospital networks with prophylactic biologics. REACH compliance mandates across European manufacturing impose reformulation investments to reduce temperature-controlled distribution footprints. Munich's specialist immunology clinics standardize protocol templates for subcutaneous self-administration adoption.
Japan
PMDA's Sakigake designation system compresses review timelines for breakthrough plasma kallikrein inhibitors targeting ultra-rare populations. Tokyo's university hospital networks anchor acute intervention capacity with 24-hour infusion availability. Osaka's pharmaceutical manufacturing corridor concentrates recombinant C1-inhibitor production for Asia-Pacific distribution.
Switzerland
Swissmedic's expedited access pathway enables earlier market entry for oral small-molecule prophylactics. Basel's biologics manufacturing cluster sustains monoclonal antibody production for quarterly injection schedules. Zurich's specialty pharmacy channels capture patient onboarding functions previously performed in hospital infusion centers.
United Kingdom
NHS England's specialized commissioning framework concentrates reimbursement negotiation for advanced biologics around designated rare disease centers. The MHRA's post-Brexit regulatory autonomy enables accelerated assessment timelines for plasma kallikrein inhibitors. London's academic medical centers anchor protocol standardization for homecare migration of subcutaneous therapies.
Angioedema Treatment Market Vendor Landscape
The competitive structure tilts toward integrated plasma-derived and recombinant product portfolios spanning prophylactic and acute indications. Large-cap pharmaceutical groups with rare disease divisions anchor market concentration through bundled reimbursement negotiations. Three archetypes dominate: plasma collection infrastructure owners, oral small-molecule specialists, and monoclonal antibody developers. Strategic moves center on portfolio diversification across delivery modes and geographic expansion through EMA priority medicines pathways.
Among integrated biopharmaceutical groups, Takeda Pharmaceutical Company Limited and CSL Behring exemplify the plasma-derived and recombinant convergence archetype. BioCryst Pharmaceuticals, Inc. occupies a distinct position representing oral small-molecule kallikrein inhibition specialists differentiating against injectable standards.
| Leading Market Players |
|---|
| Pharming Group N.V. |
| KalVista Pharmaceuticals, Inc. |
| Takeda Pharmaceutical Company Limited |
| Astria Therapeutics |
| Sanofi |
| CSL Behring |
| Ionis Pharmaceuticals, Inc. |
| Shire |
| BioCryst Pharmaceuticals, Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal sustainability mandates are forcing pharmaceutical procurement officers to rebalance supplier selection toward manufacturers with reduced cold-chain footprints, compelling reformulation investments that compress margins and reshape competitive access across European hospital networks.
Pricing Analysis
Value-based pricing anchored to attack frequency reduction and hospitalization avoidance dominates reimbursement negotiations for plasma kallikrein inhibitors. Pricing stratifies across premium biologic tiers with orphan drug exclusivity, standard recombinant products, and economy-positioned plasma-derived concentrates. Cost compression in the standard tier is intensifying as biosimilar pathways mature for C1-inhibitor products. Hospital formulary directors exhibit highest price sensitivity; specialist immunology centers demonstrate lowest sensitivity due to bundled outcome contracts.
Supply Chain Analysis
Workforce availability constraints in Pennsylvania's plasma fractionation corridor and Baden-Württemberg's recombinant protein manufacturing base are tightening production scheduling flexibility. Supply concentrates in the United States, Germany, and Switzerland for advanced biologics; plasma collection infrastructure draws from geographically dispersed donor networks across North America and Europe. Single-source vulnerability in plasma-derived C1-inhibitor production exposes manufacturers to collection disruptions. Distribution runs through specialty pharmacy channels displacing hospital-based infusion center fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated plasma-derived and recombinant portfolios, with post-market pharmacovigilance scale-up costs forcing subscale developers toward exit or acquisition.
For Market Incumbents: To counter oral small-molecule displacement of injectable biologics, Takeda and CSL Behring should deepen backward integration into plasma collection networks to secure supply security, while accelerating oral prophylactic pipeline investments to capture patient segments refusing needle-based regimens. For New Entrants and Emerging Players: Begin with idiopathic angioedema cases escaping specialist referral pathways, where diagnostic underrecognition creates white-space opportunity for patient education platforms and direct-to-specialist telemedicine channels that compress time-to-diagnosis and treatment initiation. For Investors and Strategic Acquirers: The window for entry favors oral small-molecule specialists with EMA priority medicines designation and late-stage clinical assets, with long-term viability hinging on reimbursement negotiation outcomes for next-generation prophylactics. Watch FDA biosimilar approval timelines for C1-inhibitor products as the inflection signal for margin compression in the plasma-derived segment.| Strategic Initiative | Industry Significance |
|---|---|
| Oral Prophylactic Pipeline Advancement | Daily small-molecule dosing captures needle-averse patients refusing subcutaneous biologics. |
| Plasma Collection Infrastructure Expansion | Vertically integrated donor networks in the United States secure C1-inhibitor concentrate supply security. |
| EMA Priority Medicines Pathway Navigation | Accelerated European assessment enables first-mover positioning before FDA orphan exclusivity expires. |
| Specialty Pharmacy Channel Partnership | Patient onboarding capture shifts economic flows from hospital infusion centers. |
| Post-Market Pharmacovigilance Scale-Up | Long-acting monoclonal antibody registries satisfy tightening EMA and FDA surveillance obligations. |
Methodological Framework
FDA orphan drug designations, EMA priority medicines submissions, and ClinicalTrials.gov protocol records formed the secondary backbone, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, formulary directors, and payer access specialists across the United States, Germany, and Switzerland. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation validated segment sizing.
Historical trendline analysis of plasma-derived and recombinant product revenue trajectories informed the analytical framework across the analysis window, with segmentation modeling across therapy area, delivery mode, and regional regulatory cluster. CAGRs derived from attack frequency reduction outcomes and hospitalization cost avoidance data informed value-based pricing assumptions.
Regulatory approval delays, plasma collection disruptions, and biosimilar entry acceleration are the dominant revision risks to forecast assumptions. Material deviation in any named trigger warrants pause and re-evaluation of market penetration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Frozen Skin Graft Market