
 Rosai-Dorfman Disease (RDD) Therapeutics Market | 2026-2036
Rosai-Dorfman Disease (RDD) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Rosai-Dorfman Disease (RDD) Therapeutics Market Analytics
Oncology referral networks is restructuring how RDD therapeutics reach patients, shifting volume toward centers with dedicated histiocytosis programs. Novartis AG anchors its presence through immunotherapy research platforms that address rare histiocytic disorders. Pfizer Inc. competes via established hospital formulary relationships that facilitate off-label utilization in acute RDD cases. Teva Pharmaceuticals Ltd. leverages generic manufacturing scale to supply corticosteroid and chemotherapy backbones used in first-line RDD management.
Rosai-Dorfman Disease therapeutics encompass pharmaceutical interventions targeting sinus histiocytosis with massive lymphadenopathy, a rare non-Langerhans cell histiocytosis characterized by emperipolesis on histopathological examination. These treatments primarily function to control lymphadenopathy, extranodal involvement, and systemic inflammation in patients with symptomatic disease. Immunotherapy commands attention as the fastest-expanding therapy type, driven by MEK inhibitor and BRAF-targeted investigations in refractory cases. The intravenous administration route maintains its entrenched position in hospital settings, while oral formulations gain traction in maintenance protocols through specialty clinic channels.
The FDA's Orphan Drug Designation and Rare Pediatric Disease Priority Review Voucher programs shape developer incentives, accelerating clinical trial enrollment and shortening regulatory timelines for RDD-focused candidates. EMA's Committee for Orphan Medicinal Products provides parallel European pathways, though histiocytosis-specific guidance remains less codified than for more prevalent oncologic indications. Stakeholders must monitor biomarker-driven trial designs and real-world evidence generation to differentiate therapies in this ultra-rare indication with heterogeneous clinical presentations.
Market Dynamics
The FDA's Orphan Drug Designation program is compressing clinical trial timelines for RDD candidates while EMA's parallel pathways expand developer incentives across the Atlantic. This regulatory acceleration is reshaping how ultra-rare histiocytic disorder therapies advance from bench to bedside.
Growth Catalysts
- Orphan Drug Incentives:The FDA's tax credits and market exclusivity provisions lower financial barriers for developers targeting sinus histiocytosis with massive lymphadenopathy. Pediatric rare disease priority review vouchers create secondary revenue streams.
- MEK Inhibitor Platforms:Targeted kinase inhibition is demonstrating efficacy in refractory RDD cases with BRAF pathway mutations. Academic medical centers are expanding compassionate use protocols.
- Histiocytosis Society Networks:Patient advocacy infrastructure in the United States is streamlining referral pathways to specialty centers with dedicated RDD expertise. Registry data generation is accelerating natural history studies.
Market Restraints
- Ultra-Rare Prevalence:Incidence below one per million creates prohibitive patient recruitment costs for randomized controlled trials. Natural history data scarcity complicates endpoint selection.
- Corticosteroid Backbone Dependence:First-line management relies on generic prednisone with established hospital formulary placement. Novel mechanisms face reimbursement scrutiny without head-to-head superiority data.
- Diagnostic Pathology Bottlenecks:Emperipolesis identification requires specialized hematopathology expertise concentrated at tertiary academic centers. Community hospital misdiagnosis delays appropriate referral.
Strategic Opportunities
- Real-World Evidence Generation:EMA's adaptive pathways framework accepts expanded access data as confirmatory evidence. European reference networks for rare diseases provide structured data collection infrastructure.
- Companion Diagnostic Development:BRAF V600E and MAP2K1 mutation profiling is enabling biomarker-stratified trial designs. Central laboratory partnerships with oncology networks expand testing access.
- Maintenance Oral Formulations:Transition from intravenous to oral MEK inhibitor dosing is opening ambulatory care channels. Specialty pharmacy distribution models reduce hospital infusion center burden.
Industry Challenges
- Histiocytosis Specialist Scarcity:Fellowship-trained physicians capable of managing complex extranodal RDD remain concentrated at fewer than fifty US academic centers. Telemedicine credentialing across state lines creates operational friction.
- Biomarker Assay Standardization:Variable immunohistochemistry protocols for S100 and CD68 staining produce inconsistent diagnostic sensitivity. Cross-platform harmonization efforts lack industry sponsorship.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosai-Dorfman Disease (RDD) Therapeutics Market |
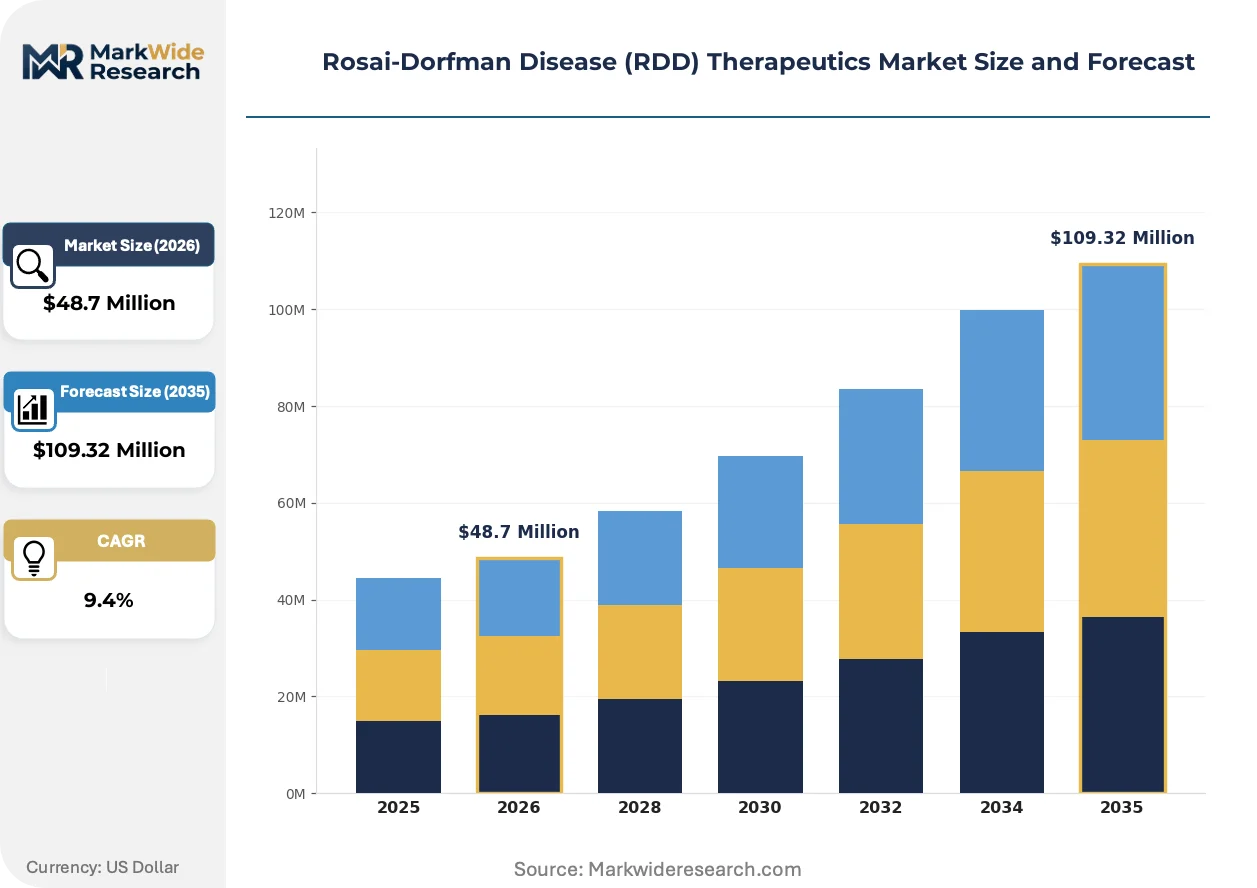
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Administration Route: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Homecare, Research Institutions Formulation: Injectable, Tablet, Cream, Powder |
| Companies Covered | Teva Pharmaceuticals Ltd., Novartis AG, Pfizer Inc., Sun Pharmaceuticals Industries Ltd., Dr. Reddy's Laboratories Ltd., Aurobindo Pharma, Zydus Pharmaceuticals, Inc., Viatris Inc., Advanz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosai-Dorfman Disease (RDD) Therapeutics Market Evolving Landscape
Immunomodulatory mechanisms are displacing cytotoxic backbones in RDD therapeutic development, with targeted pathway inhibition commanding preclinical investment. Three convergent forces are reshaping clinical and commercial trajectories.
Next-generation sequencing panels are automating molecular characterization of histiocytic neoplasms, enabling rapid BRAF and MAP2K1 mutation detection at academic pathology laboratories. Community oncology practices are adopting these platforms through reference laboratory partnerships. This technology is automating patient stratification for MEK inhibitor eligibility, compressing time-to-appropriate-therapy from months to weeks.
EMA's Committee for Orphan Medicinal Products is streamlining histiocytosis-specific scientific advice procedures, reducing protocol assessment timelines for ultra-rare indications. Parallel FDA rare disease endpoint advancement grants are funding natural history study infrastructure. European reference networks for rare hematologic diseases are responding with standardized data collection templates to support marketing authorization applications.
Specialty clinic consolidation is centralizing RDD case volume at centers with embedded clinical trial units, displacing fragmented community-based management. University hospital networks are acquiring community oncology practices to capture referral flow. This concentration is most visible in the United States, where NCI-designated cancer centers are establishing dedicated histiocytosis programs with multidisciplinary tumor boards.
Rosai-Dorfman Disease (RDD) Therapeutics Market Segmentation
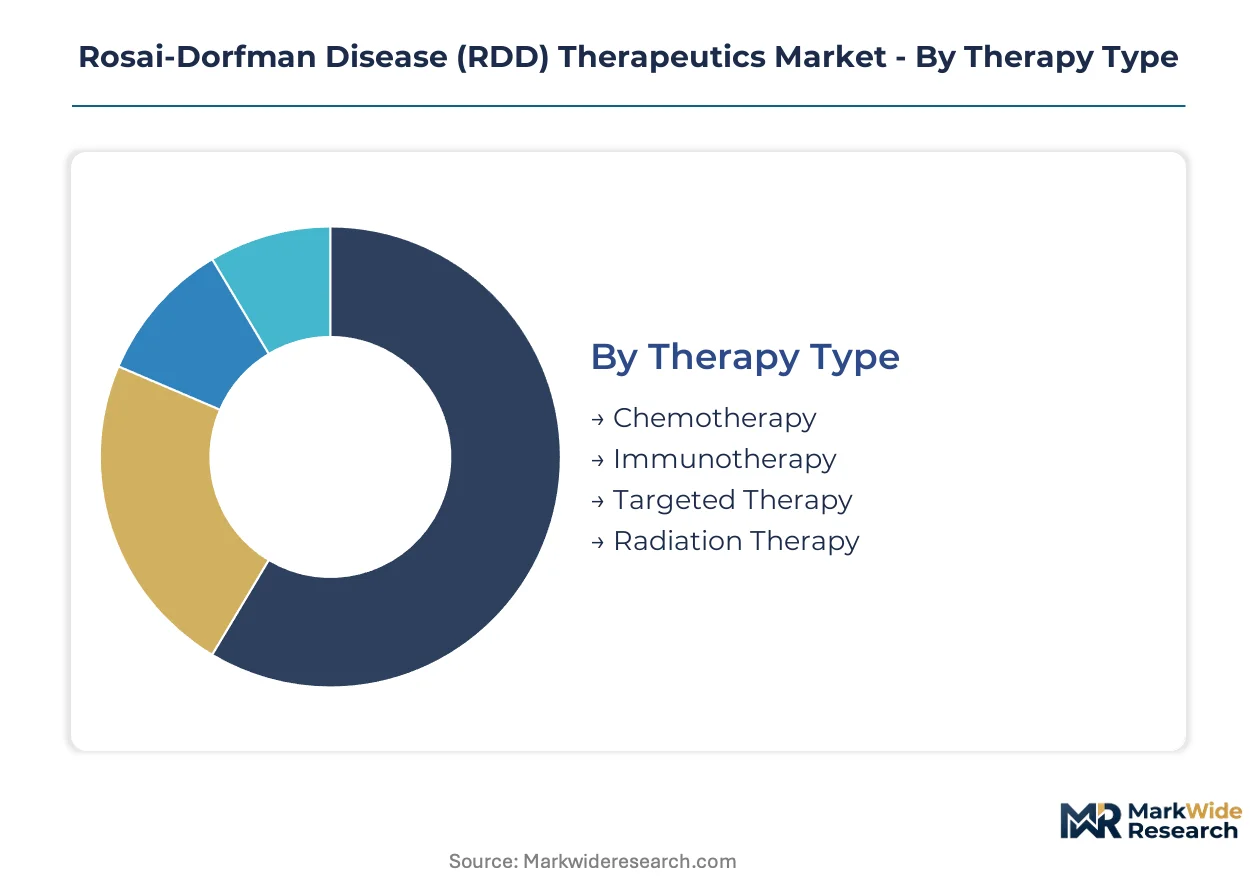
Rosai-Dorfman Disease therapeutics fragment across therapy mechanisms, delivery modes, and care settings. Each segmentation axis reveals distinct supply chain configurations and patient access patterns that shape commercial strategy in this ultra-rare indication.
Therapy Type:
Supply concentration in RDD therapeutics clusters around established mechanism classes with proven formulary placement, while novel modalities remain dependent on academic medical center procurement channels.
- Immunotherapy:MEK inhibitors and BRAF-targeted agents constitute the mechanism class attracting preclinical investment and compassionate use expansion. Demand concentrates at NCI-designated cancer centers with embedded histiocytosis programs, driven by biomarker-stratified patient identification through next-generation sequencing panels.
- Targeted Therapy:Kinase inhibition platforms address refractory cases with MAPK pathway mutations, requiring centralized pathology review and molecular tumor board coordination. Academic referral networks in the United States channel these patients toward centers with clinical trial infrastructure.
- Chemotherapy:Generic alkylating agents and vinca alkaloids maintain hospital formulary dominance through decades of established utilization in histiocytic disorders.
- Radiation Therapy:External beam applications target localized extranodal disease with curative intent in isolated bone or soft tissue involvement.
Immunotherapy absorbs the bulk of installed capacity among novel mechanisms; targeted therapy is expanding most quickly through biomarker-driven trial enrollment.
Administration Route:
Cost tier differentiation separates hospital-based infusion services from ambulatory oral dispensing, with reimbursement mechanics determining route selection more than clinical preference alone.
- Intravenous:Hospital infusion centers administer cytotoxic backbones and biologic agents requiring monitoring. This route commands premium reimbursement through Medicare Part B in the United States, anchoring revenue at academic medical centers with dedicated histiocytosis units.
- Oral:MEK inhibitor tablets enable maintenance protocols outside hospital settings, reducing infusion center burden. Specialty pharmacy distribution networks in the United States manage prior authorization complexity for these high-cost oral agents.
- Subcutaneous:Limited applications include interferon formulations for select refractory cases with cutaneous predominance.
- Topical:Localized skin-directed therapy addresses isolated cutaneous RDD without systemic involvement.
Intravenous administration retains the majority of procedure volume; oral formulations are climbing the fastest as maintenance protocols extend duration of therapy.
End User:
Customer type fragmentation reflects the concentration of diagnostic expertise at tertiary centers versus the dispersion of stable patients into community settings.
- Hospitals:Academic medical centers with hematopathology expertise and emperipolesis-capable pathologists anchor initial diagnosis and acute management. These institutions capture complex extranodal cases requiring multidisciplinary coordination across otolaryngology, neurosurgery, and orthopedic oncology.
- Specialty Clinics:Dedicated histiocytosis programs at NCI-designated centers concentrate longitudinal care and clinical trial access. Patient advocacy networks in the United States streamline referrals to these specialized units.
- Homecare:Oral maintenance therapy and nursing support for stable patients transition care away from institutional settings.
- Research Institutions:Natural history registries and biomarker repositories operate through Histiocytosis Society-affiliated centers.
Hospitals retain the dominant share of acute episode value; specialty clinics are gaining share fastest through patient consolidation and trial unit expansion.
Formulation:
Manufacturing maturity separates sterile injectable capacity from solid oral dosage forms, with compounding pharmacy regulations creating additional segmentation in topical and powder presentations.
- Injectable:Lyophilized biologics and cytotoxic agents require cold chain distribution to hospital pharmacies. Contract manufacturing organizations with sterile fill-finish capability anchor supply security for these presentations.
- Tablet:Oral MEK inhibitors and corticosteroid taper packs enable ambulatory management. High-throughput solid dose manufacturing at established pharmaceutical facilities supports scale.
- Cream:Topical corticosteroid and calcineurin inhibitor preparations address cutaneous manifestations through dermatology channels.
- Powder:Reconstitution-required formulations for hospital pharmacy compounding occupy niche applications in pediatric dosing flexibility.
Injectable formulations command the majority of manufacturing investment; tablets are expanding most quickly through oral targeted therapy development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rosai-Dorfman Disease therapeutic development concentrates where rare disease infrastructure and orphan drug incentives align, while consumption patterns follow diagnostic pathology expertise to tertiary academic centers.
United States
The National Institutes of Health maintains the Histiocytosis Association registry and funds natural history studies through its Rare Diseases Clinical Research Network. FDA's Orphan Drug Designation program provides tax credits and seven-year market exclusivity for RDD-focused developers. NCI-designated cancer centers in Boston, Houston, and New York anchor the nation's dedicated histiocytosis programs with embedded clinical trial units.
Germany
EMA's Committee for Orphan Medicinal Products streamlines scientific advice for histiocytosis drug developers seeking European marketing authorization. The German Federal Institute for Drugs and Medical Devices enforces parallel national requirements for rare disease trial protocols. Heidelberg and Berlin university hospitals concentrate the country's emperipolesis-capable pathology expertise and molecular tumor board infrastructure.
United Kingdom
NHS England's Highly Specialised Services framework commissions centralized RDD management through designated supraregional centers. The Medicines and Healthcare products Regulatory Agency coordinates with EMA on orphan drug assessments while maintaining national pharmacovigilance oversight. London's Royal Free Hospital and University College London Hospitals anchor the country's referral networks for complex extranodal cases.
Japan
PMDA's Sakigake designation system accelerates regulatory review for innovative therapies targeting ultra-rare indications including histiocytic disorders. The Ministry of Health, Labour and Welfare maintains the National Rare Disease Registry to support post-market surveillance. Tokyo and Osaka university hospitals concentrate the nation's fellowship-trained hematopathologists capable of definitive RDD diagnosis.
Switzerland
Swissmedic's pediatric investigation plan requirements shape development timelines for RDD therapies with potential childhood indications. The Federal Office of Public Health coordinates reference center designation for rare hematologic diseases across cantonal healthcare systems. Basel and Zurich academic medical centers anchor the country's molecular diagnostics infrastructure for BRAF and MAP2K1 mutation profiling.
Rosai-Dorfman Disease (RDD) Therapeutics Market Competitive Landscape
Top-tier vendors anchor immunotherapy and targeted therapy development, while mid-scale generic manufacturers supply corticosteroid and chemotherapy backbones. The competitive structure stratifies across three archetypes: multinational pharmaceutical conglomerates with rare disease platforms, established generic houses with hospital formulary relationships, and emerging biotechs pursuing biomarker-stratified kinase inhibitors. Consolidation pressures intensify as specialty clinic networks centralize procurement decisions at fewer academic centers. Dominant competitive moves include strategic partnerships with molecular diagnostics laboratories and geographic expansion through European reference network affiliations.
Among the established pharmaceutical tier, Novartis AG and Pfizer Inc. exemplify contrasting strategic positions—Novartis occupying the immunotherapy research platform archetype while Pfizer represents the hospital formulary relationship model. Teva Pharmaceuticals Ltd. anchors the generic manufacturing scale archetype supplying first-line corticosteroid management. These three entities collectively represent the competitive spectrum from novel mechanism development to established backbone supply.
| Leading Market Players |
|---|
| Teva Pharmaceuticals Ltd. |
| Novartis AG |
| Pfizer Inc. |
| Sun Pharmaceuticals Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Aurobindo Pharma |
| Zydus Pharmaceuticals, Inc. |
| Viatris Inc. |
| Advanz Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient sourcing costs for MEK inhibitor production flow through Swiss and German contract manufacturing organizations before reaching tiered reimbursement brackets at US academic medical centers. This upstream cost concentration shapes downstream pricing power for novel immunotherapy candidates while generic corticosteroid backbones compete on hospital formulary placement.
Pricing Analysis
Margin tightening in oral maintenance therapy reflects specialty pharmacy prior authorization complexity and Medicare Part D coverage gap exposure. Three-tier pricing structure across premium biologics, standard targeted agents, and economy generic backbones dominates hospital procurement. Pricing pressure intensifies in first-line corticosteroid segments as Teva and Viatris compete on prednisone tablet tenders. Community oncology practices demonstrate highest price sensitivity; NCI-designated centers absorb premium pricing for biomarker-stratified therapies.
Supply Chain Analysis
Single-source vulnerability sits with Swiss sterile fill-finish capacity for lyophilized biologics and Indian API manufacturing for corticosteroid intermediates. MEK inhibitor synthesis draws from Chinese specialty chemical precursors and German chromatography resin suppliers. Regulatory restriction risk centers on FDA import alerts affecting Indian API facilities. Distribution runs through specialty pharmacy networks for oral agents and hospital central pharmacy procurement for intravenous formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rosai-Dorfman Disease therapeutics represents a vertical-integration race where backward control over biomarker assay development separates winners from formulary-dependent suppliers. Players are pursuing captive pathology laboratory partnerships to lock patient identification upstream of treatment selection.
For Market Incumbents: Deploy molecular diagnostic platform acquisitions to secure emperipolesis-capable pathology capacity before emerging biotechs consolidate reference laboratory networks. Novartis and Pfizer must defend against kinase inhibitor commoditization by embedding clinical trial units within Histiocytosis Society-affiliated centers. Channel control through specialty pharmacy exclusive distribution agreements protects oral MEK inhibitor margins from generic substitution pressure. For New Entrants and Emerging Players: Academic medical center pathology partnerships offer the most penetrable entry channel for biomarker-stratified therapy developers. Target European reference networks for rare hematologic diseases where EMA adaptive pathways accept real-world evidence from expanded access programs. Go-to-market positioning should emphasize companion diagnostic co-development with centralized laboratory networks in Germany and the United Kingdom. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale biotechs with orphan drug designation already secured and Phase I/II histiocytosis data in hand. Long-term viability hinges on five-to-ten year exclusivity runway maintenance through pediatric indication expansion. Watch FDA rare disease endpoint advancement grant awards as inflection signals for natural history study infrastructure availability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Central laboratory partnerships with Foundation Medicine or Tempus accelerate biomarker-stratified patient identification for MEK inhibitor eligibility. |
| Orphan Drug Designation Pursuit | FDA tax credits and seven-year exclusivity provisions lower financial barriers for developers targeting ultra-rare histiocytic disorders. |
| European Reference Network Affiliation | EMA's ERN-RARE framework provides structured data collection infrastructure supporting marketing authorization applications for histiocytosis therapies. |
| Specialty Clinic Acquisition | University hospital networks acquiring community oncology practices capture RDD referral flow toward embedded clinical trial units. |
| Real-World Evidence Generation | Expanded access protocol data satisfies EMA adaptive pathways requirements for confirmatory evidence in ultra-rare indications. |
Research Methodology
Document review covered FDA orphan drug designation filings, EMA Committee for Orphan Medicinal Products opinions, ClinicalTrials.gov histiocytosis protocol registrations, and Histiocytosis Association registry publications, complemented by interviews with drug development executives at rare disease-focused biotechs, regulatory affairs leads navigating FDA rare disease programs, formulary directors at NCI-designated cancer centers, and payer access specialists managing specialty pharmacy prior authorization workflows. Secondary validation drew from SEC 10-K rare disease revenue disclosures, CMS Medicare Part B infusion reimbursement data, and European hospital procurement database extracts. Bottom-up patient prevalence modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Market sizing outputs incorporated therapy-type splits across immunotherapy, targeted therapy, chemotherapy, and radiation segments alongside administration route differentiation between intravenous hospital infusion and oral specialty pharmacy dispensing. The projection horizon spans from base-year assessment through decade-forward modeling, with CAGRs derived from orphan drug approval velocity and histiocytosis program expansion rates at academic medical centers. Forecast inputs included MEK inhibitor pipeline progression timelines, corticosteroid generic tender pricing trajectories, and biomarker testing adoption curves at community oncology practices.
Caveats apply where FDA regulatory pathway changes, EMA scientific advice reinterpretations, or diagnostic pathology automation breakthroughs could materially shift the outlook. Forecasts reflect assumptions about referral network consolidation velocity and orphan drug incentive program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Byler Disease Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Aicardi Syndrome Market