
 Muckle-Wells Syndrome Market | 2026-2036
Muckle-Wells Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Muckle-Wells Syndrome Market Foresight
Orphan drug exclusivity is repositioning the cost-of-entry calculus for developers targeting rare autoinflammatory indications. Kiniksa Pharmaceuticals leverages its pipeline concentration on cryopyrin-associated periodic syndromes to sustain clinical momentum. AbbVie anchors its immunology franchise through broad IL-1 pathway expertise. Novartis AG differentiates via established rare-disease infrastructure and global regulatory navigation.
Muckle-Wells syndrome represents a rare autosomal dominant autoinflammatory disorder driven by NLRP3 gene mutations that trigger uncontrolled IL-1β release, with systemic amyloidosis as the life-threatening long-term complication. Treatment aims to suppress IL-1 signaling through biologic intervention, preventing organ damage and preserving quality of life. Biologics and monoclonal antibodies command the deepest margin pools given their validated efficacy and premium positioning, while gene therapy remains pre-commercial with transformative potential. Injectable delivery dominates current practice, though homecare settings are gaining traction as self-administration protocols mature.
The FDA orphan drug program and EMA's Committee for Orphan Medicinal Products shape development timelines and exclusivity value across North America and Europe. Health Technology Assessment bodies in Germany and France influence reimbursement thresholds for biologic therapies in this ultra-rare space. Stakeholders must monitor pipeline transitions from acute treatment toward long-term management paradigms and the evolving competitive dynamics between IL-1α and IL-1β targeted mechanisms.
Market Dynamics
Orphan drug exclusivity is compressing development timelines for NLRP3 pathway inhibitors while specialty clinics expand rare-disease service lines to capture diagnosed patients. The FDA's seven-year market exclusivity window is accelerating biologic submissions ahead of gene therapy maturation.
Growth Catalysts
- FDA Orphan Drug Exclusivity:The seven-year exclusivity framework for biologics targeting cryopyrin-associated periodic syndromes reduces competitive entry risk and incentivizes pipeline investment in ultra-rare indications.
- Specialty Clinic Expansion:Academic medical centers in Boston, London, and Paris are establishing dedicated autoinflammatory disease units with integrated genetic counseling and long-term amyloidosis monitoring protocols.
- IL-1 Biologics Maturation:Validated manufacturing processes for monoclonal antibodies against IL-1β are reducing production batch variability and enabling consistent supply for chronic administration regimens.
Market Restraints
- Plasma-Derived Input Volatility:Biologic production depends on human serum albumin and other blood-derived components with supply concentration in US and European collection networks.
- Diagnostic Bottlenecks:NLRP3 genetic testing requires specialized sequencing capabilities concentrated at reference laboratories in Baltimore, Heidelberg, and Singapore, creating access gaps in secondary markets.
- Substitution from Small-Molecule JAK Inhibitors:Off-label use of tofacitinib and baricitinib for autoinflammatory symptom management presents pricing pressure on premium biologic positioning.
Strategic Opportunities
- Underpenetrated Diagnosis in Germany:Health Technology Assessment bodies in Berlin and Munich are expanding newborn screening protocols to capture familial cold autoinflammatory syndrome precursors before amyloidosis onset.
- Homecare Self-Administration:Subcutaneous injection training programs through specialty pharmacy networks in California and Texas are shifting treatment delivery from infusion centers to patient homes.
- EMA PRIME Designation:The Priority Medicines scheme is accelerating regulatory pathways for novel IL-1 pathway modulators with differentiated mechanism-of-action profiles.
Industry Challenges
- Genetic Counselor Workforce Constraints:Autoinflammatory disease expertise requires specialized training in Mendelian inheritance patterns with accredited programs concentrated at Johns Hopkins, University of Geneva, and Karolinska Institutet.
- Long-Term Safety Surveillance Infrastructure:Post-marketing pharmacovigilance for biologics requires patient registries with twenty-year follow-up horizons, demanding sustained data collection investment beyond initial approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muckle-Wells Syndrome Market |
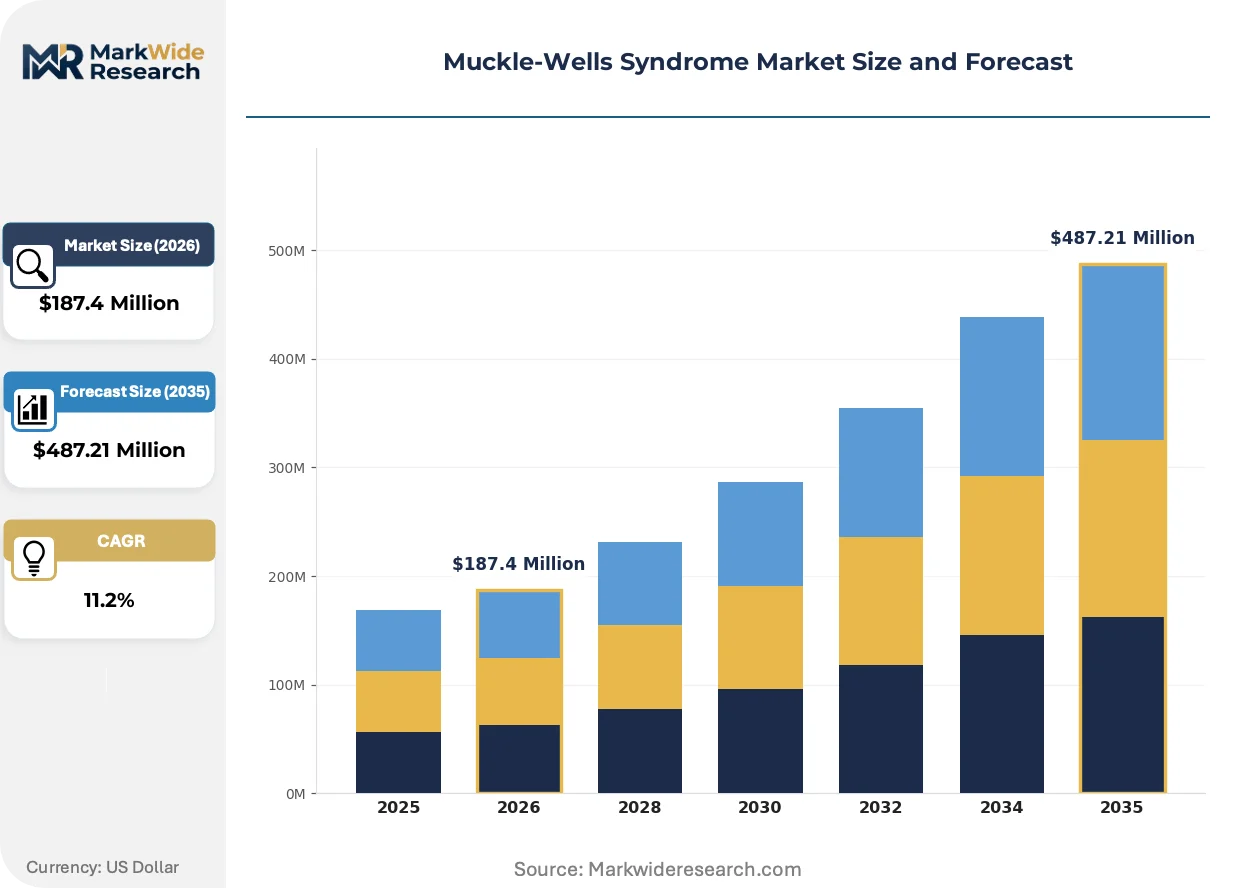
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Gene Therapy, Monoclonal Antibodies End User: Hospitals, Specialty Clinics, Research Institutions, Homecare Settings Delivery Mode: Injectable, Oral, Infusion, Topical Treatment Stage: Acute Treatment, Long-term Management, Clinical Trials, Palliative Care |
| Companies Covered | Kiniksa Pharmaceuticals, AbbVie, Novartis AG, Pfizer, Johnson & Johnson, Regeneron Pharmaceuticals, Takeda Pharmaceutical Company, Sanofi, Swedish Orphan Biovitrum AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muckle-Wells Syndrome Market Shifts & Advancements
Next-generation sequencing platforms are compressing diagnostic timelines from months to weeks while regulatory frameworks adapt to accelerated approval pathways for transformative therapies. Three developments are restructuring competitive positioning.
CRISPR-based gene editing approaches targeting somatic NLRP3 correction are unifying preclinical development pipelines across academic and commercial laboratories. Boston Children's Hospital and Leiden University Medical Center are advancing ex vivo hematopoietic stem cell protocols toward investigational new drug submission readiness. This convergence is compressing the timeline between proof-of-concept and first-in-human trials for curative rather than chronic management paradigms.
REACH authorization requirements for novel biologic substances are mandating extended environmental fate studies for monoclonal antibody manufacturing byproducts. ECHA's updated guidance on persistent, bioaccumulative, and toxic substance classification is extending facility permitting timelines for production sites in the Port of Rotterdam cluster and Basel pharmaceutical corridor. Contract manufacturing organizations with established environmental risk assessment capabilities are capturing outsourced production from developers lacking in-house toxicology infrastructure.
Patient advocacy organizations are consolidating procurement influence through centralized purchasing cooperatives that negotiate indication-based value agreements directly with manufacturers. The Autoinflammatory Alliance and EURORDIS are establishing reference pricing databases across France, Italy, and Spain that benchmark annual treatment costs against quality-adjusted life year thresholds. This aggregation is most visible in Paris and Madrid, where hospital pharmacy committees now defer to cooperative pricing benchmarks rather than conducting independent health technology assessments for ultra-rare indications.
Muckle-Wells Syndrome Market Segmentation
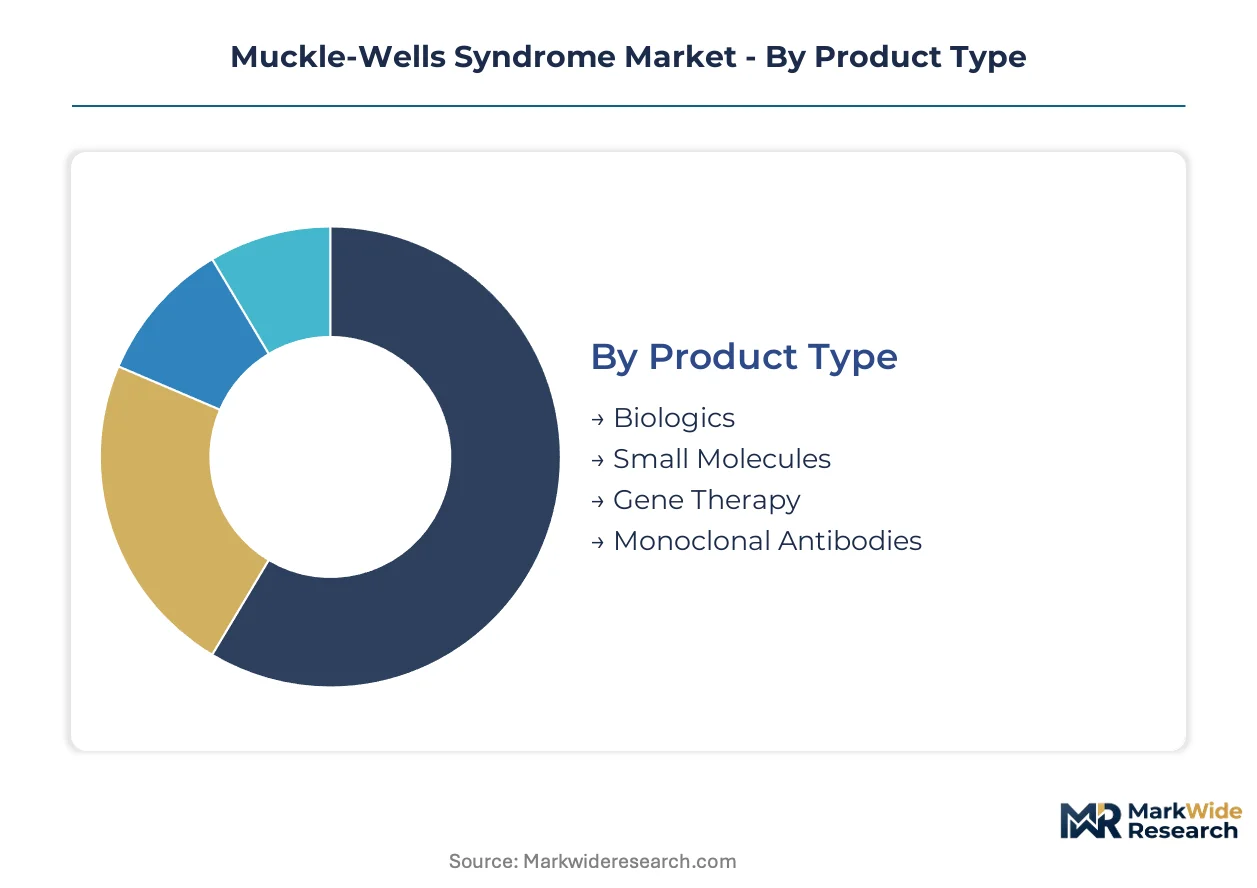
Segmentation in the Muckle-Wells syndrome market reflects divergent development timelines between validated IL-1 pathway biologics and emerging curative modalities. Manufacturers align portfolio investments with distinct reimbursement pathways and patient access infrastructures.
Product Type:
Technology platforms differentiate by clinical validation depth and manufacturing complexity.
- Biologics:Engineered proteins targeting IL-1β signaling dominate current therapeutic protocols. Demand concentrates in United States specialty clinics where payer coverage for cryopyrin-associated periodic syndromes has matured, though batch consistency requirements constrain supply elasticity.
- Monoclonal Antibodies:Fully humanized constructs with validated Fc-region engineering command premium positioning through established amyloidosis prevention data. United States academic medical centers in Boston and Baltimore anchor adoption, driven by long-term safety registries tracking renal function preservation.
- Small Molecules:Oral NLRP3 inflammasome inhibitors offer administration convenience but lack regulatory approval for this indication.
- Gene Therapy:Pre-commercial somatic correction approaches target curative outcomes through ex vivo hematopoietic stem cell editing.
Biologics lead on scale; gene therapy leads on momentum.
End User:
Care delivery settings fragment by diagnostic capability and reimbursement sophistication.
- Specialty Clinics:Dedicated autoinflammatory disease units integrate genetic counseling with amyloidosis monitoring protocols. Demand concentrates in Paris and London where EMA-aligned Health Technology Assessment frameworks enable rapid biologic access post-diagnosis.
- Hospitals:Academic medical centers manage severe systemic amyloidosis complications through multidisciplinary nephrology-rheumatology teams. United States tertiary centers in Baltimore and Boston anchor complex case volume, driven by NLRP3 sequencing availability at reference laboratories.
- Homecare Settings:Subcutaneous self-administration programs shift treatment delivery from infusion centers.
- Research Institutions:Clinical trial sites advance novel mechanism-of-action candidates through FDA orphan drug pathways.
Hospitals lead on scale; homecare settings expand most quickly.
Delivery Mode:
Administration route determines patient autonomy and healthcare resource utilization patterns.
- Injectable:Subcutaneous formulations enable home-based administration with established cold-chain logistics. United States specialty pharmacy networks in California and Texas drive adoption, supported by nurse training programs reducing clinic dependency.
- Infusion:Intravenous delivery maintains position for acute flares and hospitalized patients requiring rapid cytokine suppression.
- Oral:Small-molecule candidates in development target chronic maintenance without injection burden.
- Topical:Limited applicability given systemic nature of NLRP3-driven inflammation.
Injectable leads on scale; oral climbs the fastest.
Treatment Stage:
Clinical indication shapes therapy duration and value demonstration requirements.
- Long-term Management:Chronic IL-1 suppression prevents progressive amyloidosis and preserves organ function. Demand concentrates in Germany where newborn screening expansion captures familial cold autoinflammatory syndrome precursors before irreversible damage.
- Acute Treatment:Interventional protocols address severe inflammatory flares requiring hospitalization.
- Clinical Trials:Investigational sites test next-generation NLRP3 pathway modulators through FDA and EMA accelerated pathways.
- Palliative Care:Symptom-focused approaches address end-stage amyloidosis with limited reversibility.
Long-term management leads on scale; clinical trials gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Muckle-Wells syndrome therapeutics originated in European academic centers during the 1990s, with foundational NLRP3 research emerging from Leiden University Medical Center and subsequent biologic development scaling through Basel and Boston pharmaceutical corridors.
United States
Academic medical centers in Boston and Baltimore anchor diagnostic and treatment volume, driven by NLRP3 genetic testing availability at Johns Hopkins reference laboratories. FDA orphan drug exclusivity provides seven-year market protection for novel IL-1 pathway biologics, accelerating pipeline investment. Specialty pharmacy networks in California and Texas are expanding subcutaneous self-administration programs to shift care from infusion centers to patient homes.
Germany
Health Technology Assessment bodies in Berlin and Munich influence reimbursement thresholds for ultra-rare biologic therapies, with expanding newborn screening protocols capturing familial cold autoinflammatory syndrome precursors. The country's statutory health insurance system maintains mature coverage frameworks for cryopyrin-associated periodic syndromes. Heidelberg hosts specialized sequencing capabilities that reduce diagnostic timelines for suspected cases.
France
Paris anchors dedicated autoinflammatory disease units integrating genetic counseling with long-term amyloidosis monitoring protocols. ANSM regulates biologic approval pathways while hospital pharmacy committees reference EURORDIS cooperative pricing benchmarks. The Île-de-France region concentrates both clinical trial sites and patient advocacy organization headquarters coordinating centralized purchasing negotiations.
United Kingdom
London academic centers maintain established rare-disease infrastructure with integrated rheumatology-nephrology multidisciplinary teams. The MHRA aligns with EMA accelerated pathways for novel IL-1 pathway modulators. NHS England's specialized commissioning framework enables rapid biologic access post-diagnosis for confirmed cryopyrin-associated periodic syndrome patients.
Switzerland
Basel's pharmaceutical corridor hosts established manufacturing infrastructure for monoclonal antibody production serving European supply requirements. Swissmedic maintains aligned regulatory pathways with EMA for orphan biologic approvals. The country's concentrated biotech ecosystem supports both commercial production and early-stage gene therapy development for curative NLRP3 approaches.
Muckle-Wells Syndrome Market Competitive Landscape
The competitive structure tilts toward diversified immunology specialists with IL-1 pathway expertise rather than rare-disease pure-plays. Three archetypes dominate: large-cap pharmaceutical conglomerates with broad immunology franchises, mid-cap biotech firms with concentrated autoinflammatory pipelines, and emerging gene therapy developers advancing pre-commercial curative modalities. Capacity expansion in monoclonal antibody manufacturing and strategic partnerships for diagnostic-coupled treatment protocols represent the dominant competitive moves.
Within the large-cap immunology tier, AbbVie anchors broad IL-1 pathway expertise across multiple inflammatory indications, while Novartis AG leverages established rare-disease infrastructure and global regulatory navigation capabilities. Kiniksa Pharmaceuticals exemplifies the mid-cap concentrated approach, with pipeline focus specifically on cryopyrin-associated periodic syndromes sustaining clinical momentum in this ultra-rare space.
| Leading Market Players |
|---|
| Kiniksa Pharmaceuticals |
| AbbVie |
| Novartis AG |
| Pfizer |
| Johnson & Johnson |
| Regeneron Pharmaceuticals |
| Takeda Pharmaceutical Company |
| Sanofi |
| Swedish Orphan Biovitrum AB |
| Others |
Supply & Pricing Matrix
Plasma-derived human serum albumin costs cascade through monoclonal antibody manufacturing into premium biologic pricing tiers, with batch variability penalties absorbed by developers or passed to United States payers through indication-based value agreements.
Pricing Analysis
Annual subscription-based pricing for chronic IL-1 suppression dominates the Muckle-Wells syndrome market, with differentiation anchored in amyloidosis prevention data depth and Fc-engineering sophistication. Price compression stems from off-label JAK inhibitor substitution in managed care formularies. Medicaid programs exhibit highest price sensitivity; commercial plans with rare-disease carve-outs demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for GMP-grade cell culture media mandate qualification of suppliers in both Switzerland and the United States, protecting against single-site contamination events. Manufacturing draws from Chinese recombinant protein feedstocks, German chromatography resins, and Singaporean fill-finish capacity. Tariff exposure on Chinese inputs threatens cost structures. Distribution runs through specialty pharmacy networks with cold-chain integrity protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Muckle-Wells syndrome market offers margin expansion through manufacturing scale-down in batch production and premium-tier positioning around curative gene therapy candidates.
For Market Incumbents: Extend manufacturing capacity into Basel and Boston corridors to capture gene therapy contract demand before CDMO consolidation. Secure dual-source agreements for plasma-derived inputs to defend against United States collection network volatility. Deepen relationships with Johns Hopkins and Leiden reference laboratories to lock diagnostic-coupled treatment protocols against emerging NLRP3 sequencing competitors. For New Entrants and Emerging Players: The mid-tier pricing gap between infused biologics and oral small-molecule candidates offers entry through subcutaneous biosimilar development targeting German statutory reimbursement thresholds. Target underpenetrated diagnosis in Spain and Italy where newborn screening expansion lags Northern European benchmarks. Lead with nurse training partnerships to accelerate homecare adoption curves. For Investors and Strategic Acquirers: Consolidation pressure builds where gene therapy platforms lack commercial manufacturing infrastructure and must partner or sell to scaled biologic producers. Five-to-ten year viability favors developers with both IL-1 pathway expertise and ex vivo editing capabilities. Watch EMA PRIME designation velocity as inflection signal for regulatory pathway competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands Basel and Singapore capacity to meet chronic administration demand for validated IL-1 biologics. |
| Diagnostic Partnership | Integrates NLRP3 sequencing at Johns Hopkins and Heidelberg reference laboratories to compress diagnostic timelines. |
| Regulatory Approval Pathway | Leverages FDA orphan drug exclusivity and EMA PRIME designation to accelerate novel mechanism submissions. |
| Homecare Training Program | Shifts subcutaneous administration from infusion centers to patient homes through California and Texas specialty pharmacy networks. |
| Pipeline Diversification | Adds CRISPR-based somatic correction approaches to complement chronic IL-1 suppression portfolios. |
Research Methodology
Multiple input streams — regulatory filing analysis, clinical trial database extraction, and payer policy documentation — were reconciled against primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA orphan drug designations, EMA Committee for Orphan Medicinal Products opinions, ClinicalTrials.gov protocols, and German G-BA benefit assessment records. Bottom-up patient population estimates and top-down manufacturer revenue triangulation anchored market sizing.
Data-stream reconciliation across product type, end user, delivery mode, and treatment stage dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from longitudinal tracking of diagnosed patient incidence, treatment penetration curves, and annual therapy costs across United States, German, French, and United Kingdom regulatory clusters. Forecast inputs incorporated Health Technology Assessment reimbursement decisions and specialty clinic expansion timelines.
Caveats apply where gene therapy clinical trial readouts or regulatory pathway disruptions could materially shift the outlook. Deviation in EMA PRIME designation velocity or FDA orphan exclusivity interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Pompe Disease Market