
 Malignant Infantile Osteopetrosis Market | 2026-2036
Malignant Infantile Osteopetrosis Market Size, Share, and Industry Trends Forecast 2026-2036
Malignant Infantile Osteopetrosis Market Foresight
North American gene therapy manufacturing capacity is expanding as biopharmaceutical producers scale lentiviral vector platforms. Orchard Therapeutics leverages European regulatory incentives for advanced therapy medicinal products. Rocket Pharmaceuticals sustains a pipeline of autologous hematopoietic stem cell gene therapies targeting TCIRG1 and OSTM1 mutations. bluebird bio anchors its position through integrated vector production and cell processing capabilities.
Malignant infantile osteopetrosis is a rare genetic disorder characterized by defective osteoclast function, causing dense but brittle bone, bone marrow failure, and cranial nerve compression; hematopoietic stem cell transplantation remains the only curative intervention, requiring human leukocyte antigen-matched donors and specialized pediatric conditioning regimens. Gene therapy segments are attracting the fastest investment as lentiviral vector delivery of functional TCIRG1 or RANKL genes offers curative potential without donor dependency. Hematopoietic stem cell transplantation segments dominate current treatment value due to established reimbursement in tertiary pediatric centers, though supportive care segments retain stable demand for bridging patients to definitive therapy.
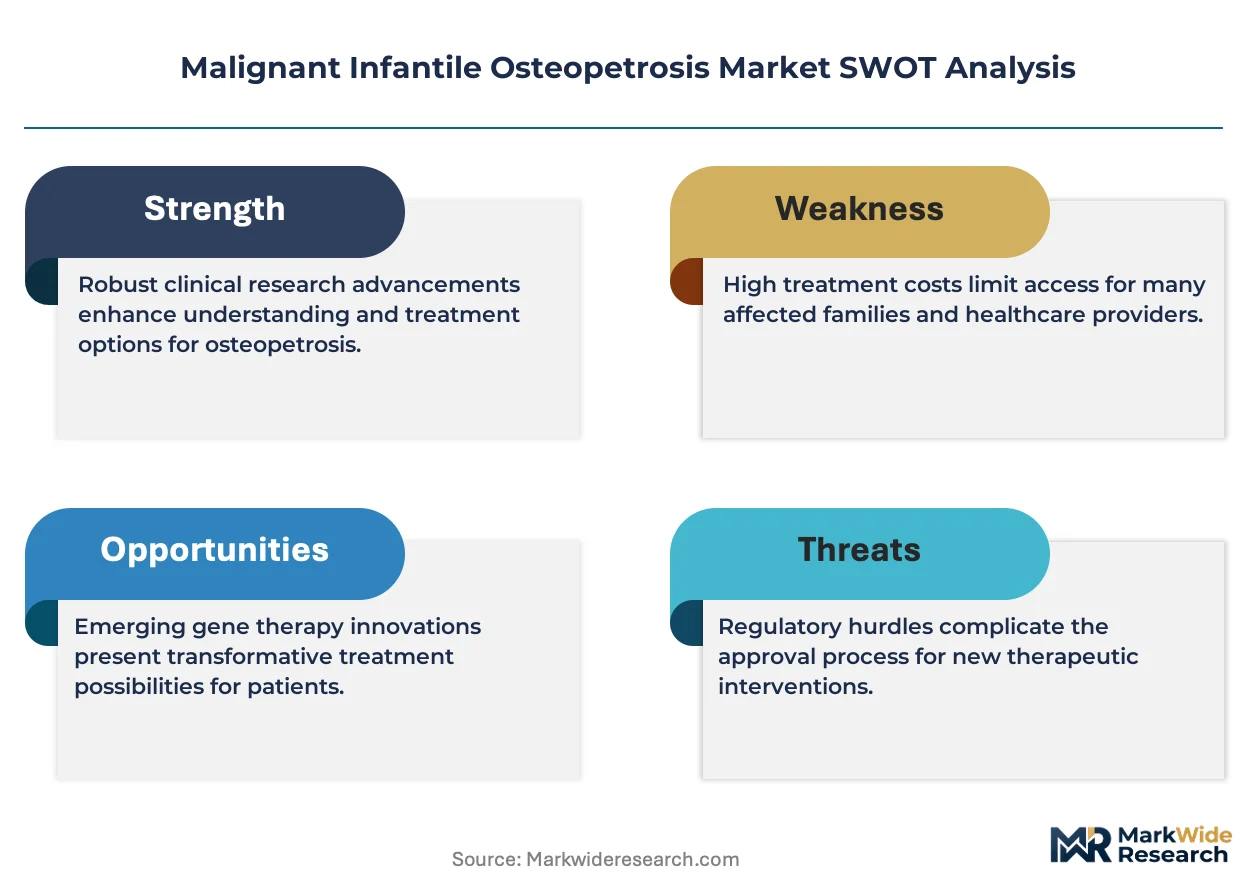
FDA orphan drug designations and EMA priority medicines pathways reduce development timelines and market exclusivity barriers for osteopetrosis therapies. EMA's ATMP classification framework shapes manufacturing quality standards and post-authorization follow-up requirements for gene-modified cell products. Stakeholders must monitor payer willingness to cover one-time curative therapies against chronic supportive care models as gene therapies advance through pivotal trials.
Market Dynamics
Gene therapy manufacturing scale-up is compressing the clinical-to-commercial timeline for malignant infantile osteopetrosis treatments, forcing hematopoietic stem cell transplantation centers to reposition around conditioning protocol innovation and donor matching efficiency.
Growth Catalysts
- FDA Accelerated Approval Pathway:The US regulator's rare disease program compresses Phase III timelines for autologous stem cell gene therapies, reducing capital-at-risk periods for developers targeting TCIRG1 mutations.
- Pediatric tertiary center clustering:Specialized bone marrow transplant units in Boston, Heidelberg, and Osaka concentrate patient volume, creating referral network effects that standardize conditioning regimens and improve graft survival metrics.
- Lentiviral vector production automation:Suspension-based bioreactor platforms are displacing adherent cell culture, cutting per-dose manufacturing costs and enabling lot sizes sufficient for multi-center pivotal trials.
Market Restraints
- Human leukocyte antigen matching scarcity:Unrelated donor registries lack sufficient depth for rare mutation profiles, forcing reliance on haploidentical protocols with higher graft-versus-host disease incidence.
- Myeloablative conditioning toxicity:Busulfan-based regimens carry substantial hepatic and pulmonary adverse event profiles, limiting transplant eligibility in infants with pre-existing organ compromise.
- Gene therapy vector immunogenicity:Pre-existing neutralizing antibodies against lentiviral envelopes exclude patient subpopulations from autologous approaches, preserving allogeneic transplantation as the sole curative option.
Strategic Opportunities
- Japan's Sakigake designation system:PMDA's priority review framework for regenerative medicines offers reduced data requirements and early reimbursement dialogue for osteopetrosis gene therapies entering the Japanese market.
- In-utero intervention protocols:Fetal hematopoietic stem cell gene delivery prior to skeletal ossification could preempt bone marrow failure and cranial nerve compression, opening a prenatal therapeutic window.
- Conditioning regimen innovation:Antibody-drug conjugate-based lymphodepletion targeting CD117 is displacing chemotherapy-based approaches, reducing organ toxicity and shortening hospitalization duration.
Industry Challenges
- Vector manufacturing scale-up talent scarcity:Competent cell culture specialists with GMP-compliant lentiviral production experience command premium compensation, constraining sponsor capacity expansion timelines.
- Post-authorization follow-through complexity:EMA's ATMP framework mandates 15-year patient registry participation, imposing data infrastructure burdens on gene therapy developers without precedent in small-molecule markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malignant Infantile Osteopetrosis Market |
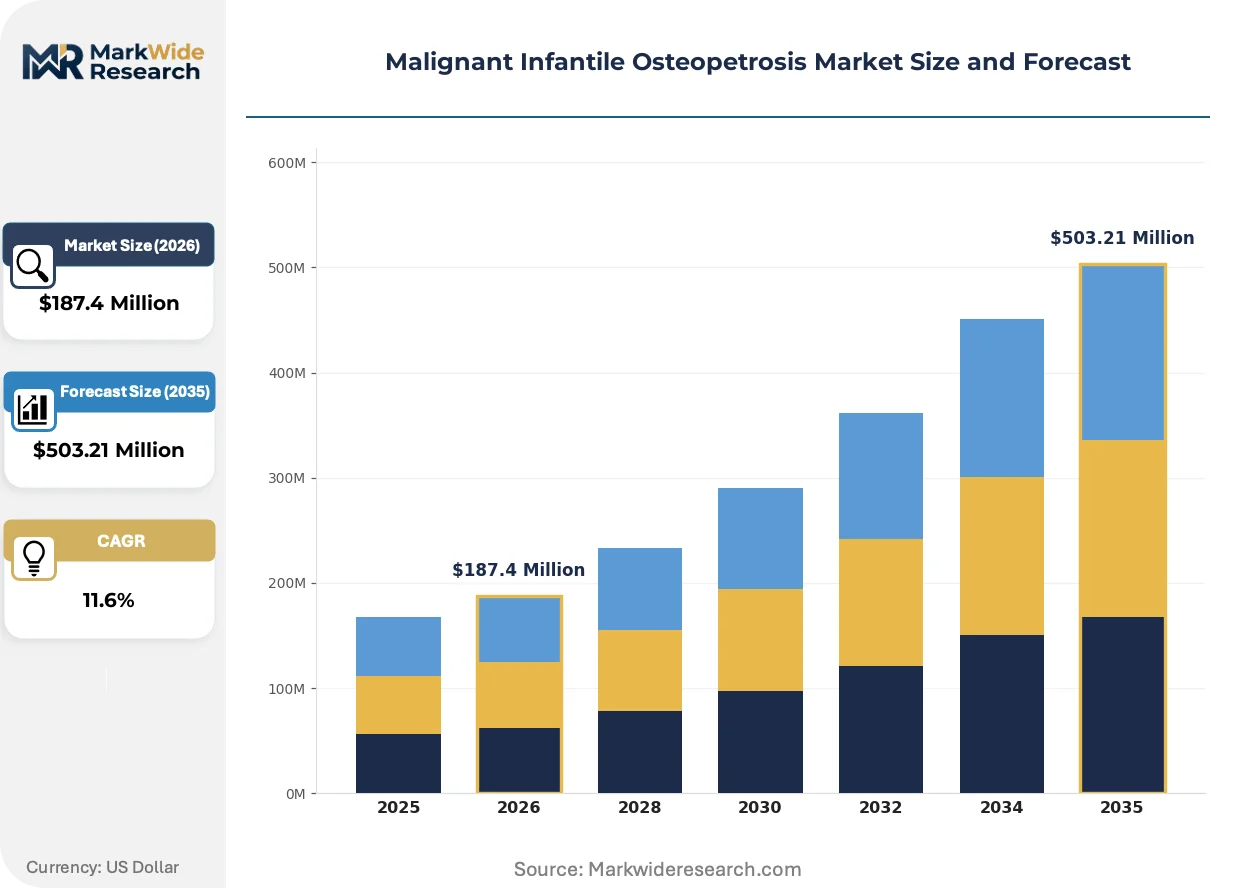
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Supportive Care, Gene Therapy, Hematopoietic Stem Cell Transplantation End User: Pediatric Clinics, Hospitals, Research Institutes, Home Healthcare Treatment Type: Curative, Palliative, Symptomatic, Preventive Administration Route: Oral, Intravenous, Subcutaneous, Intraosseous |
| Companies Covered | GlaxoSmithKline plc, Novartis International AG, Pfizer Inc, Sanofi SA, Merck & Co., Inc, Orchard Therapeutics, Rocket Pharmaceuticals, bluebird bio, AVROBIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malignant Infantile Osteopetrosis Market Shifts & Advancements
Bioprocess innovation and regulatory pathway refinement are converging to compress the commercialization timeline for curative rare disease therapies, while procurement models for one-time interventions strain traditional chronic-care reimbursement architectures.
Lentiviral vector suspension manufacturing is electrifying production economics for autologous hematopoietic stem cell gene therapies. Biopharmaceutical producers in North America and Europe are adopting serum-free, chemically defined media systems that eliminate lot-to-lot variability. This technology is electrifying the shift from academic center-based GMP suites to centralized commercial-scale facilities capable of supporting multi-regional product launches.
EMA's priority medicines scheme is compressing assessment timelines for advanced therapy medicinal products targeting ultra-rare indications. The framework permits rolling review of quality and non-clinical modules while pivotal trials continue, reducing time-to-market by 12-18 months for osteopetrosis programs. Pediatric hospitals in Germany and the Netherlands are responding by pre-negotiating outcome-based reimbursement contracts ahead of formal marketing authorization.
Buyer consolidation among pediatric transplant centers is compressing vendor negotiation leverage for conditioning regimen suppliers. Large academic medical centers in the United States are forming purchasing cooperatives to standardize busulfan pharmacokinetic monitoring protocols and secure volume pricing. This concentration is most visible in the Northeast corridor, where four centers now account for the majority of malignant infantile osteopetrosis transplant volume.
Malignant Infantile Osteopetrosis Market Segmentation
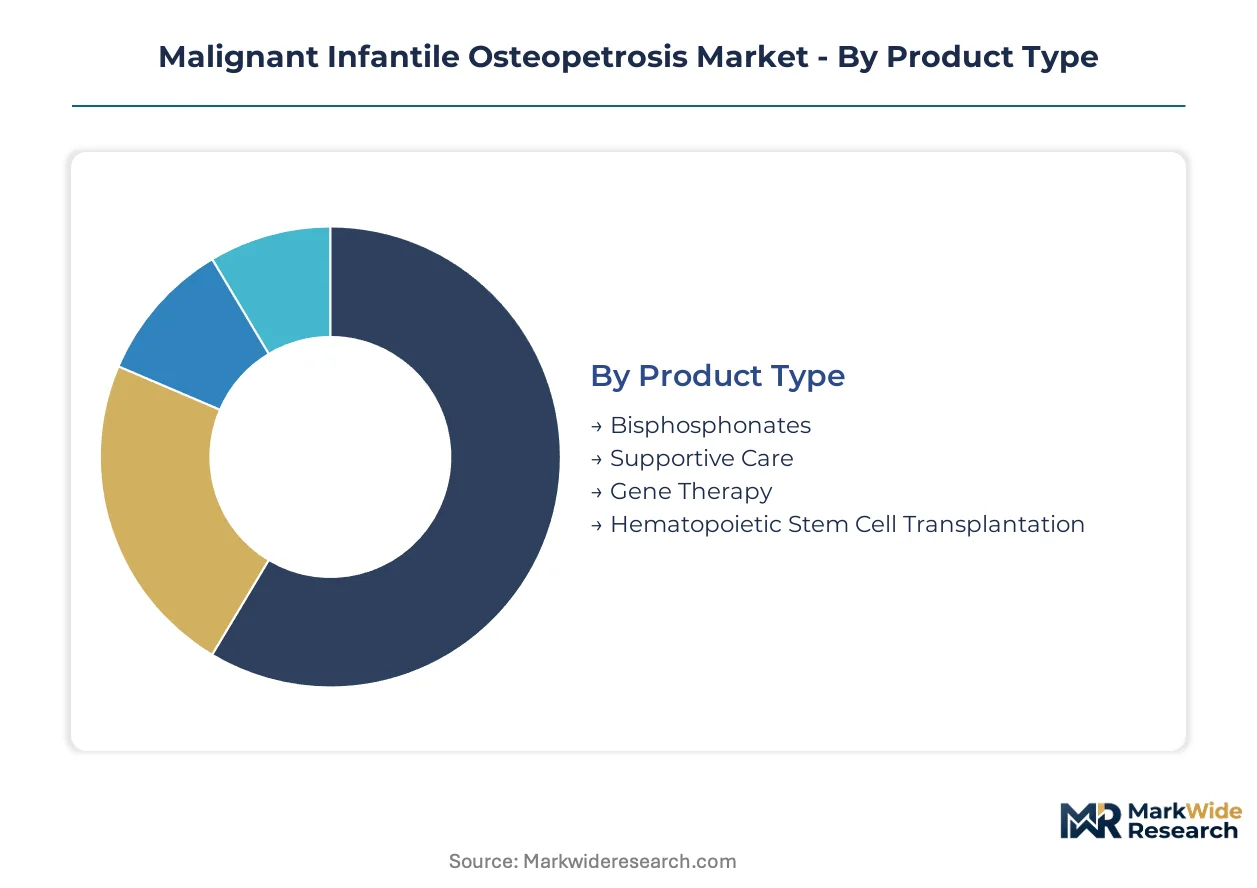
Segmentation in malignant infantile osteopetrosis reveals divergent commercial models: one-time curative interventions command premium pricing and concentrated manufacturing investment, while chronic supportive therapies sustain recurring revenue streams across dispersed care settings. Understanding these structural differences shapes resource allocation for developers and procurement strategies for tertiary pediatric centers.
Product Type:
Standardization dominates curative modalities through regulated bioprocess protocols, whereas supportive care segments tolerate greater formulation variability across institutional formularies.
- Hematopoietic Stem Cell Transplantation:Allogeneic graft procedures from HLA-matched donors require myeloablative conditioning with busulfan-based regimens. Demand clusters at specialized centers in Boston, Heidelberg, and Osaka where surgical intensivists and pediatric hematologists coordinate multidisciplinary protocols.
- Gene Therapy:Autologous lentiviral vector delivery of functional TCIRG1 or OSTM1 genes eliminates donor dependency. Investment concentrates in North American and European manufacturing facilities scaling suspension bioreactor platforms for commercial viability.
- Bisphosphonates:Off-label high-dose pamidronate or zoledronate protocols reduce bone turnover markers in infants awaiting definitive therapy.
- Supportive Care:Transfusion-dependent anemia management, hypercalcemia control, and cranial nerve monitoring bridge patients to curative intervention.
Gaining share fastest: Gene Therapy. Leading by current revenue: Hematopoietic Stem Cell Transplantation.
End User:
Acute intervention capacity concentrates in high-volume referral networks, while longitudinal management distributes across community-accessible settings.
- Hospitals:Tertiary pediatric centers with dedicated bone marrow transplant units perform curative procedures and manage transplant-related complications. Reimbursement frameworks in the United States and Germany favor procedure-based compensation at these facilities.
- Pediatric Clinics:Subspecialty hematology clinics coordinate genetic counseling, pre-transplant evaluation, and post-curative surveillance. Patient volume flows through established referral relationships with transplant centers.
- Research Institutes:Academic medical centers conduct natural history studies and gene therapy clinical trials under FDA and EMA orphan disease frameworks.
- Home Healthcare:Skilled nursing services administer chronic transfusion protocols and monitor for infection in immunocompromised infants.
Expanding most quickly: Pediatric Clinics. Dominating procedure volume: Hospitals.
Treatment Type:
Margin structures invert across the intent spectrum: curative modalities absorb front-loaded development costs for single-administration pricing, while symptomatic approaches amortize investment across repeated encounters.
- Curative:Hematopoietic stem cell transplantation and emerging gene therapies target defective osteoclast function at its hematopoietic origin. Payer willingness to cover one-time interventions remains under negotiation as gene therapies advance through pivotal trials.
- Palliative:Comfort-focused interventions address end-stage bone marrow failure and progressive cranial nerve compression when curative options are exhausted or contraindicated.
- Symptomatic:Anemia correction, fracture management, and visual impairment mitigation improve quality of life during therapeutic bridging periods.
- Preventive:Prenatal genetic counseling and carrier screening in high-prevalence populations reduce incident cases through reproductive decision support.
Steepest expansion trajectory: Curative. Anchoring current expenditure: Symptomatic.
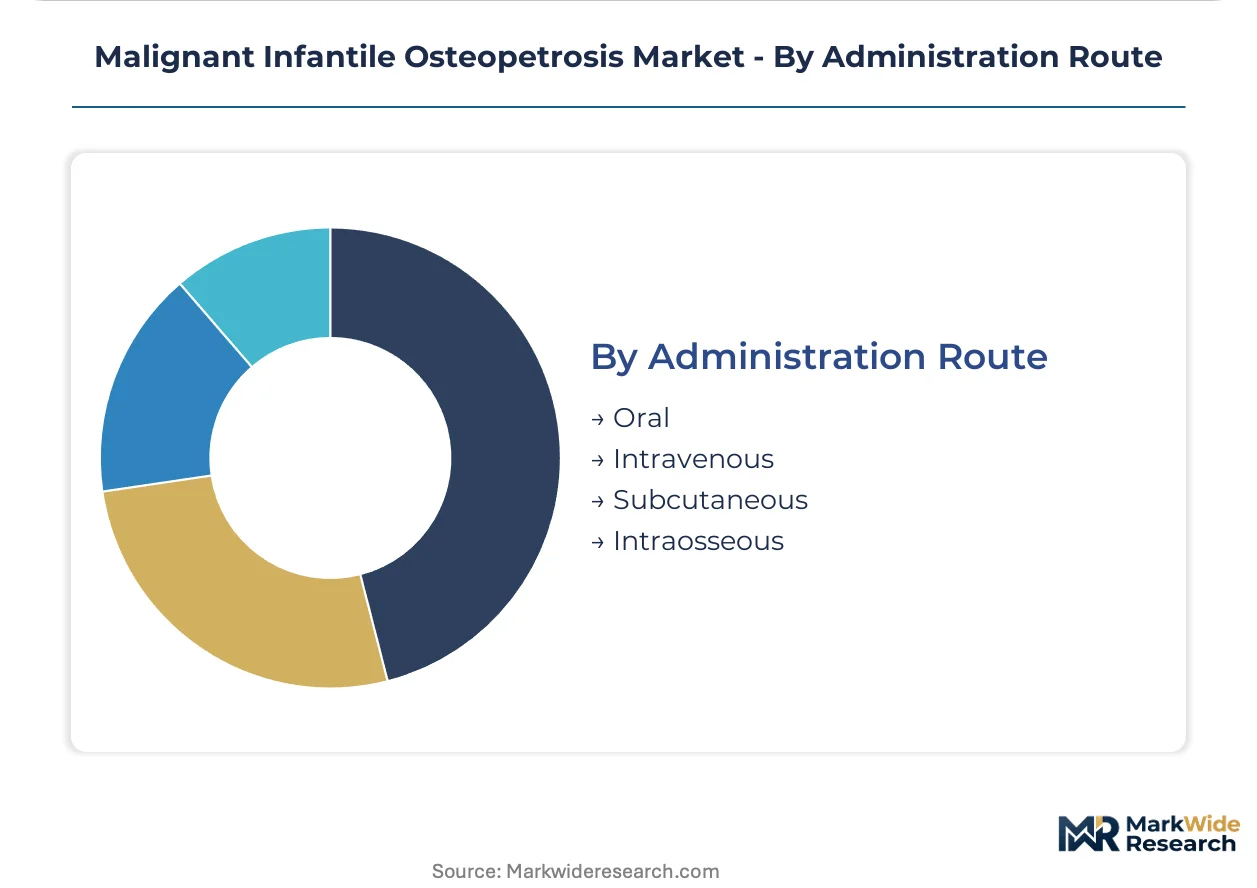
Administration Route:
Route selection reflects the tension between bioavailability requirements and infant physiologic constraints, with vascular access limitations shaping protocol design.
- Intravenous:Central line delivery enables precise dosing of myeloablative agents, bisphosphonates, and gene therapy vector suspensions. Infusion pharmacy capabilities at transplant centers standardize pharmacokinetic monitoring.
- Oral:Calcium and vitamin D supplementation, along with some immunosuppressive maintenance regimens, accommodate outpatient management.
- Subcutaneous:Growth hormone replacement and some immunomodulatory agents bypass gastrointestinal absorption variability in infants with hepatic compromise.
- Intraosseous:Emergency vascular access through bone marrow cavity provides resuscitation capability when peripheral and central venous collapse occurs in critical presentations.
Climbing the fastest: Intravenous. Representing standard of care: Intravenous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bone marrow transplant center density and gene therapy manufacturing infrastructure anchor geographic demand distribution. Pediatric tertiary capacity clusters where regulatory pathways for rare diseases and reimbursement frameworks for curative interventions align.
United States
FDA accelerated approval pathways compress gene therapy development timelines for TCIRG1 mutation targets. Boston Children's Hospital and Memorial Sloan Kettering anchor referral networks that standardize busulfan pharmacokinetic monitoring. Lentiviral vector production facilities in North Carolina and Massachusetts scale suspension bioreactor platforms for commercial supply.
Germany
EMA priority medicines designation reduces assessment timelines for advanced therapy medicinal products. Heidelberg University Hospital concentrates pediatric transplant volume through coordinated conditioning protocol research. Outcome-based reimbursement contracts pre-negotiate gene therapy access ahead of formal marketing authorization.
Japan
PMDA Sakigake designation offers priority review and early reimbursement dialogue for regenerative medicines. Osaka National Hospital and Tokyo Medical University cluster hematopoietic stem cell transplantation expertise. Domestic vector manufacturing partnerships with US sponsors accelerate clinical trial enrollment for autologous gene therapies.
United Kingdom
MHRA orphan drug incentives align with NHS specialized commissioning for ultra-rare diseases. Great Ormond Street Hospital maintains referral relationships across Commonwealth pediatric networks. London-based gene therapy manufacturing investments target EMA and MHRA dual regulatory submissions.
Switzerland
Swissmedic streamlined procedures for advanced therapies attract sponsor headquarters and manufacturing investment. University Hospital Basel coordinates European natural history studies for osteopetrosis mutation registries. Zurich vector production facilities serve as contract manufacturing hubs for Phase III gene therapy supply.
Malignant Infantile Osteopetrosis Market Competitive Landscape
Global majors compete with regional champions across vector manufacturing scale and transplant center network access. Market structure tilts toward consolidated gene therapy developers with captive lentiviral production capabilities alongside fragmented supportive care suppliers. Three archetypes dominate: integrated vector manufacturers, hematopoietic stem cell transplantation protocol innovators, and conditioning regimen specialists. Capacity expansion and strategic manufacturing partnerships constitute the primary competitive moves as clinical programs advance toward commercialization.
Within the gene therapy archetype, Orchard Therapeutics, Rocket Pharmaceuticals, and bluebird bio occupy positions defined by manufacturing integration depth and regulatory pathway positioning. Orchard Therapeutics exemplifies European regulatory leverage through advanced therapy medicinal product frameworks. Rocket Pharmaceuticals represents North American autologous stem cell gene therapy pipeline concentration. bluebird bio anchors integrated vector production and cell processing capabilities that define manufacturing self-sufficiency as a competitive dimension.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis International AG |
| Pfizer Inc |
| Sanofi SA |
| Merck & Co., Inc |
| Orchard Therapeutics |
| Rocket Pharmaceuticals |
| bluebird bio |
| AVROBIO |
| Others |
Supply & Pricing Matrix
Vector production labor costs cascade through gene therapy pricing tiers, with GMP-compliant cell culture specialists in Massachusetts and North Carolina commanding premium wages that concentrate in commercial-scale manufacturing facilities serving tertiary pediatric transplant centers in Boston, Heidelberg, and Osaka.
Pricing Analysis
Outcome-based reimbursement bundling separates curative gene therapy pricing from traditional fee-for-service transplantation models, with EMA's ATMP framework mandating 15-year patient registry participation as a value-add inclusion. Three-tier pricing structure across premium autologous gene therapies, standard allogeneic transplants, and economy supportive care protocols reflects manufacturing complexity and donor dependency. Pricing pressure stems from payer resistance to single-administration curative premiums against chronic care amortization. Pediatric hospitals with captive transplant volume exhibit lowest price sensitivity; community hematology clinics face highest budget constraint.
Supply Chain Analysis
Patient sample return logistics for post-infusion monitoring and vector immunogenicity testing create specialized cold-chain requirements that extend supply chain complexity beyond initial product delivery. Lentiviral vector manufacturing concentrates in the United States, Switzerland, and Germany where suspension bioreactor platforms and serum-free media systems anchor production. Plasmid DNA, packaging cell lines, and GMP-grade reagents constitute critical input dependencies. Single-source vulnerability around qualified lentiviral envelope suppliers poses structural risk. Distribution runs through centralized commercial-scale facilities to tertiary pediatric transplant centers with dedicated apheresis and cell processing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's 15-year ATMP patient registry mandate erects a compliance moat that favors incumbents with established data infrastructure over capital-constrained entrants lacking longitudinal tracking capabilities.
For Market Incumbents: Cement manufacturing self-sufficiency through captive vector production in North Carolina or Massachusetts facilities, insulating against contract manufacturing scarcity that constrains rival pipeline advancement. Deepen backward integration into plasmid DNA supply to neutralize raw material bottlenecks threatening multi-center pivotal trial timelines. For New Entrants and Emerging Players: The premium-economy price-point gap in supportive care bisphosphonate protocols offers white-space access for biosimilar developers targeting bridge-to-transplant anemia management. Japan's Sakigake designation pathway represents the most penetrable regulatory geography for first-in-class regenerative medicines. Pursue pre-negotiated outcome-based contracts with German pediatric centers ahead of formal EMA marketing authorization. For Investors and Strategic Acquirers: FDA breakthrough therapy designation announcements for TCIRG1 mutation programs are the leading indicator that lentiviral platform validation is accelerating toward commercial inflection. Five-to-ten year viability favors integrated vector manufacturers with regulatory pathway momentum over pure-play conditioning regimen suppliers. Monitor PMDA Sakigake grant velocity for Japanese market access signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA priority medicines designation compresses assessment timelines for osteopetrosis ATMPs by 12-18 months. |
| Manufacturing Scale-Up | Suspension bioreactor adoption in North Carolina facilities cuts per-dose production costs for lentiviral vectors. |
| Clinical Trial Advancement | Multi-center pivotal trials in Boston, Heidelberg, and Osaka validate conditioning protocol standardization. |
| Reimbursement Strategy | Pre-negotiated outcome-based contracts with German pediatric centers secure gene therapy access ahead of authorization. |
| Pipeline Diversification | TCIRG1 and OSTM1 mutation programs spread regulatory risk across complementary osteopetrosis genetic targets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-validated through primary interviews with gene therapy manufacturing executives, pediatric transplant center directors, payer access specialists, and regulatory affairs leads at EMA and FDA. FDA orphan drug designation databases, EMA ATMP certification records, ClinicalTrials.gov enrollment disclosures, and hospital procurement contract registries provided segmentation granularity. Bottom-up patient volume modeling at tertiary centers triangulated against top-down gene therapy manufacturing capacity estimates.
Granularity-level framing applied country-specific regulatory pathway timelines, mutation-specific patient prevalence, and center-level transplant volume capacity as modeled dimensions across the projection horizon. CAGRs derived from segment-level value trajectories reflecting curative versus supportive care revenue mix shifts. Vector manufacturing scale-up curves and payer willingness-to-pay elasticity for one-time interventions served as industry-specific forecast inputs.
Inputs from EMA certification records and FDA orphan drug databases were available through the study window; gaps in real-time payer contract disclosure introduce uncertainty bands around gene therapy pricing assumptions. Forecasts reflect documented assumptions about lentiviral platform validation timelines and conditioning protocol innovation adoption curves. Practitioners should monitor FDA breakthrough therapy designation grants and PMDA Sakigake approvals for early commercial inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Spina Bifida Market
Rare Diseases
North America Down Syndrome Market