
 Creutzfeldt-Jakob Disease (CJD) Market | 2026-2036
Creutzfeldt-Jakob Disease (CJD) Market Size, Share, and Industry Trends Forecast 2026-2036
Creutzfeldt-Jakob Disease (CJD) Market Outlook
Recombinant protein assays are rebalancing diagnostic economics as laboratories shift away from animal-based bioassays. F. Hoffmann-La Roche leverages its molecular diagnostics infrastructure to anchor European hospital networks. Ionis Pharmaceuticals, Inc. specializes in antisense oligonucleotide platforms that target prion protein suppression. QPS Holdings, LLC operates contract research capabilities that sustain preclinical validation pipelines for emerging drug candidates.
Creutzfeldt-Jakob Disease constitutes a fatal neurodegenerative disorder caused by misfolded prion proteins that induce progressive spongiform encephalopathy, with diagnostic confirmation requiring cerebrospinal fluid 14-3-3 protein testing, RT-QuIC assays, or neuropathological examination. Its primary commercial purpose centers on enabling rapid differential diagnosis against other dementias and supporting clinical trial enrollment for disease-modifying therapies. Diagnostic Methods command the dominant revenue share due to mandatory confirmatory testing protocols, while Experimental Therapies represent the fastest-expanding segment as antisense and immunotherapy candidates advance through regulatory pathways. Supportive Care occupies a stable margin pool tied to long-term palliative management in tertiary neurology centers.
The FDA maintains orphan drug designation pathways that compress development timelines for prion disease therapeutics, while the EMA applies similar incentives under its orphan medicinal products framework. The NIH and CDC coordinate surveillance protocols that standardize diagnostic reporting and shape laboratory accreditation requirements. Stakeholders must monitor biomarker qualification progress and regulatory precedent for accelerated approval in ultra-rare neurodegenerative conditions.
Market Dynamics
Orphan drug incentives from the FDA and EMA are compressing therapeutic development timelines while recombinant protein assays restructure diagnostic economics away from animal-based bioassays.
Growth Catalysts
- Orphan Drug Designation:The FDA's orphan drug pathway accelerates regulatory review for prion disease therapeutics, reducing time-to-market for experimental antisense platforms.
- Academic Medical Hub Clustering:Specialized neurology centers concentrate around research universities in the United States, creating dense referral networks that streamline clinical trial enrollment.
- RT-QuIC Assay Adoption:Real-time quaking-induced conversion technology is displacing slower immunohistochemistry methods in hospital laboratories across tertiary care networks.
Market Restraints
- Ultra-Rare Disease Prevalence:CJD's incidence of approximately one case per million population annually constrains commercial addressable market calculations for therapeutic developers.
- Cerebrospinal Fluid Collection Requirements:Invasive lumbar puncture procedures for 14-3-3 protein and RT-QuIC testing limit screening penetration in outpatient settings.
- Prion Protein Structural Complexity:The conformational variability of pathogenic prion strains complicates universal therapeutic targeting and biomarker standardization.
Strategic Opportunities
- Blood-Based Biomarker Development:Plasma prion seeding amplification assays could enable non-invasive population screening and expand addressable testing volume.
- EMA Priority Medicines Scheme:European accelerated assessment pathways for prion disease therapeutics offer reduced fee structures and enhanced scientific advice.
- Antisense-Immunotherapy Convergence:Combination platforms pairing prion protein suppression with monoclonal antibody clearance represent untapped mechanistic synergy.
Industry Challenges
- Neuropathology Specialist Scarcity:Diagnostic confirmation requires board-certified neuropathologists with prion disease expertise, creating bottleneck capacity at referral centers.
- Biosafety Level 3 Infrastructure:Prion research and manufacturing demand specialized containment facilities that carry capital intensity exceeding standard biologics production.
- Biomarker Qualification Pathways:FDA and EMA evidentiary requirements for surrogate endpoints in ultra-rare neurodegenerative conditions remain underdeveloped, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creutzfeldt-Jakob Disease (CJD) Market |
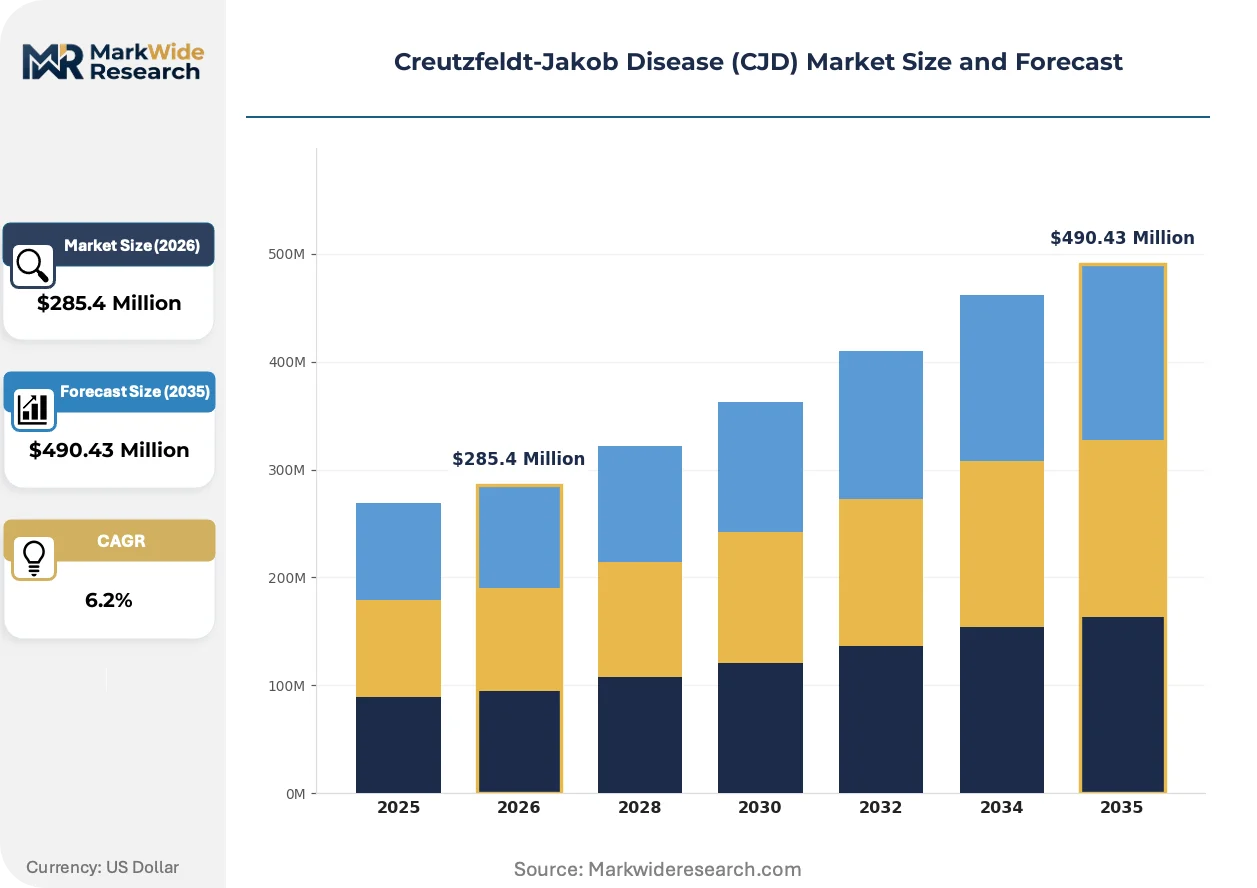
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Methods, Symptomatic Treatments, Experimental Therapies, Supportive Care End User: Hospitals, Research Institutes, Specialty Clinics, Home Care Application: Clinical Diagnosis, Research Studies, Patient Management, Public Health Delivery Mode: Inpatient, Outpatient, Telemedicine, Emergency Services |
| Companies Covered | F. Hoffmann-La Roche, Becton, Dickinson and Company, Ionis Pharmaceuticals, Inc., QPS Holdings, LLC, Roche Diagnostics International, Pfizer Inc., Mylan N.V., GlaxoSmithKline, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creutzfeldt-Jakob Disease (CJD) Market Strategic Shifts
Diagnostic automation and therapeutic modality diversification are converging to reshape competitive positioning across the prion disease landscape.
RT-QuIC platform miniaturization is rewriting laboratory workflow economics. Hospital-based diagnostic programs in the United States and Germany are adopting benchtop instruments that reduce assay turnaround from days to hours. This compression is enabling same-day differential diagnosis against rapidly progressive dementias and accelerating clinical trial screening throughput.
The FDA's Breakthrough Therapy designation pathway is creating regulatory precedent for prion disease therapeutics. Antisense oligonucleotide candidates targeting prion protein suppression receive intensive FDA guidance engagement, compressing Phase 1 to Phase 2 transition timelines. European developers are responding by pre-submission alignment with EMA scientific advice procedures.
Academic medical centers are consolidating prion disease care into multidisciplinary encephalopathy units. Tertiary neurology centers in the United States, United Kingdom, and Japan are unifying diagnostic testing, genetic counseling, and experimental therapy access under single institutional umbrellas. This concentration is displacing fragmented referral patterns and creating preferred site networks for sponsor-sponsored trials.
Creutzfeldt-Jakob Disease (CJD) Market Segmentation
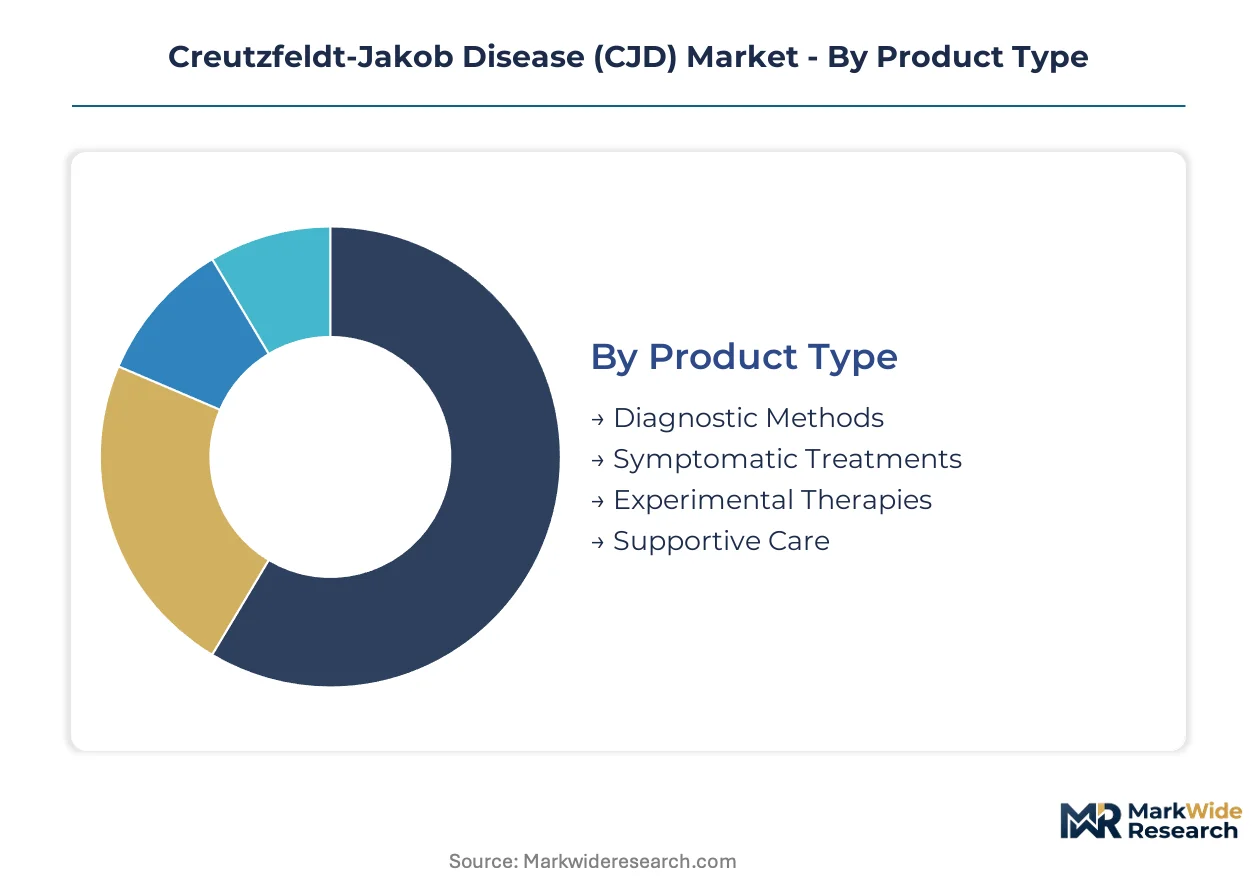
Prion disease market segmentation reveals how diagnostic infrastructure, therapeutic modality, and care setting intersect to determine commercial opportunity. Each dimension carries distinct margin profiles and regulatory pathways that shape stakeholder investment priorities.
Product Type:
Supply concentration in molecular diagnostics equipment anchors revenue distribution across this category.
- Diagnostic Methods:RT-QuIC assays, cerebrospinal fluid 14-3-3 protein testing, and neuropathological examination constitute mandatory confirmatory protocols. United States tertiary neurology centers drive installed base expansion as academic medical hubs deepen investment in rapid differential diagnosis capabilities.
- Experimental Therapies:Antisense oligonucleotide platforms and immunotherapy candidates target prion protein suppression or clearance. FDA orphan drug designation accelerates regulatory timelines, drawing venture capital into mechanism-of-concept validation despite ultra-rare disease prevalence constraints.
- Symptomatic Treatments:Pharmacological management of myoclonus, psychiatric symptoms, and pain in CJD patients.
- Supportive Care:Palliative services including nutritional support, mobility assistance, and end-of-life coordination in specialized neurology units.
Diagnostic Methods absorb the bulk of installed capacity; Experimental Therapies are expanding most quickly.
End User:
Cost tier stratification separates high-complexity institutional purchasers from dispersed lower-acuity settings.
- Hospitals:Tertiary care centers with embedded prion disease units perform confirmatory testing and manage experimental therapy protocols. Germany and Japan maintain dense concentrations of Biosafety Level 3-capable facilities that constrain competitor entry.
- Research Institutes:Academic and government laboratories conduct biomarker qualification studies and preclinical therapeutic validation. NIH and CDC surveillance coordination in the United States standardizes sample collection protocols across multi-site consortia.
- Specialty Clinics:Neurology-focused outpatient centers handling initial suspicion and referral coordination.
- Home Care:Community-based providers delivering terminal-stage nursing and family support services.
Hospitals command the premium pricing tier; Research Institutes show steepest investment trajectory as biomarker programs scale.
Application:
Volume concentration in differential diagnosis against rapidly progressive dementias shapes demand patterns.
- Clinical Diagnosis:Definitive CJD confirmation through CSF analysis, genetic testing for familial forms, and neuropathological examination. United Kingdom National Health Service referral networks demonstrate how centralized suspicion-to-confirmation pathways compress time-to-diagnosis.
- Research Studies:Natural history cohorts, biomarker discovery programs, and therapeutic trial infrastructure. EMA scientific advice procedures and FDA breakthrough therapy designations create dual-track regulatory engagement for sponsors.
- Patient Management:Coordinated care across neurology, psychiatry, and palliative specialties.
- Public Health:Variant CJD surveillance, blood supply screening, and iatrogenic transmission prevention protocols.
Clinical Diagnosis generates the highest procedure volume; Research Studies demonstrate the fastest protocol innovation cycle.
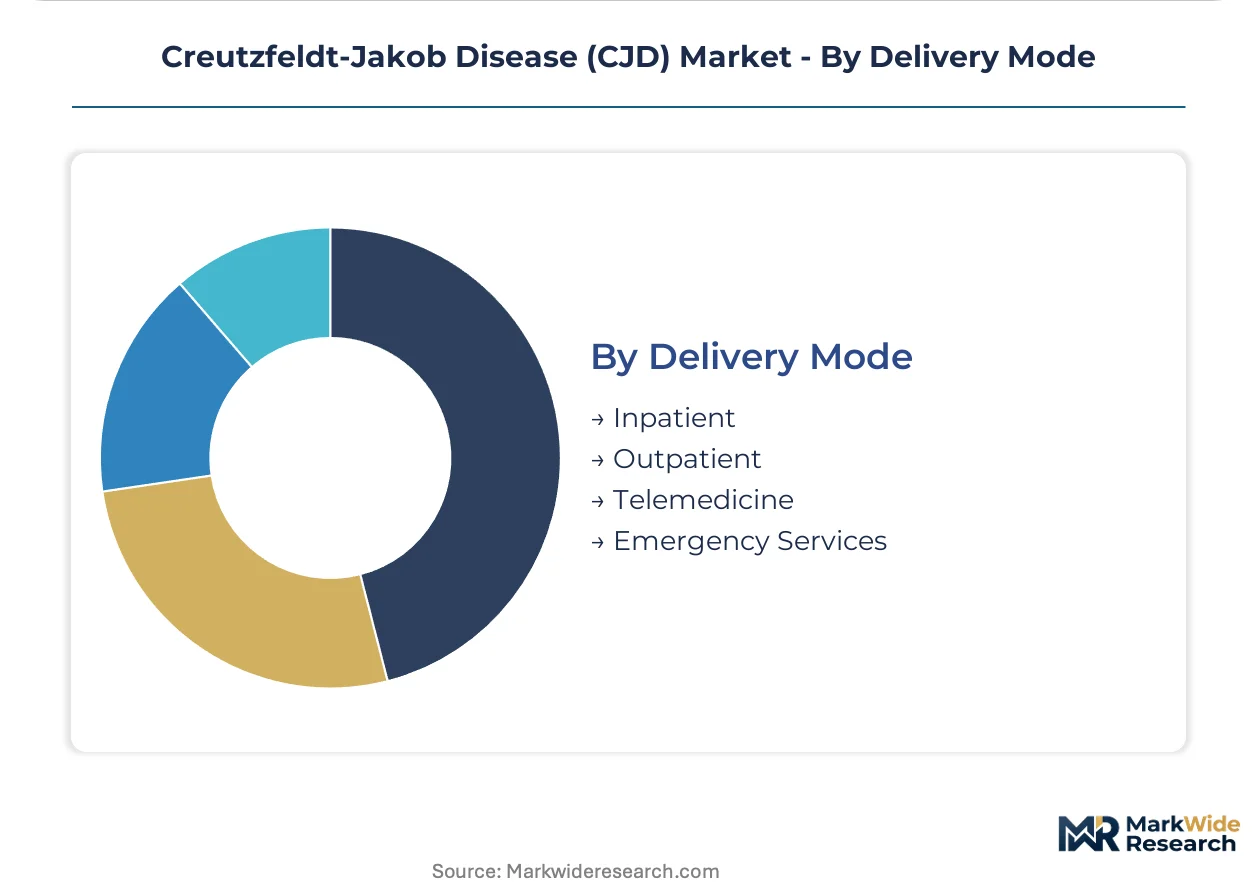
Delivery Mode:
Customer type segmentation distinguishes acute intervention requirements from longitudinal monitoring relationships.
- Inpatient:Acute hospitalization for rapid neurological decline, diagnostic workup, and experimental therapy administration. Swissmedic and TGA regulatory alignment on prion disease therapeutic trials enables multi-site recruitment across Switzerland and Australia.
- Outpatient:Scheduled specialist consultations for disease monitoring and family genetic counseling.
- Telemedicine:Remote neurological assessment and care coordination for dispersed patient populations.
- Emergency Services:Initial presentation management for acute neuropsychiatric deterioration requiring differential diagnosis.
Inpatient settings concentrate high-value procedures; Telemedicine is gaining share fastest as diagnostic suspicion networks extend beyond academic hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for CJD diagnostics and therapeutics concentrates in countries with dense academic medical center networks and active prion disease surveillance programs. The United States, Germany, Japan, United Kingdom, and Switzerland host the majority of specialized neurology hubs and Biosafety Level 3 research infrastructure.
United States
Academic medical centers in Boston, Baltimore, and San Francisco anchor diagnostic referral networks for rapidly progressive dementias. The FDA maintains orphan drug designation pathways that compress development timelines for prion disease therapeutics. NIH surveillance coordination through the National Prion Disease Pathology Surveillance Center standardizes diagnostic reporting across 50 states.
Germany
Tertiary neurology centers in Munich, Heidelberg, and Berlin maintain Europe's densest concentration of RT-QuIC testing capacity. The Paul-Ehrlich-Institute regulates diagnostic assay validation under national medical device frameworks. Bavarian research institutes coordinate with Swissmedic-aligned trials across the German-Swiss border region.
Japan
PMDA orphan drug incentives accelerate antisense therapeutic development timelines for domestic biotech sponsors. The National Center of Neurology and Psychiatry in Tokyo anchors prion disease diagnostic networks across the Kanto region. Osaka-based medical device distributors import European RT-QuIC platforms for hospital laboratory installation.
United Kingdom
NHS England's National Prion Clinic in London centralizes suspicion-to-confirmation diagnostic pathways. The Medicines and Healthcare products Regulatory Agency applies EMA orphan medicinal products frameworks for accelerated therapeutic assessment. Edinburgh neuropathology units provide diagnostic confirmation services for Scottish referral networks.
Switzerland
Swissmedic regulates multi-site prion disease therapeutic trials enabling recruitment across Zurich and Geneva academic hospitals. The Swiss National Reference Centre for Prion Diseases coordinates diagnostic standardization with EU surveillance networks. Basel-based molecular diagnostics infrastructure supports both clinical testing and pharmaceutical research partnerships.
Creutzfeldt-Jakob Disease (CJD) Market Competitive Environment
Strategic partnerships between diagnostic equipment manufacturers and academic medical centers dominate the current landscape. Market structure consolidates around three tiers: multinational molecular diagnostics conglomerates, specialized antisense therapeutic developers, and contract research organizations with prion disease expertise. Two strategic archetypes predominate: platform licensors leveraging existing hospital installed bases, and mechanism-focused biotechs advancing disease-modifying candidates. Competitive intensity centers on RT-QuIC assay automation and orphan drug designation acquisition.
Within the molecular diagnostics tier, F. Hoffmann-La Roche and Roche Diagnostics International exemplify platform leverage strategies, anchoring European hospital networks through integrated instrument-reagent systems. Among therapeutic developers, Ionis Pharmaceuticals, Inc. occupies a position representing antisense oligonucleotide specialization, while QPS Holdings, LLC sits within the contract research archetype sustaining preclinical validation pipelines. Becton, Dickinson and Company represents the diversified medical technology conglomerate model with diagnostic distribution reach.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Becton, Dickinson and Company |
| Ionis Pharmaceuticals, Inc. |
| QPS Holdings, LLC |
| Roche Diagnostics International |
| Pfizer Inc. |
| Mylan N.V. |
| GlaxoSmithKline |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Hospital laboratory procurement consolidation around automated RT-QuIC platforms is forcing diagnostic equipment manufacturers to bundle reagent contracts with instrument placement, compressing per-test margins while locking in long-term revenue streams. This buyer-driven consolidation reshapes supply chain economics toward captive consumable models.
Pricing Analysis
Volume concentration in hospital-based testing separates high-throughput tertiary centers from lower-volume specialty clinics. Three-tier pricing structure across premium, standard, and economy levels aligns with Biosafety Level 3 certification tiers and assay automation capabilities. Pricing pressure stems from academic medical hub procurement coalitions negotiating enterprise-wide instrument contracts. Research institutes demonstrate lowest price sensitivity due to grant-funded experimental protocols, while community hospitals face tightest budget constraints.
Supply Chain Analysis
FDA and EMA diagnostic assay qualification requirements gate entry for RT-QuIC platform manufacturers, limiting approved suppliers to Roche Diagnostics International and select specialized vendors. Component sourcing draws from Germany for precision optics, Japan for microfluidic consumables, and the United States for recombinant protein reagents. Single-source vulnerability concentrates in prion protein reference material suppliers. Distribution runs through hospital GPO contracts and direct academic medical center relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosafety Level 3 manufacturing capacity scarcity constrains therapeutic developer entry, propping pricing power for incumbent diagnostic platform holders and contract research organizations with certified containment infrastructure.
For Market Incumbents: Acquire antisense oligonucleotide manufacturing capabilities to capture vertical integration synergies as prion protein suppression candidates advance. Ionis Pharmaceuticals platform specialization threatens standalone diagnostic equipment margins; counter by embedding RT-QuIC instruments within multidisciplinary encephalopathy units. Deepen reagent contract lock-in through expedited assay turnaround guarantees. For New Entrants and Emerging Players: Academic medical center partnerships offer the most penetrable channel for blood-based biomarker assay commercialization. Target telemedicine-enabled diagnostic suspicion networks extending beyond established neurology hubs. Pursue EMA Priority Medicines Scheme pre-submission alignment to compress European market entry timelines. For Investors and Strategic Acquirers: The window for entry favors contract research organizations with prion disease expertise and Biosafety Level 3 infrastructure. Long-term viability hinges on biomarker qualification progress enabling surrogate endpoint pathways. Watch FDA breakthrough therapy designation precedent for prion disease therapeutics as the signal for regulatory inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Acquisition | FDA pathway compression accelerates antisense candidate timelines for prion protein suppression platforms. |
| RT-QuIC Platform Miniaturization | Benchtop automation reduces hospital laboratory assay turnaround from days to hours. |
| Academic Medical Center Partnership | Multidisciplinary encephalopathy unit consolidation creates preferred clinical trial site networks. |
| Blood-Based Biomarker Development | Plasma prion seeding amplification assays enable non-invasive population screening expansion. |
| Biosafety Level 3 Capacity Expansion | Specialized containment infrastructure scarcity constrains therapeutic manufacturing competitor entry. |
Study Parameters
Independent corroboration across hospital laboratory directors, diagnostic equipment procurement managers, and prion disease therapeutic development executives underwrites the qualitative findings. Primary fieldwork engaged regulatory affairs specialists at FDA and EMA, neuropathologists at National Prion Disease Pathology Surveillance Center, and contract research organization operations leads. Secondary validation drew from FDA orphan drug designation filings, EMA scientific advice procedures, ClinicalTrials.gov prion disease protocols, and hospital GPO contract databases. Bottom-up installed base modeling triangulated against top-down addressable patient population estimates.
Rate-of-change decomposition separated diagnostic procedure volume expansion from experimental therapy development timeline compression across the analysis window. Segmentation modeling incorporated product type tiers, end-user cost stratification, application purpose clusters, and delivery mode settings. CAGRs derived from logistic diffusion curves for assay adoption and pipeline probability-adjusted net present values for therapeutic candidates. Forecast inputs included academic medical hub concentration metrics and biomarker qualification pathway progression indicators.
Caveats apply where blood-based biomarker validation failure or prion protein structural complexity breakthroughs could materially shift the outlook. Forecasts reflect assumptions about regulatory precedent continuity and diagnostic reimbursement stability. A model refresh is warranted upon material change in FDA accelerated approval framework for ultra-rare neurodegenerative conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Pure Red Cell Aplasia Market