
 Mesenchymal Stem Cells Market | 2026-2036
Mesenchymal Stem Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Mesenchymal Stem Cells Market Intelligence
The bundling of characterized mesenchymal stem cell lines with validated culture media and differentiation kits is hardening buyer preferences for complete workflow solutions. This move away from component sales benefits integrated suppliers. Lonza Group AG leverages its extensive manufacturing capabilities to offer GMP-grade cells and media systems. STEMCELL Technologies Inc. differentiates through its comprehensive portfolio supporting the entire research workflow, from isolation to analysis.
Mesenchymal stem cells are multipotent stromal cells capable of differentiating into various cell lineages, including osteoblasts, chondrocytes, and adipocytes. Their primary function in medicine is to facilitate tissue repair and modulate immune responses in regenerative therapies. Bone marrow-derived MSCs represent a mature product segment, though umbilical cord-derived cells are gaining share due to non-invasive collection. The orthopedics therapy area commands a significant portion of the market, driven by applications in cartilage and bone repair.
Regulatory frameworks from the US FDA and Europe's EMA dictate stringent requirements for clinical-grade MSC manufacturing and therapeutic applications. In parallel, Japan's PMDA has established an accelerated approval pathway for regenerative medicine products, influencing development strategies. These agencies' oversight of cell sourcing, processing, and characterization directly shapes market access and product development costs. Navigating the evolving standards for cell therapy classification and approval remains a critical determinant of commercial success.
Market Dynamics
The market's central dynamic is the tension between the push for standardized, complete workflow solutions for research and the complex, high-cost regulatory pathway for clinical applications, which demands extensive validation and bespoke manufacturing processes for therapeutic use.
Growth Catalysts
- Advanced Cryopreservation:Improvements in vitrification and controlled-rate freezing technologies are enhancing the post-thaw viability and functional stability of MSCs, expanding their availability for on-demand therapeutic and research applications.
- Orthopedic Applications:The expanding use of MSCs in orthopedics for cartilage regeneration, bone fusion, and treating osteoarthritis provides a significant and clinically validated demand stream, particularly for bone marrow-derived cells.
- Regulatory Streamlining:Japan's PMDA has established an accelerated approval pathway for regenerative medicine products, creating a powerful incentive for developers to prioritize this market and shortening time-to-revenue for new therapies.
Market Restraints
- High Manufacturing Costs:The expense associated with GMP-compliant cell culture media, growth factors, and cleanroom facilities for producing clinical-grade MSCs creates a significant financial barrier for market entry and patient access.
- Stringent Regulatory Hurdles:Navigating the complex and lengthy approval processes mandated by agencies like the US FDA and Europe's EMA for cell-based therapies remains a primary constraint on commercialization timelines.
- Functional Inconsistency:Batch-to-batch variability in cell potency and differentiation capacity, stemming from donor differences and manufacturing processes, presents a major technical challenge for achieving consistent therapeutic outcomes.
Strategic Opportunities
- Allogeneic "Off-the-Shelf" Therapies:Developing universal, non-patient-specific MSC therapies offers a path to overcome the logistical and cost limitations of autologous treatments, enabling scalable production and immediate availability.
- Exosome-Based Therapeutics:Isolating and utilizing the exosomes secreted by MSCs, which contain their therapeutic signaling molecules, presents an opportunity for cell-free regenerative medicine with a potentially simpler regulatory and manufacturing profile.
- Gene-Editing Enhancements:The convergence of MSC technology with CRISPR-based gene editing tools opens possibilities for creating cells with enhanced therapeutic properties, targeted functions, or improved safety profiles for specific diseases.
Industry Challenges
- Potency Assay Standardization:A lack of universally accepted, standardized assays to measure the therapeutic potency of MSC products complicates regulatory submissions and makes it difficult to compare results across different clinical studies.
- Scalable Bioprocessing:Transitioning from manual, flask-based culture methods to automated, large-scale bioreactor systems for commercial production presents a significant technical and capital investment challenge for many developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesenchymal Stem Cells Market |
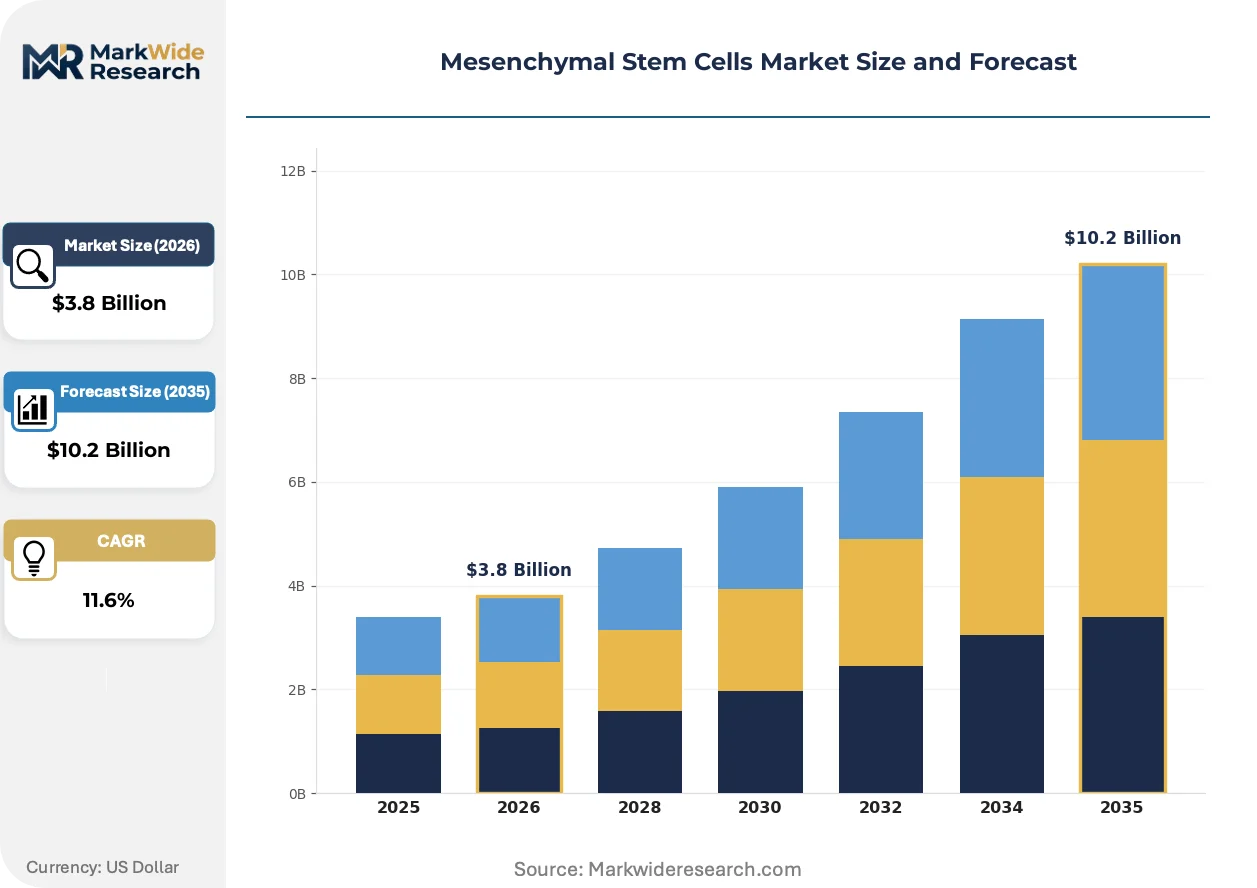
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Marrow-Derived, Adipose Tissue-Derived, Umbilical Cord-Derived, Dental Pulp-Derived Therapy Area: Orthopedics, Neurology, Cardiology, Dermatology, Immunology End User: Research Institutes, Biopharmaceutical Firms, Contract Research Organizations, Academic Labs Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intra-articular |
| Companies Covered | Thermo Fisher Scientific Inc, Merck KGaA, STEMCELL Technologies Inc, Axol Bioscience Ltd, Lonza Group AG, Cell Applications Inc, PromoCell GmbH, Cyagen Biosciences Inc, Celprogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesenchymal Stem Cells Market Strategic Shifts & Innovations
The market is shifting from a focus on basic cell biology to the industrialization of cell therapy. This evolution is driven by technologies that enable scale and consistency, regulatory frameworks that define the path to commercialization, and buyer behavior that prioritizes efficiency and reproducibility.
Automated Bioreactor Systems
Automated bioreactor systems provide a controlled environment for large-scale MSC expansion, ensuring consistency and reducing manual labor. Biopharmaceutical firms and contract development and manufacturing organizations are adopting these systems to transition from research-scale to commercial-grade production. This technology is rewriting the economics of cell therapy by making the manufacturing of allogeneic treatments commercially viable at scale.
Advanced Therapy Medicinal Product (ATMP) Framework
Europe's classification of many cell-based products as Advanced Therapy Medicinal Products (ATMPs) under the EMA mandates rigorous quality, safety, and efficacy standards. This regulation increases the compliance burden and development costs for therapies targeting the European market. Developers of allogeneic MSC products are most affected, redesigning their manufacturing processes and quality control systems to align with the stringent ATMP guidelines.
Workflow Solution Bundling
Research labs are increasingly purchasing complete, pre-validated workflow solutions rather than sourcing individual components. This behavioral shift favors suppliers who bundle characterized cell lines with optimized culture media, reagents, and differentiation kits, displacing vendors of standalone products. The trend is most visible in competitive academic research centers in the United States and Germany, where workflow efficiency and data reproducibility are paramount.
Mesenchymal Stem Cells Market Segmentation
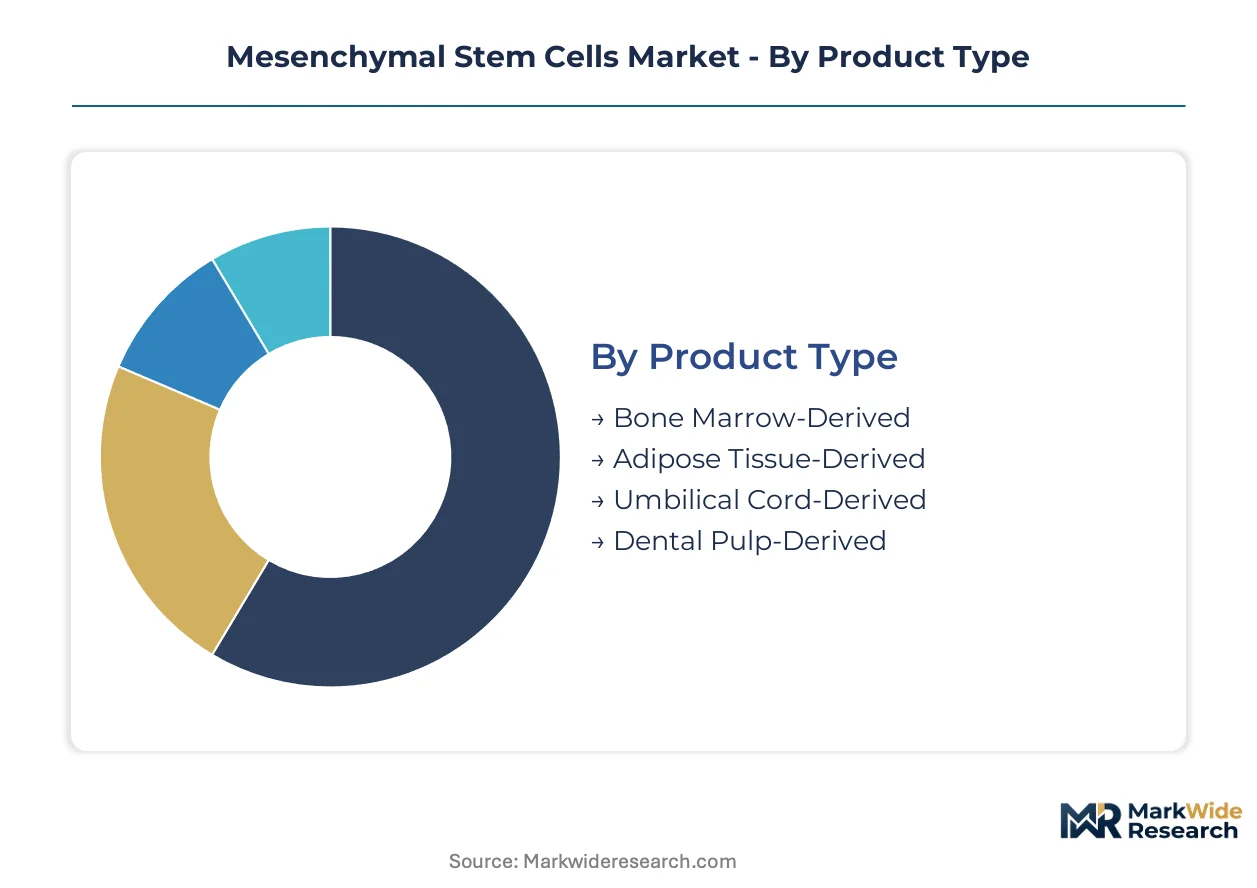
The segmentation of the mesenchymal stem cells market provides a structured view of its diverse components, highlighting the specific product types, therapeutic applications, end-user profiles, and delivery methods that define its commercial landscape. Understanding these segments is crucial for strategic planning within the regenerative medicine sector.
Product Type:
The market's product type segmentation highlights the varying degrees of processing and integration required for different mesenchymal stem cell sources.
- Bone Marrow-Derived:These MSCs are harvested from bone marrow aspirates, representing a well-established and clinically advanced source for cellular therapies. Demand concentrates in orthopedic applications across the United States, driven by extensive research and regulatory acceptance for tissue regeneration.
- Umbilical Cord-Derived:Sourced from umbilical cord tissue, these MSCs offer a non-invasive collection method and high proliferative capacity, making them attractive for allogeneic therapeutic development. Biopharmaceutical firms in Japan are increasingly investing in this segment due to favorable regulatory pathways and ease of scalability.
- Adipose Tissue-Derived:These cells are readily isolated from fat tissue, offering an abundant source for regenerative medicine applications.
- Dental Pulp-Derived:MSCs extracted from dental pulp exhibit high plasticity, showing promise for neurological and dental repair research.
Volume placements concentrate in Bone Marrow-Derived MSCs; the faster expansion belongs to Umbilical Cord-Derived cells.
Therapy Area:
Therapy area segmentation delineates the primary medical applications where mesenchymal stem cells are deployed for regenerative purposes.
- Orthopedics:This segment encompasses the use of MSCs for cartilage repair, bone regeneration, and osteoarthritis treatment, representing a significant portion of current clinical applications. Demand is particularly strong in Germany, where aging populations drive the need for joint and musculoskeletal therapies.
- Neurology:MSCs are explored for treating neurodegenerative diseases, spinal cord injuries, and stroke recovery due to their neurotrophic and immunomodulatory properties. Academic labs in the United States are intensely focused on advancing these complex therapeutic approaches.
- Cardiology:MSCs are investigated for myocardial repair following infarction and for treating various cardiovascular diseases.
- Dermatology:Applications include wound healing, scar reduction, and aesthetic skin rejuvenation using MSC-based therapies.
- Immunology:MSCs are utilized for their immunomodulatory effects in conditions such as graft-versus-host disease and autoimmune disorders.
Orthopedics currently accounts for the largest share of therapeutic applications, while neurological indications demonstrate the steepest expansion trajectory.
End User:
End user segmentation distinguishes between the institutional and commercial entities driving both research and clinical development of MSC technologies.
- Research Institutes:These institutions are primarily engaged in basic science and preclinical studies, exploring novel applications and mechanisms of action for mesenchymal stem cells. They often collaborate with industry partners for translational research.
- Biopharmaceutical Firms:These companies focus on developing, manufacturing, and commercializing clinical-grade MSC therapies, often investing heavily in large-scale production and regulatory navigation. Demand for GMP-grade cells and media systems is high among these entities.
- Contract Research Organizations:CROs provide specialized research services to biopharmaceutical firms and academic institutions, supporting preclinical and clinical trials for MSC products.
- Academic Labs:University-affiliated laboratories conduct fundamental research into MSC biology, differentiation, and therapeutic potential, often contributing to early-stage discovery.
Biopharmaceutical firms represent the largest commercial purchasers, with academic labs showing sustained research investment.
Delivery Mode:
Delivery mode segmentation reflects the diverse methods employed to administer mesenchymal stem cells, each tailored to specific therapeutic targets and physiological requirements.
- Intravenous:This systemic delivery method allows MSCs to circulate throughout the body, targeting distant sites of injury or inflammation, and is often used for immunomodulatory effects. Clinical trials in Europe frequently utilize this route for conditions like graft-versus-host disease.
- Intra-articular:Direct injection into joint spaces is a common method for orthopedic applications, ensuring localized delivery of MSCs to treat conditions like osteoarthritis and cartilage defects. This mode is particularly prevalent in orthopedic clinics across Japan.
- Intramuscular:MSCs are injected directly into muscle tissue, a method explored for localized muscle repair or systemic distribution in specific conditions.
- Subcutaneous:This delivery method involves injecting MSCs beneath the skin, often for dermatological applications or systemic delivery in certain therapeutic contexts.
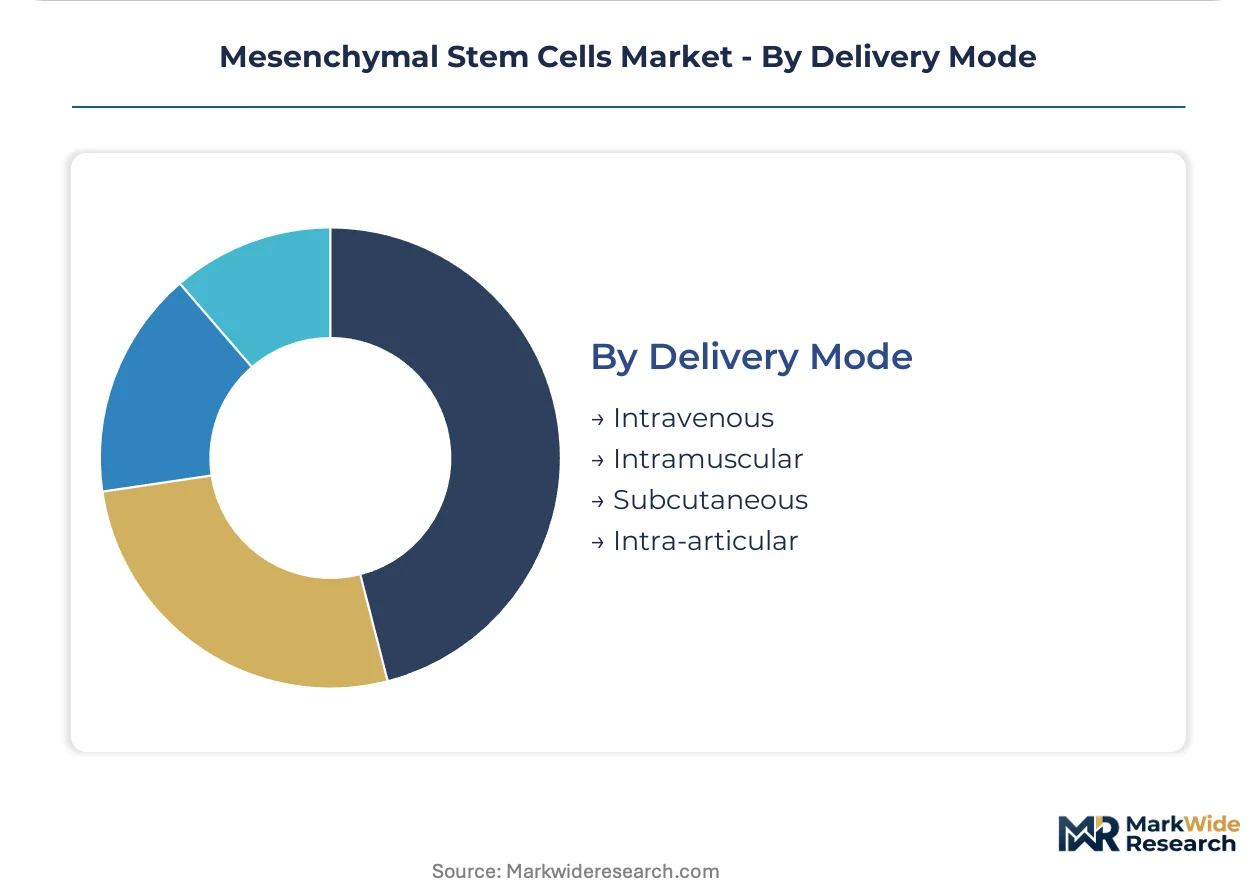
Intra-articular administration is critical for localized orthopedic applications, whereas intravenous delivery offers systemic distribution for broader indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global mesenchymal stem cells market exhibits a clear division between established research and emerging therapeutic applications. Production capabilities are concentrating in advanced economies with robust biopharmaceutical infrastructure. Consumption patterns reflect both academic investigation and clinical adoption for regenerative medicine.
United States
Demand for mesenchymal stem cells in the United States is strong across orthopedic and neurological research. The US FDA dictates stringent requirements for clinical-grade MSC manufacturing and therapeutic applications, influencing development strategies. Academic labs in Boston and San Francisco intensely focus on advancing complex neurological therapeutic approaches.
Germany
Germany's market for mesenchymal stem cells is propelled by orthopedic applications and academic research. Europe's EMA mandates rigorous quality, safety, and efficacy standards for cell-based products, increasing compliance burdens. Competitive academic research centers in Munich and Berlin prioritize workflow efficiency and data reproducibility.
Japan
Japan shows significant investment in umbilical cord-derived mesenchymal stem cells due to favorable regulatory pathways. The PMDA has established an accelerated approval pathway for regenerative medicine products, shortening time-to-revenue. Biopharmaceutical firms in Tokyo are increasingly investing in this segment, leveraging ease of scalability.
United Kingdom
The United Kingdom demonstrates significant activity in mesenchymal stem cell research and early-stage clinical development. Products targeting the European market must align with the EMA's Advanced Therapy Medicinal Product (ATMP) framework. Biotech clusters in Cambridge and London are actively engaged in developing novel allogeneic MSC therapies for various indications.
Mesenchymal Stem Cells Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in mesenchymal stem cells, creating a dynamic competitive environment. The market structure features both large, established life science suppliers offering broad portfolios and specialized biotech firms targeting niche applications. Archetypes include integrated solution providers, specialized cell therapy developers, and research reagent manufacturers. Strategic partnerships and technology licensing agreements represent dominant competitive moves among these players, alongside targeted capacity expansion.
Integrated solution providers like Lonza Group AG exemplify the trend towards comprehensive workflow offerings, leveraging extensive manufacturing capabilities for GMP-grade cells and media systems. STEMCELL Technologies Inc. occupies a position as a specialized provider, differentiating through its comprehensive portfolio supporting the entire research workflow, from isolation to analysis. Thermo Fisher Scientific Inc., a large diversified scientific instrumentation and services company, represents a major supplier of research tools and reagents essential for MSC development and characterization. These entities collectively underscore the market's need for both broad-spectrum support and specialized expertise.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Merck KGaA |
| STEMCELL Technologies Inc |
| Axol Bioscience Ltd |
| Lonza Group AG |
| Cell Applications Inc |
| PromoCell GmbH |
| Cyagen Biosciences Inc |
| Celprogen Corporation |
Cost & Logistics Intelligence
GMP-grade cell culture media costs cascade through the mesenchymal stem cell supply chain, influencing pricing tiers for both research and clinical-grade products. This cost structure impacts market access and commercial viability for therapeutic applications.
Pricing Analysis
Cost-down pressure on research-grade mesenchymal stem cells accelerates because academic labs prioritize efficiency and reproducibility in their workflow solutions. Contract-based pricing models dominate for large biopharmaceutical firms purchasing clinical-grade cells for therapeutic development. Price differentiation stems from quality grade, such as GMP compliance, and the volume scale of purchases. Academic labs exhibit the highest price sensitivity, often seeking bundled workflow solutions that offer cost efficiencies, while biopharmaceutical firms prioritize regulatory compliance and consistent potency for clinical applications.
Supply Chain Analysis
Direct sales channels and specialized distributors handle the distribution of mesenchymal stem cell products to biopharmaceutical firms and academic labs. Supply concentration for advanced MSC production facilities is noted across the United States, Germany, and Japan. Raw material dependencies include specialized cell culture media, growth factors, and cryopreservation reagents. Regulatory restriction on cell sourcing, particularly for human-derived materials, represents a structural supply chain risk for developers. The distribution model for research-grade materials often involves catalog sales, while clinical-grade cells require direct, validated cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mesenchymal stem cells market operates as a supply-constrained story, with GMP-compliant manufacturing capacity for clinical-grade products representing a significant bottleneck propping pricing for therapeutic applications.
For Market Incumbents: Deepen vertical integration into specialized media and reagent production to mitigate supply chain risks and control input costs. Expand GMP manufacturing facilities strategically in regions like the United States and Europe to meet escalating demand for clinical-grade MSCs. Invest in advanced cryopreservation technologies to enhance product stability and extend shelf life, addressing functional inconsistency. This proactive approach helps defend against emerging entrants offering cost-effective alternatives.
For New Entrants and Emerging Players: Launch via specialized research kit bundling, targeting academic labs and early-stage biotechs that value complete workflow solutions. Focus on developing allogeneic "off-the-shelf" therapies or exosome-based therapeutics, which offer potentially simpler regulatory pathways and scalability. The academic research segment, particularly in neurology and immunology, presents a penetrable entry point for novel MSC applications. Emphasize consistent potency assays and differentiation capacity to build early market credibility.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cell therapy developers in regions with accelerated regulatory pathways, such as Japan. The long-term viability of the mesenchymal stem cell market remains strong over the next decade, driven by expanding therapeutic applications. Acquisition targets should possess robust intellectual property in gene-editing enhancements or scalable bioprocessing technologies. Successful Phase 3 clinical trial readouts for allogeneic MSC therapies represent a critical signal to watch as an inflection indicator for broader commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Enables commercial viability for allogeneic therapies and meets growing demand from biopharmaceutical firms. |
| Regulatory Approval Pathway Navigation | Accelerates market access for new therapies, particularly in regions with favorable frameworks like Japan. |
| Product Launch: Exosome-based Therapeutics | Captures a cell-free regenerative medicine segment with potentially simpler manufacturing and regulatory profiles. |
| Technology Licensing: CRISPR Integration | Enhances therapeutic properties and targeted functions of MSCs for specific disease indications. |
| Strategic Partnership with Biopharma | Secures funding and expertise for clinical development and commercialization of advanced MSC products. |
Research Approach
Document review covered scientific literature databases, regulatory agency guidelines from the FDA, EMA, and PMDA, and company annual reports, complemented by interviews with biopharmaceutical R&D leads, academic principal investigators, regulatory affairs specialists, and contract manufacturing executives. This multi-faceted approach ensured both bottom-up market insights and top-down validation of industry trends. Secondary data sources included clinical trial registries and specialized industry reports to inform market sizing and segmentation.
Historical market data was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, therapy area, end user, delivery mode, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth trends and projected market shifts influenced by technological advancements. Key forecast inputs included advancements in cryopreservation technologies and the increasing adoption of automated bioreactor systems.
Unforeseen clinical trial failures, evolving regulatory interpretations, and new competitive technologies are the dominant revision risks for market forecasts. Forecasts reflect a synthesis of primary and secondary research findings, acknowledging inherent market uncertainties. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
North America Stem Cell Therapy Market