
 Asia-Pacific Gene Therapy Market | 2026-2036
Asia-Pacific Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gene Therapy Market Insights
Market Context
Synthetic AAV capsids are shifting cost structures away from first-generation serotypes across the Asia-Pacific Gene Therapy Market. Novartis AG leverages its Basel-derived manufacturing protocols to anchor premium vector supply into Japanese and Australian hospital networks. WuXi AppTec Co Ltd dominates contract development across China's biotech corridor, while Samsung Biologics extends its CDMO footprint to capture Korean and Southeast Asian gene therapy production demand.
Technical Definition and Segment Structure
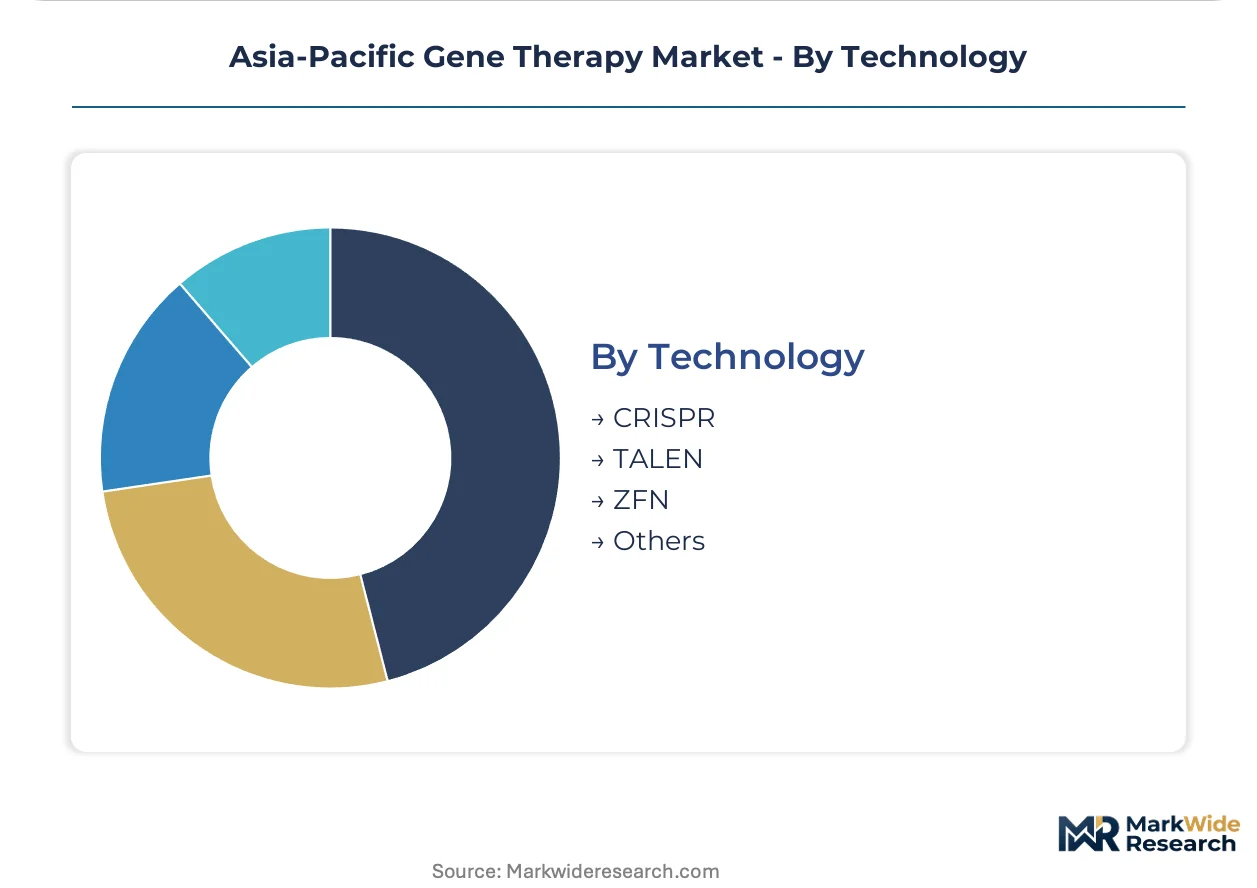
Gene therapy encompasses the therapeutic delivery of nucleic acids into patient cells to correct or replace dysfunctional genetic sequences, typically employing viral vectors engineered to transduce target tissues with precision tropism and controlled expression kinetics. Lentiviral vectors occupy the largest product type position due to stable genomic integration requirements in hematopoietic stem cell applications, while adenoviral vectors compete in oncology settings demanding transient, high-capacity transgene expression. CRISPR-based technology leads the fastest-expanding technology segment as Chinese and Korean regulators streamline investigational new drug pathways for ex vivo edited cell therapies.
Regulatory Framework and Outlook
Japan's PMDA operates Sakigake designation pathways that compress gene therapy review timelines, while Australia's TGA aligns its orphan drug framework with comparable access incentives; China's NMPA meanwhile enforces Good Manufacturing Practice standards for viral vector facilities that filter market entrants by capital intensity. CDSCO in India maintains evolving biosimilar-like oversight for gene therapy imports that shapes multinational licensing strategies. Stakeholders must monitor divergence between national cell and gene therapy frameworks when allocating regional clinical development resources.
Market Dynamics
China's NMPA accelerated review pathways are compressing clinical trial timelines and redrawing competitive positioning across the Asia-Pacific Gene Therapy Market. Japanese hospital networks are expanding oncology gene therapy capacity while Korean regulators streamline investigational new drug pathways for ex vivo edited cell therapies.
Growth Catalysts
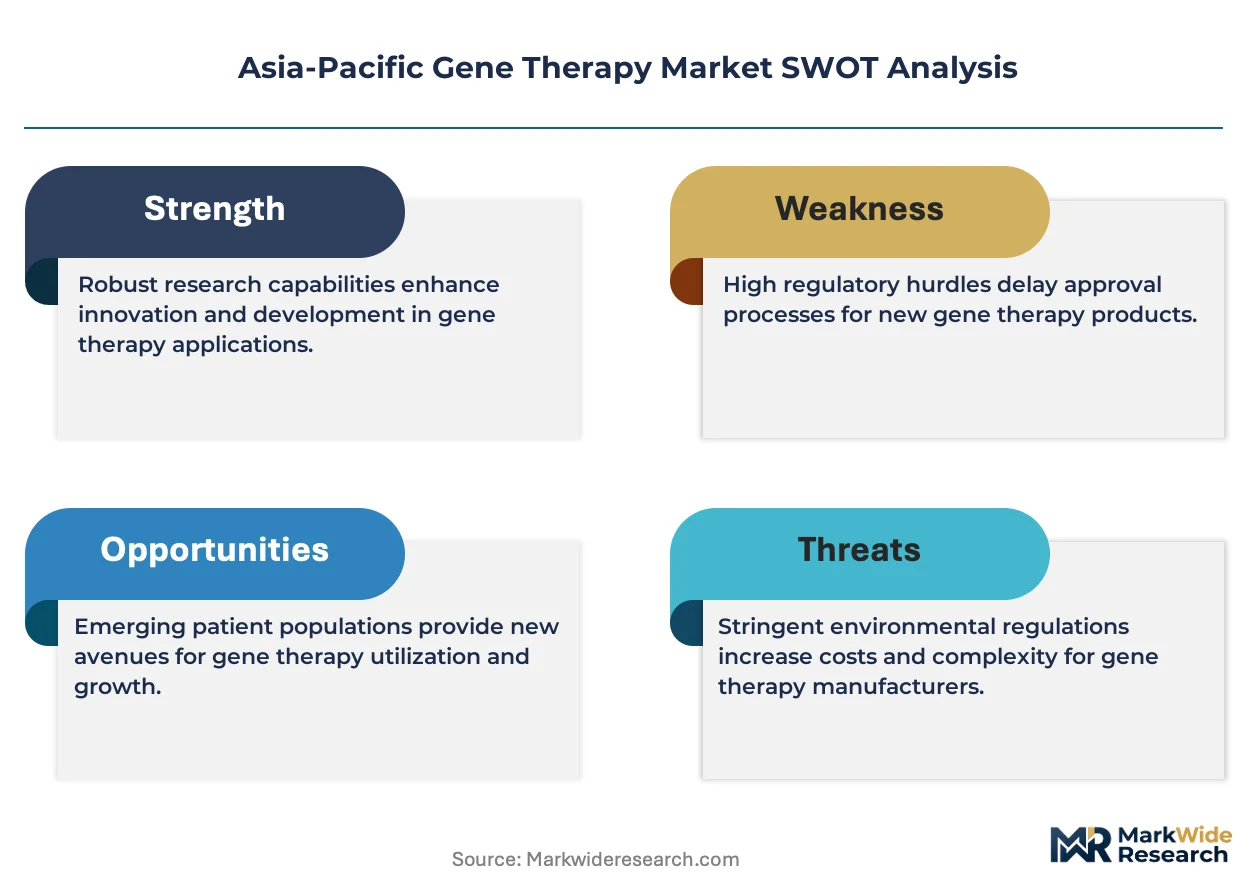
- Sakigake Designation Pathways:Japan's PMDA compresses gene therapy review timelines, attracting multinational sponsors seeking first-in-region approvals for novel vectors.
- Hematopoietic Stem Cell Applications:Lentiviral vector demand accelerates as regional hospitals expand treatment protocols for inherited blood disorders.
- Tokyo Biomedical Cluster:Japan's Kanto region concentrates specialized manufacturing infrastructure and clinical research sites, anchoring regional demand.
Market Restraints
- Viral Vector Production Bottlenecks:Plasmid DNA and transfection reagent supply concentration in select bioreactor facilities limits batch scalability.
- Good Manufacturing Practice Compliance:China's NMPA enforces facility standards that filter entrants by capital intensity, raising fixed-cost barriers.
- Allogeneic Cell Therapy Substitution:Off-the-shelf edited cell products threaten autologous gene therapy economics in oncology indications.
Strategic Opportunities
- Southeast Asia Greenfield Entry:Singapore and Thailand lack domestic viral vector manufacturing, creating first-mover advantage for CDMO partnerships.
- CRISPR-Base Editing Convergence:Korean and Chinese regulators are streamlining pathways for precision genome editing without double-strand breaks.
- Orphan Drug Framework Alignment:Australia's TGA access incentives match Japanese and Korean programs, enabling unified regional development strategies.
Industry Challenges
- Vector Process Development Talent Scarcity:Upstream bioprocessing and analytical development functions face acute shortages across Chinese and Korean biotech corridors.
- Legacy Quality System Integration:Multinational sponsors struggle to harmonize electronic batch records across NMPA, PMDA, and TGA inspection requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gene Therapy Market |
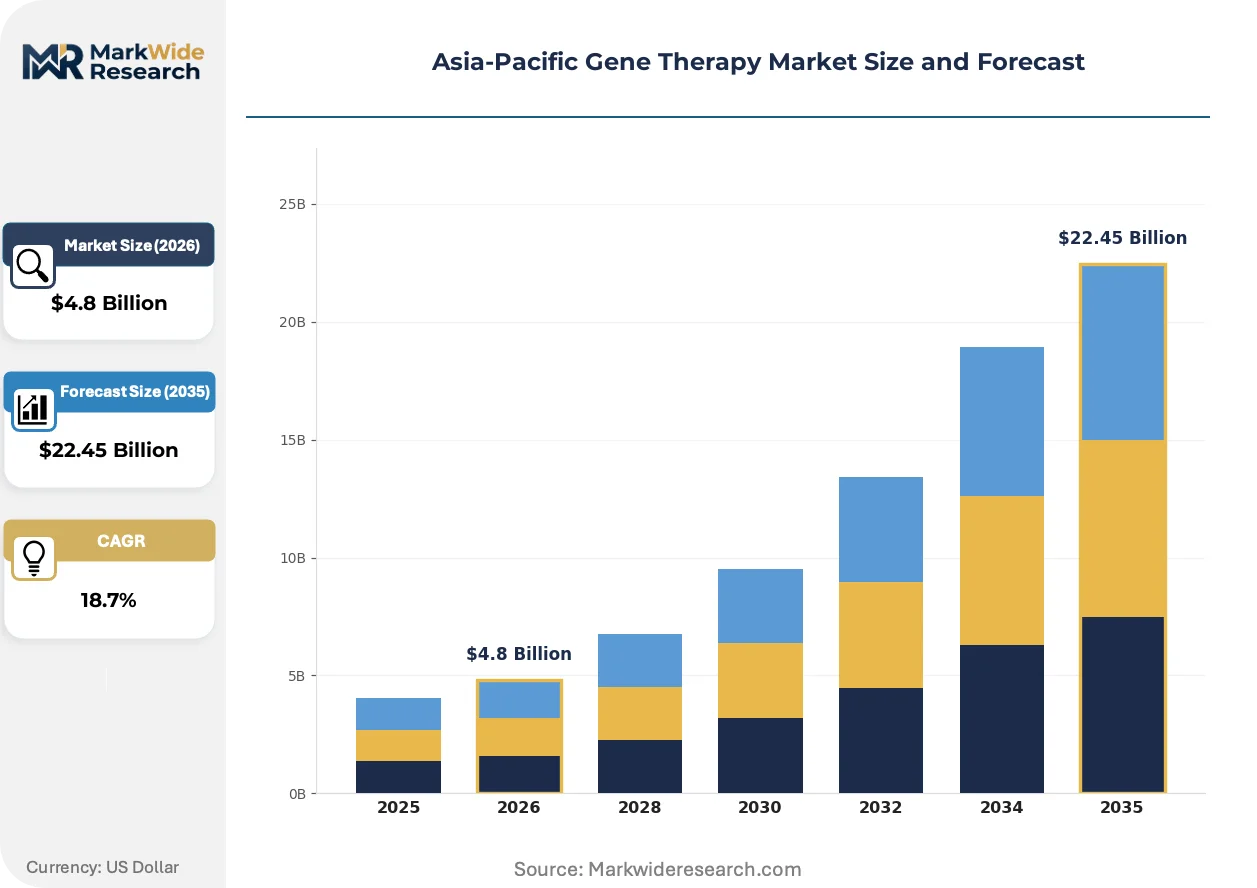
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenoviral Vectors, Lentiviral Vectors, Plasmid DNA, Others Application: Cancer Treatment, Genetic Disorders, Infectious Diseases, Neurological Disorders End User: Hospitals, Clinics, Research Institutes, Pharmaceutical Companies Technology: CRISPR, TALEN, ZFN, Others |
| Companies Covered | Novartis AG, Gilead Sciences, Inc., Biogen, Amgen Inc., Spark Therapeutics, Inc., WuXi AppTec Co Ltd, Lonza Group AG, Samsung Biologics, Sarepta Therapeutics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gene Therapy Market Trends and Innovations
Synthetic biology tools are rewriting vector engineering workflows across the Asia-Pacific Gene Therapy Market. Regional regulators are adapting faster than global counterparts, while hospital procurement patterns are consolidating around integrated supply agreements.
Next-generation AAV capsid engineering is absorbing directed evolution and machine learning screening to evade pre-existing neutralizing antibodies. Japanese and Australian hospital networks are prioritizing these synthetic serotypes for systemic delivery programs. The technology is absorbing manufacturing complexity as regional CDMOs retool from first-generation serotype production.
China's NMPA conditional approval framework is compressing Phase II-to-market timelines for breakthrough gene therapies. The policy shift enables earlier revenue recognition for sponsors willing to accept post-marketing efficacy commitments. Oncology indications with unmet need are responding fastest, with several programs advancing under this pathway.
Japanese university hospitals are consolidating gene therapy procurement through designated supplier frameworks that bundle vector supply with clinical trial execution. The model displaces fragmented purchasing across individual principal investigators. Kanto region academic medical centers are most advanced in this transition, with Osaka and Fukuoka clusters following.
Asia-Pacific Gene Therapy Market Segmentation
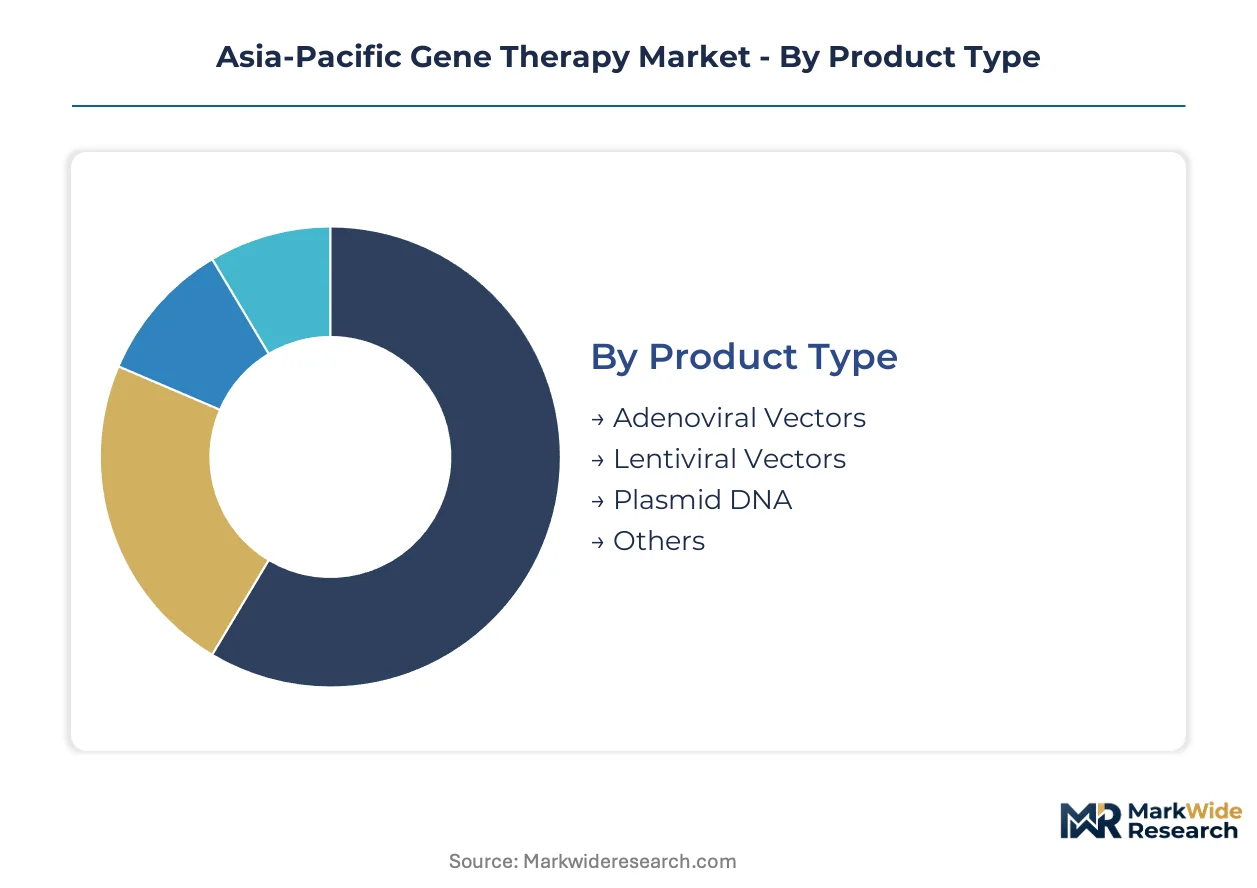
Gene therapy segmentation in the Asia-Pacific region reflects divergent manufacturing requirements across viral and non-viral platforms. Each category demands distinct regulatory pathways, capital deployment, and clinical infrastructure that shape competitive positioning.
Product Type:
Customization intensity varies sharply across this category, from bespoke AAV engineering to standardized plasmid production protocols.
- Lentiviral Vectors:These RNA-based retroviral systems integrate stably into host genomes, enabling permanent correction of hematopoietic stem cells. Japan's Kanto region hospitals dominate demand for inherited blood disorder protocols, though plasmid DNA supply constraints limit batch scalability.
- Adenoviral Vectors:Double-stranded DNA viruses deliver transient, high-capacity transgene expression ideal for oncology applications. Australian and Korean cancer centers are expanding treatment capacity fastest, drawn by rapid manufacturing turnaround and lower integration risk profiles.
- Plasmid DNA:Non-viral circular DNA constructs serve as raw material for viral vector production and direct therapeutic applications. Chinese CDMOs are scaling GMP-grade manufacturing to reduce import dependency.
- Others:AAV serotypes, synthetic nanoparticles, and exosome-based delivery systems occupy emerging niches. Singaporean research institutes are piloting next-generation platforms.
Most installed capacity flows through lentiviral vector production. Expansion is steepest in adenoviral vector segments.
Application:
Margin profiles diverge across this category based on trial complexity and reimbursement certainty.
- Cancer Treatment:Oncolytic viruses and CAR-T gene modifications target solid and hematological malignancies. China's NMPA conditional approval framework accelerates commercial timelines for breakthrough therapies, compressing Phase II-to-market intervals.
- Genetic Disorders:Single-gene correction therapies address hemophilia, sickle cell disease, and lysosomal storage diseases. Japanese PMDA Sakigake designation attracts sponsors seeking first-in-region approvals for rare disease indications.
- Infectious Diseases:Vaccine and immunotherapy applications leverage gene delivery for pathogen targeting. Australian TGA orphan drug incentives support development for neglected tropical diseases affecting regional populations.
- Neurological Disorders:CNS-targeted vectors for Parkinson's, ALS, and spinal muscular atrophy require specialized blood-brain barrier penetration. Korean MFDS streamlines pathways for intrathecal delivery programs.
Cancer treatment commands the dominant revenue share. Genetic disorders are gaining share fastest.
End User:
Procurement sophistication determines pricing power across customer tiers in this category.
- Hospitals:Academic medical centers with integrated cell processing facilities perform in-house vector administration and patient monitoring. Tokyo's biomedical cluster anchors regional demand through designated supplier frameworks.
- Clinics:Specialized outpatient facilities focus on commercialized therapies with established reimbursement codes. Australian private oncology networks are consolidating purchasing through group procurement organizations.
- Research Institutes:University and government laboratories conduct early-phase vector development and preclinical validation. Chinese national labs receive prioritized NMPA review for investigator-initiated trials.
- Pharmaceutical Companies:Sponsors outsource manufacturing to CDMOs while retaining regulatory strategy and commercialization rights. Samsung Biologics and WuXi AppTec capture dominant contract volumes.
Hospital procurement absorbs the majority of vector supply. Pharmaceutical company outsourcing is expanding most quickly.
Technology:
Patent landscape density shapes competitive moats across editing platform categories.
- CRISPR:RNA-guided nuclease systems enable precise, programmable genome editing with reduced off-target profiles. Chinese and Korean regulators have streamlined investigational new drug pathways for ex vivo edited cell therapies, accelerating clinical entry.
- TALEN:Transcription activator-like effector nucleases offer smaller protein size and reduced immunogenicity compared to earlier platforms. Japanese research consortia maintain active programs for hematopoietic applications.
- ZFN:Zinc finger nucleases represent first-generation editing tools with established clinical safety data. Legacy programs continue in Australian and Indian research networks.
- Others:Base editing, prime editing, and epigenetic modifiers are advancing through preclinical pipelines. Singaporean synthetic biology institutes lead regional innovation.
CRISPR platforms dominate active clinical programs. Base editing derivatives are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's biomedical cluster anchors regional gene therapy demand through designated supplier frameworks and integrated hospital procurement. China's NMPA conditional approval pathways compress commercial timelines for breakthrough therapies. Korean regulators streamline investigational new drug applications for ex vivo edited cell therapies.
Japan
Japan's Kanto region concentrates lentiviral vector demand for hematopoietic stem cell applications at Tokyo academic medical centers. PMDA Sakigake designation pathways compress gene therapy review timelines and attract multinational sponsors seeking first-in-region approvals. Osaka and Fukuoka hospital clusters are consolidating procurement through bundled vector supply agreements.
China
Chinese national labs receive prioritized NMPA review for investigator-initiated trials while WuXi AppTec dominates contract development across the biotech corridor. NMPA enforces Good Manufacturing Practice standards for viral vector facilities that filter market entrants by capital intensity. Yangtze River Delta bioreactor facilities face plasmid DNA supply constraints that limit batch scalability.
South Korea
Korean MFDS streamlines regulatory pathways for intrathecal delivery programs targeting neurological disorders. Samsung Biologics extends its CDMO footprint to capture regional gene therapy production demand. Busan-Ulsan manufacturing zones are retooling from first-generation serotype production toward synthetic AAV capsid engineering.
Australia
Australian private oncology networks are consolidating purchasing through group procurement organizations for adenoviral vector therapies. TGA orphan drug framework aligns access incentives with Japanese and Korean programs, enabling unified regional development strategies. Sydney and Melbourne research institutes maintain active programs for neglected tropical disease applications.
Singapore
Singaporean synthetic biology institutes lead regional innovation in base editing and prime editing platforms. The city-state lacks domestic viral vector manufacturing, creating first-mover advantage for CDMO partnerships. Research consortia are piloting next-generation exosome-based delivery systems for preclinical validation.
Asia-Pacific Gene Therapy Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory navigation capabilities. The market structure reflects tiered consolidation where multinational sponsors retain regulatory strategy while outsourcing production to specialized CDMOs. Three archetypes dominate: integrated pharmaceutical conglomerates with captive vector supply, pure-play contract manufacturers with regional facility networks, and emerging biotech sponsors with platform licensing strategies. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure bioreactor access and plasmid supply agreements.
Among Asia-Pacific-based contract manufacturers, WuXi AppTec Co Ltd and Samsung Biologics exemplify the scale-driven CDMO archetype, while Lonza Group AG represents the integrated global supplier model with regional manufacturing presence. Novartis AG anchors the multinational sponsor tier through its Basel-derived manufacturing protocols and premium vector supply into Japanese and Australian hospital networks. Gilead Sciences, Inc. occupies a position within the oncology-focused gene therapy segment through its Kite Pharma cell therapy infrastructure.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences, Inc. |
| Biogen |
| Amgen Inc. |
| Spark Therapeutics, Inc. |
| WuXi AppTec Co Ltd |
| Lonza Group AG |
| Samsung Biologics |
| Sarepta Therapeutics |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals and NMPA Good Manufacturing Practice standards gate qualified viral vector supply and premium-tier pricing access for sponsors seeking conditional approval pathways. Bioreactor facilities in the Yangtze River Delta that meet these sustainability and quality mandates command pricing premiums from multinational pharmaceutical sponsors.
Pricing Analysis
Input-cost pass-through from plasmid DNA and transfection reagent supply constraints shapes pricing dynamics across lentiviral and adenoviral vector tiers. Three-tier pricing structure across premium, standard, and economy levels separates Sakigake-designated Japanese supply from NMPA-conditional Chinese production and Southeast Asian greenfield CDMO alternatives. Pricing pressure stems from allogeneic cell therapy substitution threats in oncology indications. Academic medical centers in Tokyo's Kanto region exhibit lowest price sensitivity due to bundled procurement frameworks, while Australian private oncology networks drive hardest volume negotiations.
Supply Chain Analysis
Workforce availability for upstream bioprocessing and analytical development functions concentrates supply chain gravity in China's Yangtze River Delta, South Korea's Busan-Ulsan corridor, and Japan's Kanto biomedical cluster. Plasmid DNA, specialized bioreactor hardware, and synthetic AAV capsid engineering talent draw from concentrated pools in these three geographies. Single-source vulnerability for GMP-grade transfection reagents creates structural risk for batch scalability. Distribution runs through designated supplier frameworks at Japanese university hospitals and group procurement organizations in Australian private networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where sponsors exploit the twelve-to-eighteen-month gap between NMPA conditional approval timelines and PMDA Sakigake review compression to optimize capital deployment.
For Market Incumbents: Deploy backward integration into plasmid DNA manufacturing to secure supply against Chinese bioreactor concentration. Capture Korean and Southeast Asian CDMO partnerships before synthetic AAV capsid engineering retooling completes. Allogeneic cell therapy substitution in oncology indications threatens autologous gene therapy economics and demands defensive positioning through next-generation editing platform licensing. For New Entrants and Emerging Players: MFDS streamlined pathways in South Korea for intrathecal delivery programs open a window for neurological disorder specialization with lower competitive density than oncology. Target Singapore's viral vector manufacturing gap through CDMO partnerships before domestic capacity emerges. Base editing convergence in Korean and Chinese regulatory frameworks offers the most penetrable technology entry point for precision genome editing without double-strand breaks. For Investors and Strategic Acquirers: Roll-up economics work for regional CDMO specialists because vector process development talent scarcity prevents rapid organic scale-up by fragmented competitors. Five-to-ten-year viability hinges on securing bioreactor access and plasmid supply agreements ahead of capacity constraints. Watch for NMPA enforcement actions against non-compliant viral vector facilities as the inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Bioreactor capacity expansion in Busan-Ulsan corridor captures Korean and Southeast Asian gene therapy production demand. |
| Regulatory Approval Pathway | Sakigake designation navigation compresses PMDA review timelines for first-in-region vector approvals. |
| Licensing Agreement | Next-generation AAV capsid engineering partnerships displace first-generation serotype supply contracts. |
| Clinical Trial Advancement | Conditional approval framework exploitation accelerates Phase II-to-market revenue recognition in China. |
| Pipeline Diversification | CRISPR-base editing programs hedge against allogeneic cell therapy substitution in oncology indications. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement contract records, CDMO capacity utilization disclosures, and vector engineering patent landscapes — were reconciled to construct this analysis. Primary interviews with gene therapy development executives, regulatory affairs leads at multinational sponsors, hospital procurement managers in Tokyo's Kanto cluster, and viral vector manufacturing specialists informed demand-side and supply-side assumptions. Secondary validation drew from NMPA approval announcements, PMDA Sakigake designations, ClinicalTrials.gov registry entries, and TGA orphan drug determinations. Bottom-up vector production capacity estimates and top-down regional reimbursement forecasts were triangulated to anchor market sizing.
Data-stream reconciliation across the projection horizon employed segment-level modeling for lentiviral vectors, adenoviral vectors, plasmid DNA, and emerging AAV platforms. Application dimensions including cancer treatment, genetic disorders, infectious diseases, and neurological indications were cross-tabulated against end-user procurement sophistication tiers. Technology trajectories for CRISPR, TALEN, ZFN, and base editing platforms informed adoption curve assumptions. CAGRs were derived from installed capacity expansion timelines, regulatory pathway compression effects, and vector manufacturing yield improvement rates across Chinese, Japanese, Korean, and Australian markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA enforcement intensity shifts or PMDA Sakigake pathway modifications. Assumptions regarding plasmid DNA supply scalability and synthetic AAV capsid engineering timelines underpin the projection framework. Material deviation in allogeneic cell therapy clinical efficacy or CRISPR off-target profile revelations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market