
 Mrna Vaccines and Therapeutics Market | 2026-2036
Mrna Vaccines and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Mrna Vaccines and Therapeutics Market Intelligence
The EU Green Deal's pharmaceutical sustainability targets is shifting procurement criteria across European hospital networks. Moderna, Inc. leverages its integrated manufacturing platform to control supply chain quality from plasmid DNA to finished drug product. BioNTech SE anchors its position through deep specialization in individualized neoantigen therapies. Pfizer Inc. competes by extending its commercial reach through established vaccine distribution infrastructure across multiple continents.
Messenger RNA therapeutics consist of synthetic nucleotide sequences encapsulated in lipid nanoparticles that instruct host cells to produce therapeutic proteins, with LNP formulation determining cellular uptake efficiency and immunogenicity profile. Prophylactic vaccines occupy the largest revenue share due to established COVID-19 and influenza programs, while cancer treatments represent the fastest-expanding category as personalized neoantigen vaccines advance through late-stage trials. LNP Formulation technology dominates manufacturing investment because delivery efficiency directly correlates with clinical efficacy across both infectious disease and oncology applications.
The FDA maintains accelerated approval pathways for mRNA breakthrough therapies, while EMA's adaptive licensing frameworks reduce time-to-market for novel modalities. WHO prequalification standards shape access for low-income country procurement, creating tiered market entry requirements. Stakeholders must monitor regulatory convergence on LNP characterization standards as agencies harmonize chemistry-manufacturing-controls expectations across jurisdictions.
Market Dynamics
Manufacturing scale-up constraints are compressing competitive timelines as hospital networks demand guaranteed supply commitments before formulary inclusion. The tension between batch consistency requirements and flexible production scheduling is forcing capital allocation trade-offs across the value chain.
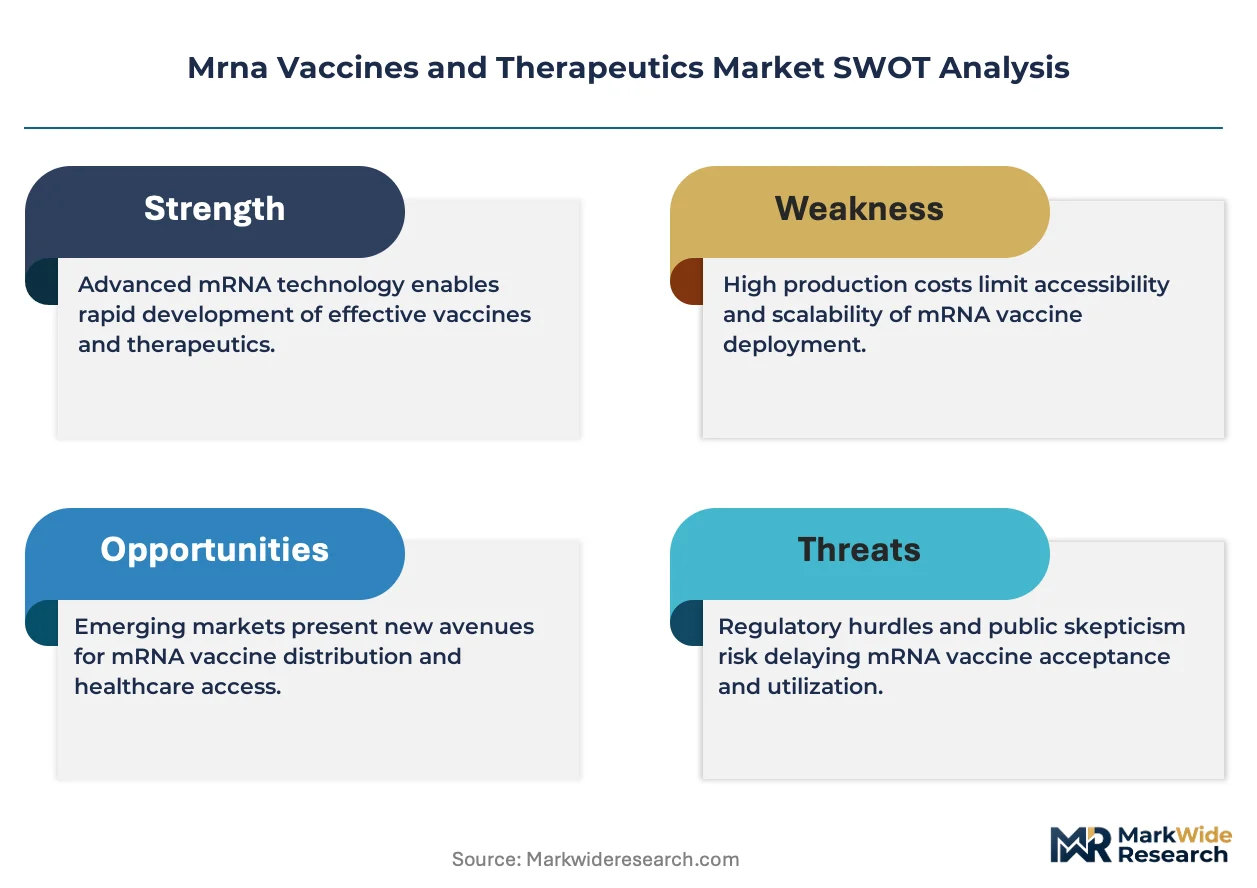
Growth Catalysts
- EMA Adaptive Licensing:The European framework compresses clinical-to-commercial transitions for breakthrough mRNA oncology candidates. Hospital procurement committees now prioritize therapies with conditional marketing authorization pathways.
- Lipid Nanoparticle Optimization:Formulation advances in ionizable lipid chemistry are expanding tissue targeting beyond hepatic delivery. This unlocks intratumoral and mucosal administration routes previously inaccessible to nucleic acid therapeutics.
- German Manufacturing Clusters:Dedicated mRNA production campuses in Marburg and Dresden are attracting specialized talent pools and supplier ecosystems. Regional concentration reduces logistics costs for European distribution networks.
Market Restraints
- Specialized Cold Chain Requirements:Ultra-low temperature storage infrastructure limits distribution reach to tertiary medical centers. Rural hospital networks lack capital budgets for -80°C capacity expansion.
- Single-Source Lipid Suppliers:Proprietary ionizable lipid intellectual property concentrates with two specialty chemical manufacturers. Supply disruption risk elevates security-of-supply premiums in contract negotiations.
- Immunogenicity Uncertainty:Repeat dosing tolerance remains unresolved for chronic disease applications. This technical ceiling restricts mRNA therapeutics to acute or intermittent treatment paradigms.
Strategic Opportunities
- Japanese Oncology Networks:Underpenetrated hospital formulary access for personalized neoantigen vaccines creates first-mover positioning. PMDA's sakigake designation accelerates reimbursement discussions.
- Self-Amplifying RNA Platforms:Reduced dose requirements from replicon technology convergence with standard mRNA manufacturing infrastructure. This hybrid approach lowers cost-per-dose thresholds for tropical disease applications.
- EU Green Deal Procurement Mandates:Sustainability scoring in hospital tender evaluations favors suppliers with carbon-transparent supply chains. Early compliance creates preferential access to European public procurement frameworks.
Industry Challenges
- LNP Characterization Standardization:Divergent FDA and EMA chemistry-manufacturing-controls expectations for particle size distribution and encapsulation efficiency create dual filing burdens. Harmonization timelines remain uncertain.
- Process Analytical Technology Integration:Real-time release testing requires capital-intensive spectroscopic and chromatographic infrastructure. Mid-scale manufacturers face obsolescence without platform upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mrna Vaccines and Therapeutics Market |
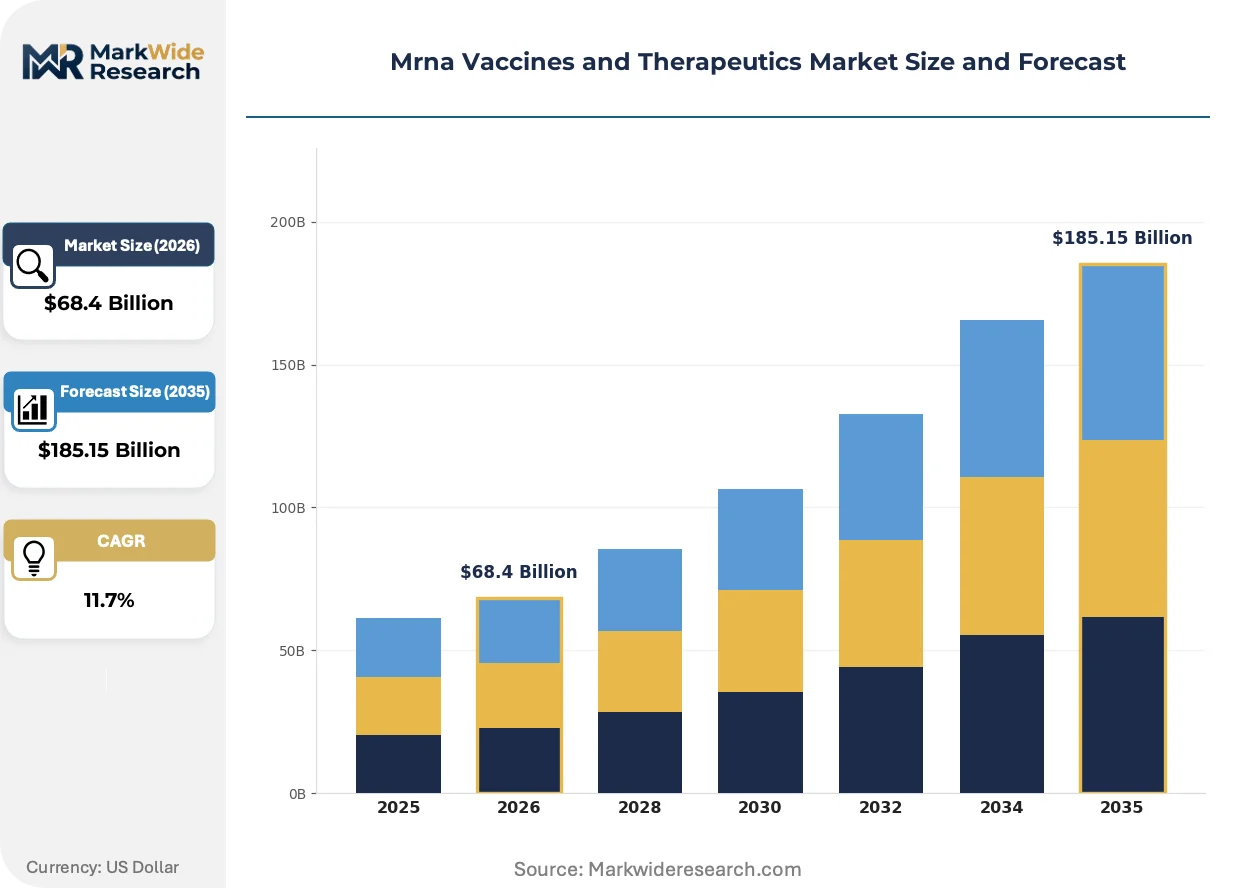
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prophylactic Vaccines, Therapeutic Vaccines, Antiviral Products, Cancer Treatments Technology: Self-amplifying mRNA, Nanoparticle Delivery, LNP Formulation, DNA-based mRNA End User: Pharmaceutical Companies, Research Institutions, Hospitals, Government Agencies Delivery Mode: Intramuscular Injection, Intravenous Injection, Oral Administration, Nasal Spray |
| Companies Covered | Moderna, Inc., BioNTech SE, Pfizer Inc., CureVac SE, GSK plc., Sanofi, Arcturus Therapeutics, AIM Vaccine Corporation, Ethris GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mrna Vaccines and Therapeutics Market Strategic Shifts & Innovations
Technology convergence between synthetic biology and automated manufacturing is collapsing development timelines for personalized therapeutics. This structural acceleration is redrawing competitive boundaries between platform specialists and integrated pharmaceutical operations.
Self-amplifying RNA constructs are absorbing manufacturing capacity investments previously directed toward conventional mRNA templates. The replicon architecture enables lower dose volumes while maintaining equivalent protein expression. Biomanufacturing facilities in Germany and the United States are retrofitting production suites to accommodate the longer RNA templates and modified purification workflows this technology requires.
REACH regulatory updates in Europe are mandating disclosure of novel lipid excipient toxicological profiles before commercial authorization. The industrial consequence is extended preclinical safety packages and elevated regulatory affairs staffing for European market entry. Oncology applications face the steepest compliance burden due to chronic dosing regimens and cumulative exposure concerns.
Hospital procurement committees are consolidating supplier relationships around single-platform vendors capable of spanning infectious disease and oncology portfolios. Group purchasing organizations are displacing individual hospital negotiations with multi-year framework agreements tied to volume commitments. This concentration is most visible in United States health systems where integrated delivery networks control formulary access across dozens of affiliated facilities.
Mrna Vaccines and Therapeutics Market Segmentation
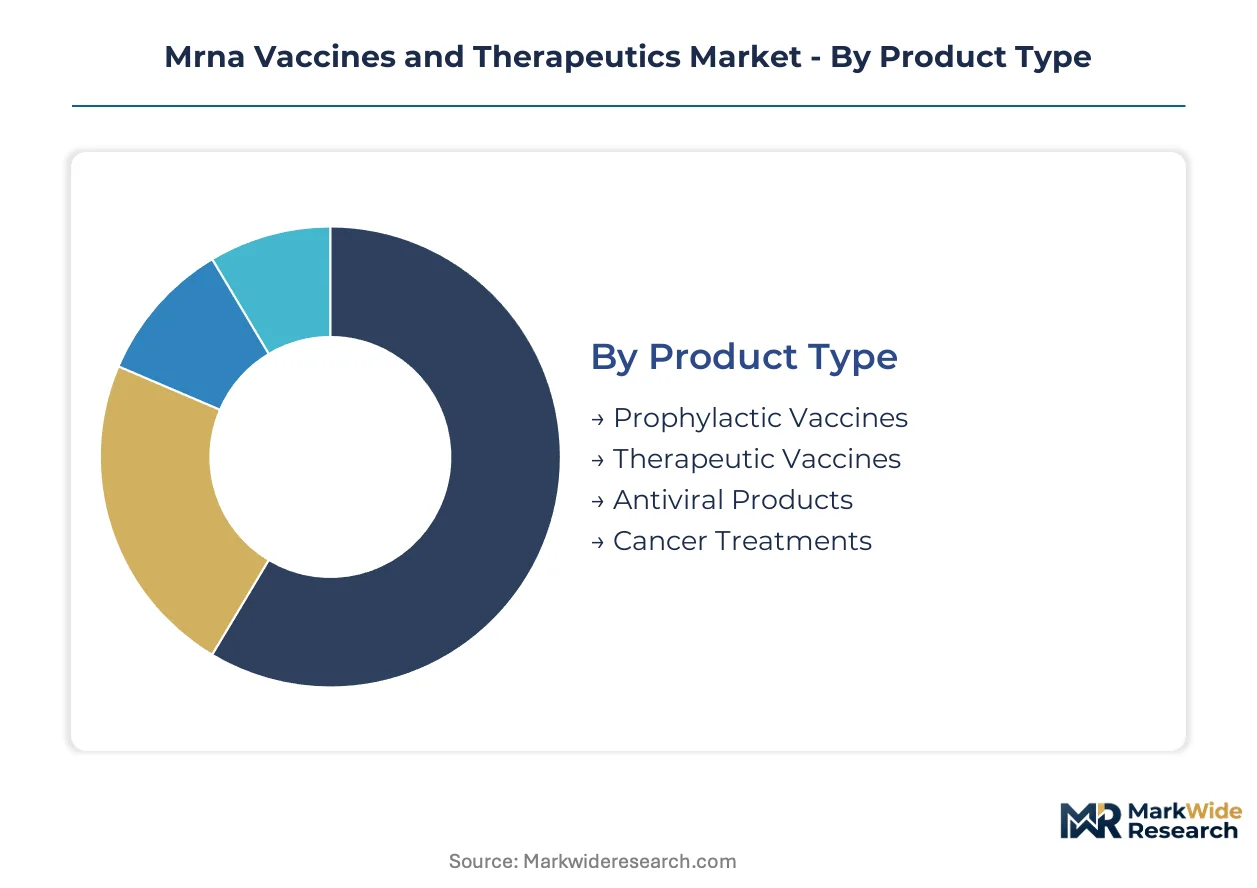
mRNA market segmentation reveals how technology platforms, delivery systems, and institutional buyers allocate capital across the value chain. Each dimension carries distinct procurement criteria and regulatory pathways that determine commercial access.
Product Type:
Lipid nanoparticle encapsulation chemistry varies substantially across therapeutic objectives, creating divergent manufacturing specifications and stability profiles.
- Prophylactic Vaccines:Synthetic mRNA sequences encoding viral antigens, formulated in ionizable lipid nanoparticles for intramuscular depot release. Hospital networks in the United States and Germany prioritize these for formulary inclusion due to established cold chain infrastructure and FDA/EMA accelerated approval precedents.
- Cancer Treatments:Patient-specific neoantigen vaccines requiring rapid manufacturing turnaround from tumor biopsy to infusion. Oncology centers in Japan and the United States drive demand as PMDA and FDA frameworks for individualized therapies mature.
- Therapeutic Vaccines:mRNA encoding disease-associated antigens for autoimmune and chronic infectious conditions.
- Antiviral Products:mRNA encoding monoclonal antibodies or immunomodulatory proteins for passive immunization.
Prophylactic vaccines lead on scale; cancer treatments lead on momentum.
Technology:
Platform selection determines dose sparing, tissue targeting, and compatibility with existing biomanufacturing infrastructure.
- LNP Formulation:Ionizable lipid systems enabling endosomal escape and cytoplasmic mRNA release, with composition patents concentrated among specialty chemical manufacturers. EMA and FDA chemistry-manufacturing-controls convergence efforts are reshaping analytical requirements for particle size distribution and encapsulation efficiency.
- Self-amplifying mRNA:Replicon constructs encoding viral RNA polymerase for intracellular amplification, reducing dose requirements. German manufacturing clusters in Marburg and Dresden are retrofitting production suites to accommodate longer RNA templates and modified purification workflows.
- Nanoparticle Delivery:Polymeric and peptide-based alternatives to lipid systems for targeted tissue distribution.
- DNA-based mRNA:In vivo transcription platforms using DNA templates with self-cleaving ribozyme elements.
LNP formulation dominates current manufacturing investment; self-amplifying RNA platforms are climbing the fastest.
End User:
Procurement authority and technical specifications diverge sharply between commercial pharmaceutical operations and public health institutions.
- Pharmaceutical Companies:Integrated manufacturers controlling supply chain quality from plasmid DNA through finished drug product, with dedicated mRNA production campuses attracting specialized talent pools. United States and German facilities anchor regional supplier ecosystems.
- Hospitals:Integrated delivery networks consolidating supplier relationships around single-platform vendors capable of spanning infectious disease and oncology portfolios. Group purchasing organizations in the United States are displacing individual hospital negotiations with multi-year framework agreements.
- Research Institutions:Academic medical centers and contract development organizations advancing early-stage candidates.
- Government Agencies:National stockpile authorities and pandemic preparedness programs with procurement tied to WHO prequalification standards.
Pharmaceutical companies lead on scale; hospitals lead on momentum.
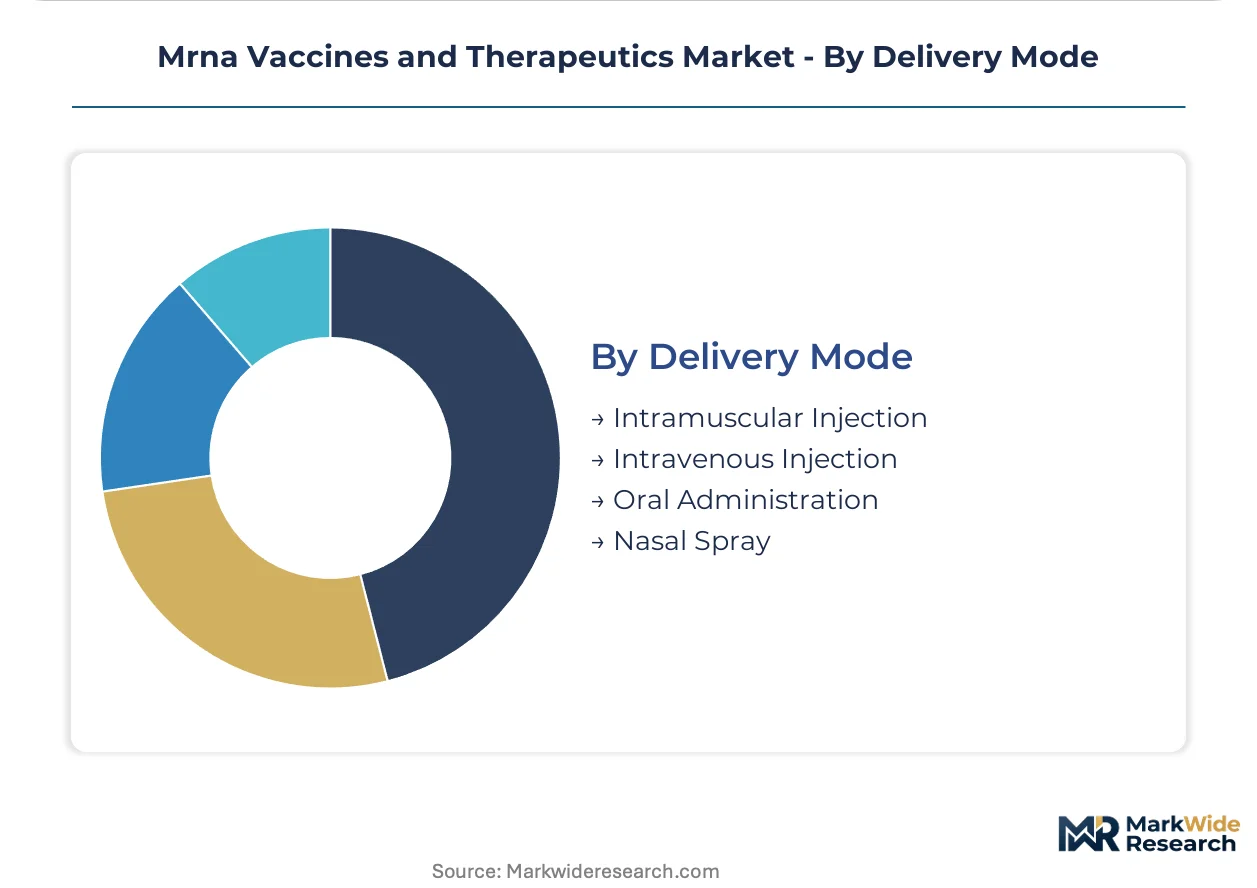
Delivery Mode:
Route of administration determines formulation viscosity, stability requirements, and point-of-care infrastructure needs.
- Intramuscular Injection:Standard depot-forming administration for vaccine applications, compatible with existing primary care and pharmacy clinic workflows. Ultra-low temperature storage infrastructure limits distribution reach to tertiary medical centers with -80°C capacity.
- Nasal Spray:Mucosal delivery for respiratory pathogen vaccines, bypassing cold chain constraints of injectable formulations. EMA adaptive licensing frameworks are compressing clinical-to-commercial transitions for breakthrough candidates targeting this route.
- Intravenous Injection:Systemic distribution for therapeutic protein replacement and oncology applications.
- Oral Administration:Gastrointestinal-stable formulations using enteric coatings or self-amplifying replicons for mucosal immune priming.
Intramuscular injection leads on scale; nasal spray leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
mRNA therapeutics originated in United States academic laboratories before scaling through German manufacturing partnerships. The technology's commercialization now spans dedicated production campuses across three continents. Hospital procurement networks in each region impose distinct qualification criteria on suppliers.
United States
FDA accelerated approval pathways compress clinical-to-commercial timelines for oncology candidates. The IRA's drug pricing provisions reshape reimbursement negotiations for chronic disease applications. Greater Boston and Research Triangle Park anchor integrated manufacturing campuses controlling supply chain quality from plasmid DNA through finished drug product.
Germany
EMA adaptive licensing frameworks prioritize breakthrough mRNA therapies in hospital procurement committees. EU Green Deal sustainability scoring favors suppliers with carbon-transparent supply chains. Marburg and Dresden production clusters attract specialized talent pools and reduce logistics costs for European distribution networks.
Japan
PMDA's sakigake designation accelerates reimbursement discussions for personalized neoantigen vaccines. METI funding programs support domestic mRNA manufacturing infrastructure expansion. Kanto region oncology centers drive demand as formulary access for individualized therapies matures.
United Kingdom
MHRA post-Brexit regulatory autonomy enables faster approval timelines for novel modalities. NHS England's specialized commissioning frameworks concentrate demand in designated tertiary centers. Oxford-Cambridge corridor research institutions advance early-stage candidates through contract development partnerships.
Switzerland
Swissmedic's streamlined authorization procedures attract clinical trial sponsors seeking European market entry. Federal procurement frameworks emphasize security-of-supply agreements for pandemic preparedness. Basel region biomanufacturing infrastructure supports contract manufacturing for multinational pharmaceutical operations.
Mrna Vaccines and Therapeutics Market Key Industry Players
Premium-margin players sit above commodity-margin players across manufacturing integration and intellectual property depth. The vendor base stratifies between platform specialists controlling proprietary lipid chemistries and integrated pharmaceutical operations leveraging established distribution infrastructure. Three archetypes dominate: LNP formulation innovators, self-amplifying RNA platform developers, and contract manufacturers with captive supply agreements. Capacity expansion and strategic partnerships constitute the dominant competitive moves as hospital networks demand guaranteed supply commitments.
Within the integrated manufacturing tier, Moderna, Inc. and BioNTech SE exemplify platform specialists with end-to-end supply chain control. Pfizer Inc. occupies a position leveraging commercial reach through established vaccine distribution infrastructure. These three entities represent divergent strategic postures: pure-play mRNA focus, deep oncology specialization, and diversified pharmaceutical scale.
| Leading Market Players |
|---|
| Moderna, Inc. |
| BioNTech SE |
| Pfizer Inc. |
| CureVac SE |
| GSK plc. |
| Sanofi |
| Arcturus Therapeutics |
| AIM Vaccine Corporation |
| Ethris GmbH |
| Others |
Cost & Logistics Intelligence
Specialized lipid chemists concentrated in Germany's Marburg-Dresden corridor command compensation premiums that compress standard-tier margins while widening spreads to premium formulations. Labor-cost differentials between European manufacturing clusters and emerging production sites in Asia-Pacific feed directly into three-tier pricing structures for lipid nanoparticle supply contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs mRNA manufacturing inputs, with ionizable lipid quality grades and FDA-tier certification status as primary differentiation drivers. Cost compression in standard-tier plasmid DNA sourcing is intensifying because hospital procurement committees now demand carbon-transparent supply chain documentation. Government stockpile buyers exhibit highest price sensitivity due to volume aggregation and tender-based competition, while oncology centers show lowest sensitivity for personalized neoantigen vaccines where manufacturing turnaround time dominates total cost.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal and Japan's METI funding programs are reshaping sourcing patterns for critical inputs, pushing pharmaceutical companies toward regional supplier qualification. Manufacturing draws from ionizable lipid specialists in Germany, plasmid DNA producers in the United States, and purification resin suppliers in Switzerland. Single-source vulnerability for proprietary lipid intellectual property concentrates with two specialty chemical manufacturers. Distribution runs through integrated delivery networks and group purchasing organizations that consolidate multi-hospital demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital formulary committees now prioritize suppliers with conditional marketing authorization pathways and carbon-transparent supply chains over pure price competition.
For Market Incumbents: Extend manufacturing platform coverage from infectious disease into oncology applications to defend against specialized neoantigen competitors. Secure captive supply agreements for ionizable lipids before contract renewal cycles, as single-source supplier concentration creates security-of-premium risk. Add capacity in German manufacturing clusters to capture EU Green Deal procurement preference.
For New Entrants and Emerging Players: Begin with self-amplifying RNA platform development targeting tropical disease applications where dose-sparing technology lowers cost-per-treatment thresholds. Japanese oncology networks offer the most penetrable geography due to underdeveloped formulary access for personalized vaccines. Pursue PMDA sakigake designation to accelerate reimbursement discussions ahead of commercial launch.
For Investors and Strategic Acquirers: Contract manufacturers with captive lipid supply agreements are the most active acquirer targets in this space, as integrated pharmaceutical operations seek backward control over proprietary formulation chemistry. The five-to-ten year viability window favors platform specialists with end-to-end quality control from plasmid DNA through finished drug product. Watch FDA-EMA convergence timelines on LNP characterization standards as the inflection signal for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Hospital networks demand guaranteed supply commitments before formulary inclusion. |
| Regulatory Approval Pathway | FDA accelerated approval and EMA adaptive licensing compress commercialization timelines. |
| Backward Integration | Control over ionizable lipid supply reduces single-source vulnerability and security premiums. |
| Licensing Agreement | Self-amplifying RNA technology access enables dose-sparing applications for tropical diseases. |
| Pipeline Diversification | Oncology neoantigen vaccines represent fastest-expanding category beyond established infectious disease programs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up manufacturing capacity estimates and top-down hospital demand projections were cross-referenced for triangulation.
Segment-weighting approaches applied analytical frameworks across product type, technology platform, end user category, and delivery mode dimensions throughout the forecast period. CAGRs were derived from modeled adoption curves for prophylactic vaccines and cancer treatments, incorporating regulatory pathway timelines and manufacturing scale-up constraints as industry-specific inputs.
Several conditions sit outside the modeled scope, including pandemic emergency authorization disruptions, breakthrough technology obsolescence, and raw material supply shocks beyond single-source lipid concentration. Forecasts reflect documented assumptions about regulatory convergence timelines and hospital infrastructure investment patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market