
 Stem Cell Concentration System Market | 2026-2036
Stem Cell Concentration System Market Size, Share, and Industry Trends Forecast 2026-2036
Stem Cell Concentration System Market Analytics
Closed-system automation is tilting the technology stack away from open manual processing toward sterile, GMP-compliant concentration platforms. STEMCELL Technologies leverages deep expertise in cell culture media to anchor its position in research-grade concentration workflows. Zimmer Biomet sustains orthopedic channel dominance by integrating concentration systems into its broader regenerative portfolio. Terumo Corporation navigates stringent Asian regulatory requirements with manufacturing scale across its Japanese production base.
A stem cell concentration system isolates, enriches, and harvests target cell populations from heterogeneous biological samples through controlled centrifugal force, membrane filtration, or immunomagnetic selection, typically achieving concentration factors of 10x to 50x while maintaining viability thresholds above 90% for downstream therapeutic applications. Automated systems command premium positioning due to their closed-loop architecture and compliance with current Good Manufacturing Practice standards for cell therapy production. Among applications, regenerative medicine occupies the deepest margin pools as hospital buyers prioritize traceability and batch consistency over capital cost, while cell therapy represents the fastest-growing segment driven by autologous treatment protocols.
FDA enforces current Good Tissue Practice and GMP guidelines that mandate validated concentration processes for investigational new drug submissions, while EMA's Advanced Therapy Medicinal Products framework imposes comparable manufacturing controls across Europe. Japan's PMDA operates accelerated approval pathways for regenerative products that reward sponsors with verified concentration and characterization methodologies. Stakeholders must monitor evolving ISO standards for automated cell processing equipment and align R&D roadmaps with emerging pharmacopoeial requirements for in-process control documentation.
Market Dynamics
Closed-system automation is compressing the competitive set around GMP-validated platforms, forcing manual processing equipment toward obsolescence as hospital networks and cell therapy manufacturers consolidate purchasing around traceable, batch-consistent workflows.
Growth Catalysts
- FDA current Good Tissue Practice:Mandates validated concentration processes for investigational new drug submissions, concentrating procurement among sponsors with compliant platform partnerships.
- Orthopedic regenerative procedures:Hospital networks in the United States and Germany are upgrading concentration capabilities to support autologous stem cell therapies for joint repair.
- Japan's PMDA accelerated approval pathways:Reward sponsors with verified concentration methodologies, pulling investment toward automated characterization systems.
Market Restraints
- Single-use consumable costs:Proprietary sterile kits and closed-loop disposables impose recurring operational burdens that compress margins for high-volume processing centers.
- Technical scalability limits:Existing membrane filtration systems face throughput ceilings below commercial cell therapy manufacturing volumes, constraining batch economics.
- EMA Advanced Therapy Medicinal Products compliance:Extensive validation documentation requirements extend commercialization timelines for novel concentration platforms.
Strategic Opportunities
- Point-of-care deployment in Germany:Ambulatory surgical centers remain undersupplied with compact, validated concentration systems for same-day orthopedic procedures.
- Convergence of microfluidic sorting with centrifugal concentration:Hybrid architectures promise 10x throughput improvements while preserving cell viability thresholds.
- India's CDSCO cell therapy framework:Emerging regulatory clarity creates first-mover positioning for GMP-compliant platform providers in domestic manufacturing partnerships.
Industry Challenges
- Cross-functional talent scarcity:Cell therapy manufacturing requires hybrid competencies combining bioprocessing engineering with regulatory affairs expertise that existing training pipelines undersupply.
- ISO 13485 certification timelines:Automated processing equipment faces 18-24 month quality management system validation cycles that delay product launches.
- Legacy LIMS integration:Hospital information systems and manufacturing execution platforms require custom middleware development for real-time concentration data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stem Cell Concentration System Market |
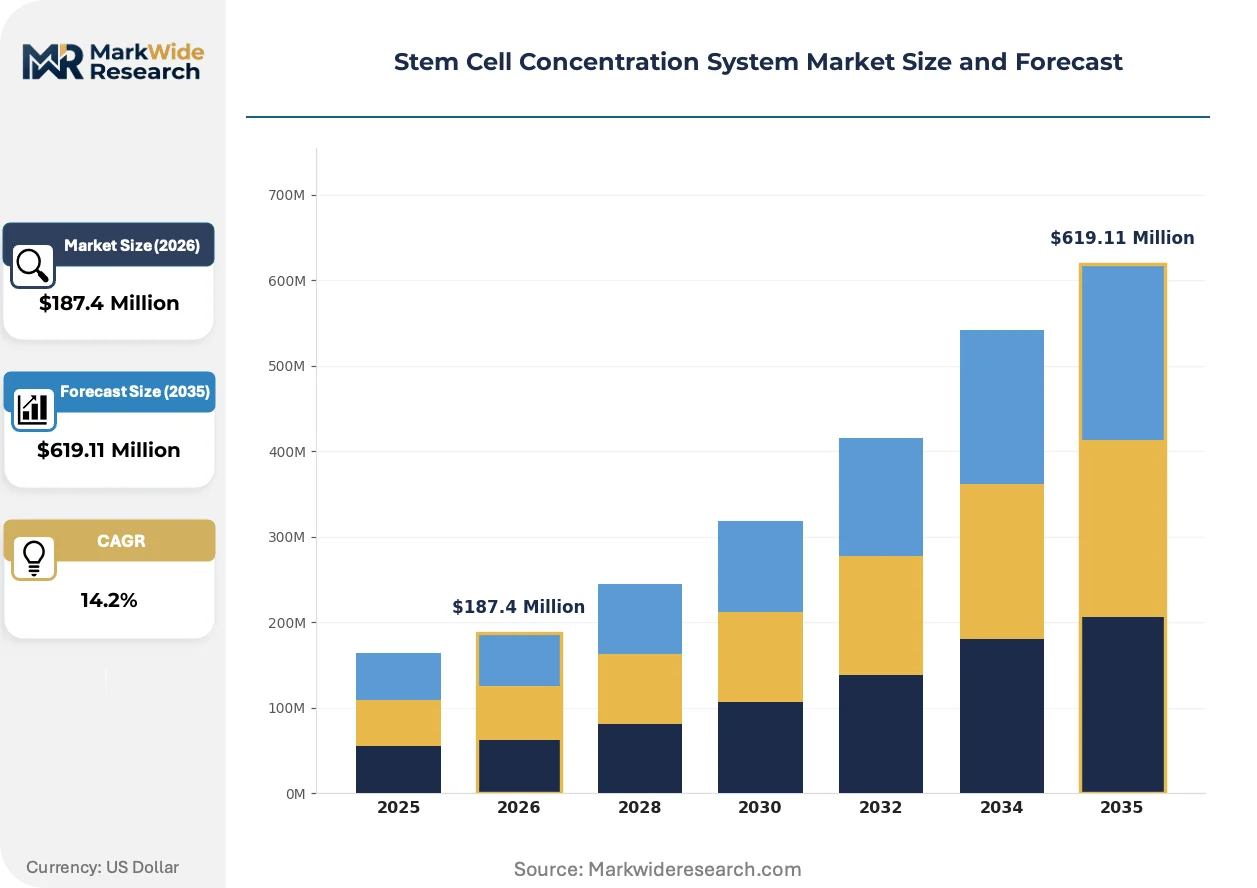
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Hybrid Systems, Single-Use Systems Application: Tissue Engineering, Regenerative Medicine, Drug Discovery, Cell Therapy End User: Biotechnology Companies, Research Laboratories, Hospitals, Academic Institutions Technology: Centrifugation, Filtration, Magnetic Separation, Immunomagnetic Techniques |
| Companies Covered | STEMCELL Technologies, Zimmer Biomet, Isto Biologics, Celling Biosciences, Arthrex, EmCyte Corporation, Harvest Technologies, Argos Technologies, Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stem Cell Concentration System Market Evolving Landscape
Automation architectures are bifurcating the installed base between research-grade open systems and clinical-scale closed platforms, with regulatory validation becoming the decisive purchasing criterion across hospital and biotech buyer segments.
Microfluidic concentration technology is hybridizing precision cell sorting with continuous-flow processing, enabling real-time viability monitoring that manual centrifugation cannot replicate. Academic medical centers in Boston and Heidelberg are piloting these platforms for autologous therapy protocols. The structural consequence is compressing equipment replacement cycles from seven years toward four as viability data becomes a competitive differentiator.
EMA's MDR Annex XVI expansion is reclassifying certain cell concentration devices as Class III medical products, triggering notified body involvement for previously self-certified equipment. Manufacturers serving European hospital networks must now submit clinical evidence packages that add 12-18 months to registration timelines. German orthopedic chains are responding by consolidating vendor relationships around established CE-marked platform providers.
Hospital procurement departments are unbundling capital equipment purchases from multi-year service contracts, compressing vendor margins on installation and training while expanding competitive bidding for maintenance. This pattern is most visible in United States academic medical centers where GPOs have standardized concentration platform specifications. Japanese university hospitals retain bundled purchasing, preserving integrated service economics for domestic equipment suppliers.
Stem Cell Concentration System Market Segmentation
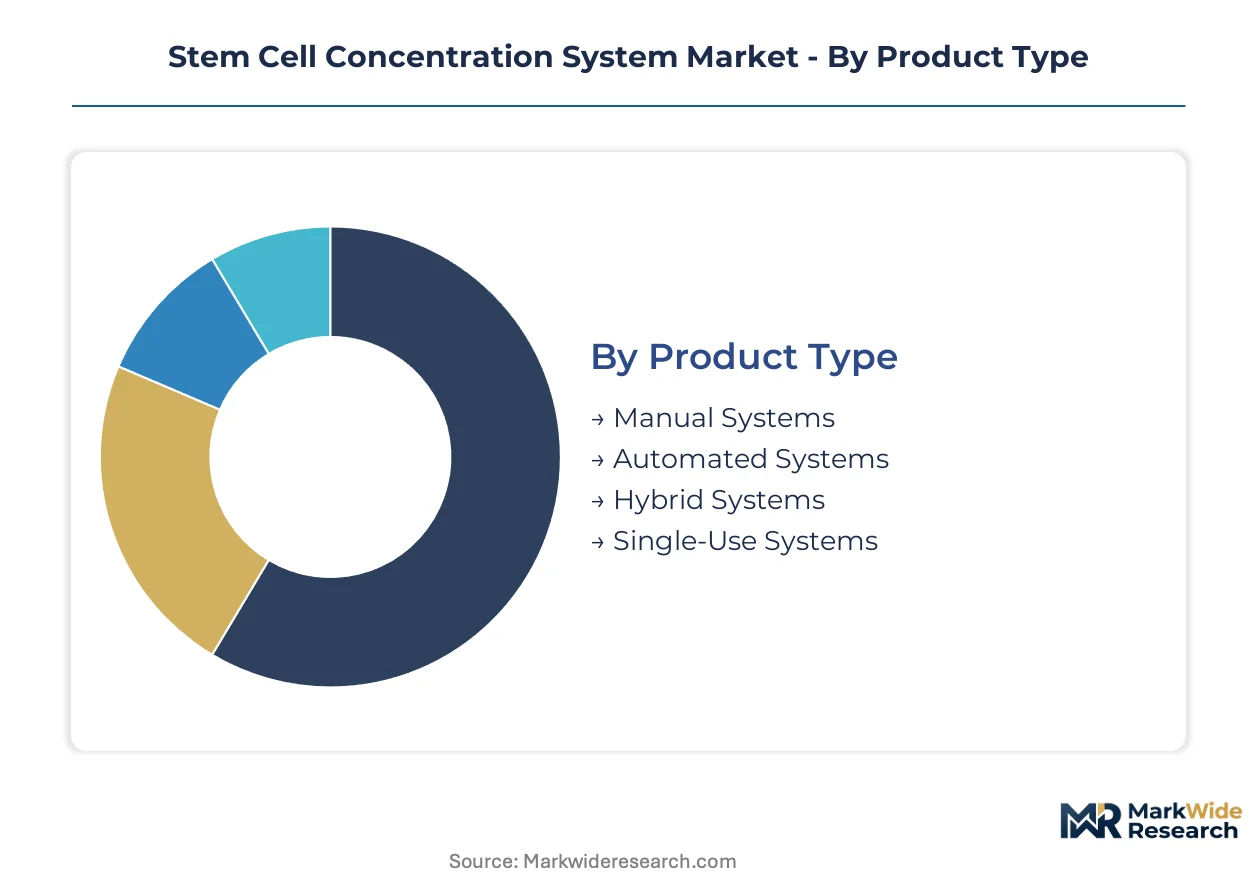
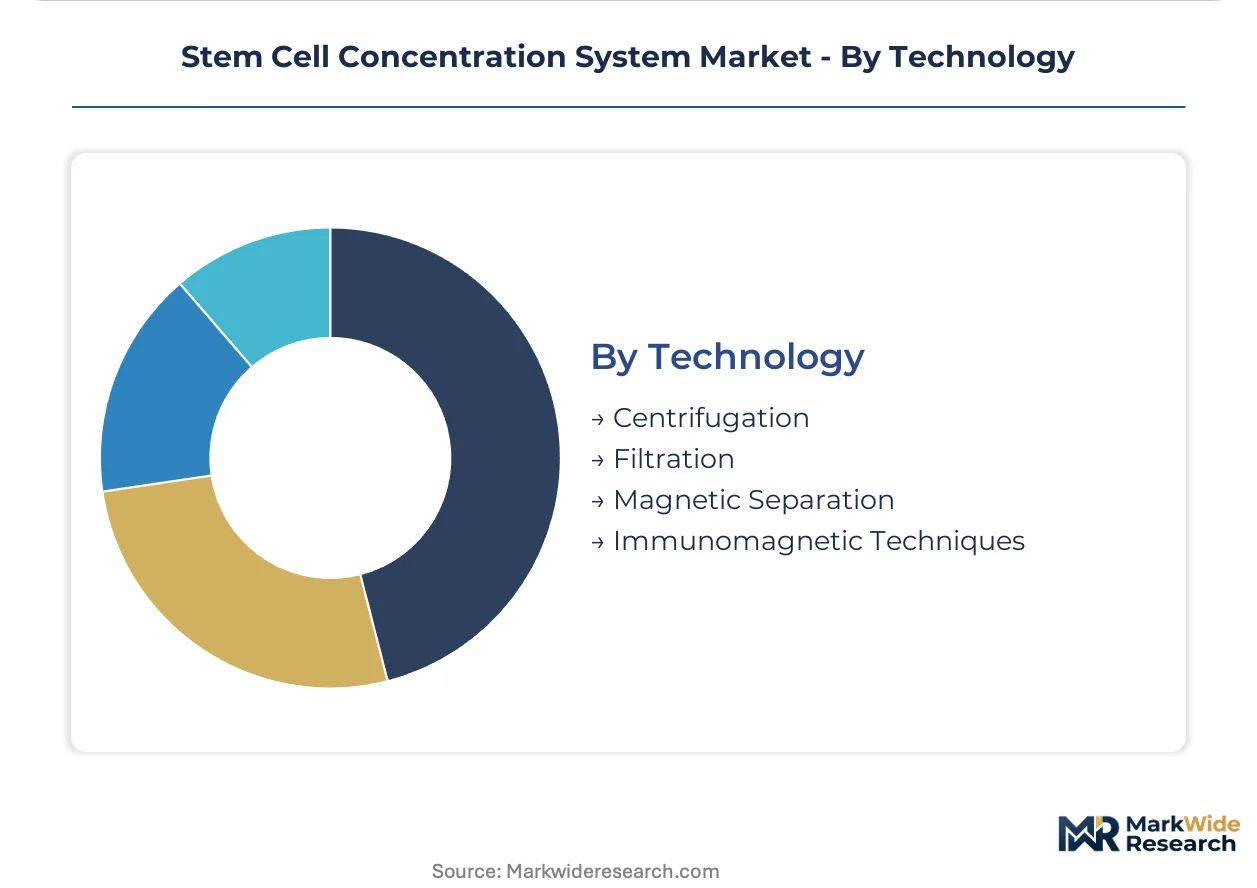
Stem cell concentration systems serve divergent operational environments, from research laboratories processing exploratory samples to commercial cell therapy manufacturers requiring GMP-validated batch consistency. Segmentation reveals how technology choices, end-user scale, and regulatory compliance requirements fragment purchasing criteria across the installed base.
Product Type:
Use-case spectrum spans exploratory research with intermittent processing demands through to commercial manufacturing requiring continuous validated operation.
- Automated Systems:Closed-loop architectures integrate centrifugal concentration with sterile fluid handling and real-time monitoring, achieving batch-to-batch reproducibility essential for FDA investigational new drug submissions. Hospital networks in the United States and Germany consolidate procurement around these platforms for orthopedic regenerative procedures.
- Manual Systems:Open-bench centrifugation and decanting workflows dominate academic settings where capital constraints outweigh traceability requirements. Research laboratories in Japan retain significant installed base for exploratory cell biology studies.
- Hybrid Systems:Semi-automated configurations balance throughput gains with operator intervention flexibility for process development environments.
- Single-Use Systems:Pre-sterilized disposable fluid paths eliminate cross-contamination risk for autologous therapy manufacturing.
The dominant share belongs to Automated Systems, while Single-Use Systems is closing the gap fastest.
Application:
Revenue concentration aligns with therapeutic maturity and reimbursement clarity across clinical versus preclinical environments.
- Regenerative Medicine:Orthopedic applications command premium positioning as hospital buyers prioritize traceability and batch consistency over capital cost for joint repair procedures. German ambulatory surgical centers drive point-of-care deployment demand.
- Cell Therapy:Autologous treatment protocols require patient-specific concentration workflows with validated characterization methodologies. Japan's PMDA accelerated approval pathways reward sponsors with verified concentration systems.
- Tissue Engineering:Scaffold seeding applications demand precise cell density control for construct uniformity.
- Drug Discovery:High-throughput screening relies on rapid sample processing with viability preservation for assay reliability.
Regenerative Medicine captures the largest revenue pool, though Cell Therapy is expanding most quickly.
End User:
Procurement authority and validation requirements diverge sharply between commercial manufacturing and exploratory research settings.
- Biotechnology Companies:Cell therapy manufacturers require GMP-compliant platforms with extensive documentation packages for EMA Advanced Therapy Medicinal Products submissions. These buyers concentrate demand for automated closed systems.
- Hospitals:Orthopedic departments in the United States academic medical centers upgrade concentration capabilities for same-day autologous procedures, with GPOs standardizing platform specifications.
- Research Laboratories:Exploratory studies prioritize flexibility and capital efficiency over regulatory validation.
- Academic Institutions:Grant-funded operations balance publication requirements with equipment cost constraints.
Biotechnology Companies lead segment value, while Hospitals is gaining share fastest.
Technology:
Processing physics determines throughput ceilings, cell viability thresholds, and scalability for commercial manufacturing volumes.
- Centrifugation:Differential density separation remains the workhorse technology, achieving concentration factors of 10x to 50x with viability thresholds above 90%. Continuous-flow centrifugal systems face throughput ceilings below commercial cell therapy manufacturing volumes.
- Magnetic Separation:Immunomagnetic bead-based selection enables target population purity unattainable through physical separation alone. Academic medical centers in Boston pilot hybrid microfluidic-magnetic platforms for autologous therapy protocols.
- Filtration:Membrane-based concentration suits large-volume processing with gentle shear profiles for sensitive cell types.
- Immunomagnetic Techniques:Antibody-coated magnetic particle selection achieves specificity for rare cell populations in research applications.
Centrifugation holds the dominant technology position, while Magnetic Separation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and biotech manufacturers concentrate demand across four national markets where regulatory validation and GMP compliance determine vendor selection.
United States
FDA current Good Tissue Practice mandates validated concentration processes for investigational new drug submissions, concentrating procurement among sponsors with compliant platform partnerships. Academic medical centers in Boston upgrade concentration capabilities for same-day autologous orthopedic procedures. Greater Boston's biotech corridor pilots hybrid microfluidic-magnetic platforms for autologous therapy protocols.
Germany
EMA's Advanced Therapy Medicinal Products framework imposes extensive manufacturing controls that extend commercialization timelines for novel concentration platforms. Ambulatory surgical centers remain undersupplied with compact, validated concentration systems for same-day orthopedic procedures. Heidelberg's university hospitals drive point-of-care deployment demand for regenerative joint repair.
Japan
PMDA accelerated approval pathways reward sponsors with verified concentration and characterization methodologies, pulling investment toward automated systems. METI standards govern manufacturing scale across domestic production bases. Tokyo's university hospitals retain bundled purchasing patterns, preserving integrated service economics for domestic equipment suppliers.
India
CDSCO cell therapy framework creates first-mover positioning for GMP-compliant platform providers in domestic manufacturing partnerships. Hospital networks upgrade concentration workflows to support emerging autologous treatment protocols. Maharashtra's biotech clusters develop exploratory cell biology studies with research-grade open systems.
Switzerland
Swissmedic enforces comparable manufacturing controls to EMA for cell therapy production, requiring extensive documentation packages for commercial approval. Precision manufacturing traditions support equipment quality validation. Basel's pharmaceutical corridor concentrates demand for traceable, batch-consistent concentration workflows.
Stem Cell Concentration System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three tiers: orthopedic device conglomerates with regenerative portfolios, bioprocessing equipment multinationals with Asian manufacturing scale, and cell culture media specialists leveraging research-grade workflow expertise. M&A activity consolidates point-of-care capabilities into broader regenerative medicine platforms. Strategic partnerships between equipment vendors and hospital GPOs standardize procurement specifications.
Within the research-grade workflow tier, STEMCELL Technologies anchors expertise in cell culture media applications. Zimmer Biomet occupies a position among orthopedic channel controllers with regenerative portfolio integration. Terumo Corporation exemplifies Asian manufacturing scale navigating stringent regulatory requirements. These three represent distinct archetypes: media-specialist, orthopedic-conglomerate, and Asian-scale multinational.
| Leading Market Players |
|---|
| STEMCELL Technologies |
| Zimmer Biomet |
| Isto Biologics |
| Celling Biosciences |
| Arthrex |
| EmCyte Corporation |
| Harvest Technologies |
| Argos Technologies, Inc. |
| Terumo Corporation |
| Others |
Value Network & Pricing Analysis
Japanese precision manufacturing clusters anchor sterile component supply for closed-system concentration platforms, concentrating margin capture among GMP-validated equipment tiers while manual processing equipment faces commoditization pressure from research-grade buyers.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate automated system procurement, particularly for single-use sterile kits where polymer feedstock volatility passes through to hospital networks. Pricing stratifies across GMP-certified premium platforms, validated standard systems, and research-grade economy configurations. Cost compression in manual equipment intensifies as biotechnology companies consolidate purchasing around traceable automated workflows. Academic medical centers exhibit highest price sensitivity, while cell therapy manufacturers prioritize batch consistency over capital expenditure.
Supply Chain Analysis
Upstream feedstock for sterile disposables draws from Japanese polymer processing, German precision engineering, and United States medical-grade tubing fabrication. Critical dependencies include fluoropolymer membranes, medical-grade stainless steel, and electromagnetic drive components. Single-source vulnerability concentrates in membrane filtration substrates where qualified alternative suppliers require 18-month validation cycles. Distribution runs through orthopedic device distributors for hospital networks and direct manufacturer relationships for commercial cell therapy producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in stem cell concentration systems hinge on interoperability between concentration hardware and hospital information systems, with Boston's academic medical centers piloting real-time data integration that rewards vendors with validated middleware capabilities.
For Market Incumbents: Build regulatory certification moats by accelerating FDA Master File submissions and EMA Design Dossier completions ahead of MDR Annex XVI reclassifications. Capacity addition in Heidelberg's orthopedic corridor captures point-of-care deployment demand. Channel control through GPO exclusivity agreements defends against emerging microfluidic entrants.
For New Entrants and Emerging Players: Build out ambulatory surgical center presence in Germany's same-day orthopedic procedure segment, where compact validated systems remain undersupplied. India's CDSCO framework creates penetrable regulatory entry for GMP-compliant platform partnerships. Go-to-market through domestic manufacturing joint ventures bypasses established distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid technology specialists combining microfluidic precision with centrifugal throughput, positioned for viability-data differentiation. Long-term viability across the analysis window rests on middleware integration capabilities rather than hardware specifications alone. Watch for ISO 13485 certification completion rates as inflection signal for commercial readiness timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Annex XVI reclassification demands clinical evidence packages extending registration timelines for European market access. |
| Hospital System Partnership | GPO standardization at United States academic medical centers locks in multi-year concentration platform specifications. |
| Software Companion Development | Real-time viability monitoring middleware differentiates automated systems in Boston's autologous therapy pilot programs. |
| FDA Submission | Investigational New Drug enabling studies require validated concentration process documentation for cell therapy sponsors. |
| Reimbursement Strategy | Japan's PMDA accelerated approval pathways reward sponsors with verified concentration methodologies for regenerative products. |
Research Methodology
The analysis maps automated closed systems, manual open platforms, hybrid configurations, and single-use disposables, each validated through biomedical engineers, hospital GPO contracts managers, regulatory affairs leads, and cell therapy manufacturing directors. Primary interviews with these stakeholders combined with secondary triangulation across FDA 510(k) filings, EMA Design Dossier databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up equipment shipment data and top-down therapeutic procedure volumes were reconciled.
Assumptions held fixed include current FDA Good Tissue Practice enforcement intensity and EMA Advanced Therapy Medicinal Products compliance timelines, while variables spanned autologous therapy protocol adoption rates and microfluidic technology maturation. Segmentation dimensions modeled encompass product architecture, therapeutic application, end-user scale, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to equipment replacement cycles and concentration throughput scaling factors.
Stress conditions across PMDA approval pathway utilization, single-use consumable cost trajectories, and membrane filtration throughput ceilings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledgment that ISO standard revisions or notified body capacity constraints could materially revise projections. Cross-checking against hospital capital expenditure surveys and cell therapy manufacturing capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Oncolytic Adenovirus Market