
 Induced Pluripotent Stem Cells Production Market | 2026-2036
Induced Pluripotent Stem Cells Production Market Size, Share, and Industry Trends Forecast 2026-2036
Induced Pluripotent Stem Cells Production Market Intelligence
Automated bioreactor systems and serum-free culture media formulations is rewriting the economics of iPSC manufacturing, collapsing per-batch variability while steepening quality thresholds. FUJIFILM Cellular Dynamics leverages its Madison, Wisconsin production campus to anchor North American supply of clinical-grade iPSC lines for drug developers. Lonza sustains one of the broadest GMP-compliant manufacturing footprints, spanning Basel and Singapore facilities that serve contract cell therapy programs. Thermo Fisher Scientific dominates the upstream reagent layer, controlling distribution channels that reach into most research laboratories worldwide.
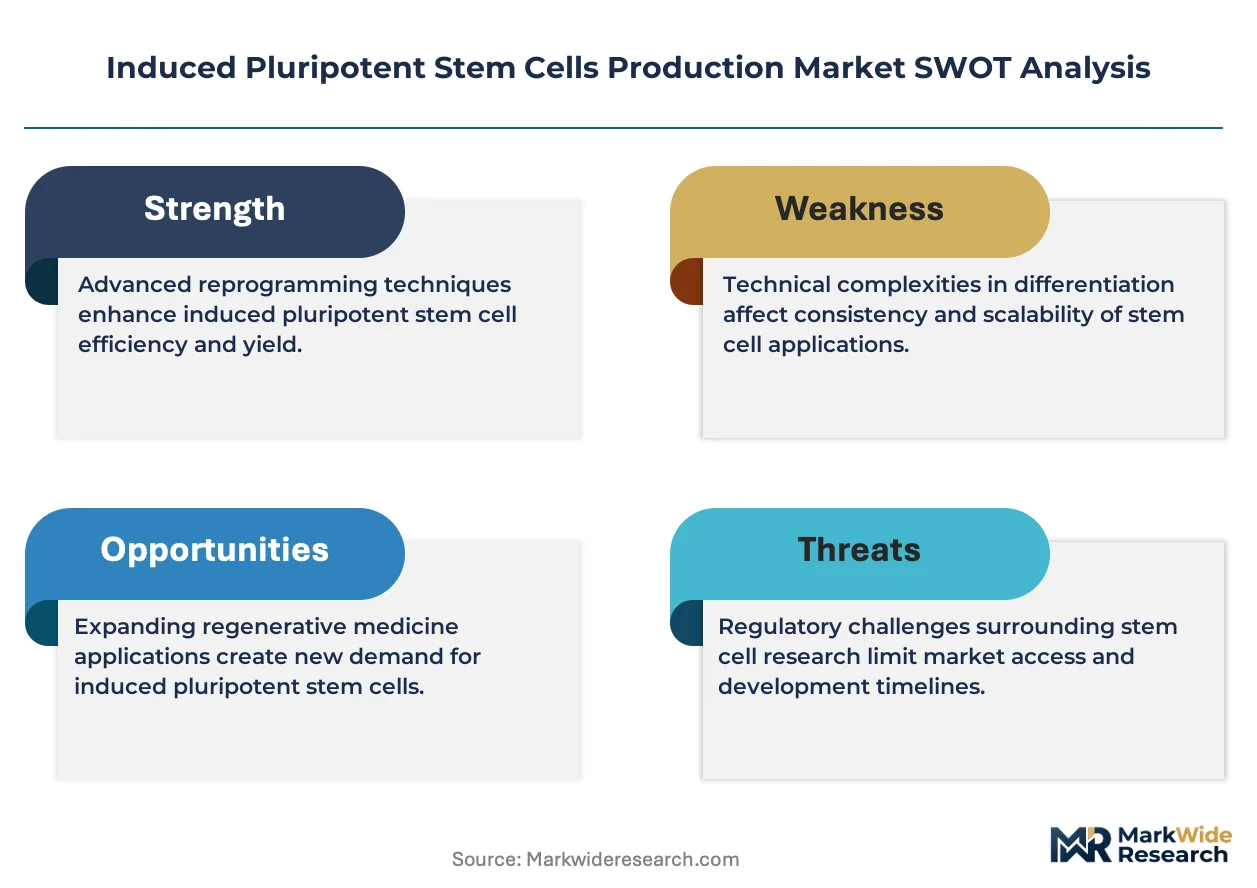
Induced pluripotent stem cells are somatic cells reprogrammed to a pluripotent state through forced expression of transcription factors, typically Oct4, Sox2, Klf4, and c-Myc, enabling differentiation into any human cell type for research or therapeutic applications. The technology dimension shows electroporation and small-molecule reprogramming methods gaining ground against legacy virus-based delivery, driven by residual DNA integration concerns that regulators flag during IND reviews. Among applications, regenerative medicine commands the deepest value pools as developers advance iPSC-derived tissues toward clinical validation, while drug discovery retains the widest installed base across biotechnology companies and pharmaceutical firms.
The FDA enforces Current Good Tissue Practice and Good Manufacturing Practice standards that dictate facility design, donor traceability, and release testing for iPSC-derived products entering clinical trials. The EMA's ATMP framework and Japan's PMDA regenerative medicine guidelines create parallel compliance architectures that multinational sponsors must navigate simultaneously. Stakeholders should monitor how emerging ISO standards for stem cell characterization reshape supplier qualification criteria and procurement patterns across the production ecosystem.
Market Dynamics
The FDA's evolving guidance on cell therapy manufacturing is accelerating compliance investments across the iPSC value chain, forcing producers to reconfigure facility designs and quality systems before clinical entry.
Growth Catalysts
- Regenerative medicine demand:Pharmaceutical firms are channeling capital into disease-specific iPSC lines for cardiac, neural, and ocular tissue programs. This pulls manufacturing capacity toward GMP-grade production.
- Electroporation methods:Non-viral reprogramming technologies are displacing legacy lentiviral vectors, addressing residual DNA integration concerns that regulators flag during IND reviews.
- Boston-San Diego corridor:Clustered biotech hubs in these cities anchor both research-scale and commercial iPSC production, concentrating talent and infrastructure investment.
Market Restraints
- Serum-free media costs:Defined culture formulations command 3-5x premium over fetal bovine serum, compressing margins for research-grade producers.
- Donor traceability requirements:FDA Current Good Tissue Practice mandates extensive documentation chains, extending qualification timelines for new cell lines.
- Allogeneic immunology:iPSC-derived tissues face rejection risks that autologous approaches avoid, limiting addressable patient populations for off-the-shelf products.
Strategic Opportunities
- Japan's PMDA regenerative medicine framework:Accelerated approval pathways for iPSC-derived therapies create first-mover advantages for sponsors establishing local manufacturing.
- Organoid applications:Three-dimensional tissue models for toxicology screening represent underpenetrated demand from contract research organizations.
- ISO stem cell characterization standards:Emerging quality benchmarks will reshape supplier qualification criteria, rewarding early adopters with preferred vendor status.
Industry Challenges
- GMP facility commissioning:Cell therapy suites require 18-24 month buildout cycles with specialized HVAC and environmental monitoring systems.
- Reprogramming consistency:Batch-to-batch variability in transcription factor expression complicates process validation for regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Induced Pluripotent Stem Cells Production Market |
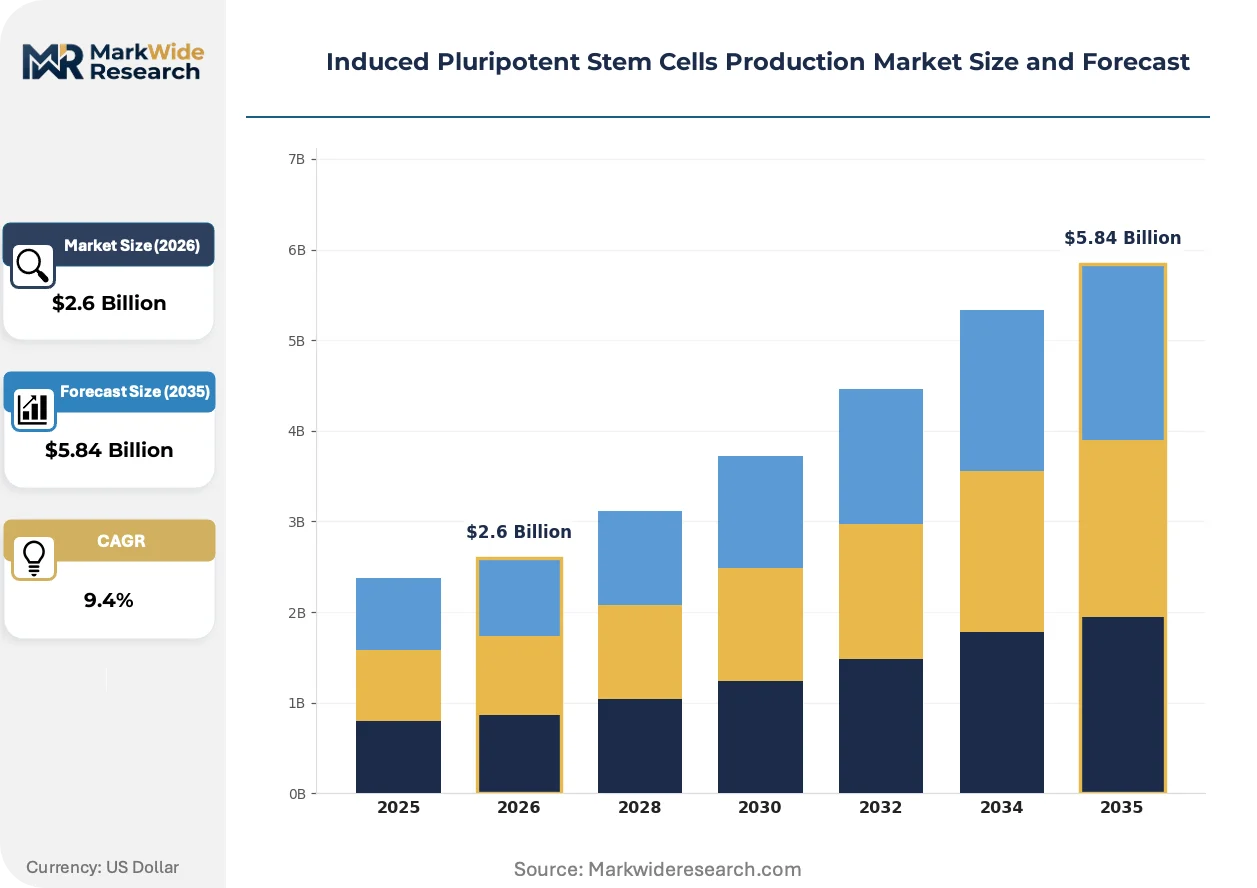
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Media, Reagents, Kits, Equipment End User: Research Laboratories, Biotechnology Companies, Pharmaceutical Firms, Academic Institutions Application: Drug Discovery, Disease Modeling, Regenerative Medicine, Toxicology Testing Technology: Transfection, Electroporation, Virus-Based Delivery, Small Molecules |
| Companies Covered | FUJIFILM Cellular Dynamics, Lonza, Thermo Fisher Scientific, Axol Bioscience, Evotec, REPROCELL, Fate Therapeutics, Ncardia, Applied StemCell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Induced Pluripotent Stem Cells Production Market Strategic Shifts & Innovations
Automated manufacturing platforms and defined culture systems are collapsing the cost structure of clinical-grade iPSC production while steepening quality thresholds for market entry.
Closed-system bioreactors with integrated perfusion control are collapsing per-batch labor requirements and contamination risk profiles. Mid-scale cell therapy developers are adopting these platforms to bridge research and GMP phases without facility rebuilds. The technology is collapsing the traditional scale-up barrier that forced sponsors into expensive CDMO relationships.
EMA's ATMP framework revisions are tightening comparability requirements for iPSC-derived products manufactured across multiple sites. Sponsors must now demonstrate analytical equivalence between production batches from different facilities. European developers are responding by consolidating manufacturing within single-campus architectures rather than distributed networks.
Pharmaceutical procurement teams are unbundling reagent sourcing from equipment purchasing, creating direct relationships with specialty media suppliers. Thermo Fisher's historical channel dominance faces erosion as buyers negotiate serum-free formulation contracts separately from instrumentation. This pattern is most visible among Boston-area biotechs with dedicated cell therapy sourcing functions.
Induced Pluripotent Stem Cells Production Market Segmentation
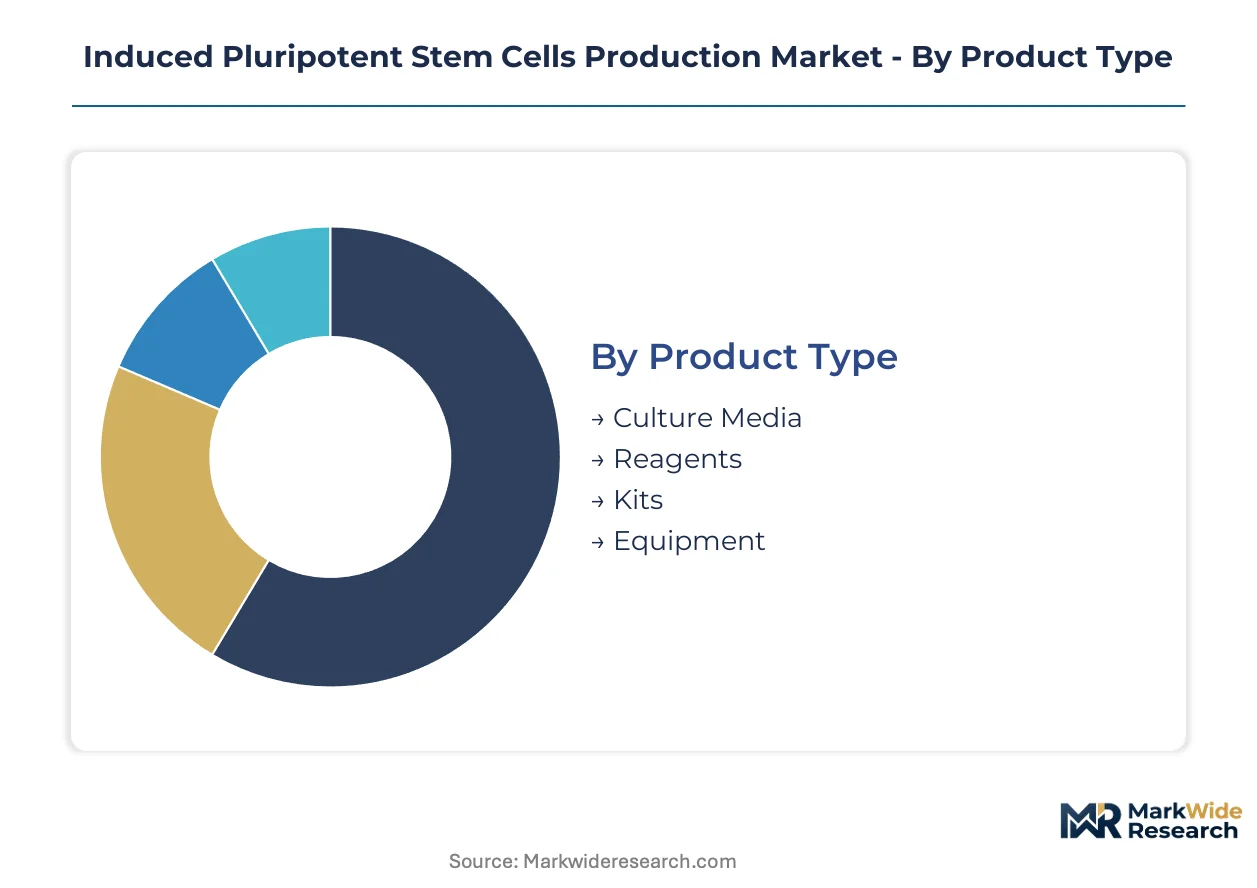
iPSC production segments exhibit divergent inventory velocities and margin profiles, with consumables turning monthly while capital equipment cycles span years. Understanding these turnover patterns clarifies where procurement budgets concentrate versus where long-term vendor relationships form.
Product Type:
Cycle times range from single-batch consumables to decade-scale equipment investments, creating distinct purchasing rhythms across the production stack.
- Culture Media:Serum-free and defined formulations require fresh preparation or frozen aliquoting every 48-72 hours during active culture expansion. Pharmaceutical sponsors in the Boston corridor now specify chemically defined media in master cell bank protocols, locking suppliers into multi-year formulation contracts.
- Reagents:Antibodies, growth factors, and matrix proteins stabilize cell identity during directed differentiation. Academic core facilities in San Diego report 20-30% annual budget growth for reprogramming-grade cytokines as group size expands.
- Kits:All-in-one reprogramming systems compress technical barriers for laboratories lacking vector production capabilities.
- Equipment:Bioreactors, electroporation systems, and automated cell handlers anchor facility capital planning with 7-10 year depreciation schedules.
Culture media anchors the volume base while reagents gain share at the steepest rate.
End User:
Customer sophistication tiers separate protocol developers from protocol adopters, with procurement authority residing at different organizational levels.
- Research Laboratories:Individual principal investigators control smaller budgets but drive early method validation that shapes downstream standardization.
- Biotechnology Companies:Venture-backed cell therapy developers concentrate in Madison, Wisconsin and Basel, Switzerland corridor, outsourcing GMP manufacturing while retaining process development internally.
- Pharmaceutical Firms:Merck, Roche, and Takeda maintain dedicated iPSC groups that qualify suppliers through extensive analytical comparability studies before clinical entry.
- Academic Institutions:Stanford, Kyoto University, and Cambridge University stem cell institutes train technical workforce while publishing open-source differentiation protocols.
Pharmaceutical firms anchor the volume base while biotechnology companies expand most quickly as cell therapy pipelines mature.
Application:
Value capture potential varies dramatically across the research-to-clinic continuum, with regulatory burden scaling nonlinearly.
- Drug Discovery:High-throughput screening platforms consume iPSC-derived cardiomyocytes and neurons in 384-well formats for liability prediction. Novartis and AstraZeneca have replaced animal models with human iPSC systems for early safety pharmacology.
- Disease Modeling:Patient-specific lines recapitulate monogenic disorders in vitro, enabling mechanism studies impossible in animal systems. Cystic fibrosis and cardiac channelopathy programs at University of California, San Francisco leverage these models for target identification.
- Regenerative Medicine:Clinical-grade tissues face FDA Current Good Tissue Practice and GMP compliance requirements that multiply production costs tenfold over research grade.
- Toxicology Testing:Hepatocyte and cardiac platforms support regulatory submission packages for new chemical entities, with European Medicines Agency guidance increasingly accepting iPSC-derived data.
Drug discovery anchors the volume base while regenerative medicine climbs the fastest toward commercial realization.
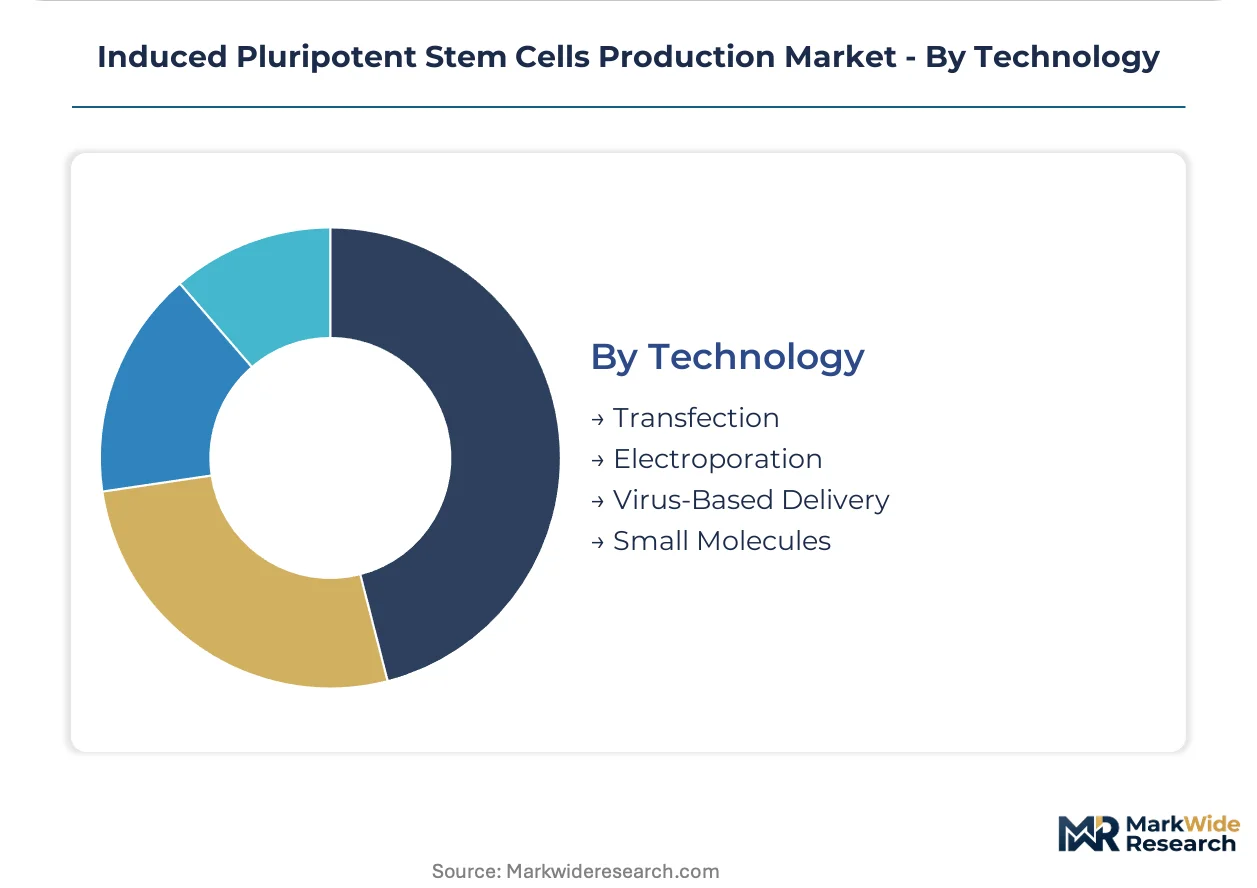
Technology:
Reprogramming modality selection commits producers to specific regulatory pathways and intellectual property positions.
- Transfection:Lipid-based and polymer systems deliver episomal vectors with moderate efficiency but simple workflow integration.
- Electroporation:High-voltage pulse systems achieve superior transfection efficiency in feeder-free culture conditions. Lonza's Nucleofector platform dominates installed base in European contract development facilities.
- Virus-Based Delivery:Lentiviral and Sendai virus systems retain residual DNA integration risks that FDA reviewers flag during IND safety assessments.
- Small Molecules:Chemical reprogramming avoids genetic manipulation entirely, potentially streamlining regulatory review but requiring extended timeline optimization.
Electroporation anchors the volume base while small molecules gain share fastest as integration-free requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsors and biotechnology developers concentrate procurement authority in clustered innovation hubs where regulatory familiarity and technical workforce availability intersect. Facility investment patterns track FDA, EMA, and PMDA guidance evolution, with sponsors prioritizing jurisdictions offering accelerated clinical pathways.
United States
Regenerative medicine venture financing and pharmaceutical R&D budgets drive demand for clinical-grade iPSC lines. FDA Current Good Tissue Practice and evolving cell therapy manufacturing guidance enforce facility design standards that extend commissioning timelines. The Boston-San Diego corridor anchors both research-scale production and commercial GMP capacity, with Madison, Wisconsin emerging as a secondary manufacturing hub.
Japan
PMDA's regenerative medicine framework offers accelerated approval pathways that attract multinational sponsors establishing local manufacturing. METI funding programs support domestic iPSC banking infrastructure and standardization initiatives. The Kansai region, centered on Osaka and Kyoto, concentrates academic stem cell institutes and translational research facilities with strong ties to clinical centers.
Germany
EMA's ATMP framework and tightening comparability requirements drive consolidation of multi-site manufacturing into single-campus architectures. Federal research funding through the DFG supports academic-industry consortia in cell therapy process development. The Basel-Mannheim corridor hosts contract development organizations serving European pharmaceutical sponsors with GMP-compliant iPSC manufacturing.
Switzerland
Swissmedic's alignment with EMA standards enables seamless access to European markets while maintaining independent regulatory credibility. Federal innovation programs under Innosuisse support biotechnology scale-up from academic spinouts. The Basel metropolitan area concentrates pharmaceutical headquarters and specialized CDMO capacity for cell therapy manufacturing.
Singapore
Economic Development Board incentives and biomedical sciences initiative funding attract multinational cell therapy manufacturers establishing Asia-Pacific supply nodes. Health Sciences Authority's regulatory convergence with FDA and EMA standards facilitates parallel submission strategies. Tuas Biomedical Park hosts dedicated cell therapy manufacturing zones with specialized infrastructure and workforce training programs.
Induced Pluripotent Stem Cells Production Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. Reagent distributors with global logistics networks face erosion from direct procurement relationships between pharmaceutical sponsors and specialty media formulators. The market structure separates upstream consumables suppliers, midstream manufacturing service providers, and downstream therapeutic developers. Strategic moves concentrate on GMP facility commissioning, electroporation technology licensing, and geographic expansion into PMDA-accelerated jurisdictions.
Within the integrated manufacturing tier, FUJIFILM Cellular Dynamics and Lonza exemplify archetypes combining production infrastructure with regulatory expertise. Thermo Fisher Scientific occupies a position representing channel-controlling upstream supply. These three entities anchor competitive dynamics across research-grade and clinical-grade market segments, with their geographic footprints spanning Madison, Basel, and distributed global distribution networks.
| Leading Market Players |
|---|
| FUJIFILM Cellular Dynamics |
| Lonza |
| Thermo Fisher Scientific |
| Axol Bioscience |
| Evotec |
| REPROCELL |
| Fate Therapeutics |
| Ncardia |
| Applied StemCell |
| Others |
Cost & Logistics Intelligence
Thermo Fisher Scientific's upstream control over reagent distribution channels concentrates margin capture at the consumables layer, forcing downstream bioreactor manufacturers and cell therapy developers into price-taker positions on standardized inputs while premium pools accrue to GMP-grade media formulators with direct pharmaceutical relationships.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate serum-free media procurement between specialty suppliers and pharmaceutical sponsors. Three-tier pricing structure across GMP-certified, research-grade, and basic formulations separates clinical-compliant batches from exploratory production. Pricing pressure stems from biotechnology companies consolidating vendor panels to secure volume discounts on defined culture systems. Academic core facilities exhibit highest price sensitivity, while pharmaceutical firms with dedicated cell therapy programs prioritize batch consistency over per-unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates raw material sourcing decisions for growth factors and recombinant proteins. Manufacturing concentration in Switzerland, Singapore, and United States anchors GMP-compliant iPSC production capacity. Supply chains draw from Chinese recombinant protein foundries, German precision instrumentation suppliers, and Japanese cell banking infrastructure. Single-source vulnerability persists for clinical-grade electroporation systems with limited qualified alternatives. Distribution runs through direct procurement relationships with pharmaceutical sponsors, bypassing traditional research distributor channels for high-volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical sponsors with dedicated cell therapy procurement functions, fragmenting the vendor landscape as biotechnology companies consolidate supplier panels and demand analytical comparability guarantees before clinical entry.
For Market Incumbents: Entrench GMP facility footprints in Madison and Basel through capacity additions that match pharmaceutical sponsor qualification timelines. Deepen backward integration into serum-free media formulation to capture margin pools escaping to specialty chemical suppliers. Defend against emerging electroporation technology licensors by locking in multi-year service contracts with installed-base customers. For New Entrants and Emerging Players: Organoid toxicology screening services for contract research organizations in Boston and San Diego represent the most penetrable entry point, with unmet demand for iPSC-derived liver and cardiac platforms. Japan's PMDA-accelerated manufacturing zones offer regulatory arbitrage for GMP-compliant production without FDA facility inspection backlogs. Partner with academic stem cell institutes for protocol validation that transfers to commercial sponsorship. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed biotechnology developers that have completed process validation but lack capital for Phase I manufacturing campaigns. Five-to-ten year viability hinges on successful navigation of FDA comparability requirements for multi-site production. Watch for EMA ATMP framework revisions tightening analytical equivalence standards as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Commissioning | FDA Current Good Tissue Practice compliance separates clinical-grade from research-grade producers. |
| Electroporation Technology Licensing | Non-viral reprogramming patents address residual DNA integration concerns flagged in IND reviews. |
| Serum-Free Media Formulation Contracts | Direct pharmaceutical procurement relationships erode Thermo Fisher's historical channel dominance. |
| Japan Manufacturing Footprint Expansion | PMDA accelerated approval pathways reward first-mover sponsors with local GMP capacity. |
| ISO Stem Cell Characterization Adoption | Emerging quality benchmarks reshape supplier qualification criteria across procurement panels. |
Research Approach
A spread of perspectives from cell therapy process development heads, regulatory affairs leads at multinational sponsors, GMP facility quality directors, and academic stem cell institute directors converged on the working assumptions. Primary interviews combined with secondary validation against FDA guidance documents, EMA ATMP framework revisions, PMDA regenerative medicine submissions, and ClinicalTrials.gov cell therapy protocols. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocations across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling consumption by product type, end user sophistication tier, application regulatory burden, and reprogramming technology modality. CAGRs derived from segment-level growth rate reconciliation with overall market expansion. Forecast inputs incorporated pharmaceutical sponsor pipeline maturity assessments and GMP facility commissioning timelines without year-specific project scheduling.
Macroeconomic conditions sit as an overlay; deviation in venture capital availability for cell therapy developers or NIH regenerative medicine funding levels would shift the trajectory. Forecasts reflect documented assumptions on regulatory approval pathway durations and electroporation technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market