
 Europe Cancer Vaccines Market | 2026-2036
Europe Cancer Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cancer Vaccines Market Foresight
Subscription-based patient monitoring and biomarker tracking services is pivoting cancer vaccine delivery from one-time administration to longitudinal care models. Bristol-Myers Squibb leverages its immuno-oncology infrastructure to bundle vaccine therapies with post-treatment surveillance programs. BioNTech anchors mRNA manufacturing scale across German production sites, sustaining supply security for personalized neoantigen platforms. Merck & Co. Inc. differentiates through companion diagnostic integration, controlling patient selection workflows that determine therapeutic vaccine eligibility.
Cancer vaccines are biologics designed to stimulate antigen-specific T-cell responses against tumor-associated antigens, typically formulated as peptide, nucleic acid, or cellular products requiring cold-chain distribution at minus 70 degrees Celsius for mRNA formats. Their primary purpose is to prevent recurrence or eradicate residual disease in patients with minimal residual burden after standard therapy. Therapeutic vaccines and autologous vaccines command premium positioning due to manufacturing complexity and patient-specific production requirements, while preventive vaccines maintain broader addressable populations through standardized HPV-targeted formulations. Intravenous and subcutaneous administration routes dominate clinical practice, though intramuscular delivery is gaining traction for mRNA platforms based on immunogenicity profiles.
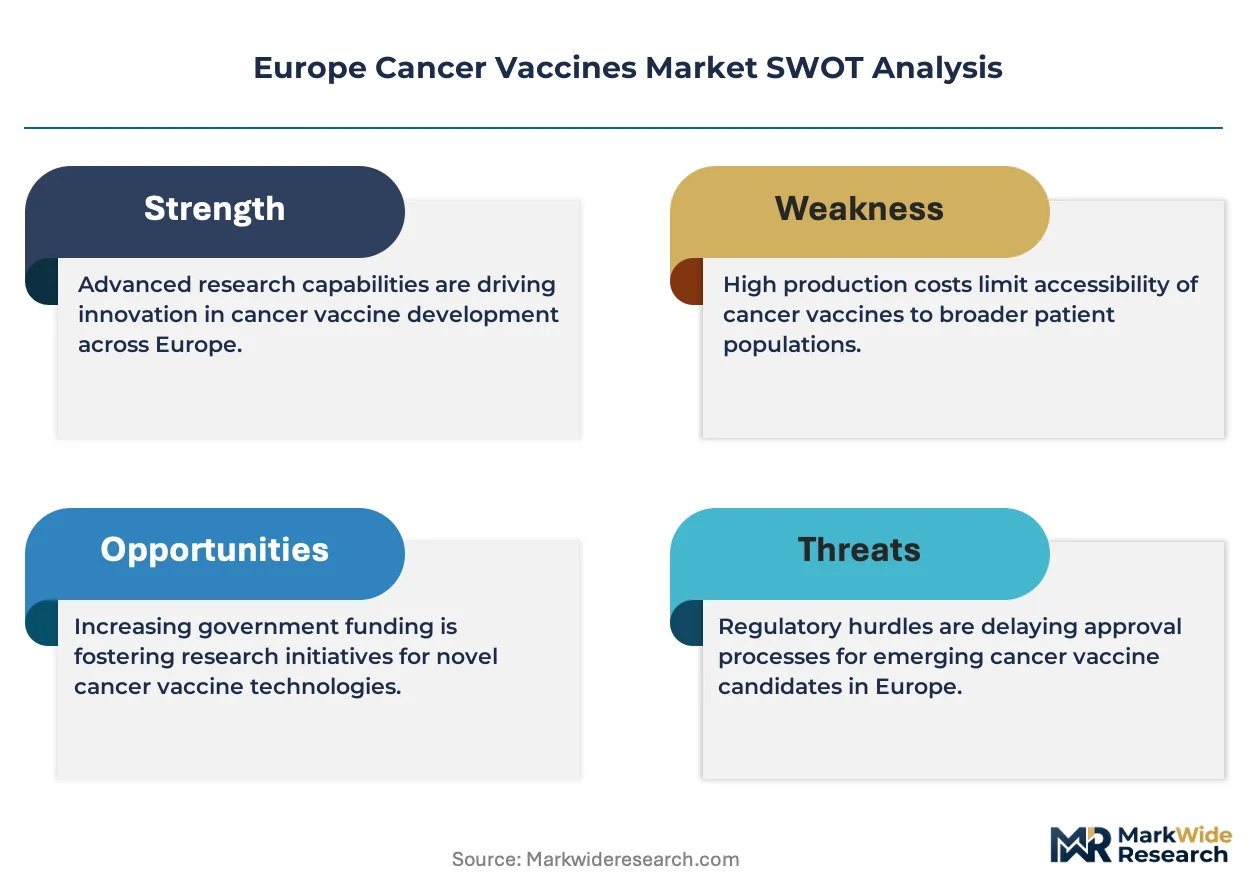
EMA's centralized marketing authorization procedure governs pan-European commercial access, while the EU AI Act introduces documentation requirements for algorithm-driven patient stratification tools used in vaccine trials. Germany's national reimbursement authority, the G-BA, evaluates oncology innovation through early benefit assessments that shape pricing and hospital procurement decisions. France's HAS and Italy's AIFA apply parallel health technology assessment frameworks that create fragmented market access timelines across major EU markets. Stakeholders must monitor evolving EU pharmaceutical legislation on data exclusivity and the European Health Data Space's impact on real-world evidence generation for adaptive vaccine licensing.
Market Dynamics
The EU's Clinical Trials Regulation harmonization is compressing multi-country study timelines, pulling oncology centers toward therapeutic vaccine adoption as checkpoint inhibitor complements reshape treatment protocols across university hospital networks.
Growth Catalysts
- EMA Centralized Marketing Authorization:The pan-European approval pathway accelerates commercial access across member states, reducing fragmentation that previously stalled cross-border patient recruitment.
- mRNA Manufacturing Scale-Up:German production sites now anchor continent-wide supply security for personalized neoantigen platforms, enabling patient-specific production at viable unit economics.
- University Hospital Networks:Germany's immuno-oncology infrastructure supports complex patient stratification workflows, creating concentrated demand nodes that validate therapeutic vaccine efficacy data.
Market Restraints
- Ultra-Low Temperature Cold Chain:Minus 70 degrees Celsius distribution requirements for mRNA formats impose specialized logistics infrastructure that limits site activation to major metropolitan oncology centers.
- Fragmented HTA Timelines:France's HAS, Italy's AIFA, and Germany's G-BA apply parallel health technology assessment frameworks, creating reimbursement uncertainty that delays hospital procurement decisions.
- Autologous Manufacturing Complexity:Patient-specific production requirements constrain batch throughput, extending lead times from biopsy to administration beyond clinically optimal windows.
Strategic Opportunities
- Longitudinal Care Models:Subscription-based biomarker tracking services pivot vaccine delivery from one-time administration to ongoing patient monitoring, capturing recurring revenue streams.
- Companion Diagnostic Integration:Patient selection workflows that determine therapeutic vaccine eligibility create control points for differentiated positioning in precision oncology.
- European Health Data Space:Real-world evidence generation frameworks enable adaptive licensing pathways that compress post-market confirmatory study requirements.
Industry Challenges
- Algorithm Documentation Burden:The EU AI Act imposes technical documentation requirements on patient stratification tools used in vaccine trials, extending validation timelines for machine learning-driven eligibility screening.
- Data Exclusivity Uncertainty:Evolving EU pharmaceutical legislation on protection periods creates investment risk for personalized vaccine platforms where development cycles exceed standard small-molecule timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cancer Vaccines Market |
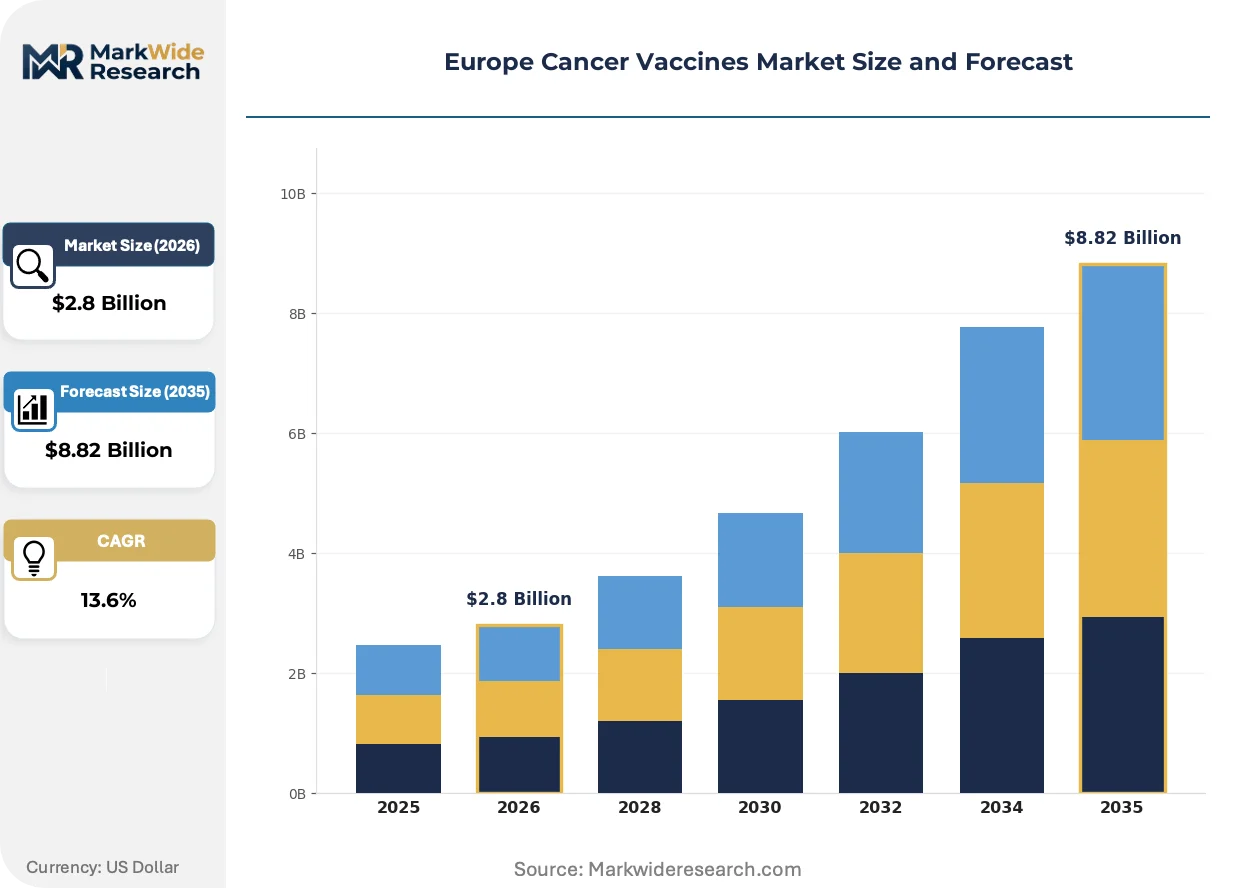
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Preventive Vaccines, Therapeutic Vaccines, Autologous Vaccines, Allogeneic Vaccines Administration Route: Intravenous, Subcutaneous, Intramuscular, Oral Target Indication: Melanoma, Prostate Cancer, Cervical Cancer, Colorectal Cancer Manufacturing Stage: Clinical Development, Commercial Production, Preclinical Testing, Regulatory Approval |
| Companies Covered | Merck & Co. Inc., Bristol-Myers Squibb, GlaxoSmithKline PLC, Amgen Inc., ASE Immunotherapeutics, AstraZeneca PLC, Sanofi SA, Moderna Inc., BioNTech, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cancer Vaccines Market Shifts & Advancements
mRNA platform standardization is compressing development timelines while regulatory frameworks adapt to algorithm-driven patient selection, and procurement patterns shift toward bundled surveillance contracts.
Personalized neoantigen prediction algorithms are consolidating around validated computational pipelines that integrate tumor sequencing with HLA typing. Oncology centers in Germany and France are adopting these platforms at accelerating pace, compressing the competitive gap between academic medical centers and community hospital networks. The technology is consolidating patient stratification capabilities into integrated diagnostic-vaccine workflows that lock in referral relationships.
The EU AI Act introduces mandatory documentation requirements for algorithm-driven patient stratification tools deployed in clinical trials. This regulatory friction is forcing vaccine developers to retrofit existing machine learning pipelines with explainability features and audit trails. Personalized vaccine trials face the steepest compliance burden, as neoantigen prediction models directly determine patient eligibility and dosing protocols.
Hospital procurement departments are unbundling post-treatment surveillance from vaccine administration, creating separate contracting streams for biomarker monitoring services. Oncology centers in the UK and Netherlands are piloting subscription-based patient tracking that extends provider relationships beyond the initial therapeutic window. France's university hospital networks show the fastest adoption of this consumption-pattern shift, driven by budgetary pressure to capture recurring revenue from immunotherapy patient cohorts.
Europe Cancer Vaccines Market Segmentation
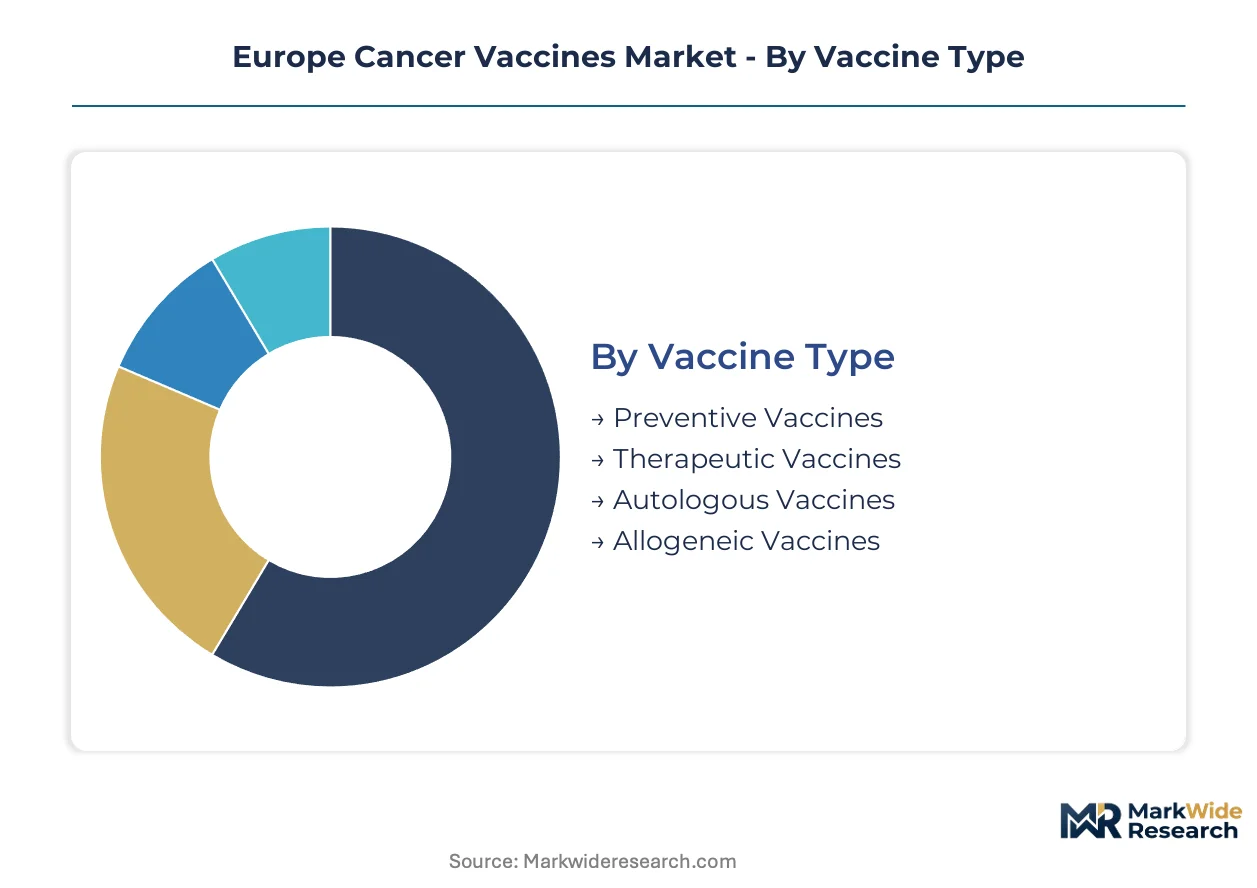
Cancer vaccine segmentation in Europe reflects the tension between personalized manufacturing complexity and scalable platform economics. Each dimension—vaccine type, delivery route, disease target, and production stage—carries distinct regulatory pathways and reimbursement implications that shape commercial strategy.
Vaccine Type:
Customization intensity spans from standardized population-wide formulations to patient-specific bioprocessing workflows that strain manufacturing infrastructure.
- Therapeutic Vaccines:Designed to treat existing malignancies by stimulating antigen-specific T-cell responses against tumor-associated antigens. Demand concentrates in Germany's university hospital networks where immuno-oncology infrastructure supports complex patient stratification workflows for checkpoint inhibitor combinations.
- Autologous Vaccines:Manufactured from patient-derived tumor material requiring individualized production runs with extended lead times from biopsy to administration. France's HAS reimbursement assessments favor these premium therapies in melanoma indications where residual disease burden demands personalized intervention.
- Preventive Vaccines:Standardized HPV-targeted formulations serve broader addressable populations through established cold-chain distribution networks.
- Allogeneic Vaccines:Off-the-shelf formulations derived from donor cell lines enable batch manufacturing scale that reduces per-dose production costs.
Most installed capacity flows through Preventive Vaccines. Expansion is steepest in Autologous Vaccines.
Administration Route:
Route selection hinges on immunogenicity profiles, site-of-care logistics, and the temperature stability requirements of nucleic acid payloads.
- Intravenous:Enables systemic immune activation through direct vascular delivery, preferred for advanced-stage malignancies requiring rapid lymphoid tissue engagement.
- Subcutaneous:Dominates clinical practice across UK oncology centers where depot formation sustains antigen release kinetics over extended dosing intervals.
- Intramuscular:Gaining traction for mRNA platforms based on superior immunogenicity profiles and compatibility with standard primary care administration workflows.
- Oral:Remains experimental due to gastrointestinal degradation of peptide and nucleic acid formulations, though mucosal immune targeting drives continued development investment.
Subcutaneous delivery commands the largest patient volume base. Intramuscular administration is climbing the fastest as mRNA platforms mature.
Target Indication:
Indication prioritization follows tumor immunogenicity, antigen characterization maturity, and the availability of companion diagnostic infrastructure.
- Melanoma:High mutational burden generates abundant neoantigen targets that validate personalized vaccine approaches. Italian AIFA reimbursement pathways favor melanoma therapeutics where checkpoint inhibitor resistance creates urgent unmet need.
- Prostate Cancer:Well-defined tumor-associated antigens enable off-the-shelf therapeutic development with clearer regulatory endpoints than heterogeneous solid tumors.
- Cervical Cancer:HPV-driven etiology provides standardized antigen targets that simplify manufacturing and support preventive vaccine integration into national immunization programs.
- Colorectal Cancer:Microsatellite instability subpopulations offer discrete patient segments for targeted therapeutic development despite broader tumor heterogeneity challenges.
Melanoma accounts for the majority of active clinical trial enrollment. Prostate Cancer is expanding most quickly as urology networks build vaccine administration capabilities.
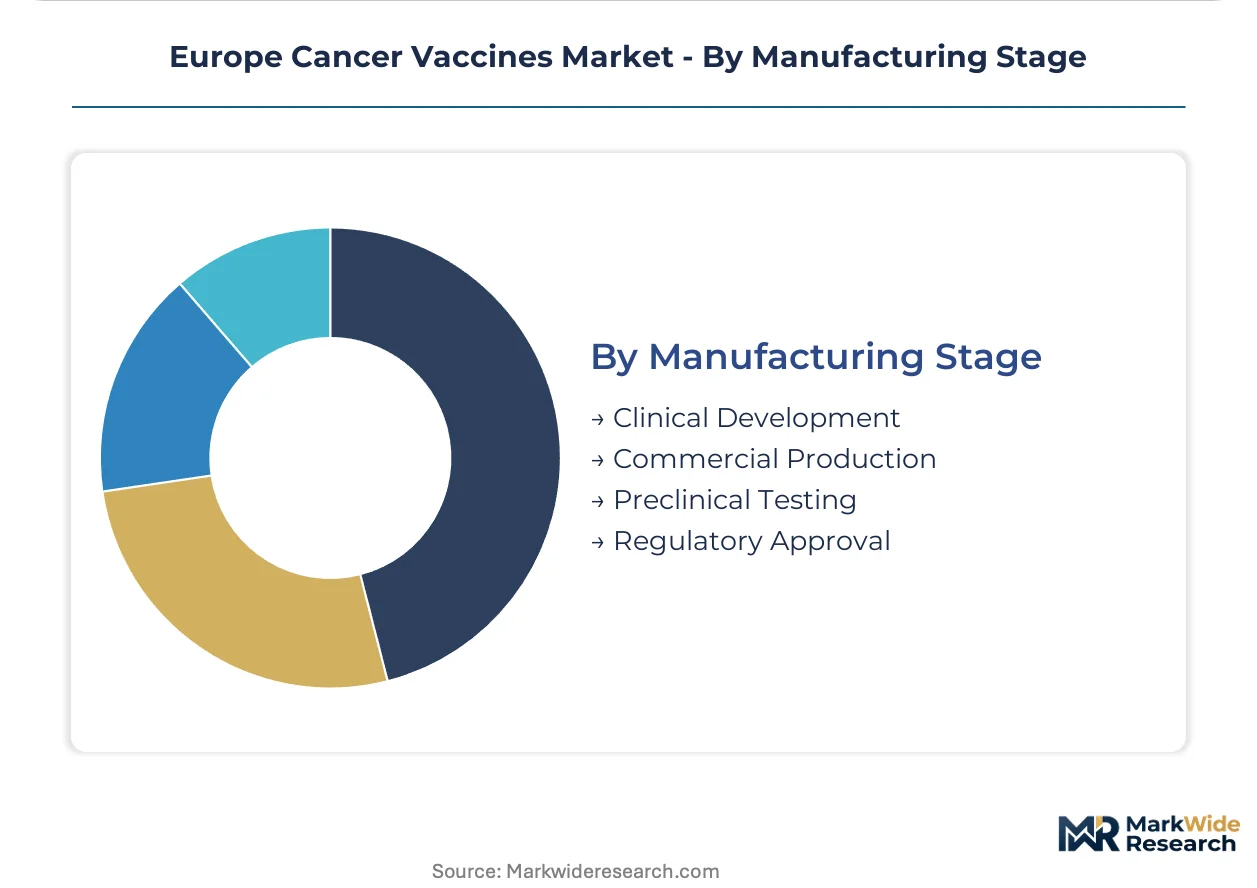
Manufacturing Stage:
Stage positioning determines capital intensity, regulatory engagement depth, and the timeline to revenue realization across European markets.
- Commercial Production:GMP-certified facilities in Germany and Belgium anchor continent-wide supply security for approved mRNA and peptide platforms with established EMA marketing authorizations.
- Clinical Development:Phase II and III trials concentrate in France and the Netherlands where EU Clinical Trials Regulation harmonization compresses multi-country study activation timelines.
- Preclinical Testing:Academic medical center partnerships in Switzerland and Denmark generate early-stage asset pipelines feeding into commercial development tracks.
- Regulatory Approval:EMA centralized procedures govern pan-European access, with national HTA bodies subsequently determining hospital procurement and reimbursement eligibility.
Clinical Development absorbs the greatest R&D investment flow. Commercial Production is gaining share fastest as pipeline assets transition to approved status.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed base of immuno-oncology infrastructure, while France accelerates therapeutic vaccine adoption through centralized reimbursement pathways that favor personalized interventions.
Germany
University hospital networks in Munich and Heidelberg drive concentrated demand for autologous vaccine platforms, leveraging established GMP manufacturing corridors. The G-BA evaluates oncology innovation through early benefit assessments that directly shape hospital procurement budgets. Bavaria's biotech cluster anchors continent-wide supply security for mRNA production, with BioNTech's Marburg facility sustaining patient-specific manufacturing at scale.
France
The HAS reimbursement framework prioritizes melanoma therapeutics where checkpoint inhibitor resistance creates urgent unmet need, channeling investment toward personalized neoantigen platforms. EU Clinical Trials Regulation harmonization compresses multi-country study activation timelines through Paris and Lyon oncology centers. The Île-de-France region concentrates Phase II and III trial activity, validating therapeutic efficacy data for EMA centralized marketing authorization submissions.
United Kingdom
NHS England's specialized commissioning frameworks concentrate cancer vaccine access through designated tertiary centers in London and Manchester. The MHRA's post-Brexit regulatory autonomy enables accelerated approval pathways for mRNA platforms while maintaining EMA alignment for pan-European commercialization. Cambridge's biotech corridor hosts preclinical development partnerships that feed pipeline assets into commercial tracks.
Italy
AIFA reimbursement assessments favor melanoma indications with established companion diagnostic infrastructure, creating controlled entry points for therapeutic vaccine eligibility. Lombardy's university hospital networks in Milan deploy complex patient stratification workflows that validate combination therapy protocols with checkpoint inhibitors. The country's northern manufacturing belt anchors peptide formulation capacity for off-the-shelf therapeutic development.
Netherlands
Leiden's life sciences cluster concentrates clinical development operations for European trial coordination, exploiting centralized ethics review procedures that accelerate site activation. Dutch oncology centers pilot subscription-based biomarker tracking services that extend provider relationships beyond initial therapeutic windows. The country's logistics infrastructure supports minus 70 degrees Celsius distribution requirements for mRNA formats across Benelux hospital networks.
Europe Cancer Vaccines Market Competitive Landscape
Top-tier vendors anchor platform-scale manufacturing, while mid-tier specialists concentrate on patient-specific production workflows. The market structure reflects consolidation around mRNA technology holders and fragmentation across autologous vaccine developers. Strategic archetypes include integrated immuno-oncology conglomerates, pure-play mRNA platform companies, and diagnostic-vaccine workflow integrators. Dominant competitive moves encompass companion diagnostic partnerships and backward integration into GMP manufacturing capacity.
Among US-based pharmaceutical conglomerates, Merck & Co. Inc. and Bristol-Myers Squibb occupy positions representing integrated immuno-oncology infrastructure, while BioNTech exemplifies the mRNA platform archetype with German manufacturing anchoring. These three entities represent distinct strategic vectors: diagnostic-controlled patient selection, bundled surveillance service models, and supply-secured personalized production.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Bristol-Myers Squibb |
| GlaxoSmithKline PLC |
| Amgen Inc. |
| ASE Immunotherapeutics |
| AstraZeneca PLC |
| Sanofi SA |
| Moderna Inc. |
| BioNTech |
| Others |
Supply & Pricing Matrix
Captive GMP manufacturing networks in Germany and Belgium anchor both supply security and pricing power for personalized cancer vaccines, creating a structural moat that outsourced bioprocessing competitors cannot replicate without multi-year facility buildouts. This integration choice locks in margin control for autologous platforms while forcing price premiums that reflect patient-specific production complexity rather than commodity manufacturing economics.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for mRNA platforms as BioNTech's Marburg facility and competing GMP sites expand batch throughput. Three-tier pricing structure across personalized autologous, allogeneic therapeutic, and preventive HPV formulations reflects manufacturing complexity and cold-chain requirements. Cost compression in preventive vaccines is intensifying because standardized formulations invite multi-supplier competition. Hospital procurement managers in France and Italy show highest price sensitivity for off-the-shelf therapeutics, while German university networks accept premium positioning for checkpoint inhibitor combination therapies.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Belgium orchestrate hub-and-spoke patterns for minus 70 degrees Celsius mRNA logistics, with Leiden and Antwerp anchoring Benelux cold-chain networks. Manufacturing concentrates in Germany, Belgium, and Switzerland, drawing from lipid nanoparticle formulations, synthetic peptide substrates, and patient-derived tumor biopsy logistics. Single-source vulnerability in lipid nanoparticle supply creates exposure to raw material bottlenecks. Distribution runs through specialized oncology pharmacy networks rather than general hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement frameworks increasingly favor premium therapeutics with demonstrated progression-free survival advantages over commodity immunotherapy combinations.
For Market Incumbents: To counter margin compression in preventive vaccine segments, BioNTech and Merck & Co. should deepen backward integration into lipid nanoparticle production and lock in exclusive GMP capacity at German university hospital networks. Companion diagnostic partnerships control patient selection workflows that determine therapeutic vaccine eligibility, creating defensive switching costs. For New Entrants and Emerging Players: Capture white-space in colorectal cancer microsatellite instability subpopulations where checkpoint inhibitor resistance rates exceed melanoma benchmarks and companion diagnostic infrastructure remains underdeveloped. Italian AIFA reimbursement pathways for MSI-high indications offer the most penetrable entry point, with hospital system partnerships as the essential go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for diagnostic-vaccine workflow integrators because fragmented neoantigen prediction algorithm vendors lack standalone commercialization infrastructure and face EU AI Act compliance burdens that favor acquisition by scaled platform holders. Watch EMA centralized marketing authorization timelines as the signal for inflection in platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Marketing Authorization | Pan-European approval compresses fragmented national timelines and accelerates hospital procurement decisions. |
| Companion Diagnostic Partnership | Patient selection workflow control creates differentiated positioning in precision oncology combination therapies. |
| GMP Manufacturing Scale-Up | German facility expansion sustains supply security for personalized neoantigen platforms at viable unit economics. |
| Longitudinal Care Model Development | Subscription-based biomarker tracking pivots revenue from one-time administration to recurring surveillance contracts. |
| EU AI Act Compliance Investment | Explainability features and audit trails for patient stratification algorithms preempt regulatory validation delays. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through EMA submissions, ClinicalTrials.gov records, and G-BA benefit assessment documents; plus customs and trade data on biologics cold-chain logistics — were reconciled through bottom-up patient-flow modeling and top-down market sizing triangulation.
Data-stream reconciliation across vaccine type, administration route, target indication, and manufacturing stage dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from patient population epidemiology, therapy penetration assumptions, and pricing trajectory modeling anchored in HTA reimbursement framework evolution. Forecast inputs incorporated EU Clinical Trials Regulation harmonization timelines and GMP capacity expansion pipelines.
Underlying measurement precision varies by segment; preventive vaccines with standardized formulations carry tighter precision than autologous platforms where patient-specific production introduces batch-to-batch variability. Forecasts reflect documented assumptions on regulatory approval timelines and reimbursement decisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market