
 Sandhoff Disease Therapeutics Market | 2026-2036
Sandhoff Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Sandhoff Disease Therapeutics Market Analytics
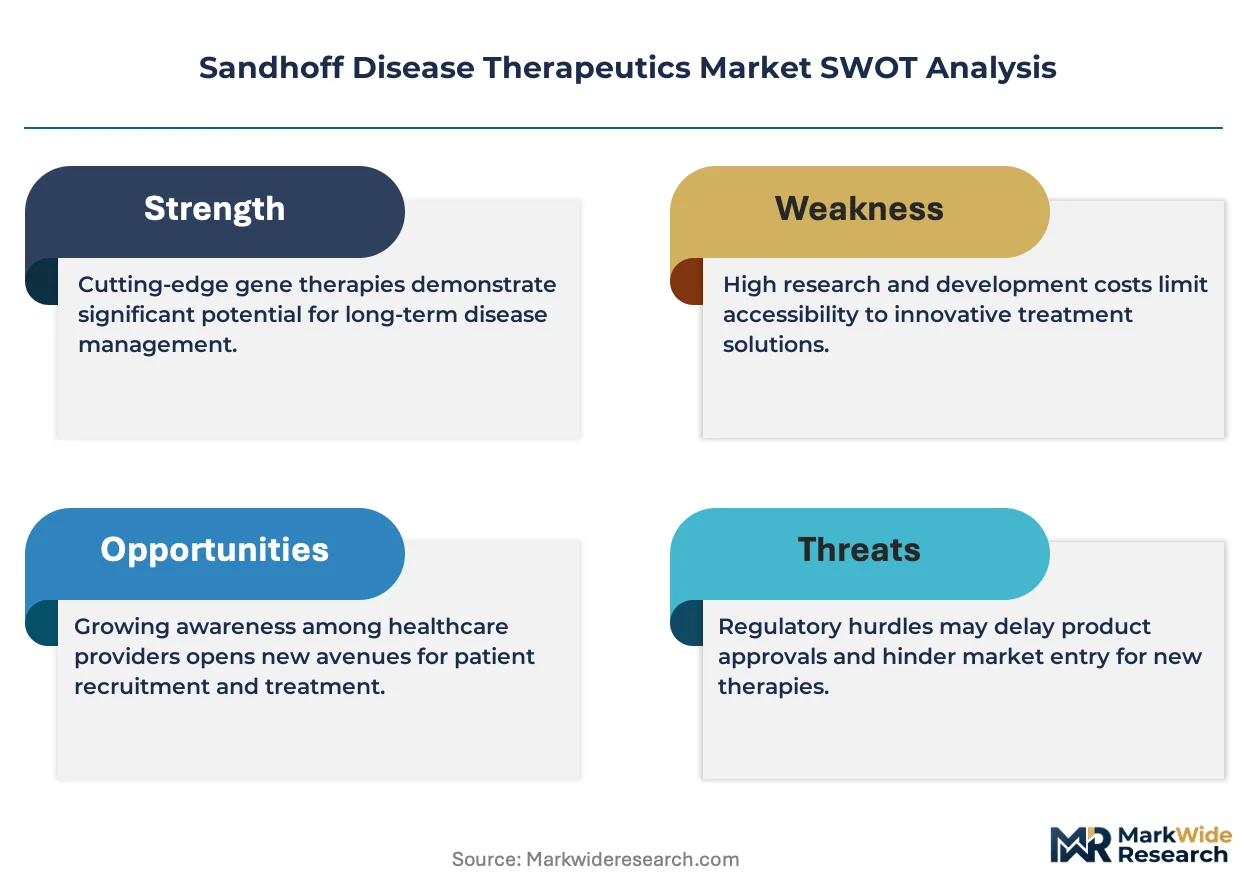
Gene therapy platform access is broadening what manufacturers sell beyond vials to long-term patient monitoring contracts and biomarker-driven dosing protocols. Novartis AG leverages its established rare disease infrastructure to anchor complex logistics for intrathecal delivery. REGENXBIO Inc. specializes in AAV9 vector manufacturing, sustaining supply security for neurology-focused programs. Sanofi Genzyme dominates the legacy enzyme replacement segment while navigating competitive pressure from novel modalities.
Sandhoff disease therapeutics target the inherited deficiency of hexosaminidase A and B enzymes caused by mutations in the HEXB gene, requiring interventions that restore lysosomal ganglioside clearance in neural tissue. Gene therapy and substrate reduction therapy represent the fastest-expanding segments, with margin pools concentrating in intra-thecal delivery systems where technical barriers limit competition. Enzyme replacement therapy remains the most mature category, though its efficacy ceiling in central nervous system penetration constrains long-term positioning. Pediatric hospitals constitute the dominant end-user channel, absorbing the highest per-patient treatment costs due to intensive monitoring requirements.
FDA orphan drug exclusivity and EMA priority medicines designation shape trial enrollment speed and reimbursement negotiations across North America and Europe. The EU AI Act and GDPR impose data governance requirements on patient registries that feed real-world evidence submissions for accelerated approvals. Stakeholders must monitor how payer evidence thresholds evolve for one-time gene therapies against chronic enzyme administration models.
Market Dynamics
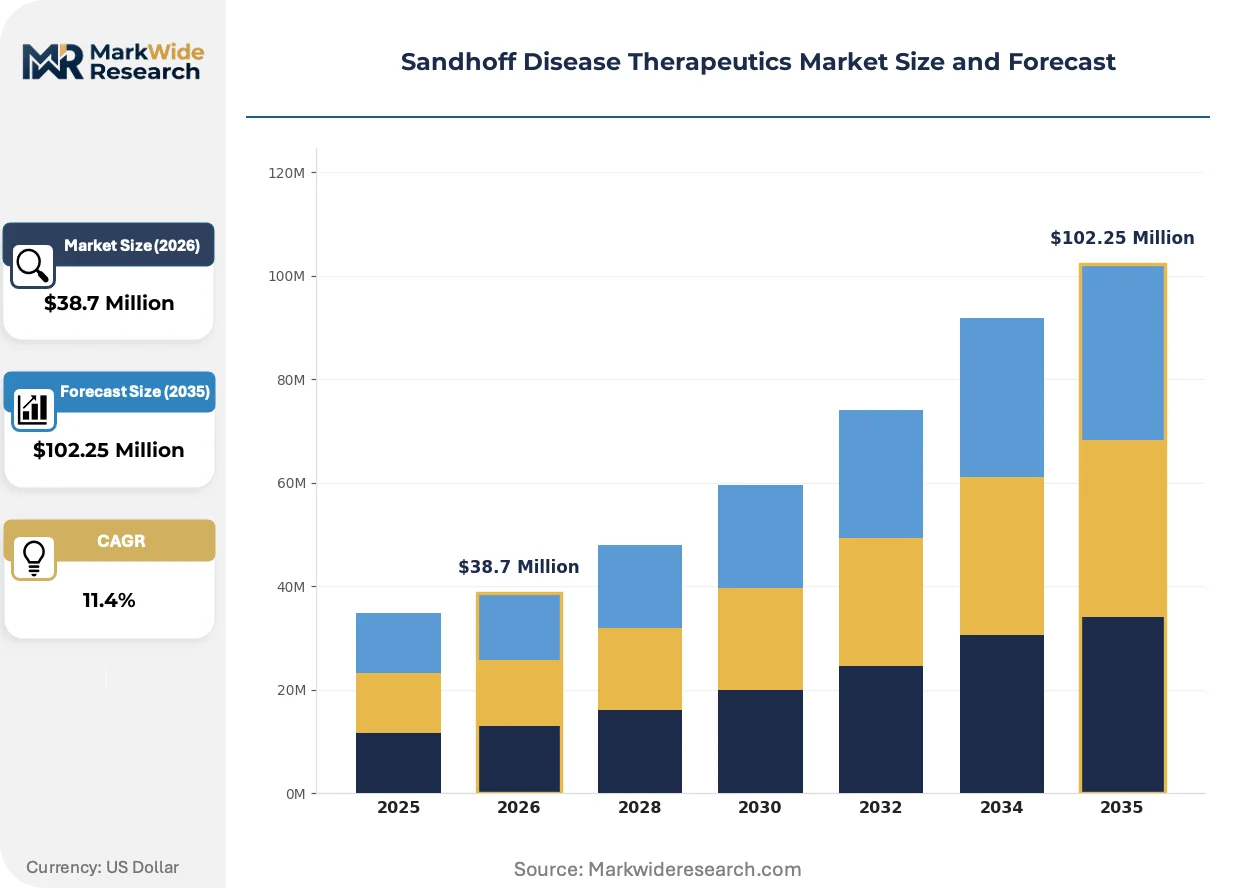
Gene therapy manufacturing capacity constraints are compressing clinical trial timelines while FDA orphan drug incentives accelerate enrollment. Intrathecal delivery technical barriers create supply-side scarcity that shapes competitive positioning across pediatric metabolic centers.
Growth Catalysts
- FDA Orphan Drug Exclusivity:This framework accelerates trial design and reimbursement negotiations for developers targeting rare lysosomal storage disorders.
- AAV9 Vector Manufacturing Scale-up:Contract development organizations are expanding viral production capacity to address bottlenecks in neurology-focused gene therapy supply.
- Pediatric Hospital Clustering:Specialized metabolic centers in the United States, Germany, and Japan concentrate patient access and payer engagement for novel modalities.
Market Restraints
- Central Nervous System Penetration Limits:Enzyme replacement therapy faces efficacy ceilings in neural tissue clearance that constrain long-term clinical outcomes.
- Single-Source Vector Supply:AAV9 manufacturing concentrates among limited contract manufacturers, creating vulnerability in gene therapy program continuity.
- GDPR Data Governance Burden:EU patient registry requirements impose compliance costs on real-world evidence collection for accelerated approval pathways.
Strategic Opportunities
- Substrate Reduction Therapy Convergence:Small-molecule approaches combining with gene transfer vectors offer combination protocol potential in pediatric dosing.
- EMA Priority Medicines Designation:This regulatory pathway reduces time-to-market for therapies addressing unmet neurological needs in European markets.
- Japan PMDA Sakigake Framework:Early approval pathways for regenerative medicines create first-mover positioning for intrathecal delivery innovators.
Industry Challenges
- Biomarker Validation Timelines:Ganglioside clearance surrogates require extended longitudinal studies to satisfy payer evidence thresholds for one-time therapies.
- Intrathecal Administration Training:Specialized neurosurgical capability scarcity limits site activation speed across pediatric hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandhoff Disease Therapeutics Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Substrate Reduction Therapy, Antisense Oligonucleotide Delivery Mode: Intravenous, Subcutaneous, Oral, Intra-thecal End User: Pediatric Hospitals, Specialized Clinics, Homecare Settings, Research Institutions Therapy Area: Neurological Disorders, Metabolic Diseases, Genetic Conditions, Rare Diseases |
| Companies Covered | Novartis AG, REGENXBIO Inc., Sanofi Genzyme, IntraBio, Amicus Therapeutics Inc., Pfizer Inc., Ultragenyx Pharmaceutical Inc., Polaryx Therapeutics, Biogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandhoff Disease Therapeutics Market Evolving Landscape
Biomarker-driven dosing protocols are displacing fixed-regimen administration across lysosomal storage disorder programs. Real-world evidence infrastructure investments by payers and regulators reshape how manufacturers demonstrate durable clinical benefit.
AAV9-mediated gene transfer is expanding into Sandhoff disease programs after validation in related hexosaminidase deficiencies. Pediatric metabolic centers are adopting this platform at accelerating pace as manufacturing yields improve. The technology is expanding into long-term patient monitoring contracts that extend manufacturer revenue streams beyond single-dose vial sales.
The EU AI Act imposes algorithmic transparency requirements on predictive models used in patient stratification for gene therapy trials. Clinical sponsors must document training data provenance and bias mitigation for machine learning tools supporting enrollment decisions. European gene therapy developers are restructuring data governance frameworks to maintain regulatory compliance while preserving trial efficiency.
Payers are unbundling intensive monitoring services from drug reimbursement in pediatric rare disease programs. Hospital systems now negotiate separate contracts for biomarker collection, neurodevelopmental assessment, and adverse event surveillance. This shift is most visible in United States Medicaid managed care plans serving specialized metabolic center networks.
Sandhoff Disease Therapeutics Market Segmentation
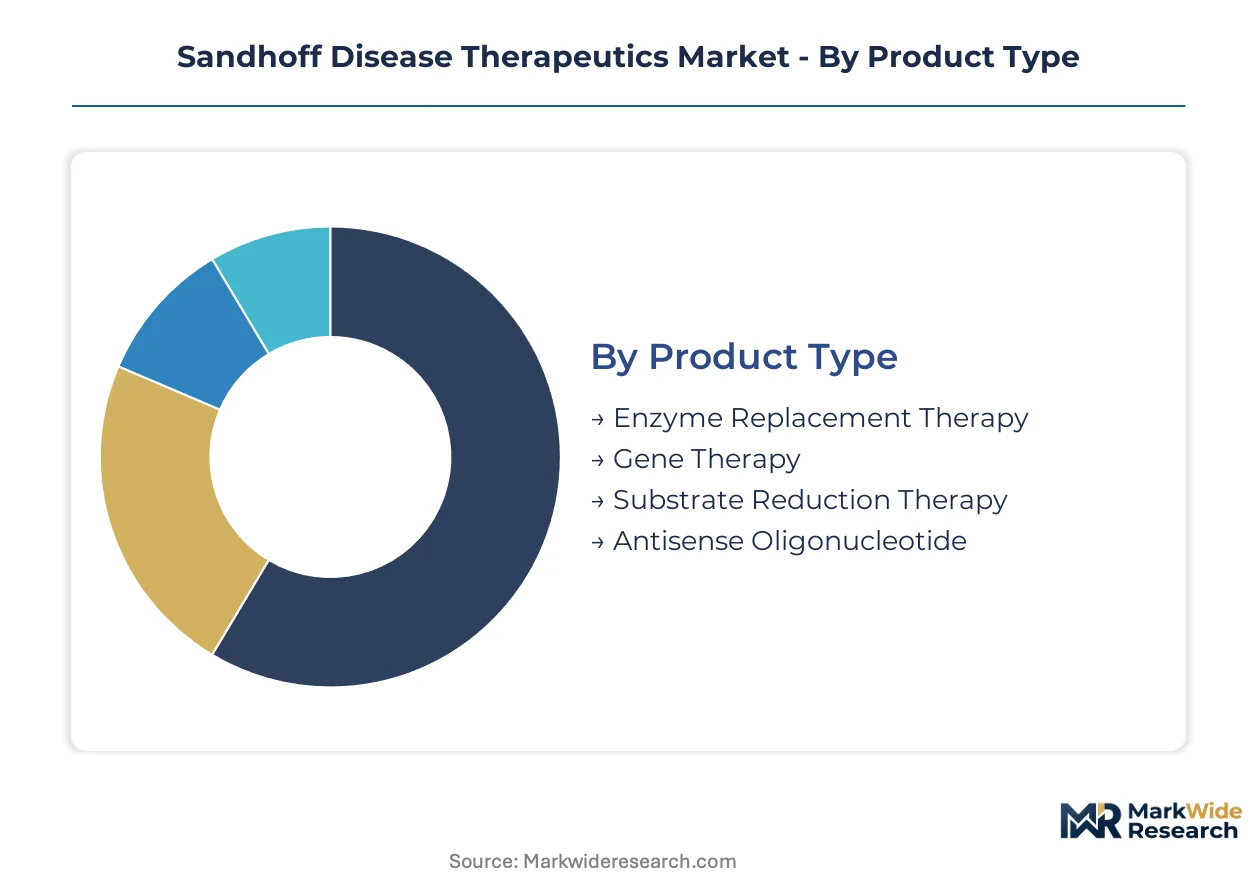
Sandhoff disease therapeutics fragment across four distinct dimensions where supply constraints and clinical complexity reshape competitive boundaries. Manufacturers must navigate divergent manufacturing requirements, delivery logistics, and reimbursement frameworks within each segment cluster.
Product Type:
Gene therapy vector production concentrates among limited contract manufacturers, creating supply scarcity that shapes competitive positioning across all modalities.
- Gene Therapy:AAV9-mediated hexosaminidase gene transfer requires specialized viral manufacturing suites with multi-month production cycles. Pediatric metabolic centers in the United States, Germany, and Japan absorb the highest per-patient costs due to intensive neurosurgical monitoring requirements.
- Enzyme Replacement Therapy:Recombinant hexosaminidase A and B protein formulations face central nervous system penetration limits that constrain efficacy in neural tissue clearance. Legacy infrastructure at Sanofi Genzyme dominates installed capacity despite competitive pressure from novel modalities.
- Substrate Reduction Therapy:Small-molecule ganglioside synthesis inhibitors offer oral administration advantages in combination protocols with gene transfer vectors.
- Antisense Oligonucleotide:HEXB-targeted splice-switching approaches remain in early clinical development with manufacturing scale-up pending regulatory validation.
Enzyme replacement therapy absorbs the bulk of installed capacity; gene therapy is expanding most quickly.
Delivery Mode:
Route selection directly determines reimbursement complexity and site activation requirements across pediatric hospital networks.
- Intra-thecal:Direct cerebrospinal fluid delivery via lumbar puncture or intraventricular reservoir requires specialized neurosurgical capability that limits site availability. FDA orphan drug incentives accelerate enrollment at centers with established intrathecal gene therapy programs.
- Intravenous:Systemic enzyme administration leverages existing infusion center infrastructure but suffers from blood-brain barrier exclusion that restricts neural tissue exposure.
- Subcutaneous:Home administration potential reduces hospital burden though immunogenicity concerns require careful monitoring protocols.
- Oral:Substrate reduction therapy candidates enable outpatient management without surgical intervention, appealing to Medicaid managed care plans serving dispersed populations.
Intravenous delivery maintains the broadest site footprint; intra-thecal administration is climbing the fastest as gene therapy programs mature.
End User:
Payer unbundling of monitoring services from drug reimbursement reshapes contract structures across institutional categories.
- Pediatric Hospitals:Specialized metabolic centers concentrate patient access, biomarker collection infrastructure, and neurodevelopmental assessment capability. United States children's hospitals negotiate separate contracts for intensive monitoring services under Medicaid managed care arrangements.
- Specialized Clinics:Lysosomal storage disorder referral networks in Germany and Japan coordinate pre-trial screening and long-term follow-up protocols.
- Homecare Settings:Subcutaneous enzyme administration enables decentralized management though adverse event surveillance requirements limit adoption.
- Research Institutions:Academic medical centers anchor natural history studies and biomarker validation timelines for accelerated approval pathways.
Pediatric hospitals command the highest per-patient revenue; specialized clinics are gaining share fastest as European networks expand.
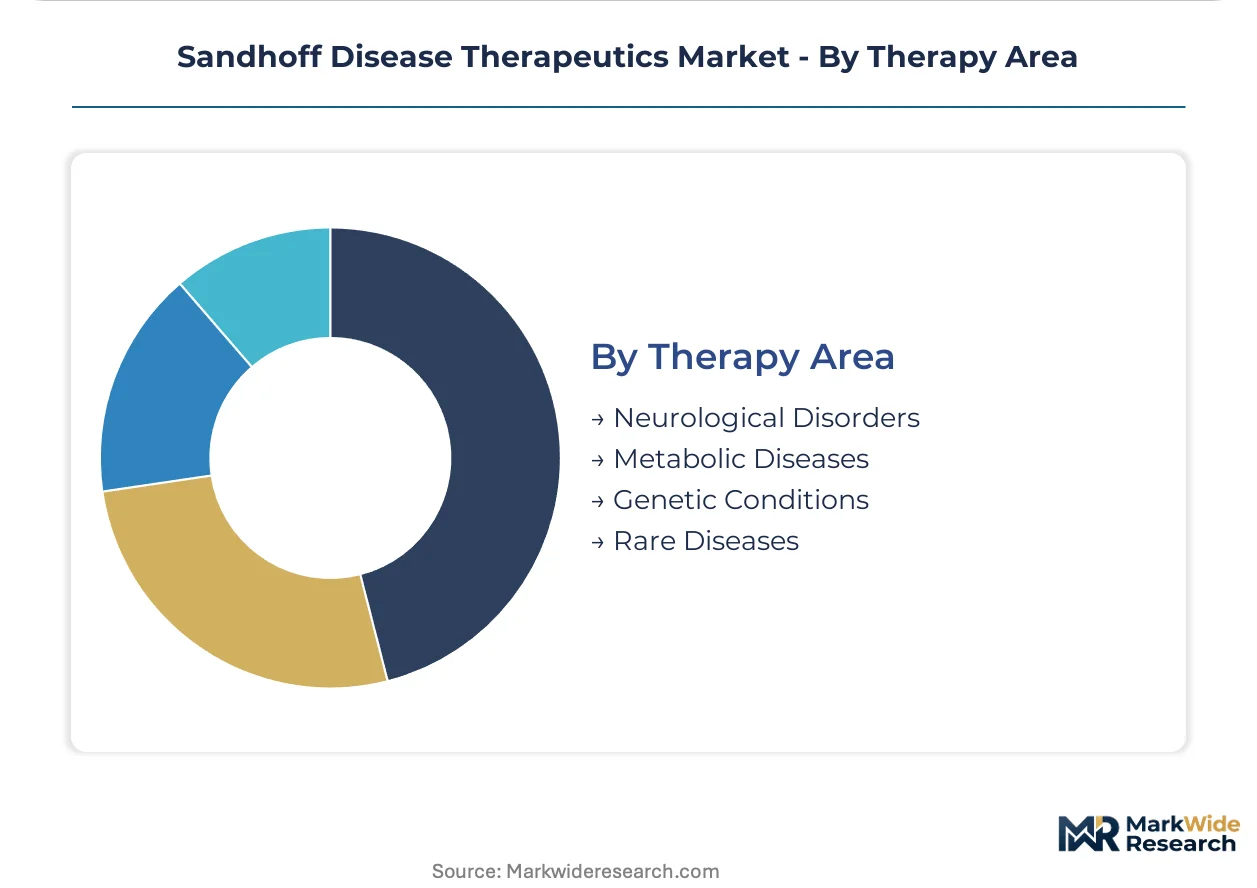
Therapy Area:
Regulatory designation frameworks vary across disease classifications, influencing trial design and priority review eligibility.
- Rare Diseases:FDA orphan drug exclusivity and EMA priority medicines designation accelerate enrollment and reimbursement negotiations for hexosaminidase deficiency programs.
- Neurological Disorders:Central nervous system targeting requirements impose biomarker validation timelines that extend payer evidence thresholds for one-time therapies.
- Genetic Conditions:Germline mutation confirmation mandates shape screening protocols and patient stratification for gene therapy trials.
- Metabolic Diseases:Lysosomal storage classification aligns with established payer pathways for enzyme replacement reimbursement.
Rare disease designation captures the bulk of regulatory investment; neurological disorder targeting is expanding most quickly as vector engineering advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing concentrates in the United States, Germany, and Japan, while patient access networks extend into specialized pediatric clusters across these markets. Consumption patterns track toward metabolic centers with intrathecal delivery capability. Regulatory pathways diverge across FDA, EMA, and PMDA jurisdictions.
United States
Pediatric hospital networks in Boston and Philadelphia anchor clinical trial enrollment for hexosaminidase gene transfer programs. FDA orphan drug exclusivity accelerates reimbursement negotiations for developers targeting rare lysosomal storage disorders. The NIH Rare Diseases Clinical Research Network coordinates natural history studies across academic medical centers.
Germany
Specialized metabolic centers in Munich and Heidelberg concentrate patient screening infrastructure for accelerated approval pathways. EMA priority medicines designation reduces time-to-market for neurological gene therapies addressing unmet needs. The EU AI Act imposes algorithmic transparency requirements on predictive enrollment models.
Japan
PMDA Sakigake framework creates first-mover positioning for intrathecal delivery innovators in Tokyo and Osaka clusters. Regenerative medicine designation accelerates review timelines for AAV9-mediated programs targeting pediatric populations. National health insurance pricing negotiations favor one-time therapies over chronic administration models.
United Kingdom
NHS specialized commissioning frameworks concentrate Sandhoff disease care in London and Manchester referral networks. MHRA rolling review procedures align with EMA accelerated pathways for rare disease therapeutics. Genomics England infrastructure supports germline mutation confirmation for trial stratification.
Switzerland
Swissmedic early access programs attract gene therapy developers to Basel and Zurich biotech clusters. Orphan drug incentives mirror EMA frameworks while offering streamlined pediatric investigation plans. University hospital networks coordinate longitudinal biomarker collection for payer evidence packages.
Sandhoff Disease Therapeutics Market Competitive Landscape
Top-tier vendors anchor vector manufacturing and rare disease infrastructure, while mid-cap specialists concentrate on substrate reduction and antisense platforms. The market exhibits tiered consolidation around intrathecal delivery capabilities and AAV9 supply security. Three archetypes dominate: diversified pharmaceutical conglomerates with metabolic portfolios, gene therapy pure-plays with viral manufacturing expertise, and enzyme replacement incumbents navigating modality transition. Competitive moves center on manufacturing capacity expansion and long-term patient monitoring contract structures.
Within the diversified pharmaceutical tier, Novartis AG and Pfizer Inc. occupy positions leveraging established rare disease infrastructure for complex logistics. REGENXBIO Inc. exemplifies the gene therapy pure-play archetype with AAV9 vector specialization. Sanofi Genzyme represents enzyme replacement incumbents adapting portfolio strategy toward novel modalities. These three anchors illustrate how competitive positioning fragments across manufacturing scale, delivery technology, and reimbursement contract sophistication.
| Leading Market Players |
|---|
| Novartis AG |
| REGENXBIO Inc. |
| Sanofi Genzyme |
| IntraBio |
| Amicus Therapeutics Inc. |
| Pfizer Inc. |
| Ultragenyx Pharmaceutical Inc. |
| Polaryx Therapeutics |
| Biogen Inc. |
| Others |
Value Network & Pricing Analysis
EMA priority medicines designation and FDA orphan drug exclusivity frameworks gate qualified supply access for Sandhoff disease therapeutics while enabling premium-tier pricing for compliant manufacturers. These regulatory moats concentrate pricing power among vector producers with validated pediatric neurosurgical delivery capabilities.
Pricing Analysis
Margin tightening in gene therapy tiers reflects AAV9 manufacturing scarcity and multi-month viral production cycles. Three-tier pricing structure across premium intrathecal gene transfer, standard enzyme replacement, and economy substrate reduction segments stratifies by central nervous system penetration efficacy. Cost compression in enzyme replacement intensifies as gene therapy programs mature and payer unbundling separates drug reimbursement from monitoring services. Medicaid managed care plans demonstrate highest price sensitivity; pediatric metabolic centers with established neurosurgical infrastructure show lowest sensitivity due to bundled contract structures.
Supply Chain Analysis
AAV9 vector supply rests on contract manufacturing organizations concentrated in the United States, Germany, and Switzerland with specialized viral production suites. Plasmid DNA, HEK293 cell lines, and chromatography resins constitute critical input dependencies with limited qualified suppliers. Single-source vulnerability in viral vector manufacturing creates program continuity risk for neurology-focused gene therapy developers. Distribution runs through cold-chain logistics networks anchored at pediatric hospital metabolic centers with intrathecal administration capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sandhoff disease therapeutics operate as a cost-of-compliance market where EU AI Act algorithmic transparency requirements and GDPR patient registry governance create barrier-to-entry moats for compliant developers.
For Market Incumbents: Anchor AAV9 manufacturing capacity through captive supply agreements or backward integration into viral vector production to defend against emerging gene therapy pure-plays. Prioritize long-term patient monitoring contract structures that extend revenue streams beyond single-dose vial sales and lock in site relationships at pediatric metabolic centers. For New Entrants and Emerging Players: Direct-to-patient digital enrollment platforms offer lower-friction access to dispersed rare disease populations outside established metabolic center clusters. Target substrate reduction therapy combinations with oral administration profiles as the most penetrable entry point, leveraging existing payer familiarity with small-molecule metabolic disease management. For Investors and Strategic Acquirers: PMDA Sakigake framework approvals for intrathecal delivery innovators are the leading indicator that Japanese market positioning will drive regional valuation premiums. Focus acquisition screening on gene therapy pure-plays with validated AAV9 supply security and established pediatric hospital site relationships across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Intrathecal Delivery Capability Expansion | Pediatric neurosurgical site activation accelerates patient enrollment for hexosaminidase gene transfer programs. |
| AAV9 Manufacturing Scale-Up | Contract development organization partnerships address supply bottlenecks constraining neurology-focused clinical trial timelines. |
| Long-Term Monitoring Contract Structuring | Biomarker-driven patient surveillance extends manufacturer revenue beyond single-dose gene therapy administration. |
| EMA Priority Medicines Designation Pursuit | Accelerated regulatory pathway reduces time-to-market for therapies addressing unmet neurological needs in European markets. |
| Substrate Reduction Therapy Pipeline Addition | Small-molecule combination protocols diversify portfolio exposure beyond viral vector manufacturing constraints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Sandhoff disease therapeutics analysis. Primary interviews with gene therapy development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed demand-side validation. FDA orphan drug designations, EMA priority medicines submissions, ClinicalTrials.gov entries, and pediatric hospital formulary databases supplied secondary triangulation. Bottom-up patient population modeling and top-down metabolic center capacity assessment were reconciled across the analytical framework.
Data-stream reconciliation combined volume projections from treatment-eligible patient cohorts with value outputs from reimbursement contract analysis. Segmentation dimensions spanned product type, delivery mode, end-user institution, and regional regulatory cluster. CAGRs were derived from longitudinal biomarker validation timelines and payer evidence threshold evolution. Manufacturing yield improvements and intrathecal site activation rates served as industry-specific forecast inputs throughout the projection horizon.
The model holds under sustained FDA and EMA orphan incentive frameworks; deviation in payer unbundling speed or AAV9 supply disruption would shift forecast boundaries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market