
 Co-Polymer Resin Market | 2026-2036
Co-Polymer Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Polymer Resin Market Outlook
Automotive component demand is rebalancing toward lightweight structural parts, pulling styrene-butadiene and acrylonitrile-butadiene-styrene grades into broader chassis applications. BASF SE leverages its integrated precursor supply to dominate European automotive qualification programs. Dow anchors North American ethylene-vinyl acetate supply through Gulf Coast petrochemical scale. Kukdo Chemical Co., Ltd. specializes in epoxy-hybrid copolymers for Asian electronics laminates.
Co-polymer resin denotes macromolecules synthesized from two or more distinct monomer species, typically exhibiting glass transition temperatures between minus forty and plus one hundred twenty degrees Celsius and melt indices tunable from zero point one to fifty grams per ten minutes for extrusion or injection molding compatibility. These materials primarily serve as impact modifiers, adhesion promoters, and barrier layers across packaging films and structural composites. Ethylene-vinyl acetate commands the largest volume pool in flexible packaging sealants due to its hot-tack performance and clarity balance. Acrylonitrile-butadiene-styrene claims the fastest value growth trajectory as appliance and electronics housings demand higher heat distortion resistance without metal replacement penalties. Styrene-acrylonitrile occupies a mature niche in cosmetic and pharmaceutical blister packs where rigidity and vapor barrier specifications dominate margin capture.
EPA fuel-economy standards and NHTSA safety mandates jointly force automotive formulators toward copolymer grades that reduce mass without sacrificing crash-energy absorption. REACH restrictions on residual monomer content and ECHA substance-of-very-high-concern listings redirect European adhesive and coating procurement toward compliant styrenic alternatives with full supply-chain disclosure. Stakeholders must monitor regulatory divergence between California Air Resources Board thresholds and federal EPA harmonization timelines to avoid stranded inventory in cross-border automotive supply chains.
Market Dynamics
Automotive lightweighting mandates and battery-packaging specifications are compressing formulation cycles across ethylene-vinyl acetate and acrylonitrile-butadiene-styrene supply chains, forcing resin producers to pre-qualify grades for multi-year platform commitments before volume contracts finalize.
Growth Catalysts
- EPA Fuel-Economy Standards:Corporate Average Fuel Economy targets push chassis engineers toward copolymer impact modifiers that cut mass without sacrificing crash-performance thresholds. ABS and SBC grades now penetrate structural bumper beams and underbody shields previously reserved for metal stampings.
- China EV Battery Packaging:Domestic electric vehicle production concentrates demand for flame-retardant epoxy-hybrid copolymers in cell-to-pack enclosures. Local integrators specify thermal-runaway barriers that EVA and modified-polyolefin grades must pass before supplier approval.
- REACH SVHC Disclosure:European adhesive and coating procurement now requires full supply-chain transparency on residual styrene monomer content. Formulators pivot toward compliant styrenic alternatives with documented sub-ppm thresholds to maintain automotive qualification status.
Market Restraints
- Crude-Derivative Feedstock Volatility:Ethylene and benzene pricing swings compress margin predictability for integrated producers. Spot naphtha differentials in Asia-Pacific force quarterly contract renegotiations that destabilize long-term automotive supply agreements.
- Butadiene Supply Concentration:Global rubber-grade butadiene capacity clusters in South Korea, China, and the US Gulf Coast. Disruptions at any major steam cracker cascade through acrylonitrile-butadiene-styrene and styrene-butadiene copolymer availability within 6-8 weeks.
- High-Temperature Performance Ceiling:Standard EVA grades soften above 85°C, limiting under-hood automotive applications. Polyamide and PBT thermoplastics retain share in engine-bay components where continuous-use temperatures exceed copolymer thermal limits.
Strategic Opportunities
- India Automotive Localization:Production-Linked Incentive schemes for advanced chemistry cell batteries create captive demand for copolymer encapsulants and thermal interface materials. Domestic compounding capacity remains underdeveloped versus projected EV assembly growth.
- Medical-Grade Copolymer Certification:US FDA 21 CFR 177.1520 and EU MDR biocompatibility pathways open premium pricing for styrene-ethylene-butylene-styrene in drug-delivery devices and diagnostic cartridge housings. Few Asian producers have completed full regulatory dossiers.
- Chemical Recycling Integration:Pyrolysis-derived monomer streams enable mass-balance certified copolymers for brand-owner sustainability commitments. Early movers in pyrolysis-oil purification secure offtake agreements with packaging multinationals before capacity scales.
Industry Challenges
- Multi-Regulatory Qualification Burden:Simultaneous EPA, REACH, and China GB standard compliance extends automotive resin approval cycles to 18-24 months. Formulators must maintain parallel testing protocols that strain technical service bandwidth.
- Specialized Compounding Talent Scarcity:Reactive extrusion and melt-blending expertise for high-performance copolymer grades concentrates among veteran technologists at established producers. Succession planning gaps threaten formulation continuity at mid-tier compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Polymer Resin Market |
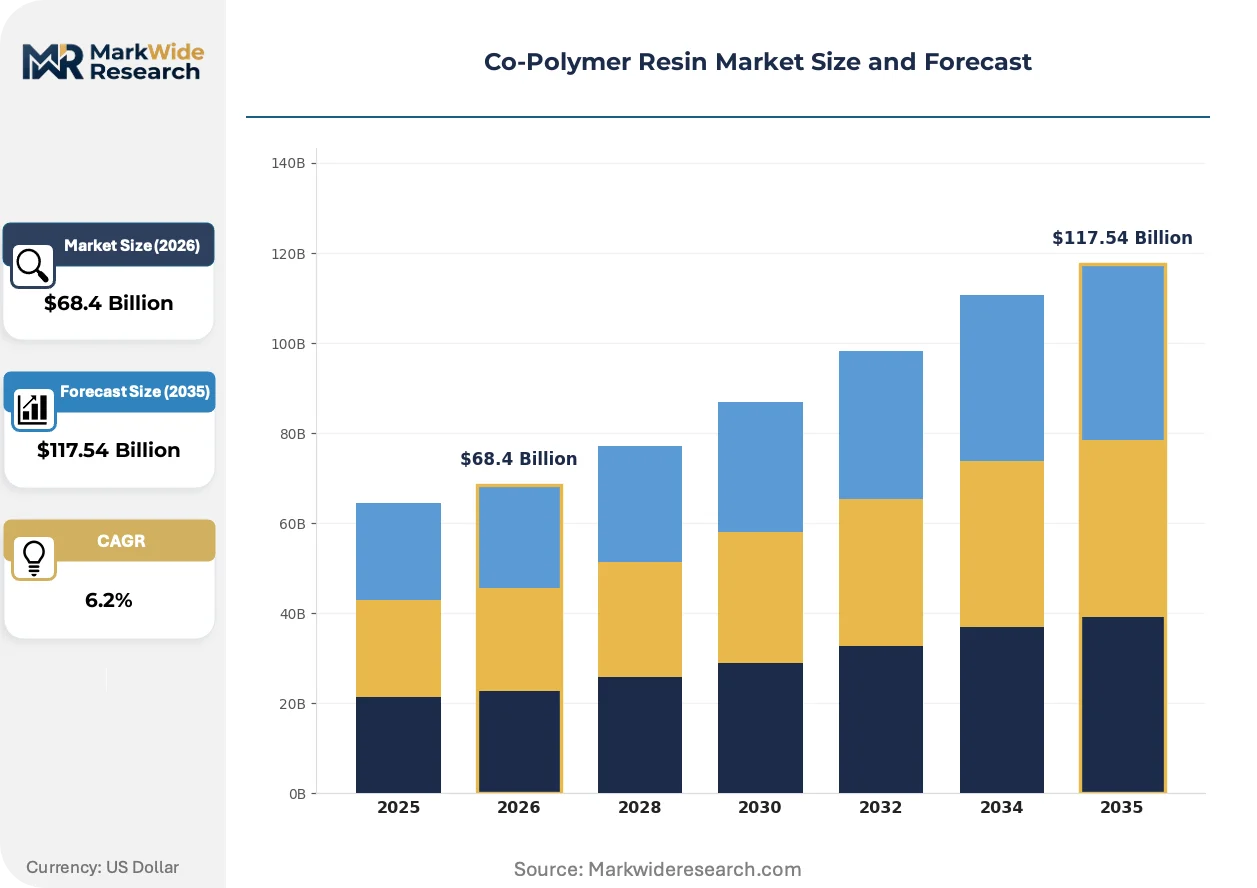
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene-Butadiene, Ethylene-Vinyl Acetate, Styrene-Acrylonitrile, Acrylonitrile-Butadiene-Styrene Application: Adhesives, Coatings, Packaging, Automotive Components End User: Construction, Automotive, Consumer Goods, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Dow, Huntsman International LLC, Olin Corporation, Westlake Corporation, DIC Corporation, Kukdo Chemical Co., Ltd., Celanese Corporation, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Polymer Resin Market Strategic Shifts
Reactive extrusion technologies and monomer recovery systems are compressing the cost-performance frontier for engineered copolymers, while regulatory disclosure requirements and brand-owner carbon-accounting demands reshape procurement specifications across packaging and mobility end-uses.
Tandem reactive extrusion with in-situ compatibilization is modularizing production economics for multilayer packaging films. Converters in Germany and Japan adopt these lines to eliminate separate adhesive lamination steps. The technology collapses capital intensity for barrier film structures that previously required solvent-based tie layers.
REACH Article 33 SCIP database obligations force full material composition disclosure across European electronics and automotive supply chains. Component suppliers now demand copolymer certificates of analysis with monomer-level traceability. EV battery packagers in Hungary and Poland requalify grades that lack documented SVHC-free status.
Automotive tier-one suppliers consolidate resin procurement under platform-direct contracts that bypass traditional distributor channels. Material specifications now flow from OEM engineering centers straight to qualified compounders in China, Mexico, and Germany. This channel compression squeezes margin for regional distributors holding speculative EVA and ABS inventory positions.
Co-Polymer Resin Market Segmentation
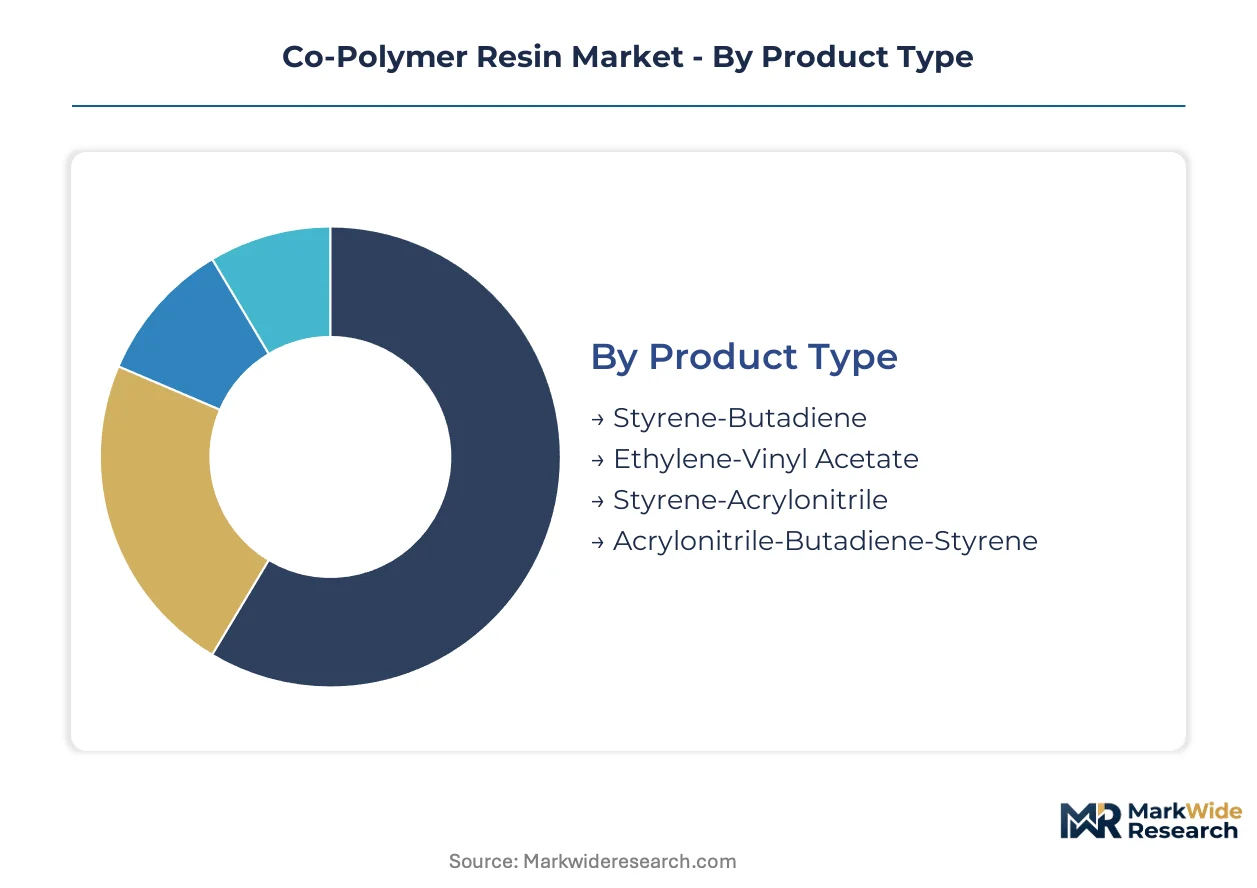
Segmentation in co-polymer resins separates commodity grades from engineered specifications, determining margin capture and qualification complexity. Product chemistry dictates thermal and mechanical boundaries, while application verticals impose distinct regulatory and performance thresholds.
Product Type:
Volume production concentrates in commodity ethylene-based grades, while premium pricing attaches to styrenic copolymers with tailored glass-transition and impact-modification profiles.
- Styrene-Butadiene:Random and block architectures deliver elastomeric recovery for tire manufacturing and asphalt modification. US Gulf Coast producers supply SBR latex streams to domestic tire plants facing NHTSA rolling-resistance mandates.
- Ethylene-Vinyl Acetate:VA content ranging from 9% to 40% tunes flexibility and adhesion for flexible packaging sealants and solar encapsulant films. Chinese EVA demand clusters in photovoltaic module manufacturing where anti-PID formulations command specification premiums.
- Styrene-Acrylonitrile:Transparent, rigid copolymer with excellent chemical resistance for cosmetic packaging and medical device housings. FDA 21 CFR compliance requirements limit qualified Asian suppliers in US medical markets.
- Acrylonitrile-Butadiene-Styrene:Terpolymer combining acrylonitrile chemical resistance, butadiene toughness, and styrene processability for appliance housings and automotive interior trim. REACH SVHC disclosure pressures European formulators toward low-residual-monomer grades.
Mature deployment sits with Ethylene-Vinyl Acetate in mass-market packaging. Newer deployment is concentrated in Acrylonitrile-Butadiene-Styrene for structural automotive applications.
Application:
End-use specifications fragment procurement channels, with automotive and medical applications demanding lot-traceable supply chains absent in construction adhesives.
- Adhesives:Hot-melt and pressure-sensitive formulations exploit EVA tackification and SBS elastomeric properties. European woodworking and bookbinding sectors drive demand for solvent-free adhesive systems under REACH VOC restrictions.
- Coatings:Waterborne styrene-acrylic copolymers provide gloss and durability for architectural and industrial finishes. China's MEE environmental enforcement accelerates substitution of solvent-borne alkyd systems in Yangtze River Delta manufacturing zones.
- Packaging:Multilayer films combine EVA seal layers with EVOH barriers for meat and cheese packaging. Japanese convenience-store food packaging specifications demand optical clarity and hot-tack performance that narrow qualified resin grades.
- Automotive Components:Interior trim, bumper fascias, and battery enclosures require heat-distortion resistance and crash-energy management. German OEMs specify ABS and PC-ABS grades with documented carbon footprints under EU Green Deal supply-chain disclosure rules.
Standardized procurement dominates Packaging through distributor channels. Custom qualification requirements concentrate in Automotive Components with direct-compounder relationships.
End User:
Customer sophistication varies sharply, with electronics and automotive buyers imposing full material disclosure versus construction sector price-focused purchasing.
- Construction:Waterproofing membranes, carpet backing, and sealants consume SBR latex and EVA at scale. India's Production-Linked Incentive schemes for affordable housing accelerate domestic compounding capacity expansion.
- Automotive:Interior, exterior, and under-hood applications drive specification-grade ABS and modified-PP demand. Mexican assembly plants serving US markets require simultaneous EPA and NOM environmental compliance documentation.
- Consumer Goods:Appliance housings, toys, and sporting equipment balance aesthetics with cost. South Korean electronics brands audit supplier carbon intensity for ESG reporting under CSRD-aligned disclosure frameworks.
- Electronics:Laminates, connectors, and enclosures demand flame-retardant grades with UL94 V-0 certification. Taiwan's PCB manufacturing cluster sources epoxy-hybrid copolymers with controlled dielectric properties for high-frequency applications.
Electronics represents the fastest-growing trajectory as 5G infrastructure and EV power electronics expand high-performance laminate demand.
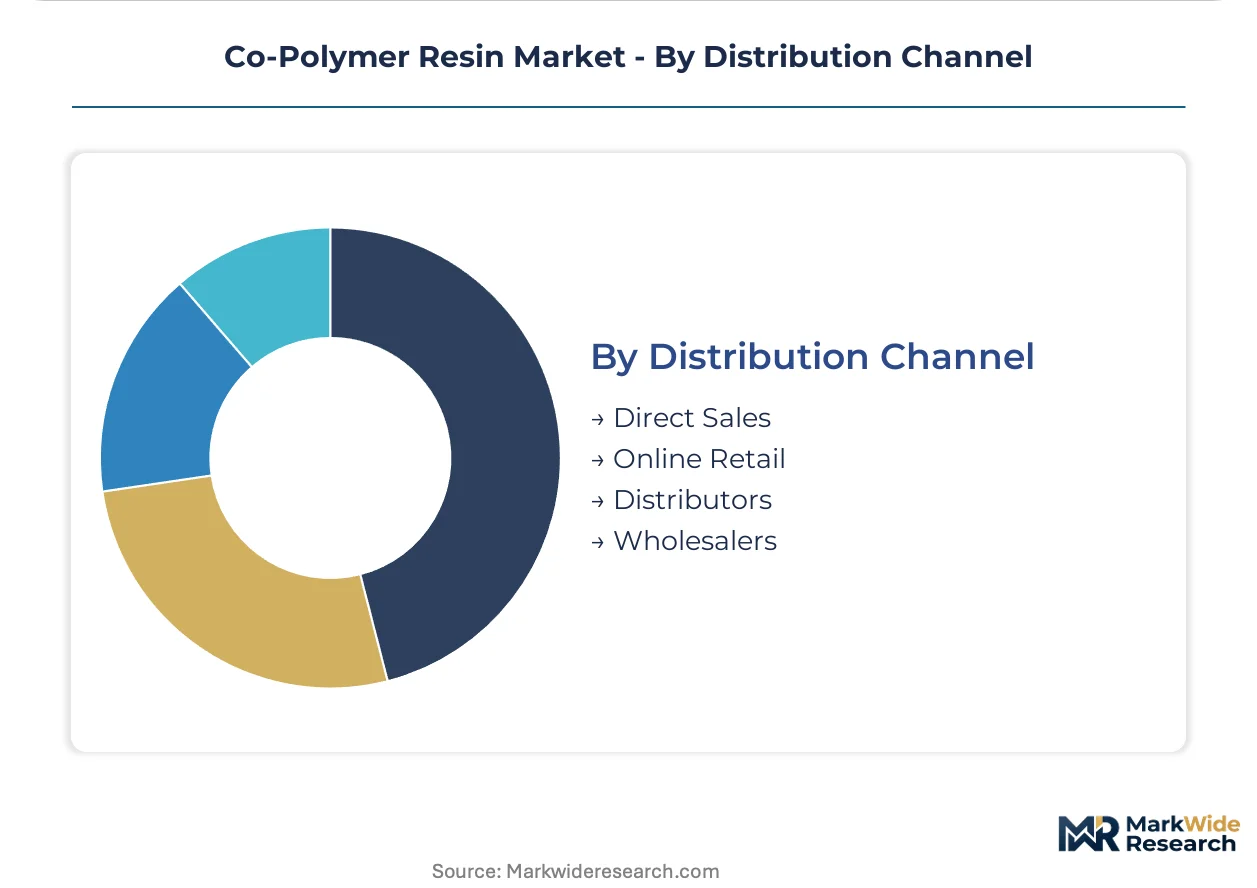
Distribution Channel:
Channel selection reflects order scale and technical service intensity, with bulk automotive contracts bypassing traditional intermediaries.
- Direct Sales:Platform-direct contracts link compounders to automotive OEM engineering centers, eliminating distributor margin. BASF and Dow maintain technical service teams at customer R&D facilities for co-development programs.
- Online Retail:Small-lot specialty grades and 3D printing filaments reach researchers and prototype shops through digital channels. Alibaba and specialty chemical platforms aggregate Asian producer offerings for global buyers.
- Distributors:Regional inventory positions serve mid-tier processors lacking volume for direct mill relationships. European distributors face margin compression as REACH documentation burdens increase operational costs.
- Wholesalers:Bulk commodity EVA and SBR grades flow through construction-focused supply chains with limited technical support. US Gulf Coast petrochemical wholesalers manage just-in-time delivery to domestic roofing membrane manufacturers.
Established volume flows through Distributors. Channel migration is accelerating toward Direct Sales as automotive platform consolidation concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in China concentrate EV battery packaging demand, while US Gulf Coast petrochemical corridors anchor ethylene-vinyl acetate supply. European REACH compliance redirects formulation procurement toward documented low-residual-monomer grades.
United States
Automotive lightweighting mandates from NHTSA and EPA drive ABS specification in structural bumper applications. Gulf Coast ethylene crackers supply EVA feedstock to domestic flexible packaging converters. Houston petrochemical clusters manage just-in-time delivery to roofing membrane manufacturers facing OSHA workplace exposure limits.
Germany
OEM engineering centers in Stuttgart and Munich specify PC-ABS grades with EU Green Deal carbon footprint documentation. REACH Article 33 SCIP database obligations force full material composition disclosure across automotive supply chains. BASF's Ludwigshafen complex dominates European automotive qualification programs with integrated precursor supply.
China
MIIT dual carbon goals accelerate substitution of solvent-borne coating systems in Yangtze River Delta manufacturing zones. Domestic EV production concentrates demand for flame-retardant epoxy-hybrid copolymers in cell-to-pack enclosures. Shenzhen and Shanghai battery integrators specify thermal-runaway barriers that EVA grades must pass before supplier approval.
India
Production-Linked Incentive schemes for advanced chemistry cell batteries create captive demand for copolymer encapsulants. DGFT import substitution policies favor domestic compounding capacity expansion in Gujarat and Maharashtra. Mumbai-Pune automotive corridors require simultaneous BIS and AIS certification for interior trim applications.
South Korea
CSRD-aligned disclosure frameworks from Seoul electronics brands audit supplier carbon intensity for ESG reporting. Busan-Ulsan petrochemical complexes supply SBR latex streams to tire plants facing MFDS rolling-resistance mandates. Daegu-Gyeongbuk regions concentrate epoxy-hybrid copolymer demand for PCB laminates in 5G infrastructure.
Co-Polymer Resin Market Competitive Environment
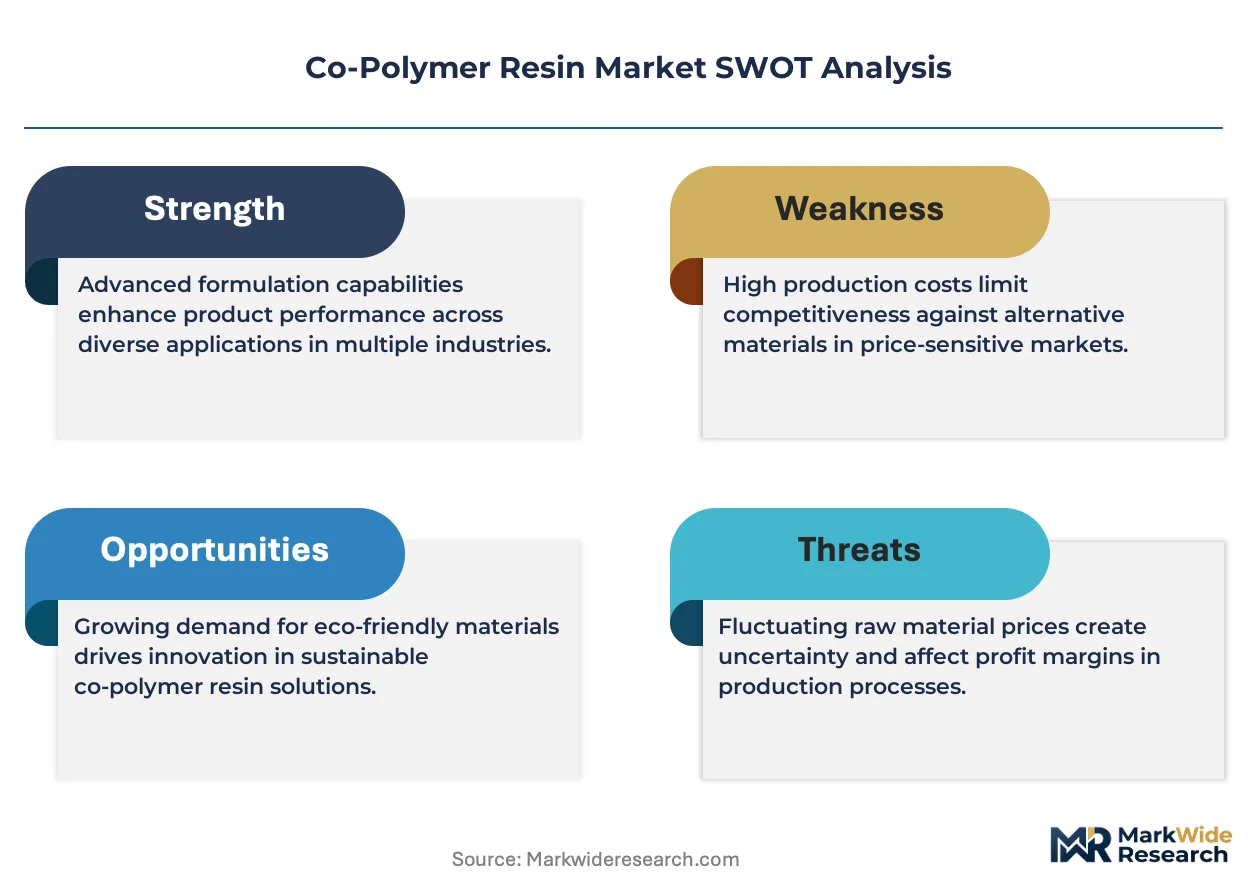
Top-tier vendors anchor integrated petrochemical supply, while mid-tier compounders specialize in reactive extrusion formulations. The market structures around three tiers: multinational chemical conglomerates with captive monomer supply, regional compounders with automotive qualification expertise, and specialty distributors serving prototype-scale buyers. Two dominant competitive moves reshape positioning: backward integration into pyrolysis-oil purification for mass-balance certified grades, and platform-direct technical service teams at OEM R&D facilities.
Within the integrated precursor tier, BASF SE and Dow exemplify divergent geographic anchoring strategies. BASF SE represents European automotive qualification dominance through Ludwigshafen complex integration. Dow occupies North American ethylene-vinyl acetate supply positioning through Gulf Coast scale. Kukdo Chemical Co., Ltd. exemplifies Asian electronics specialization, anchoring epoxy-hybrid copolymer expertise for laminate applications. These three entities collectively illustrate the market's tripartite regional specialization without exhausting competitive archetypes.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Huntsman International LLC |
| Olin Corporation |
| Westlake Corporation |
| DIC Corporation |
| Kukdo Chemical Co., Ltd. |
| Celanese Corporation |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon footprint documentation gates qualified supply for automotive-grade ABS and PC-ABS resins, while simultaneously filtering premium-tier pricing access to compounders with verified mass-balance certification. REACH SVHC disclosure requirements impose documentation costs that stratify pricing tiers between compliant European producers and non-compliant spot suppliers.
Pricing Analysis
Short lead-time premiums command substantial markups as automotive platform-direct contracts compress qualification cycles to 18-24 months. Three-tier pricing structure across premium, standard, and economy levels separates mass-balance certified grades from REACH-compliant standard tiers and spot-market commodity EVA. Price differentiation hinges on residual monomer certification and automotive qualification status. Pricing pressure stems from naphtha derivative volatility in Asia-Pacific spot markets. Construction sector buyers exhibit highest price sensitivity, while medical-grade SEBS purchasers absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Reverse logistics for pyrolysis-derived monomer streams enable circular feedstock integration at BASF's Ludwigshafen complex and Dow's Gulf Coast operations. Supply concentrates in Germany, China, and the US Gulf Coast, with ethylene crackers anchoring EVA feedstock availability. Raw material dependencies rest on benzene, butadiene, and vinyl acetate monomer flows. Single-source vulnerability clusters around South Korean and Chinese butadiene capacity. Distribution runs through platform-direct technical service teams for automotive OEMs, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Article 33 SCIP database obligations erect a cost-of-compliance barrier that moats qualified European compounders against non-compliant import competition. The regulation's material disclosure requirements demand supply-chain transparency investments that mid-tier Asian producers struggle to fund.
For Market Incumbents: Deploy mass-balance certification as the anchor lever for brand-owner sustainability commitments. BASF and Dow should deepen captive pyrolysis-oil purification capacity to secure packaging multinational offtake before chemical recycling scales. Defend automotive qualification status by maintaining parallel EPA, REACH, and China GB testing protocols despite technical service bandwidth strain. Threat: mid-tier compounders with reactive extrusion expertise poaching electronics laminate share. For New Entrants and Emerging Players: Alibaba and specialty chemical platforms offer the lowest-friction route to prototype-scale buyers in North American and European research markets. Target medical-grade SEBS certification under FDA 21 CFR 177.1520, where few Asian producers have completed full regulatory dossiers. White-space sits in India's Production-Linked Incentive schemes for advanced chemistry cell battery encapsulants. Go-to-market angle: partner with domestic Indian compounders lacking EV assembly scale. For Investors and Strategic Acquirers: First-mover pyrolysis-oil purification offtake agreements with packaging multinationals are the leading indicator that mass-balance certified copolymer capacity will command scarcity premiums. Long-term viability frames around 5-10 year windows for chemical recycling integration. Acquisition target archetype: mid-tier compounders with reactive extrusion expertise and existing automotive qualification relationships. Signal to watch: European electronics brands auditing supplier carbon intensity under CSRD-aligned disclosure frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis-Oil Purification | Mass-balance certification secures packaging multinational offtake before capacity scales. |
| Platform-Direct Technical Service Deployment | BASF and Dow co-development teams at OEM R&D facilities compress qualification cycles. |
| Medical-Grade SEBS Regulatory Dossier Completion | FDA 21 CFR 177.1520 compliance opens premium pricing in drug-delivery devices. |
| India PLI Scheme Domestic Compounding Capacity | Gujarat and Maharashtra expansion captures captive demand for EV battery encapsulants. |
| REACH SVHC-Free Grade Requalification | Hungary and Poland battery packagers demand documented SCIP database compliance. |
Study Parameters
Multi-period observation of EPA fuel-economy standard tightening, REACH SVHC listing expansions, and China MIIT dual carbon goal implementation anchored the trend analysis, supplemented by interviews with resin plant managers, automotive Tier 1 procurement leads, distribution channel partners, and technical R&D directors at compounders. Secondary validation drew from ECHA substance-of-very-high-concern notifications, US SEC 10-K petrochemical segment disclosures, Cefic plastics production statistics, and customs/trade flow data. Bottom-up grade-level volume builds triangulated against top-down end-use demand segmentation.
Input-output matrices mapped ethylene, benzene, and butadiene feedstock availability through steam cracker utilization rates to copolymer grade production capacity across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use vertical, automotive qualification status, and regional production hub. CAGRs derived from elasticity-adjusted demand projections tied to named regulatory mandates and OEM platform commitments. Industry-specific forecast inputs incorporated photovoltaic module anti-PID formulation specifications and EV battery thermal-runaway barrier testing protocols.
The model holds under stable regulatory harmonization timelines between EPA and California Air Resources Board thresholds; deviation in crude-derivative feedstock volatility or butadiene supply disruptions would shift volume and value trajectories. Forecasts reflect documented assumptions regarding automotive lightweighting penetration rates and chemical recycling capacity scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Polysulfide Market