
 Polyether Block Amide Market | 2026-2036
Polyether Block Amide Market Size, Share, and Industry Trends Forecast 2026-2036
Polyether Block Amide Market Analytics
Advanced extrusion and overmolding integration is reshaping how polyether block amide components are fabricated for minimally invasive medical devices. Arkema leverages its Pebax portfolio to sustain leadership in high-performance catheter shafts and balloon tubing. Evonik anchors its position through specialized polyamide 12 chemistry for electrical insulation and cable jacketing. BASF SE competes across automotive fuel line and pneumatic tubing segments with tailored PA 610 and PA 1010 grades.
Polyether block amide denotes a thermoplastic elastomer comprising rigid polyamide blocks and flexible polyether segments, typically processed by injection molding or extrusion at melt temperatures between 170°C and 280°C, yielding Shore D hardness ranging from 25 to 70 depending on block ratio. PA 12 dominates current volume owing to established supply chains and hydrolysis resistance, while PA 1010 represents the fastest-expanding chemistry as bio-based feedstocks gain traction among sustainability-focused compounders. Automotive Components leads application value due to under-the-hood thermal and chemical exposure requirements, though Medical is displacing traditional silicone in long-term implantable delivery systems.
FDA 21 CFR biocompatibility testing and EU MDR Class III device regulations govern material qualification timelines for medical-grade polyether block amide suppliers. REACH substance restrictions and ECHA candidate list screenings constrain certain plasticizer and stabilizer chemistries, pushing reformulation toward halogen-free additive packages. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance scrutiny, as fluorinated processing aids face phasedown pressure that could redirect compounding routes toward alternative lubricant systems.
Market Dynamics
Medical device OEMs are consolidating supplier relationships around vertically integrated compounders capable of delivering FDA 21 CFR biocompatibility documentation and REACH-compliant material traceability from a single source. This procurement consolidation is compressing the viable supplier base while elevating technical service requirements.
Growth Catalysts
- EU MDR Class III device regulations:Stringent material qualification timelines are favoring established polyether block amide suppliers with validated master files, accelerating replacement of silicone in long-term implantable delivery systems.
- Minimally invasive surgical expansion:Catheter shaft miniaturization below 2 French diameter demands Pebax-based multilayer tubing with tailored Shore D hardness gradients.
- Germany's precision medical cluster:Concentrated demand around Freiburg and Stuttgart creates captive pull for high-purity PA 12 and bio-based PA 1010 grades.
Market Restraints
- Caprolactam feedstock volatility:Polyamide 12 precursor costs fluctuate with cyclohexane supply disruptions, compressing compounder margins during crude oil price spikes.
- REACH substance restrictions:ECHA candidate list screenings of certain plasticizers and stabilizers force reformulation cycles that extend qualification timelines by 12-18 months.
- Fluoropolymer substitution threat:FEP and ETFE tubing retains dominance in high-temperature autoclave sterilization applications above 134°C.
Strategic Opportunities
- India's CDSCO medical device registration pathway:Simplified import licensing for notified body-certified materials opens access to a surgical instrument manufacturing base expanding at 15% annually.
- Automotive thermal management convergence:Battery electric vehicle coolant line integration with ADAS sensor cabling creates demand for single-material solutions combining chemical resistance and electrical insulation.
- EU Green Deal bio-content mandates:PA 1010 derived from castor oil feedstocks qualifies for sustainable procurement preferences in public healthcare tenders.
Industry Challenges
- Multilayer extrusion technician scarcity:Precision catheter manufacturing requires operators trained in concentricity control and balloon-forming thermal profiles, with limited vocational pipeline output.
- ISO 10993-18 chemical characterization backlog:Third-party testing laboratory capacity constraints extend biocompatibility documentation delivery from 16 to 28 weeks.
- Legacy pneumatic tubing specification inertia:Automotive Tier 1 suppliers resist requalifying PA 610 fuel line assemblies despite PA 1010 performance equivalence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyether Block Amide Market |
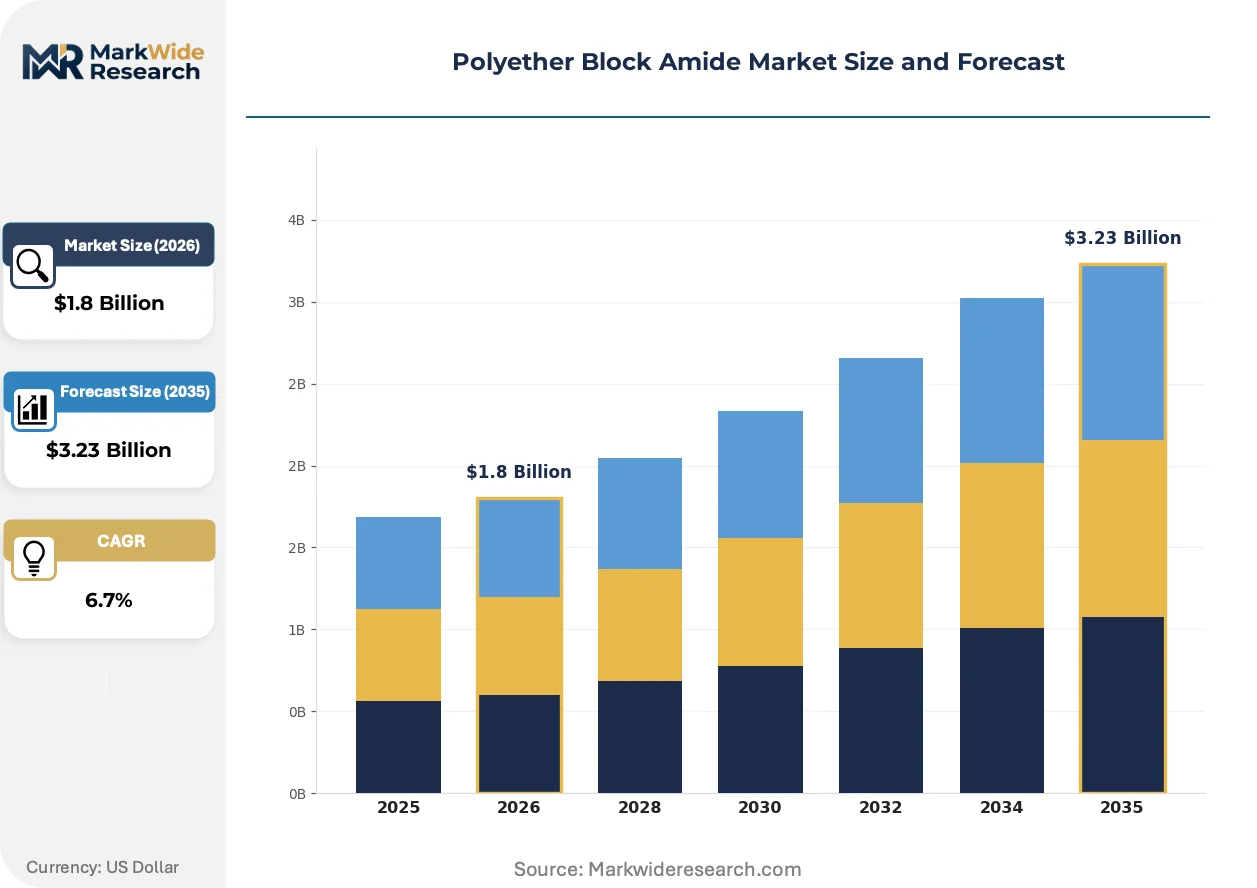
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 11, PA 12, PA 610, PA 1010 Application: Automotive Components, Electrical Insulations, Adhesives, Coatings End User: Automotive, Electronics, Consumer Goods, Medical Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Arkema, Evonik, UBE Corporation, BASF SE, EMS, Solvay, Huntsman Corporation, DuPont, SAINT-GOBAIN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyether Block Amide Market Evolving Landscape
Material science convergence with digital manufacturing protocols is redefining how polyether block amide specifications are transmitted from OEM design teams to extrusion floor operations. This interface standardization is compressing development cycles.
Coextrusion of Pebax with thermoplastic polyurethane is hybridizing catheter shaft constructions, enabling torque response and kink resistance in a single continuous profile. Neurovascular device manufacturers in Minnesota and Massachusetts are adopting these constructions for stroke intervention platforms. The technology is hybridizing previously separate silicone and nylon component supply chains into unified thermoplastic elastomer sourcing.
EPA scrutiny of per- and polyfluoroalkyl substances is forcing compounders to eliminate fluorinated processing aids from extrusion operations. Arkema and Evonik are reformulating lubricant packages toward halogen-free alternatives ahead of anticipated phasedown mandates. Medical tubing extruders in North Carolina and Ohio face the steepest compliance timelines given FDA master file amendment requirements.
Hospital procurement consortia are consolidating polymer sourcing decisions through centralized value analysis committees, displacing individual physician preference item selection. This concentration elevates total cost of ownership analytics over unit price in supplier selection. The shift is most visible in German university hospital networks and US integrated delivery networks exceeding 50 facilities.
Polyether Block Amide Market Segmentation
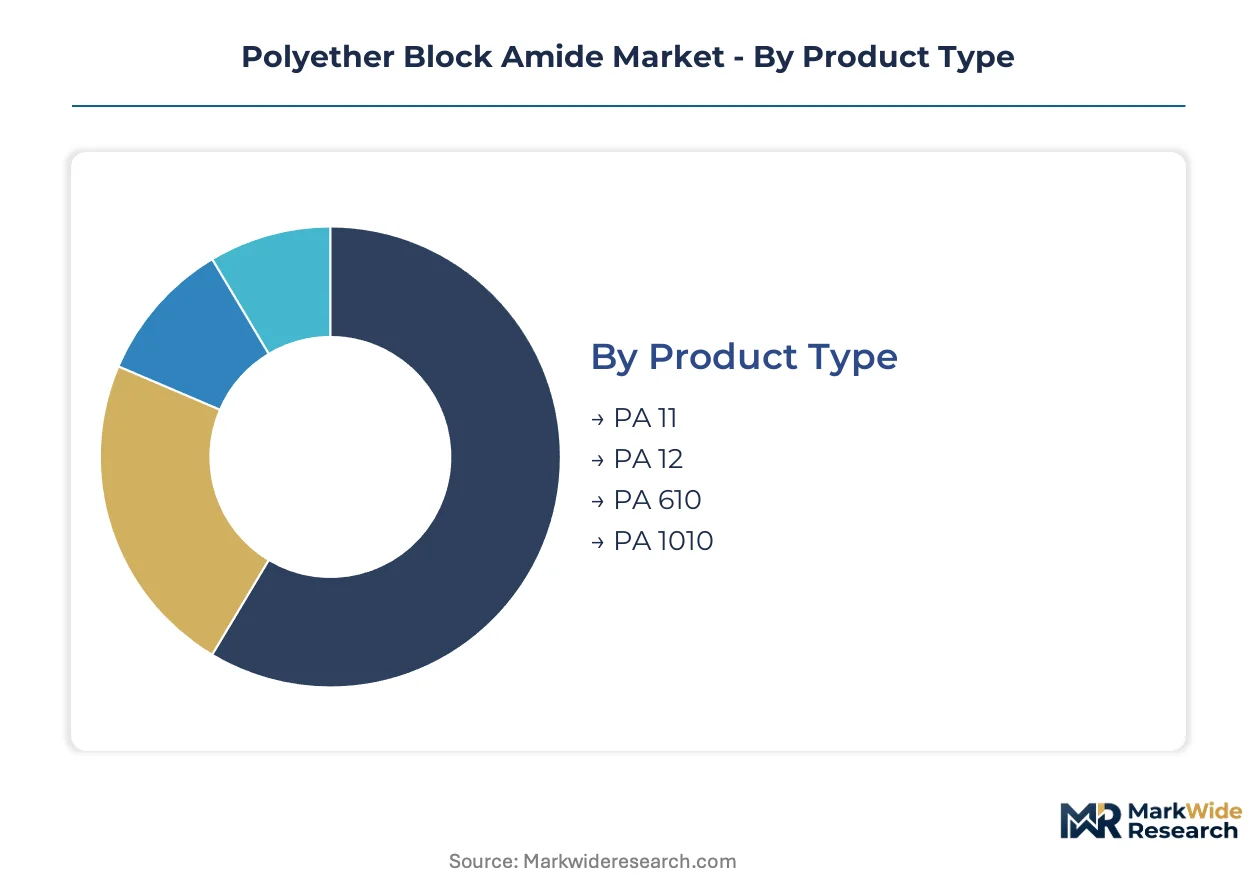
Segmentation in the polyether block amide market reveals distinct procurement rhythms across chemistry grades and end-use verticals. Material qualification timelines vary dramatically between automotive fuel line approvals and FDA 21 CFR biocompatibility documentation for medical devices.
Product Type:
PA 12 turns inventory fastest through established automotive supply chains, while PA 1010 qualification cycles extend longest due to bio-based feedstock traceability requirements.
- PA 12:Polyamide 12 block chemistry delivers hydrolysis resistance and established supply chain density. Demand concentrates in Germany's Stuttgart automotive basin for under-the-hood fuel and pneumatic tubing where thermal cycling durability is non-negotiable. REACH-compliant master batches from Arkema and Evonik dominate specification sheets.
- PA 1010:Castor oil-derived bio-polyamide blocks qualify for EU Green Deal sustainable procurement preferences. Expansion concentrates in Freiburg's precision medical cluster where long-term implantable delivery systems require renewable content documentation for public hospital tenders.
- PA 11:Rilsan-branded chemistry from Arkema serves niche aerospace cable jacketing with low-temperature flexibility.
- PA 610:Sebacic acid-based blocks occupy mid-tier electrical insulation with cost-positioning between PA 12 and bio-grades.
PA 12 dominates installed base. PA 1010 is where expansion concentrates.
Application:
Cost tiering separates specification-driven automotive contracts from price-sensitive coating formulations.
- Automotive Components:Fuel lines, pneumatic tubing, and thermal management hoses demand Shore D 55-70 hardness grades with continuous service temperatures above 125°C. Stuttgart-based Tier 1 suppliers specify Arkema Pebax for battery electric vehicle coolant integration combining chemical resistance with electrical insulation properties.
- Electrical Insulations:Cable jacketing and wire coatings require tailored dielectric strength with flexibility retention. Evonik's specialized polyamide 12 chemistry anchors this segment for offshore wind turbine cabling in the North Sea.
- Adhesives:Hot-melt formulations for textile lamination favor lower-viscosity PA 610 grades.
- Coatings:Powder coating applications for metal substrates represent the most price-elastic demand tier.
Automotive Components commands premium pricing. Electrical Insulations is climbing the fastest on electrification infrastructure buildout.
End User:
Customer type determines technical service intensity, with medical device OEMs requiring deepest compounder integration.
- Medical:Catheter shafts, balloon tubing, and surgical instruments demand FDA 21 CFR biocompatibility documentation and EU MDR Class III device master files. Minnesota and Massachusetts neurovascular device manufacturers specify Pebax-based multilayer constructions below 2 French diameter.
- Automotive:Fuel system and thermal management procurement consolidates around vertically integrated compounders capable of REACH-compliant material traceability from single sources.
- Electronics:Connector overmolding and cable management favors medium-hardness grades with rapid cycle times.
- Consumer Goods:Sporting equipment and appliance components represent specification-light, volume-driven demand.
Automotive anchors volume throughput. Medical is gaining share fastest on silicone displacement in long-term implants.
Distribution Channel:
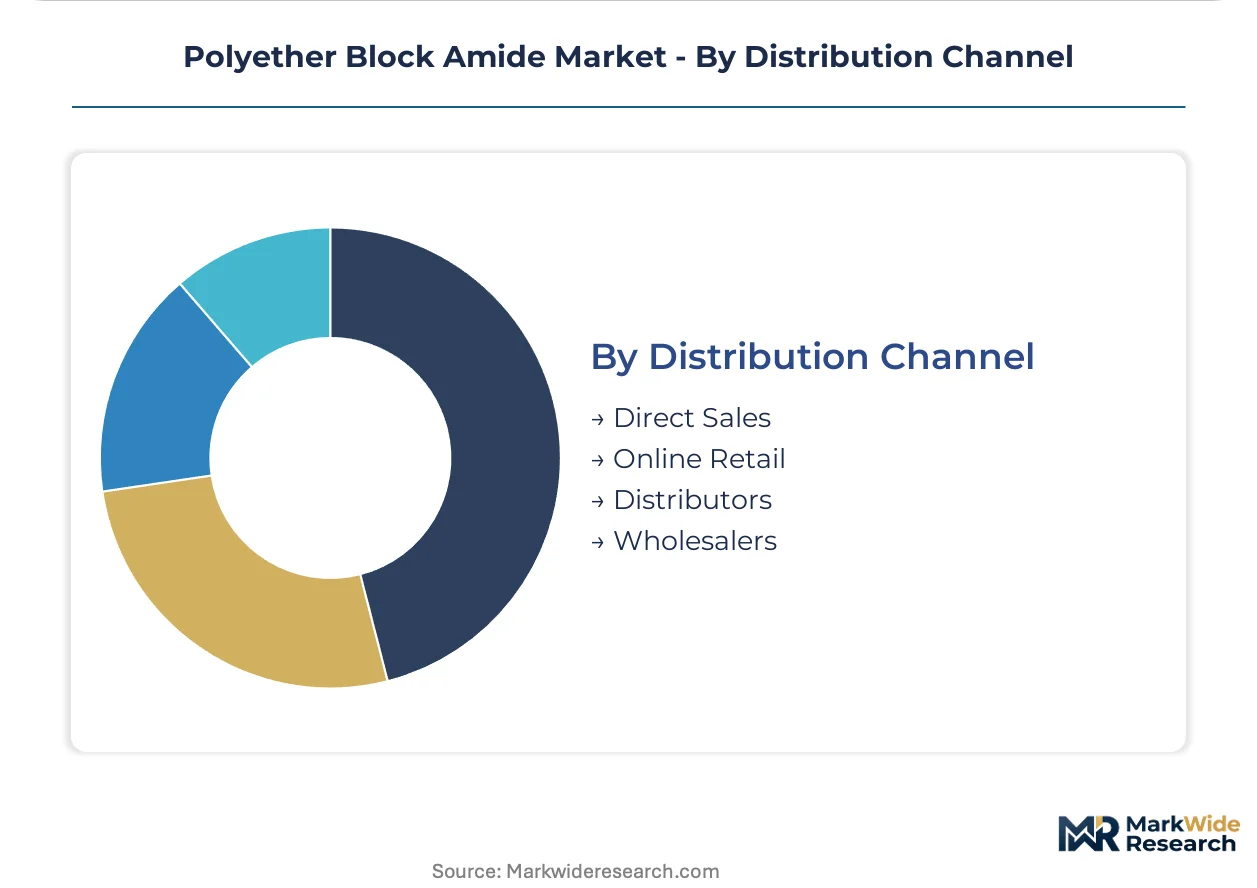
Supply concentration favors direct relationships for qualified medical grades, while commoditized automotive volumes flow through distributor networks.
- Direct Sales:Medical device OEMs and automotive Tier 1 suppliers negotiate frame contracts with compounders for validated master file grades. Arkema and Evonik maintain dedicated technical service teams for catheter shaft and fuel line co-development programs.
- Distributors:Regional polymer distributors stock standard PA 12 and PA 610 grades for automotive aftermarket and general industrial applications with shorter lead time requirements.
- Online Retail:Small-lot specialty compounders serve prototyping and R&D quantities through e-commerce portals.
- Wholesalers:Bulk volume aggregation for coating and adhesive formulators with limited technical specification needs.
Direct Sales captures margin concentration. Distributors handle volume velocity for specification-mature grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device OEMs and automotive Tier 1 suppliers cluster in manufacturing basins with validated compounder relationships and REACH-compliant material traceability infrastructure. Procurement decisions concentrate where FDA master file documentation and EU MDR Class III device certification intersect with established extrusion capabilities.
Germany
Freiburg's precision medical cluster drives demand for high-purity PA 12 catheter tubing, while Stuttgart's automotive basin specifies Pebax grades for battery electric vehicle coolant integration. REACH substance restrictions and EU MDR certification requirements tighten material traceability standards for compounders serving both segments. Baden-Württemberg hosts the densest concentration of vertically integrated medical device suppliers in Europe.
United States
Minnesota and Massachusetts neurovascular device manufacturers specify multilayer Pebax constructions below 2 French diameter for stroke intervention platforms. FDA 21 CFR biocompatibility testing requirements govern material qualification timelines, with EPA per- and polyfluoroalkyl substance scrutiny forcing reformulation of fluorinated processing aids. North Carolina and Ohio extrusion operations face compressed compliance timelines for halogen-free additive packages.
China
Surgical instrument manufacturing bases expand adoption of thermoplastic elastomers for catheter tubing as domestic medical device production scales. NMPA regulatory pathways for imported polymer materials create qualification bottlenecks for foreign compounders. Yangtze River Delta medical device clusters concentrate demand for bio-based PA 1010 grades in public hospital procurement.
India
CDSCO simplified import licensing for notified body-certified materials opens access to surgical instrument manufacturing expanding at 15% annually. Domestic catheter and guidewire producers qualify polyether block amide grades for export markets. Maharashtra and Gujarat medical device parks attract compounder technical service investments.
Japan
PMDA quality management system requirements extend material qualification cycles for long-term implantable delivery systems. METI industrial policy supports domestic polymer compounding capacity for automotive thermal management applications. Kansai region medical device manufacturers specify high-clarity grades for minimally invasive surgical instruments.
Polyether Block Amide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification-driven medical grades and volume-anchored automotive segments. Market structure consolidates around vertically integrated compounders capable of delivering REACH-compliant traceability and FDA master file documentation from single sources. Three archetypes dominate: diversified chemical conglomerates with polymer portfolios, specialized polyamide compounders with medical-grade purification capabilities, and regional distributors serving specification-mature automotive volumes. Competitive moves center on backward integration into caprolactam feedstocks and strategic partnerships with catheter shaft OEMs for co-development programs.
Within the diversified chemical conglomerate tier, Arkema and BASF SE exemplify channel-controlling positions through established Pebax and tailored polyamide grade portfolios. Evonik anchors the specialized compounder archetype with dedicated polyamide 12 chemistry for electrical insulation and medical tubing applications. These three entities represent the primary technical service capacity for multilayer extrusion co-development with medical device OEMs and automotive Tier 1 suppliers.
| Leading Market Players |
|---|
| Arkema |
| Evonik |
| UBE Corporation |
| BASF SE |
| EMS |
| Solvay |
| Huntsman Corporation |
| DuPont |
| SAINT-GOBAIN |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp barge freight corridors govern caprolactam feedstock cost dynamics, concentrating pricing power among compounders with captive European supply while forcing downstream differentiation between REACH-certified medical grades and standard automotive volumes.
Pricing Analysis
Cost-plus contracts indexed to cyclohexane spot markets dominate PA 12 procurement, with Arkema and Evonik applying premium markups for FDA master file documentation against commodity-grade PA 610. Price differentiation separates EU MDR Class III certified lots from standard industrial batches by certification burden and testing backlog. Pricing pressure stems from caprolactam volatility compressing compounder margins during crude oil spikes. Automotive Tier 1 suppliers exhibit highest price sensitivity, while neurovascular device OEMs absorb premiums for validated biocompatibility packages.
Supply Chain Analysis
Upstream caprolactam production anchors in Germany, France, and Russia, with polymerization capacity concentrating around Ludwigshafen and Marl. Polyether block amide compounding draws from sebacic acid, castor oil derivatives, and polyether diols as critical inputs. Single-source vulnerability runs through Russian cyclohexane supply exposed to trade restriction risk. Distribution runs through direct frame contracts for medical grades and regional distributors for specification-mature automotive volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
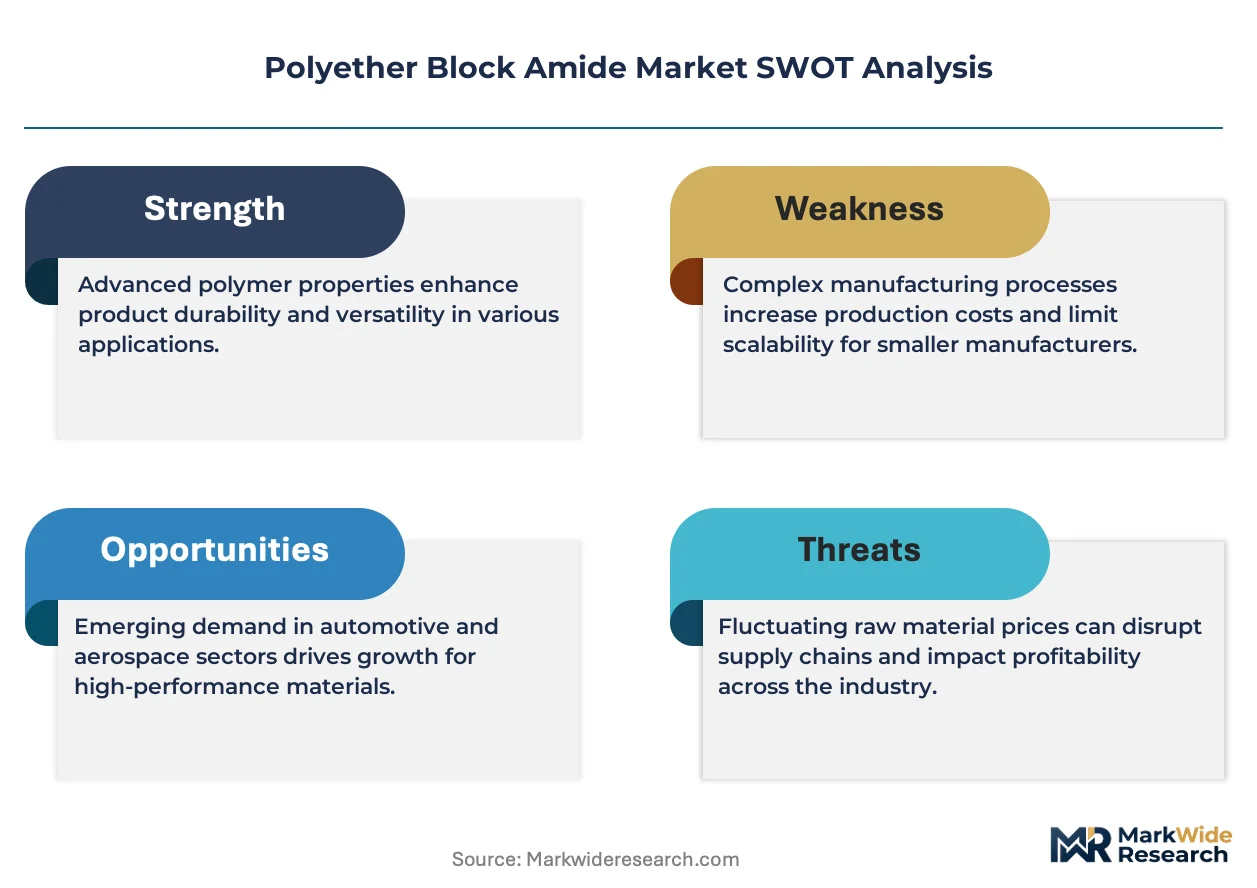
This market functions as a regulatory entrenchment story, where FDA 21 CFR master file validation and EU MDR Class III certification create switching costs that compounder incumbents exploit to defend margin structures.
For Market Incumbents: Build certification moats through accelerated ISO 10993-18 testing capacity investments to compress 28-week documentation timelines toward 16-week delivery. Threat from fluoropolymer substitution in autoclave applications above 134°C demands counter-positioning through halogen-free additive reformulation ahead of EPA phasedown mandates. Leverage rests on backward integration into castor oil feedstocks for PA 1010 bio-content positioning in EU Green Deal tenders. For New Entrants and Emerging Players: India's CDSCO simplified import licensing represents the most penetrable regulatory pathway, with Maharashtra and Gujarat medical device parks expanding at 15% annually and lacking indigenous high-purity PA 12 supply. Target catheter shaft prototyping services for Minnesota and Massachusetts neurovascular OEMs as entry wedge, co-developing multilayer extrusion capabilities with regional technical service partnerships rather than asset-heavy compounder investments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking portfolio rationalization, specifically polyamide divisions with medical-grade purification assets but subscale automotive volume positions. Long-term viability centers on regulatory entrenchment durability against bio-based polymer substitution threats. Signal to watch is CDSCO registration acceleration triggering compounder technical service deployment decisions in India.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Feedstocks | PA 1010 bio-content positioning captures EU Green Deal sustainable procurement preferences in Freiburg medical cluster tenders. |
| Halogen-Free Additive Reformulation | EPA per- and polyfluoroalkyl substance scrutiny forces lubricant package redesign ahead of anticipated processing aid phasedown mandates. |
| CDSCO Technical Service Investment | Simplified import licensing for notified body-certified materials opens access to Maharashtra surgical instrument manufacturing expansion. |
| ISO 10993-18 Testing Capacity Expansion | Third-party laboratory backlog extension from 16 to 28 weeks creates competitive advantage through faster biocompatibility documentation delivery. |
| Multilayer Extrusion Co-Development Programs | Catheter shaft miniaturization below 2 French diameter demands Pebax-based torque response and kink resistance hybrid constructions. |
Research Methodology
The analysis maps PA 12, PA 1010, PA 11, and PA 610 chemistry grades, each validated through catheter shaft design engineers, automotive Tier 1 procurement leads, polymer distribution channel partners, and regulatory affairs specialists at compounders. Primary interview data triangulates against customs trade records, ECHA REACH registration databases, FDA 510(k) and master file submissions, and SEC filings from disclosed polymer segments. Bottom-up volume modeling from end-use application demand and top-down supply capacity verification ensure convergence.
Assumptions held fixed include EU MDR Class III device regulation timelines and REACH substance restriction enforcement intensity, while caprolactam feedstock cost trajectories and EPA fluorinated processing aid phasedown schedules were varied across sensitivity scenarios. Segmentation dimensions span chemistry block ratio, Shore D hardness tier, end-use vertical, and geographic regulatory cluster. CAGRs derive from installed base replacement rates and silicone displacement elasticity in long-term implantable applications.
Practitioners should monitor CDSCO registration velocity, NMPA polymer import qualification bottlenecks, and ECHA candidate list expansion for early signals of forecast revision. Cross-checking against customs import data for polyether block amide resin volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market