
 Asia-Pacific Polyvinylpyrrolidone (PVP) Market | 2026-2036
Asia-Pacific Polyvinylpyrrolidone (PVP) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyvinylpyrrolidone (PVP) Market Outlook
Multi-sourced pharmaceutical-grade feedstock procurement is realigning how regional formulators manage supply security and cost exposure. Boai NKY Pharmaceuticals Ltd. leverages captive acetylene-to-vinylpyrrolidone capacity to insulate margin structures from monomer volatility. Ashland Global Holdings Inc. competes through technical service depth in complex drug delivery applications across Japan and South Korea. BASF SE anchors its Asia-Pacific position with integrated Ludwigshafen-to-Shanghai supply chain coordination.
Polyvinylpyrrolidone is a water-soluble polymer synthesized via free-radical polymerization of N-vinylpyrrolidone monomer, with K-value (viscosity-molecular weight index) spanning 12–90 for commercial grades. Its amphoteric solubility profile and complexation capacity with hydrophobic actives make it indispensable as a binder, film former, and solubilizer in oral dosage forms and topical preparations. Pharmaceutical grade commands the dominant value share due to stringent endotoxin and peroxide specifications that filter out commodity producers. Cosmetic grade registers faster volume expansion as K-beauty and J-beauty brands incorporate PVP-hair fixative complexes into styling formulations. Industrial grade occupies a mature, price-sensitive position where adhesive and textile dye applications tolerate broader K-value ranges.
China's NMPA enforces pharmaceutical excipient registration under关联审评审批 (associated review and approval) rules that tie PVP quality to drug product licensure. Japan's PMDA maintains ICH Q3D elemental impurity alignment for excipients used in export-oriented formulations. India's CDSCO and BIS jointly govern import testing protocols for PVP destined into domestic generic tablet production. Stakeholders must monitor how China's SAMR enforcement of GB standards for food-grade PVP migrates toward pharmaceutical-grade parity, as this convergence would reshape supplier qualification burdens and regional trade flows.
Market Dynamics
China's NMPA关联审评审批 rules are tightening pharmaceutical excipient accountability, forcing PVP suppliers to align batch documentation with drug product licensure cycles and compressing qualification timelines for cross-border shipments.
Growth Catalysts
- Tablet formulation complexity:Multi-layer and sustained-release oral dosages require pharmaceutical-grade PVP as a controlled-release matrix. Formulators in India's CDSCO-regulated facilities are expanding binder specifications to accommodate high-shear granulation demands.
- Cosmetic grade volume expansion:K-beauty and J-beauty brands are incorporating PVP-hair fixative complexes into styling formulations. South Korea's MFDS cosmetic notification pathway enables faster ingredient approval for film-forming polymers.
- GB standards convergence:China's SAMR enforcement of food-grade PVP purity benchmarks is migrating toward pharmaceutical-grade parity. This regulatory elevation filters out commodity producers and consolidates qualified supplier pools.
Market Restraints
- Vinylpyrrolidone monomer volatility:Acetylene-based N-vinylpyrrolidone synthesis exposes margin structures to petrochemical feedstock swings. Captive acetylene capacity remains concentrated among integrated Chinese producers.
- Endotoxin specification barriers:Pharmaceutical-grade PVP requires sub-10 EU/g endotoxin limits that exclude regional commodity manufacturers. Testing infrastructure gaps in Southeast Asian supply bases extend certification timelines.
- Cellulose ether substitution:Hydroxypropyl methylcellulose competes in tablet binding applications where delayed-release profiles are acceptable. Generic tablet producers in India's BIS-regulated sector evaluate cost-performance trade-offs.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing:Greenfield API facilities in Binh Duong province lack established excipient supplier networks. PVP distributors can anchor qualification programs ahead of formulation scale-up.
- Solubilization complexation:Amorphous solid dispersion applications for poorly soluble actives expand PVP's role beyond conventional binders. Japan's PMDA QbD guidelines encourage polymer-drug compatibility studies.
- Digital batch release platforms:Blockchain-anchored documentation accelerates cross-border customs clearance for pharmaceutical excipients. Shanghai customs pilots are reducing port detention for EU-sourced PVP.
Industry Challenges
- Analytical method harmonization:Peroxide value testing protocols vary between China's GB standards and Japan's PMDA pharmacopoeial references. Dual-method validation burdens contract laboratories serving multinational formulators.
- ICH Q3D elemental impurity compliance:Excipient producers must demonstrate control over catalyst residues from vinylpyrrolidone polymerization. X-ray fluorescence capability gaps at mid-tier Chinese facilities delay audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyvinylpyrrolidone (PVP) Market |
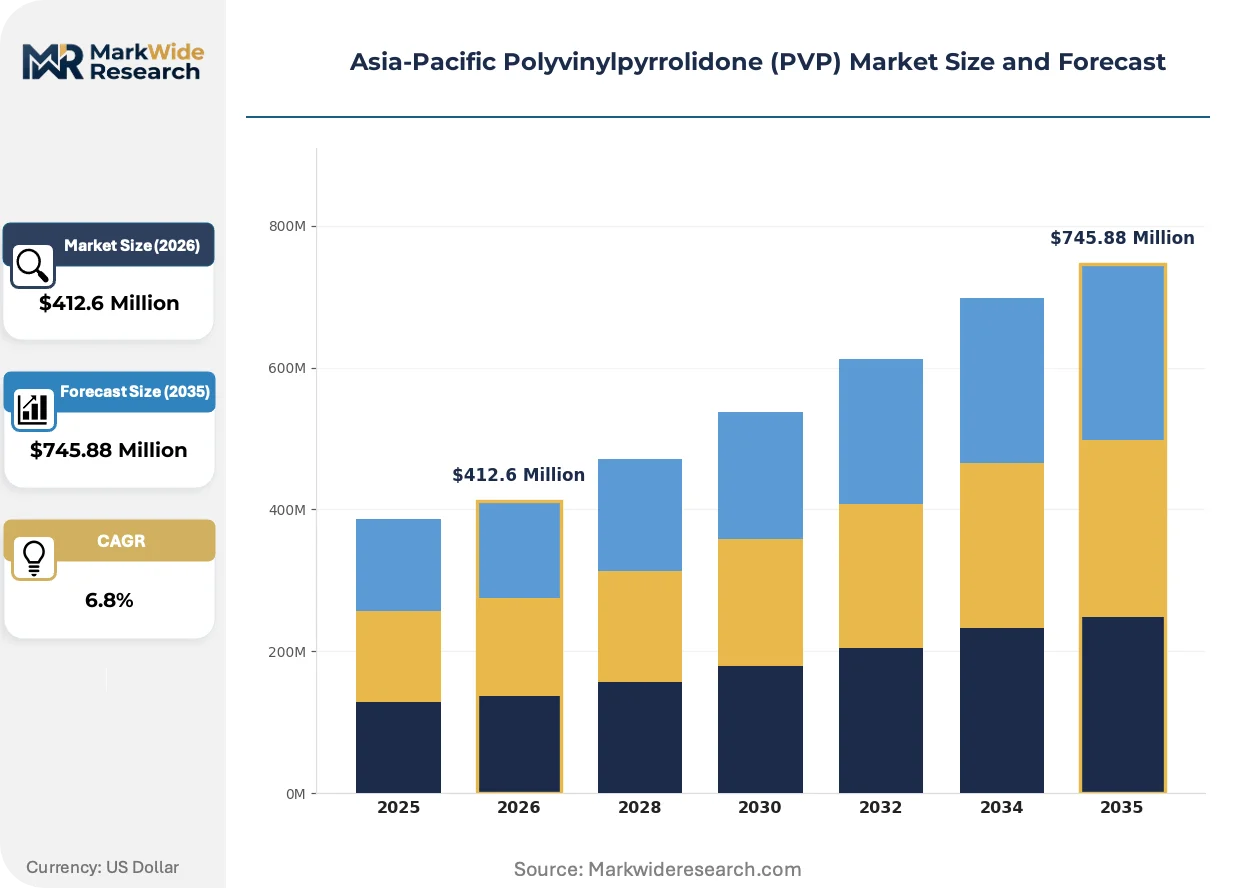
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Cosmetic Grade, Industrial Grade, Food Grade Application: Pharmaceuticals, Personal Care, Food & Beverages, Adhesives End User: Manufacturers, Healthcare Providers, Food Industry, Cosmetic Companies Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Boai NKY Pharmaceuticals Ltd., Anhui Wanwei Group Co., Ltd., BASF SE, Lotte Fine Chemical, Zhejiang Tianyi Chemical Co., Ltd., Ashland Global Holdings Inc., Merck KGaA, SNF Floerger, Nippon Shokubai Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyvinylpyrrolidone (PVP) Market Strategic Shifts
Continuous processing technologies and real-time release testing are compressing batch cycle times for pharmaceutical-grade PVP, while regulatory data integrity requirements reshape documentation architectures across Asia-Pacific supply chains.
Controlled-release matrix systems employing high-K-value PVP are overtaking conventional hydroxypropyl cellulose in sustained-release tablet cores. Japanese formulators at PMDA-inspected sites are adopting these complexes for once-daily cardiovascular dosages. The technology is overtaking batch-release paradigms by enabling real-time dissolution monitoring during compression.
China's GB 1886.73 food additive standard revisions are extending purity specifications toward pharmaceutical-grade endotoxin and peroxide thresholds. Domestic producers face capital outlays for sterile filtration infrastructure previously reserved for drug substance manufacturing. Pharmaceutical-grade PVP imports from BASF's Ludwigshafen complex are capturing share among conservative formulators pending domestic certification completion.
Formulator procurement teams are consolidating excipient supplier panels to reduce audit burden under ICH Q7 and Q11 guidelines. Japanese and South Korean drug manufacturers are disqualifying single-grade commodity PVP sources in favor of dual pharmaceutical-cosmetic grade producers. The concentration is most visible in Osaka and Seoul formulation clusters where quality agreement standardization accelerates vendor rationalization.
Asia-Pacific Polyvinylpyrrolidone (PVP) Market Segmentation
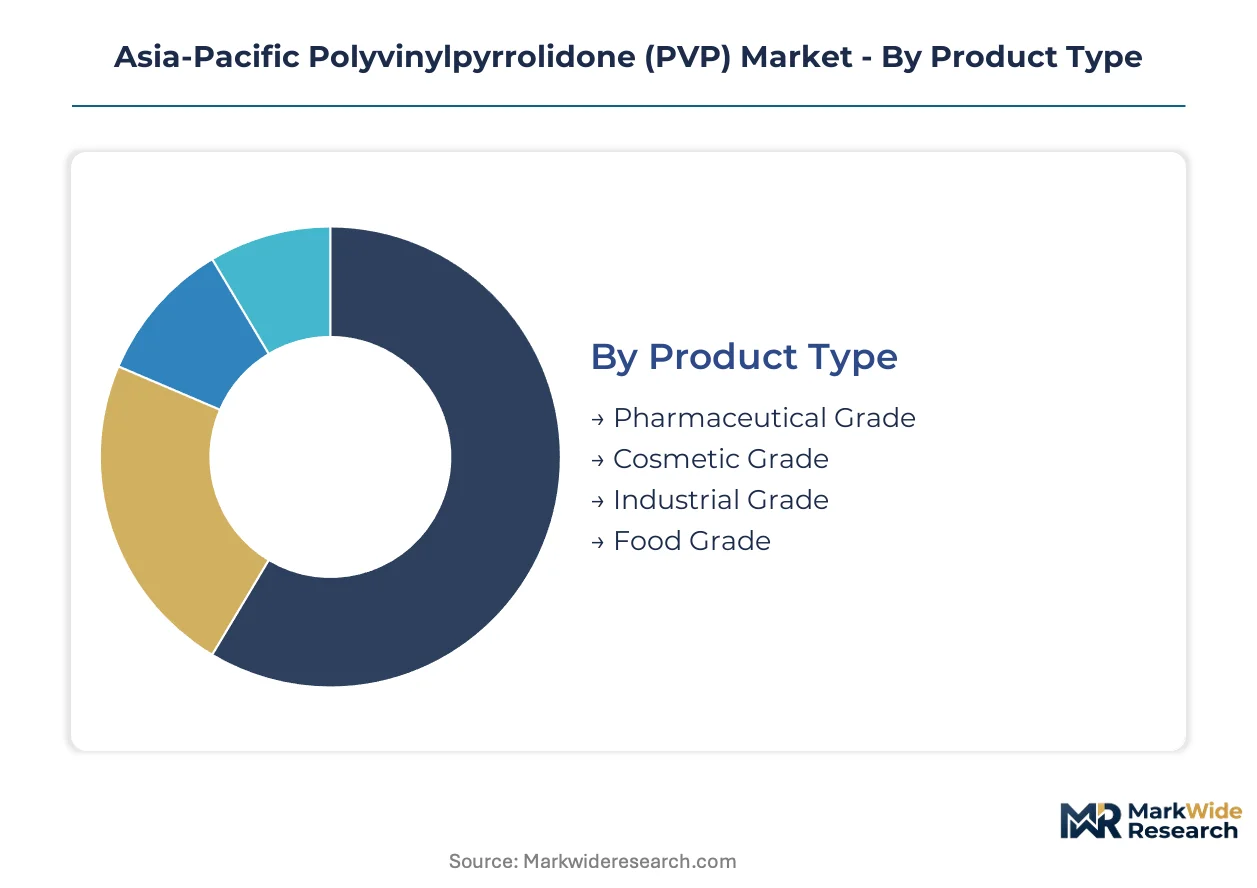
Segmentation in the Asia-Pacific PVP market reveals how purity specifications and regulatory pathways fragment procurement strategies across pharmaceutical, cosmetic, and industrial buyers. Each tier operates under distinct certification burdens that reshape supplier qualification timelines and margin structures.
Product Type:
Purity thresholds and endotoxin specifications drive buyer selection, with regulatory grade boundaries determining which producers can serve pharmaceutical versus commodity applications.
- Pharmaceutical Grade:Sub-10 EU/g endotoxin limits and peroxide value controls under China's NMPA关联审评审批 rules filter out commodity producers. Formulators in Shanghai and Zhejiang clusters require batch documentation tied to drug product licensure cycles, compressing qualification windows for cross-border shipments.
- Cosmetic Grade:Film-forming polymers for hair fixative complexes in K-beauty and J-beauty formulations carry lower purity thresholds than pharmaceutical grades. South Korea's MFDS cosmetic notification pathway enables faster ingredient approval, accelerating volume expansion in Seoul formulation clusters.
- Industrial Grade:Adhesive and textile dye applications tolerate broader K-value ranges from 12–90. Price sensitivity dominates procurement as buyers prioritize cost over endotoxin controls.
- Food Grade:China's GB 1886.73 standard revisions are extending purity specifications toward pharmaceutical-grade parity. SAMR enforcement is forcing capital outlays for sterile filtration infrastructure previously reserved for drug substance manufacturing.
Pharmaceutical Grade leads on scale; Cosmetic Grade leads on momentum.
Application:
End-use concentration patterns align with regional manufacturing clusters and regulatory inspection intensity.
- Pharmaceuticals:Multi-layer and sustained-release oral dosages require controlled-release matrix systems. India's CDSCO-regulated facilities are expanding binder specifications to accommodate high-shear granulation demands for generic tablet production.
- Personal Care:PVP-hair fixative complexes dominate styling formulations across South Korean and Japanese cosmetic brands. Osaka and Seoul formulation clusters are consolidating supplier panels to reduce audit burden under ICH Q7 guidelines.
- Food & Beverages:Food-grade PVP serves as a stabilizer and clarifying agent. China's SAMR migration of GB standards toward pharmaceutical-grade parity is reshaping supplier qualification pools.
- Adhesives:Industrial-grade PVP functions as a tackifier and viscosity modifier. Applications tolerate broader K-value ranges and prioritize cost performance over purity certification.
Pharmaceuticals anchors revenue concentration; Personal Care is climbing the fastest.
End User:
Procurement sophistication varies sharply between integrated manufacturers and fragmented downstream buyers.
- Manufacturers:Active pharmaceutical ingredient producers near Shanghai and Zhejiang province cluster demand pharmaceutical-grade PVP with full batch traceability. Captive acetylene-to-vinylpyrrolidone capacity insulates integrated Chinese producers from monomer volatility.
- Healthcare Providers:Hospital and clinic pharmacies sourcing compounded formulations require smaller lot sizes with rapid turnaround. Documentation burdens under Japan's PMDA ICH Q3D alignment extend lead times for import sourcing.
- Food Industry:Processors and ingredient blenders face GB standard convergence pressures as China's SAMR elevates purity benchmarks. Testing infrastructure gaps at mid-tier facilities delay audit readiness.
- Cosmetic Companies:K-beauty and J-beauty brands prioritize film-forming performance over pharmaceutical-grade certification. MFDS notification pathways enable faster formulation iteration than pharmaceutical excipient registration.
Manufacturers dominate procurement volume; Cosmetic Companies show steepest expansion trajectory.
Distribution Channel:
Channel selection reflects lot size requirements, documentation complexity, and customs clearance speed.
- Online Retail:Small-lot cosmetic and food-grade PVP moves through B2B platforms serving formulation laboratories and regional blenders. Documentation standardization remains uneven across cross-border shipments.
- Wholesale Distributors:Regional distributors stock pharmaceutical and industrial grades for just-in-time delivery to manufacturing clusters. Inventory carrying costs concentrate in eastern China's pharmaceutical corridor.
- Direct Sales:Multinational formulators in Japan and South Korea negotiate quality agreements directly with BASF's Ludwigshafen-to-Shanghai supply chain coordination. Technical service depth anchors these relationships.
- Specialty Stores:Laboratory supply outlets serve research institutions and pilot-scale formulation facilities. Limited volume but high margin through certification documentation bundling.
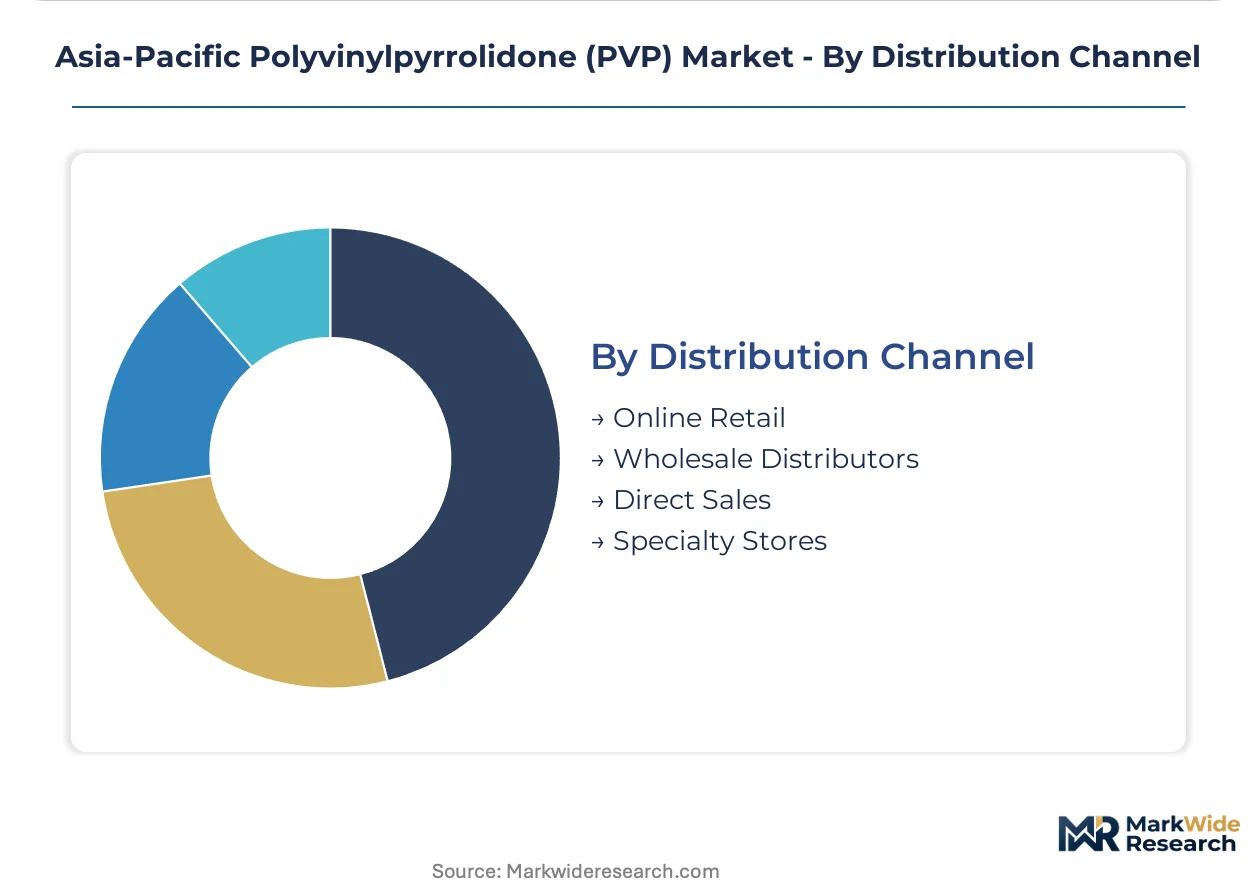
Wholesale Distributors capture the largest flow; Direct Sales gains share fastest among quality-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors regional PVP demand through its concentration of pharmaceutical API manufacturing and formulation facilities clustered around Shanghai.
China
Pharmaceutical-grade PVP procurement concentrates in Zhejiang province and Shanghai's eastern manufacturing corridor where active ingredient producers cluster. NMPA's 关联审评审批 rules tie excipient batch documentation to drug product licensure cycles, compressing qualification timelines for cross-border shipments. Domestic producers like Boai NKY Pharmaceuticals leverage captive acetylene-to-vinylpyrrolidone capacity to insulate margins from petrochemical feedstock swings.
Japan
Osaka and Tokyo formulation clusters drive demand for high-K-value PVP in controlled-release cardiovascular tablets. PMDA maintains ICH Q3D elemental impurity alignment for excipients used in export-oriented formulations, requiring rigorous catalyst residue documentation. Japanese formulators are consolidating supplier panels under ICH Q7 guidelines, disqualifying single-grade commodity sources in favor of dual pharmaceutical-cosmetic grade producers.
India
CDSCO-regulated generic tablet facilities in Maharashtra and Gujarat are expanding binder specifications to accommodate high-shear granulation demands. BIS import testing protocols govern PVP destined for domestic production, with mid-tier facilities facing X-ray fluorescence capability gaps that delay ICH Q3D audit readiness. Cost-performance trade-offs with hydroxypropyl methylcellulose intensify in price-sensitive generic segments.
South Korea
Seoul's cosmetic formulation clusters propel PVP-hair fixative complex demand through K-beauty brand expansion. MFDS cosmetic notification pathways enable faster ingredient approval for film-forming polymers than pharmaceutical excipient registration. Korean drug manufacturers mirror Japanese procurement patterns by rationalizing vendor bases under quality agreement standardization.
Vietnam
Greenfield API facilities in Binh Duong province lack established excipient supplier networks, creating qualification opportunities for distributors ahead of formulation scale-up. The country's national pharmaceutical regulator is building testing infrastructure for endotoxin and peroxide specifications that currently exclude regional commodity manufacturers. Pharmaceutical manufacturing investment flows from neighboring markets are accelerating local supply chain development needs.
Asia-Pacific Polyvinylpyrrolidone (PVP) Market Competitive Environment
Global majors compete with regional champions across technical service depth and integrated supply chain coordination. BASF anchors its position through Ludwigshafen-to-Shanghai logistics synchronization, while Chinese producers exploit captive raw material positions. Three archetypes dominate: integrated petrochemical players with backward acetylene control, technical service specialists in complex drug delivery applications, and commodity-scale regional suppliers. Competitive moves center on supplier panel consolidation by multinational formulators and capital outlays for sterile filtration infrastructure.
Among Asia-Pacific-based producers, Boai NKY Pharmaceuticals Ltd. exemplifies the integrated archetype with captive monomer capacity. Ashland Global Holdings Inc. represents technical service differentiation in Japan and South Korean markets. BASF SE occupies the multinational coordination position linking European production bases to regional distribution hubs.
| Leading Market Players |
|---|
| Boai NKY Pharmaceuticals Ltd. |
| Anhui Wanwei Group Co., Ltd. |
| BASF SE |
| Lotte Fine Chemical |
| Zhejiang Tianyi Chemical Co., Ltd. |
| Ashland Global Holdings Inc. |
| Merck KGaA |
| SNF Floerger |
| Nippon Shokubai Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Acetylene feedstock costs cascade through pharmaceutical-grade PVP pricing tiers, with integrated Chinese producers capturing margin insulation unavailable to import-reliant competitors serving Japan's PMDA-inspected formulation clusters.
Pricing Analysis
Input-cost pass-through from N-vinylpyrrolidone monomer volatility dominates margin structures across the Asia-Pacific PVP landscape. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates qualified excipient suppliers from commodity producers. Cost compression in industrial-grade segments intensifies because cellulose ether substitutes erode pricing power. Generic tablet manufacturers in India's BIS-regulated sector exhibit highest price sensitivity, while Japanese cardiovascular formulators accept premium positioning for controlled-release matrix systems.
Supply Chain Analysis
Single-source vulnerability sits with acetylene-based monomer production concentrated among integrated Chinese facilities in Zhejiang and Shandong provinces. Raw material dependencies span petrochemical feedstocks, catalyst systems for polymerization, and sterile filtration membranes. Supply chain risk centers on regulatory restriction as China's NMPA关联审评审批 rules compress cross-border qualification timelines. Distribution runs through wholesale distributors anchored in Shanghai's eastern manufacturing corridor, with direct sales channels gaining share among quality-sensitive multinational formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's GB 1886.73 standard migration toward pharmaceutical-grade parity creating irreversible demand elevation for qualified suppliers.
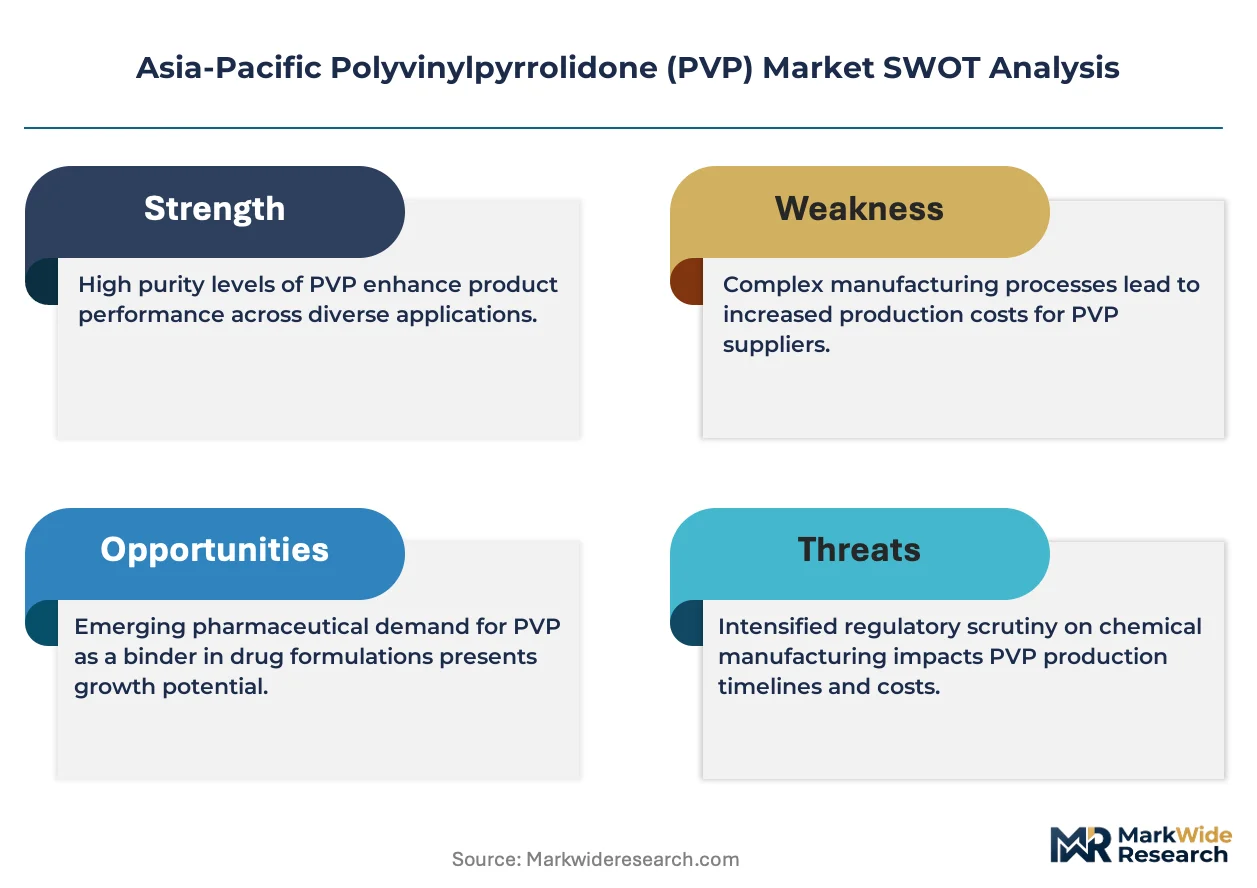
For Market Incumbents: Anticipate endotoxin specification barriers hardening as Vietnam's national pharmaceutical regulator builds testing infrastructure. Defensive consolidation moves should prioritize backward integration into captive acetylene capacity and sterile filtration infrastructure investments ahead of domestic certification completion. Hydroxypropyl methylcellulose substitution in India's generic tablet segment represents the most pressing substitute technology threat. For New Entrants and Emerging Players: NMPA's 关联审评审批 rules in China open a window for technical service specialists who can anchor batch documentation to drug product licensure cycles. The most penetrable white-space target sits with greenfield API facilities in Vietnam's Binh Duong province, where established excipient supplier networks remain absent. A qualification-first go-to-market angle, bundling endotoxin certification with rapid lot turnaround, outperforms price-led entry strategies. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier Chinese facilities face capital outlays for X-ray fluorescence capability gaps delaying ICH Q3D audit readiness. Long-term viability favors dual pharmaceutical-cosmetic grade producers with demonstrated polymer-drug compatibility study capabilities. The signal to watch as inflection indicator is Japanese formulator supplier panel rationalization velocity under ICH Q7 guidelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Capacity | Captive monomer supply insulates Boai NKY Pharmaceuticals from petrochemical feedstock volatility. |
| Sterile Filtration Infrastructure Investment | Domestic Chinese producers require capital outlays to meet GB 1886.73 pharmaceutical-grade parity thresholds. |
| Blockchain-Anchored Batch Release Platform | Shanghai customs pilots reduce port detention for EU-sourced PVP through documentation standardization. |
| Dual Pharmaceutical-Cosmetic Grade Certification | Japanese and South Korean formulators disqualify single-grade commodity sources under ICH Q7 vendor rationalization. |
| Amorphous Solid Dispersion Technical Service | Polymer-drug compatibility studies expand PVP's role beyond conventional binders in Japan's PMDA QbD-aligned facilities. |
Study Parameters
Direct dialogue with pharmaceutical procurement managers, excipient technical directors, regulatory affairs leads at CDSCO and NMPA, and cosmetic formulation chemists grounded qualitative insights in operational reality. Secondary validation drew from customs trade databases, SEC filings of listed chemical producers, pharmacopoeial reference updates, and associated review and approval rule publications. Bottom-up demand modeling across tablet formulation, hair fixative, and adhesive applications triangulated against top-down excipient market sizing.
Bottom-up volume builds aggregated consumption estimates across pharmaceutical, cosmetic, and industrial grade tiers, while top-down analysis calibrated against regional chemical production indices. Segmentation dimensions spanned purity grade, K-value specification, end-use industry, and regulatory compliance cluster. CAGRs derived from elasticity-adjusted demand projections incorporating substitution dynamics with hydroxypropyl methylcellulose and high-shear granulation adoption rates.
Revisions become necessary when regulatory enforcement intensity shifts, monomer supply disruptions materialize, or cellulose ether substitution accelerates in price-sensitive generic segments. Forecasts reflect documented assumptions about certification timeline compression and infrastructure buildout trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Plastisols Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Modified Alkyd Resin Market