
 Ocular Adhesives and Sealants Market | 2026-2036
Ocular Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Adhesives and Sealants Market Intelligence
Cyanoacrylate formulations is decoupling from older fibrin-based systems in corneal applications, reducing per-procedure material costs while improving wound-closure speed. Baxter International leverages its plasma-derived protein expertise to sustain a specialized position in tissue sealant supply chains. Johnson & Johnson competes through its broad surgical portfolio, while Ocular Therapeutix, Inc. differentiates via hydrogel-based drug-delivery platforms that integrate sealant functionality.
Ocular adhesives and sealants comprise biocompatible polymer systems—typically cyanoacrylates, polyethylene glycol hydrogels, or fibrinogen-thrombin composites—engineered for intraocular and periocular tissue approximation with tensile strengths between 0.5 and 4.0 N and degradation profiles tunable from days to months. These materials serve primarily to replace or augment mechanical suturing in delicate ophthalmic tissues where needle penetration risks further structural damage. Surgical adhesives currently anchor the highest margin pools due to premium pricing on synthetic formulations with controlled polymerization rates. Retinal repair applications are expanding fastest as vitreoretinal surgeons adopt injectable sealants for macular hole and retinal detachment procedures, while corneal surgery remains the most mature segment with established reimbursement pathways.
FDA 510(k) clearances and CE marking under the EU Medical Device Regulation shape product-entry timelines and clinical-evidence requirements for manufacturers targeting the United States and European markets. ISO 10993 biocompatibility testing standards govern cytotoxicity and sensitization thresholds that all commercial formulations must satisfy before clinical deployment. The report identifies material-innovation cycles and regulator-industry dialogue on biodegradable synthetic platforms as the critical dynamics stakeholders must track to anticipate shifts in competitive advantage.
Market Dynamics
Cyanoacrylate polymerization kinetics are displacing fibrin-based closure systems in corneal surgery, compressing procedure times while FDA 510(k) pathways tighten biocompatibility documentation requirements for synthetic formulations.
Growth Catalysts
- EU MDR compliance deadlines:CE marking renewals under the Medical Device Regulation are forcing manufacturers to upgrade clinical evidence packages, accelerating consolidation toward firms with robust quality-management systems.
- Retinal detachment volumes:Vitreoretinal surgical centers in Germany and Japan are expanding macular hole repair programs, creating pull-through demand for injectable hydrogel sealants with tunable degradation profiles.
- Cataract center expansion:Ambulatory surgical facilities in the United States are replacing mechanical suturing with biocompatible adhesives to reduce operative time and needle-related tissue trauma.
Market Restraints
- Plasma-derived fibrinogen supply:Baxter International's concentrated position in human protein sourcing creates vulnerability to blood-collection center capacity constraints and viral screening cost inflation.
- ISO 10993 testing burdens:Cytotoxicity and sensitization protocols for novel synthetic polymers extend development timelines by 18-24 months before clinical deployment.
- Suture substitution ceiling:Deep stromal lacerations and high-tension wound closures in corneal transplantation still require 10-0 nylon, limiting addressable procedure volume for adhesive-only approaches.
Strategic Opportunities
- Drug-device convergence:Hydrogel platforms integrating dexamethasone or anti-VEGF agents are opening post-surgical inflammation management protocols previously served by separate pharmaceutical drops.
- Japanese specialized eye hospitals:PMDA's streamlined review track for breakthrough devices is attracting foreign manufacturers to partner with Tokyo and Osaka academic medical centers for first-in-human trials.
- Outpatient procedure migration:Cataract surgery's shift from hospital-based to ambulatory settings in the United States favors single-use, pre-mixed adhesive delivery systems over multi-component fibrin kits.
Industry Challenges
- Polymerization control precision:Balancing rapid wound closure with avoidance of toxic exotherm or inflammatory foreign-body response demands formulation chemists with rare ophthalmic biomaterials expertise.
- FDA 510(k) predicate strategy:Establishing substantial equivalence for novel synthetic sealants against decades-old fibrin benchmarks requires extensive mechanical testing and clinical bridging studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Adhesives and Sealants Market |
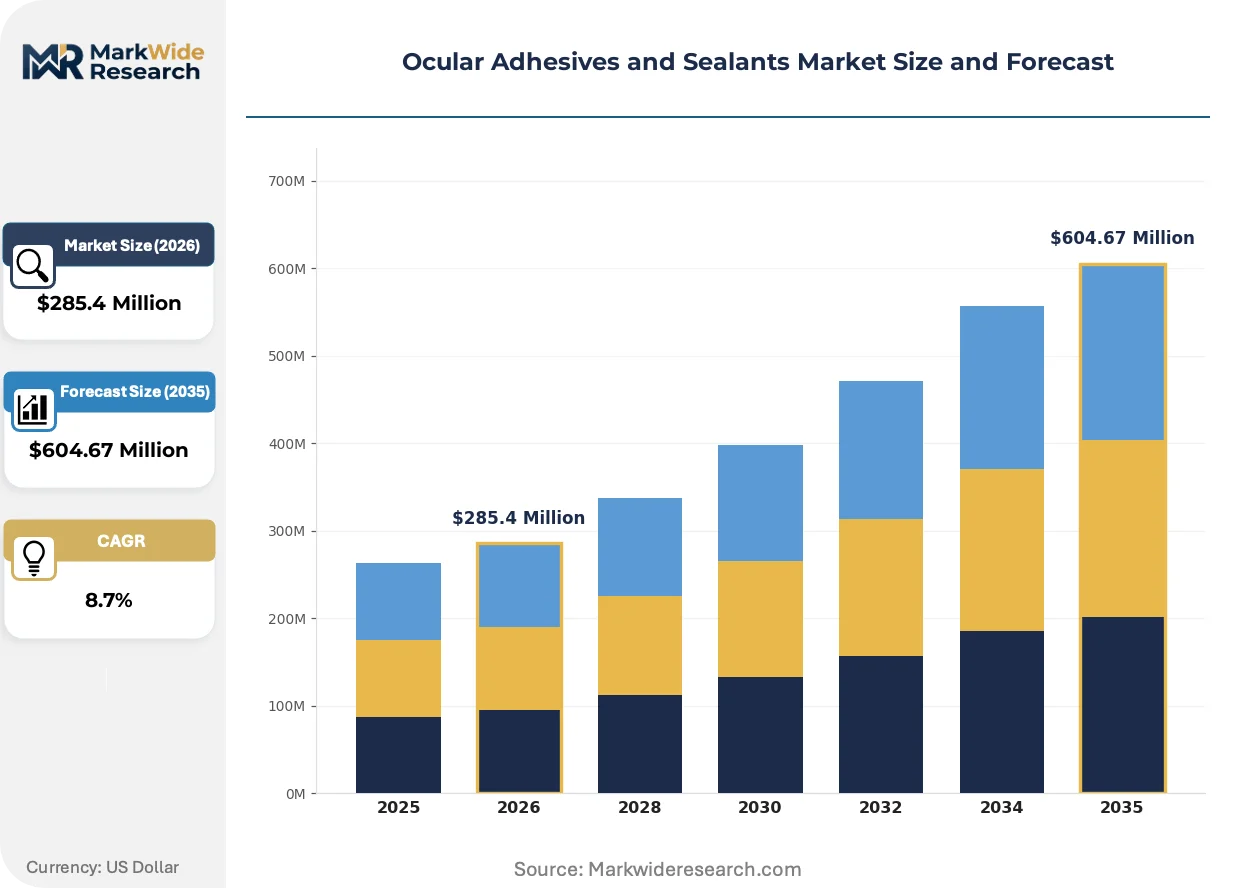
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Adhesives, Tissue Sealants, Medical Glues, Biocompatible Adhesives Application: Corneal Surgery, Cataract Surgery, Retinal Repair, Oculoplastic Procedures End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories Delivery Mode: Topical Application, Injectable Formulation, Spray Application, Patch Application |
| Companies Covered | Ocular Therapeutix, Inc., Reliance Life-Sciences, Baxter International, Medtronic PLC, B. Braun Melsungen AG, Johnson & Johnson, 3M Company, Henkel AG & Co. KGaA, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Adhesives and Sealants Market Strategic Shifts & Innovations
Material innovation cycles in ophthalmic sealants are compressing as synthetic polymer chemistry converges with controlled-release drug delivery, while regulatory frameworks on both sides of the Atlantic recalibrate safety thresholds.
Photocurable polyethylene glycol hydrogels are automating wound closure in corneal lamellar surgery by enabling on-demand gelation through brief UV-A exposure. Cataract centers in Germany and the United States are adopting these systems for Descemet membrane endothelial keratoplasty procedures. This automation is eliminating the manual mixing steps and variable setting times that plague fibrin-based alternatives.
FDA's tightened scrutiny of degradable synthetic polymers under updated biocompatibility guidance is extending premarket notification review timelines for cyanoacrylate formulations. Manufacturers must now submit comprehensive degradation product toxicology data previously accepted through literature review. Retinal applications face the steepest compliance burden due to intraocular placement and limited clearance pathways.
Hospital purchasing consortia in the United States are consolidating ophthalmic supply contracts around dual-source adhesive arrangements that guarantee volume commitments in exchange for price protection. Independent cataract surgery centers are responding by joining regional group purchasing organizations to match hospital bargaining leverage. This concentration is most pronounced in the Southeast and Midwest, where ASC networks have achieved 15-20% material cost reductions through collective tendering.
Ocular Adhesives and Sealants Market Segmentation
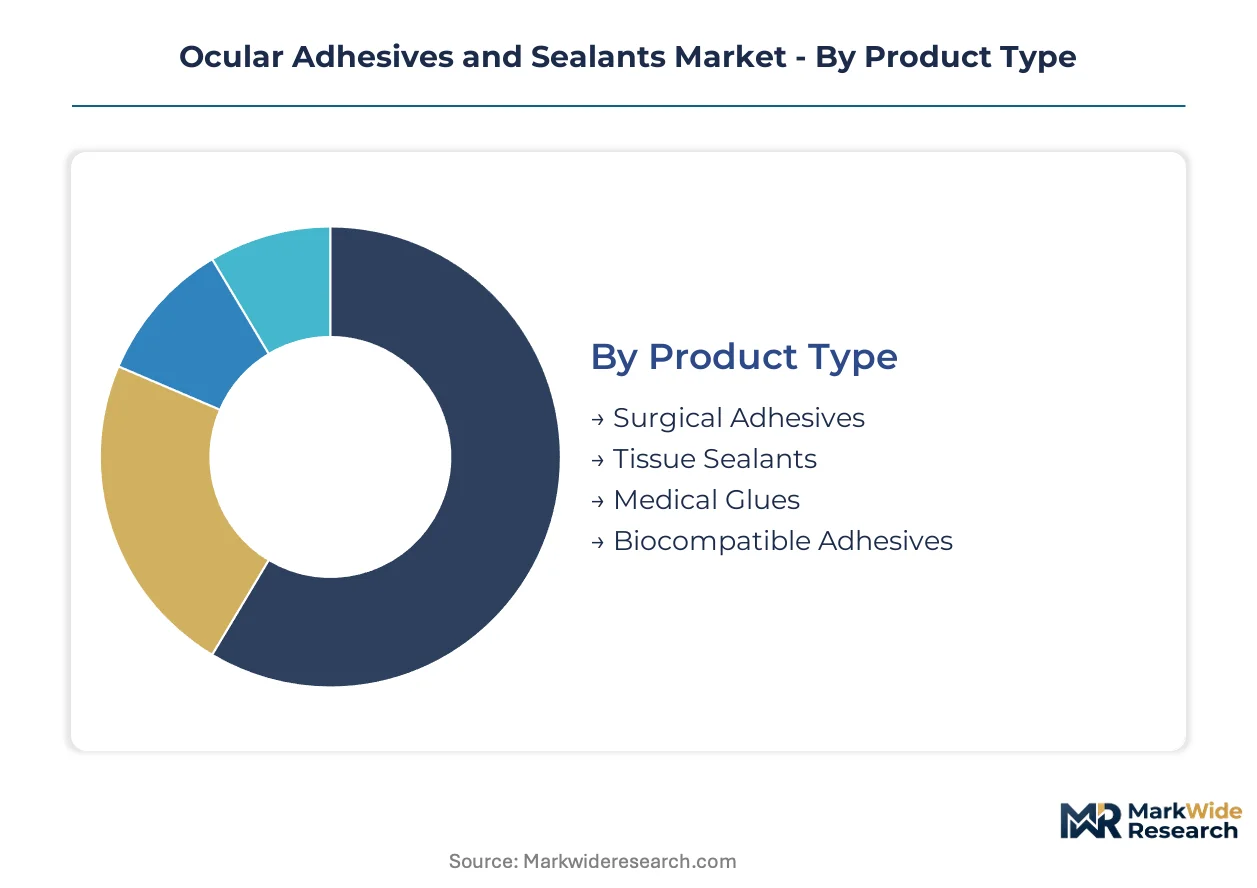
Ocular adhesives and sealants segment along four functional axes that determine procurement patterns and margin structures. Product chemistry defines reimbursement tiers, while application site dictates regulatory pathway complexity. End-user setting shapes packaging and delivery format preferences, with delivery mode increasingly influencing surgeon workflow efficiency.
Product Type:
Synthetic polymer chemistry and biological derivation separate these categories across price-performance tradeoffs.
- Surgical Adhesives:Cyanoacrylate and polyethylene glycol formulations dominate corneal lamellar procedures in Germany and the United States. Premium pricing reflects controlled polymerization kinetics and ISO 10993 biocompatibility certification. Demand concentrates in ambulatory surgical centers replacing mechanical suturing for Descemet membrane endothelial keratoplasty.
- Tissue Sealants:Fibrinogen-thrombin composites derived from human plasma anchor retinal detachment repair in specialized eye hospitals across Japan. Baxter International's concentrated supply position creates procurement vulnerability to blood-collection center capacity constraints. Surgeons value these for hemostatic control in vitreoretinal surgery.
- Medical Glues:Modified cyanoacrylates with reduced exotherm profiles serve superficial corneal lacerations in emergency departments.
- Biocompatible Adhesives:Hydrogel platforms with tunable degradation profiles integrate drug-delivery functionality for post-operative inflammation management.
Surgical adhesives lead on scale; biocompatible adhesives lead on momentum.
Application:
Anatomical site determines tensile strength requirements and degradation timeline specifications.
- Corneal Surgery:Established reimbursement pathways and mature clinical evidence support adhesive substitution for 10-0 nylon in penetrating keratoplasty. Photocurable polyethylene glycol systems are automating wound closure through brief UV-A exposure in German and US cataract centers.
- Retinal Repair:Injectable hydrogel sealants with tunable degradation profiles are expanding fastest as vitreoretinal surgeons adopt them for macular hole procedures. PMDA's streamlined breakthrough device track in Japan accelerates first-in-human trials for novel formulations.
- Cataract Surgery:Biocompatible sealants reduce operative time and needle-related tissue trauma in phacoemulsification wound closure.
- Oculoplastic Procedures:Lower tensile strength requirements permit broader adhesive adoption in periocular skin approximation.
Corneal surgery leads on scale; retinal repair leads on momentum.
End User:
Facility type determines volume scale, sterility requirements, and supply chain access.
- Hospitals:Academic medical centers in Tokyo and Osaka drive procurement of investigational sealants through PMDA breakthrough pathways. Consolidated purchasing consortia in the US Southeast and Midwest achieve 15-20% material cost reductions through collective tendering.
- Ambulatory Surgical Centers:Single-use, pre-mixed adhesive delivery systems displace multi-component fibrin kits as cataract surgery migrates from hospital-based to outpatient settings across the United States.
- Clinics:Lower procedural volumes favor economical topical application formats over sophisticated injectable systems.
- Research Laboratories:Preclinical testing demand supports specialized formulations for mechanical validation studies.
Hospitals lead on scale; ambulatory surgical centers lead on momentum.
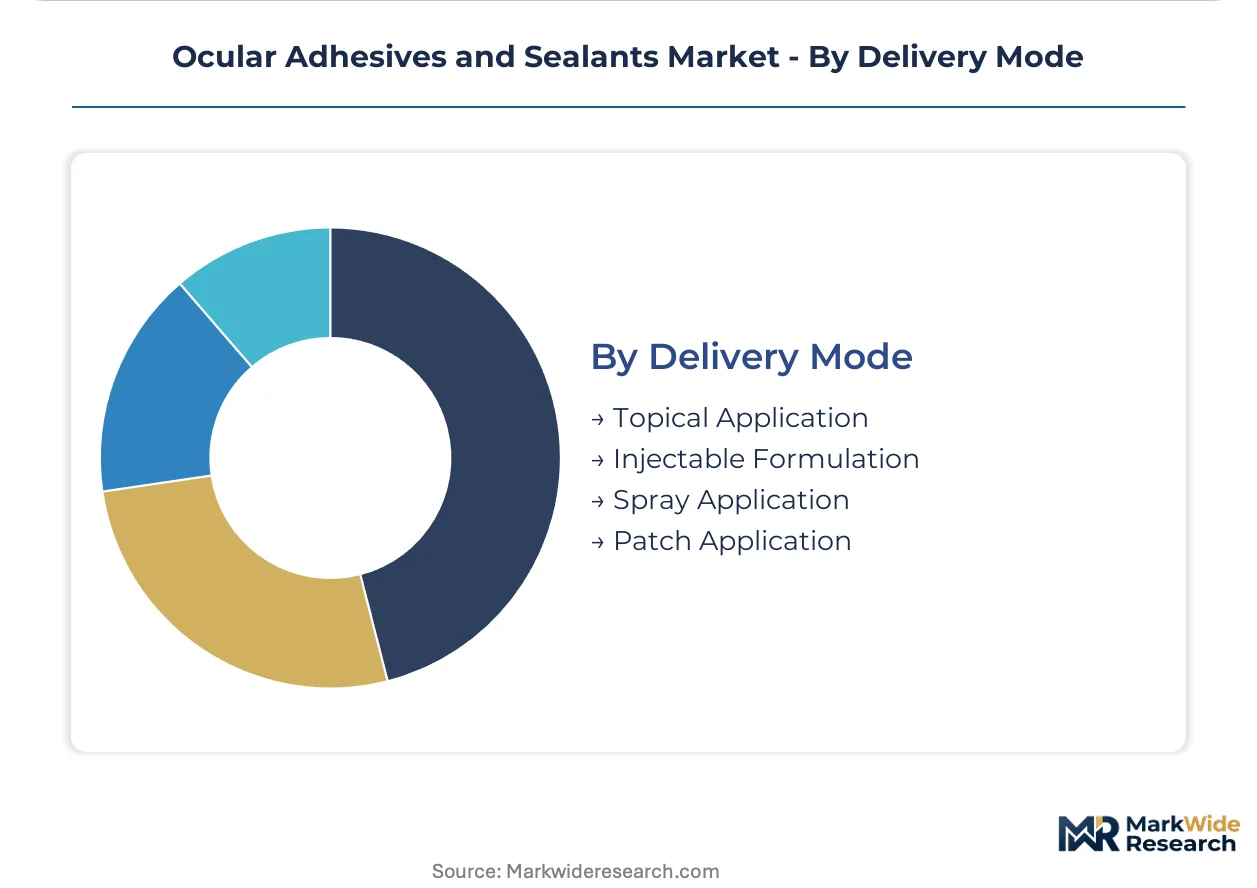
Delivery Mode:
Application method shapes surgeon training requirements and sterile field management.
- Injectable Formulation:Precision placement in intraocular spaces demands formulation chemists with rare ophthalmic biomaterials expertise. FDA 510(k) predicate strategies for novel synthetics require extensive mechanical testing against fibrin benchmarks.
- Topical Application:Surface-level corneal and conjunctival procedures favor simplicity and reduced regulatory burden in US and European markets.
- Spray Application:Uniform coating of large surface areas suits oculoplastic and periocular applications.
- Patch Application:Pre-formed adhesive matrices enable controlled drug release in post-surgical protocols.
Injectable formulation leads on scale; topical application leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cataract centers drive procurement volume for photocurable sealants, while specialized eye hospitals in Japan and the United States concentrate demand for advanced formulations. Regulatory pathways in each geography shape product-entry timelines and clinical-evidence requirements.
United States
Ambulatory surgical centers in the Southeast and Midwest are replacing mechanical suturing with biocompatible adhesives for phacoemulsification wound closure. FDA 510(k) clearances for synthetic formulations now require comprehensive degradation product toxicology data. Hospital purchasing consortia in these regions achieve material cost reductions through collective tendering arrangements.
Germany
Academic medical centers in Berlin and Munich are adopting photocurable polyethylene glycol hydrogels for Descemet membrane endothelial keratoplasty procedures. EU MDR compliance deadlines for CE marking renewals are forcing manufacturers to upgrade clinical evidence packages. The country's specialized eye hospitals anchor European demand for premium synthetic sealants with controlled polymerization kinetics.
Japan
Vitreoretinal surgical centers in Tokyo and Osaka are expanding macular hole repair programs using injectable hydrogel sealants. PMDA's streamlined breakthrough device review track accelerates first-in-human trials for novel formulations. These academic clusters attract foreign manufacturers seeking early clinical validation for retinal applications.
India
Specialized eye hospitals in Maharashtra and Karnataka are building vitreoretinal surgery capacity to address rising retinal detachment volumes. CDSCO regulatory pathways for ophthalmic devices are tightening material-safety documentation requirements. Mumbai and Bangalore clusters concentrate procurement for cost-effective tissue sealants in high-volume cataract programs.
United Kingdom
London and Manchester academic centers are evaluating drug-device convergence platforms integrating anti-inflammatory agents with sealant functionality. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR biocompatibility standards while streamlining UK-specific approval timelines. These institutions pilot post-surgical inflammation management protocols previously served by separate pharmaceutical drops.
Ocular Adhesives and Sealants Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers extend synthetic polymer expertise into drug-delivery integration. The market structure concentrates around three strategic archetypes: diversified healthcare conglomerates with broad surgical portfolios, specialized ophthalmic biomaterials firms with hydrogel platforms, and plasma-derived protein suppliers with concentrated tissue sealant positions. M&A activity and technology licensing arrangements represent the dominant competitive moves as firms seek rare formulation chemistry capabilities.
Within the diversified healthcare tier, Johnson & Johnson and Medtronic PLC occupy positions spanning multiple surgical specialties, while Baxter International exemplifies the plasma-derived protein archetype with concentrated supply chain control. Ocular Therapeutix, Inc. represents the specialized ophthalmic biomaterials segment, anchoring innovation in hydrogel-based platforms. These three entities collectively illustrate the competitive vectors shaping procurement relationships with cataract centers and specialized eye hospitals across Germany, the United States, and Japan.
| Leading Market Players |
|---|
| Ocular Therapeutix, Inc. |
| Reliance Life-Sciences |
| Baxter International |
| Medtronic PLC |
| B. Braun Melsungen AG |
| Johnson & Johnson |
| 3M Company |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Others |
Cost & Logistics Intelligence
Human plasma-derived fibrinogen feedstock costs cascade through three-tier pricing structures across premium, standard, and economy levels as Baxter International's concentrated sourcing position in United States blood-collection centers shapes procurement negotiations downstream with German and Japanese specialized eye hospitals.
Pricing Analysis
Input-cost pass-through from plasma protein purification to finished sealant formulations varies by ISO 10993 certification tier and controlled polymerization kinetics specifications. Premium cyanoacrylate and polyethylene glycol hydrogels command price separation from economy fibrin-based alternatives based on degradation profile tunability and drug-delivery integration. Pricing pressure stems from hospital purchasing consortia in the United States Southeast and Midwest achieving material cost compression through collective tendering arrangements. Ambulatory surgical centers exhibit highest price sensitivity due to volume scale constraints, while academic medical centers in Tokyo and Osaka prioritize performance specifications over unit economics.
Supply Chain Analysis
Photocurable polyethylene glycol precursor supply rests on German and United States specialty chemical producers with concentrated capacity in industrial polymer corridors near Berlin and Chicago. Raw material dependencies span medical-grade cyanoacrylate monomers, recombinant thrombin preparations, and UV-A photoinitiator compounds. Single-source vulnerability concentrates in Baxter International's plasma-derived protein sourcing from United States blood-collection centers. Distribution runs through hospital purchasing consortia and regional group purchasing organizations serving ambulatory surgical centers, with direct manufacturer relationships dominating specialized eye hospital procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as vitreoretinal surgical centers in Germany and Japan shift procurement specifications toward tunable degradation profiles and drug-device convergence platforms.
For Market Incumbents: Anticipate margin compression from synthetic polymer entrants by deepening captive supply of plasma-derived fibrinogen and accelerating CE marking renewals under EU MDR compliance deadlines. Secure predicate device strategies for FDA 510(k) submissions against tightening biocompatibility documentation requirements. Prioritize hydrogel platform R&D integration with dexamethasone or anti-VEGF agents to defend positioning in post-surgical inflammation management protocols. For New Entrants and Emerging Players: PMDA's streamlined breakthrough device review track in Japan opens a window for first-in-human trial partnerships with Tokyo and Osaka academic medical centers seeking novel retinal sealant formulations. Target ambulatory surgical centers in the United States Midwest with single-use, pre-mixed adhesive delivery systems displacing multi-component fibrin kits. Pursue white-space penetration in cost-effective tissue sealants for high-volume cataract programs in Maharashtra and Karnataka, India. For Investors and Strategic Acquirers: Consolidation pressure builds where rare ophthalmic biomaterials formulation expertise concentrates among specialized hydrogel platform developers. Long-term viability over the next decade hinges on backward integration into medical-grade polymer precursor supply and regulatory approval pathway acceleration. Acquisition target archetypes include mid-cap firms with ISO 10993 certification infrastructure and established surgeon training programs. Watch PMDA breakthrough device designations and FDA 510(k) clearance timelines for novel synthetic formulations as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance deadlines force clinical evidence package upgrades among manufacturers targeting German cataract centers. |
| Hospital System Partnership | Academic medical centers in Tokyo and Osaka attract foreign manufacturers through PMDA's streamlined breakthrough device review track. |
| Backward Integration | Captive supply of medical-grade cyanoacrylate monomers reduces exposure to German and United States specialty chemical producer pricing. |
| Reimbursement Strategy | Established pathways for corneal surgery adhesives contrast with emerging coverage negotiations for retinal hydrogel sealants. |
| Software Companion Development | Photocurable system integration with UV-A dosing automation supports workflow efficiency in Descemet membrane endothelial keratoplasty procedures. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vitreoretinal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CE marking databases under EU MDR, PMDA approval records, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across synthetic polymer and biological derivation categories.
Segment-weighting approaches distributed value and volume across product chemistry tiers, anatomical application sites, end-user facility types, and delivery mode configurations throughout the forecast period. CAGRs derived from elasticity-adjusted procedure growth projections and pricing trajectory assumptions indexed to ISO 10993 certification tier and controlled polymerization specification premiums. Industry-specific inputs incorporated vitreoretinal surgical center expansion rates in Germany and Japan, cataract surgery migration patterns to ambulatory settings in the United States, and plasma-collection center capacity constraints affecting fibrinogen supply economics.
Revisions become necessary when regulatory pathway timelines shift materially, plasma-derived protein supply disruptions emerge, or synthetic polymer degradation product toxicology guidance tightens unexpectedly. Forecasts reflect documented assumptions about procedure substitution ceilings for adhesive-only approaches and reimbursement pathway maturation for retinal applications. A small set of named triggers warrants ongoing watch: PMDA breakthrough device designation velocity, FDA 510(k) review timeline extensions for novel synthetics, and EU MDR notified body capacity constraints affecting CE marking renewal schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
Global Dental Adhesives and Sealants Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market