
 Global Molecular Weight Marker Market | 2026-2036
Global Molecular Weight Marker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molecular Weight Marker Market Intelligence
The direct-to-lab sales channel is fragmenting the traditional distributor-led supply model for life science consumables. This shift creates new access points for specialized suppliers while challenging established incumbents. Thermo Fisher Scientific Inc. leverages its extensive e-commerce platform to maintain market reach. New England Biolabs differentiates through its focus on high-purity reagents for genomics research, while QIAGEN sustains its position with integrated workflow solutions.
A molecular weight marker is a mixture of proteins or nucleic acids with known, predefined sizes. These markers function as a standard scale to estimate the size of unknown molecules during gel electrophoresis procedures. In terms of product type, pre-stained markers offer convenience for visualizing protein migration in real-time and dominate routine laboratory use. The proteomics analysis application represents the fastest-growing segment, driven by biomarker discovery and personalized medicine initiatives.
Product quality and consistency are governed by standards from regulatory bodies like the US FDA and the European Medicines Agency (EMA), especially for markers used in diagnostic assay development and biopharmaceutical quality control. ISO 9001 certification is also a critical differentiator for suppliers selling into regulated environments. Vendor selection will increasingly depend on the ability to provide extensive batch-to-batch consistency documentation and validation support for GMP-compliant workflows.
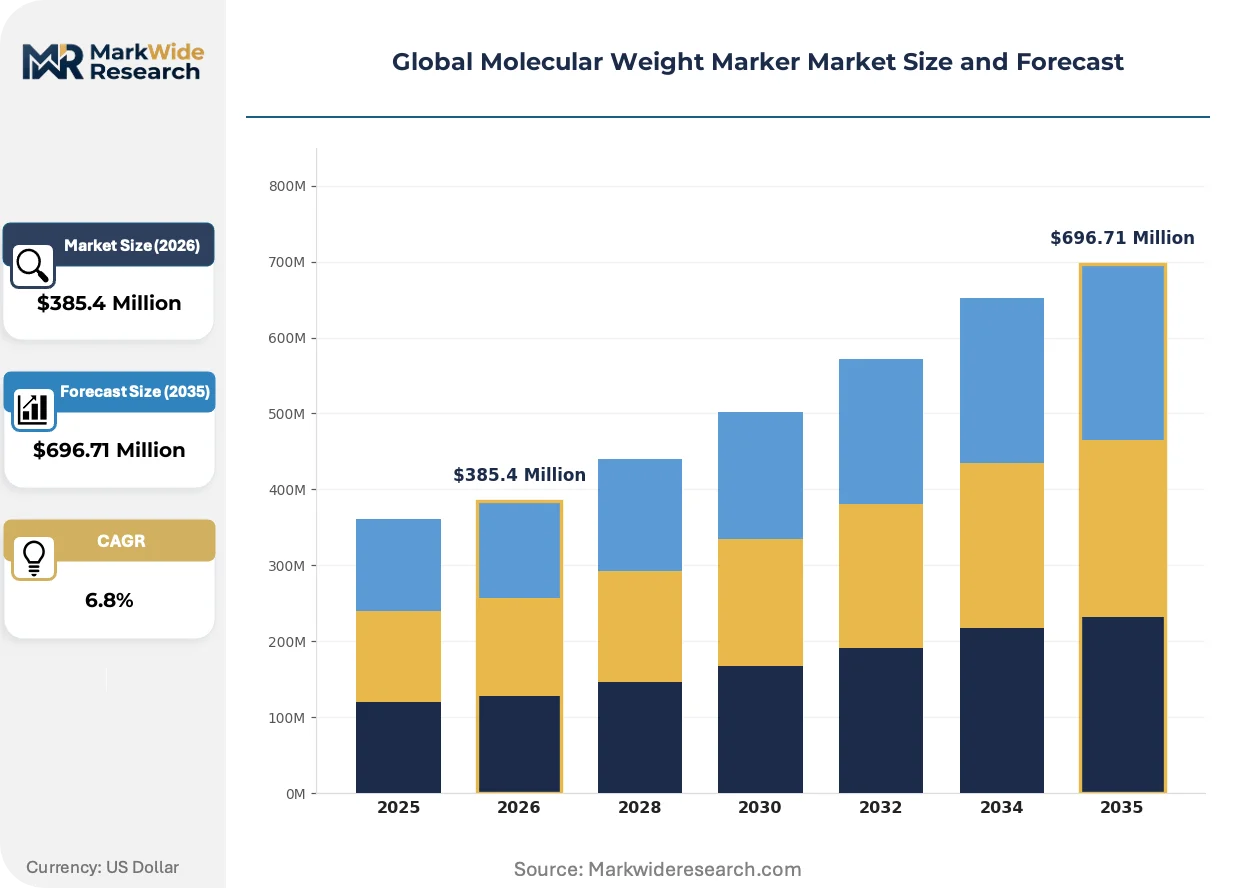
Market Dynamics
The central force shaping the market is the convergence of advanced therapeutic development and stringent regulatory oversight. As gene therapies and personalized medicines move from research to clinical production, molecular weight markers are evolving from simple laboratory consumables into critical, documented components within GMP-compliant manufacturing and quality control workflows.
Growth Catalysts
- CRISPR Gene-Editing Technologies:The expanding application of CRISPR systems for therapeutic development requires exceptionally pure nucleic acid markers to validate guide RNA integrity and confirm successful gene edits, driving demand for specialized, high-resolution products.
- Biopharmaceutical Quality Control:Growth in biologics and biosimilars manufacturing necessitates consistent protein markers to satisfy batch-to-batch consistency requirements from regulatory bodies like the FDA and EMA for product release testing.
- National Biotechnology Investments:Government-led initiatives, particularly in China and South Korea, are injecting substantial capital into life sciences research and development infrastructure, directly boosting consumption of essential reagents in academic and industrial labs.
Market Restraints
- High Production Costs:The manufacturing of high-purity recombinant protein and synthetic nucleic acid markers involves complex processes and expensive raw materials, which translates to premium pricing that can be prohibitive for budget-constrained academic laboratories.
- Threat of Technological Substitution:Automated capillary electrophoresis and microfluidics platforms, which often incorporate internal software-based sizing standards, reduce the reliance on traditional slab gel electrophoresis and physical markers in high-throughput screening environments.
- Inherent Product Variability:Markers derived from natural sources, such as cell lysates, can exhibit significant lot-to-lot variability, posing a challenge for sensitive assays and pushing users towards more expensive but consistent recombinant alternatives.
Strategic Opportunities
- Markers for Novel Modalities:There is a clear opportunity to develop and validate markers specifically designed for the quality control of emerging therapeutics like mRNA vaccines and CAR-T cell therapies, where QC standards are still being defined. li>Smart Packaging Integration: Incorporating technologies like RFID or QR codes on marker packaging can enable automated tracking of lot numbers, expiration dates, and storage conditions, supporting compliance with GMP inventory management systems.
- Expansion in Diagnostic Networks:Targeting clinical diagnostic laboratory networks in Brazil, India, and Southeast Asia represents a significant growth vector as these regions rapidly adopt molecular diagnostic techniques for infectious disease and genetic testing.
Industry Challenges
- Burdensome Compliance Requirements:Achieving and maintaining ISO 9001 certification and compiling the extensive validation data required for GMP-compliant customers creates a significant operational and financial barrier for new or smaller market entrants.
- Cold Chain Logistics Complexity:Ensuring the integrity of temperature-sensitive protein and pre-stained markers during global distribution requires a robust and expensive cold chain, posing risks of product degradation and logistical delays.
- Lack of Cross-Platform Standardization:The absence of a universal standard for marker performance across different gel chemistries and buffer systems compels end-users to conduct extensive internal validation, which can complicate and deter vendor switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molecular Weight Marker Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-stained Markers, Unstained Markers, Western Blot Markers, DNA Ladders, RNA Markers Technology: Gel Electrophoresis, Capillary Electrophoresis, Mass Spectrometry, Chromatography, Spectrophotometry Application: Proteomics Analysis, Genomics Research, Drug Discovery, Quality Control, Forensic Science End User: Biotechnology Firms, Research Institutions, Pharmaceutical Developers, Academic Laboratories, Diagnostic Centers |
| Companies Covered | QIAGEN, Promega Corporation, Thermo Fisher Scientific Inc., New England Biolabs, Agilent Technologies, Merck KGaA, F. Hoffmann-La Roche Ltd, Takara Bio Inc., Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molecular Weight Marker Market Strategic Shifts & Innovations
Marker utility is evolving from a basic sizing reference to an integrated component of validated analytical workflows. This shift is driven by the dual pressures of laboratory automation and the stringent quality demands inherent in regulated bioprocessing and diagnostics development.
Advanced fluorescently-labeled markers allow for the simultaneous visualization of a size ladder and specific proteins of interest within multiplex assays. These multi-color reagents are being adopted in proteomics research to streamline complex Western blotting experiments. This capability is hybridizing size standardization with internal quantitative controls, reducing the need for separate normalization steps and accelerating discovery workflows.
Stricter enforcement of Good Manufacturing Practice guidelines by regulators like the US FDA and the European Medicines Agency for ancillary materials is a significant market force. This pressure compels suppliers to provide markers with extensive documentation, including detailed Certificates of Analysis and raw material traceability. Consequently, the biopharmaceutical quality control segment now heavily favors vendors with auditable quality management systems and validated production processes.
Researchers increasingly prefer to purchase complete workflow kits that bundle markers with precast gels, buffers, and transfer membranes. This behavior displaces the traditional à la carte purchasing of individual consumables, benefiting suppliers that offer integrated and pre-validated systems. This shift is most pronounced in academic labs and biotechnology startups where experimental standardization and user convenience are prioritized to enhance reproducibility.
Global Molecular Weight Marker Market Segmentation
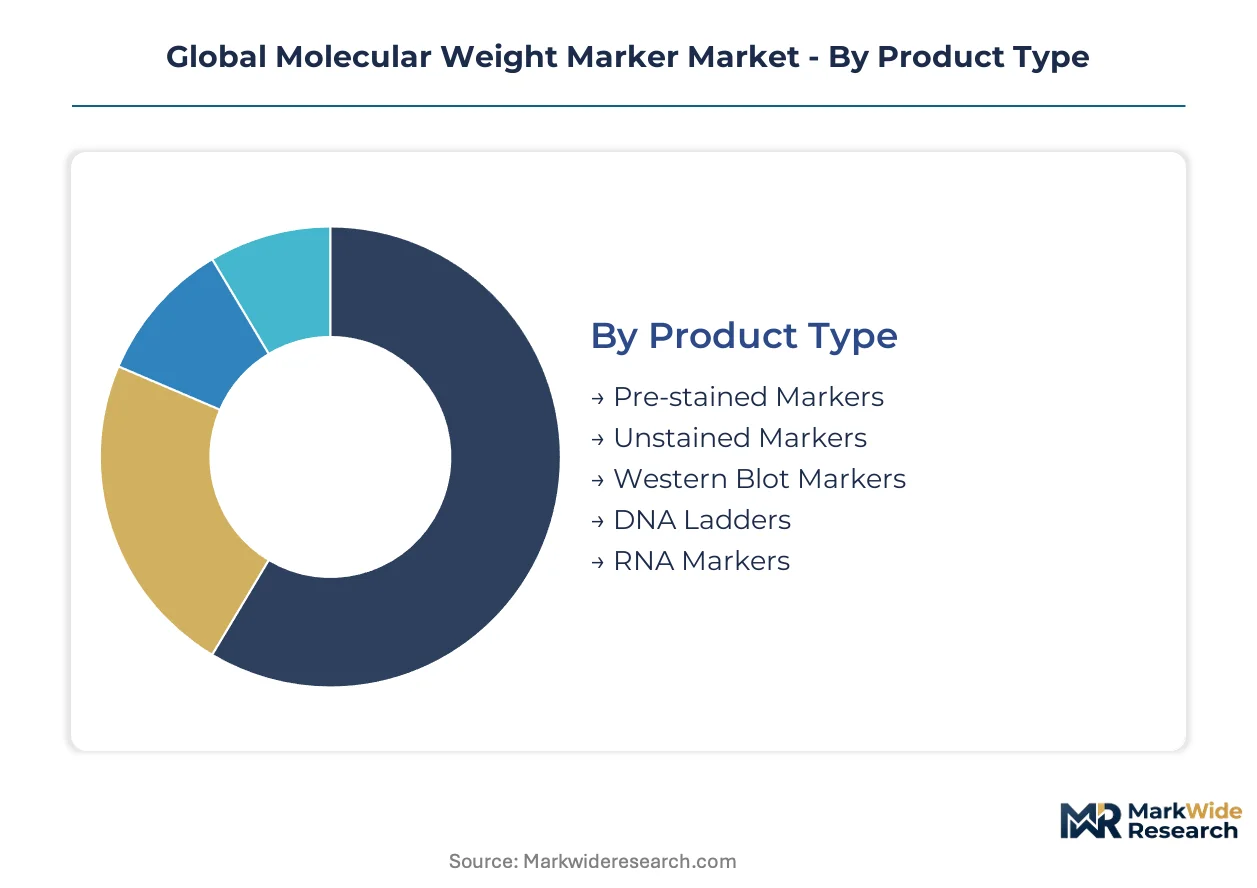
Market segmentation for molecular weight markers illuminates the specific product attributes, technological platforms, end-user requirements, and application areas driving demand across the life sciences sector. Understanding these distinctions is crucial for suppliers to tailor product development and market strategies effectively.
Product Type:
The product type segmentation highlights the diverse use-case spectrum for molecular weight markers across various laboratory techniques.
- Pre-stained Markers:These markers incorporate dyes that bind to proteins or nucleic acids, allowing real-time visualization of migration during gel electrophoresis without additional staining steps. Demand concentrates in academic laboratories and biotechnology firms prioritizing workflow efficiency and rapid experimental feedback.
- DNA Ladders:Comprising DNA fragments of known lengths, these markers are essential for estimating the size of unknown DNA molecules in agarose or polyacrylamide gels, critical for gene cloning, PCR product analysis, and sequencing validation. Genomics research initiatives in China and the US heavily rely on high-quality DNA ladders.
- Unstained Markers:These markers lack pre-bound dyes and require post-electrophoresis staining for visualization, offering higher sensitivity and accuracy for precise molecular weight determination. Research institutions utilize unstained markers for quantitative analysis in proteomics.
- Western Blot Markers:Specialized protein markers designed for Western blotting applications, often including biotinylated or fluorescently labeled components for detection with specific antibodies or probes.
- RNA Markers:Consisting of RNA molecules of defined sizes, these markers are employed to determine the size of RNA transcripts in northern blotting or RNA integrity assessment.
The dominant share belongs to Pre-stained Markers, while DNA Ladders are closing the gap fastest.
Technology:
Technology segmentation reflects the maturity and sophistication of analytical methods employing molecular weight markers.
- Gel Electrophoresis:This foundational technique separates molecules based on size and charge through a gel matrix, utilizing molecular weight markers as a standard reference for size estimation. Gel electrophoresis remains a ubiquitous method in research institutions and diagnostic centers globally.
- Capillary Electrophoresis:An automated, high-resolution separation technique that uses narrow capillaries to separate molecules, often incorporating internal or external sizing standards to determine molecular weights with high precision. This technology is gaining traction in pharmaceutical development for its speed and quantitative capabilities.
- Mass Spectrometry:While not directly using physical markers in the same way as gel-based methods, mass spectrometry platforms often employ calibrants or internal standards to accurately determine molecular masses.
- Chromatography:Size-exclusion chromatography (SEC) separates molecules by size, and molecular weight standards are crucial for calibrating columns and determining the molecular weight distribution of samples.
- Spectrophotometry:This technique measures the absorption or transmission of light, used indirectly for concentration determination of samples whose molecular weight is known.
Gel Electrophoresis maintains a substantial base, but Capillary Electrophoresis is expanding most quickly.
Application:
Application scope outlines how molecular weight markers support critical research and development activities.
- Proteomics Analysis:This application involves the large-scale study of proteins, where molecular weight markers are essential for separating, identifying, and quantifying proteins in complex biological samples. Proteomics analysis represents the fastest-growing segment, driven by biomarker discovery and personalized medicine initiatives in the US and Europe.
- Genomics Research:Molecular weight markers are fundamental for analyzing DNA and RNA fragments, validating gene edits, and assessing nucleic acid integrity in various genomic studies. The expanding application of CRISPR gene-editing technologies in biotechnology firms drives demand for specialized nucleic acid markers.
- Drug Discovery:Markers assist in the characterization of therapeutic proteins, antibodies, and nucleic acid-based drugs during the early stages of pharmaceutical development.
- Quality Control:In biopharmaceutical manufacturing, molecular weight markers are critical for ensuring batch-to-batch consistency and purity of biologics and biosimilars, adhering to regulatory standards from the FDA and EMA.
- Forensic Science:DNA ladders are used in forensic laboratories for DNA profiling and identification, comparing unknown samples to known standards.
Proteomics Analysis drives significant demand, with Genomics Research also gaining substantial traction.
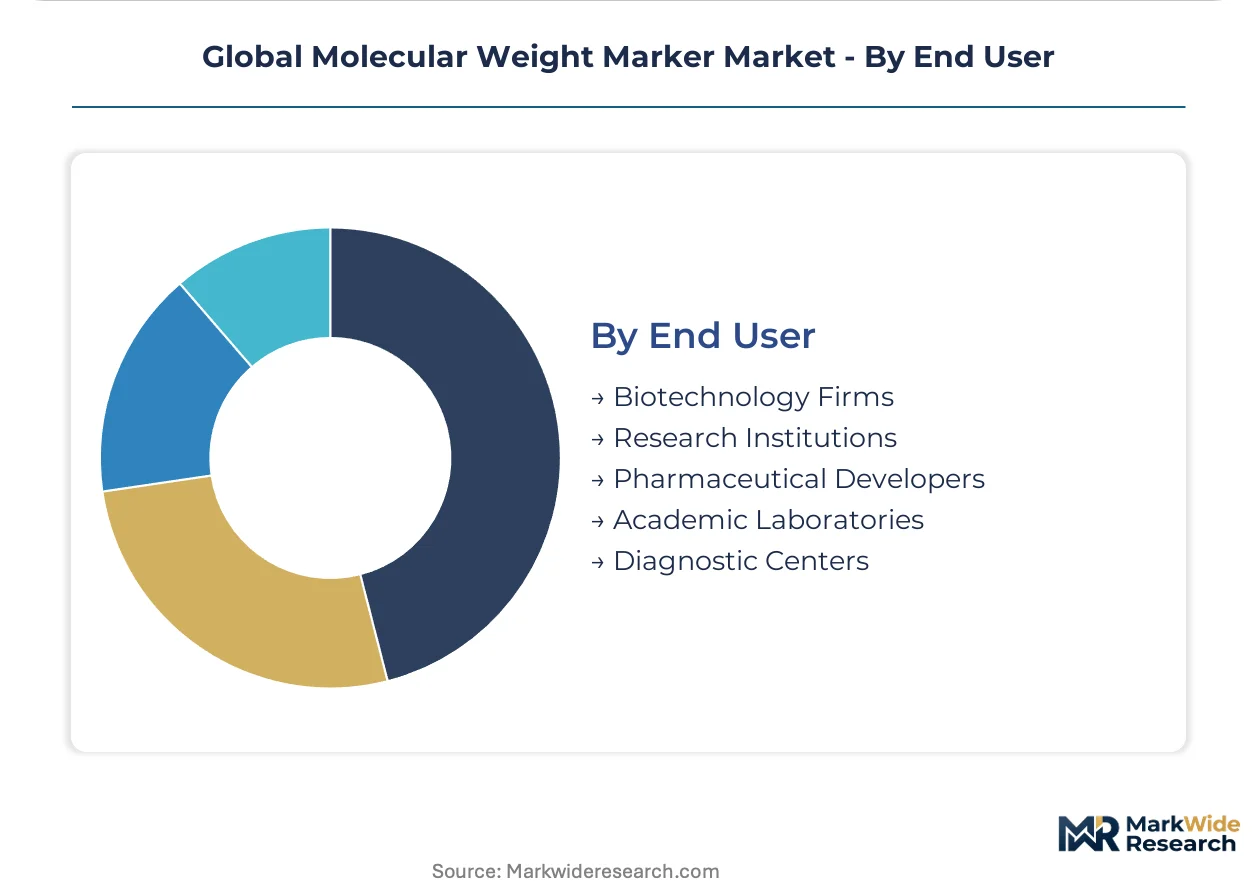
End User:
Customer type differentiation reveals the varied institutional needs for molecular weight marker products.
- Biotechnology Firms:These companies utilize molecular weight markers extensively in R&D for novel therapeutic development, gene editing, and protein characterization, often requiring high-purity and well-documented products. Expanding applications in proteomics analysis within these firms drive significant consumption.
- Pharmaceutical Developers:Engaged in the development and manufacturing of drugs, pharmaceutical companies require molecular weight markers for quality control, process monitoring, and regulatory compliance of biopharmaceutical products. Growth in biologics and biosimilars manufacturing necessitates consistent protein markers.
- Research Institutions:Academic and government-funded research laboratories represent a broad user base for molecular weight markers in fundamental biological studies, often balancing budget constraints with performance requirements. National biotechnology investments in China and South Korea boost consumption in these institutions.
- Academic Laboratories:University-based labs use markers for teaching purposes and basic research, often prioritizing cost-effectiveness and ease of use for routine experiments.
- Diagnostic Centers:Clinical diagnostic laboratories employ molecular weight markers for various molecular diagnostic tests, including infectious disease detection and genetic screening.
Biotechnology Firms represent a core consumption base, as Pharmaceutical Developers increase their market influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry defines regional market dynamics, with the United States often commanding premium pricing for advanced molecular markers. China's substantial government investments drive significant volume growth but also exert downward pressure on pricing in certain segments. This divergence shapes supplier strategies across major global markets.
United States
Proteomics analysis and personalized medicine initiatives drive strong demand for molecular weight markers in the United States. US FDA standards for diagnostic assay development necessitate high-purity and consistent products. The Boston-Cambridge biotech cluster remains a focal point for novel marker development and application in advanced research.
Germany
German biopharmaceutical quality control and advanced therapeutic development efforts require consistent molecular weight markers. European Medicines Agency (EMA) guidelines for biologics manufacturing emphasize batch-to-batch consistency for ancillary materials. Munich's vibrant life science sector actively integrates GMP-compliant workflows, boosting demand for validated markers.
China
China's national biotechnology investments and expanding CRISPR gene-editing applications fuel substantial marker consumption. NMPA standards for biopharmaceutical products influence supplier selection for quality control applications. Shanghai's biomedical parks are rapidly expanding, leading to increased demand for essential research reagents.
South Korea
South Korean genomics research and government-led life science initiatives create a strong market for molecular weight markers. MFDS oversight for diagnostic and research reagents promotes adherence to quality standards. Seoul's biotech cluster supports high-throughput screening and advanced molecular diagnostics.
India
Expanding diagnostic networks and pharmaceutical drug discovery activities drive marker demand in India. CDSCO guidelines for pharmaceutical quality control emphasize product consistency. Hyderabad's Genome Valley fosters significant growth in molecular diagnostics and R&D activities.
Global Molecular Weight Marker Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the molecular weight marker market. The direct-to-lab sales channel fragments the traditional distributor-led supply model, creating new access points. Archetypes include integrated workflow providers, high-purity reagent specialists, and e-commerce-driven suppliers. Competitive moves involve e-commerce expansion and specialized portfolio development.
Within the integrated workflow solutions tier, QIAGEN and Thermo Fisher Scientific Inc. anchor positions with broad product portfolios and extensive distribution networks. New England Biolabs exemplifies specialization in high-purity reagents, particularly for genomics research. These companies represent diverse strategic approaches to market penetration and customer engagement.
| Leading Market Players |
|---|
| QIAGEN |
| Promega Corporation |
| Thermo Fisher Scientific Inc. |
| New England Biolabs |
| Agilent Technologies |
| Merck KGaA |
| F. Hoffmann-La Roche Ltd |
| Takara Bio Inc. |
| Bio-Rad Laboratories Inc. |
| Others |
Cost & Logistics Intelligence
China's dominance in raw material supply for synthetic nucleic acids and recombinant proteins concentrates margin pools upstream. This upstream control influences pricing power across the molecular weight marker value chain.
Pricing Analysis
Configured-to-order high-purity markers command premium pricing, contrasting with the per-unit transactional model for standard pre-stained markers. Price differentiation hinges on certification level, such as ISO 9001, and the volume scale of procurement. Pricing softness stems from the increasing availability of direct-to-lab sales channels, bypassing traditional distributors. Academic laboratories are the most price-sensitive segment, while biopharmaceutical developers prioritize consistency over cost for GMP-compliant workflows.
Supply Chain Analysis
Stringent export controls on advanced biotechnology components, particularly from the United States and European Union, limit the free flow of specialized reagents. Global supply for molecular weight markers heavily sources from manufacturing hubs in China, the United States, and Germany. Raw material dependencies include highly purified oligonucleotides and recombinant proteins. Cold chain logistics complexity represents a significant structural risk, threatening product integrity during global transit. Direct-to-lab sales channels and established distributor networks form the dominant downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
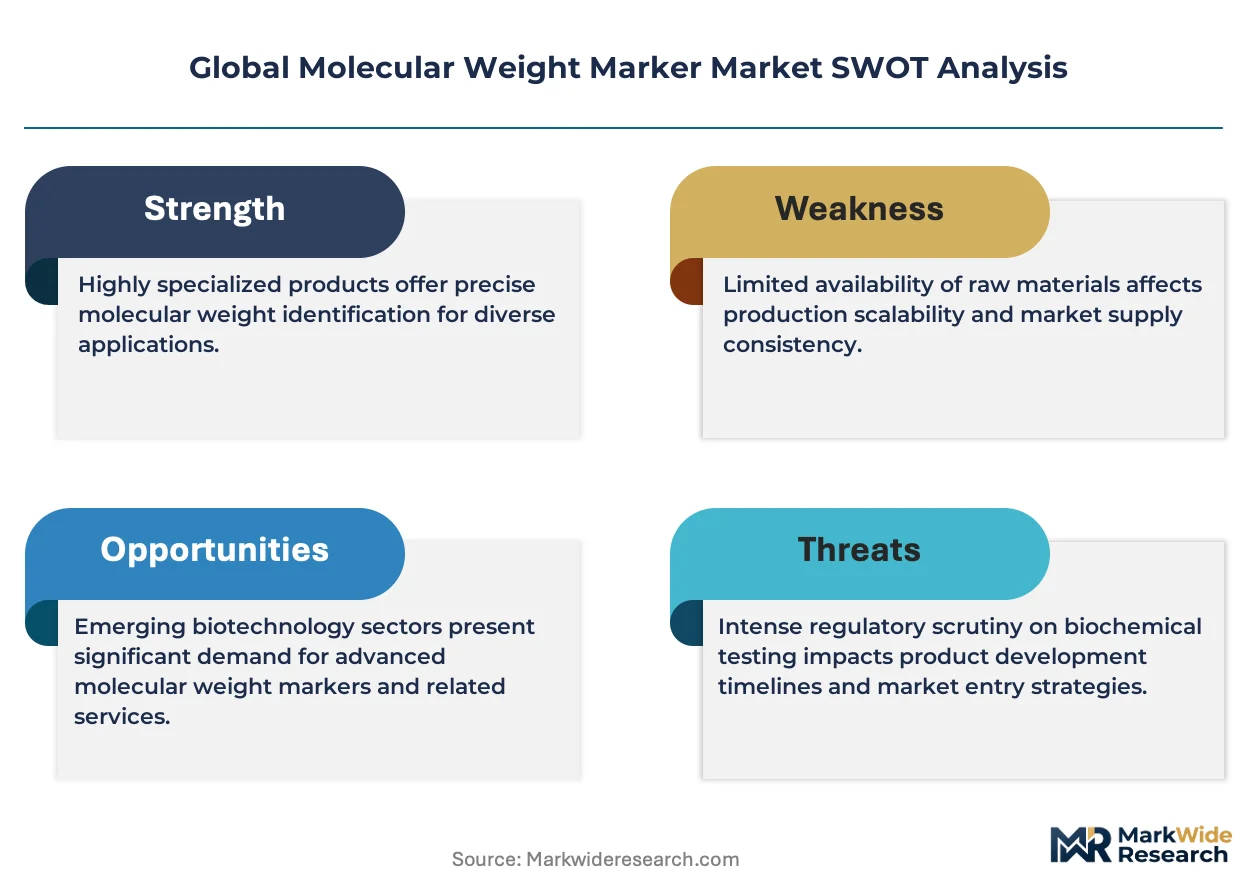
The molecular weight marker market presents a defensive moat, primarily due to regulatory entrenchment requiring extensive product validation. This high barrier to entry protects established suppliers.
For Market Incumbents: Insulate core market share by investing in auditable quality management systems, specifically ISO 9001 and GMP compliance. Expand specialized portfolios for emerging therapeutic modalities like mRNA vaccines to counter the threat of technological substitution from microfluidics. Deepen channel partnerships with biopharmaceutical developers, providing extensive batch-to-batch consistency documentation. This strategy strengthens customer switching costs within regulated environments.
For New Entrants and Emerging Players: Establish a beachhead in academic laboratories and biotechnology startups by offering workflow kits that bundle markers with precast gels. Target underpenetrated diagnostic networks in India and Southeast Asia, focusing on cost-effective, routine-use markers. A direct-to-lab e-commerce model with simplified ordering and transparent pricing offers a compelling go-to-market angle. This approach leverages convenience and budget constraints in less regulated segments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap specialists focused on high-purity reagents for genomics research. Long-term viability over a five-to-ten year window favors firms with strong intellectual property in novel marker design for emerging therapeutic modalities. Acquisition targets include companies with established ISO 9001 certification and robust cold chain logistics capabilities. Watch for accelerating regulatory convergence between the US FDA and European EMA on ancillary materials as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand GMP-Compliant Marker Portfolio | This initiative directly addresses biopharmaceutical quality control requirements from regulators like the FDA and EMA. |
| Develop Markers for mRNA Vaccines | This move capitalizes on the emerging therapeutic modality, establishing early market leadership in novel QC standards. |
| Strengthen Direct-to-Lab E-commerce Platform | This enhances market reach, fragmenting traditional distributor channels and improving customer access for specialized products. |
| Acquire Cold Chain Logistics Expertise | This mitigates risks associated with temperature-sensitive reagents, ensuring product integrity during global distribution. |
| Pursue ISO 9001 Certification for All Product Lines | This provides a critical differentiator for suppliers selling into regulated environments, supporting customer validation efforts. |
Research Approach
A spread of perspectives from R&D directors, procurement leads, regulatory affairs specialists, and academic researchers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were rigorously validated against secondary data from US FDA filings, EMA guidelines, and biotechnology industry reports. This approach employed both bottom-up market sizing and top-down validation to ensure robust data integrity.
Demand-supply balance across the molecular weight marker market was meticulously modeled over the projection horizon, considering both volume and value. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates were derived through an analytical framework, integrating historical trends with anticipated technological advancements. Key forecast inputs included CRISPR gene-editing adoption rates and biopharmaceutical pipeline expansion.
Stress conditions across raw material costs, regulatory enforcement, and technological substitution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions concerning market dynamics. Material shifts in global biopharmaceutical R&D funding would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Automotive Silicone Market